
 Global Plastic Surgery Instruments Market | 2026-2036
Global Plastic Surgery Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plastic Surgery Instruments Market Foresight
German stainless steel forging capacity is broadening output of precision-grade surgical alloys. Zimmer Biomet Holdings Inc. leverages its orthopedic manufacturing scale to anchor plastic surgery instrument supply chains. B. Braun Melsungen AG sustains dominance in electrosurgical device integration through captive R&D programs. KLS Martin Group specializes in craniofacial tool sets that occupy premium positioning across European surgical centers.
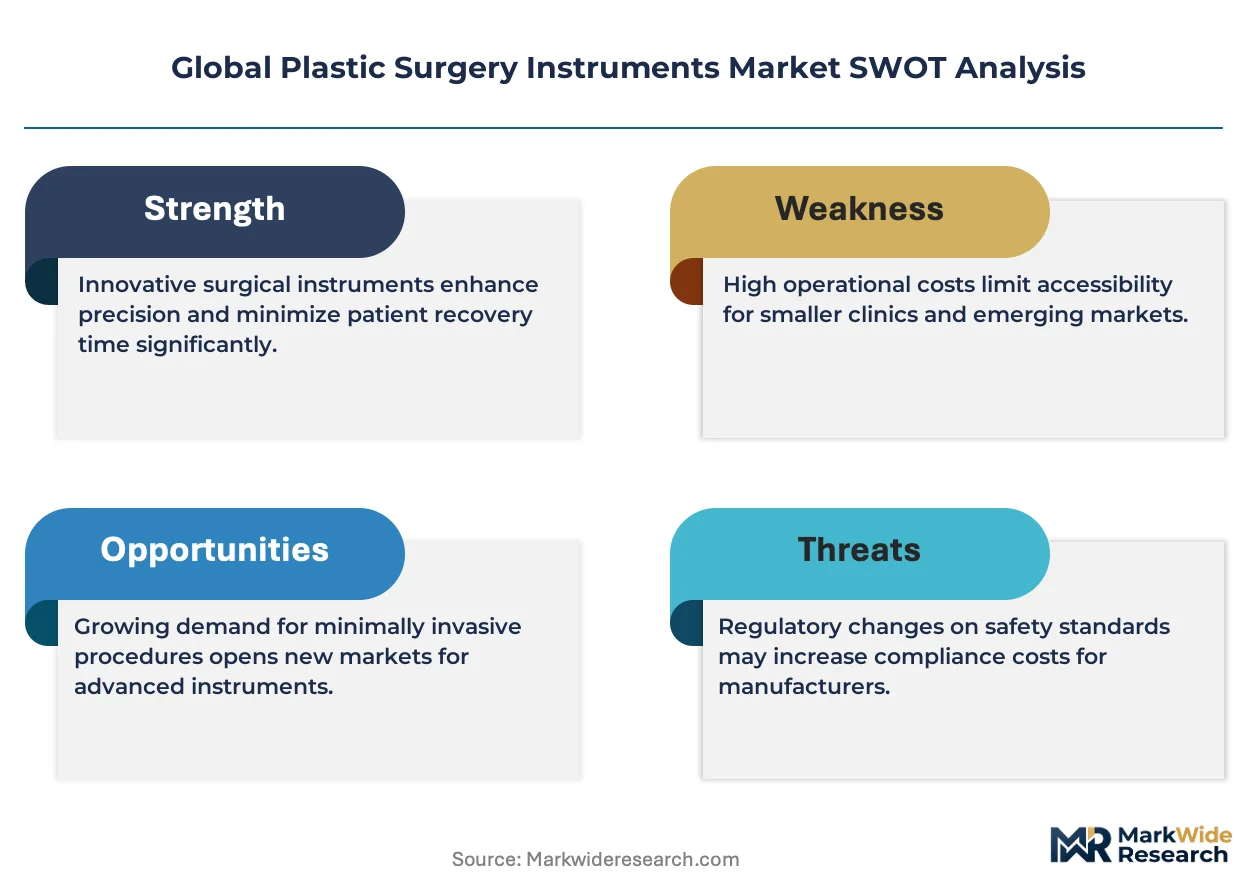
Plastic surgery instruments comprise precision-manufactured handheld and powered devices, typically forged from martensitic stainless steel or titanium alloys with Rockwell hardness ratings between 48 and 58 HRC, designed to cut, grasp, retract, or coagulate tissue during aesthetic and reconstructive procedures. Scalpels and forceps command the largest revenue share due to universal procedural necessity and high replacement frequency from sharpening degradation. Electrosurgical devices represent the fastest-expanding technology segment as bipolar and monopolar platforms displace traditional mechanical cutting in operating rooms. Cosmetic surgery applications generate disproportionate margin pools compared to reconstructive cases, driven by elective procedure pricing power and instrument customization requirements.
FDA 510(k) clearance pathways govern US market entry for reusable and single-use instruments, while the EU Medical Device Regulation imposes Unique Device Identification and enhanced clinical evidence requirements on Class IIa and higher surgical tools. ISO 13485 quality management certification has become a non-negotiable threshold for supplier qualification by private hospital chains and ambulatory surgical facilities. Stakeholders must monitor how Japan's PMDA and South Korea's MFDS converge their sterilization validation standards, as harmonization would reshape procurement specifications across Asia-Pacific supply agreements.
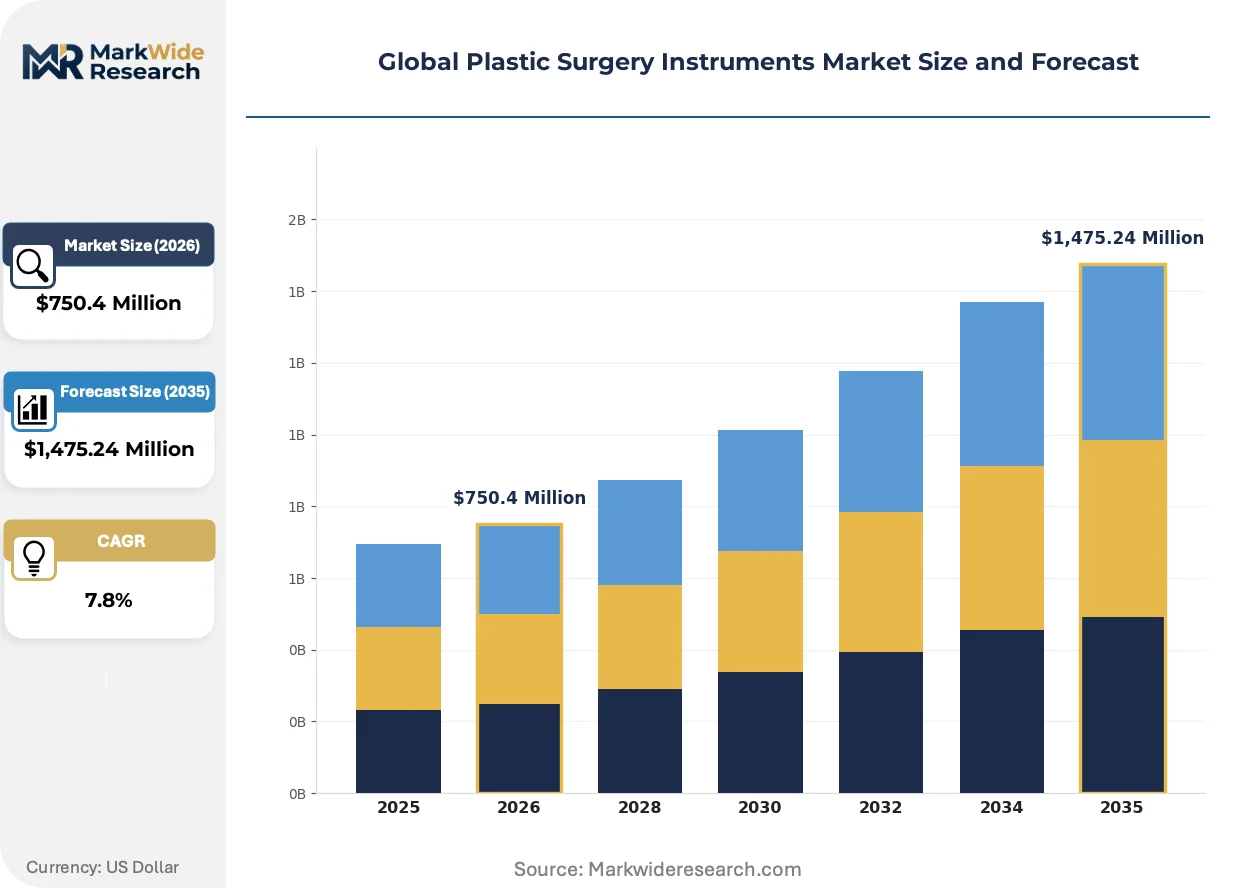
Market Dynamics
EU MDR sterilization mandates are compressing procurement cycles for reusable instrument suites while Korean cosmetic surgery clusters expand titanium-alloy forceps orders, creating divergent demand pressures across regulatory jurisdictions.
Growth Catalysts
- MDR sterilization validation:EU Medical Device Regulation requirements for reusable tool traceability are accelerating hospital replacement of legacy stainless steel sets with certified instrument platforms.
- Brazilian private surgical centers:Elective procedure volume in São Paulo and Rio de Janeiro is expanding procurement of electrosurgical handpieces for liposuction and rhinoplasty suites.
- Titanium alloy adoption:Martensitic stainless steel instruments face substitution by lighter, non-magnetic titanium variants in craniofacial and microsurgical applications.
Market Restraints
- German forging concentration:Precision surgical alloy production clusters in Solingen and Tuttlingen create single-source vulnerability for high-hardness instrument blanks.
- Electrosurgical device capex:Bipolar and monopolar platform installation requires surgical suite electrical infrastructure upgrades that ambulatory centers defer.
- ISO 13485 certification timelines:Quality management system audits for Class IIa instruments impose 12-18 month supplier qualification delays.
Strategic Opportunities
- Indian tier-2 cities:Underpenetrated aesthetic surgery demand in Ahmedabad and Chandigarh creates first-mover positioning for disposable instrument kits.
- Japan-South Korea harmonization:Convergence of PMDA and MFDS sterilization validation standards would streamline cross-border procurement contracts.
- Direct-to-clinic distribution:Bypassing traditional medical device distributors through manufacturer-owned digital procurement portals reduces channel margin capture.
Industry Challenges
- Rockwell hardness calibration:Maintaining 48-58 HRC specifications across titanium and stainless steel batches requires specialized metallurgical expertise that contract manufacturers lack.
- 510(k) predicate navigation:FDA clearance pathways for modified instrument geometries demand extensive equivalence documentation that stretches regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plastic Surgery Instruments Market |
| Market Size in 2026 | $750.4 Million |
| Market Size in 2035 | $1,475.24 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scalpels, Forceps, Scissors, Needle Holders, Retractors, Sutures Application: Reconstructive Surgery, Cosmetic Surgery, Craniofacial Surgery, Hand Surgery, Burn Repair, Microsurgery End User: Specialty Clinics, Surgical Centers, Plastic Surgery Practitioners, Private Hospitals, Academic Institutions, Ambulatory Surgical Facilities Technology: Electrosurgical Devices, Ultrasonic Instruments, Laser Technology, Cryosurgical Tools, Sterilization Equipment, Imaging Systems |
| Companies Covered | Zimmer Biomet Holdings Inc., Sklar Surgical Instruments, B. Braun Melsungen AG, Tekno-Medical Optik-Chirurgie GmbH, BMT Medizintechnik GmbH, Integra LifeSciences Corporation, KLS Martin Group, Bolton Surgical Ltd., KARL STORZ SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plastic Surgery Instruments Market Shifts & Advancements
Digital sterilization tracking and single-use instrument economics are compressing the traditional reusable-durable paradigm, while regulatory divergence between major jurisdictions forces parallel compliance investments.
Radio-frequency identification (RFID) tagging embedded in surgical instrument handles enables real-time sterilization cycle counting and automated replacement triggering. Major hospital chains in Germany and the United States are mandating RFID-enabled forceps and retractors for operating room inventory management. This sensor integration is decentralizing asset tracking from central sterile supply departments to point-of-use surgical suites, compressing instrument utilization analytics into real-time workflow dashboards.
EU Medical Device Regulation Unique Device Identification requirements for Class IIa surgical tools impose serialized labeling and enhanced clinical evidence standards. Manufacturers must maintain post-market surveillance registries for reusable instrument failure modes that were previously exempt. European surgical centers are responding by consolidating supplier relationships toward vendors with captive sterilization validation laboratories, reducing approved vendor lists by forty to sixty percent.
Cosmetic surgery clinics in Seoul and São Paulo are unbundling instrument procurement from capital equipment leases, purchasing scalpels and forceps directly through manufacturer e-commerce portals rather than distributor networks. This disintermediation is compressing price transparency and enabling volume-based contracting for high-turnover consumables. The shift is most visible in South Korean clinic chains where procedure volume justifies direct container shipments from Solingen forging houses.
Global Plastic Surgery Instruments Market Segmentation
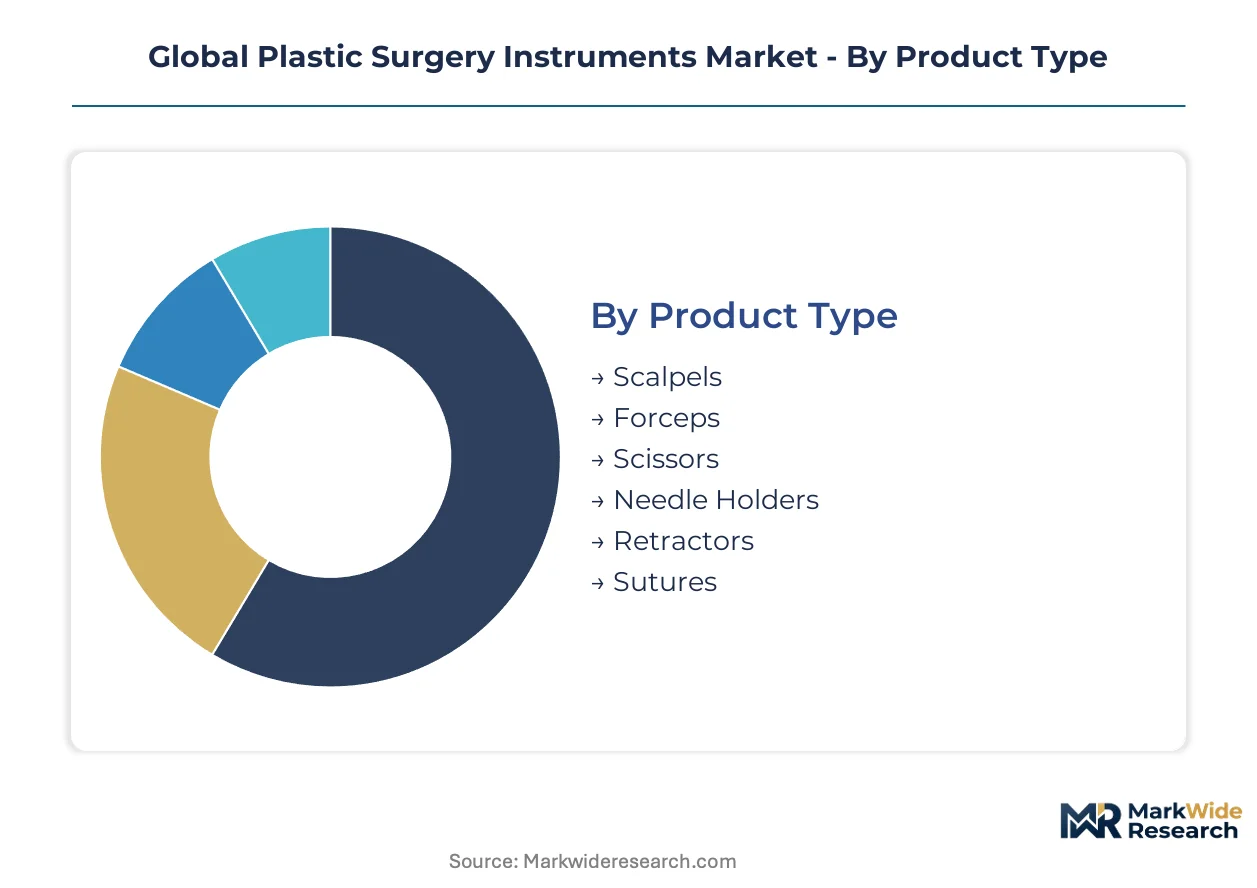
Plastic surgery instrument procurement patterns diverge sharply across clinical settings and procedural types. Upgrade cycles and replacement frequency vary from months for disposable consumables to years for capital-intensive electrosurgical platforms.
Product Type:
Replacement cycles drive purchasing rhythms across instrument categories, with high-wear items commanding recurring revenue streams.
- Scalpels:Disposable carbon steel and reusable stainless steel variants require constant replenishment due to edge degradation. Brazilian private surgical centers in São Paulo and Rio de Janeiro purchase scalpels in bulk through direct manufacturer portals, bypassing traditional distributors.
- Forceps:Titanium-alloy and martensitic stainless steel forceps with Rockwell hardness ratings between 48 and 58 HRC dominate craniofacial suites. Seoul cosmetic surgery clusters are expanding titanium forceps orders as Korean clinics unbundle procurement from equipment leases.
- Scissors:Supercut and tungsten carbide-edged variants serve precise tissue dissection requirements.
- Needle Holders:Ratchet-lock and non-locking designs accommodate varying suture calibers across reconstructive procedures.
- Retractors:Self-retaining and hand-held configurations address exposure needs in abdominal and facial surgeries.
- Sutures:Absorbable and non-absorbable threads complete wound closure protocols across all procedural categories.
Scalpels sit at the top of the volume ranking, with titanium-alloy forceps climbing the fastest.
Application:
Margin structures differ substantially between elective cosmetic work and medically necessary reconstruction.
- Cosmetic Surgery:Elective aesthetic procedures generate disproportionate margin pools due to pricing power and instrument customization requirements. German surgical centers prioritize premium instrument sets for rhinoplasty and liposuction suites.
- Craniofacial Surgery:Precision demands for maxillofacial reconstruction drive adoption of microsurgical instrument platforms. KLS Martin Group's specialized tool sets occupy premium positioning across European centers performing orthognathic procedures.
- Reconstructive Surgery:Post-traumatic and oncological reconstruction relies on versatile instrument configurations.
- Hand Surgery:Microvascular and tendon repair procedures require specialized fine instrumentation.
- Burn Repair:Escharotomy and skin grafting instruments address acute and chronic thermal injury management.
- Microsurgery:Free tissue transfer and replantation procedures demand highest-grade optical-assisted instrumentation.
Cosmetic surgery commands the steepest expansion trajectory in absolute value terms, while craniofacial applications gain share fastest among reconstructive categories.
End User:
Procurement authority concentrates differently across facility types, shaping vendor access strategies.
- Specialty Clinics:Concentrated procedure volumes in Seoul and São Paulo cosmetic surgery chains enable direct container shipments from Solingen forging houses. These clinics bypass distributor networks entirely through manufacturer e-commerce portals.
- Surgical Centers:Ambulatory facilities in Brazil's private sector are expanding electrosurgical handpiece procurement for liposuction suites. Electrical infrastructure upgrades remain a capital constraint for bipolar and monopolar platform installation.
- Plastic Surgery Practitioners:Solo and group practices maintain individualized instrument preferences.
- Private Hospitals:German and US hospital chains mandate RFID-enabled forceps and retractors for operating room inventory management.
- Academic Institutions:Training programs require durable, standardized instrument sets for resident education.
- Ambulatory Surgical Facilities:Same-day discharge protocols favor disposable instrument economics over reusable sterilization cycles.
Specialty clinics sit at the top of the volume ranking, with ambulatory surgical facilities climbing the fastest.
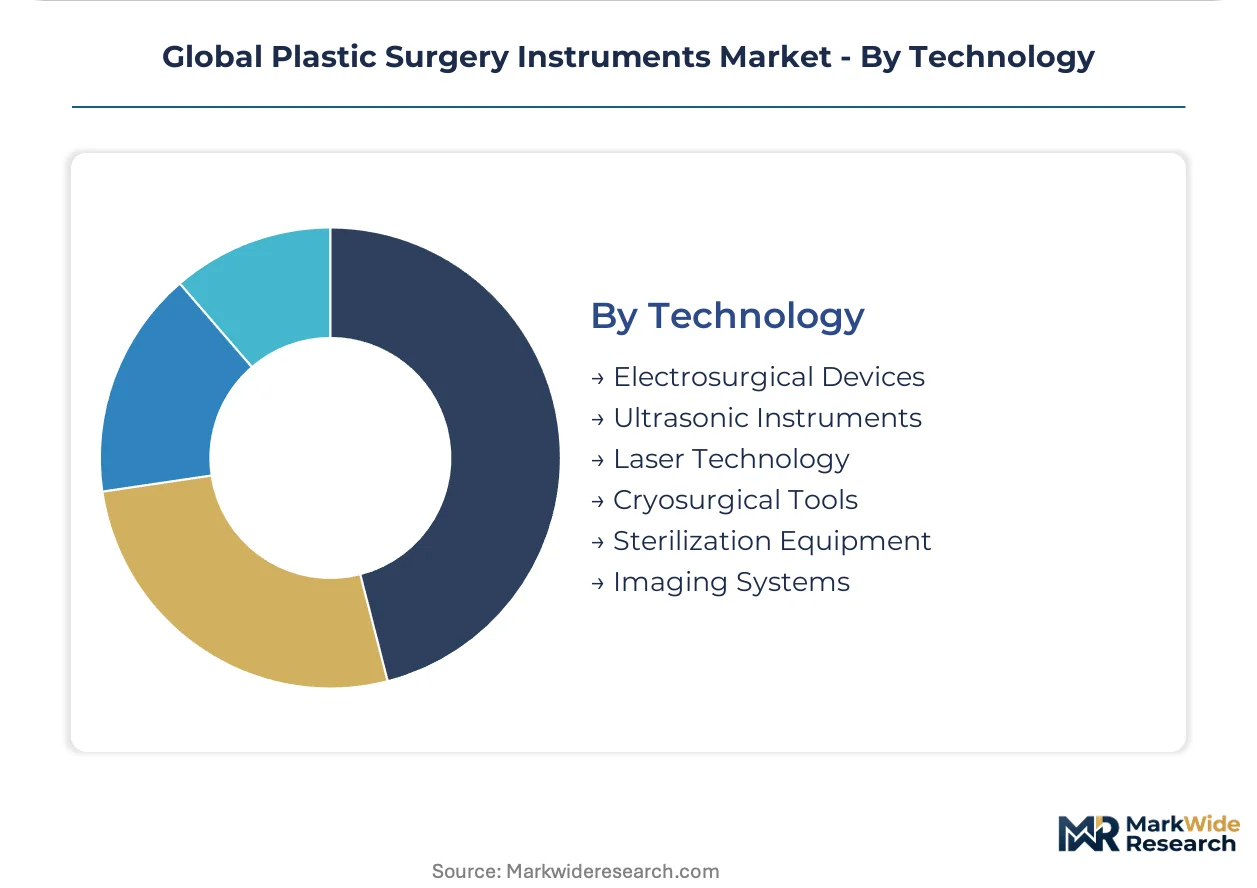
Technology:
Capital intensity and regulatory burden separate powered platforms from mechanical handheld tools.
- Electrosurgical Devices:Bipolar and monopolar platforms are displacing traditional mechanical cutting in operating rooms. B. Braun Melsungen AG sustains dominance in electrosurgical device integration through captive R&D programs.
- Laser Technology:Ablative and non-ablative systems serve skin resurfacing and hair removal applications. FDA 510(k) clearance pathways govern US market entry for these powered instruments.
- Ultrasonic Instruments:Harmonic scalpel technology enables precise cutting with minimal thermal spread.
- Cryosurgical Tools:Liquid nitrogen and argon-based systems target dermatological lesion destruction.
- Sterilization Equipment:Steam, hydrogen peroxide, and ozone systems support reusable instrument reprocessing.
- Imaging Systems:Intraoperative navigation and visualization platforms enhance procedural precision.
Electrosurgical devices sit at the top of the volume ranking, with laser technology climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian private surgical centers purchase electrosurgical handpieces at volumes that rival German hospital chains, yet Seoul cosmetic surgery clusters now source titanium forceps through direct manufacturer portals that bypass traditional distribution entirely.
United States
Hospital chains in Texas and Florida mandate RFID-enabled forceps for operating room inventory tracking. FDA 510(k) clearance pathways govern reusable instrument entry, with predicate device navigation consuming extensive regulatory bandwidth. Boston and Minneapolis surgical centers consolidate supplier relationships toward vendors with captive sterilization validation laboratories.
Germany
Solingen forging houses supply precision-grade martensitic stainless steel blanks to instrument manufacturers across Europe. EU Medical Device Regulation imposes Unique Device Identification and enhanced clinical evidence requirements on Class IIa surgical tools. Tuttlingen industrial clusters maintain specialized metallurgical expertise for Rockwell hardness calibration between 48 and 58 HRC specifications.
South Korea
Seoul cosmetic surgery chains unbundle instrument procurement from capital equipment leases, purchasing scalpels and forceps through manufacturer e-commerce portals. MFDS sterilization validation standards are converging with Japan's PMDA frameworks, potentially streamlining cross-border procurement contracts. Gangnam district clinics now receive direct container shipments from European forging houses.
Brazil
São Paulo and Rio de Janeiro private surgical centers expand electrosurgical handpiece procurement for liposuction and rhinoplasty suites. ANVISA governs medical device registration with pathways distinct from FDA or EU MDR frameworks. Electrical infrastructure upgrades remain a capital constraint for bipolar and monopolar platform installation in ambulatory facilities.
Japan
Tokyo and Osaka hospital systems prioritize premium instrument sets for cosmetic and reconstructive procedures. PMDA sterilization validation standards are harmonizing with South Korean MFDS requirements, reshaping Asia-Pacific supply agreement specifications. Kanto region academic medical centers maintain durable standardized instrument sets for resident training programs.
Global Plastic Surgery Instruments Market Competitive Landscape
German producers anchor one tier of precision forging capacity; US-based specialists hold another tier of integrated orthopedic and surgical instrument manufacturing. The vendor base clusters around three strategic archetypes: diversified orthopedic conglomerates with plastic surgery instrument divisions, mid-sized German fabricators with captive metallurgical expertise, and specialized craniofacial tool set manufacturers. Dominant competitive moves include backward integration into stainless steel and titanium alloy forging, plus direct-to-clinic distribution portal development that disintermediates traditional medical device distributors.
Within the diversified orthopedic tier, Zimmer Biomet Holdings Inc. and Integra LifeSciences Corporation occupy positions that leverage scale across surgical instrument supply chains. Among German-based fabricators, B. Braun Melsungen AG and KLS Martin Group exemplify archetypes of electrosurgical integration and craniofacial specialization respectively. Tekno-Medical Optik-Chirurgie GmbH represents the precision-optical instrument segment that serves microsurgical applications.
| Leading Market Players |
|---|
| Zimmer Biomet Holdings Inc. |
| Sklar Surgical Instruments |
| B. Braun Melsungen AG |
| Tekno-Medical Optik-Chirurgie GmbH |
| BMT Medizintechnik GmbH |
| Integra LifeSciences Corporation |
| KLS Martin Group |
| Bolton Surgical Ltd. |
| KARL STORZ SE & Co. KG |
| Others |
Supply & Pricing Matrix
Chromium-molybdenum alloy price indices from Solingen forging houses cascade through three distinct pricing tiers: premium titanium-alloy instrument sets for Seoul cosmetic surgery chains, standard martensitic stainless steel configurations for Brazilian private surgical centers, and economy-grade disposable kits for Indian tier-2 ambulatory facilities. Each tier absorbs raw material volatility differently, with direct-to-clinic procurement compressing channel margins at the premium end while distributor markups persist in fragmented emerging markets.
Pricing Analysis
Distributor margin compression now defines the channel economics of plastic surgery instruments, with traditional medical device distributors facing disintermediation as Seoul and São Paulo clinic chains migrate to manufacturer-owned digital procurement portals. Three-tier pricing structure across premium, standard, and economy levels reflects Rockwell hardness certification grades, ISO 13485 compliance status, and volume scale. Pricing pressure stems from EU MDR sterilization validation costs that manufacturers must absorb or pass through. Brazilian private surgical centers exhibit highest price sensitivity due to ANVISA registration cost burdens, while German hospital chains prioritize certified instrument platforms over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Seoul cosmetic surgery chains and São Paulo private surgical centers, bypassing traditional distributor networks entirely. German forging capacity in Solingen and Tuttlingen anchors precision surgical alloy supply, with secondary concentration in Japanese metallurgical facilities for titanium-alloy variants. Raw material dependencies center on martensitic stainless steel blanks, titanium sponge feedstock, and tungsten carbide cutting edges. Single-source vulnerability concentrates in Solingen's specialized Rockwell hardness calibration expertise. Distribution runs through manufacturer-owned e-commerce portals for premium accounts and regional medical device distributors for fragmented ambulatory markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as EU MDR sterilization mandates and MFDS-PMDA harmonization drive procurement toward certified instrument platforms with captive validation capabilities. Demand is shifting toward premium titanium-alloy specifications that command pricing power through metallurgical differentiation.
For Market Incumbents: Hedge against titanium-alloy substitution by deepening captive forging relationships in Solingen and Tuttlingen industrial clusters. Defensive consolidation moves include acquiring sterilization validation laboratories to meet EU MDR post-market surveillance requirements, and establishing direct-to-clinic digital procurement portals to preempt distributor disintermediation. Electrosurgical device integration from B. Braun's R&D model offers a template for backward control over powered platform supply chains.
For New Entrants and Emerging Players: Tier-2 Indian cities present an underserved buyer archetype with minimal penetration from established German and US manufacturers. White-space targets include disposable instrument kits for Ahmedabad and Chandigarh ambulatory surgical facilities, and mid-tier titanium-alloy forceps for Korean cosmetic surgery chains seeking alternatives to premium European brands. A go-to-market angle anchored on ISO 13485 pre-certification and direct manufacturer relationships bypasses traditional distributor qualification delays.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-sized German fabricators possessing captive metallurgical expertise for 48-58 HRC calibration. Long-term viability favors vendors with integrated sterilization validation capabilities that can consolidate EU hospital vendor lists. The inflection signal to watch is Japan-South Korea regulatory harmonization completion, which would unlock cross-border procurement contract standardization across Asia-Pacific supply agreements.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Sterilization Validation Laboratory Acquisition | Captive validation capabilities reduce hospital vendor consolidation risk from forty to sixty percent. |
| Direct-to-Clinic Digital Procurement Portal Launch | Seoul and São Paulo clinic chains now bypass traditional medical device distributors entirely. |
| Titanium-Alloy Forging Capacity Expansion | Gangnam district clinics source direct container shipments from European forging houses. |
| RFID-Enabled Instrument Handle Integration | German and US hospital chains mandate real-time sterilization cycle counting for operating room inventory. |
| MFDS-PMDA Harmonization Compliance Investment | Converging sterilization standards reshape Asia-Pacific procurement specifications across supply agreements. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with instrument procurement managers at Seoul cosmetic surgery chains, biomedical engineers at German hospital systems, regulatory affairs leads navigating FDA 510(k) pathways, and GPO contracts managers at Brazilian private surgical centers. Secondary validation drew from FDA 510(k) clearance databases, EU MDR Class IIa registration filings, ANVISA medical device registration records, and hospital procurement database extracts. Bottom-up instrument shipment modeling triangulated against top-down surgical procedure volume estimates.
Segment-weighting across the projection horizon applied product type, application, end user, and technology dimensions, with electrosurgical devices and titanium-alloy forceps receiving distinct growth coefficients. CAGRs derived from surgical procedure volume elasticity, instrument replacement frequency by Rockwell hardness degradation curves, and regulatory-driven upgrade cycle compression. Industry-specific forecast inputs included EU MDR implementation timelines and MFDS-PMDA harmonization progress indicators.
Underlying measurement precision varies by segment; electrosurgical device and RFID-enabled instrument categories carry tighter precision than economy disposable kits due to concentrated manufacturer reporting. Forecasts reflect assumptions around regulatory implementation pace, raw material alloy price stability, and distributor channel structure evolution. Periodic stress-testing of base assumptions is recommended given sterilization standard harmonization uncertainty and titanium sponge supply concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Cheilectomy Market
Surgical Instruments
Surgical Retainers Market
Surgical Instruments
Global Surgical Suction Instruments Market
Surgical Instruments
Americas Suture Needles Market
Surgical Instruments
Global Surgical Instrument Tracking System Market
Surgical Instruments
Absorbable PGA Surgical Sutures Market
Surgical Instruments
Asia Pacific Surgical Equipment Market
Surgical Instruments
Hand-Held Surgical Instruments Market
Surgical Instruments
Iraq Healthcare (Surgical Procedures) Market
Surgical Instruments
Global Dental Surgical Instruments Market
Surgical Instruments
Hemostatic Instruments Market
Surgical Instruments
Middle East and Africa Lancet and Pen Needles Market
Surgical Instruments
Global Minimally Invasive Surgery (MIS) Market
Surgical Instruments
Minimally Invasive Gastrointestinal Surgical System Market
Surgical Instruments
Absorbable Surgical Suture with Needle Market
Surgical Instruments
US Integrated Operating Rooms Market