
 Hemostatic Instruments Market | 2026-2036
Hemostatic Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Hemostatic Instruments Market Intelligence
Electrosurgical integration with hemostatic forceps is reconfiguring how surgeons achieve vessel sealing during open and minimally invasive procedures. Johnson & Johnson leverages its broad energy platform to bundle monopolar and advanced bipolar instruments with proprietary hemostatic coatings. Baxter International anchors its position through concentrated R&D in recombinant thrombin and absorbable hemostat matrices for trauma applications. B. Braun Melsungen AG differentiates via vertical control over German manufacturing for stainless steel and polymer instrument lines.
Hemostatic instruments are surgical devices engineered to arrest bleeding through mechanical compression, thermal coagulation, chemical activation, or a combination thereof, typically manufactured from medical-grade stainless steel, titanium, or bioabsorbable polymers with working surfaces calibrated to vessel diameters below 7 millimeters. Their primary purpose is to reduce intraoperative blood loss, shorten operative time, and minimize transfusion requirements across surgical disciplines. Clamps and sutures retain the largest installed base in cardiac and orthopedic applications, while hemostatic gels command premium pricing in liver resections where diffuse oozing defies mechanical control. Delivery through robotic platforms represents the fastest-expanding channel, though laparoscopic instruments still generate the majority of recurring revenue in high-volume hospital systems.
The FDA enforces biocompatibility and sterilization validation under 21 CFR Part 820 quality system regulations, while the EU Medical Device Regulation requires notified body certification for Class IIa and above surgical instruments entering European markets. ISO 10993 biological evaluation standards and ASTM F2902 for surgical instrument marking further constrain material selection and traceability protocols. Stakeholders must monitor how MDR transition timelines and FDA digital health pre-certification pilots reshape competitive access for integrated smart-hemostasis devices.
Market Dynamics
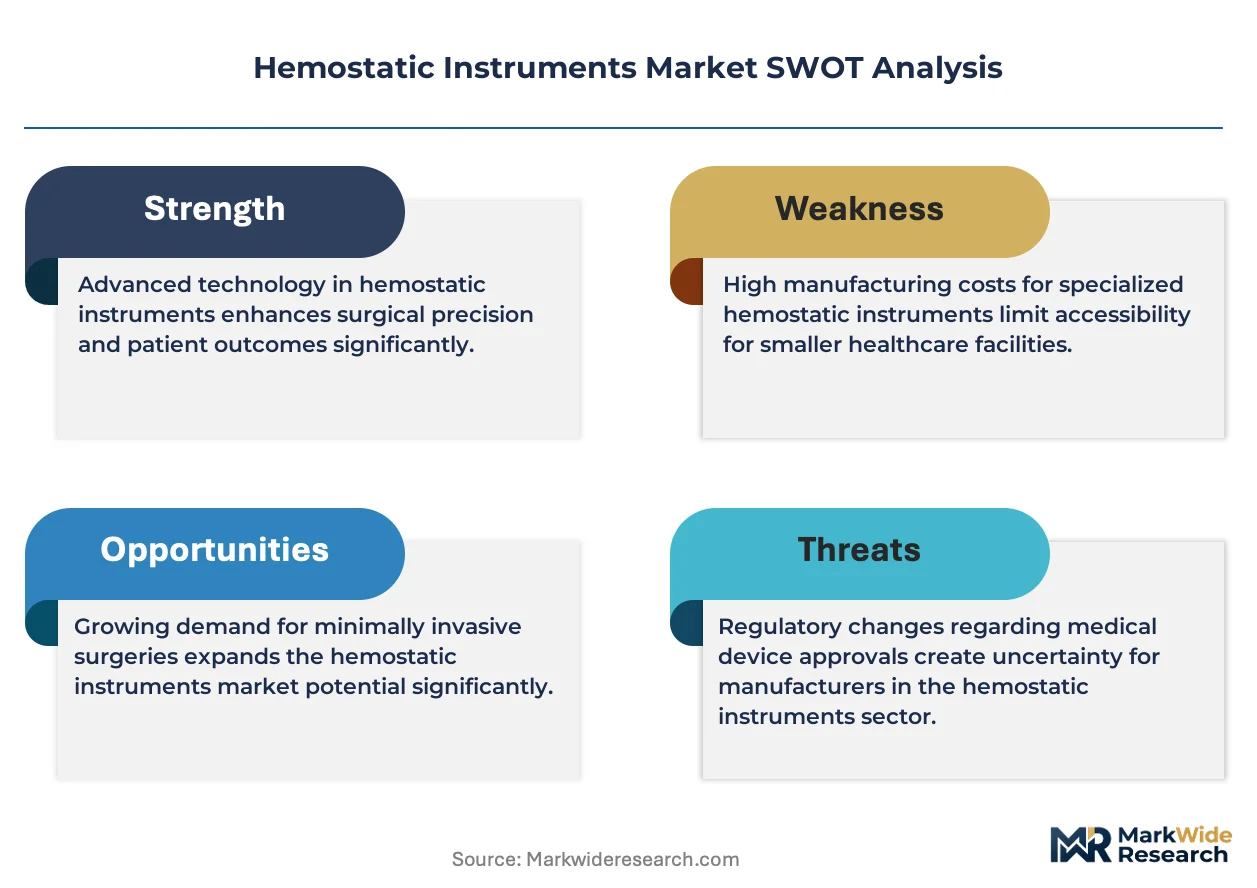
Electrosurgical integration is compressing the traditional boundary between energy platforms and mechanical hemostasis, forcing instrument manufacturers to recalibrate R&D roadmaps around sealed vessel integrity rather than standalone clamp performance. This convergence is redistributing value capture toward systems integrators and away from pure-play instrument suppliers.
Growth Catalysts
- FDA Biocompatibility Guidance:Updated 21 CFR Part 820 quality system regulations are accelerating validation cycles for hemostatic gel formulations, creating first-mover advantages for manufacturers with pre-submission pathways.
- Cardiac Surgery Suite Modernization:United States hospital systems are retiring reusable instrument inventories in favor of single-use alternatives, driven by infection control protocols and sterilization cost accounting.
- German University Hospital Procurement:Berlin and Munich clusters are standardizing around integrated hemostasis systems, concentrating demand volume and enabling vendor-managed inventory arrangements.
Market Restraints
- Medical-Grade Polymer Supply Concentration:Bioabsorbable polymer feedstocks for hemostat matrices depend on a limited supplier base concentrated in Western Europe, exposing manufacturers to input volatility.
- EU MDR Transition Friction:Notified body certification bottlenecks for Class IIa surgical instruments are extending time-to-market for updated product lines, compressing revenue recognition windows.
- Mechanical Clamp Substitution:Advanced bipolar vessel sealers are displacing traditional hemostatic forceps in laparoscopic procedures, eroding installed base replacement demand.
Strategic Opportunities
- Robotic Platform Integration:Da Vinci-compatible hemostatic instruments represent an underpenetrated channel where specialized tip designs command premium positioning.
- Trauma Field Applications:Recombinant thrombin and flowable hemostat adoption in military and emergency medicine settings offers expansion beyond elective surgery volumes.
- Smart-Device Pre-Certification:FDA digital health pilot programs are creating regulatory tailwinds for sensor-integrated hemostasis systems with real-time tissue feedback.
Industry Challenges
- Biocompatibility Testing Talent Scarcity:ISO 10993 study design and GLP execution capabilities are concentrated among a small pool of contract research organizations, extending validation timelines.
- Legacy System Integration Complexity:Electrosurgical generators from incumbent energy platforms require proprietary handpiece protocols, complicating third-party hemostatic instrument compatibility.
- ASTM F2902 Traceability Compliance:Laser marking and UDI implementation for surgical instrument identification demands capital-intensive production line reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemostatic Instruments Market |
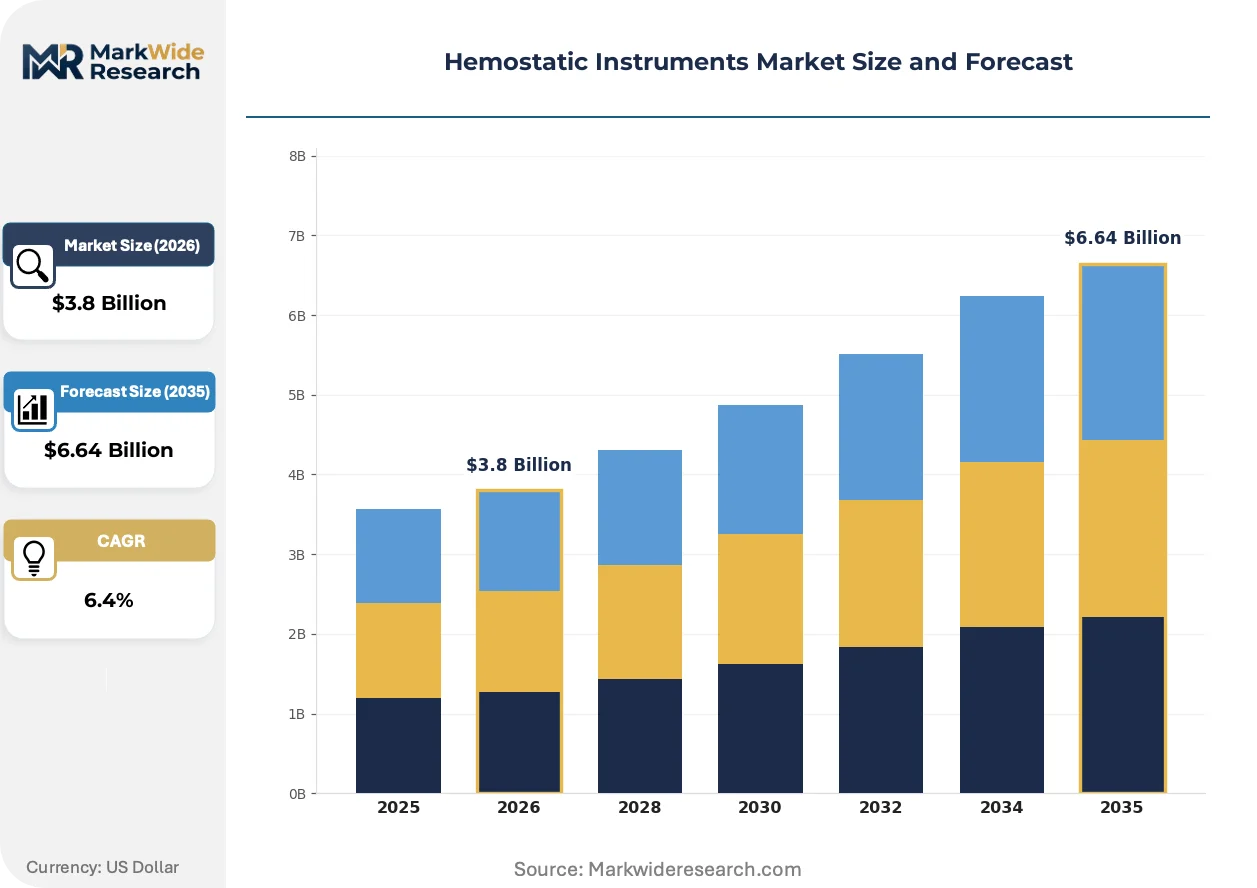
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clamps, Utensils, Sutures, Gels Application: Cardiac Surgery, Trauma, Orthopedic Procedures, Liver Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutes Delivery Mode: Open Surgery, Minimally Invasive Surgery, Laparoscopic Surgery, Robotic Surgery |
| Companies Covered | Johnson & Johnson, Baxter International, B. Braun Melsungen AG, Becton, Dickinson and Company, Medtronic, Pfizer, Stryker Corporation, Integra LifeSciences Corporation, Artivion, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemostatic Instruments Market Strategic Shifts & Innovations
Convergence between thermal energy delivery and mechanical compression is redefining performance benchmarks for vessel sealing, while regulatory digitization and procurement centralization are reshaping how manufacturers access hospital customers. These forces are compressing traditional competitive moats around material science alone.
Advanced bipolar vessel sealing technology is migrating from monopolar dominance in open surgery toward integrated platforms that combine mechanical compression with controlled radiofrequency energy delivery. Cardiac surgery suites in high-volume United States hospital systems are adopting these systems at accelerated replacement cycles. This migration from standalone instruments to energy-integrated platforms is compressing margins for suppliers lacking proprietary generator compatibility.
EU Medical Device Regulation notified body certification requirements are extending technical documentation scrutiny for Class IIa hemostatic instruments entering European markets. Manufacturers must demonstrate clinical evidence for absorbable hemostat performance claims under stricter equivalence pathways. German university hospitals are responding by consolidating supplier panels around MDR-ready vendors with Berlin and Munich procurement offices leading qualification standardization.
Hospital procurement offices are consolidating hemostatic instrument purchasing through vendor-managed inventory agreements that shift working capital burden onto suppliers. United States health system GPOs are displacing individual hospital contracting for cardiac surgery consumables, compressing price negotiation leverage for mid-tier manufacturers. This concentration is most visible in integrated delivery networks across the American Midwest, where standardization committees now mandate single-source hemostasis platforms.
Hemostatic Instruments Market Segmentation
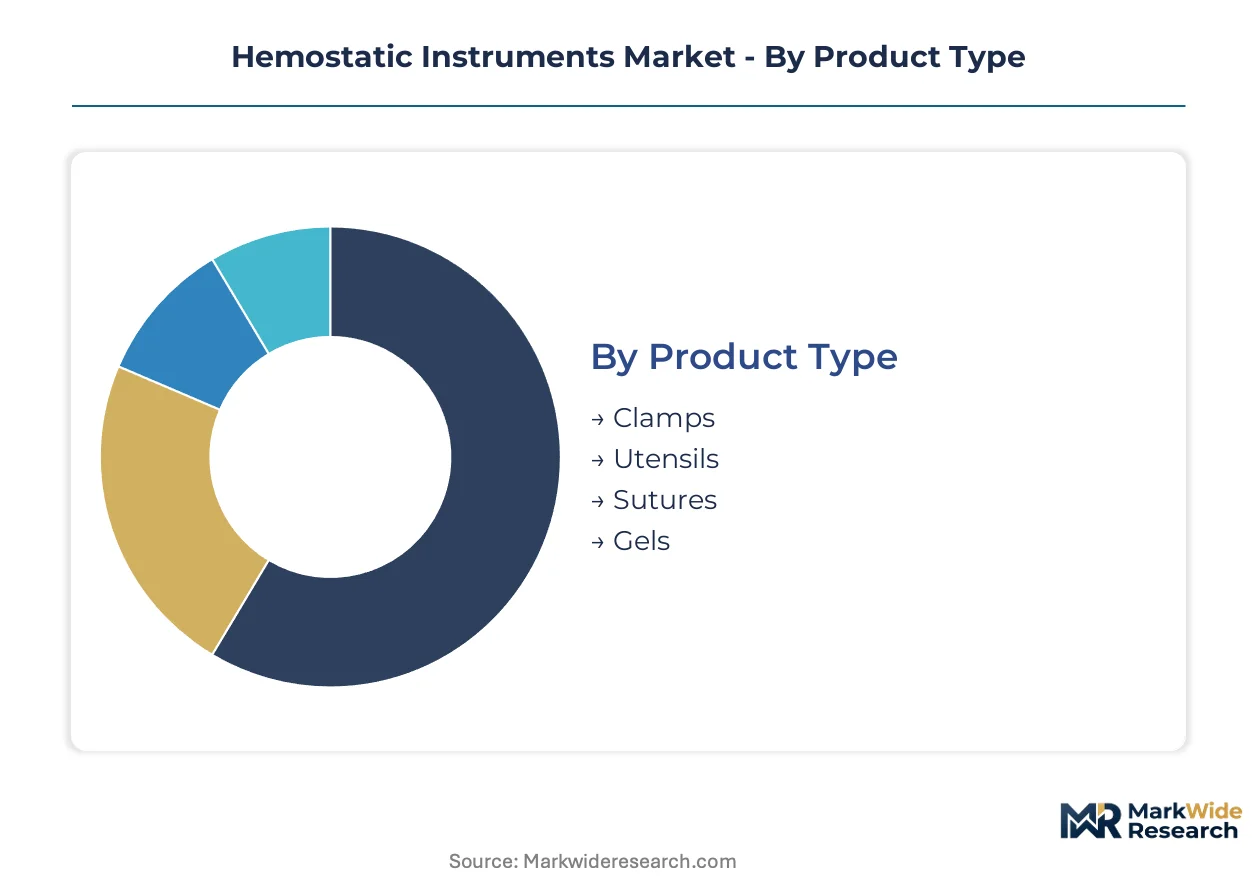
Hemostatic instruments serve divergent clinical workflows ranging from emergency trauma stabilization to precision robotic vessel sealing. Segmentation reveals how product specifications, surgical setting, and delivery technology allocate value across the care continuum.
Product Type:
Mechanical and chemical modalities span a cost-performance spectrum from reusable stainless steel to premium bioabsorbable matrices.
- Clamps:Stainless steel and titanium forceps with calibrated jaw surfaces deliver mechanical compression for vessels below 7 millimeters. Demand concentrates in United States cardiac surgery suites where hospitals are retiring reusable inventories in favor of single-use alternatives.
- Gels:Flowable hemostats and fibrin sealants combine thrombin with collagen or gelatin matrices for diffuse bleeding control. German university hospitals in Berlin and Munich are standardizing procurement around integrated systems that bundle gels with mechanical platforms.
- Sutures:Absorbable and non-absorbable threads with attached needles enable ligation in open and laparoscopic contexts. Vascular surgery departments favor braided synthetic formulations for tensile strength.
- Utensils:Specialized dissecting forceps and needle holders incorporate hemostatic surface coatings. Electrosurgical compatibility requirements are reshaping R&D priorities for this segment.
The dominant share belongs to Clamps, while Gels is closing the gap fastest.
Application:
Surgical discipline dictates instrument selection based on bleeding pattern, tissue type, and operative urgency.
- Cardiac Surgery:Sternotomy and cardiopulmonary bypass procedures demand hemostatic precision for arterial and venous cannulation sites. United States hospital systems are accelerating replacement cycles for energy-integrated forceps in high-volume cardiac suites.
- Trauma:Combat casualty care and emergency department settings deploy recombinant thrombin and flowable hemostats for uncontrolled hemorrhage. Military medical procurement is expanding absorbable matrix adoption beyond elective surgery volumes.
- Orthopedic Procedures:Total joint arthroplasty and spine surgery utilize mechanical clamps and bipolar sealers for cancellous bone bleeding. Ambulatory surgical centers are driving demand for disposable instrument kits.
- Liver Surgery:Hepatic resection presents diffuse oozing from parenchymal transection surfaces that mechanical control cannot address. Premium-priced hemostatic gels command positioning where standard techniques fail.
Cardiac Surgery holds the largest installed base, though Trauma is expanding most quickly.
End User:
Facility type determines purchasing authority, sterilization infrastructure, and preference for reusable versus disposable platforms.
- Hospitals:Integrated delivery networks and academic medical centers with cardiac surgery programs generate the majority of recurring revenue. Group purchasing organizations are consolidating supplier panels and compressing price negotiation leverage.
- Ambulatory Surgical Centers:Freestanding facilities performing orthopedic and ophthalmic procedures favor single-use instrument kits to eliminate sterilization overhead. Volume growth is accelerating in United States outpatient settings.
- Specialty Clinics:Dermatologic and plastic surgery practices utilize hemostatic forceps for minor procedures under local anesthesia. Procurement concentrates through distributor networks rather than direct manufacturer contracts.
- Research Institutes:Preclinical testing facilities and medical device incubators purchase instruments for biocompatibility validation and prototype evaluation. ISO 10993 study design requirements shape specification priorities.
Hospitals retain the dominant procurement volume, yet Ambulatory Surgical Centers are gaining share fastest.
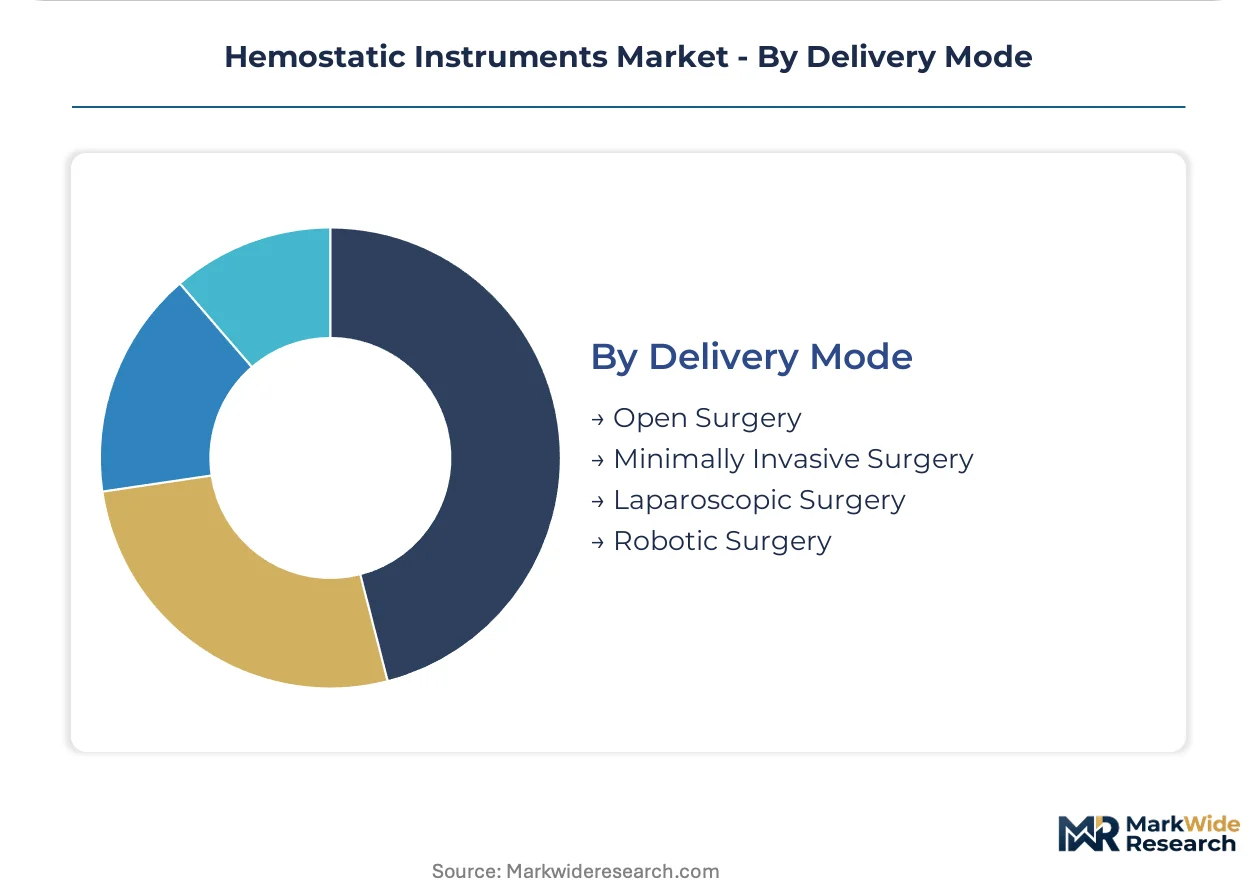
Delivery Mode:
Surgical access technique determines instrument shaft length, articulation requirements, and energy platform compatibility.
- Open Surgery:Traditional sternotomy and laparotomy approaches utilize standard-length forceps and clamps with direct manual control. Cardiac procedures in mature markets still generate substantial instrument consumption.
- Minimally Invasive Surgery:Reduced-access techniques through small incisions require elongated shafts and specialized tip geometries. German university hospitals are standardizing integrated hemostasis systems for these workflows.
- Laparoscopic Surgery:Insufflated abdominal procedures depend on insulated instruments compatible with monopolar and bipolar generators. Advanced bipolar vessel sealers are displacing traditional forceps in this channel.
- Robotic Surgery:Da Vinci-compatible instruments with wristed articulation command premium positioning for vessel sealing. This channel represents the steepest expansion trajectory as surgical robotics penetrate cardiac and general surgery.
Open Surgery maintains the largest procedure volume, while Robotic Surgery is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision-engineered hemostatic instruments to United States hospital systems, while Japanese suppliers serve cardiac surgery suites across East Asia. This trade corridor shapes procurement patterns in high-volume surgical markets.
United States
FDA 21 CFR Part 820 quality system regulations are accelerating biocompatibility validation cycles for hemostatic gel formulations. Hospital systems in the American Midwest are consolidating procurement through group purchasing organizations for cardiac surgery consumables. The Cleveland Clinic and Mayo Clinic clusters are standardizing around integrated hemostasis platforms with vendor-managed inventory arrangements.
Germany
EU Medical Device Regulation notified body certification requirements are extending technical documentation scrutiny for Class IIa surgical instruments. Berlin and Munich university hospitals are consolidating supplier panels around MDR-ready vendors with standardized qualification protocols. Baden-Württemberg manufacturing clusters maintain vertical control over stainless steel and polymer instrument lines.
Japan
PMDA regulatory pathways for surgical devices are converging with ISO 10993 biological evaluation standards for material traceability. The Kanto region around Tokyo generates concentrated demand for robotic-compatible hemostatic instruments. Osaka-based medical device distributors are expanding procurement networks for advanced bipolar vessel sealers.
China
NMPA medical device registration requirements are tightening clinical evidence standards for absorbable hemostat performance claims. The Yangtze River Delta manufacturing corridor is scaling production of medical-grade stainless steel instrument components. Shanghai teaching hospitals are piloting integrated hemostasis systems for minimally invasive surgical workflows.
India
CDSCO medical device rules are harmonizing with ISO standards for surgical instrument biocompatibility testing. Maharashtra and Gujarat manufacturing zones are expanding capacity for disposable hemostatic forceps targeting export markets. Delhi-NCR tertiary care centers are adopting recombinant thrombin formulations for trauma and emergency applications.
Hemostatic Instruments Market Key Industry Players
Channel-controlling players compete with product-specialist players for procurement contracts in consolidated hospital systems. The vendor base organizes around three tiers: diversified medical technology conglomerates with energy platform integration, mid-cap instrument specialists with regional manufacturing depth, and niche suppliers of bioabsorbable hemostat matrices. Strategic moves center on M&A for generator compatibility protocols and backward integration into polymer feedstock supply.
Within the diversified conglomerate tier, Johnson & Johnson and Baxter International exemplify platform-integrated positioning. B. Braun Melsungen AG represents the mid-cap specialist archetype with German manufacturing concentration. These three anchors illustrate how competitive positioning diverges between systems integrators and component suppliers in procurement negotiations with university hospital clusters.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Baxter International |
| B. Braun Melsungen AG |
| Becton, Dickinson and Company |
| Medtronic |
| Pfizer |
| Stryker Corporation |
| Integra LifeSciences Corporation |
| Artivion, Inc. |
| Others |
Cost & Logistics Intelligence
Medical-grade polymer supply concentration in Western Europe determines both the premium-mid-economy pricing differentiation across hemostatic matrix tiers and the geographic shape of instrument manufacturing networks. This input dependency forces manufacturers to absorb working capital burdens through vendor-managed inventory arrangements while passing selective cost exposure downstream.
Pricing Analysis
Next-generation energy-integrated vessel sealers command substantial premiums over prior-generation mechanical forceps and economy-tier reusable clamps. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 21 CFR Part 820 certification status, proprietary generator compatibility protocols, and volume scale through GPO contracts. Cost compression in the standard tier is intensifying because advanced bipolar sealers are displacing traditional forceps in laparoscopic workflows. Ambulatory surgical centers exhibit the highest price sensitivity due to sterilization cost accounting pressures, while German university hospital clusters demonstrate lowest sensitivity given procurement standardization around integrated systems.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are becoming standard as manufacturers absorb working capital pressure from vendor-managed inventory arrangements with consolidated hospital systems. Bioabsorbable polymer feedstock production centers on Germany, Switzerland, and the Netherlands, while medical-grade stainless steel instrument forging concentrates in Baden-Württemberg and the Yangtze River Delta. Raw material dependencies encompass recombinant thrombin biologics, collagen matrices, and titanium alloys. Single-source vulnerability for specialized polymer formulations exposes manufacturers to input volatility. Distribution runs through hospital GPOs and specialized surgical device distributors rather than direct manufacturer contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hemostatic instruments market represents a high-growth disruption driven by FDA digital health pre-certification pilots enabling sensor-integrated hemostasis systems with real-time tissue feedback capabilities.
For Market Incumbents: Pre-empt displacement from advanced bipolar vessel sealers by accelerating proprietary generator compatibility investments and securing exclusive handpiece protocols with electrosurgical platform leaders. Deepen backward integration into bioabsorbable polymer feedstock supply to insulate margin structures from Western European input volatility. Lock in multi-year vendor-managed inventory contracts with German university hospital clusters before MDR certification bottlenecks ease.
For New Entrants and Emerging Players: Establish a beachhead in robotic-compatible hemostatic instruments for Da Vinci platforms, where specialized tip designs remain underpenetrated and premium positioning is achievable. Target trauma field applications with recombinant thrombin and flowable hemostat formulations, leveraging military medical procurement expansion beyond elective surgery volumes. Pursue regulatory fast-track pathways through FDA digital health pilot programs as the primary go-to-market angle.
For Investors and Strategic Acquirers: EU MDR transition timelines reshape the acquisition landscape by compressing revenue recognition windows for non-certified vendors and concentrating valuation premiums on MDR-ready assets. Frame long-term viability around five-to-ten year regulatory digitization and robotic platform penetration trajectories. Prioritize mid-cap instrument specialists with German manufacturing depth and established notified body relationships. Monitor FDA pre-certification pilot expansion as the critical signal for smart-hemostasis device inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Digital Health Pre-Certification | Accelerates market access for sensor-integrated hemostasis systems with real-time feedback capabilities. |
| EU MDR Notified Body Certification | Enables continued European market participation for Class IIa surgical instruments under stricter equivalence pathways. |
| Robotic Platform Partnership | Secures premium positioning in Da Vinci-compatible instruments through proprietary wristed articulation designs. |
| Backward Polymer Integration | Captures margin protection from Western European bioabsorbable feedstock supply concentration. |
| Vendor-Managed Inventory Expansion | Locks in procurement standardization with German university hospital clusters through working capital absorption. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across cardiac surgery suites, trauma field medical officers, hospital procurement committees, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contract registries, and ISO 10993 biocompatibility study records. Bottom-up instrument shipment modeling and top-down surgical procedure volume estimates were triangulated to constrain forecast variance.
Calibration against historical replacement cycle data and robotic platform penetration curves anchored the analytical framework across the projection horizon. Segmentation dimensions encompassed product modality, surgical discipline, facility type, and delivery access technique. CAGRs were derived from logistic diffusion modeling of energy-integrated platform adoption and laparoscopic-to-robotic procedural shift rates. Forecast inputs included cardiac surgery suite modernization timelines and German university hospital procurement standardization protocols.
Sensitivities concentrate around EU MDR notified body capacity constraints, FDA digital health pilot program expansion velocity, and bioabsorbable polymer feedstock supply disruptions. Forecasts reflect documented assumptions regarding regulatory pathway timelines and hospital capital expenditure prioritization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
India Surgical Sutures Market
Surgical Instruments
Operating Room Smoke Aspirators Market
Surgical Instruments
Absorbable PGA Surgical Sutures Market
Surgical Instruments
Iraq Healthcare (Surgical Procedures) Market
Surgical Instruments
Gynecology Surgical Instruments Market
Surgical Instruments
Pneumoperitoneum Market
Surgical Instruments
Cryosurgical Equipment Market
Surgical Instruments
Knotless Tissue Control Devices Market
Surgical Instruments
Laparoscopic Power Morcellators Market
Surgical Instruments
Global Veterinary Surgical Instruments Market
Surgical Instruments
Surgical Sphincteroplasty Market
Surgical Instruments
Electrosurgery Market
Surgical Instruments
Neurosurgery Surgical Power Tools Market
Surgical Instruments
Absorbable Sutures Market
Surgical Instruments
Asia Pacific Surgical Equipment Market
Surgical Instruments
Dissolvable Sutures Market