
 Global Surgical Suction Instruments Market | 2026-2036
Global Surgical Suction Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surgical Suction Instruments Market Foresight
The surgical suction instruments market is rebalancing between premium integrated operating room systems and commodity-grade portable units, with procurement officers now weighting total cost of ownership against upfront capital expenditure. Stryker Corporation leverages its installed base of surgical visualization platforms to bundle suction modules, while Medtronic anchors its position through deep R&D investment in aspiration control algorithms. B. Braun Melsungen AG differentiates via vertical integration into polymer suction catheter manufacturing, controlling resin-to-device quality chains.
Surgical suction instruments are vacuum-assisted devices engineered to evacuate blood, fluids, and tissue debris from operative fields, typically operating at negative pressures between 80 and 700 mmHg depending on procedural requirements; their primary purpose is maintaining visibility and hemostasis during open, laparoscopic, and endoscopic interventions. Electric suction units dominate hospital capital budgets due to programmable pressure profiles and integration with anesthesia workstations, while disposable suction catheters capture recurring revenue streams through infection control protocols that mandate single-patient use. Deployment through integrated operating room equipment is accelerating fastest in newly constructed hybrid surgical suites where centralized suction infrastructure reduces footprint and simplifies HVAC load management.
The FDA enforces 510(k) premarket notification requirements for powered suction apparatus, while the EU MDR mandates updated clinical evidence and unique device identification for reusable suction instruments entering European markets; ISO 13485 certification shapes supplier qualification across both jurisdictions. Health Canada and Japan's PMDA impose additional electromagnetic compatibility testing that filters out low-cost entrants lacking dedicated regulatory affairs capacity. Stakeholders must monitor how post-market surveillance databases in the United States and Europe flag adverse events tied to suction tip design, as these signals increasingly trigger product modification orders ahead of scheduled refresh cycles.
Market Dynamics
The surgical suction instruments market is experiencing structural pressure from the EU MDR's sterilization mandates, which are accelerating the shift from reusable to single-use suction catheters and forcing manufacturers to redesign legacy product lines for biocompatibility compliance.
Growth Catalysts
- Outpatient procedure volume expansion:Ambulatory surgical centers in Germany and the United States are scaling portable suction unit procurement to support same-day discharge protocols and minimize capital footprint.
- ISO 13485 certification harmonization:Standardized quality management systems are reducing supplier qualification friction across FDA and PMDA jurisdictions, compressing market entry timelines for compliant manufacturers.
- Hybrid surgical suite construction:Hospital infrastructure modernization programs in Japan are embedding centralized suction infrastructure into new-build operating theaters, creating bundled equipment demand.
Market Restraints
- Polymer resin cost volatility:Suction catheter manufacturers face margin compression from fluctuating medical-grade polymer feedstock prices, particularly affecting disposable product lines with thin pricing buffers.
- Electromagnetic compliance testing burden:Health Canada and Japan's PMDA impose dedicated EMC validation requirements that filter out low-cost entrants lacking in-house regulatory affairs capacity.
- Reusable instrument obsolescence risk:The EU MDR's tightened clinical evidence requirements for reusable suction instruments are rendering legacy product portfolios non-compliant without costly redesign investment.
Strategic Opportunities
- India's hospital infrastructure buildout:Tier-2 and tier-3 cities are expanding surgical capacity under government health schemes, creating first-mover advantage for portable suction unit suppliers with localized service networks.
- AI-enabled aspiration control convergence:Machine learning algorithms for pressure modulation are integrating with existing anesthesia workstations, opening premium pricing tiers for intelligent suction modules.
- Direct-to-facility distribution channels:E-procurement platforms are disintermediating traditional medical device distributors in the United States, allowing manufacturers to capture margin previously allocated to channel intermediaries.
Industry Challenges
- Biocompatibility testing timeline compression:ISO 10993 cytotoxicity and sensitization studies for new polymer formulations are extending product development cycles by 8-14 months, delaying revenue recognition.
- Legacy HVAC integration complexity:Retrofitting centralized suction infrastructure into existing operating rooms requires coordination with hospital facilities management and often triggers unplanned infrastructure upgrade costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surgical Suction Instruments Market |
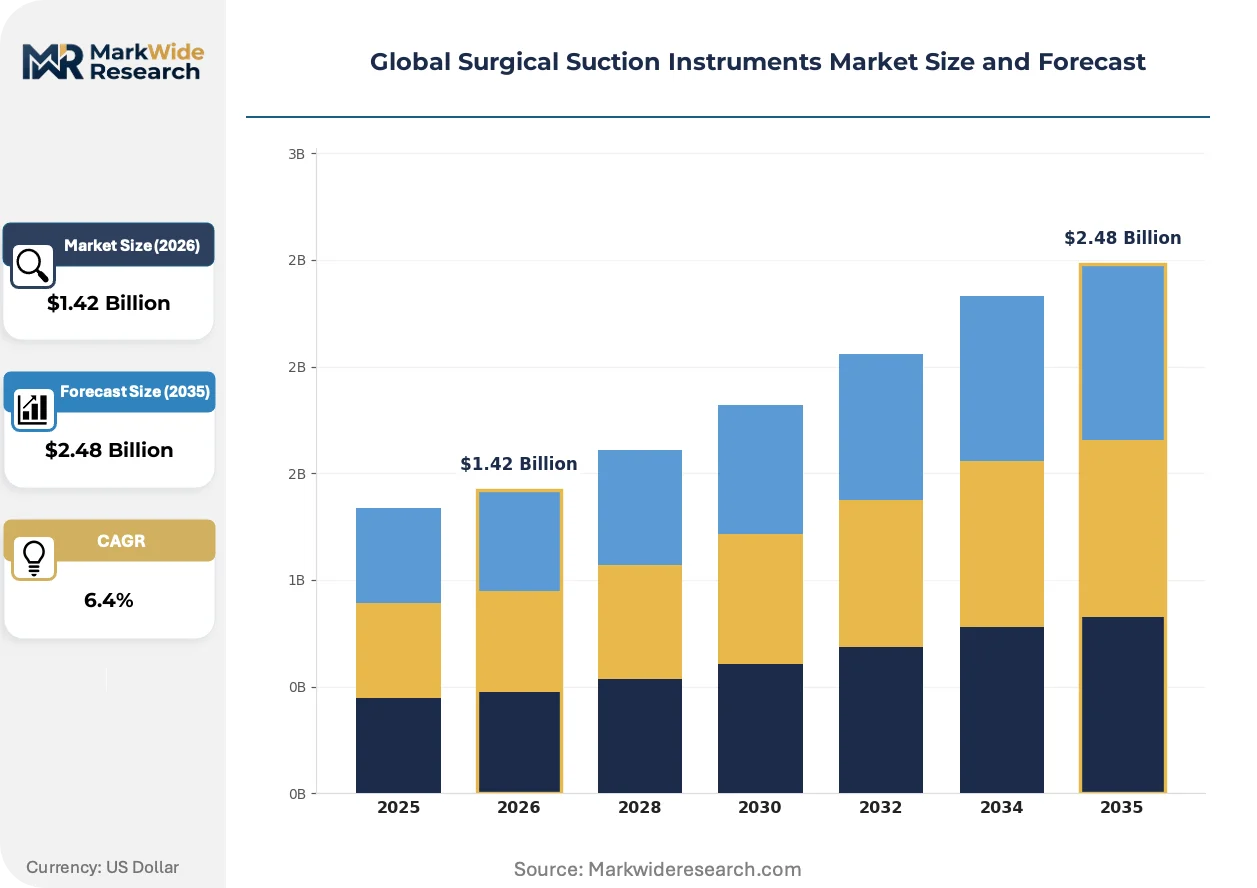
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Suction Devices, Electric Suction Units, Wall-Mounted Suction Devices, Portable Suction Machines, Disposable Suction Catheters Application: General Surgery, Neurosurgery, Orthopedic Procedures, Endoscopic Surgery, Plastic Surgery, Emergency Medicine End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Trauma Centers, Outpatient Clinics Deployment: Standalone Systems, Integrated Operating Room Equipment, Mobile Units, Centralized Suction Systems, Modular Units |
| Companies Covered | Cardinal Health, Stryker Corporation, Olympus, Medtronic, B. Braun Melsungen AG, CONMED Corporation, Teleflex Incorporated, BD, Integra Lifesciences Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surgical Suction Instruments Market Shifts & Advancements
Digital pressure sensing and closed-loop control systems are actively displacing analog suction regulators, enabling real-time aspiration adjustment that reduces tissue trauma and operative time across laparoscopic and open procedures.
Smart suction catheters with embedded pressure sensors and wireless data transmission are integrating with surgical navigation platforms, allowing anesthesia teams to monitor and adjust negative pressure remotely. Academic medical centers in Germany and the United States are piloting these connected systems in hybrid cardiac and neurosurgical suites. This convergence is compressing the traditional separation between suction hardware and surgical visualization ecosystems, forcing standalone manufacturers to develop software interfaces or risk exclusion from integrated OR tenders.
The EU MDR's unique device identification mandate for reusable suction instruments is imposing serialized traceability requirements that extend from manufacturing through sterilization cycles. Device manufacturers must now maintain post-market surveillance databases capturing adverse events tied to suction tip design, with regulatory authorities in France and Germany flagging patterns that trigger product modification orders. Reusable instrument specialists are responding by accelerating single-use portfolio development to sidestep the clinical evidence burden entirely.
Hospital procurement officers are unbundling after-sales service contracts from capital equipment purchases, demanding transparent parts pricing and third-party maintenance options for electric suction units. This behavior is most pronounced in Japan's consolidated hospital networks and Germany's university hospital systems, where centralized procurement functions negotiate multi-year total cost of ownership agreements rather than upfront capital expenditure deals. Equipment vendors are adapting by introducing modular service tiers and remote diagnostic capabilities to defend recurring revenue streams.
Global Surgical Suction Instruments Market Segmentation
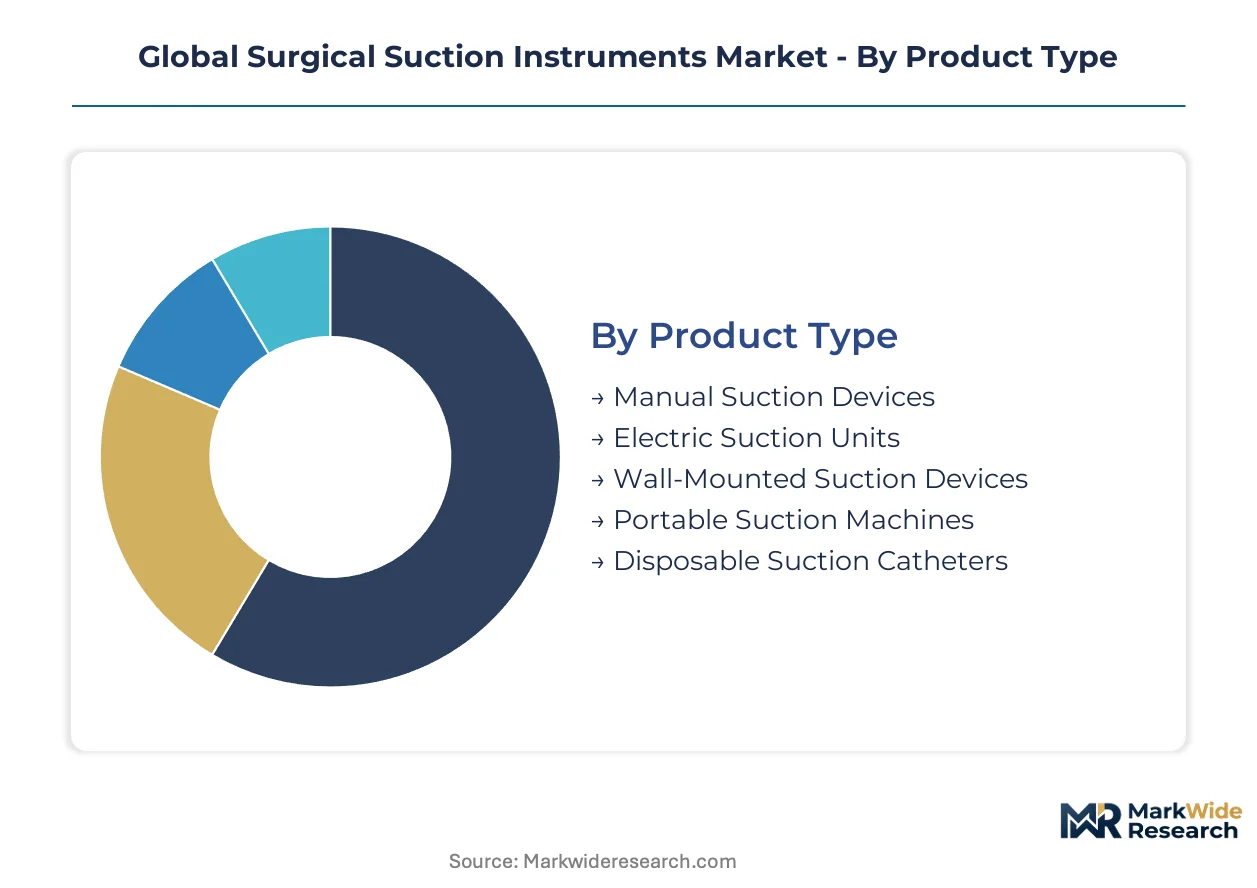
Segmentation in surgical suction instruments reveals how procurement priorities diverge between capital-intensive hospital infrastructure and cost-sensitive outpatient settings. Equipment replacement cycles and regulatory compliance timelines vary sharply across product categories, creating distinct competitive arenas for manufacturers.
Product Type:
Upgrade cycles for powered suction apparatus are compressing as digital pressure modulation displaces analog controls, while single-use catheter portfolios expand to offset reusable instrument obsolescence under EU MDR.
- Electric Suction Units:Programmable negative pressure modules operating between 80-700 mmHg dominate hospital capital budgets through integration with anesthesia workstations. Demand concentrates in Germany and Japan where hybrid surgical suite construction mandates centralized infrastructure with remote monitoring capabilities.
- Disposable Suction Catheters:Single-use polymer devices capture recurring revenue streams through infection control protocols mandating single-patient use. Procurement is accelerating in United States ambulatory surgical centers seeking to eliminate sterilization logistics and comply with Joint Commission standards.
- Manual Suction Devices:Hand-operated vacuum systems serve backup power failure scenarios and resource-constrained settings.
- Wall-Mounted Suction Devices:Fixed infrastructure common in older operating theater designs facing retrofit complexity.
- Portable Suction Machines:Battery-powered units address emergency transport and field deployment requirements.
Volume placements concentrate in Disposable Suction Catheters; the faster expansion belongs to Electric Suction Units.
Application:
Procedure-specific suction requirements create tiered performance specifications, with high-precision neurosurgical applications commanding premium pricing against commoditized general surgery segments.
- General Surgery:Open abdominal and thoracic procedures utilize high-volume aspiration for blood and irrigation fluid evacuation. Demand clusters in United States hospital systems performing high-throughput elective procedures with standardized equipment protocols.
- Neurosurgery:Microsurgical suction demands ultra-low pressure precision to prevent neural tissue damage, driving adoption of closed-loop digital control systems. Academic medical centers in Germany and Japan are piloting AI-enabled pressure modulation in hybrid suites.
- Orthopedic Procedures:Bone debris and marrow aspiration require robust filtration and clog-resistant tip designs.
- Endoscopic Surgery:Laparoscopic suction integrates with insufflation systems for smoke evacuation and fluid management.
- Plastic Surgery:Liposuction and tissue reconstruction utilize specialized cannula configurations with tumescent fluid handling.
- Emergency Medicine:Pre-hospital and trauma bay suction prioritizes rapid deployment and ruggedized construction.
Revenue concentration sits with General Surgery; Neurosurgery is gaining share fastest through technology premium capture.
End User:
Customer-type segmentation exposes diverging procurement authority structures, with consolidated hospital networks negotiating multi-year total cost of ownership agreements against fragmented clinic spot purchasing.
- Hospitals:Integrated delivery networks in Japan and Germany bundle suction equipment into centralized infrastructure tenders with 7-10 year service contracts. These accounts demand ISO 13485-certified suppliers with dedicated regulatory affairs capacity for FDA and PMDA submissions.
- Ambulatory Surgical Centers:Same-day discharge protocols in United States outpatient facilities are scaling portable unit procurement to minimize capital footprint and HVAC load. E-procurement platforms are disintermediating traditional distributors in this segment.
- Specialty Clinics:Ophthalmology and dermatology practices require procedure-specific suction configurations.
- Trauma Centers:Level I facilities mandate redundant suction capacity with emergency power backup.
- Outpatient Clinics:Primary care and urgent care settings utilize basic suction for minor procedures.
Contract value concentrates in Hospitals; Ambulatory Surgical Centers are expanding most quickly through outpatient volume migration.
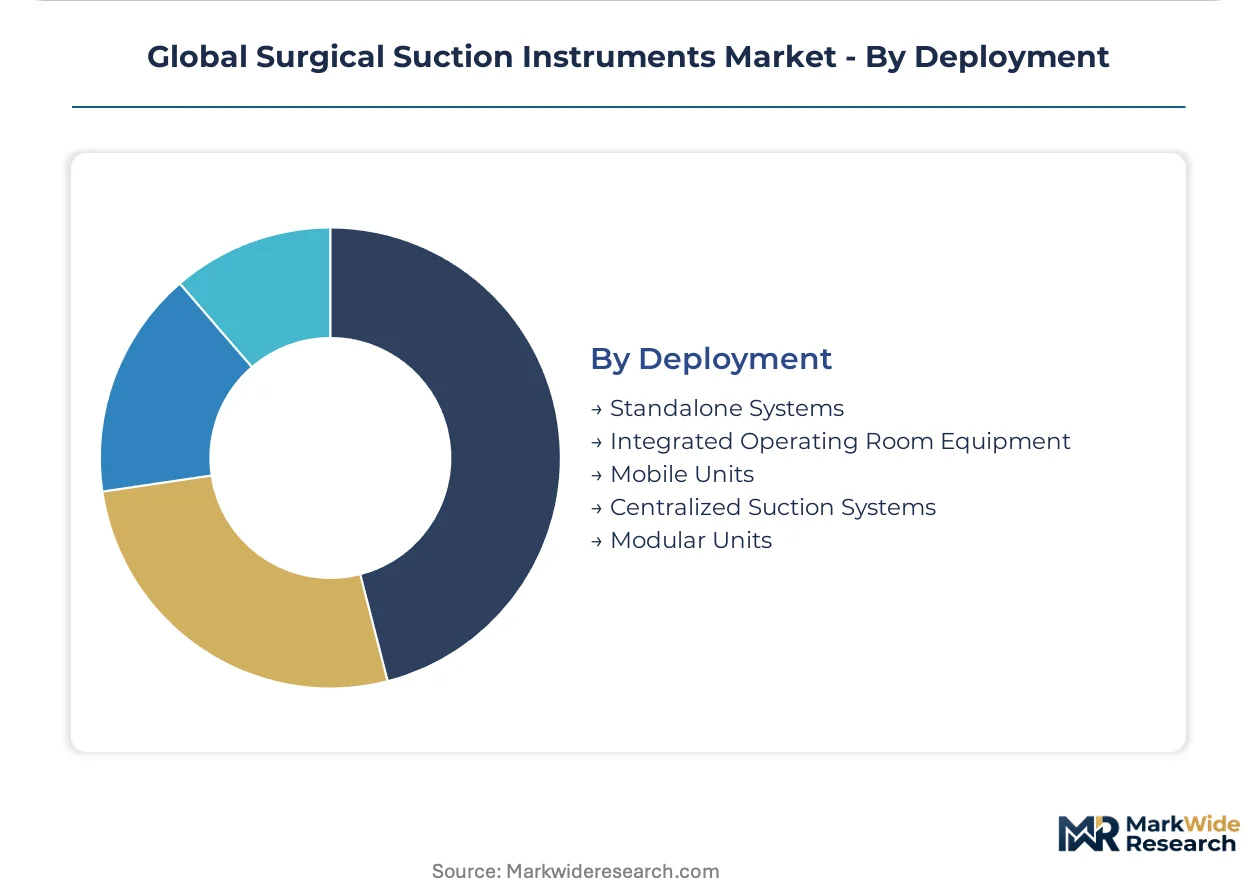
Deployment:
Physical integration architecture determines competitive access routes, with modular designs enabling incremental upgrade paths against standalone equipment replacement cycles.
- Integrated Operating Room Equipment:Ceiling-mounted and boom-integrated suction infrastructure reduces floor footprint and coordinates with surgical lighting and visualization systems. New-build hybrid suites in Japan are embedding these configurations with centralized HVAC management.
- Centralized Suction Systems:Pipeline networks serving multiple operating theaters require hospital facilities coordination and trigger unplanned infrastructure upgrade costs during retrofit scenarios.
- Standalone Systems:Electric suction units on mobile carts serve flexible room utilization in smaller facilities.
- Mobile Units:Battery-powered and wheeled configurations address intra-hospital transport and temporary procedure setups.
- Modular Units:Component-based designs allow pressure generator separation from collection canisters for customized configurations.
Installed base concentrates in Standalone Systems; Integrated Operating Room Equipment is climbing the fastest through new construction preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo anchors surgical suction instrument procurement through Japan's concentrated hospital infrastructure modernization, with hybrid surgical suite construction driving integrated equipment demand across the Kanto region.
United States
Ambulatory surgical centers in Texas and Florida are scaling portable suction unit procurement to support same-day discharge protocols. The FDA enforces 510(k) premarket notification requirements for powered suction apparatus. Hospital networks in the Greater Boston area are piloting AI-enabled aspiration control systems in academic medical centers.
Germany
University hospital systems in Bavaria and North Rhine-Westphalia negotiate multi-year total cost of ownership agreements for electric suction units. The EU Medical Device Regulation mandates updated clinical evidence and unique device identification for reusable instruments. Medical technology clusters around Tübingen and Leipzig are developing smart suction catheters with embedded pressure sensors.
Japan
Metropolitan hospital networks in Osaka and Nagoya are embedding centralized suction infrastructure into new-build hybrid surgical suites. Japan's PMDA imposes electromagnetic compatibility testing that filters out low-cost entrants. The Chubu region around Nagoya is consolidating procurement through integrated delivery networks with 7-10 year service contracts.
India
Tier-2 cities in Maharashtra and Gujarat are expanding surgical capacity under government health schemes, creating demand for portable suction units. The Central Drugs Standard Control Organization regulates medical device imports and local manufacturing. Medical device manufacturing zones in Hyderabad and Chennai are attracting contract manufacturers for disposable suction catheters.
United Kingdom
NHS trusts in London and the Midlands are unbundling after-sales service contracts from capital equipment purchases for electric suction units. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR requirements post-Brexit. Research hospitals in Cambridge and Oxford are testing closed-loop digital control systems for neurosurgical applications.
Global Surgical Suction Instruments Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory certification depth, with ISO 13485-certified manufacturers capturing hospital infrastructure tenders while non-certified suppliers serve price-sensitive outpatient segments. The vendor base stratifies into three tiers: diversified medical technology conglomerates with anesthesia workstation integration capabilities, specialized suction instrument manufacturers with captive polymer production, and regional assemblers dependent on imported pressure generator components. Dominant competitive moves include backward integration into medical-grade polymer resin supply and strategic partnerships with e-procurement platforms to disintermediate traditional distributors.
Among diversified medical technology conglomerates, Stryker Corporation and Medtronic exemplify the premium-tier archetype through deep installed bases in surgical visualization and anesthesia platforms. B. Braun Melsungen AG occupies a distinct position through upstream control over polymer suction catheter manufacturing. These three anchors represent contrasting strategic postures: equipment-led bundling, algorithm-driven aspiration control, and resin-to-device quality chain management.
| Leading Market Players |
|---|
| Cardinal Health |
| Stryker Corporation |
| Olympus |
| Medtronic |
| B. Braun Melsungen AG |
| CONMED Corporation |
| Teleflex Incorporated |
| BD |
| Integra Lifesciences Holdings Corporation |
| Others |
Supply & Pricing Matrix
Medical-grade polymer resin costs cascade through three distinct pricing tiers, with ISO 13485-certified manufacturers in Germany and Japan commanding premiums for captive supply chains while non-certified assemblers in India compete on spot-market catheter pricing.
Pricing Analysis
Throughput-linked contracts anchor hospital procurement, with electric suction units priced against guaranteed uptime and disposable catheters indexed to procedure volumes. Certification grade and after-sales service bundling separate premium-tier vendors from economy suppliers. Cost compression in disposable lines intensifies because polymer feedstock volatility erodes thin margins. Ambulatory surgical centers exhibit highest price sensitivity, demanding transparent parts pricing and third-party maintenance options.
Supply Chain Analysis
India's phased domestic-content mandates for government health scheme procurement are reshaping sourcing patterns, pushing multinational catheter manufacturers toward Hyderabad and Chennai contract facilities. Polymer resin supply concentrates in Germany, the United States, and Japan; pressure generators and precision sensors draw from South Korean and Japanese component specialists. Single-source vulnerability in medical-grade silicone feedstock poses structural risk. Distribution runs through hospital GPOs and e-procurement platforms in the United States, direct tenders in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into polymer manufacturing and captive sterilization capacity defines competitive positioning, with EU MDR compliance costs making in-house biocompatibility testing an essential defensive lever.
For Market Incumbents: Deepen control over resin-to-device quality chains to offset margin pressure from reusable instrument obsolescence under EU MDR sterilization mandates. Expand ISO 13485-certified production footprint in India to capture government health scheme volume while defending premium positioning in German and Japanese hospital tenders through anesthesia workstation integration. For New Entrants and Emerging Players: E-procurement platform partnerships offer the lowest-friction route to ambulatory surgical center accounts in the United States, bypassing traditional distributor markups. Target tier-2 Indian cities with portable suction units featuring localized service networks, leveraging CDSCO regulatory pathways for import substitution. For Investors and Strategic Acquirers: AI-enabled aspiration control FDA submissions are the leading indicator that algorithm-driven pressure modulation will capture premium pricing tiers. Position for five-to-ten year consolidation around software-integrated suction modules, prioritizing targets with embedded sensor development capabilities and existing anesthesia workstation partnerships.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements filter out non-compliant reusable instrument portfolios. |
| Hospital System Partnership | Integrated delivery networks in Japan and Germany bundle 7-10 year service contracts with capital purchases. |
| Software Companion Development | Closed-loop pressure modulation algorithms integrate with existing anesthesia workstations for premium positioning. |
| Backward Integration | Captive polymer catheter manufacturing insulates margins from resin cost volatility and biocompatibility timeline compression. |
| Reimbursement Strategy | Same-day discharge protocol alignment drives ambulatory surgical center procurement of portable units. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospital procurement managers, biomedical engineers, GPO contracts specialists, and regulatory affairs leads at device manufacturers. FDA 510(k) databases, EU MDR notified body submissions, PMDA approval records, and hospital capital expenditure disclosures provided segmentation baselines. Bottom-up unit economics and top-down spending allocation models were triangulated against clinician procedure volume estimates.
Data-stream reconciliation across the projection horizon employed product-type, application, end-user, and deployment architecture dimensions. CAGRs derived from installed base replacement cycles, outpatient procedure migration rates, and hybrid surgical suite construction pipelines. Modeled inputs included ISO 13485 certification penetration by supplier tier and AI-enabled aspiration control adoption curves in academic medical centers.
Inputs from regulatory submission databases and hospital procurement platforms were available through the study window; gaps in real-time polymer resin pricing and confidential contract terms introduce uncertainty bands around margin projections. Forecasts reflect documented assumptions about EU MDR enforcement consistency and ambulatory surgical center construction rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Retractable Needles Market
Surgical Instruments
Disposable Ophthalmic Surgical Products Market
Surgical Instruments
US Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
Global Veterinary Surgical Instruments Market
Surgical Instruments
India Surgical Sutures Market
Surgical Instruments
Knotless Tissue Control Devices Market
Surgical Instruments
Gynecology Surgical Instruments Market
Surgical Instruments
Monopolar Electrosurgery Instrument Market
Surgical Instruments
Thoracic Surgery Market
Surgical Instruments
Resectoscopes Market
Surgical Instruments
Brazil General Surgical Devices Market
Surgical Instruments
Global Surgical Scalpel Market
Surgical Instruments
Medical Penlights Market
Surgical Instruments
Absorbable Surgical Suture with Needle Market
Surgical Instruments
Surgical Clips Market
Surgical Instruments
Middle East and Africa Lancet and Pen Needles Market