
 Global Surgical Instrument Tracking System Market | 2026-2036
Global Surgical Instrument Tracking System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surgical Instrument Tracking System Market Foresight
Silicon-based RFID inlays is broadening the addressable market for high-temperature sterilization environments previously closed to polymer tags. Fortive Corporation leverages its Fluke Health Solutions platform to sustain recurring software revenue across integrated health networks. Becton Dickinson and Company anchors its position through end-to-end medication management systems that incorporate surgical asset traceability. STERIS competes by embedding tracking modules directly into sterilization equipment workflows, creating captive demand for its consumables.
A surgical instrument tracking system combines auto-identification hardware with software platforms to record the location, usage history, and sterilization status of reusable medical instruments throughout clinical workflows. RFID tags rated for autoclave cycles exceeding 1,000 exposures at 134°C now dominate durable tagging applications, replacing laser-etched barcodes that degrade under repeated thermal stress. Radio Frequency Identification leads technology adoption due to its non-line-of-sight readability through surgical trays and linens, though Bluetooth Low Energy represents the fastest-growing segment as battery efficiency improves for mobile-enabled point-of-use documentation. Cloud-Based deployment captures expanding margin pools as hospitals shift capital expenditure to operational expenditure models, while On-Premise installations retain dominance among defense and government healthcare facilities with stringent data sovereignty requirements.
The FDA's Unique Device Identification rule shapes demand by mandating standardized device identifiers across the US supply chain, while the EU Medical Device Regulation requires enhanced traceability documentation for Class IIa and higher instruments entering European markets. ISO 13485 quality management certification functions as a de facto market access gate for software vendors serving regulated health systems. Stakeholders must monitor convergence between instrument tracking data and AI-driven predictive maintenance platforms as the next frontier for differentiation.
Market Dynamics
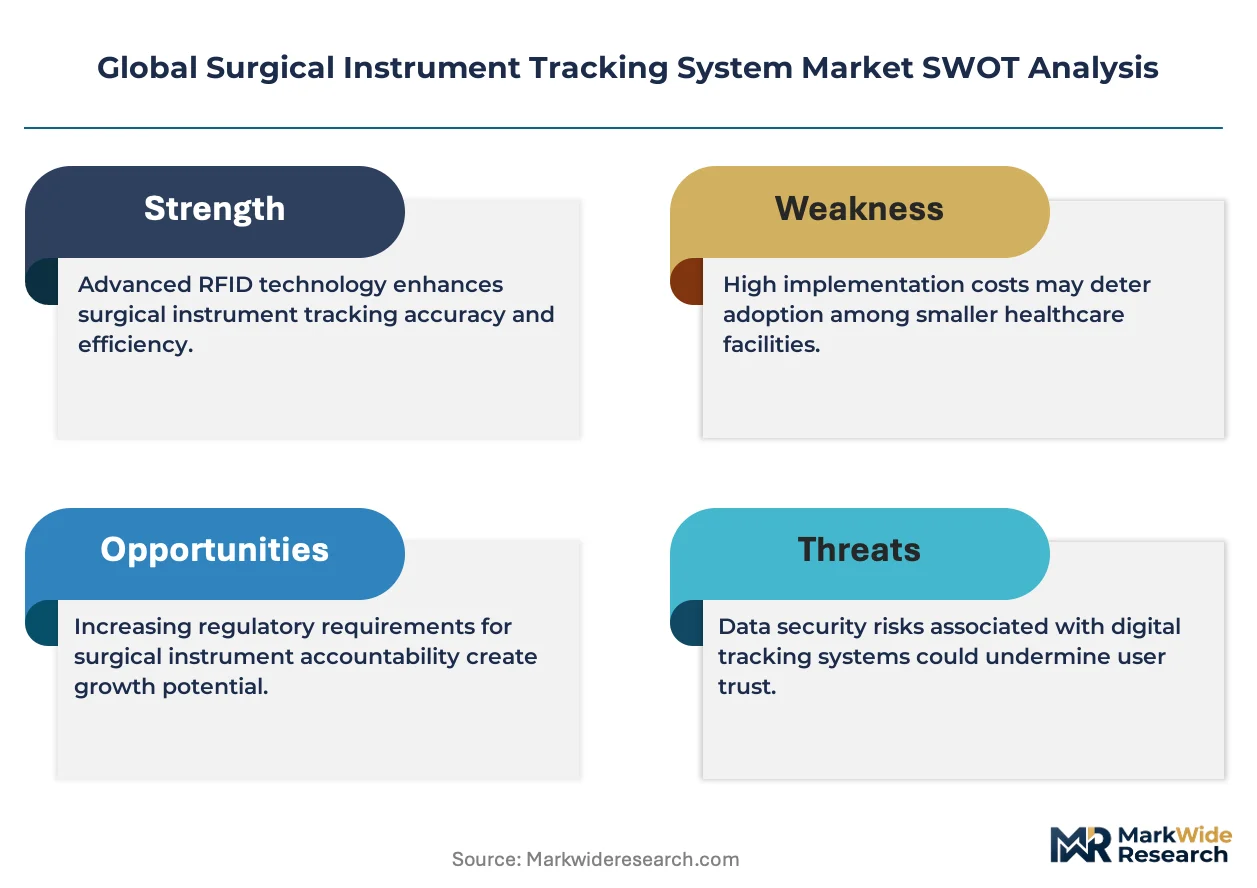
RFID sterilization-grade tagging is consolidating procurement decisions around single-vendor platform ecosystems, compressing the addressable supplier base while elevating software-integrated hardware bundles over standalone tag transactions.
Growth Catalysts
- FDA UDI Mandate:The Unique Device Identification rule compels US hospitals to deploy automated traceability infrastructure, creating immediate replacement demand for legacy barcode systems in surgical supply chains.
- Silicon RFID Thermal Resistance:Tags rated for 1,000+ autoclave cycles at 134°C now penetrate instrument sets previously excluded from electronic tracking due to polymer degradation limits.
- Ambulatory Surgery Center Expansion:Freestanding ASC networks in the United States are deploying real-time location systems to meet Joint Commission accreditation standards without enterprise hospital IT overhead.
Market Restraints
- RFID Inlay Supply Concentration:High-temperature silicon inlay production concentrates among Southeast Asian semiconductor packaging houses, exposing buyers to substrate cost volatility and single-source risk.
- Legacy Capital Lock-In:Hospitals with depreciated laser-etching infrastructure face stranded asset risk when migrating to RFID, delaying full-system replacement timelines.
- EU MDR Documentation Burden:The Medical Device Regulation's enhanced traceability requirements for Class IIa instruments impose compliance costs that deter mid-tier European manufacturers from market entry.
Strategic Opportunities
- Bluetooth Low Energy Convergence:BLE tag battery efficiency improvements enable mobile point-of-use documentation in sterile corridors, opening workflow capture previously requiring fixed RFID portal infrastructure.
- Cloud Subscription Migration:Health systems in Germany and France are shifting capital expenditure to operational expenditure models, expanding recurring software revenue pools for platform vendors.
- AI Predictive Maintenance Integration:Instrument usage data streams from tracking systems are converging with machine learning platforms to forecast sterilization equipment maintenance, creating adjacent service revenue.
Industry Challenges
- ISO 13485 Certification Timeline:Software vendors face 12-18 month quality management system audits to serve regulated health systems, compressing competitive response windows.
- Interoperability Fragmentation:Proprietary data formats between sterilizer OEMs and tracking software platforms force expensive middleware development for hospital IT departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surgical Instrument Tracking System Market |
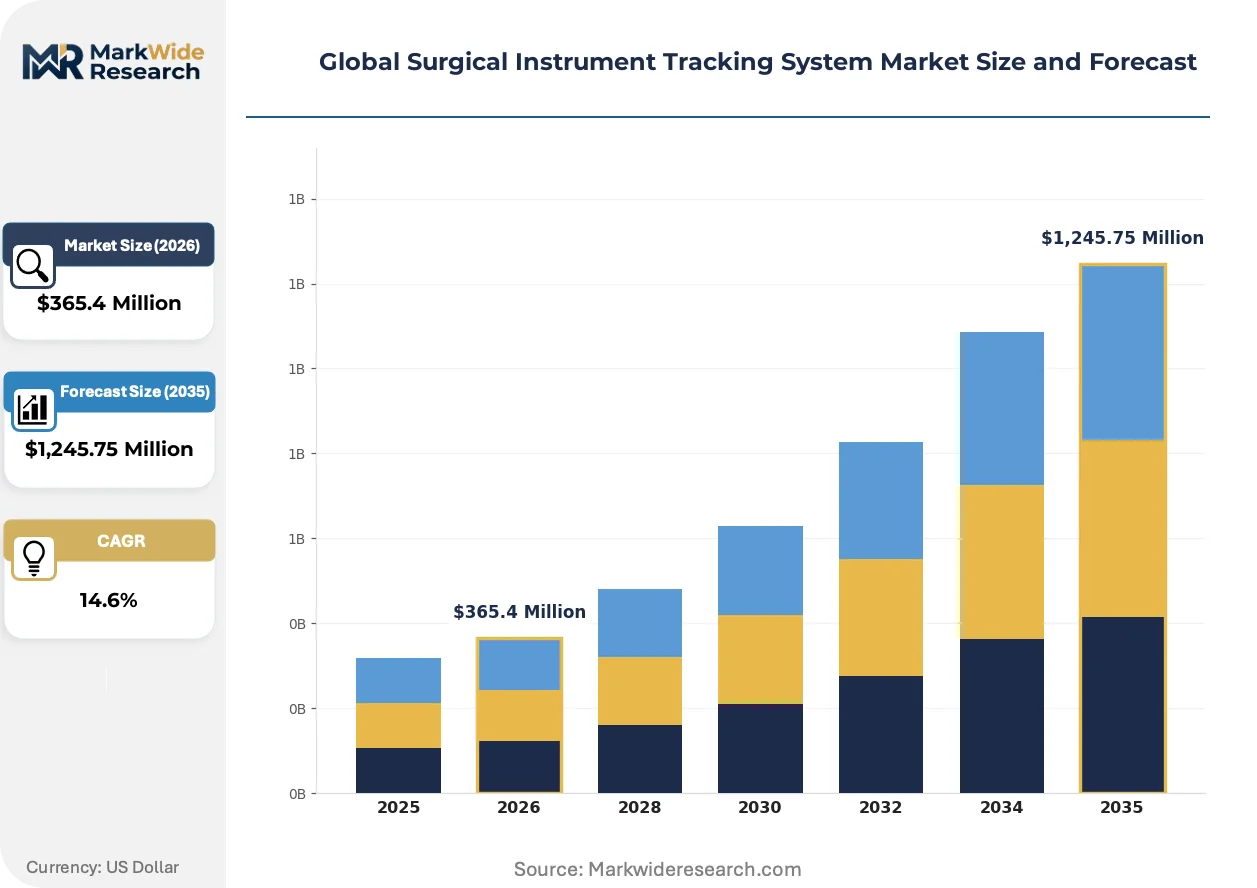
| Market Size in 2026 | $365.4 Million |
| Market Size in 2035 | $1,245.75 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Radio Frequency Identification, Barcode Scanning, Near Field Communication, Bluetooth Low Energy, Ultrasound Tracking End User: Hospitals, Ambulatory Surgery Centers, Diagnostic Laboratories, Specialty Clinics, Medical Device Manufacturers Application: Instrument Sterilization Monitoring, Inventory Management, Surgical Workflow Optimization, Asset Management, Compliance Reporting Deployment: On-Premise, Cloud-Based, Hybrid Solutions, Mobile-Enabled Platforms, Software as a Service |
| Companies Covered | Fortive Corporation, Becton Dickinson and Company, STERIS, Getinge AB, B. Braun SE, Censis Technologies, Mobile Aspects, Xerafy, SpaTrack Medical Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surgical Instrument Tracking System Market Shifts & Advancements
Sterilization-grade RFID is consolidating hardware procurement around integrated platform vendors while regulatory mandates accelerate compliance technology refresh cycles across multiple geographies.
Silicon-based RFID inlays rated for 1,000+ autoclave exposures are consolidating durable tagging applications against laser-etched barcodes that degrade under thermal stress. United States academic medical centers are adopting these tags at replacement cycle points for legacy instrument sets. The technology is consolidating vendor selection criteria around thermal durability certifications rather than unit cost alone.
The EU Medical Device Regulation's traceability documentation requirements for Class IIa and higher instruments are reshaping European supply chain data architecture. Manufacturers must now maintain device history records accessible across the distribution chain. German and French hospital groups are responding by mandating RFID-native instrument sourcing in procurement tenders.
Subscription-based cloud deployment is displacing perpetual license models among non-government health systems seeking to convert capital expenditure to operational expenditure. United States integrated delivery networks are leading this transition, unbundling software maintenance from hardware tag purchases. The shift concentrates margin capture with vendors offering integrated hardware-software-recurring service bundles.
Global Surgical Instrument Tracking System Market Segmentation
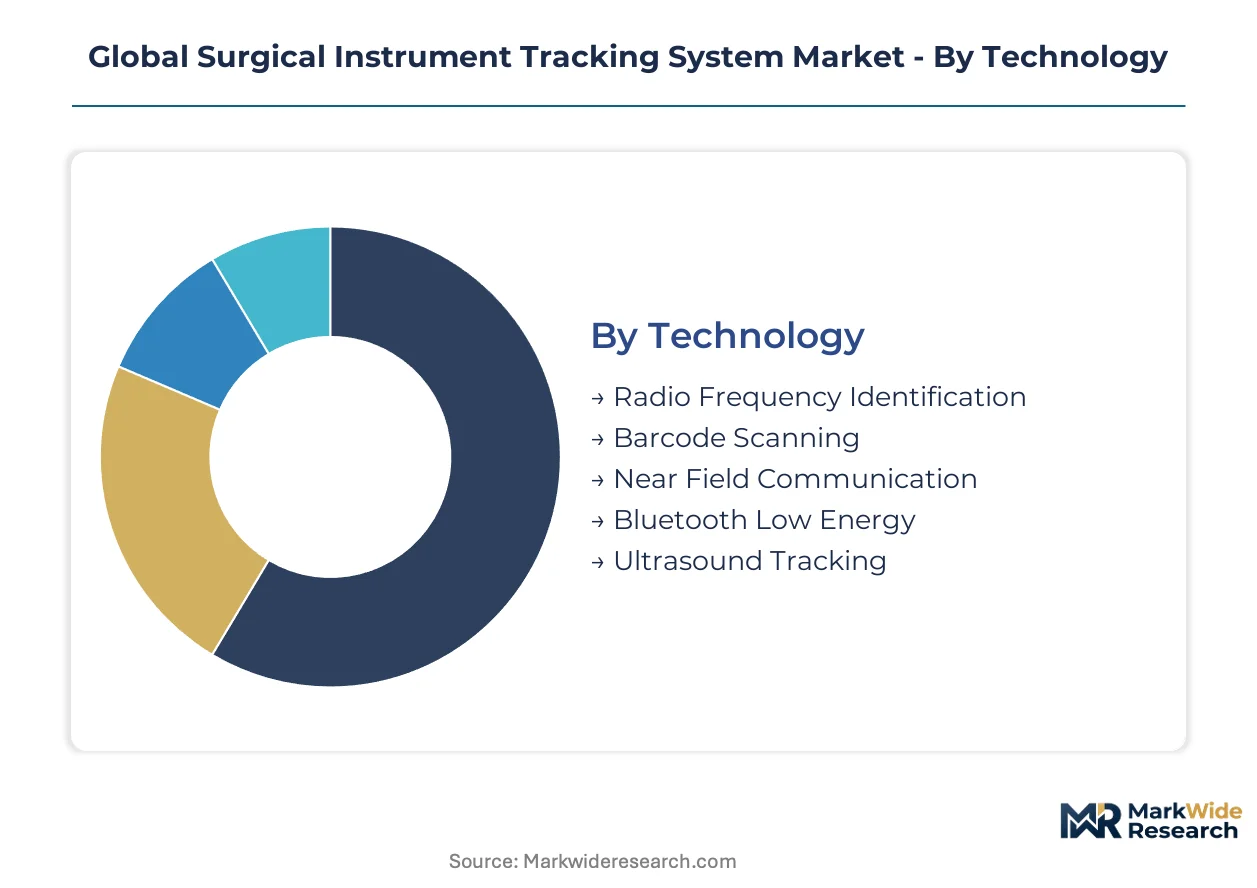
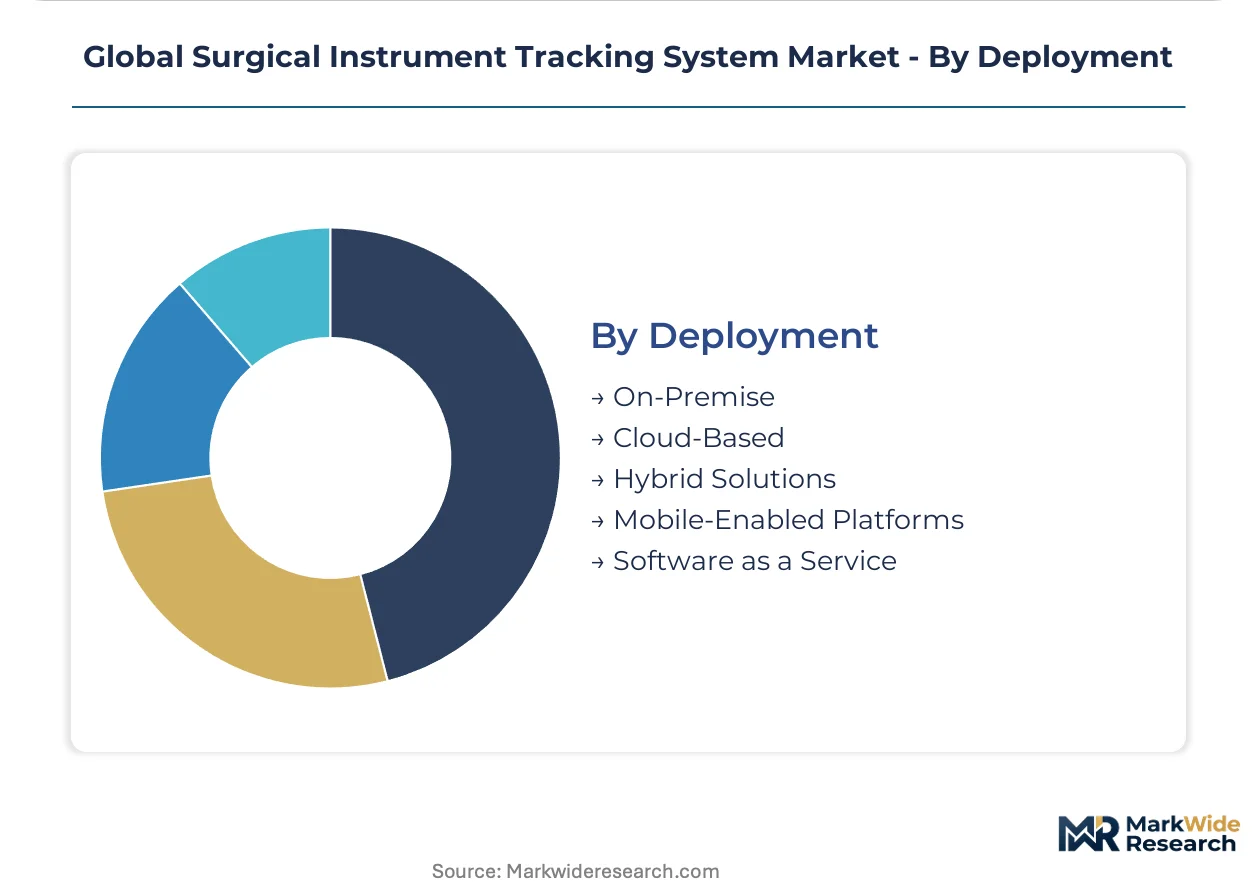
Technology selection in surgical instrument tracking determines sterilization compatibility, read range, and total cost of ownership across clinical workflows. Deployment architecture shapes capital allocation and cybersecurity posture for health system procurement committees.
Technology:
Buyer decisions pivot on thermal durability and read reliability through surgical linens and metal instrument trays.
- Radio Frequency Identification:Silicon inlays rated for 1,000+ autoclave cycles at 134°C dominate durable tagging. United States academic medical centers are replacing laser-etched barcodes at instrument set refresh points due to thermal degradation limits.
- Bluetooth Low Energy:Battery efficiency improvements now enable mobile point-of-use documentation in sterile corridors. German hospital groups are piloting BLE for workflow capture previously requiring fixed RFID portal infrastructure.
- Barcode Scanning:Legacy infrastructure in depreciated hospital systems faces stranded asset risk during RFID migration.
- Near Field Communication:Short-range contact requirements limit adoption to verification checkpoints rather than continuous tracking.
- Ultrasound Tracking:Niche applications in metal-dense environments where RF interference disrupts standard tag performance.
Volume sits with Radio Frequency Identification; growth tilts toward Bluetooth Low Energy.
End User:
Facility scale determines IT overhead tolerance and regulatory compliance automation requirements.
- Hospitals:Enterprise health systems in the United States deploy integrated hardware-software bundles across multiple surgical suites. The FDA's UDI mandate compels automated traceability infrastructure replacement for legacy barcode systems.
- Ambulatory Surgery Centers:Freestanding networks require real-time location systems without enterprise hospital IT overhead. Joint Commission accreditation standards are driving RFID adoption among United States ASC expansions.
- Diagnostic Laboratories:Specimen tracking convergence with instrument traceability creates bundled procurement opportunities.
- Specialty Clinics:Limited sterilization volumes favor lower-cost barcode solutions over capital-intensive RFID deployment.
- Medical Device Manufacturers:EU MDR traceability documentation requirements for Class IIa instruments are mandating RFID-native sourcing in German and French procurement tenders.
Revenue concentrates with Hospitals; Ambulatory Surgery Centers are expanding most quickly.
Application:
Workflow integration depth separates point solutions from platform ecosystems in vendor selection.
- Instrument Sterilization Monitoring:Cycle count logging and thermal exposure tracking ensure FDA compliance for reusable device reprocessing. STERIS embeds tracking modules directly into sterilization equipment workflows to create captive consumables demand.
- Surgical Workflow Optimization:Real-time instrument location data reduces case delays and improves operating room turnover. United States integrated delivery networks prioritize this application for throughput gains.
- Inventory Management:Par level automation reduces manual counts but competes with established ERP system investments.
- Asset Management:Capital equipment tracking extends beyond instruments to endoscopes and powered surgical devices.
- Compliance Reporting:EU MDR device history record requirements are reshaping European supply chain data architecture toward automated documentation.
Adoption is deepest in Instrument Sterilization Monitoring; Surgical Workflow Optimization is gaining share fastest.
Deployment:
Capital expenditure constraints versus data sovereignty requirements drive architecture selection.
- Cloud-Based:Subscription models convert capital expenditure to operational expenditure for non-government health systems. United States integrated delivery networks are unbundling software maintenance from hardware tag purchases.
- On-Premise:Defense and government healthcare facilities with stringent data sovereignty requirements retain local server installations. HIPAA compliance automation favors controlled infrastructure environments.
- Hybrid Solutions:Edge computing for real-time sterilization data with cloud analytics for enterprise reporting.
- Mobile-Enabled Platforms:Point-of-use documentation via smartphone and tablet applications reduces fixed infrastructure requirements.
- Software as a Service:Recurring revenue concentration with vendors offering integrated hardware-software-service bundles.
Installed base favors On-Premise; Cloud-Based deployment shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Shenzhen and Shanghai concentrate RFID component manufacturing for surgical instrument tracking systems serving hospitals worldwide. These zones attract semiconductor packaging houses through tax incentives and streamlined customs procedures. Production clusters here supply silicon inlays rated for 1,000+ autoclave cycles.
United States
Academic medical centers in Boston and the Research Triangle replace legacy laser-etched barcodes with sterilization-grade RFID at instrument set refresh points. The FDA's Unique Device Identification rule compels automated traceability infrastructure deployment across surgical supply chains. Integrated delivery networks in Texas and California prioritize surgical workflow optimization applications for operating room throughput gains.
Germany
Hospital groups in Bavaria and North Rhine-Westphalia mandate RFID-native instrument sourcing in procurement tenders to satisfy EU Medical Device Regulation traceability requirements. The country's national pharmaceutical regulator enforces enhanced documentation standards for Class IIa and higher reusable devices. Medical technology clusters around Tübingen and Erlangen develop sterilization equipment with embedded tracking modules.
Japan
Metropolitan Tokyo hospitals deploy real-time location systems to manage high-volume surgical instrument inventories across multiple facilities. METI promotes smart hospital infrastructure investments through subsidized digital transformation programs. Osaka-based medical device manufacturers integrate tracking capabilities into sterilization workflows for export markets.
United Kingdom
NHS trusts in London and the Midlands convert capital expenditure to operational expenditure through cloud-based subscription models for instrument tracking software. The country's national pharmaceutical regulator aligns post-Brexit device traceability requirements with residual EU MDR frameworks. Cambridge health technology clusters pilot Bluetooth Low Energy mobile documentation in sterile corridors.
France
Public hospital networks in Île-de-France and Auvergne-Rhône-Alpes unbundle software maintenance from hardware tag purchases under recurring revenue contracts. ANSM enforces device history record accessibility across distribution chains for regulated instruments. Lyon medical device sterilization facilities adopt hybrid edge-cloud architectures for real-time cycle count logging.
Global Surgical Instrument Tracking System Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors capturing software-integrated hardware bundles while standalone tag suppliers face margin compression. The market structure concentrates procurement decisions around single-vendor ecosystems capable of delivering end-to-end traceability infrastructure. Three archetypes dominate: sterilization equipment OEMs embedding tracking modules, health technology conglomerates leveraging recurring software platforms, and RFID component specialists supplying thermal-resistant inlays. Competitive moves center on strategic partnerships between sterilizer manufacturers and software developers, plus geographic expansion through cloud subscription models that convert hospital capital expenditure to operational expenditure.
Among diversified health technology conglomerates, Fortive Corporation and Becton Dickinson and Company exemplify platform-centric positioning that anchors recurring revenue across integrated health networks. STERIS represents the sterilization equipment OEM archetype, embedding tracking capabilities directly into reprocessing workflows. These three companies occupy positions that illustrate how vendor selection criteria increasingly prioritize thermal durability certifications and software integration depth over unit cost considerations alone.
| Leading Market Players |
|---|
| Fortive Corporation |
| Becton Dickinson and Company |
| STERIS |
| Getinge AB |
| B. Braun SE |
| Censis Technologies |
| Mobile Aspects |
| Xerafy |
| SpaTrack Medical Limited |
| Others |
Supply & Pricing Matrix
Silicon wafer substrate costs cascade through sterilization-grade RFID inlay production into three-tier pricing structures across premium, standard, and economy levels for health system procurement committees. Thermal durability certifications and ISO 13485 compliance tiers separate vendor quotations as United States integrated delivery networks negotiate bundled hardware-software-service contracts against standalone tag purchases.
Pricing Analysis
Short lead-time premiums attach to silicon inlay orders from Southeast Asian semiconductor packaging houses facing capacity constraints, while spot inventory discounts emerge for legacy polymer tags in depreciated hospital systems. Subscription-based SaaS models dominate cloud deployment segments, with price differentiation resting on thermal cycle certification levels and after-sales service bundling. Cost compression in standard-tier RFID tags is intensifying because Chinese substrate suppliers are expanding high-temperature packaging capacity. Ambulatory surgery centers exhibit highest price sensitivity due to constrained capital budgets, while United States academic medical centers prioritize certification depth over unit cost.
Supply Chain Analysis
Freight cost volatility from Southeast Asian semiconductor packaging hubs to German and United States hospital distribution centers is reshaping procurement timing strategies for sterilization-grade inlay shipments. Supply concentrates in Malaysia, Thailand, and Vietnam for silicon substrate processing, with raw material dependencies spanning high-purity silicon wafers, autoclave-resistant adhesives, and antenna-grade copper etching chemicals. Single-source vulnerability permeates high-temperature inlay production as substrate cost swings transmit directly to tag pricing. Distribution runs through sterilization equipment OEM direct sales forces and health technology distributors serving integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Surgical Instrument Tracking System Market sits in a technology-transition phase as silicon-based RFID inlays displace laser-etched barcodes that degrade under repeated autoclave thermal stress.
For Market Incumbents: Anchor recurring revenue streams through cloud subscription migration that converts hospital capital expenditure to operational expenditure, while embedding tracking modules directly into sterilization equipment workflows to create captive consumables demand. Fortify ISO 13485 certification depth against emerging software vendors facing 12-18 month quality management system audit timelines. Prioritize backward integration into silicon inlay supply relationships to mitigate Southeast Asian substrate cost volatility. For New Entrants and Emerging Players: Launch via mobile-enabled Bluetooth Low Energy platforms targeting ambulatory surgery centers in United States expansion markets, where Joint Commission accreditation standards drive RFID adoption without enterprise hospital IT overhead. Exploit interoperability fragmentation between sterilizer OEMs and incumbent tracking software platforms by offering middleware solutions that bridge proprietary data formats. Focus initial deployment on surgical workflow optimization applications rather than sterilization monitoring where STERIS maintains embedded advantages. For Investors and Strategic Acquirers: FDA UDI mandate enforcement acceleration is the leading indicator that replacement demand for legacy barcode infrastructure will concentrate procurement decisions around integrated platform vendors capable of delivering end-to-end traceability. Long-term viability favors sterilization equipment OEMs with embedded tracking modules and health technology conglomerates leveraging recurring software platforms across integrated health networks. Monitor EU MDR traceability documentation compliance timelines as signals for European market entry opportunity windows.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Subscription Migration | Converts hospital capital expenditure to operational expenditure across United States integrated delivery networks. |
| Silicon Inlay Backward Integration | Secures thermal-resistant substrate supply against Southeast Asian packaging house concentration risk. |
| BLE Mobile Platform Launch | Captures ambulatory surgery center expansion without fixed RFID portal infrastructure requirements. |
| ISO 13485 Certification Investment | Functions as de facto market access gate for software vendors serving regulated health systems. |
| AI Predictive Maintenance Integration | Converges instrument usage data streams with machine learning platforms for adjacent service revenue. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, sterilization equipment OEM technical directors, and biomedical engineering leads underwrites the qualitative findings in this study. Primary fieldwork with GPO contracts managers and health system supply chain executives combined with secondary validation from FDA UDI guidance documents, EU MDR regulatory texts, and hospital procurement database disclosures. Bottom-up instrument set refresh cycle analysis and top-down health technology spending pattern triangulation anchored segmentation sizing.
Rate-of-change decomposition across technology adoption curves, regulatory compliance timelines, and health system capital allocation shifts structured the analytical framework over the projection horizon. Segmentation dimensions modeled span auto-identification technology, deployment architecture, facility scale, and application workflow depth. CAGRs derived from instrument replacement cycle velocity, ambulatory surgery center network expansion rates, and cloud subscription conversion trajectories. Forecast inputs incorporated autoclave cycle durability certification adoption curves and EU MDR Class IIa traceability documentation compliance deadlines.
Regulatory enforcement delays, silicon substrate supply disruptions, and health system IT budget freezes are the dominant revision risks that could alter trajectory assumptions across the modeling period. Forecasts reflect documented assumptions about technology substitution rates and procurement cycle timing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Surgical Hand-Access Port Market
Surgical Instruments
Middle East and Africa Lancet and Pen Needles Market
Surgical Instruments
Cheilectomy Market
Surgical Instruments
Global Myomectomy Market
Surgical Instruments
Surgical Drainage Devices Market
Surgical Instruments
Electrocautery Enhanced Delivery System Market
Surgical Instruments
Surgical Snare Market
Surgical Instruments
Global Surgical Scissors Market
Surgical Instruments
Neurosurgical Drills Market
Surgical Instruments
Global Microsurgery Market
Surgical Instruments
Hemostatic Instruments Market
Surgical Instruments
Cleft Lip and Palate Repair Surgical Instrument Package Market
Surgical Instruments
Global Bipolar Electrosurgical Devices Market
Surgical Instruments
GCC Minimally Invasive Surgery Market
Surgical Instruments
Plastic Wound Retractor Market
Surgical Instruments
Medical Tuning Fork Market