
 Dyspareunia Treatment Market | 2026-2036
Dyspareunia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Dyspareunia Treatment Market Foresight
Good Manufacturing Practice certification for active pharmaceutical ingredients is unwinding the competitive set, favoring sponsors with validated supply chains. Pfizer Inc. leverages its scale in hormone manufacturing to sustain formulary access across institutional purchasers. Myovant Sciences anchors its position through targeted development in gonadotropin-releasing hormone modulation. Novo Nordisk A/S competes by extending its metabolic expertise into estrogen-progesterone combination platforms.
Dyspareunia treatment encompasses pharmacological, mechanical, and behavioral interventions designed to alleviate painful sexual intercourse, with hormonal formulations typically containing estradiol or testosterone derivatives administered via vaginal inserts, transdermal patches, or oral tablets to restore mucosal elasticity and neural sensitivity. The primary commercial purpose centers on restoring functional intimacy and reducing associated psychological comorbidities in patients across menopausal, postpartum, and chronic pain populations. Pharmaceuticals dominate current revenue flows due to established reimbursement codes and prescriber familiarity, while Devices are gaining traction among patients seeking non-hormonal alternatives with lower systemic exposure profiles. Topical delivery modes command premium positioning in the channel mix, though Oral formulations retain volume leadership through pharmacy benefit manager coverage.
The FDA oversees premarket approval and labeling requirements for hormone-containing products, while the EMA's MDR framework governs device-based interventions in European markets, and ISO 13485 certification shapes quality expectations for mechanical dilator and laser system manufacturers seeking multi-jurisdiction commercialization. These regulatory layers elevate compliance costs but simultaneously create defensible positions for sponsors with established quality management systems. Stakeholders must monitor evolving FDA guidance on compounded bioidentical hormones and state-level scope-of-practice expansions that could shift treatment administration from specialist clinics to primary care settings.
Market Dynamics
Good Manufacturing Practice certification requirements for active pharmaceutical ingredients are compressing the supplier base, favoring sponsors with validated estrogen and testosterone supply chains while marginalizing smaller compounders.
Growth Catalysts
- FDA hormone therapy labeling guidance:Evolving premarket requirements are accelerating investment in clinical endpoint standardization, creating clearer pathways for novel estradiol formulations to secure formulary access.
- Gynecology clinic service line expansion:Dedicated pelvic pain centers are institutionalizing dyspareunia as a reimbursable specialty, driving prescriber familiarity with vaginal insert and transdermal delivery systems.
- Postpartum patient identification:Rising screening rates in obstetric follow-up protocols are expanding the addressable population beyond menopausal cohorts into younger demographics.
Market Restraints
- API supply concentration:Estradiol and testosterone raw material production clusters in China and India, exposing formulators to export restriction risks and quality inconsistency.
- Compounded bioidentical substitution:503A and 503B compounding pharmacies offer unregulated alternatives at price points that undercut approved products, eroding commercial volume.
- EMA MDR device certification timelines:Laser and dilator manufacturers face 18-24 month conformity assessment delays, constraining European market entry for mechanical interventions.
Strategic Opportunities
- Telehealth platform integration:Virtual pelvic floor therapy and prescription fulfillment models are opening rural and underserved urban corridors previously unreachable by specialty clinics.
- Non-hormonal device category development:Low-level laser therapy and neuromodulation systems are capturing patients with estrogen contraindications, creating premium positioning outside pharmaceutical reimbursement codes.
- Primary care scope-of-practice expansion:State-level licensing changes in the United States are shifting initial diagnosis and maintenance prescribing from gynecology to family medicine, multiplying access points.
Industry Challenges
- ISO 13485 quality management implementation:Device manufacturers must maintain dual compliance with FDA 21 CFR Part 820 and European notified body requirements, doubling documentation overhead.
- Pelvic pain specialist workforce scarcity:Fellowship-trained physicians remain concentrated in academic medical centers, creating bottlenecks for complex case triage and device-based intervention referrals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dyspareunia Treatment Market |
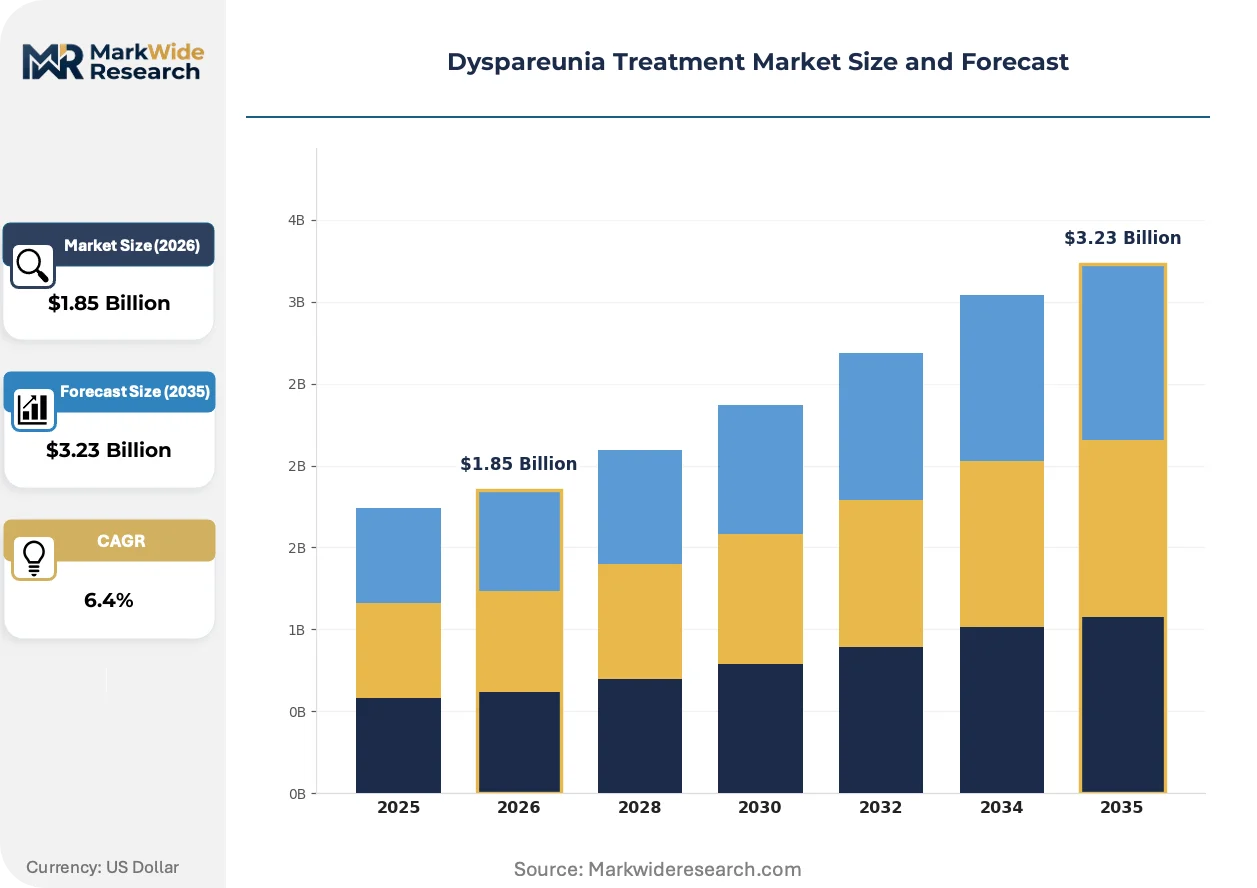
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Devices, Therapies, Lubricants Delivery Mode: Topical, Oral, Injectable, Transdermal End User: Clinics, Hospitals, Home Care, Healthcare Providers Age Group: Adults, Adolescents, Seniors, Middle-Aged |
| Companies Covered | TherapeuticsMD Inc., Myovant Sciences, Pfizer Inc., Viatris Inc., Novo Nordisk A/S, AbbVie Inc., AMAG Pharmaceuticals Inc., Amneal Pharmaceuticals LLC., Duchesnay Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dyspareunia Treatment Market Shifts & Advancements
Digital health integration and delivery mode diversification are fragmenting the traditional pharmaceutical-centric treatment paradigm, opening entry points for device and behavioral intervention sponsors.
Low-level laser therapy systems are decomposing the assumption that dyspareunia requires hormonal intervention. Gynecology clinics in the United States and Germany are adopting these devices for patients with breast cancer history or thromboembolic risk factors. The technology is decomposing the market into hormone-eligible and hormone-ineligible segments, forcing pharmaceutical sponsors to defend mucosal elasticity claims against mechanical alternatives.
EMA's Medical Device Regulation framework is tightening clinical evidence requirements for vaginal dilators and laser platforms. Manufacturers must now submit prospective safety data rather than predicate device equivalence, extending development timelines by 12-18 months. European notified bodies are prioritizing submissions from sponsors with established quality management systems, advantaging incumbent device firms over new entrants.
Patient-initiated switching between delivery modes is compressing brand loyalty cycles. Pharmacy benefit manager formularies in the United States now permit 90-day trials across vaginal insert, transdermal patch, and oral tablet categories without prior authorization. This behavior is most pronounced in commercially insured populations where out-of-pocket differentials remain minimal, pressuring sponsors to demonstrate rapid onset of mucosal improvement.
Dyspareunia Treatment Market Segmentation
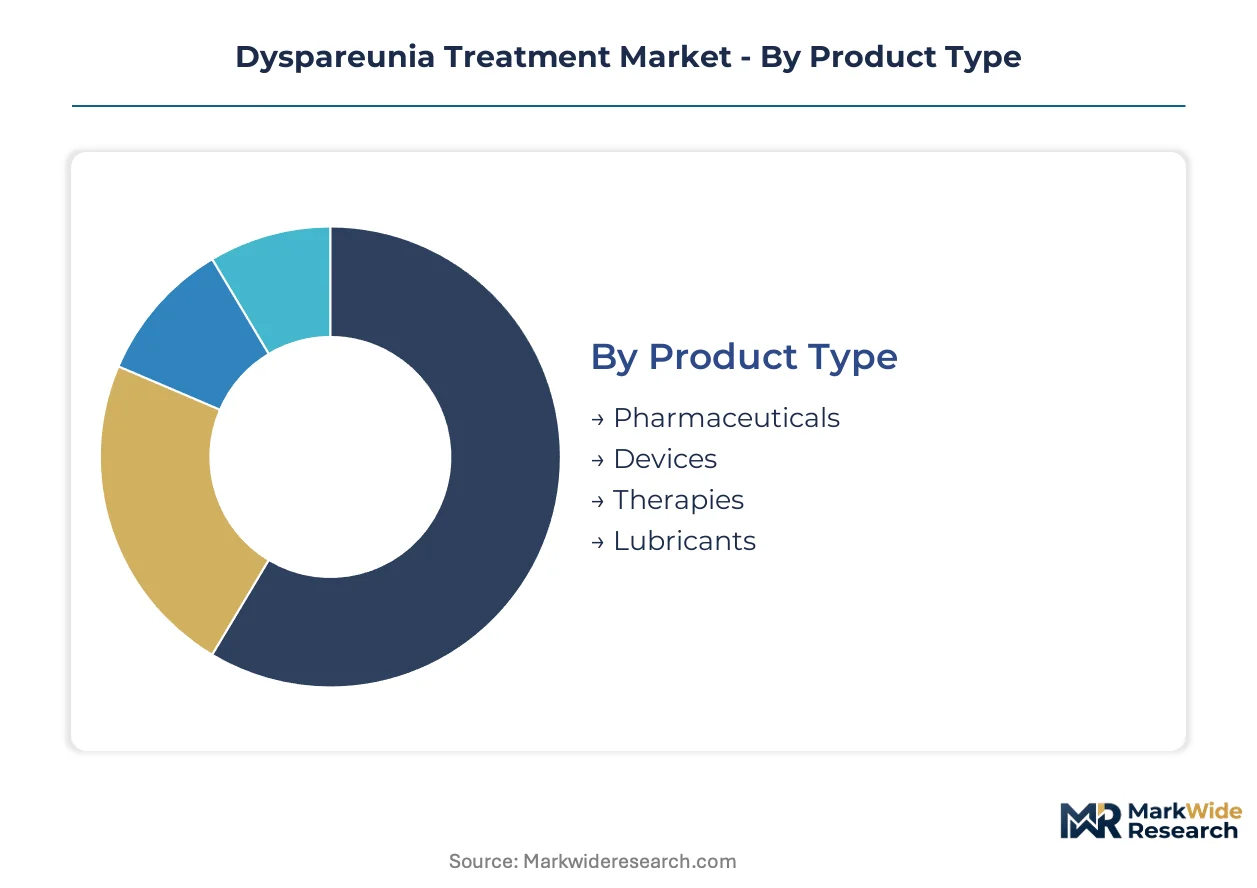
Dyspareunia treatment flows through fragmented channel structures where reimbursement codes, prescriber specialization, and patient self-selection determine which segments capture volume. Channel economics favor institutional procurement for invasive interventions while direct-to-consumer models accelerate access for maintenance therapies.
Product Type:
Pharmaceuticals command institutional formularies through established reimbursement pathways, while Devices and Lubricants fragment across retail and direct-pay channels based on regulatory classification.
- Pharmaceuticals:Hormonal formulations containing estradiol or testosterone derivatives restore mucosal elasticity through systemic or local action. United States gynecology clinics drive prescription volume through dedicated pelvic pain service lines where prior authorization requirements favor approved products over compounded alternatives.
- Devices:Mechanical dilators, low-level laser systems, and neuromodulation platforms deliver non-hormonal intervention for patients with estrogen contraindications. German and United States academic medical centers anchor adoption where fellowship-trained specialists control referral pathways for device-based therapy.
- Therapies:Pelvic floor physical therapy and cognitive-behavioral protocols address neuromuscular and psychological comorbidities. Telehealth platforms in rural United States corridors are expanding access beyond metropolitan specialty clinic networks.
- Lubricants:Over-the-counter vaginal moisturizers and silicone-based formulations provide symptomatic relief without prescription requirements. Pharmacy retail chains and direct-to-consumer e-commerce capture volume from patients seeking immediate access without clinical consultation.
Pharmaceuticals dominate installed base through reimbursement lock-in. Devices are where expansion concentrates as patients with hormone ineligibility seek alternatives.
Delivery Mode:
Route of administration determines prescriber control, patient compliance economics, and manufacturing complexity tiers across the value chain.
- Topical:Vaginal inserts, creams, and gels deliver localized estradiol with minimal systemic absorption. United States pharmacy benefit managers classify these as preferred tier products, reducing out-of-pocket exposure for commercially insured populations.
- Oral:Systemic hormone tablets remain the volume leader through broad prescriber familiarity and pharmacy benefit manager coverage density. Primary care physicians in expanded-scope states now initiate maintenance prescribing, multiplying access points beyond gynecology specialists.
- Injectable:Depot formulations and biologic injections target refractory cases requiring sustained pharmacokinetic profiles. Hospital outpatient departments control procurement through specialty pharmacy networks.
- Transdermal:Patches and gels offer steady-state delivery with bypass of first-pass hepatic metabolism. Patient switching behavior compresses brand loyalty as formularies permit 90-day trials across delivery categories without prior authorization.
Oral formulations anchor volume leadership through coverage breadth. Topical delivery is climbing the fastest as mucosal specificity claims differentiate positioning.
End User:
Site of care determines reimbursement intensity, regulatory oversight level, and patient acuity segmentation across the treatment pathway.
- Clinics:Dedicated gynecology and urogynecology practices concentrate complex case triage and device-based intervention referrals. United States academic medical centers anchor specialist workforce training, creating geographic access bottlenecks.
- Hospitals:Inpatient and outpatient departments manage surgical complications, cancer-related dyspareunia, and multidisciplinary pelvic pain programs. EMA MDR certification requirements for laser and dilator systems extend European hospital procurement timelines.
- Home Care:Self-administered vaginal inserts, lubricants, and telehealth-guided pelvic floor therapy shift treatment outside institutional settings. Rural United States corridors previously unreachable by specialty clinics now access care through virtual platforms.
- Healthcare Providers:Primary care physicians and nurse practitioners in expanded-scope states capture initial diagnosis and maintenance prescribing. State-level licensing changes multiply access points while diluting specialist concentration.
Clinics retain margin concentration through specialist scarcity. Home Care is gaining share fastest as direct-to-consumer models bypass traditional gatekeepers.
Age Group:
Physiological life stage determines etiology distribution, hormone eligibility, and channel preference across the patient journey.
- Adults:Postpartum and perimenopausal populations present mixed etiologies requiring individualized hormonal and mechanical intervention combinations. Obstetric follow-up protocols in United States health systems are expanding screening rates beyond traditional menopausal cohorts.
- Adolescents:Congenital anomalies, trauma history, and psychosexual development disorders drive specialized referral patterns. Pediatric and adolescent gynecology fellowship programs remain scarce, concentrating expertise in major metropolitan academic centers.
- Seniors:Genitourinary syndrome of menopause dominates etiology, with estrogen therapy constrained by cardiovascular and oncologic comorbidity histories. Low-level laser systems capture this segment where hormone contraindications prevail.
- Middle-Aged:Perimenopausal transition creates fluctuating symptom profiles requiring dynamic treatment adjustment. Patient-initiated switching between delivery modes is most pronounced in this commercially insured demographic.
Seniors anchor pharmaceutical volume through chronic maintenance patterns. Adults represent the steepest expansion trajectory as postpartum identification protocols widen the addressable population.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA reimbursement frameworks for women's health services concentrate commercial opportunity in the United States, while EMA MDR certification timelines reshape European device market entry patterns. Germany and United Kingdom gynecology networks anchor European adoption, with Asia-Pacific markets developing through regulatory harmonization initiatives.
United States
Pharmacy benefit manager formularies for vaginal inserts and transdermal patches drive prescriber concentration in gynecology clinic service lines. FDA hormone therapy labeling guidance accelerates clinical endpoint standardization for novel estradiol formulations. Massachusetts and California academic medical centers train fellowship pelvic pain specialists, creating geographic access bottlenecks that telehealth platforms now penetrate.
Germany
Low-level laser therapy adoption concentrates in university hospital gynecology departments serving patients with estrogen contraindications. EMA MDR framework extends conformity assessment timelines for dilator and laser system manufacturers to 18-24 months. Bavaria and North Rhine-Westphalia host notified body prioritization of quality management system submissions from established device sponsors.
United Kingdom
National Health Service pelvic pain referral pathways institutionalize dyspareunia screening within obstetric follow-up protocols. MHRA post-Brexit regulatory autonomy maintains alignment with EMA MDR device certification requirements. London and Manchester metropolitan areas concentrate specialist workforce training, with primary care scope expansion multiplying access points in surrounding regions.
Japan
PMDA hormone-containing product approvals require localized clinical data generation for estradiol and testosterone formulations. METI healthcare technology assessment programs evaluate low-level laser systems for reimbursement inclusion. Tokyo and Osaka academic medical centers anchor specialist concentration, with regional hospital networks developing pelvic floor therapy capacity through telehealth integration.
India
CDSCO regulatory pathways for hormonal formulations attract multinational sponsors seeking volume expansion beyond mature markets. Ayushman Bharat insurance coverage expansion for women's health services creates reimbursement infrastructure in tier-1 cities. Maharashtra and Karnataka host contract manufacturing organizations supplying active pharmaceutical ingredients to global formulators.
Dyspareunia Treatment Market Competitive Landscape
Player mix skews toward pharmaceutical incumbents with validated estrogen supply chains and hormone manufacturing scale. Consolidation pressure from Good Manufacturing Practice certification requirements for active pharmaceutical ingredients compresses the supplier base. Two strategic archetypes dominate: multinational hormone manufacturers leveraging formulary access, and targeted biotech developers pursuing gonadotropin-releasing hormone modulation. Competitive moves center on portfolio diversification into non-hormonal alternatives and telehealth platform partnerships for virtual pelvic floor therapy delivery.
Within the multinational pharmaceutical tier, Pfizer Inc. and Novo Nordisk A/S occupy positions anchored by manufacturing scale and metabolic expertise extension. Myovant Sciences exemplifies the targeted development archetype through gonadotropin-releasing hormone modulation focus. These three entities represent distinct competitive vectors: scale-driven formulary maintenance, cross-therapeutic platform extension, and specialized mechanism targeting.
| Leading Market Players |
|---|
| TherapeuticsMD Inc. |
| Myovant Sciences |
| Pfizer Inc. |
| Viatris Inc. |
| Novo Nordisk A/S |
| AbbVie Inc. |
| AMAG Pharmaceuticals Inc. |
| Amneal Pharmaceuticals LLC. |
| Duchesnay Inc. |
| Others |
Supply & Pricing Matrix
Compounded bioidentical hormone substitution is displacing approved pharmaceutical formulations in price-sensitive segments while simultaneously rerouting supply toward unregulated 503A and 503B compounders, compressing margins for validated manufacturers and fragmenting procurement authority across institutional and direct-pay channels.
Pricing Analysis
Certification level (FDA-approved versus compounded) creates the primary spread between premium and economy tiers, with formulary placement determining patient out-of-pocket exposure through pharmacy benefit manager tiering. Three-tier pricing structure across premium, standard, and economy levels stratifies by manufacturing quality system validation, prescriber control, and reimbursement density. Cost compression in the compounded segment is intensifying because 503B outsourcing facilities operate outside FDA premarket approval requirements. Commercially insured populations show lowest price sensitivity due to minimal copay differentials, while uninsured and high-deductible plan holders drive volume toward unregulated alternatives.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes elevates inbound logistics costs for estradiol and testosterone active pharmaceutical ingredients sourced from contract manufacturers. API production concentrates in India and China, with Maharashtra and Karnataka hosting CDSCO-registered facilities supplying global formulators. Raw material dependencies span steroid hormone precursors, specialized excipients for vaginal inserts, and medical-grade silicone for dilator systems. Single-source vulnerability in Chinese estradiol intermediate production exposes formulators to export restriction risks. Distribution runs through specialty pharmacy networks for hormonal products and direct-to-consumer e-commerce for over-the-counter lubricants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dyspareunia treatment sits in early-cycle expansion as postpartum screening protocols and telehealth platform integration widen addressable populations beyond traditional menopausal cohorts, with device-based alternatives capturing hormone-ineligible segments previously excluded from commercial pathways.
For Market Incumbents: Compound formulary lock-in through 90-day trial suppression mechanisms and prior authorization automation that steers patients away from compounded substitutes. Deepen backward integration into estradiol API supply through captive production or exclusive offtake agreements with GMP-certified Indian manufacturers. Defend against low-level laser therapy displacement by funding head-to-head mucosal elasticity trials against mechanical alternatives. For New Entrants and Emerging Players: Differentiate on non-hormonal efficacy claims for breast cancer survivors and thromboembolic risk populations where estrogen contraindications prevail. Target rural United States corridors through telehealth-integrated pelvic floor therapy platforms that bypass geographic specialist scarcity. Pursue hospital outpatient department procurement relationships for laser and neuromodulation systems where fellowship-trained physicians control referral pathways. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed device manufacturers holding EMA MDR certification momentum and established quality management systems. Five-to-ten year viability hinges on regulatory arbitrage between FDA and EMA frameworks as MDR timelines compress European competitive sets. Watch for state-level scope-of-practice expansions permitting primary care prescribing as inflection signal for channel democratization and volume multiplication.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Endpoint Standardization | FDA hormone therapy labeling guidance accelerates novel estradiol formulation approvals through validated mucosal improvement metrics. |
| Telehealth Platform Integration | Virtual pelvic floor therapy delivery penetrates rural corridors previously unreachable by metropolitan academic medical centers. |
| Non-Hormonal Device Development | Low-level laser systems capture estrogen-contraindicated patients with breast cancer history or thromboembolic risk factors. |
| GMP Certification Investment | Validated active pharmaceutical ingredient supply chains favor sponsors with audited manufacturing quality systems over compounders. |
| Primary Care Scope Expansion | State-level licensing changes multiply access points for initial diagnosis and maintenance prescribing beyond gynecology specialists. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions underpinning volume and value estimates. Primary interviews with payer access specialists and pelvic pain clinicians combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored the analytical framework.
Segmentation dimensions modeled span treatment line, dosage form, administration route, patient population, and regional regulatory cluster across the projection horizon. CAGRs derived from historical growth pattern analysis adjusted for regulatory inflection points and reimbursement framework evolution. Forecast inputs incorporated EMA MDR certification timeline delays, state-level scope-of-practice legislative tracking, and pharmacy benefit manager formulary tier migration patterns.
Decision-makers should treat outputs as directional under assumptions of sustained FDA hormone therapy labeling stability and continued telehealth reimbursement parity; material deviation in compounded bioidentical enforcement or MDR implementation pace would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Rett Syndrome Treatment Market
Medical Treatment
Peri-Implantitis Treatment Market
Medical Treatment
Radiation Therapy Market
Medical Treatment
Alagille Syndrome Treatment Market
Medical Treatment
Dengue Fever Treatment Market
Medical Treatment
Precocious Puberty Treatment Market
Medical Treatment
Stereotactic Body Radiation Therapy Market
Medical Treatment
Global Radiodermatitis Treatment Market
Medical Treatment
Iron Deficiency Anemia Treatment Market
Medical Treatment
Vulvovaginal Candidiasis Treatment Market
Medical Treatment
Peripheral Nerve Injuries Market
Medical Treatment
Europe Lysosomal Disease Treatment Market
Medical Treatment
Tinea Pedis Treatment Market
Medical Treatment
US Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Stereotactic Radiation Therapy Market
Medical Treatment
Cholera Treatment Market