
 Global Pigmentation Disorders Treatment Market | 2026-2036
Global Pigmentation Disorders Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pigmentation Disorders Treatment Market Intelligence
The distribution channel between prescription drugs and over-the-counter (OTC) products is reconfiguring the market access landscape. Galderma S.A. leverages its extensive portfolio of both prescription and aesthetic solutions. AbbVie Inc. competes through its strength in immunology and biologic drug development, targeting underlying inflammatory causes. Obagi Cosmeceuticals LLC specializes in physician-dispensed topical systems that bridge the gap between cosmetic and pharmaceutical care.
Pigmentation disorders treatment encompasses medical and aesthetic interventions designed to normalize melanin production and distribution in the skin. These therapies modulate melanocyte activity or interfere with the melanin synthesis pathway to correct hyperpigmentation or repigment affected areas. Their primary purpose is to manage conditions such as melasma, vitiligo, and post-inflammatory hyperpigmentation. Topical creams remain the dominant product type, while laser therapy represents a high-value, procedure-driven segment.
Regulatory oversight from bodies like the US FDA and the EU's EMA dictates the clinical evidence required for new drug approvals. In parallel, China's NMPA sets stringent standards for both imported drugs and aesthetic devices, influencing market entry strategies. Stakeholder success depends on aligning product development with the specific evidentiary requirements of therapeutic versus cosmeceutical regulatory pathways.
Market Dynamics
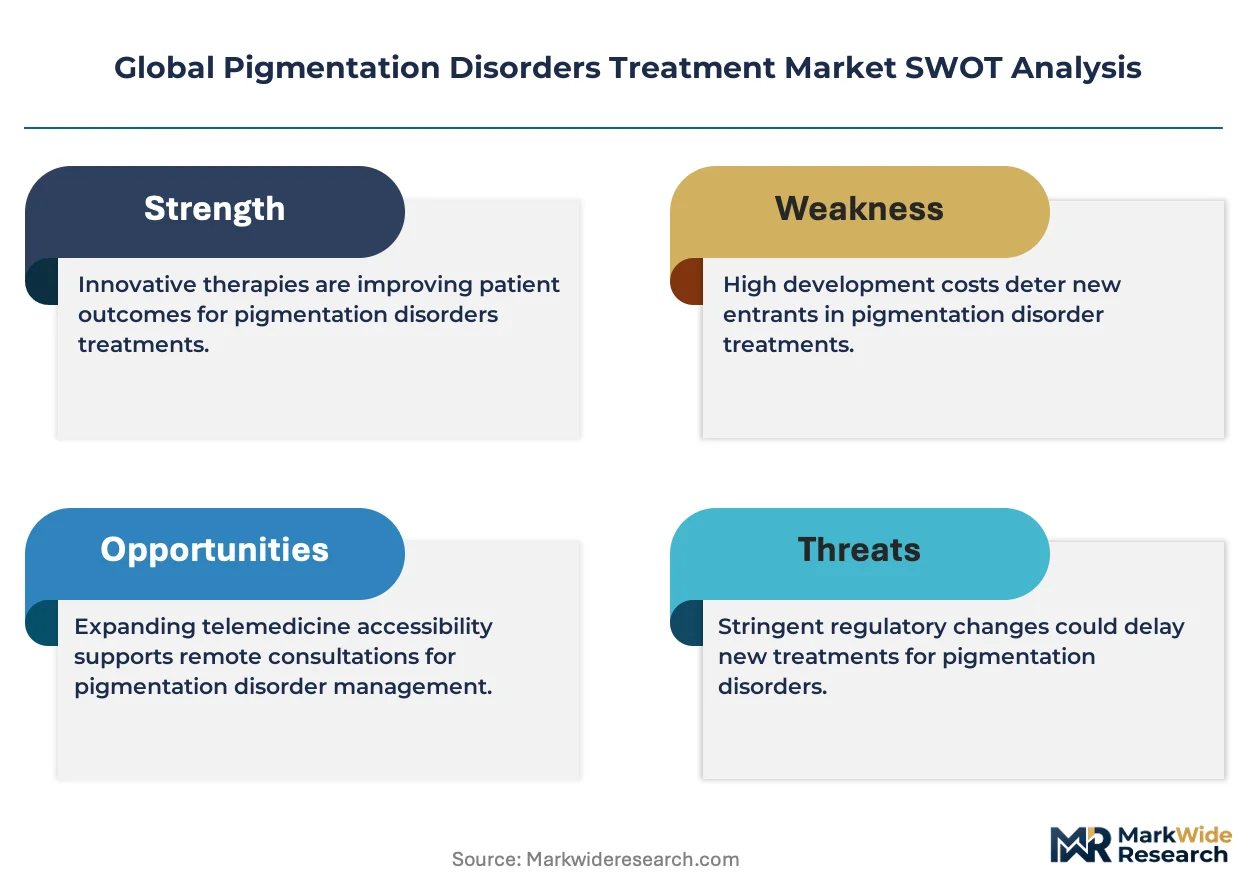
The market's central dynamic is the escalating tension between therapeutic and cosmeceutical regulatory frameworks. This divergence forces companies to navigate distinct pathways for product development, clinical validation, and marketing claims, profoundly influencing market access strategies for topical treatments and aesthetic devices.
Growth Catalysts
- Novel Formulations:The development of advanced tyrosinase inhibitors and stable, non-hydroquinone alternatives provides clinicians with safer and more effective options for long-term management of conditions like melasma, stimulating adoption in dermatology clinics.
- Aesthetic Dermatology Expansion:High consumer demand for aesthetic procedures in markets such as Brazil and South Korea creates a significant pull for new pigmentation treatments, including both topical agents and energy-based devices.
- Procedural Integration:The increasing use of topical treatments as adjunctive therapy to laser and light-based procedures enhances clinical outcomes, driving sales of professionally dispensed skincare systems within dermatology and plastic surgery practices.
Market Restraints
- High Treatment Costs:The significant expense associated with advanced options, particularly multiple sessions of laser therapy or long-term use of prescription-grade topicals, limits accessibility for a broad patient population.
- Stringent Regulatory Hurdles:Lengthy and costly clinical trial processes mandated by the US FDA and EMA for new drug approvals act as a substantial barrier to entry for novel therapeutic molecules.
- Risk of Adverse Effects:Potential side effects, such as post-inflammatory hyperpigmentation from certain lasers or ochronosis from long-term hydroquinone use, create clinical hesitation and can limit treatment protocols.
Strategic Opportunities
- Targeting Systemic Pathways:Development of oral or biologic therapies targeting the underlying inflammatory or autoimmune triggers of conditions like vitiligo represents a significant opportunity to address unmet needs beyond topical solutions.
- Teledermatology Integration:Incorporating diagnostic and prescription platforms into teledermatology services can expand market reach to underserved regions and streamline the patient journey from consultation to treatment delivery.
- Ethnic Skincare Specialization:Formulating products specifically tested and validated for skin of color, which has a higher predisposition to certain pigmentation disorders, opens a large and historically underserved market segment.
Industry Challenges
- Cross-Regulatory Compliance:Managing a product portfolio that must simultaneously comply with pharmaceutical regulations under the FDA, cosmetic standards in the EU, and device rules from China's NMPA creates immense operational complexity.
- Practitioner Skill Gaps:The effective and safe use of advanced energy-based devices requires specialized training, and a shortage of qualified technicians can constrain the growth of the procedure-driven market segment.
- Misinformation and Consumer Expectations:The proliferation of unverified claims from over-the-counter products creates unrealistic patient expectations and complicates the role of clinicians in providing evidence-based care.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pigmentation Disorders Treatment Market |
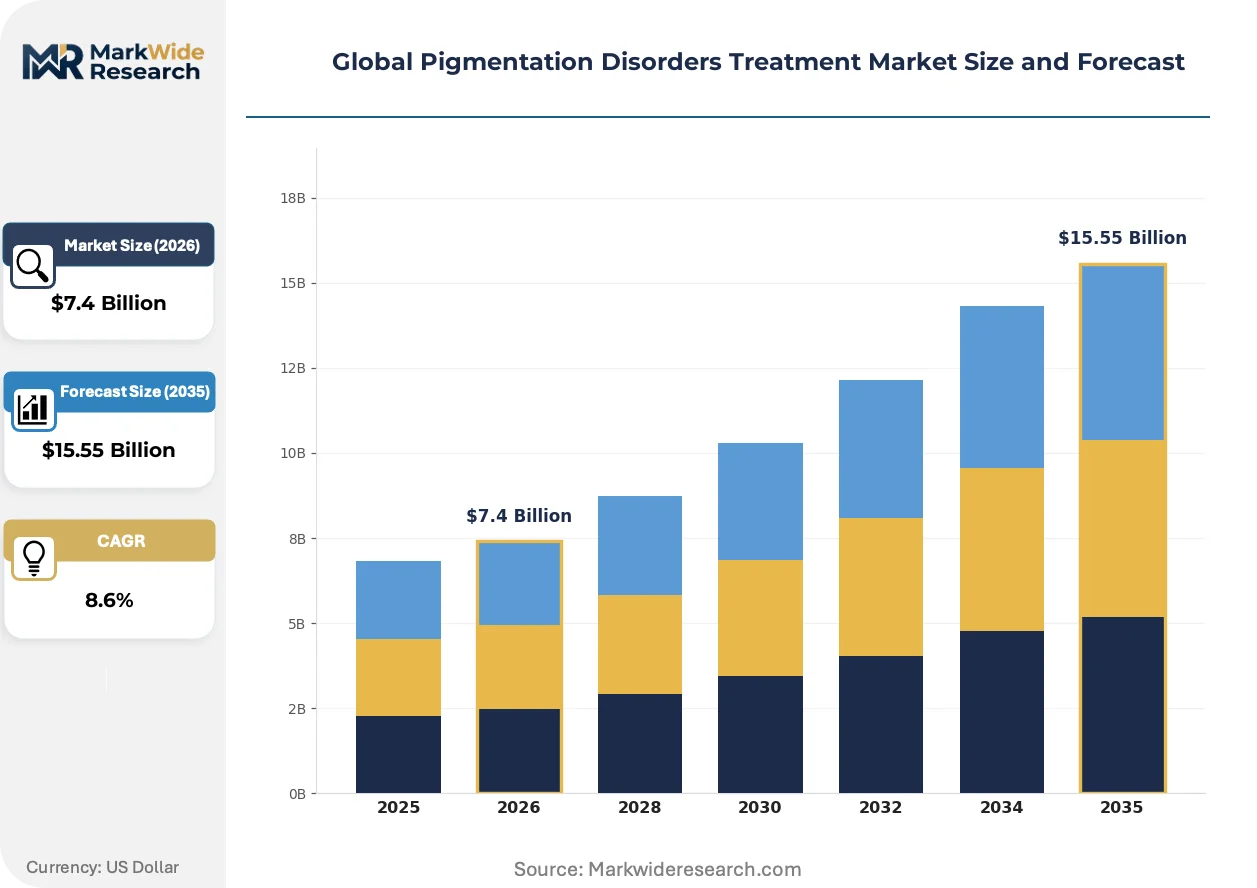
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $15.55 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Creams, Oral Tablets, Laser Therapy, Chemical Peels, Phototherapy, Cryotherapy Therapy Area: Melasma, Vitiligo, Post-Inflammatory Hyperpigmentation, Age Spots, Freckles, Lentigines End User: Dermatology Clinics, Cosmetic Centers, Research Institutes, Pharmacies, Wellness Spas Delivery Mode: In-Clinic Procedures, Home Care Treatments, Prescription Drugs, Over-the-Counter Products |
| Companies Covered | Galderma S.A., AbbVie Inc., Pfizer Inc., Obagi Cosmeceuticals LLC, Incyte Corporation, Glenmark Pharmaceuticals Ltd., Bausch Health Companies Inc., CLINUVEL PHARMACEUTICALS LTD, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pigmentation Disorders Treatment Market Strategic Shifts & Innovations
A convergence of data science and biochemistry is redefining treatment personalization. This shift moves the market beyond one-size-fits-all topicals toward patient-specific regimens that integrate diagnostics, customized formulations, and procedural interventions for improved efficacy and safety in managing pigmentation disorders.
Technology and Product Evolution
AI-powered skin analysis software provides objective, quantifiable assessment of pigmentation severity and morphology. Dermatology clinics and teledermatology platforms are rapidly adopting these tools to establish baselines and track treatment progress. This technology is virtualizing the diagnostic process, enabling remote consultations and data-driven adjustments to therapeutic regimens that were previously reliant on subjective clinical observation.
Regulatory and Policy Shifts
The European Union’s enhanced scrutiny on cosmetic product claims is forcing a change in evidence generation. New requirements under its cosmetics regulation demand more robust data to substantiate efficacy claims for products marketed as "cosmeceuticals." This shift most impacts brands at the cosmetic-pharmaceutical border, compelling them to invest in clinical-style studies to legally market their high-potency anti-pigment formulations within the EU.
Demand-Side and Behavioral Shifts
A clear behavioral shift toward combination therapy protocols is evident among both patients and clinicians. The standalone "hero" product model is being displaced by integrated systems that combine daily topical care, oral supplements, and a schedule of in-office procedures like chemical peels. This trend is most pronounced in aesthetically mature markets like South Korea, where consumers actively seek comprehensive, multi-modal treatment plans from dermatologists.
Global Pigmentation Disorders Treatment Market Segmentation
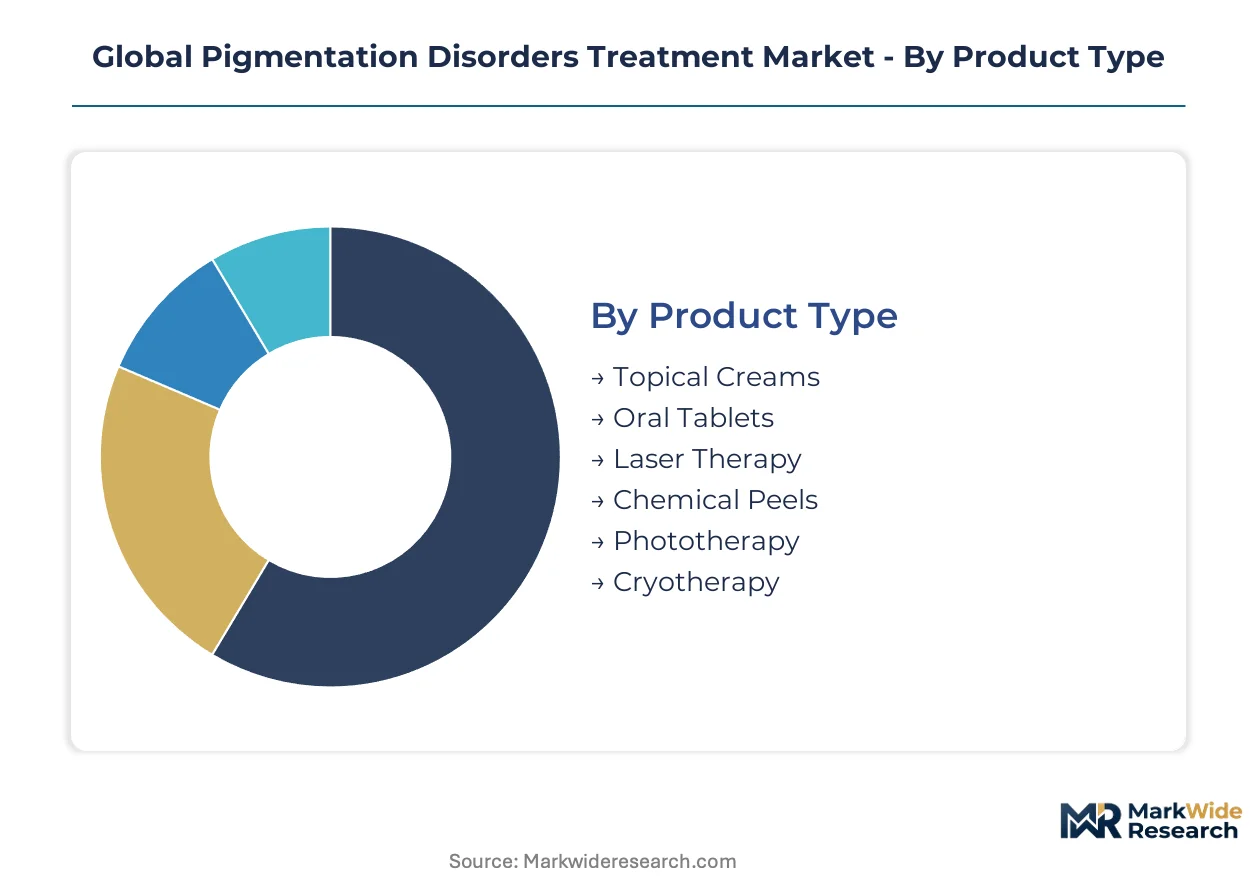
The segmentation of the global pigmentation disorders treatment market provides a granular view of product delivery, therapeutic focus, end-user engagement, and treatment modalities. Understanding these distinct segments is crucial for stakeholders to align product development and market access strategies with specific patient needs and clinical pathways.
Product Type:
The product type segmentation delineates the spectrum of interventions, from topical applications for daily management to advanced procedural solutions for targeted correction.
- Topical Creams:These formulations deliver active pharmaceutical ingredients directly to the skin, often containing tyrosinase inhibitors or retinoids to modulate melanin production. Demand for these products concentrates in dermatology clinics, particularly in markets like Brazil and South Korea, for the long-term management of melasma.
- Laser Therapy:Utilizing focused light energy to target and break down melanin pigments or stimulate melanocyte activity, laser therapy represents a high-value, procedure-driven segment. Cosmetic centers frequently employ various laser types for conditions such as age spots and post-inflammatory hyperpigmentation.
- Oral Tablets:Systemic medications, including certain antioxidants or anti-inflammatory agents, offer an adjunctive approach to topical treatments or address underlying causes of pigmentation disorders.
- Chemical Peels:Controlled exfoliation using acidic solutions removes superficial layers of skin, promoting cell turnover and reducing hyperpigmentation.
- Phototherapy:This treatment involves exposing affected skin to specific wavelengths of ultraviolet light to stimulate repigmentation, primarily used for conditions like vitiligo.
- Cryotherapy:A localized treatment that uses extreme cold to destroy abnormal skin cells, often employed for small, benign pigmented lesions such as age spots or freckles.
The dominant share belongs to Topical Creams, while Laser Therapy is closing the gap fastest.
Therapy Area:
This category segments treatments based on the specific dermatological condition they address, reflecting diverse pathophysiologies and patient needs.
- Melasma:Characterized by dark, discolored patches on the skin, melasma is often hormonally influenced and requires combination therapy for effective management. Global demand for melasma treatments is particularly strong in regions with high sun exposure and aesthetic consciousness.
- Vitiligo:An autoimmune condition causing patches of skin to lose pigment, vitiligo treatments focus on repigmentation and halting disease progression. Biologic drug development and research into systemic pathways offer significant opportunities for vitiligo therapy.
- Post-Inflammatory Hyperpigmentation:This temporary darkening of the skin occurs after injury or inflammation, common across all skin types and requiring targeted topical interventions.
- Age Spots:Also known as solar lentigines, these are flat, brown spots appearing on sun-exposed skin, primarily affecting older populations seeking aesthetic improvement.
- Freckles:Small, light brown spots that typically appear in sun-exposed areas, often genetically determined and managed with sun protection or cosmetic procedures.
- Lentigines:Larger, more defined pigmented lesions than freckles, which can be solitary or numerous, and may require medical assessment to rule out malignancy.
This distribution highlights the varying clinical complexities and treatment durations across different pigmentary concerns.
End User:
The end user segmentation illustrates the primary channels through which patients access pigmentation disorder treatments, reflecting professional oversight levels.
- Dermatology Clinics:These specialized medical facilities offer comprehensive diagnostic services and a full spectrum of therapeutic options, from prescription topicals to advanced laser procedures. Dermatology clinics are central to the adoption of novel tyrosinase inhibitors and combination therapy protocols.
- Cosmetic Centers:Focused on aesthetic enhancement, these centers provide a range of non-invasive and minimally invasive procedures, including chemical peels, microdermabrasion, and various laser treatments. Cosmetic centers drive demand for high-value procedural segments, especially in aesthetically mature markets.
- Research Institutes:These institutions are primarily involved in the discovery, development, and clinical validation of new drugs and treatment modalities for pigmentation disorders.
- Pharmacies:Pharmacies serve as distribution points for both prescription medications and a wide array of over-the-counter products targeting pigmentation concerns.
- Wellness Spas:Offering a more holistic and non-medical approach, wellness spas provide aesthetic services and topical treatments, often bridging cosmetic care with relaxation.
Dermatology Clinics remain central for complex cases, while Cosmetic Centers are expanding their procedural offerings.
Delivery Mode:
Delivery mode segmentation defines how treatments reach the patient, influencing accessibility and the level of professional guidance involved.
- In-Clinic Procedures:These treatments are administered directly by healthcare professionals within a clinical setting, encompassing laser therapy, chemical peels, and phototherapy. In-clinic procedures represent the high-value, skill-intensive segment of the market, particularly for advanced aesthetic interventions.
- Home Care Treatments:Patient-administered products used outside a clinical setting, including topical creams, serums, and oral supplements, form the foundation of daily management and long-term maintenance. Home care treatments are essential for consistent patient adherence and sustained results for conditions like melasma.
- Prescription Drugs:Medications that require a doctor's order, ensuring appropriate diagnosis and medical supervision for potent active ingredients.
- Over-the-Counter Products:Readily available without a prescription, these products typically contain milder active ingredients for addressing minor pigmentation concerns or for adjunctive care.
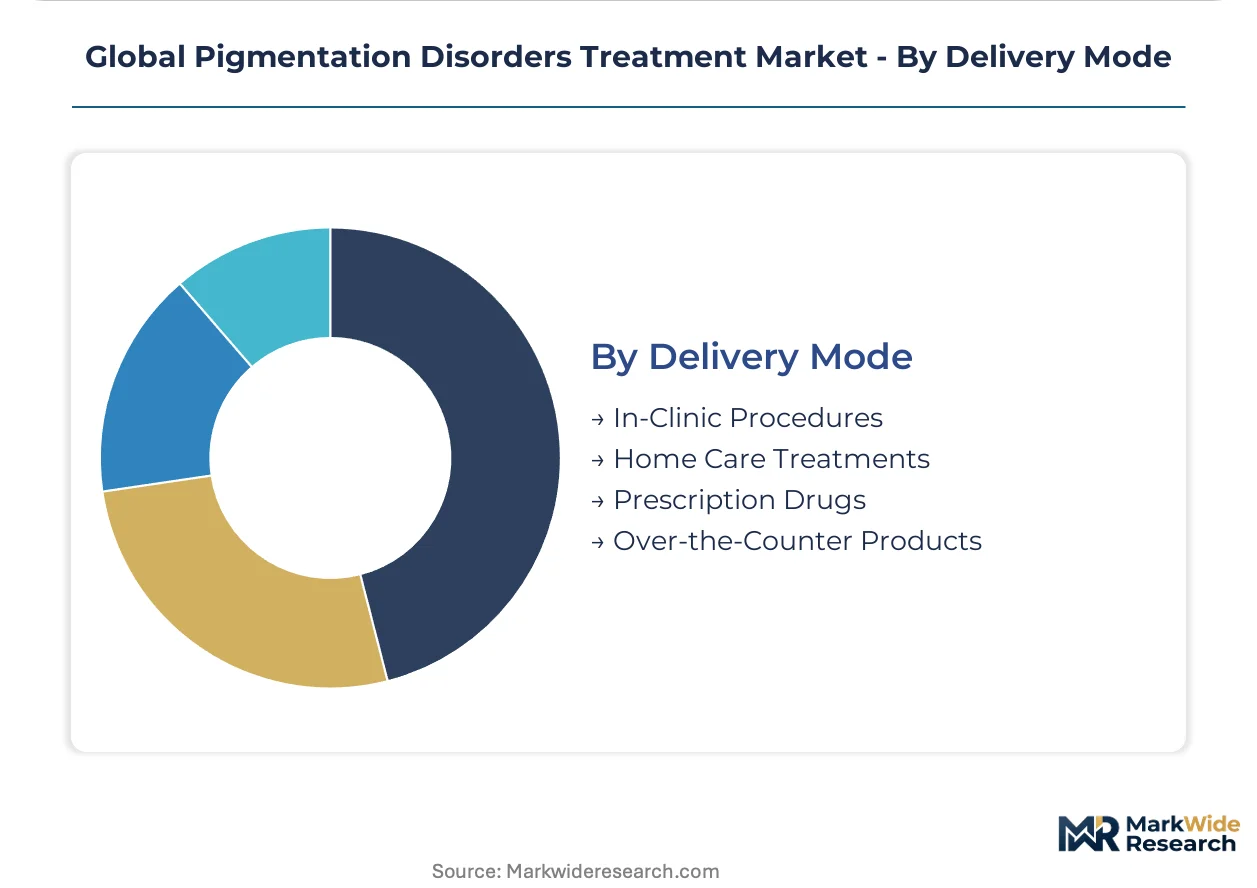
In-Clinic Procedures drive high-value segments, complemented by the consistent demand for Home Care Treatments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The robust global trade network underwrites diverse regional market dynamics for pigmentation disorder treatments. These regions demonstrate varied consumer preferences, regulatory environments, and technological adoption rates. Stakeholders must tailor their market entry and product development strategies to these distinct regional characteristics.
United States
United States consumers demand advanced cosmetic and medical interventions for skin conditions. The US FDA's stringent approval process for novel therapeutics influences product development timelines. Boston's biotech corridor houses numerous firms researching biologic treatments for autoimmune pigmentation disorders.
Germany
Germany exhibits a steady demand for high-quality dermatological treatments, driven by an aging demographic. European Medicines Agency (EMA) regulations shape the market entry strategies for new topical and systemic therapies. Pharmaceutical clusters in Frankfurt and Munich are active in developing advanced formulations for various pigmentary concerns.
Brazil
Brazil's high aesthetic consciousness and substantial sun exposure create significant demand for melasma treatments. ANVISA's regulatory framework governs the approval and marketing of both prescription and cosmetic dermatological products. São Paulo's aesthetic medicine sector leads in adopting combination therapy protocols and advanced laser technologies.
South Korea
South Korea's sophisticated beauty market drives demand for innovative and effective pigmentation solutions. The MFDS sets rigorous standards for cosmeceuticals, influencing product development and claims substantiation. Seoul's dermatology clinics are at the forefront of integrating AI-powered diagnostics with personalized treatment regimens.
Global Pigmentation Disorders Treatment Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the pigmentation disorders treatment market. The market exhibits a tiered structure, with large pharmaceutical companies offering comprehensive portfolios alongside specialized cosmeceutical firms. Strategic archetypes include global pharmaceutical giants, dedicated aesthetic solution providers, and niche biologic drug developers. Companies prioritize portfolio diversification and strategic partnerships to expand their market reach.
Specialists in dermatological and aesthetic solutions include Galderma S.A., which exemplifies a broad portfolio approach. AbbVie Inc. occupies a position among major players leveraging its strength in immunology for underlying inflammatory causes. Obagi Cosmeceuticals LLC represents the segment focused on physician-dispensed topical systems that bridge cosmetic and pharmaceutical care. These entities collectively drive innovation across various treatment modalities.
| Leading Market Players |
|---|
| Galderma S.A. |
| AbbVie Inc. |
| Pfizer Inc. |
| Obagi Cosmeceuticals LLC |
| Incyte Corporation |
| Glenmark Pharmaceuticals Ltd. |
| Bausch Health Companies Inc. |
| CLINUVEL PHARMACEUTICALS LTD |
| Johnson & Johnson |
| Others |
Cost & Logistics Intelligence
Trans-Pacific shipping lanes and European pharmaceutical logistics networks drive cost dynamics, impacting supply concentration for active ingredients and finished products, which in turn influences downstream price differentiation across various market segments.
Pricing Analysis
Tiered pricing separates premium prescription formulations from standard over-the-counter products and economy generic options. Price differentiation stems from the quality grade of active ingredients and specific regulatory certifications, such as US FDA approval. Pricing softness in high-volume topical creams reflects the entry of new market players offering similar efficacy at lower costs. Individual patients seeking aesthetic enhancements often demonstrate higher price sensitivity for long-term home care, while dermatology clinics prioritize efficacy and safety for advanced procedures.
Supply Chain Analysis
Regulatory restriction on novel ingredient imports dominates the supply chain risk for advanced pigmentation treatments. Geographic supply concentrates in China for active pharmaceutical ingredients and in Germany for specialized aesthetic device components. The market draws from a narrow base of suppliers for patented biologic drug precursors. Key raw material dependencies include specialized tyrosinase inhibitors and stable non-hydroquinone alternatives. Distribution primarily runs through specialized pharmaceutical wholesalers and direct-to-clinic channels for high-value products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Growing patient demand for comprehensive, multi-modal treatment plans shifts purchasing power towards integrated dermatology clinics and cosmetic centers.
For Market Incumbents: Build intellectual property moats around novel tyrosinase inhibitors and biologic drug patents. Invest heavily in clinical trials for new drug approvals to meet stringent US FDA and EMA standards. This defends against emerging cosmeceutical brands with less stringent regulatory burdens. Channel control through direct clinic partnerships remains a critical lever for market penetration.
For New Entrants and Emerging Players: Underserved ethnic skincare markets with formulations validated for skin of color represent a significant entry point. Teledermatology platforms integrating AI diagnostics offer a scalable pathway to remote patient care. Specific regional markets like Latin America, where aesthetic dermatology is expanding, present opportunities. Focus on digital-first diagnostic tools combined with personalized, physician-dispensed topical regimens.
For Investors and Strategic Acquirers: Niche biologic drug developers specializing in autoimmune conditions like vitiligo offer attractive long-term growth prospects. The market displays robust long-term viability over the next decade due to persistent demand for aesthetic and medical solutions. Increased regulatory clarity for cosmeceuticals in major markets signals market maturation and reduced risk for new product development.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Secures US FDA and EMA approvals for novel biologic therapies. |
| Portfolio Diversification | Expands product offerings across topical, oral, and procedural segments. |
| Strategic Partnership | Leverages specialized expertise for AI diagnostics or teledermatology platforms. |
| Manufacturing Scale-Up | Ensures consistent supply of advanced tyrosinase inhibitors. |
| Geographic Expansion | Accesses high-demand aesthetic markets like Brazil and South Korea. |
Research Approach
Initial hypotheses were tested against primary input from dermatology practitioners, pharmaceutical R&D scientists, regulatory affairs specialists, and aesthetic clinic owners, then refined. Secondary validation involved extensive review of US FDA approval databases, EMA regulatory guidelines, NMPA device registries, and clinical trial publications. This approach combined bottom-up data from market players with top-down analysis of market size and growth.
Demand-supply-balance models were applied across the analysis window to project market trajectories. Segmentation dimensions modeled included product type, therapy area, end-user, delivery mode, and regional regulatory compliance. Compound annual growth rates were derived from historical data trends and projected market expansion factors. Key industry-specific forecast inputs included incidence rates of pigmentation disorders and consumer aesthetic spending trends.
Practitioners should monitor new regulatory mandates from bodies like the US FDA or EMA for early signals of market shifts. Unforeseen advancements in gene therapy or personalized medicine could also alter long-term projections. Forecasts reflect documented assumptions and are subject to inherent market uncertainties. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Dravet Syndrome Treatment Market
Specialty Medicine
Exanthema Market
Specialty Medicine
Transthyretin (TTR) Amyloidosis Market
Specialty Medicine
Global Constipation Treatment Market
Specialty Medicine
Chromoblastomycosis Treatment Market
Specialty Medicine
Global Non-Oncology Precision Medicine Market
Specialty Medicine
Toxoplasmosis Treatment Market
Specialty Medicine
Growth Hormone Deficiency Market
Specialty Medicine
Vitiligo Treatment Market
Specialty Medicine
Selectin Blocker Market
Specialty Medicine
Cerebral Palsy Market
Specialty Medicine
Global Postmenopausal Osteoporosis Market
Specialty Medicine
North America Precision Medicine Market
Specialty Medicine
ACTH Deficiency Treatment Market
Specialty Medicine
Psychedelic Medicine Market
Specialty Medicine
Herpangina Treatment Market