
 Global Non-Oncology Precision Medicine Market | 2026-2036
Global Non-Oncology Precision Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non-Oncology Precision Medicine Market Foresight
Hospital systems with embedded genomic testing infrastructure is rotating toward diagnostic laboratories as the primary volume channel for non-oncology precision medicine. Quest Diagnostics Inc. anchors its position through extensive laboratory networks spanning multiple continents. F. Hoffmann-La Roche Ltd differentiates via integrated diagnostic-therapeutic platforms that span cardiovascular and neurological applications. Laboratory Corporation of America Holdings competes on scale, processing high-throughput biomarker panels for rare disease programs.
Non-oncology precision medicine encompasses molecular diagnostic and therapeutic approaches tailored to individual patient biology outside cancer indications, utilizing pharmacogenomic profiling, biomarker stratification, and targeted intervention design to improve efficacy and reduce adverse events in cardiovascular, neurological, infectious, and rare diseases. Genetic testing occupies the largest revenue share among product types due to its foundational role in patient stratification workflows. Companion diagnostics represents the fastest-expanding segment as regulators now mandate co-development with targeted therapies. Next-Generation Sequencing dominates the technology landscape while CRISPR applications advance in preclinical rare disease pipelines.
FDA oversees biomarker qualification and companion diagnostic approval pathways in the United States, while EMA coordinates centralized assessment for European market access under the In Vitro Diagnostic Regulation. Japan's PMDA maintains distinct but increasingly aligned standards for genomic test validation, creating a multi-jurisdictional compliance environment. Stakeholders must monitor evolving reimbursement policies for biomarker-guided therapies across national health systems to anticipate channel economics and access constraints.
Market Dynamics
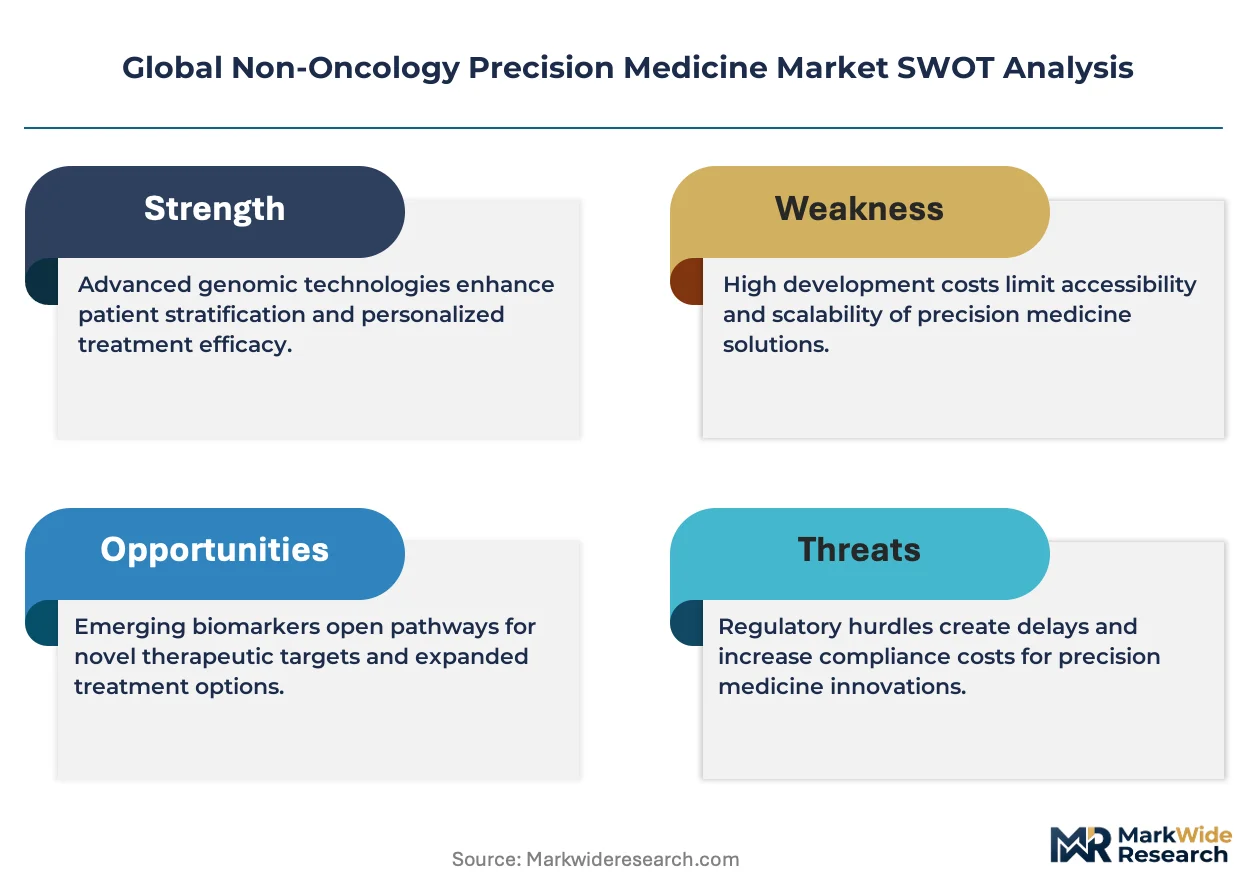
Companion diagnostic mandates from FDA and EMA are compressing development timelines and forcing pharmaceutical manufacturers to integrate biomarker strategies earlier in therapeutic pipelines, fundamentally restructuring how precision medicine products reach hospital networks.
Growth Catalysts
- Biomarker Qualification Pathways:FDA's streamlined qualification process accelerates cardiovascular and neurological therapeutic approvals, reducing time-to-market for stratified interventions.
- Pharmacogenomic Integration:Hospital systems in Germany, Japan, and the United States embed genomic testing into standard cardiology and neurology protocols, expanding addressable patient populations.
- Next-Generation Sequencing Cost Compression:Platform economics enable broader rare disease screening, unlocking previously uneconomical patient stratification workflows.
Market Restraints
- Reimbursement Fragmentation:National health systems in France, Italy, and Spain maintain inconsistent biomarker-guided therapy coverage, creating access inequities that limit commercial scalability.
- Specialized Workforce Scarcity:Clinical bioinformatics and genomic counseling talent concentrates in Boston, Basel, and Tokyo metropolitan clusters, constraining laboratory expansion elsewhere.
- IVDR Compliance Burden:Europe's In Vitro Diagnostic Regulation imposes extensive clinical evidence requirements on legacy assays, freezing product portfolios during transition periods.
Strategic Opportunities
- Infectious Disease Stratification:Antimicrobial resistance profiling opens precision medicine applications beyond chronic disease management, with tuberculosis and sepsis protocols advancing in Indian and South African hospital networks.
- CRISPR Diagnostic Convergence:Gene-editing platforms merge with point-of-care testing formats, enabling decentralized rare disease screening in rural and underserved geographies.
- Japan's Genomic Medicine Implementation:PMDA's Sakigake designation fast-tracks companion diagnostic approvals, positioning Japanese hospital systems as early-adopter reference sites for neurological precision therapies.
Industry Challenges
- Interoperability Architecture:Electronic health record systems from Epic, Cerner, and regional vendors lack standardized genomic data fields, forcing laboratories to maintain parallel informatics pipelines.
- Multi-Jurisdictional Evidence Generation:FDA, EMA, and PMDA demand divergent clinical validation cohorts, duplicating trial costs for global therapeutic launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non-Oncology Precision Medicine Market |
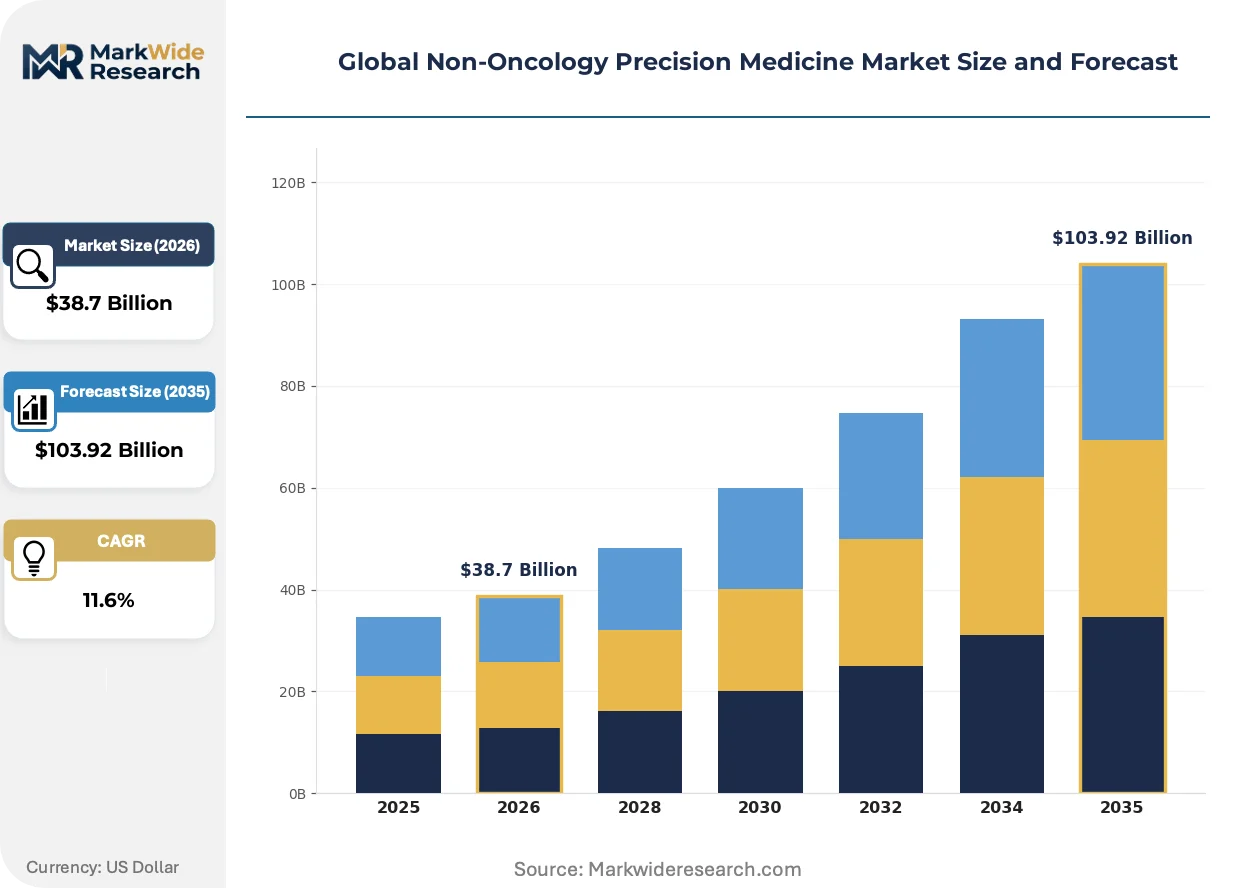
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $103.92 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Genetic Testing, Biomarker Discovery, Companion Diagnostics, Personalized Therapies End User: Hospitals, Diagnostic Laboratories, Research Institutions, Pharmacies Technology: Next-Generation Sequencing, Microarrays, CRISPR, Digital PCR Application: Cardiovascular Disorders, Neurological Disorders, Rare Diseases, Infectious Diseases |
| Companies Covered | Pfizer Inc., Qiagen Inc., Quest Diagnostics Inc., Medtronic, Novartis, Abbott Laboratories, F. Hoffmann-La Roche Ltd, Laboratory Corporation of America Holdings, bioMérieux SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non-Oncology Precision Medicine Market Shifts & Advancements
Technology convergence between sequencing platforms and artificial intelligence analytics is compressing diagnostic turnaround times while regulatory harmonization efforts reshape competitive entry barriers across major pharmaceutical markets.
Point-of-care genomic testing devices are miniaturizing. Cardiology departments in Cleveland Clinic, Charité Berlin, and University of Tokyo Hospital deploy palm-sized sequencers for bedside pharmacogenomic profiling. This format is miniaturizing laboratory infrastructure requirements, enabling specialist networks to bypass centralized reference laboratories and capture margin previously allocated to Quest Diagnostics and Laboratory Corporation of America Holdings.
EMA's In Vitro Diagnostic Regulation enforcement since 2022 imposes notified body certification on all companion diagnostic commercialization. Manufacturers must rebuild quality management systems and clinical evidence packages for legacy assays. Cardiovascular biomarker panels face the steepest compliance burden, with European launch timelines extending 18-24 months versus pre-IVDR baselines.
Hospital procurement committees now require outcome-based contracting for high-cost genomic tests. United States academic medical centers and German university hospitals lead this shift, tying laboratory payments to demonstrated reduction in adverse drug events or hospital readmissions. This restructuring displaces traditional fee-for-service pricing, compressing margins for diagnostic manufacturers unable to generate real-world evidence.
Global Non-Oncology Precision Medicine Market Segmentation
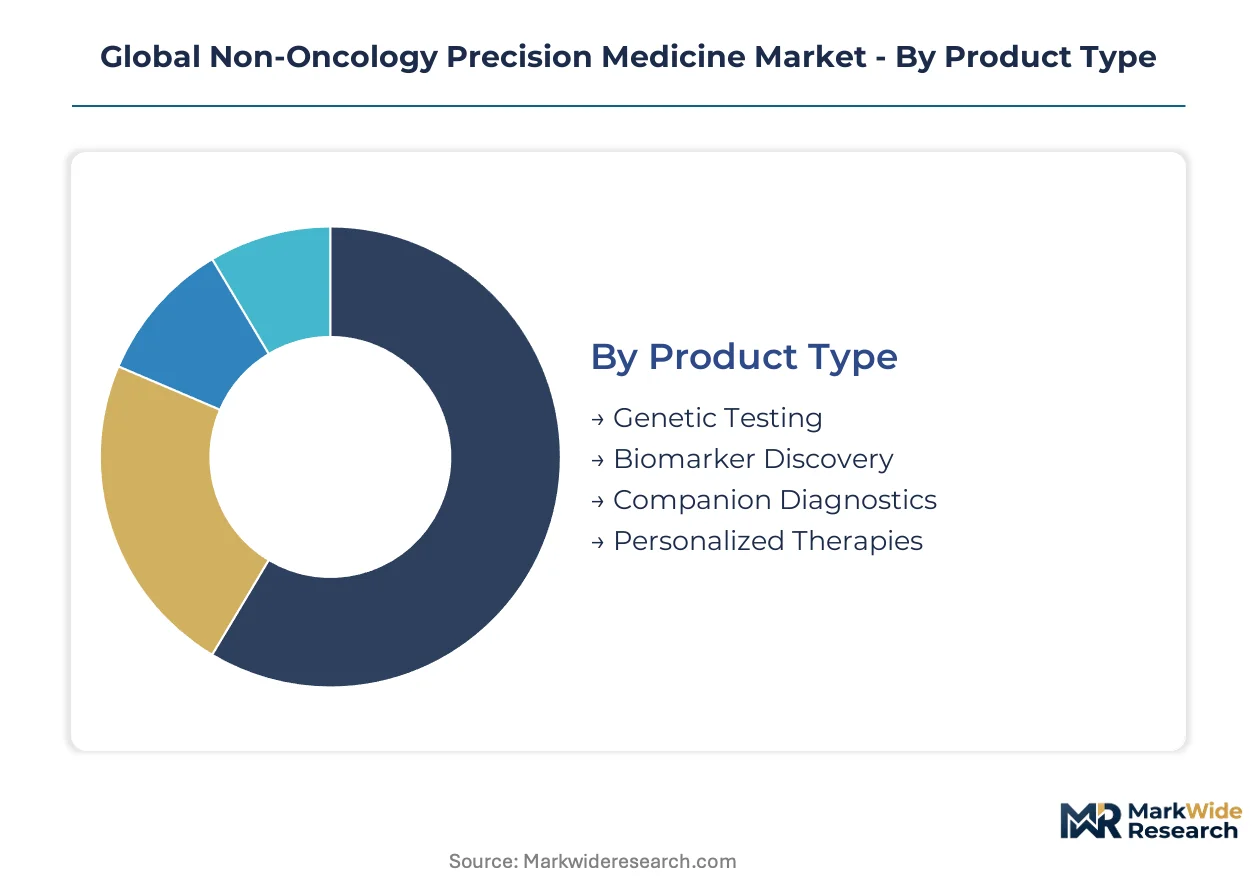
Channel economics in non-oncology precision medicine diverge sharply by product format. Diagnostic laboratories capture high-throughput genetic testing volumes while hospital networks increasingly internalize point-of-care companion diagnostics.
Product Type:
Hospital procurement committees route genetic testing through centralized laboratory contracts while companion diagnostics flow through integrated therapeutic platforms.
- Genetic Testing:Pharmacogenomic panels and germline mutation screening form the foundational infrastructure for patient stratification. United States academic medical centers in Boston and Stanford process the highest per-capita volumes as specialist networks embed pre-emptive genotyping into cardiology admission protocols.
- Companion Diagnostics:Co-developed assays mandated by FDA and EMA for targeted therapy approval represent the most tightly regulated segment. Japanese hospital systems under PMDA's Sakigake designation are expanding companion diagnostic adoption fastest as neurological therapeutic pipelines mature.
- Biomarker Discovery:Exploratory proteomic and metabolomic profiling services support pharmaceutical R&D pipelines.
- Personalized Therapies:Patient-specific intervention designs tailored to genomic profiles complete the precision medicine value chain.
By volume, Genetic Testing leads. By growth pace, Companion Diagnostics is ahead.
End User:
Cost tiering separates high-complexity laboratory services from decentralized point-of-care deployment.
- Diagnostic Laboratories:Centralized reference facilities process high-throughput biomarker panels with economies of scale. Quest Diagnostics and Laboratory Corporation of America Holdings dominate United States volumes while Charité Berlin and University of Tokyo Hospital anchor regional networks in Germany and Japan.
- Hospitals:Embedded genomic testing infrastructure enables bedside pharmacogenomic profiling with faster turnaround. Cleveland Clinic and Charité Berlin deploy palm-sized sequencers for cardiology departments, bypassing external laboratory margins.
- Research Institutions:Academic centers generate clinical validation evidence for regulatory submissions.
- Pharmacies:Retail channels support direct-to-consumer pharmacogenomic testing in select markets.
Diagnostic Laboratories process the highest test volumes. Hospitals are gaining share fastest through infrastructure internalization.
Technology:
Application requirements dictate platform selection across chronic disease management versus acute intervention scenarios.
- Next-Generation Sequencing:Massively parallel sequencing platforms enable comprehensive genomic profiling with declining per-base costs. Platform economics now support rare disease screening previously deemed uneconomical, expanding addressable populations in German and Japanese specialist networks.
- CRISPR:Gene-editing diagnostics converge with point-of-care formats for decentralized screening. Preclinical pipelines in Indian and South African hospital networks target tuberculosis and antimicrobial resistance profiling.
- Microarrays:Targeted genotyping platforms deliver cost-effective pharmacogenomic screening for common variants.
- Digital PCR:Absolute quantification technology enables high-sensitivity biomarker detection for minimal residual disease monitoring.
Next-Generation Sequencing dominates installed base. CRISPR applications are climbing the fastest toward clinical translation.
Application:
Geographic concentration of specialist expertise shapes demand patterns across therapeutic areas.
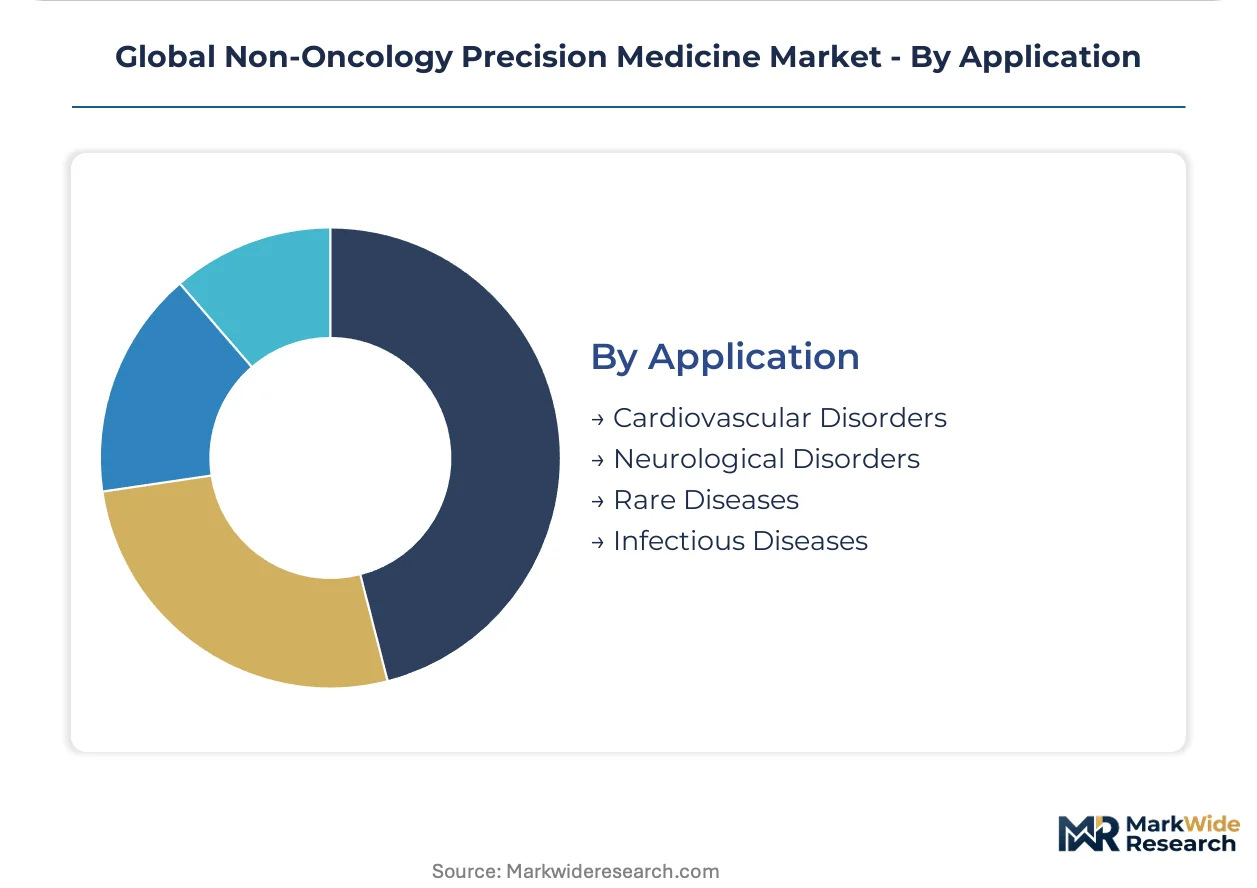
- Cardiovascular Disorders:Pharmacogenomic-guided anticoagulation and statin selection represent the most mature precision medicine workflows. German university hospitals and United States academic medical centers lead outcome-based contracting for genomic cardiology services.
- Neurological Disorders:Biomarker-stratified therapies for Alzheimer's and Parkinson's disease drive companion diagnostic development. Japanese hospital networks under PMDA's accelerated pathway are expanding fastest as neurological pipelines advance.
- Rare Diseases:Orphan condition diagnosis leverages comprehensive genomic testing with highest per-test economics.
- Infectious Diseases:Antimicrobial resistance profiling opens precision medicine beyond chronic disease management.
Cardiovascular Disorders anchor current revenue. Neurological Disorders represent the steepest expansion trajectory as therapeutic pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German diagnostic manufacturers export companion diagnostic platforms to Japanese hospital networks, establishing the primary trade corridor for precision medicine infrastructure. This bilateral flow concentrates high-value biomarker technology transfer between two regulatory-advanced jurisdictions.
United States
FDA's streamlined biomarker qualification pathways accelerate cardiovascular therapeutic approvals, compressing time-to-market for stratified interventions. The agency's companion diagnostic mandates force pharmaceutical manufacturers to integrate genomic strategies earlier in development pipelines. Boston and Stanford academic medical centers process the highest per-capita pharmacogenomic testing volumes as specialist networks embed pre-emptive genotyping into cardiology admission protocols.
Germany
EMA's In Vitro Diagnostic Regulation imposes extensive clinical evidence requirements on legacy cardiovascular biomarker assays, extending European launch timelines. German university hospitals lead outcome-based contracting for genomic cardiology services, tying laboratory payments to demonstrated reductions in adverse drug events. Charité Berlin anchors regional diagnostic networks while deploying palm-sized sequencers for bedside pharmacogenomic profiling.
Japan
PMDA's Sakigake designation fast-tracks companion diagnostic approvals for neurological precision therapies, positioning Japanese hospital systems as early-adopter reference sites. METI coordinates genomic medicine implementation across specialist networks. University of Tokyo Hospital deploys embedded genomic testing infrastructure that enables faster turnaround for cardiology departments, bypassing external laboratory margins.
India
Antimicrobial resistance profiling opens precision medicine applications beyond chronic disease management, with tuberculosis and sepsis protocols advancing in hospital networks. CDSCO maintains distinct but increasingly aligned standards for genomic test validation. Indian metropolitan clusters concentrate preclinical CRISPR diagnostic pipelines targeting infectious disease stratification in rural and underserved geographies.
United Kingdom
NHS England's genomic medicine service embeds comprehensive testing into standard care pathways for rare diseases, expanding addressable patient populations. The Medicines and Healthcare products Regulatory Agency coordinates with EMA on biomarker-qualified therapy assessments. London and Cambridge academic centers generate clinical validation evidence for regulatory submissions across cardiovascular and neurological indications.
Global Non-Oncology Precision Medicine Market Competitive Landscape
Player mix skews toward integrated diagnostic-therapeutic conglomerates with multi-continental laboratory networks. The competitive structure concentrates around three strategic archetypes: centralized reference laboratories processing high-throughput biomarker panels, integrated pharma-diagnostic platforms spanning cardiovascular and neurological applications, and specialized bioinformatics providers supporting rare disease programs. Dominant competitive moves include strategic partnerships between pharmaceutical manufacturers and diagnostic developers to satisfy FDA and EMA companion diagnostic mandates, plus geographic expansion of laboratory networks into Japanese and German hospital systems.
Within the integrated diagnostic-therapeutic tier, F. Hoffmann-La Roche Ltd and Abbott Laboratories occupy positions exemplifying platform convergence across therapeutic areas. Quest Diagnostics Inc. and Laboratory Corporation of America Holdings represent the scale-driven reference laboratory archetype with extensive North American network coverage. Qiagen Inc. and bioMérieux SA sit within the specialized molecular diagnostics segment, anchoring regional market presence through targeted assay portfolios.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Qiagen Inc. |
| Quest Diagnostics Inc. |
| Medtronic |
| Novartis |
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Laboratory Corporation of America Holdings |
| bioMérieux SA |
| Others |
Supply & Pricing Matrix
Ninety-day assay validation cycles compress pricing power for diagnostic manufacturers while simultaneously constraining inventory buffers across multi-jurisdictional supply networks. This lead-time compression concentrates margin pressure on European and Japanese laboratory networks navigating IVDR and PMDA certification requirements.
Pricing Analysis
Current-generation NGS platforms command premium pricing against prior-generation microarray systems and emerging CRISPR-based point-of-care formats. Three-tier pricing structure across premium, standard, and economy levels separates FDA-qualified companion diagnostics from CE-marked panels and research-use-only assays. Cost compression in economy-tier genetic testing is intensifying because hospital procurement committees now mandate outcome-based contracting. Academic medical centers in Boston and Stanford exhibit lowest price sensitivity due to embedded genomic infrastructure, while Indian and South African hospital networks face acute budget constraints.
Supply Chain Analysis
Inventory buffers for sequencing reagents and specialized bioinformatics hardware typically span 45-60 days across German, Japanese, and United States distribution hubs. Manufacturing concentration centers on Massachusetts, Basel, and Tokyo metropolitan clusters for high-complexity assay components. Raw material dependencies include semiconductor-grade silicon for flow cells, fluorophore chemistries for signal detection, and CRISPR guide RNA synthesis capacity. Single-source vulnerability characterizes next-generation sequencing instrument supply, with distribution running through regional reference laboratories and direct hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in non-oncology precision medicine hinge on interoperability architecture, as EHR integration failures fragment data liquidity and compress ecosystem value capture for standalone diagnostic developers.
For Market Incumbents: Fortify companion diagnostic portfolios through backward integration into bioinformatics pipelines, capturing margin previously allocated to third-party analytics providers. Secure capacity expansion in Japanese hospital networks under PMDA's Sakigake fast-track pathway to preempt emerging CRISPR diagnostic entrants. Channel control through exclusive Cleveland Clinic and Charité Berlin partnerships anchors high-volume genetic testing contracts against point-of-care decentralization threats. For New Entrants and Emerging Players: Differentiate on infectious disease stratification protocols targeting tuberculosis and sepsis screening in Indian and South African metropolitan clusters. White-space penetration concentrates in antimicrobial resistance profiling, where regulatory pathways remain less congested than cardiovascular companion diagnostics. Go-to-market execution through pharmacy retail channels for direct-to-consumer pharmacogenomic testing bypasses hospital procurement committee gatekeeping. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical conglomerates divesting non-core diagnostic divisions under portfolio rationalization pressures. Long-term viability across the analysis window rests on biomarker-qualified therapeutic co-development capabilities rather than standalone testing revenue. Monitor FDA-EMA-PMDA regulatory harmonization progress as the primary inflection signal for cross-border M&A activity acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA and EMA mandates force pharmaceutical-diagnostic partnerships earlier in therapeutic pipelines. |
| Point-of-Care Miniaturization | Palm-sized sequencers at Cleveland Clinic and University of Tokyo Hospital bypass centralized laboratory margins. |
| Outcome-Based Contracting | German university hospitals tie laboratory payments to demonstrated reductions in adverse drug events. |
| CRISPR Diagnostic Translation | Preclinical pipelines in Indian hospital networks target tuberculosis stratification in rural geographies. |
| EHR Interoperability Investment | Epic and Cerner genomic data field standardization resolves parallel informatics pipeline maintenance burdens. |
Research Methodology
Initial hypotheses were tested against primary input from diagnostic laboratory directors, pharmaceutical regulatory affairs leads, hospital procurement committee members, and bioinformatics platform engineers and refined through secondary validation against FDA 510(k) filings, EMA In Vitro Diagnostic Regulation guidance documents, ClinicalTrials.gov companion diagnostic trial records, and PMDA Sakigake designation announcements. Bottom-up assay volume modeling and top-down therapeutic pipeline sizing were triangulated to anchor market estimates.
Variance decomposition across technology platform, application area, and geographic regulatory cluster shaped the analytical framework throughout the forecast period. Segmentation dimensions included product format, end-user channel, sequencing technology generation, and therapeutic indication. CAGRs were derived from biomarker-qualified therapy approval velocity and NGS cost compression trajectories, with hospital infrastructure internalization rates and reimbursement policy evolution serving as key forecast sensitivity inputs.
Material uncertainties — reimbursement fragmentation in Southern European markets, IVDR transition timeline extensions, and CRISPR clinical translation delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory harmonization progress and hospital procurement committee behavioral shifts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Dry Eye Disease Market
Specialty Medicine
Kinase Inhibitor in Autoimmune Diseases Market
Specialty Medicine
Soft Tissue Sarcoma Market
Specialty Medicine
Disruptive Behavior Disorders Market
Specialty Medicine
Acute Lymphocytic-Lymphoblastic Leukemia (ALL) Therapeutics Market
Specialty Medicine
Palmoplantar Pustulosis Market
Specialty Medicine
Chronic Lymphocytic Leukemia Market
Specialty Medicine
Leukocytoclastic Vasculitis Market
Specialty Medicine
Cholangiocarcinoma Market
Specialty Medicine
Scleritis Market
Specialty Medicine
Ischemic Hepatitis Treatment Market
Specialty Medicine
Neuroendocrine Carcinoma Treatment Market
Specialty Medicine
Dry Eye Syndrome Market
Specialty Medicine
Global Bladder Disorders Market
Specialty Medicine
Frontotemporal Dementia Management Market
Specialty Medicine
Paediatric Sports Medicine Market