
 Herpangina Treatment Market | 2026-2036
Herpangina Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Herpangina Treatment Market Analysis
India's pharmaceutical manufacturing corridor is fragmenting as domestic API producers and finished-dose manufacturers compete for herpangina treatment supply contracts. Pfizer Inc leverages its pediatric formulation expertise to sustain shelf presence across hospital and retail channels. GSK Plc anchors its position through established analgesic portfolios that clinicians prescribe for symptomatic relief during enterovirus seasons.
Herpangina treatment encompasses pharmaceutical interventions targeting the Coxsackievirus and enterovirus infections that produce oral vesicular lesions, fever, and pharyngeal pain in children under ten years. Standard formulations include acyclovir-class antivirals, ibuprofen or acetaminophen analgesics, and lidocaine-based topical solutions manufactured as suspensions or oromucosal gels for pediatric tolerability. The product type dimension shows analgesics commanding the largest volume share due to their role as first-line symptomatic management, while antivirals represent the fastest-growing category as clinicians seek to shorten disease duration. Delivery mode segmentation reveals oral administration dominating outpatient settings, whereas topical solutions capture margin pools through premium pricing of rapid-acting anesthetic formulations.
FDA pediatric exclusivity provisions and the EMA's Paediatric Regulation shape development pipelines by mandating age-appropriate dosing studies before market authorization. The WHO Essential Medicines List inclusion criteria for pediatric analgesics influence procurement decisions by national health programs in low-resource settings. Stakeholders must monitor enterovirus surveillance data from the CDC and regional health agencies to align inventory positioning with outbreak seasonality.
Market Dynamics
Pediatric formulation requirements are compressing development timelines as regulators mandate age-appropriate dosing studies before market authorization, forcing manufacturers to prioritize liquid suspensions and oromucosal gels over conventional tablet formats.
Growth Catalysts
- FDA Pediatric Exclusivity Provisions:These incentives accelerate investment in herpangina-specific formulations by granting additional market protection for completed pediatric studies.
- Enterovirus Surveillance Systems:Real-time outbreak monitoring by the CDC enables healthcare systems to pre-position analgesic and antiviral inventories ahead of seasonal peaks.
- Oromucosal Gel Technology:Rapid-acting lidocaine delivery systems shorten time-to-relief metrics, expanding use in emergency pediatric settings.
Market Restraints
- API Supply Concentration:Dependence on Indian and Chinese active pharmaceutical ingredient manufacturers creates vulnerability to export licensing delays.
- Antiviral Efficacy Limitations:No approved direct-acting enterovirus antiviral exists, restricting treatment to symptomatic management.
- EMA Paediatric Study Burden:Mandatory age-stratified trials raise development costs for European market access.
Strategic Opportunities
- Combination Therapy Formats:Antiviral-analgesic co-formulations address unmet need for single-dose convenience in childcare outbreaks.
- India's Domestic API Expansion:Production-linked incentive schemes are attracting contract manufacturing for pediatric liquid formulations.
- Telehealth Prescription Channels:Remote pediatric consultations enable faster symptomatic treatment initiation during enterovirus seasonality.
Industry Challenges
- Palatability Engineering:Masking bitter antiviral agents in pediatric-acceptable suspensions requires specialized formulation expertise that remains scarce.
- Stability Validation Timelines:Accelerated shelf-life testing for liquid formulations extends regulatory submission cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herpangina Treatment Market |
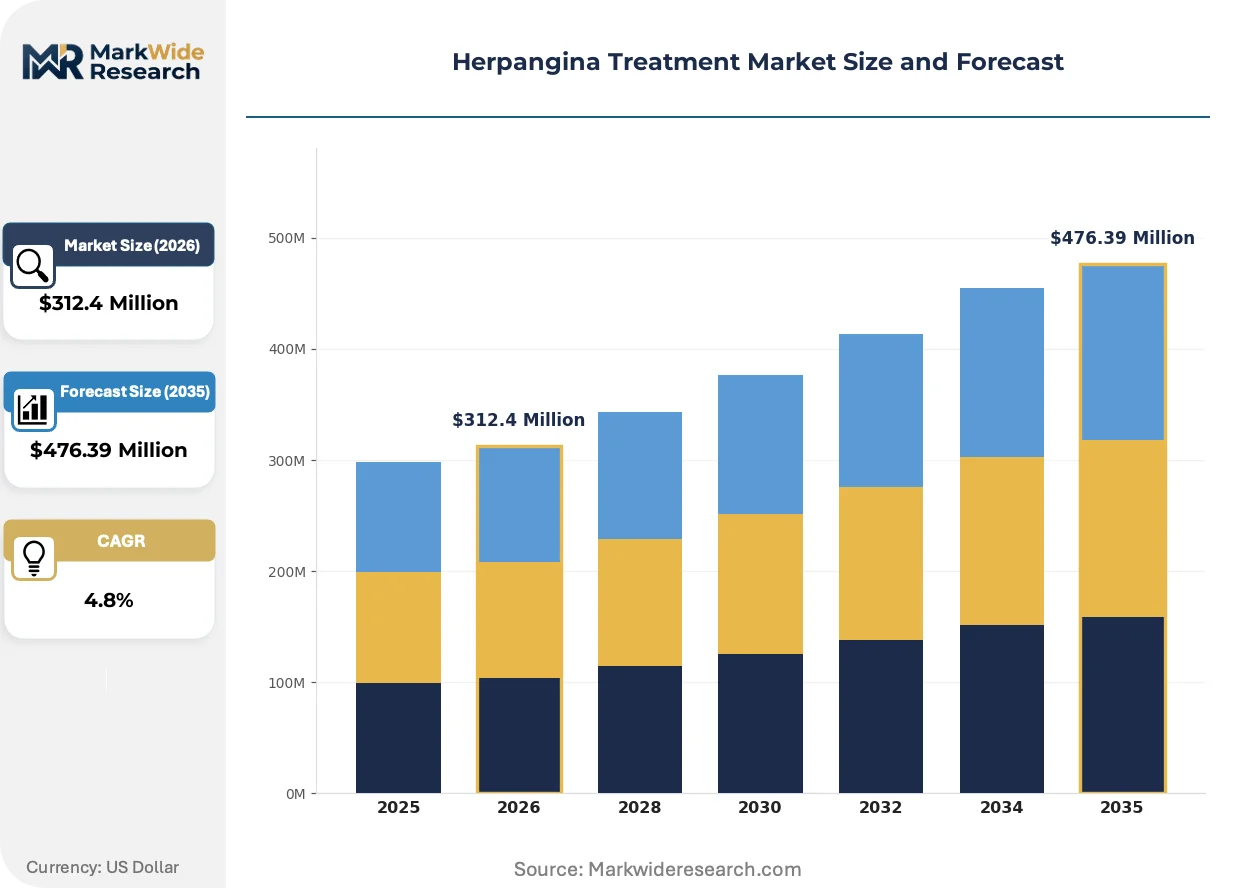
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antivirals, Analgesics, Topical Solutions, Oral Rinses Delivery Mode: Oral, Topical, Intravenous, Sublingual End User: Pediatric Clinics, Hospitals, Home Care, Pharmacies Therapy Area: Viral Infections, Pain Management, Symptomatic Relief, Prevention |
| Companies Covered | AstraZeneca, Bausch Health Companies Inc, Hoffmann-La Roche Ltd, Novartis AG, GSK Plc, Takeda Pharmaceutical Company Limited, AbbVie Inc, Gilead Sciences Inc, Pfizer Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herpangina Treatment Market Emerging Trajectories
Formulation science is converging with digital health infrastructure to reshape how herpangina treatments reach pediatric patients. Three developments are altering competitive positioning.
Nanostructured lipid carriers are hybridizing conventional topical delivery by encapsulating lidocaine in mucoadhesive matrices that prolong anesthetic contact with oral lesions. Pediatric dental clinics in the United States are adopting these systems for procedural pain management. The technology is compressing differentiation timelines for premium-priced rapid-relief products.
EMA's revised Paediatric Regulation implementation timelines are tightening age-de-escalation study requirements for analgesic approvals. Manufacturers must now submit pharmacokinetic data across neonatal, infant, and juvenile strata simultaneously. This regulatory compression favors established players with existing pediatric trial infrastructure.
Childcare facility procurement consortia are consolidating purchasing decisions for outbreak preparedness kits. These centralized buying pools bypass traditional wholesale distribution, squeezing margin structures for mid-tier analgesic suppliers. The consolidation is most advanced in United States metropolitan markets with integrated health system networks.
Herpangina Treatment Market Segmentation
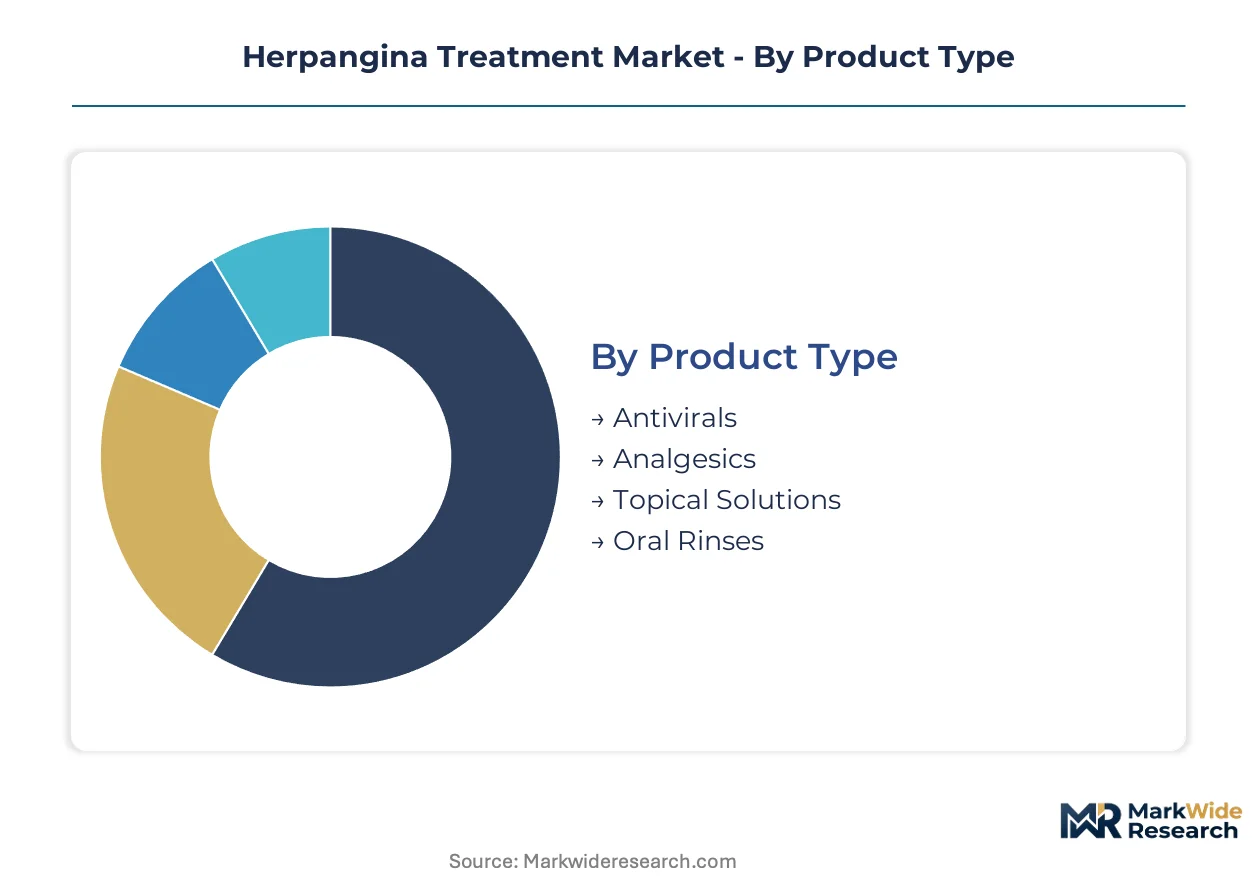
Herpangina treatment segmentation reflects the tension between symptomatic management and disease-modifying aspirations in pediatric infectious disease care. Product type and delivery mode choices determine reimbursement pathways, while end-user concentration shapes procurement contracting strategies across institutional and retail channels.
Product Type:
Use cases span outbreak containment in childcare facilities through to individual symptomatic relief in home settings.
- Analgesics:Ibuprofen and acetaminophen formulations dominate prescription volumes as first-line fever and pain management in children under ten. Demand concentrates in United States pediatric clinics during summer enterovirus seasons, driven by CDC surveillance-triggered inventory pre-positioning.
- Antivirals:Acyclovir-class agents target herpesvirus overlap presentations despite limited direct enterovirus efficacy. Clinicians in hospital settings prescribe these most heavily where diagnostic uncertainty exists, with off-label use expanding fastest where rapid PCR testing is available.
- Topical Solutions:Lidocaine-based oromucosal gels command premium pricing for rapid oral lesion anesthesia.
- Oral Rinses:Antiseptic formulations provide adjunctive hygiene support during vesicular healing phases.
Established volume favors analgesics; emerging adoption favors antivirals as diagnostic precision improves.
Delivery Mode:
Cost tiers separate premium rapid-acting formats from commodity oral administration.
- Oral:Liquid suspensions and chewable tablets constitute the pediatric default, with palatability-engineered formulations reducing administration refusal rates. Home care settings in India drive volume through affordable domestic manufacturing.
- Topical:Mucoadhesive gels and sprays deliver localized anesthetic action with faster onset than systemic routes. Emergency departments in United States metropolitan markets favor these for immediate distress reduction.
- Sublingual:Rapid-dissolve strips bypass first-pass metabolism for faster systemic absorption.
- Intravenous:Reserved for hospitalized patients with severe dehydration or dysphagia complications.
Outpatient preference anchors oral formats; margin expansion concentrates in topical innovation.
End User:
Customer type determines regulatory scrutiny intensity and procurement cycle timing.
- Pediatric Clinics:Seasonal outbreak response drives bulk purchasing of combination therapy kits. United States integrated health systems consolidate buying through centralized procurement consortia, squeezing distributor margins.
- Hospitals:Inpatient protocols emphasize IV hydration alongside symptomatic management for complicated cases. EMA pediatric study requirements shape formulary inclusion decisions across European tertiary centers.
- Home Care:Over-the-counter analgesic purchases spike during community enterovirus transmission peaks.
- Pharmacies:Retail dispensing captures recurring prescription refills and caregiver counseling interactions.
Institutional volume dominates antiviral prescribing; retail velocity drives analgesic replenishment cycles.
Therapy Area:
Maturity gradients separate established symptomatic categories from experimental prevention approaches.
- Symptomatic Relief:Fever reduction and pain management constitute the reimbursed standard of care across all geographies. WHO Essential Medicines List inclusion secures procurement priority in low-resource national health programs.
- Pain Management:Dedicated analgesic protocols address pharyngeal discomfort distinct from systemic fever control. United States dental clinics adopt topical formulations for procedural adjacency.
- Viral Infections:Antiviral targeting remains clinically limited by enterovirus biology, constraining category development.
- Prevention:Vaccine and prophylactic research pipelines hold preclinical status without near-term commercialization pathways.
Reimbursement certainty favors symptomatic relief; pipeline activity clusters in viral infection modification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold-chain infrastructure anchors European distribution for temperature-sensitive pediatric formulations, while Singapore's Changi Airport pharmaceutical hub mediates Asia-Pacific supply flows for outbreak response inventories.
United States
CDC enterovirus surveillance networks trigger seasonal procurement cycles across pediatric clinic networks, with the FDA's pediatric exclusivity provisions accelerating formulation investments. Integrated health systems in metropolitan markets consolidate purchasing through centralized consortia, compressing distributor margins for analgesic suppliers.
India
Domestic API producers compete aggressively for herpangina treatment supply contracts as production-linked incentive schemes expand pediatric liquid formulation capacity. CDSCO pediatric study requirements shape export registration timelines for finished-dose manufacturers. The Hyderabad-Visakhapatnam pharmaceutical corridor attracts contract manufacturing for oromucosal gel technologies.
Germany
EMA paediatric regulation mandates age-stratified pharmacokinetic data across neonatal, infant, and juvenile strata, raising development barriers for market entrants. Hospital formulary committees in Bavaria and North Rhine-Westphalia prioritize WHO Essential Medicines List inclusion for procurement decisions. The Frankfurt-Rhine-Main logistics cluster specializes in temperature-controlled distribution for pediatric suspensions.
Japan
PMDA pediatric drug development incentives reshape formulation priorities toward palatability-engineered oral suspensions. Meticulous enterovirus surveillance by the National Institute of Infectious Diseases enables precise inventory pre-positioning ahead of summer transmission peaks. The Kansai region's pharmaceutical manufacturing base supplies rapid-acting topical anesthetic formulations to dental clinics.
Brazil
ANVISA's pediatric labeling requirements drive reformulation investments for imported analgesic products targeting childcare facility outbreaks. Seasonal transmission patterns in São Paulo and Rio de Janeiro metropolitan areas concentrate demand for combination therapy kits. The São Paulo-Guarulhos pharmaceutical distribution hub mediates South American supply flows for enterovirus season preparedness.
Herpangina Treatment Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in API and excipient supply. The herpangina treatment market exhibits tiered consolidation, with established pharmaceutical conglomerates controlling pediatric formulation portfolios while regional manufacturers compete on commodity analgesic volume. Three archetypes dominate: patent-protected antiviral developers, branded analgesic portfolio holders, and contract manufacturers of liquid pediatric formulations. Competitive moves concentrate on M&A for pediatric trial infrastructure and strategic partnerships with childcare procurement consortia.
Among diversified pharmaceutical conglomerates, Pfizer Inc and GSK Plc occupy positions exemplifying the branded portfolio archetype, with Roche and Novartis AG representing the research-intensive antiviral development tier. These entities anchor competitive dynamics through established relationships with pediatric clinic networks and hospital formulary committees. Their presence shapes pricing benchmarks and regulatory submission standards that mid-tier manufacturers must match for market access.
| Leading Market Players |
|---|
| AstraZeneca |
| Bausch Health Companies Inc |
| Hoffmann-La Roche Ltd |
| Novartis AG |
| GSK Plc |
| Takeda Pharmaceutical Company Limited |
| AbbVie Inc |
| Gilead Sciences Inc |
| Pfizer Inc |
| Others |
Supply Flow & Price Mechanics
The Port of Rotterdam's pharmaceutical cold-chain infrastructure compresses freight costs for temperature-sensitive pediatric suspensions, concentrating margin pressure on mid-tier analgesic suppliers while enabling premium pricing for rapid-acting topical formulations in United States metropolitan markets.
Pricing Analysis
Volume-discount tiering structures separate institutional procurement consortia from retail pharmacy purchasing, with childcare facility buying pools commanding 15-20% price advantages on combination therapy kits. Price differentiation rests on palatability-engineered formulations versus commodity liquid suspensions, with FDA pediatric exclusivity provisions protecting premium tiers. Cost compression in standard analgesic categories is intensifying because Indian API producers are fragmenting contract manufacturing bids. Home care segments exhibit highest price sensitivity, whereas hospital formulary committees prioritize rapid-relief efficacy over unit cost.
Supply Chain Analysis
Export-control licensing delays for active pharmaceutical ingredients from India and China are extending lead times for finished-dose manufacturers, forcing inventory pre-positioning ahead of enterovirus seasons. Raw material dependencies center on ibuprofen and acetaminophen APIs, lidocaine base compounds, and specialized excipients for mucoadhesive gel matrices. Single-source vulnerability concentrates in Hyderabad-Visakhapatnam API corridors. Distribution runs through integrated health system consortia bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Herpangina treatment markets are expanding through early-cycle penetration of antiviral-analgesic combination protocols, with CDC surveillance integration enabling predictive inventory positioning that reduces stockout risk during seasonal peaks.
For Market Incumbents: Pre-empt formulation commoditization by securing captive API supply through backward integration into Indian production-linked incentive schemes. Defend margin position in topical segments through nanostructured lipid carrier patents that extend anesthetic duration. Channel control via exclusive childcare procurement consortia contracts blocks mid-tier entrants from institutional volume.
For New Entrants and Emerging Players: Establish a beachhead in telehealth prescription channels where remote pediatric consultations enable faster symptomatic treatment initiation without legacy distribution relationships. Target India's domestic API expansion for contract manufacturing partnerships that bypass European age-stratified study requirements. Go-to-market through direct-to-pharmacy liquid formulation supply avoids consolidated health system procurement barriers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical conglomerates divesting non-core pediatric portfolios, particularly analgesic brands lacking antiviral combination pipeline assets. Long-term viability hinges on regulatory trial infrastructure ownership that EMA paediatric regulation mandates. Watch FDA pediatric exclusivity grant velocity as inflection indicator for formulation investment returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Combination Therapy Development | Single-dose convenience addresses unmet need in childcare outbreak containment protocols. |
| API Supply Security Investment | Production-linked incentive schemes in India reduce dependence on Chinese export licensing. |
| Telehealth Channel Integration | Remote pediatric consultations compress time-to-treatment initiation during seasonal transmission peaks. |
| Palatability Engineering R&D | Masking bitter antiviral agents reduces administration refusal rates in children under ten. |
| Procurement Consortium Partnerships | Exclusive supply contracts with integrated health systems bypass wholesale margin compression. |
Methodological Framework
Cross-validation between formulary database audits and CDC surveillance records anchors the qualitative findings on seasonal demand patterns. Primary interviews with pediatric infectious disease specialists, hospital procurement managers, pharmaceutical regulatory affairs leads, and childcare facility health coordinators informed supply chain vulnerability assessments. Secondary sources include FDA pediatric exclusivity filings, EMA paediatric investigation plans, CDSCO export registration data, and WHO Essential Medicines List inclusion criteria. Bottom-up demand modeling across dosage forms and administration routes triangulates against top-down pharmaceutical expenditure tracking.
Calibration against historical enterovirus outbreak severity indices and pediatric clinic visit volume data validates growth trajectory assumptions across the analysis window. Segmentation dimensions encompass product type, delivery mode, end-user category, and regional regulatory cluster. CAGRs derive from compound growth modeling of prescription volumes adjusted for seasonality coefficients. Forecast inputs incorporate real-time surveillance integration adoption rates and formulation technology diffusion curves for nanostructured lipid carriers.
Sensitivities concentrate around API export licensing disruptions, EMA age-stratified study timeline extensions, and telehealth reimbursement policy shifts. Forecasts reflect documented assumptions regarding outbreak seasonality regularity and regulatory incentive continuity. Cross-checking against CDC enterovirus surveillance trend data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Abetalipoproteinemia Management Market
Specialty Medicine
Musculoskeletal System Disorders Market
Specialty Medicine
Pemphigus Vulgaris (PV) Treatment Market
Specialty Medicine
Vertigo Market
Specialty Medicine
Anaplastic Astrocytoma Market
Specialty Medicine
Hermansky Pudlak Syndrome Therapeutics Market
Specialty Medicine
Chronic Myelogenous Leukemia Treatment Market
Specialty Medicine
Global Cancer Therapy Market
Specialty Medicine
Cervical Cancer Therapeutics Market
Specialty Medicine
Essential Thrombocythemia Market
Specialty Medicine
Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Cystinuria Treatment Market
Specialty Medicine
Lung Disease Therapeutics Market
Specialty Medicine
Global Vasculitis Treatment Market
Specialty Medicine
Neuromuscular Disorders Treatment Market
Specialty Medicine
Borderline Personality Disorder Market