
 Non-Invasive Coronary Imaging Market | 2026-2036
Non-Invasive Coronary Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Invasive Coronary Imaging Market Intelligence
CE marking under the EU Medical Device Regulation is restructuring the cost-of-entry calculus for non-invasive coronary imaging equipment across European markets. Siemens Healthineers AG leverages its integrated CT-angiography platform to sustain leadership in low-dose radiation systems. GE HealthCare Technologies Inc. anchors its position through machine learning-enhanced image reconstruction software. Philips Healthcare differentiates via proprietary spectral CT capabilities that reduce contrast agent volumes.
Non-invasive coronary imaging encompasses computed tomography angiography, cardiac magnetic resonance imaging, positron emission tomography, and advanced echocardiography modalities that visualize coronary anatomy and myocardial perfusion without catheterization, typically operating at sub-millisievert radiation doses for CT protocols and relying on gadolinium or technetium-based contrast agents for functional assessment. CT angiography dominates procedural volume due to sub-minute scan times and widespread scanner availability, while cardiac MRI captures premium margins in myocardial viability assessment where soft-tissue contrast resolution exceeds CT capabilities. Machine learning integration represents the fastest-expanding technology segment, automating calcium scoring and stenosis quantification to reduce inter-reader variability and report turnaround times.
The FDA enforces premarket notification requirements under 21 CFR 892 for CT and MRI systems, while the EU MDR mandates clinical evidence for Class IIa and IIb imaging devices, creating divergent compliance burdens that favor manufacturers with established regulatory affairs infrastructure. ISO 13485 quality management certification has become table stakes for vendor qualification by hospital procurement committees across OECD markets. Stakeholders must monitor how CMS reimbursement decisions for coronary CT angiography in emergency department chest pain pathways reshape volume distribution between hospitals and freestanding diagnostic centers.
Market Dynamics
The FDA's low-dose radiation standards are compressing equipment replacement cycles across United States cardiology departments while machine learning integration absorbs capital budgets previously allocated to hardware upgrades.
Growth Catalysts
- EU MDR clinical evidence mandates:Class IIa and IIb imaging devices face elevated documentation requirements that favor established manufacturers with regulatory infrastructure, consolidating procurement toward certified vendors.
- CMS reimbursement pathways:Emergency department chest pain triage protocols now cover coronary CT angiography, redirecting procedural volume from catheterization laboratories to diagnostic imaging suites.
- Gadolinium-based contrast agents:Cardiac MRI programs at German university hospital networks drive demand for viability assessment protocols with superior soft-tissue resolution compared to CT alternatives.
Market Restraints
- Superconducting magnet supply concentration:Liquid helium dependency and cryogenic component manufacturing concentrate among specialty suppliers, exposing cardiac MRI system production to input volatility.
- Sub-millisievert CT protocol limitations:Radiation dose reduction below diagnostic thresholds compromises image quality in obese patients or coronary calcium scoring, restricting protocol universalization.
- 21 CFR 892 premarket notification:FDA 510(k) clearance timelines for iterative reconstruction algorithms extend software deployment cycles, delaying machine learning feature commercialization.
Strategic Opportunities
- Freestanding diagnostic center channel:CMS site-neutral payment policies enable independent imaging facilities to capture emergency department overflow volume outside hospital cost structures.
- Technetium-99m tracer convergence:Hybrid PET-CT myocardial perfusion protocols integrate metabolic and anatomical assessment, opening premium positioning against standalone functional imaging.
- ISO 13485 certification acceleration:Hospital procurement committees in OECD markets now mandate quality management documentation, creating competitive moat for certified vendors against emerging manufacturers.
Industry Challenges
- Dual-read certification requirements:Cardiac CT angiography interpretation demands specialized training beyond general radiology residency, constraining qualified reader supply and extending report turnaround times.
- Legacy PACS integration friction:Machine learning-enhanced reconstruction software requires DICOM conformance testing against hospital-specific archive systems, complicating enterprise deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Invasive Coronary Imaging Market |
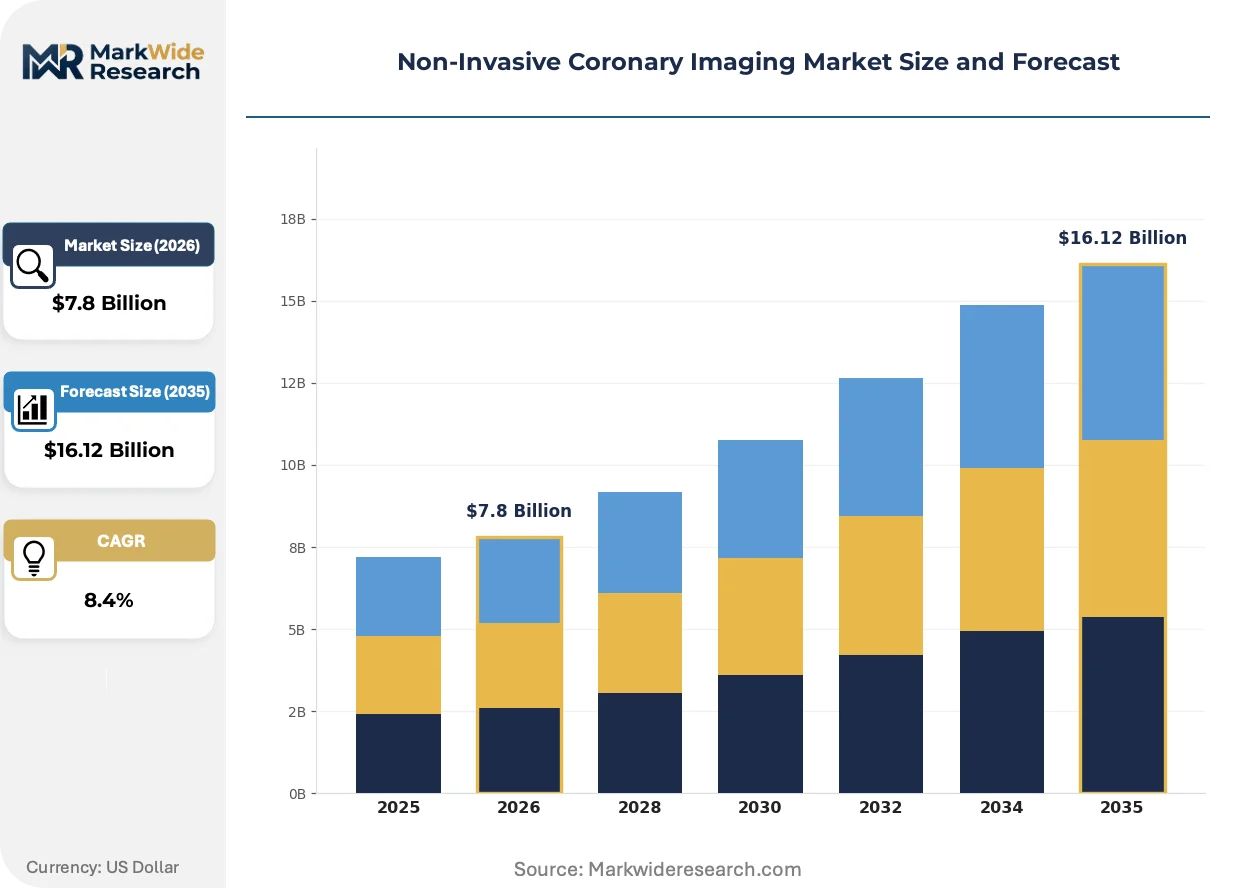
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CT Angiography, MRI, PET, Ultrasound Technology: 3D Imaging, Low-Dose Radiation, Contrast-Enhanced Imaging, Machine Learning End User: Hospitals, Diagnostic Centers, Research Institutions, Private Clinics Application: Cardiac Risk Assessment, Coronary Artery Disease, Atherosclerosis Detection, Follow-Up Imaging |
| Companies Covered | Siemens Healthineers AG, GE HealthCare Technologies Inc., Philips Healthcare, Canon Medical Systems Corporation, Fujifilm Healthcare Corporation, Neusoft Medical Systems Co., Ltd., United Imaging Healthcare, Shimadzu Corporation, Esaote SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Invasive Coronary Imaging Market Strategic Shifts & Innovations
Machine learning architectures are compressing the traditional trade-off between radiation exposure and diagnostic certainty, while spectral CT capabilities reframe contrast agent economics for high-volume screening programs.
Photon-counting detector technology is absorbing the functional role of energy-integrating detectors in coronary CT angiography systems. Tertiary hospital networks in Germany and the United States are piloting installations at replacement cycle points. This absorption is compressing the premium positioning of conventional dual-source CT platforms and accelerating depreciation schedules for installed base equipment.
The EU Medical Device Regulation's clinical evidence requirements for Class IIb imaging devices are extending conformity assessment timelines by twelve to eighteen months. Manufacturers with established notified body relationships capture procurement advantages as hospital committees prioritize CE-marked equipment. Cardiac MRI systems with gadolinium retention risk documentation face the most intensive scrutiny under MDR post-market surveillance mandates.
Hospital procurement committees are unbundling service contracts from equipment acquisition agreements, forcing vendors to price maintenance and software updates as discrete line items. This unbundling concentrates negotiating leverage among integrated delivery networks with centralized capital planning functions. The pattern is most visible in United States health systems pursuing standardization across multi-site cardiology service lines.
Non-Invasive Coronary Imaging Market Segmentation
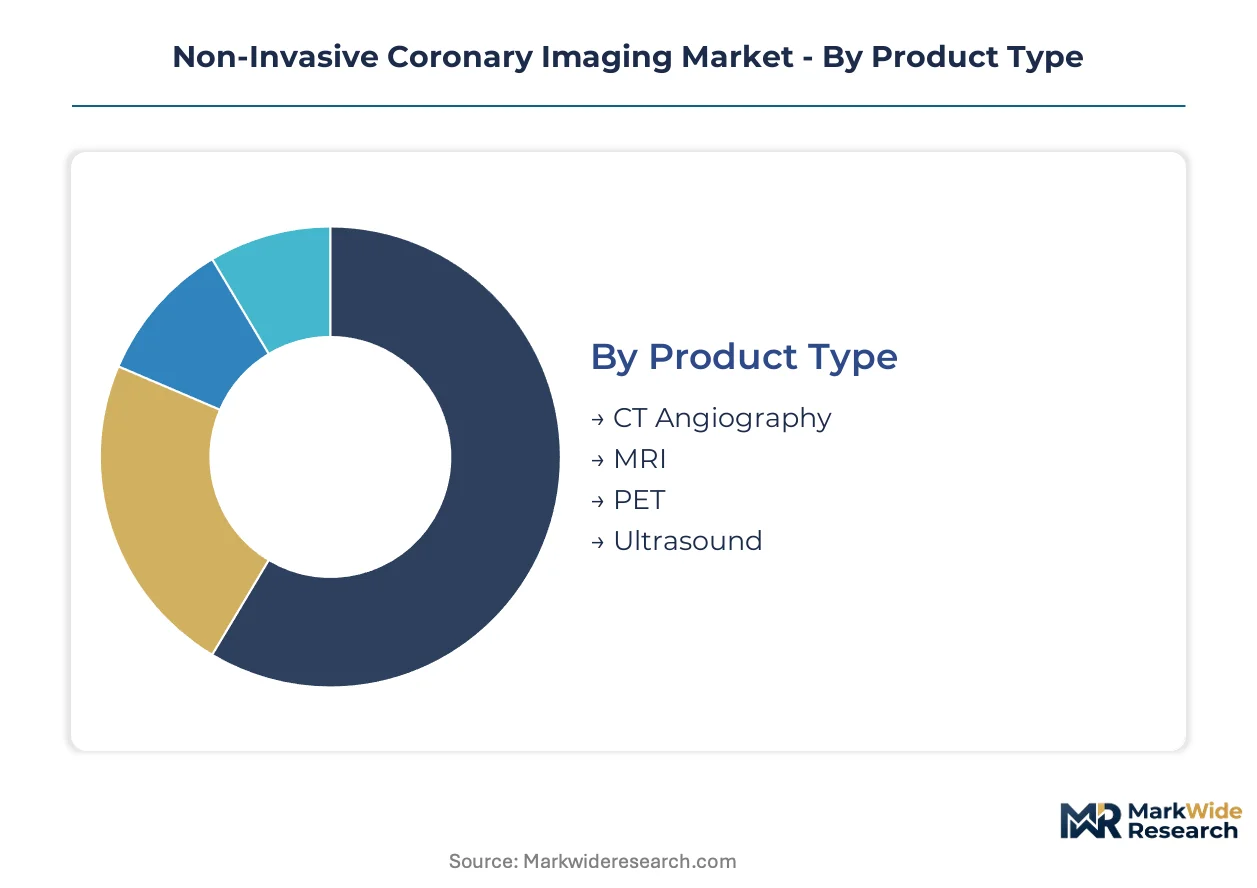
Equipment procurement committees weigh radiation exposure protocols against diagnostic throughput when selecting imaging platforms. Reimbursement pathways and contrast agent economics further segment purchasing behavior across acute care and ambulatory settings.
Product Type:
Capital allocation decisions prioritize scan speed against tissue resolution requirements.
- CT Angiography:Sub-minute acquisition times and widespread scanner availability concentrate procedural volume in emergency department chest pain triage. United States hospital networks favor iterative reconstruction algorithms to meet FDA low-dose radiation standards.
- MRI:Superior soft-tissue contrast resolution enables myocardial viability assessment with gadolinium-based agents. German university hospital networks anchor demand for cardiac MRI programs despite longer scan durations.
- PET:Hybrid perfusion-metabolic protocols require cyclotron proximity or technetium-99m supply chains, limiting deployment to tertiary centers.
- Ultrasound:Point-of-care echocardiography serves functional screening without ionizing radiation, capturing ambulatory volume outside hospital cost structures.
Volume sits with CT angiography; growth tilts toward MRI.
Technology:
Software capabilities now absorb capital budgets previously directed toward hardware replacement cycles.
- 3D Imaging:Volumetric reconstruction enables coronary tree visualization from limited-angle acquisitions, reducing breath-hold requirements for compromised patients.
- Low-Dose Radiation:Sub-millisievert protocols compress equipment replacement timelines as United States cardiology departments respond to FDA emphasis standards.
- Contrast-Enhanced Imaging:Spectral CT capabilities reduce iodinated contrast volumes, reframing agent economics for high-volume screening programs.
- Machine Learning:Automated calcium scoring and stenosis quantification reduce inter-reader variability, though FDA 510(k) clearance timelines extend software deployment cycles.
Installed base concentrates with low-dose radiation; margin expansion clusters around machine learning.
End User:
Site-neutral payment policies reshape volume distribution between integrated delivery networks and independent facilities.
- Hospitals:Tertiary centers absorb complex viability assessments and emergency department overflow, leveraging 24/7 interventional backup.
- Diagnostic Centers:Freestanding facilities capture elective coronary CT angiography volume outside hospital cost structures, enabled by CMS reimbursement pathway expansion.
- Research Institutions:Clinical trial infrastructure demands phantom validation and controlled protocol environments, limiting commercial scale.
- Private Clinics:Cardiology group practices deploy point-of-care ultrasound for functional screening, constrained by capital access relative to hospital systems.
Revenue concentrates in hospitals; volume migration favors diagnostic centers.
Application:
Clinical indication drives modality selection and reimbursement eligibility.
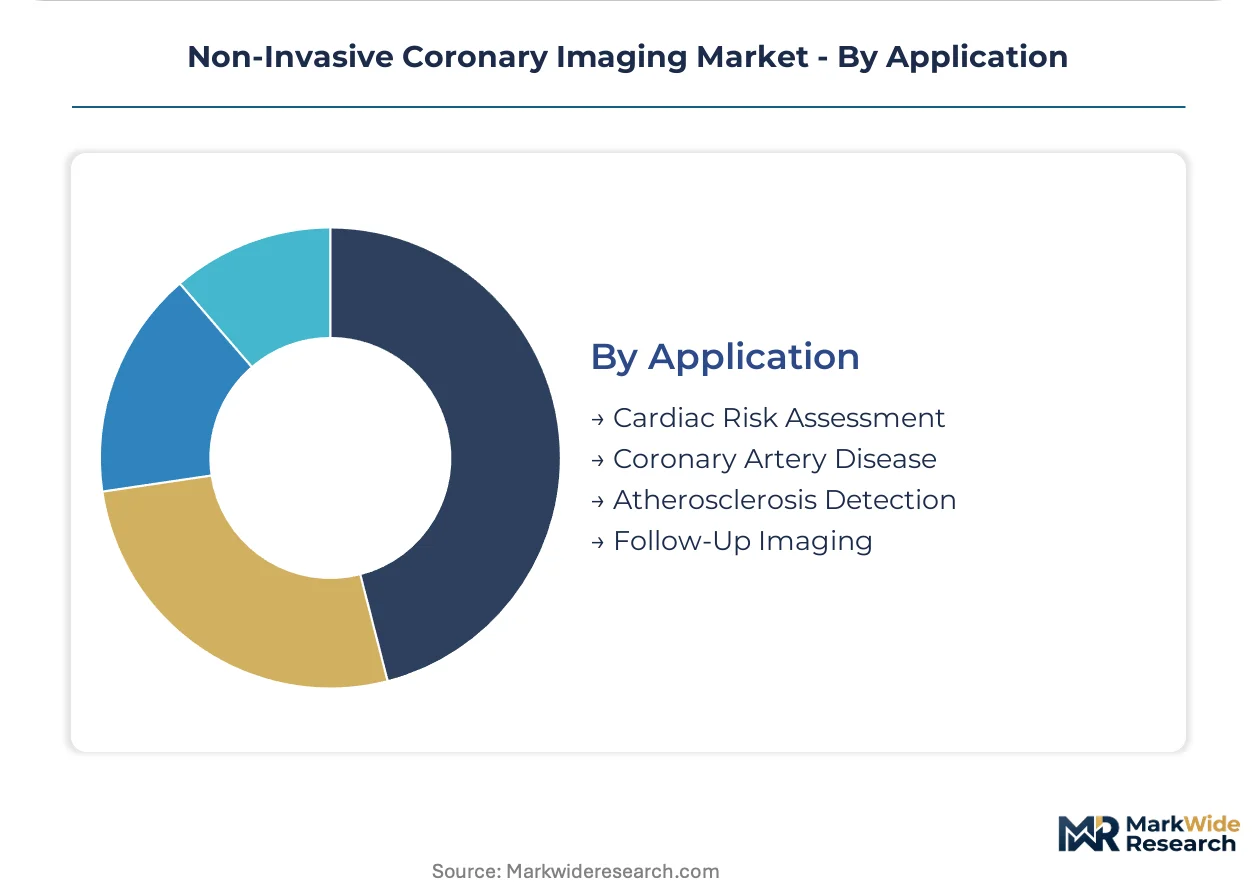
- Cardiac Risk Assessment:Asymptomatic screening programs leverage CT calcium scoring for stratification, though radiation exposure limits repeat frequency.
- Coronary Artery Disease:Anatomical stenosis quantification dominates CT angiography utilization, with machine learning automating report generation.
- Atherosclerosis Detection:Plaque characterization demands spectral CT or MRI soft-tissue contrast, commanding premium positioning.
- Follow-Up Imaging:Post-intervention surveillance protocols favor low-dose CT over invasive catheterization, absorbing repeat procedure volume.
Procedure volume clusters with coronary artery disease; protocol innovation centers on atherosclerosis detection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in Germany and the United States absorb the highest absolute equipment expenditure for non-invasive coronary imaging systems. University hospital networks in both countries anchor demand for premium cardiac MRI and spectral CT platforms. Regulatory divergence between FDA low-dose mandates and EU MDR clinical evidence requirements is reshaping vendor qualification criteria across these markets.
United States
Emergency department chest pain triage protocols now reimburse coronary CT angiography under CMS pathways, redirecting volume from catheterization laboratories. FDA enforcement of 21 CFR 892 premarket notification requirements compresses software deployment timelines for iterative reconstruction algorithms. Tertiary hospital networks in Boston and Cleveland anchor replacement cycles for photon-counting detector systems.
Germany
University hospital networks prioritize gadolinium-based cardiac MRI programs for myocardial viability assessment with superior soft-tissue resolution. CE marking under EU MDR extends conformity assessment timelines for Class IIb imaging devices by twelve to eighteen months. The Rhine-Ruhr and Bavarian medical technology clusters concentrate notified body relationships and regulatory affairs infrastructure.
China
Domestic equipment procurement is accelerating under NMPA streamlined approval pathways for innovative medical devices. National reimbursement catalog expansion for coronary CT angiography is redirecting patient volume toward tertiary hospitals in Beijing and Shanghai. The Yangtze River Delta medical device manufacturing base is absorbing localization requirements for superconducting magnet components.
Japan
PMDA regulatory harmonization with FDA standards is compressing time-to-market for low-dose radiation protocols developed in United States research programs. METI industrial policy supports domestic production of photon-counting detector arrays for next-generation CT platforms. The Kansai region around Osaka anchors precision manufacturing partnerships between imaging equipment vendors and semiconductor suppliers.
United Kingdom
NHS England specialized commissioning frameworks concentrate cardiac MRI capacity at designated supra-regional centers in London and Manchester. MHRA post-Brexit regulatory autonomy is diverging from EU MDR implementation timelines for legacy device registrations. The Oxford-Cambridge arc anchors clinical trial infrastructure for machine learning-enhanced image reconstruction validation.
Non-Invasive Coronary Imaging Market Key Industry Players
German and United States producers anchor one tier of integrated diagnostic platforms; Japanese and Chinese specialists hold positions in component supply and regional equipment distribution. The vendor structure concentrates around full-system manufacturers with captive software development capabilities, with mid-scale regional assemblers occupying secondary procurement channels. Three archetypes dominate: integrated multinationals with regulatory infrastructure, domestic champions with localization advantages, and component specialists with cryogenic or detector technology positions. Competitive dynamics center on M&A activity to acquire machine learning assets and strategic partnerships to secure superconducting magnet supply.
Within the integrated multinational tier, Siemens Healthineers AG and GE HealthCare Technologies Inc. occupy positions defined by established notified body relationships and FDA clearance infrastructure. Philips Healthcare anchors a third position in this tier through spectral CT differentiation. These three entities exemplify the regulatory-capital intensity required for Class IIb device commercialization under EU MDR and 510(k) pathways.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| GE HealthCare Technologies Inc. |
| Philips Healthcare |
| Canon Medical Systems Corporation |
| Fujifilm Healthcare Corporation |
| Neusoft Medical Systems Co., Ltd. |
| United Imaging Healthcare |
| Shimadzu Corporation |
| Esaote SpA |
| Others |
Cost & Logistics Intelligence
FDA low-dose radiation mandates gate qualified supply and premium-tier pricing access for CT angiography platforms, compressing equipment replacement cycles while concentrating procurement leverage among vendors with iterative reconstruction software cleared under 21 CFR 892.
Pricing Analysis
Lead-time-driven pricing angles dominate equipment procurement, with premium positioning for photon-counting detector systems available under twelve-month delivery windows and discounting for spot inventory of conventional dual-source CT platforms nearing replacement. Three-tier pricing structure across premium, standard, and economy levels separates spectral CT capabilities with machine learning integration from basic low-dose protocols and refurbished legacy systems. Pricing pressure stems from hospital procurement committees unbundling service contracts and demanding discrete line-item pricing for software updates. Integrated delivery networks exhibit lowest price sensitivity given centralized capital planning functions, while independent diagnostic centers negotiate aggressively on equipment acquisition costs.
Supply Chain Analysis
Workforce availability constraints in Japanese semiconductor fabrication and German precision engineering clusters limit photon-counting detector array production scaling. Superconducting magnet manufacturing concentrates in the United States, Germany, and China, with liquid helium supply chains anchored in Qatar and the United States. Raw material dependencies span rare earth elements for MRI gradient coils, high-purity silicon for detector substrates, and specialized cryogenic steel alloys. Single-source vulnerability in liquid helium refining exposes cardiac MRI system production to input volatility. Distribution runs through authorized dealer networks for hospital systems and direct vendor relationships for integrated delivery networks with multi-site standardization mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a consolidation play. EU MDR clinical evidence mandates for Class IIb imaging devices are forcing weaker manufacturers without established notified body relationships toward exit or acquisition.
For Market Incumbents: Cement regulatory-capital advantages by accelerating CE marking timelines for photon-counting detector platforms under EU MDR Article 52. Deepen backward integration into superconducting magnet supply through captive production partnerships in the Yangtze River Delta. Machine learning software assets represent the priority acquisition target to defend against iterative reconstruction algorithm specialists threatening hardware-software bundling positions.
For New Entrants and Emerging Players: Freestanding diagnostic center chains offer the most penetrable channel for CT angiography volume capture outside hospital cost structures. Target German university hospital networks for cardiac MRI program partnerships where gadolinium-based viability assessment protocols command premium positioning. A software-first go-to-market angle bypasses capital-intensive hardware manufacturing barriers.
For Investors and Strategic Acquirers: FDA 510(k) clearance for machine learning-enhanced calcium scoring algorithms is the leading indicator that automated image reconstruction is crossing from experimental to reimbursable standard of care. Long-term viability centers on vendors with dual FDA-EU regulatory infrastructure capable of serving both CMS reimbursement pathways and CE-marked European procurement. Watch for concentrated hospital procurement committee standardization decisions across multi-site cardiology service lines as the inflection signal for platform consolidation winners.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence mandates compress procurement advantages toward established notified body relationships. |
| Hospital System Partnership | Integrated delivery network standardization across multi-site cardiology service lines locks in platform replacement cycles. |
| Software Companion Development | Machine learning-enhanced calcium scoring automates report generation and reduces inter-reader variability. |
| Reimbursement Strategy | CMS emergency department chest pain pathway expansion redirects volume from catheterization laboratories to imaging suites. |
| FDA Submission | 510(k) clearance for iterative reconstruction algorithms gates commercial deployment of low-dose radiation protocols. |
Research Approach
Trade publications, FDA 510(k) clearance databases, and EU MDR notified body conformity assessment records formed the secondary backbone for equipment procurement trend validation. Primary interviews with hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and cardiology department heads combined with secondary validation through hospital procurement databases and CMS Medicare reimbursement data. Bottom-up triangulation across installed base estimates and top-down cross-check against capital expenditure disclosures anchored volume and value outputs.
Historical trendline analysis of replacement cycle timing and technology adoption S-curves informed the projection framework across the analysis window. Segmentation modeling incorporated modality type, technology tier, end-user facility category, and regional regulatory cluster dimensions. CAGRs were derived from equipment shipment unit economics and average selling price trajectories. Forecast inputs included superconducting magnet supply constraints and machine learning software penetration rates.
Caveats apply where FDA low-dose radiation standard enforcement intensity or EU MDR post-market surveillance mandate expansion could materially shift the outlook. Forecasts reflect assumptions around CMS reimbursement stability and liquid helium supply chain continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Diagnostic Imaging Market
Medical Imaging
India Digital X-Ray Market
Medical Imaging
Industrial Radiography Equipment Market
Medical Imaging
India Magnetic Resonance Imaging Market
Medical Imaging
Spain Computed Tomography Market
Medical Imaging
UK Imaging Services Market
Medical Imaging
Industrial X-Ray Machine Market
Medical Imaging
Mammography Detectors Market
Medical Imaging
United States Diagnostic Imaging Market
Medical Imaging
Global Colposcopy Market
Medical Imaging
China Mammography Market
Medical Imaging
France Mammography Market
Medical Imaging
Germany Digital Radiology Market
Medical Imaging
Functional Brain Imaging Systems Market
Medical Imaging
Italy Digital X-Ray Market
Medical Imaging
Global Veterinary Radiography System Market