
 Organic Skincare Products Market | 2026-2036
Organic Skincare Products Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Skincare Products Market Outlook
Direct-to-consumer digital channels is rewriting how organic skincare reaches buyers, bypassing traditional department store counters. L'Oréal S.A. leverages its scale to dominate mass-market organic lines across Europe and North America. Weleda AG anchors its position through biodynamic farming certifications and pharmacy-channel loyalty in German-speaking markets. Natura & Co differentiates via refill stations and carbon-neutral shipping programs in Latin America.
Organic skincare products are cosmetic formulations containing certified organic agricultural ingredients, typically requiring minimum thresholds of plant-derived components produced without synthetic pesticides or genetically modified organisms. These formulations serve consumers seeking reduced chemical exposure and environmental accountability in personal care routines. Moisturizers lead product type revenue due to daily-use frequency and premium pricing tolerance among health-conscious consumers. Botanical extracts command ingredient type preference as supply chains for aloe vera, chamomile, and green tea mature across India and Morocco. Glass jars capture packaging type margins in luxury segments despite higher logistics costs, while biodegradable tubes gain traction among eco-friendly advocates seeking plastic reduction.
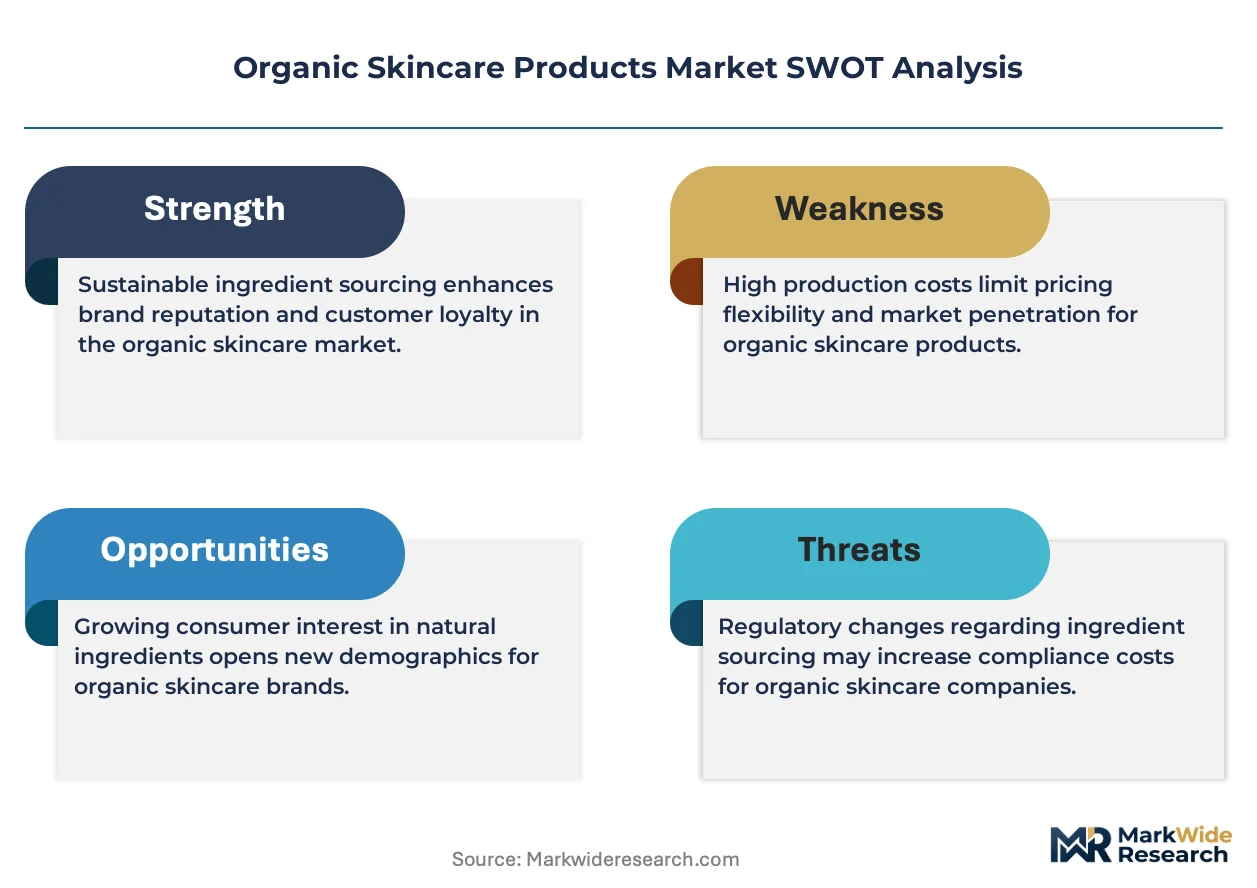
The USDA Organic seal and NSF/ANSI 305 standards govern label claims in the United States, while ECHA enforces REACH compliance for preservative restrictions across Europe. These frameworks elevate compliance costs for smaller formulators but simultaneously create market access barriers that benefit established certified producers. Stakeholders must monitor evolving definitions of natural versus organic as regulators in multiple jurisdictions consider tightening classification thresholds.
Market Dynamics
Clean beauty certification requirements are fragmenting supply chains as formulators race to meet diverging organic thresholds across jurisdictions. REACH chemical safety standards in Europe and the USDA Organic seal in the United States now demand incompatible documentation trails, forcing producers to maintain parallel compliance systems.
Growth Catalysts
- EU Green Deal mandates:The European Commission's chemical sustainability framework accelerates reformulation timelines for preservative-free product lines. German and French retailers now require full ingredient genealogy disclosure.
- Gen Z digital purchasing:Social commerce platforms capture first-time organic skincare buyers through algorithmic personalization. South Korean beauty influencers drive cross-border trial rates via live-streaming commerce.
- Biodynamic agriculture expansion:Certified organic raw material output from Moroccan cooperatives and Indian aloe vera estates is scaling to meet contract manufacturing demand.
Market Restraints
- Glass packaging logistics:Premium jar formats incur 40% higher freight costs versus plastic alternatives, compressing margin structures for mid-tier brands.
- Preservative substitution limits:Natural antimicrobial alternatives like rosemary extract and silver citrate demonstrate shorter shelf stability than synthetic parabens.
- Certification cost concentration:Small-batch formulators face disproportionate audit expenses relative to revenue, creating scale barriers in the United States and Germany.
Strategic Opportunities
- Latin American refill infrastructure:Natura & Co's carbon-neutral shipping programs demonstrate viable direct-to-consumer models for Brazilian and Mexican urban markets.
- Pharmacy channel integration:Weleda AG's apothecary partnerships in Switzerland and Austria validate clinical positioning for sensitive-skin organic segments.
- Biodegradable tube manufacturing:Sugarcane-derived packaging technologies from Brazilian suppliers align with plastic reduction commitments by major European retailers.
Industry Challenges
- Formulation chemist scarcity:Natural preservative stabilization requires specialized expertise in emulsion chemistry that outpaces current vocational training output.
- Multi-jurisdiction label compliance:Simultaneous NSF/ANSI 305, COSMOS, and EWG verification demands dedicated regulatory staff that strains emerging brand budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Skincare Products Market |
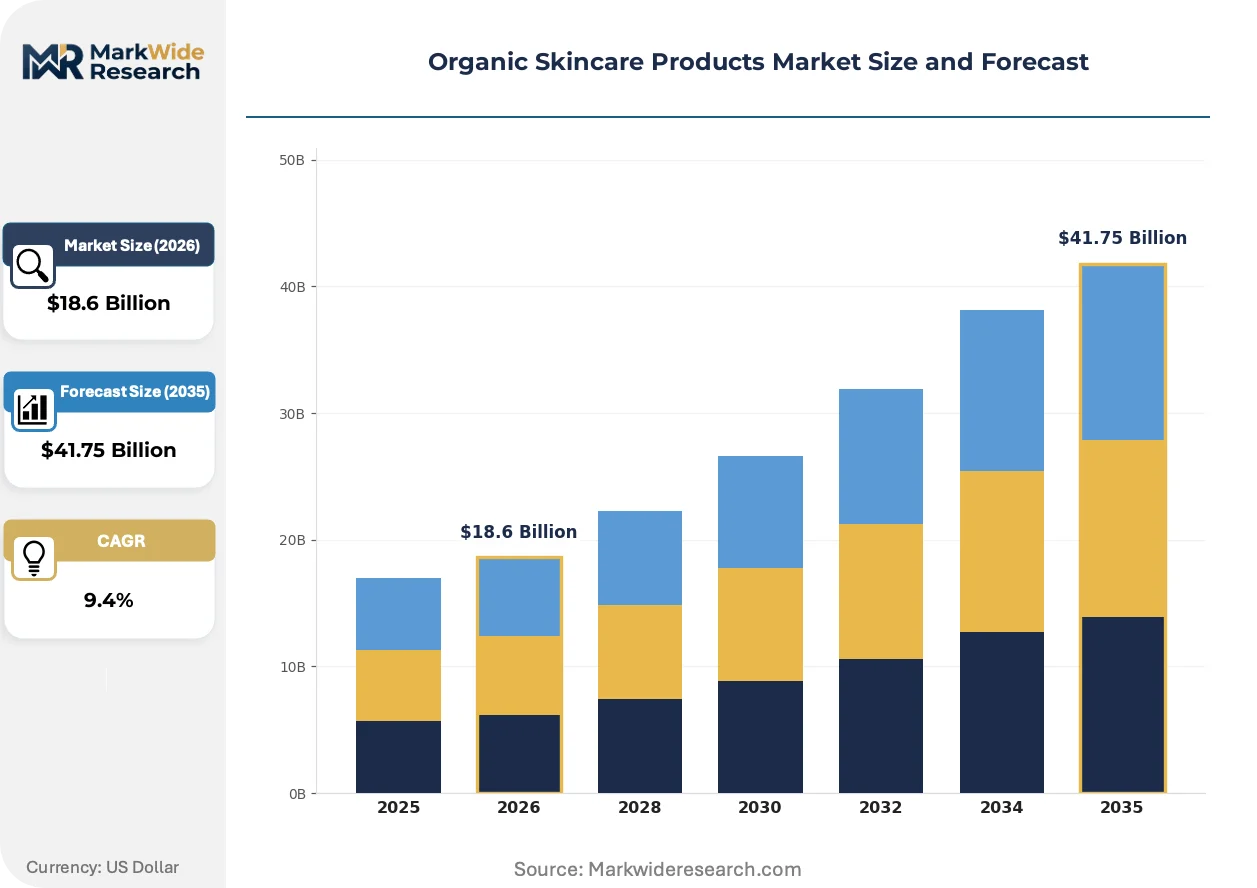
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $41.75 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Cleansers, Serums, Exfoliators Ingredient Type: Botanical Extracts, Essential Oils, Natural Surfactants, Plant-Based Emollients Packaging Type: Glass Jars, Biodegradable Tubes, Recyclable Bottles, Compostable Packs Customer Type: Health-Conscious Consumers, Eco-Friendly Advocates, Luxury Shoppers, Organic Enthusiasts |
| Companies Covered | L'Oréal S.A., The Estée Lauder Companies Inc., Shiseido Company Limited, Weleda AG, Natura & Co, Burt's Bees, The Body Shop International Limited, Hain Celestial Group, Unilever PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Skincare Products Market Strategic Shifts
Biotechnology-derived actives are displacing conventional botanical extraction methods across premium organic skincare lines. Fermentation processes now yield concentrated ceramides and peptides without petrochemical feedstocks.
Waterless formulation technology is migrating from solid shampoo bars into facial skincare categories. Indie brands in Portland and Copenhagen lead adoption with anhydrous balm concentrates. This shift compresses packaging volume requirements and reduces preservative load, enabling simpler organic certification pathways.
REACH Annex XVII updates are tightening restricted substance lists for cosmetics sold across the European Economic Area. ECHA's 2024 microplastic ban specifically targets rinse-off products with synthetic glitter and exfoliating beads. German formulators are accelerating biodegradable alternative sourcing from cellulose suppliers in Austria and the Nordic region.
Ingredient transparency apps are reshaping purchase verification habits among Millennial buyers in the United States. Third-party databases like Think Dirty and Yuka scan barcodes to flag synthetic components, bypassing brand-controlled marketing claims. Clean beauty retailers in Los Angeles and New York now integrate these tools into in-store consultation workflows.
Organic Skincare Products Market Segmentation
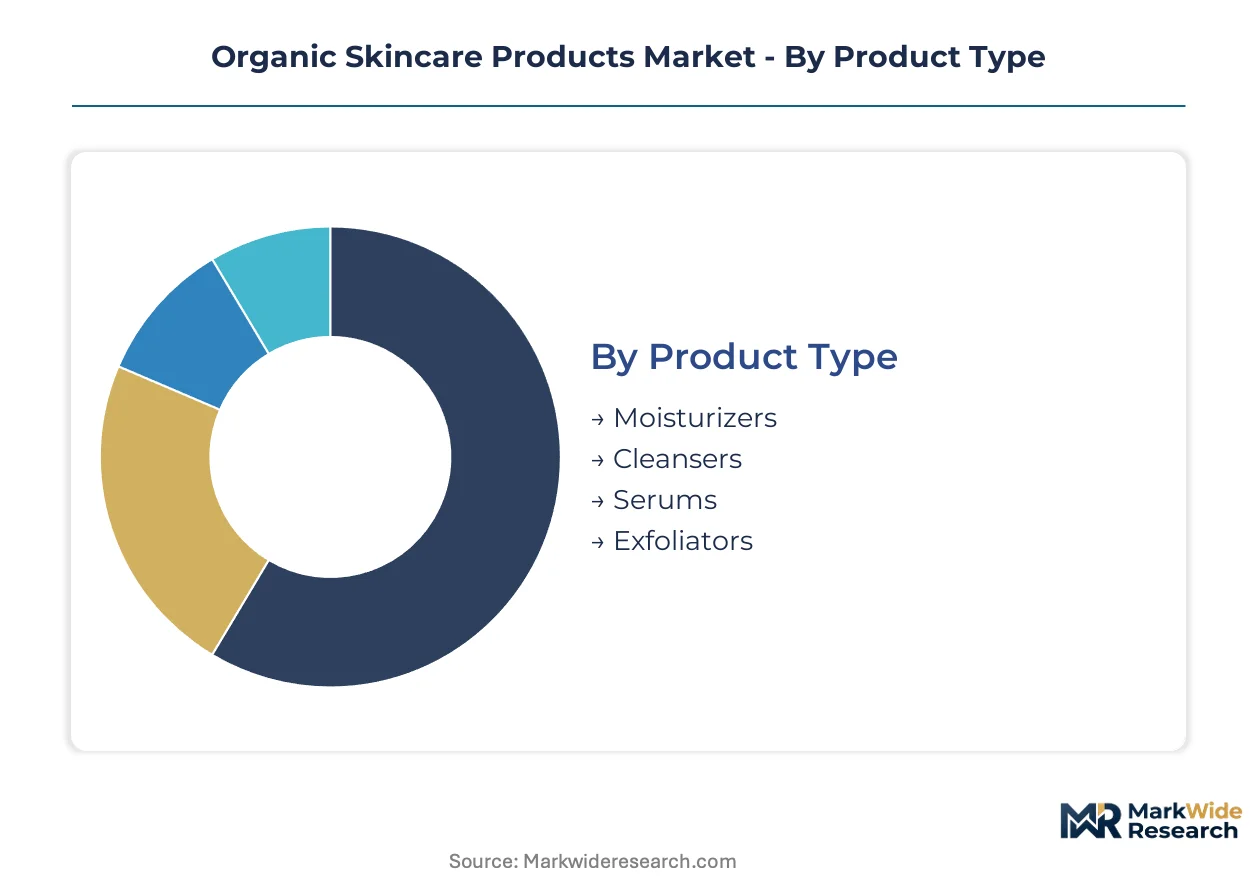
Segmentation in organic skincare reveals how certification standards, packaging economics, and purchasing psychology fragment addressable demand. Formulators must align R&D investment with distinct technical requirements across moisture barriers, preservative systems, and material compatibility.
Product Type:
Daily-use frequency spans from twice-daily rituals to weekly intensive treatments, creating divergent margin and formulation complexity profiles.
- Moisturizers:Emulsion-based formulations combining aqueous and lipid phases demand sophisticated natural preservative stabilization. Daily application frequency in the United States and Germany supports premium pricing tolerance among consumers seeking barrier repair without synthetic silicones.
- Cleansers:Surfactant systems derived from coconut glucosides or decyl glucoside require careful pH balancing to maintain efficacy without sulfates. South Korean consumers drive foaming texture innovation through amino acid-based natural surfactants.
- Serums:Concentrated active delivery vehicles with minimal emulsifier loads.
- Exfoliators:Physical and enzymatic variants utilizing fruit-derived AHAs or jojoba beads.
Established volume favors Moisturizers; emerging adoption favors Serums.
Ingredient Type:
Raw material sourcing geography and extraction method determine certification eligibility and supply security.
- Botanical Extracts:Standardized concentrations from aloe vera, chamomile, and green tea require batch-to-batch consistency verification. Moroccan cooperatives and Indian contract farms now supply ECHA-compliant documentation chains for European formulators.
- Essential Oils:Steam-distilled or cold-pressed volatile compounds from lavender, tea tree, and rosehip carry allergen disclosure obligations under REACH. French and German aromatherapy traditions sustain pharmacy-channel demand for therapeutic-grade sourcing.
- Natural Surfactants:Sugar-based cleansing agents from coconut or corn feedstocks.
- Plant-Based Emollients:Squalane from olive or sugarcane fermentation replacing shark-derived alternatives.
Supply security concentrates with Botanical Extracts; formulation innovation concentrates with Essential Oils.
Packaging Type:
Material choice directly constrains logistics economics, shelf stability, and retailer sustainability scoring.
- Glass Jars:Inert borosilicate or soda-lime containers prevent oxidation of lipid-rich formulations. Swiss and Austrian luxury retailers mandate glass for premium positioning despite 40% freight cost premiums over plastic alternatives.
- Biodegradable Tubes:Polylactic acid or sugarcane-derived polyethylene structures decompose in industrial composting facilities. Brazilian suppliers now export tube manufacturing technology aligned with European retailer plastic reduction commitments.
- Recyclable Bottles:Post-consumer resin or aluminum formats for liquid serums and toners.
- Compostable Packs:Molded fiber or seaweed-based single-use sachets for sample and travel formats.
Margin capture favors Glass Jars; volume scaling favors Biodegradable Tubes.
Customer Type:
Purchasing motivation splits between health outcomes, environmental accountability, and status signaling.
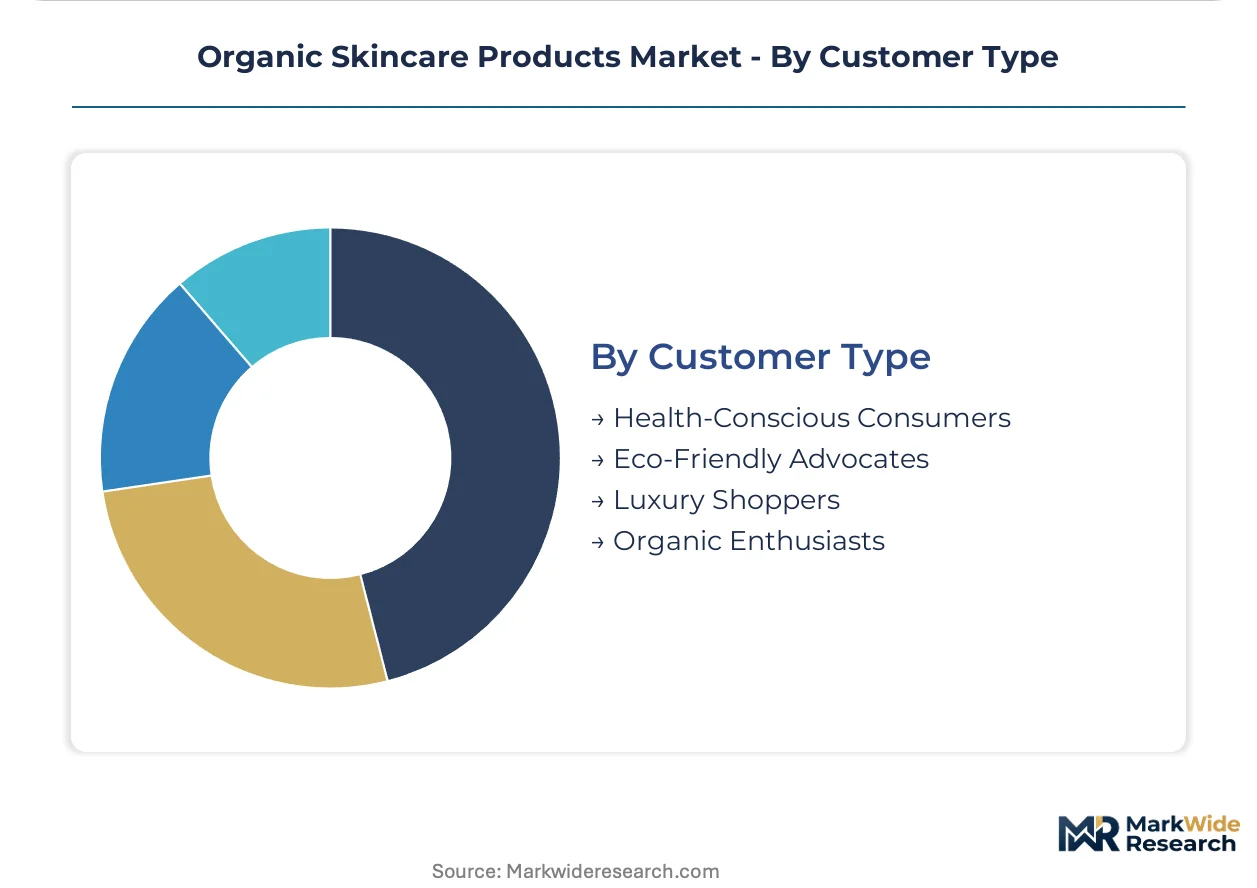
- Health-Conscious Consumers:Ingredient-averse buyers prioritizing reduced chemical exposure and dermatological safety. United States buyers utilize Think Dirty and Yuka apps to verify claims before purchase in Los Angeles and New York retail environments.
- Eco-Friendly Advocates:Carbon footprint and packaging waste drive substitution decisions. German and French urban consumers demonstrate highest willingness to pay for refill infrastructure and carbon-neutral shipping programs.
- Luxury Shoppers:Aesthetic and experiential purchasing with certification as quality signal.
- Organic Enthusiasts:Ideological commitment to agricultural purity and biodynamic farming methods.
Mass-market volume concentrates with Health-Conscious Consumers; margin expansion concentrates with Eco-Friendly Advocates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA Organic certification anchors the United States market, where FDA oversight of cosmetic labeling intersects with state-level clean beauty mandates in California and New York. REACH compliance and ECHA enforcement shape European formulation standards, while MFDS registration requirements govern South Korean ingredient disclosure.
United States
Health-conscious consumers in Los Angeles and New York utilize Think Dirty and Yuka apps to verify ingredient claims before purchase. FDA cosmetic labeling regulations require disclosure of fragrance allergens under the Fair Packaging and Labeling Act. California's Proposition 65 enforcement has driven reformulation of preservative systems across contract manufacturers in the Los Angeles basin.
Germany
Pharmacy-channel loyalty for biodynamic-certified products sustains premium pricing in Munich, Hamburg, and Berlin metropolitan areas. ECHA REACH Annex XVII restrictions on microplastics and synthetic preservatives accelerate natural alternative sourcing. The Baden-Württemberg region hosts concentrated formulator clusters serving COSMOS-certified private label contracts for French and Swiss retailers.
South Korea
Beauty influencers drive cross-border trial rates through live-streaming commerce platforms targeting Millennial and Gen Z demographics. MFDS cosmetic safety standards mandate pre-market notification for new organic ingredient combinations. Seoul's Gangnam district anchors flagship retail concepts where digital-native purchasing habits concentrate highest clean beauty penetration rates.
France
Therapeutic-grade essential oil traditions sustain pharmacy-channel demand in Paris, Lyon, and Marseille. ANSM enforces allergen labeling for fragrance compounds under EU cosmetics regulation. The Provence-Alpes-Côte d'Azur region supplies lavender and rosehip extraction capacity for certified organic supply chains serving German and Swiss formulators.
Brazil
Carbon-neutral shipping programs and refill station infrastructure target eco-friendly advocates in São Paulo and Rio de Janeiro urban markets. ANVISA cosmetic registration requires toxicological evaluation of natural preservative alternatives. São Paulo state hosts sugarcane-derived bioplastic tube manufacturing clusters aligned with European retailer plastic reduction commitments.
Organic Skincare Products Market Competitive Environment
Mass-market conglomerates and certified specialists split the market into divergent margin structures. L'Oréal S.A. leverages scale advantages across multi-brand portfolios, while Weleda AG and Natura & Co occupy certification-authenticated positions. Three archetypes dominate: scale-driven mass-market players, biodynamic-certified heritage brands, and direct-to-consumer digital natives. Competitive moves concentrate on M&A absorption of indie labels and vertical integration into raw material sourcing.
Within the heritage-certified tier, Weleda AG exemplifies biodynamic farming authentication through pharmacy-channel anchoring in German-speaking markets. Natura & Co occupies the Latin American direct-to-consumer vector with refill infrastructure and carbon-neutral logistics programs. L'Oréal S.A. represents scale-driven mass-market penetration across European and North American retail chains.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| The Estée Lauder Companies Inc. |
| Shiseido Company Limited |
| Weleda AG |
| Natura & Co |
| Burt's Bees |
| The Body Shop International Limited |
| Hain Celestial Group |
| Unilever PLC |
| Others |
Value Chain & Pricing Dynamics
Moroccan aloe vera cooperatives and Indian chamomile estates anchor global botanical extract supply, with their certified organic output contracting directly to European and North American formulators. This geographic concentration grants raw material suppliers pricing leverage over mid-tier brands unable to secure long-term offtake agreements. Glass packaging freight premiums and certification audit costs further compress margin structures for smaller players lacking scale economies.
Pricing Analysis
Price spreads between German pharmacy-channel biodynamic lines and mass-market organic alternatives in US retail chains span three distinct certification tiers. Premium-mid-economy pricing differentiation rests on COSMOS certification depth and USDA Organic seal compliance. Cost compression in the mid-tier intensifies because REACH Annex XVII reformulation demands and glass logistics premiums squeeze brands lacking L'Oréal-scale procurement leverage. Health-conscious consumers utilizing ingredient-scanning apps demonstrate highest price sensitivity, while eco-friendly advocates in Berlin and Paris accept premium positioning for refill infrastructure and carbon-neutral shipping.
Supply Chain Analysis
Contract manufacturing capacity concentrates among German private-label specialists serving COSMOS-certified pharmacy chains and Brazilian sugarcane-bioplastic tube producers supplying European retailer sustainability programs. Raw material sourcing draws from Moroccan cooperative networks, Indian aloe vera estates, and Provence lavender extraction facilities. Single-source vulnerability runs through Indian monsoon-dependent botanical harvests and Austrian cellulose suppliers for biodegradable exfoliant alternatives. Distribution runs through direct-to-consumer digital platforms capturing Gen Z trial rates, pharmacy-channel loyalty networks in German-speaking markets, and clean beauty specialty retailers in Los Angeles and New York.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward algorithmic personalization platforms and ingredient-transparency apps, fragmenting traditional brand loyalty while concentrating leverage among digital-native purchasing channels. This consolidation among discovery and verification intermediaries demands strategic repositioning across stakeholder archetypes.
For Market Incumbents: Pre-empt indie brand acquisition opportunities in waterless formulation technology and fermentation-derived active segments before valuation multiples adjust. Fortify pharmacy-channel anchoring through biodynamic certification investments that emerging digital-native competitors cannot replicate quickly. Defensive patent positioning around natural preservative stabilization chemistry blocks challenger entry in the United States and Germany.
For New Entrants and Emerging Players: Mid-market refill infrastructure in Brazilian and Mexican urban corridors represents the most penetrable entry point, with ANVISA registration pathways less congested than FDA or ECHA compliance queues. Waterless balm concentrates for facial skincare categories offer formulation differentiation with reduced certification complexity. Direct-to-consumer launch through live-streaming commerce partnerships with Seoul-based beauty influencers enables cross-border trial rate capture without legacy retail slotting fees.
For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate beauty portfolios where organic lines lack dedicated supply chain investment or certification depth. Long-term viability over the next decade hinges on backward integration into Moroccan cooperative equity stakes or Indian contract farm offtake agreements. Watch for inflection signals in ECHA microplastic enforcement acceleration and USDA Organic threshold tightening proposals.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodynamic Certification Investment | Pharmacy-channel access in Munich and Berlin validates premium positioning against mass-market competitors. |
| Refill Infrastructure Deployment | São Paulo and Rio de Janeiro urban networks capture eco-friendly advocate willingness to pay for carbon-neutral logistics. |
| Waterless Formulation Development | Anhydrous balm concentrates from Portland and Copenhagen indie brands reduce preservative load and certification pathway complexity. |
| Direct-to-Consumer Platform Launch | Algorithmic personalization through South Korean live-streaming commerce captures Gen Z first-time organic skincare trial rates. |
| Backward Integration into Raw Materials | Equity stakes in Moroccan cooperatives and Indian aloe vera estates secure ECHA-compliant documentation chains for European formulators. |
Study Parameters
The analysis maps moisturizers, cleansers, serums, and exfoliators alongside botanical extracts, essential oils, and packaging formats, each validated through formulator R&D directors, pharmacy procurement managers, clean beauty retail buyers, and contract manufacturing executives. Primary interview intelligence combined with secondary validation from USDA Organic certification databases, ECHA REACH substance registrations, MFDS cosmetic safety filings, and Nielsen retail audit data. Bottom-up unit economics and top-down category sizing triangulate volume and value estimates.
Assumption sets held regulatory enforcement timelines and raw material yield volatility fixed while varying digital channel penetration rates and refill infrastructure adoption curves across the projection horizon. Segmentation dimensions modeled include product type, ingredient sourcing geography, packaging material sustainability tier, and customer purchasing motivation archetype. CAGRs derive from cohort-based adoption curves and price elasticity estimates, with biotechnology-derived active displacement rates and waterless formulation migration serving as industry-specific forecast inputs.
Stress conditions across ECHA microplastic ban acceleration, Indian monsoon yield variance, and Gen Z platform loyalty fragmentation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with revision triggers tied to certification threshold tightening proposals and supply chain documentation requirement expansions. Quarterly review of REACH Annex XVII update schedules, Moroccan cooperative output reports, and South Korean live-streaming commerce penetration metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Hand Care Market
Skincare
Global Anti-Aging Market
Skincare
Global Scar Removal Treatment Market
Skincare
Moisturizing Cream Market
Skincare
Hidradenitis Suppurativa Market
Skincare
Skin Barrier Market
Skincare
Allantoin Extract for Skincare Products Market
Skincare
United Kingdom Skincare Market
Skincare
Acne Treatment Market
Skincare
Global Physician Dispensed Cosmeceuticals Market
Skincare
Retinol Skincare Product Market
Skincare
Biocellulose Mask Market
Skincare
Skincare Cdmo and Cmo Market
Skincare
Marine Retinol Market
Skincare
Self-Tanning Care Market
Skincare
After Sun Care Products Market