
 Homecare Dermatology Energy-Based Devices Market | 2026-2036
Homecare Dermatology Energy-Based Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Homecare Dermatology Energy-Based Devices Market Outlook
Subscription-based filter replacement and app-guided treatment calibration is expanding the recurring revenue attached to each hardware unit. Koninklijke Philips leverages its connected-care infrastructure to sustain loyalty across device generations. Lumenis Be Ltd. anchors its position through clinical-grade technology trickledown into home settings. TRIA Beauty, Inc. specializes in compact diode-laser engineering that competes with salon-based hair removal economics.
Homecare dermatology energy-based devices deploy controlled electromagnetic radiation—typically in wavelengths between 400 nm and 1,064 nm or radiofrequency spectra near 1 MHz—to induce selective photothermolysis or dermal heating without ablation. These systems target melanin, hemoglobin, or collagen structures to achieve cosmetic outcomes previously confined to clinical environments. Laser device types command the largest installed base due to decades of consumer familiarity with hair removal applications, though radiofrequency segments capture premium price points through skin-tightening claims validated by thermal imaging studies. Application-level demand clusters around acne treatment as younger demographics prioritize non-pharmaceutical intervention pathways.
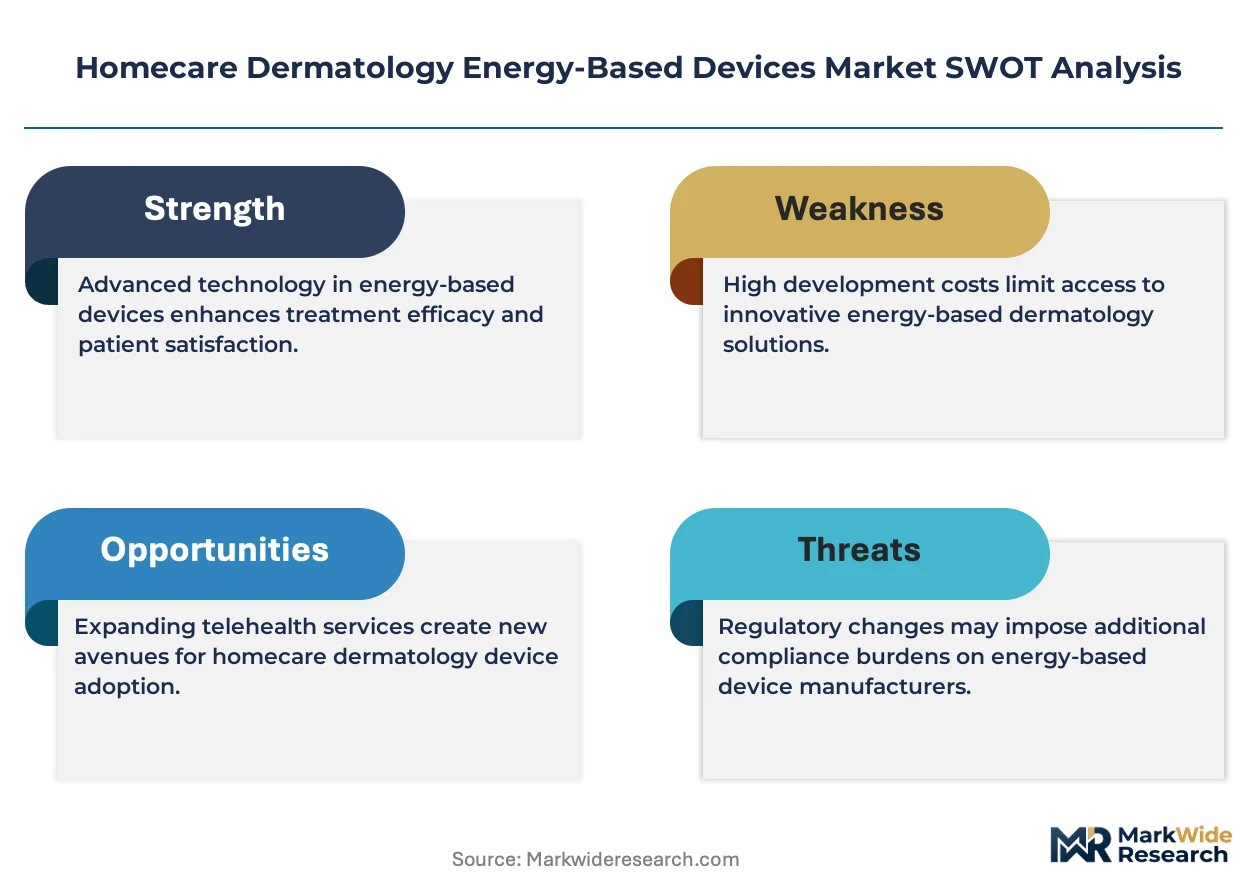
FDA 510(k) clearances govern laser intensity thresholds and eye-safety interlocks for devices sold in the United States, while the EU Medical Device Regulation imposes clinical evidence requirements that slow entry but elevate trust. Japan's PMDA maintains distinct thermal-damage testing protocols that shape product redesign cycles for Asian-market launches. Stakeholders must monitor whether regulator convergence on at-home energy limits narrows the performance gap between consumer and professional tiers.
Market Dynamics
Subscription-based filter replacement and app-guided treatment calibration is expanding recurring revenue attached to each hardware unit, transforming single-purchase economics into sustained consumer relationships across device generations.
Growth Catalysts
- FDA 510(k) Clearance Streamlining:Simplified pathways for laser intensity thresholds and eye-safety interlocks accelerate market entry in the United States, reducing time-to-revenue for diode-laser and radiofrequency device manufacturers.
- Urban Household Dermatology Adjacency:Consumers in metropolitan clusters integrate professional-grade skincare routines into home environments, creating pull-through demand for clinical-grade technology trickledown.
- Selective Photothermolysis Engineering:Advances in wavelength precision between 400 nm and 1,064 nm enable safer melanin and hemoglobin targeting without ablation, expanding treatable skin types.
Market Restraints
- EU MDR Clinical Evidence Requirements:The European Union Medical Device Regulation imposes extensive documentation burdens that slow product launches but elevate post-market surveillance costs.
- Japan PMDA Thermal-Damage Protocol Divergence:Distinct testing standards for Asian-market launches force redundant redesign cycles, fragmenting R&D resource allocation.
- Professional Salon Substitution Economics:Compact diode-laser home devices compete against established hair removal service pricing, compressing willingness-to-pay ceilings.
Strategic Opportunities
- Radiofrequency Skin-Tightening White Space:Thermal imaging validation of dermal heating claims supports premium positioning above laser hair removal saturation.
- Acne Treatment Non-Pharmaceutical Pivot:Younger demographics seek electromagnetic intervention pathways as alternatives to topical and oral medications, opening application expansion.
- Connected-Care Infrastructure Leverage:Bluetooth-enabled treatment calibration and usage tracking create data moats that sustain loyalty across hardware refresh cycles.
Industry Challenges
- Optical Engineering Talent Scarcity:Compact laser cavity design and thermal management expertise concentrates in defense and telecommunications sectors, limiting recruitment pipelines for consumer device scaling.
- Multi-Jurisdiction Certification Parallelism:Simultaneous FDA, PMDA, and CE marking submissions require specialized regulatory affairs capacity that strains mid-tier manufacturers.
- Eye-Safety Interlock Reliability:Fail-safe mechanisms for skin-contact sensors and automatic shutoff systems demand extensive failure-mode testing that extends development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Homecare Dermatology Energy-Based Devices Market |
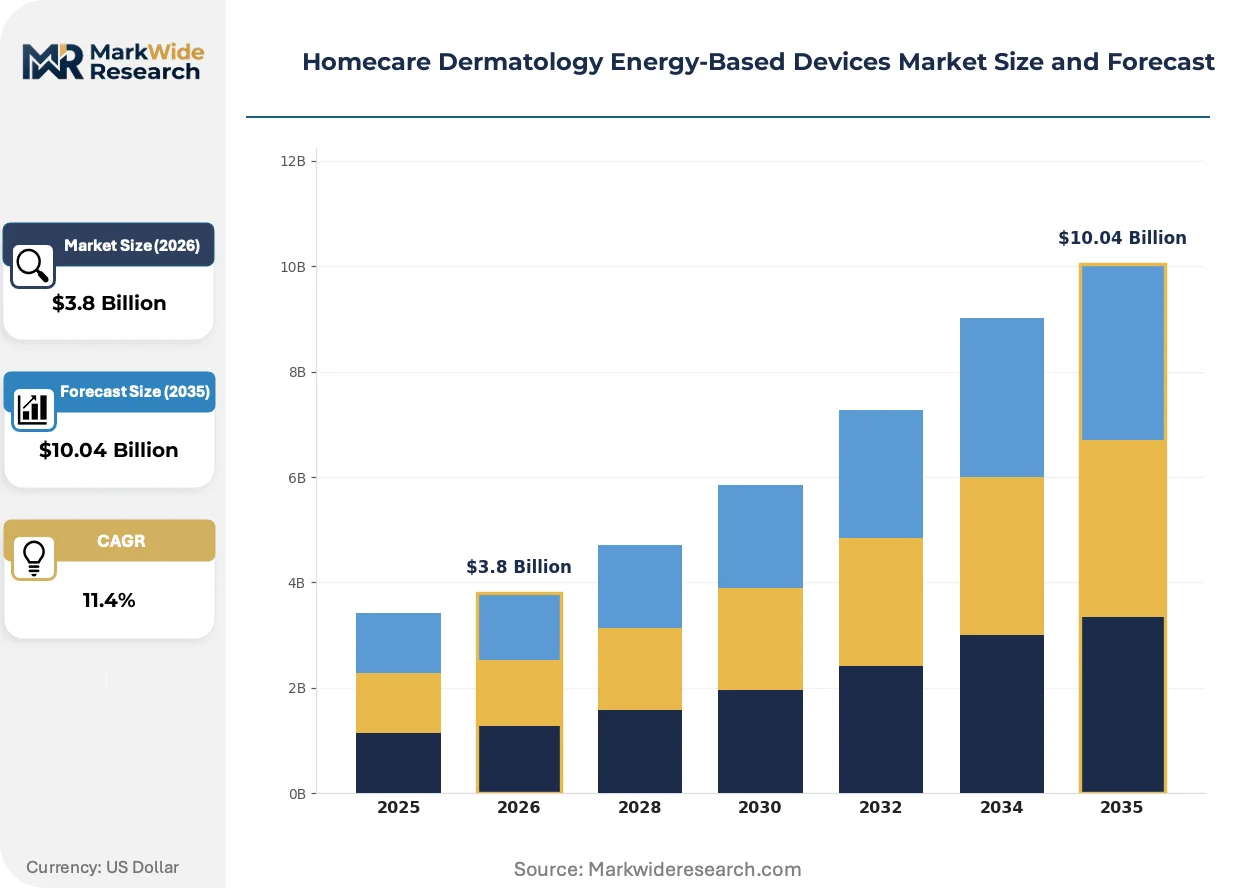
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Laser, Radiofrequency, Ultrasound, Light Therapy Application: Skin Tightening, Acne Treatment, Hair Removal, Cellulite Reduction End User: Consumers, Dermatologists, Aesthetic Clinics, Spas Technology: Fractional, Continuous Wave, Pulsed, Non-ablative |
| Companies Covered | Koninklijke Philips, Lumenis Be Ltd., Cutera, Inc., Cynosure LLC, TRIA Beauty, Inc., Alma Lasers Ltd., Syneron Candela Corporation, Home Skinovations Ltd., FOREO AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Homecare Dermatology Energy-Based Devices Market Strategic Shifts
Controlled electromagnetic radiation systems are absorbing functionality from adjacent wellness categories, blurring boundaries between cosmetic dermatology and preventive health monitoring while reshaping how consumers allocate spending across professional and home-based care.
Multi-wavelength platform engineering is absorbing diagnostic capability from clinical dermatoscopes. Compact devices now integrate melanin-mapping sensors that adjust fluence in real-time based on skin chromophore density. Younger demographics in urban United States households adopt these systems fastest, compressing the performance gap between consumer-tier and professional-grade outcomes.
Regulator convergence on at-home energy limits is absorbing attention from standards bodies. The FDA, Japan's PMDA, and the EU MDR framework are independently tightening thermal damage thresholds, forcing manufacturers to harmonize safety architectures across jurisdictions. Radiofrequency skin-tightening segments face the steepest compliance recalibration, with Asian-market launches requiring distinct hardware variants.
Service unbundling is absorbing traditional retail margins. Direct-to-consumer channels now dominate hardware acquisition, while app-based treatment guidance and consumable subscriptions capture lifetime value previously retained by dermatology clinics. This channel shift concentrates in North American metropolitan markets where telehealth infrastructure supports remote supervision of home-based energy protocols.
Homecare Dermatology Energy-Based Devices Market Segmentation
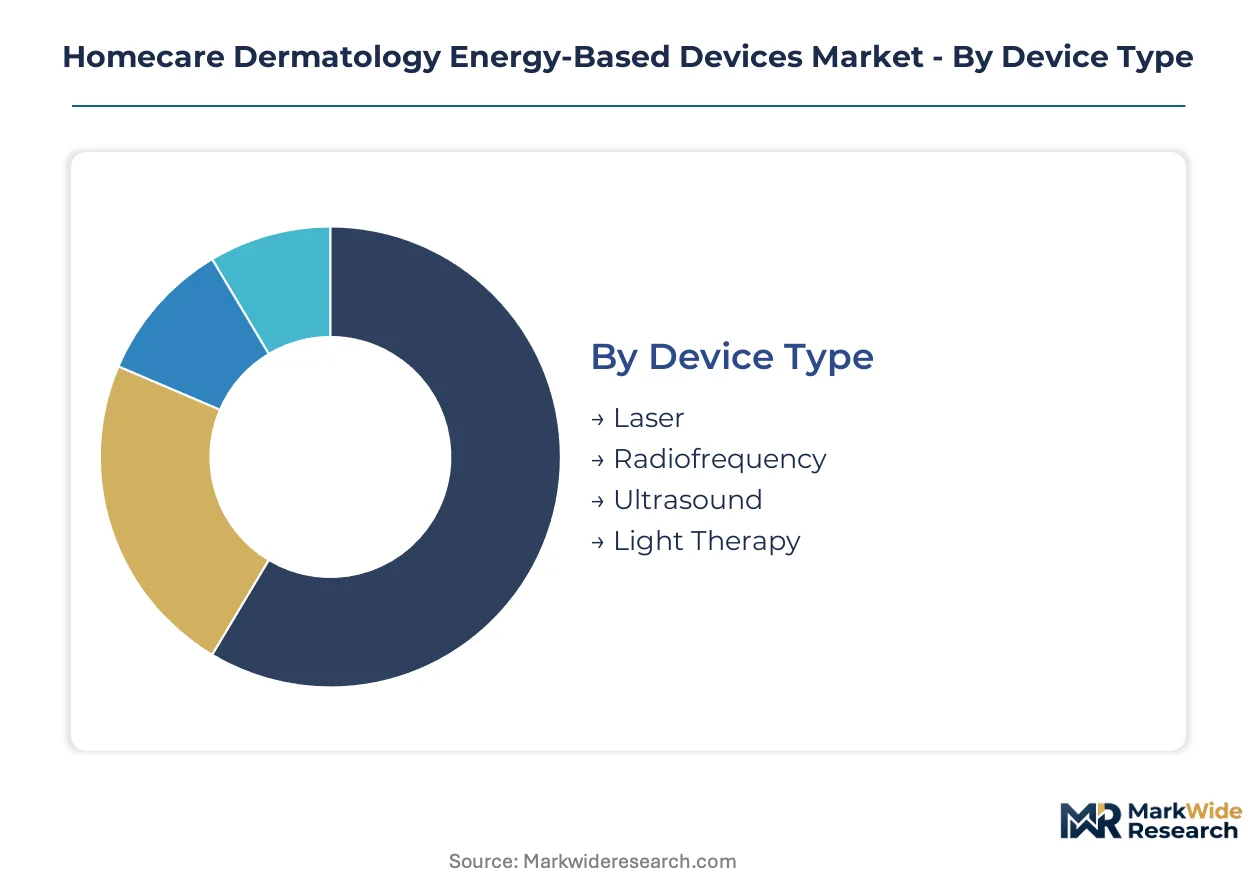
Energy-based homecare dermatology devices fragment across four critical dimensions that shape procurement decisions and margin architecture. Device type and application concentrate revenue concentration, while end-user channel and technology modality determine regulatory pathway complexity and pricing power.
Device Type:
Capital allocation intensity and treatment permanence drive buyer selection across hardware categories.
- Laser:Diode and alexandrite cavity systems deliver selective photothermolysis through wavelengths between 755 nm and 1,064 nm. Demand clusters in United States metropolitan households seeking permanent hair reduction, though eye-safety interlock requirements elevate unit costs and extend FDA 510(k) clearance timelines.
- Radiofrequency:Monopolar and bipolar configurations generate dermal heating at 1 MHz spectra without chromophore dependence, enabling treatment across all Fitzpatrick skin types. Japan's PMDA thermal-damage protocols force hardware redesigns for Asian-market launches, fragmenting R&D resource allocation.
- Ultrasound:Microfocused transducers penetrate subcutaneous tissue layers for non-invasive lifting claims.
- Light Therapy:LED arrays at 415 nm (blue) and 633 nm (red) wavelengths target acne bacteria and inflammation with minimal thermal risk.
Volume sits with Laser; growth tilts toward Radiofrequency.
Application:
Clinical outcome durability and treatment frequency shape recurring revenue potential per installed base.
- Skin Tightening:Collagen remodeling through controlled thermal injury demands precise temperature monitoring and real-time feedback systems. Thermal imaging validation supports premium positioning above commoditized hair removal segments, with United States urban consumers absorbing higher per-session costs for perceived surgical alternatives.
- Acne Treatment:Photodynamic and blue-light protocols attract younger demographics pursuing non-pharmaceutical intervention pathways. European Union MDR clinical evidence requirements slow product launches but elevate post-market surveillance standards that differentiate compliant manufacturers.
- Hair Removal:Melanin-targeting laser systems command the largest installed base from decades of consumer familiarity.
- Cellulite Reduction:Combined acoustic wave and radiofrequency approaches address subcutaneous connective tissue.
Revenue concentrates in Skin Tightening; expansion accelerates most quickly in Acne Treatment.
End User:
Channel control and supervision requirements determine regulatory classification and pricing architecture.
- Consumers:Direct-to-acquisition dominates hardware sales in North American metropolitan markets where telehealth infrastructure supports remote treatment guidance. Bluetooth-enabled calibration and consumable subscriptions capture lifetime value previously retained by clinical channels.
- Dermatologists:Prescription-grade devices with higher fluence limits require professional supervision and carry distinct liability profiles.
- Aesthetic Clinics:Hybrid home-clinic protocols leverage professional-grade hardware for initial treatment series.
- Spas:Non-medical wellness channels absorb entry-tier devices with simplified safety interlocks.
Unit shipments concentrate with Consumers; margin expansion tilts toward Dermatologists.
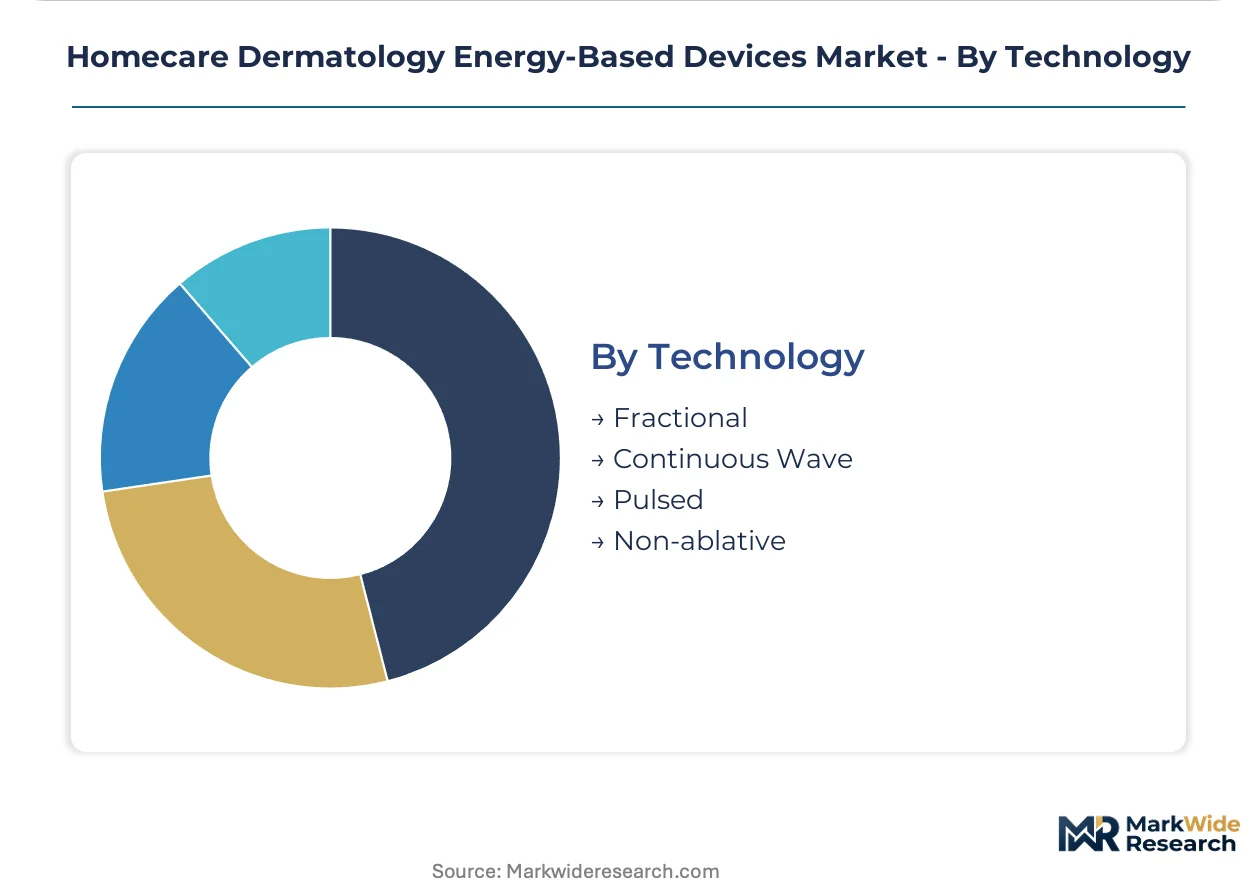
Technology:
Energy delivery modality determines treatment precision, recovery time, and cross-skin-type safety.
- Fractional:Microthermal zone arrays create controlled injury patterns with intact surrounding tissue for accelerated healing. Demand concentrates in premium United States households seeking ablative outcomes without downtime.
- Continuous Wave:Sustained energy delivery enables rapid treatment of large surface areas.
- Pulsed:Nanosecond and millisecond duration control thermal diffusion to protect adjacent structures.
- Non-ablative:Sub-epidermal heating without surface disruption attracts risk-averse first-time users.
Adoption clusters around Fractional; penetration deepens fastest in Non-ablative.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing concentrates in Israel and the United States, while consumption tilts toward affluent households in Japan, Germany, and urban American markets. This geographic split shapes regulatory compliance costs and go-to-market sequencing for energy-based dermatology hardware.
United States
FDA 510(k) clearance pathways streamline entry for diode-laser hair removal devices, reducing time-to-market for manufacturers targeting metropolitan dermatology-adjacent consumers. The FDA maintains strict eye-safety interlock requirements that elevate engineering costs but build consumer trust. Demand clusters in New York, Los Angeles, and Chicago metro areas where telehealth infrastructure supports remote treatment supervision.
Japan
PMDA thermal-damage testing protocols force hardware redesign cycles distinct from Western-market variants, fragmenting R&D budgets for companies seeking Asian expansion. Japan's aging demographic drives skin-tightening device adoption among consumers avoiding invasive procedures. Tokyo and Osaka anchor premium-tier consumption, with department store channels maintaining stronger influence than direct-to-consumer models.
Germany
EU MDR clinical evidence requirements impose documentation burdens that slow product launches but differentiate compliant manufacturers in post-market surveillance. German consumers exhibit strong preference for CE-marked medical-grade devices over cosmetic-class alternatives. Munich and Stuttgart industrial clusters host precision optics suppliers serving both consumer and professional device tiers.
Israel
Defense-sector optical engineering talent migrates into consumer dermatology device development, creating a dense ecosystem of laser cavity specialists. Israeli manufacturers leverage clinical-grade technology trickledown to compete in homecare segments. Tel Aviv and Haifa anchor R&D concentration, with companies frequently pursuing FDA clearance before EU MDR submission to accelerate revenue recognition.
South Korea
MFDS regulations align increasingly with FDA thermal-damage thresholds, enabling harmonized safety architectures for export-oriented manufacturers. K-beauty consumer behavior normalizes at-home device integration into multi-step skincare routines. Seoul Capital Area households absorb premium radiofrequency and LED therapy devices faster than regional peers, driving early adoption curves for multi-wavelength platforms.
Homecare Dermatology Energy-Based Devices Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the homecare dermatology device landscape. The vendor base separates into three tiers: diversified healthcare conglomerates with connected-care infrastructure, clinical-grade laser specialists trickling technology downward, and compact-device engineers focused on single-application economics. Consolidation pressure concentrates in the middle tier as regulatory compliance costs escalate. Dominant competitive moves include strategic partnerships with telehealth platforms and geographic expansion through jurisdiction-specific hardware variants.
Within the diversified healthcare tier, Koninklijke Philips occupies a position exemplifying connected-care ecosystem leverage. Clinical-grade specialists trickling into home settings include Lumenis Be Ltd. and Alma Lasers Ltd., representing archetypes that anchor premium positioning through thermal imaging validation and wavelength precision engineering. TRIA Beauty, Inc. sits within the compact single-application tier, competing on diode-laser miniaturization against salon-based service economics. These three anchors illustrate how regulatory compliance capacity and optical engineering access determine sustainable positioning across consumer price bands.
| Leading Market Players |
|---|
| Koninklijke Philips |
| Lumenis Be Ltd. |
| Cutera, Inc. |
| Cynosure LLC |
| TRIA Beauty, Inc. |
| Alma Lasers Ltd. |
| Syneron Candela Corporation |
| Home Skinovations Ltd. |
| FOREO AB |
| Others |
Value Chain & Pricing Dynamics
Precision optical component costs from Israeli and German suppliers cascade through three-tier pricing structures across premium, standard, and economy levels, with FDA 510(k) certification tiers amplifying spreads between diode-laser hair removal units and radiofrequency skin-tightening systems.
Pricing Analysis
Margin tightening in the standard tier reflects compact diode-laser commoditization as TRIA Beauty and Home Skinovations compete on miniaturization economics. Three-tier pricing structure across premium, standard, and economy levels separates Lumenis thermal-imaging-validated radiofrequency devices from entry-tier LED acne masks. Price differentiation hinges on FDA 510(k) clearance tier and real-time melanin-mapping sensor integration. Younger demographics in urban United States households exhibit highest price sensitivity, while dermatologist-adjacent consumers in Japan absorb premium positioning for PMDA-compliant thermal-damage architectures.
Supply Chain Analysis
Domestic-content mandates in South Korea's MFDS framework are reshaping sourcing for export-oriented manufacturers serving Seoul Capital Area demand. Supply concentrates in Israel, Germany, and the United States for laser cavity engineering and precision optics. Component dependencies include gallium arsenide laser diodes, microelectromechanical thermal sensors, and medical-grade aluminum housings. Single-source vulnerability concentrates in defense-sector optical engineering talent pipelines. Distribution runs through direct-to-consumer channels in North American metropolitan markets and department store networks in Japanese urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EU MDR clinical evidence requirements erect barrier-to-entry moats favoring manufacturers with specialized regulatory affairs capacity and documented post-market surveillance infrastructure.
For Market Incumbents: Lock in optical engineering talent through captive relationships with Israeli defense-sector specialists and Tel Aviv-area R&D clusters. Consolidate position by acquiring mid-tier compact-device engineers before EU MDR documentation burdens force distressed exits. Eye-safety interlock reliability testing capacity represents the critical lever for sustaining FDA 510(k) clearance velocity against emerging radiofrequency entrants.
For New Entrants and Emerging Players: FDA 510(k) clearance streamlining in the United States opens a window for compact radiofrequency skin-tightening devices targeting acne treatment white space. The most penetrable segment sits with younger demographics pursuing non-pharmaceutical intervention pathways in metropolitan households with telehealth infrastructure. Go-to-market angle should emphasize Bluetooth-enabled treatment calibration and consumable subscription economics to capture lifetime value.
For Investors and Strategic Acquirers: Convergence of FDA, PMDA, and EU MDR thermal-damage thresholds is the leading indicator that multi-jurisdiction certification capacity will command acquisition premiums. Long-term viability favors clinical-grade laser specialists with trickledown technology pipelines and connected-care infrastructure assets. Target acquisition archetype: Israeli or German precision optics manufacturers with existing FDA 510(k) clearance track records and dormant consumer-tier product development.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Reduces time-to-revenue for diode-laser devices targeting United States metropolitan dermatology-adjacent households. |
| Connected-Care Infrastructure Development | Bluetooth-enabled calibration creates data moats sustaining loyalty across hardware refresh cycles for Koninklijke Philips ecosystem. |
| Multi-Jurisdiction Certification Parallelism | Simultaneous FDA, PMDA, and CE marking submissions strain mid-tier manufacturers but elevate compliant player valuations. |
| Telehealth Platform Partnership | Remote treatment supervision infrastructure in North American metropolitan markets enables prescription-grade device distribution. |
| Optical Engineering Talent Acquisition | Defense-sector migration into consumer dermatology concentrates in Israeli Tel Aviv and Haifa R&D clusters. |
Study Parameters
Multi-period observation of FDA 510(k) clearance timelines, PMDA thermal-damage protocol revisions, and EU MDR post-market surveillance cost escalations anchored the trend analysis, supplemented by interviews with biomedical engineers, dermatology clinic procurement heads, regulatory affairs specialists at laser device manufacturers, and connected-care platform product managers. Secondary validation drew from FDA 510(k) database filings, EU MDR notified body documentation, Japanese PMDA approval records, and hospital GPO contract databases. Bottom-up unit shipment modeling and top-down market sizing triangulated volume estimates across device type and application segments.
Segment-weighting approaches distributed value across laser, radiofrequency, ultrasound, and light therapy device types, with further stratification by skin tightening, acne treatment, hair removal, and cellulite reduction applications. End-user channel splits between consumers, dermatologists, aesthetic clinics, and spas informed pricing architecture assumptions. CAGRs derived from installed base growth, replacement cycle compression, and recurring revenue attachment rates for filter subscriptions and app-guided calibration services. Technology modality splits across fractional, continuous wave, pulsed, and non-ablative systems captured treatment precision and recovery time differentials.
The model assumes a particular technology adoption path favoring multi-wavelength platform integration; alternative pathways for standalone radiofrequency or simplified LED therapy would alter the outlook for premium positioning and hardware refresh cycles. Forecasts reflect assumptions regarding regulator convergence on at-home energy limits, telehealth infrastructure penetration, and defense-sector optical engineering talent availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Rosacea Treatment Market
Dermatology
Dermatology Drugs Market
Dermatology
Global Ozone Therapy in Dermatology Market
Dermatology
Dermatology Software Market
Dermatology
Skin Cancer Market
Dermatology
China Scar Treatment Market
Dermatology
Saudi Arabia Hair Transplant Market
Dermatology
Dermabrasion Market
Dermatology
Lichen Sclerosus Treatment Market
Dermatology
Global Rosacea Market
Dermatology
Scar Treatment Market
Dermatology
Keloid Treatment Market
Dermatology
Erythema Treatment Market
Dermatology
Global Dermatological Therapeutics Market
Dermatology
Skin Hyperpigmentation Treatment Market
Dermatology
Prescription Dermatology Therapeutics Market