
 Psychedelic Medicine Market | 2026-2036
Psychedelic Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Psychedelic Medicine Market Analytics
A shortage of psychiatrists trained in psychedelic-assisted psychotherapy is reorganizing how clinics staff and scale their service models. Compass Pathways leverages its centralized therapist training academy to standardize protocol delivery across trial sites. Atai Life Sciences anchors its portfolio through diversified compounds spanning multiple indications rather than single-molecule dependence. MindMed competes by occupying early mover positions in LSD-derived therapies for generalized anxiety disorder.
Psychedelic medicine encompasses serotonergic compounds administered in controlled clinical settings to induce altered states of consciousness that facilitate therapeutic breakthroughs in psychiatric conditions. Synthetic psilocybin and MDMA dominate current clinical pipelines, with ketamine already cleared for depression via intravenous infusion under REMS protocols. Application segmentation reveals treatment-resistant depression as the most advanced indication, while PTSD trails closely behind pending confirmatory Phase III readouts. Product type dynamics favor psilocybin for scalability due to shorter duration of action compared to LSD analogs, though DMT derivatives attract interest for rapid onset profiles suited to outpatient settings.
FDA breakthrough therapy designations for psilocybin and MDMA have compressed development timelines and attracted institutional capital previously excluded from Schedule I research. DEA licensing requirements for Schedule I handling create structural barriers that concentrate manufacturing capabilities among entities with established controlled-substance infrastructure. EMA parallel consultations in the Netherlands and Germany signal potential pathway harmonization for European market access. Stakeholders must monitor how FDA advisory committee deliberations on abuse potential influence scheduling recommendations and subsequent payer coverage determinations.
Market Dynamics
FDA breakthrough therapy designations for psilocybin and MDMA are compressing development timelines and attracting institutional capital previously excluded from Schedule I research. This regulatory acceleration is reorganizing competitive positioning around manufacturing infrastructure and therapist training capabilities rather than compound novelty alone.
Growth Catalysts
- DEA Schedule I Licensing:Controlled-substance infrastructure requirements concentrate manufacturing capabilities among established pharmaceutical entities, creating structural moats for early entrants with compliant facilities.
- Treatment-Resistant Depression Protocols:Academic medical centers in the United States are building integrated care models that combine intravenous ketamine with psychotherapy, validating reimbursement pathways for serotonergic interventions.
- Serotonergic Compound Pipelines:Synthetic psilocybin and MDMA dominate clinical development, with shorter duration of action profiles enabling scalable outpatient administration compared to LSD analogs.
Market Restraints
- Schedule I Research Barriers:DEA licensing requirements create structural friction that limits laboratory access and concentrates research capabilities among institutions with established controlled-substance protocols.
- Therapist Supply Constraints:A shortage of psychiatrists trained in psychedelic-assisted psychotherapy restricts clinic scaling and forces reliance on centralized training academies for protocol standardization.
- Reimbursement Uncertainty:Payer coverage determinations remain contingent upon FDA advisory committee deliberations on abuse potential, creating financing gaps between regulatory approval and commercial accessibility.
Strategic Opportunities
- DMT Derivative Outpatient Models:Rapid onset profiles suited to ambulatory settings enable session-based pricing structures distinct from infusion-center dependency, attracting venture investment into short-acting compounds.
- EMA Parallel Pathways:Consultations in the Netherlands and Germany signal potential regulatory harmonization for European market access, reducing duplicative clinical trial requirements across jurisdictions.
- PTSD Indication Expansion:Confirmatory Phase III readouts for MDMA-assisted therapy would extend addressable populations beyond depression into trauma-related conditions with distinct prescriber networks.
Industry Challenges
- Protocol Standardization:Variability in set-and-setting implementation across trial sites threatens data integrity and complicates regulatory submissions requiring consistent therapeutic frameworks.
- Integration Complexity:Electronic health record systems lack coding specificity for psychedelic-assisted sessions, forcing manual claims processing and delaying revenue recognition for specialized clinics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Psychedelic Medicine Market |
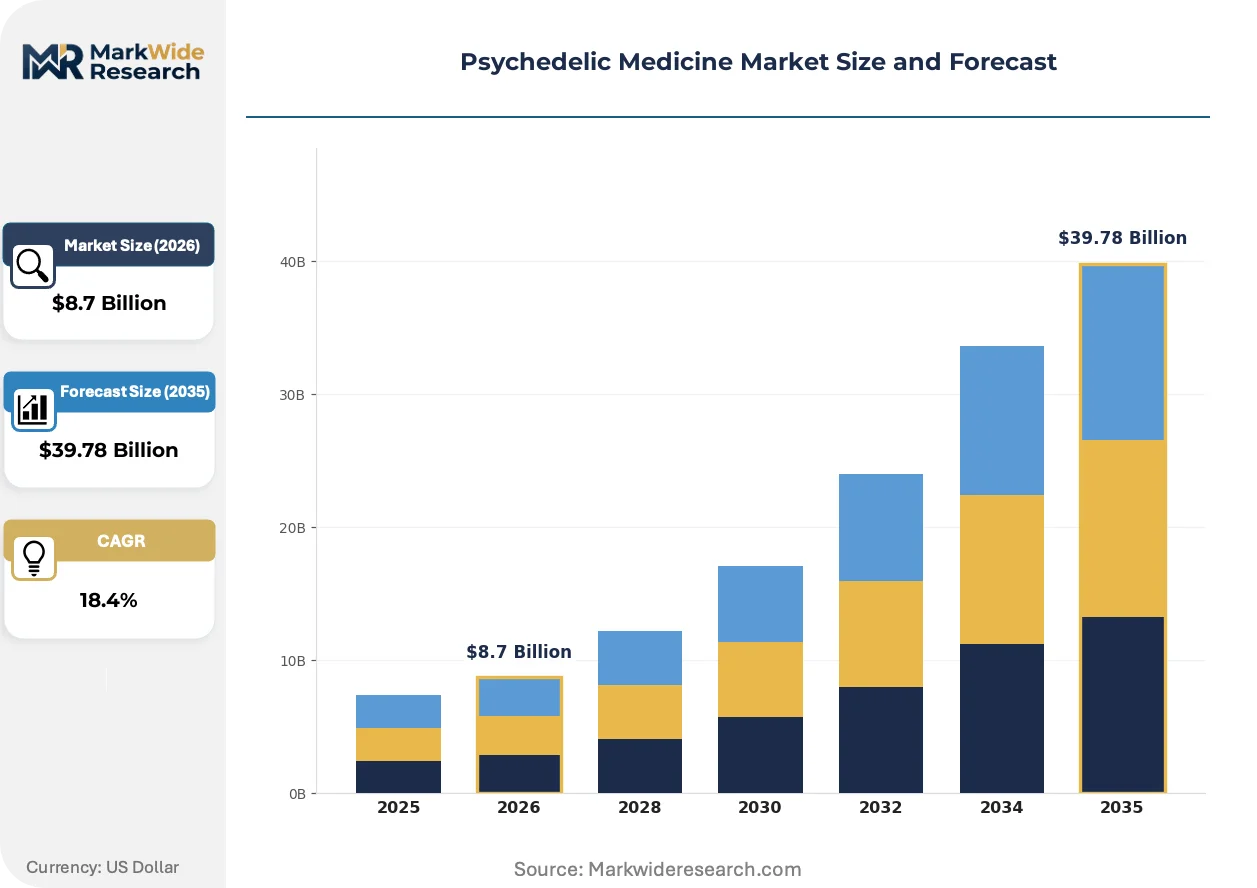
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Psilocybin, MDMA, Ketamine, DMT Application: Depression, PTSD, Anxiety, Substance Use Disorder End User: Clinics, Research Institutions, Hospitals, Health Centers Delivery Mode: Oral, Intravenous, Inhalation, Sublingual |
| Companies Covered | Compass Pathways, Atai Life Sciences, MindMed, Cybin, Beckley Psytech, GH Research, Delix Therapeutics, Johnson & Johnson, Jazz Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Psychedelic Medicine Market Evolving Landscape
Digital phenotyping and biometric monitoring are reshaping how clinicians measure subjective therapeutic outcomes. These technologies promise to objectify response prediction and dosing optimization in protocols historically dependent on qualitative assessment.
Sub-dosing and microdosing measurement technologies is fragmenting precision in compounded formulations. Compounding pharmacies and synthetic biology platforms are adopting liquid chromatography and mass spectrometry workflows to verify batch consistency at sub-milligram scales. Academic research centers are integrating these quality controls into investigator-initiated trials, compressing the gap between artisanal supply and pharmaceutical-grade standards.
EMA's rolling review pilot for novel psychiatric therapies is accelerating market access timelines for sponsors with existing FDA breakthrough designations. The pilot permits iterative data submission rather than complete dossier filing, reducing regulatory lag between US and European approvals. Sponsors with psilocybin programs are prioritizing Netherlands and Germany for initial European filings, anticipating accelerated national reimbursement negotiations.
Patient self-advocacy networks are displacing traditional physician referral pathways as the primary demand activation channel. Treatment-resistant depression patients are organizing through digital platforms to identify participating trial sites and post-approval clinics, compressing geographic information asymmetries. This behavioral shift concentrates initial commercial demand in metropolitan areas with established ketamine clinic infrastructure, particularly in California, New York, and Texas.
Psychedelic Medicine Market Segmentation
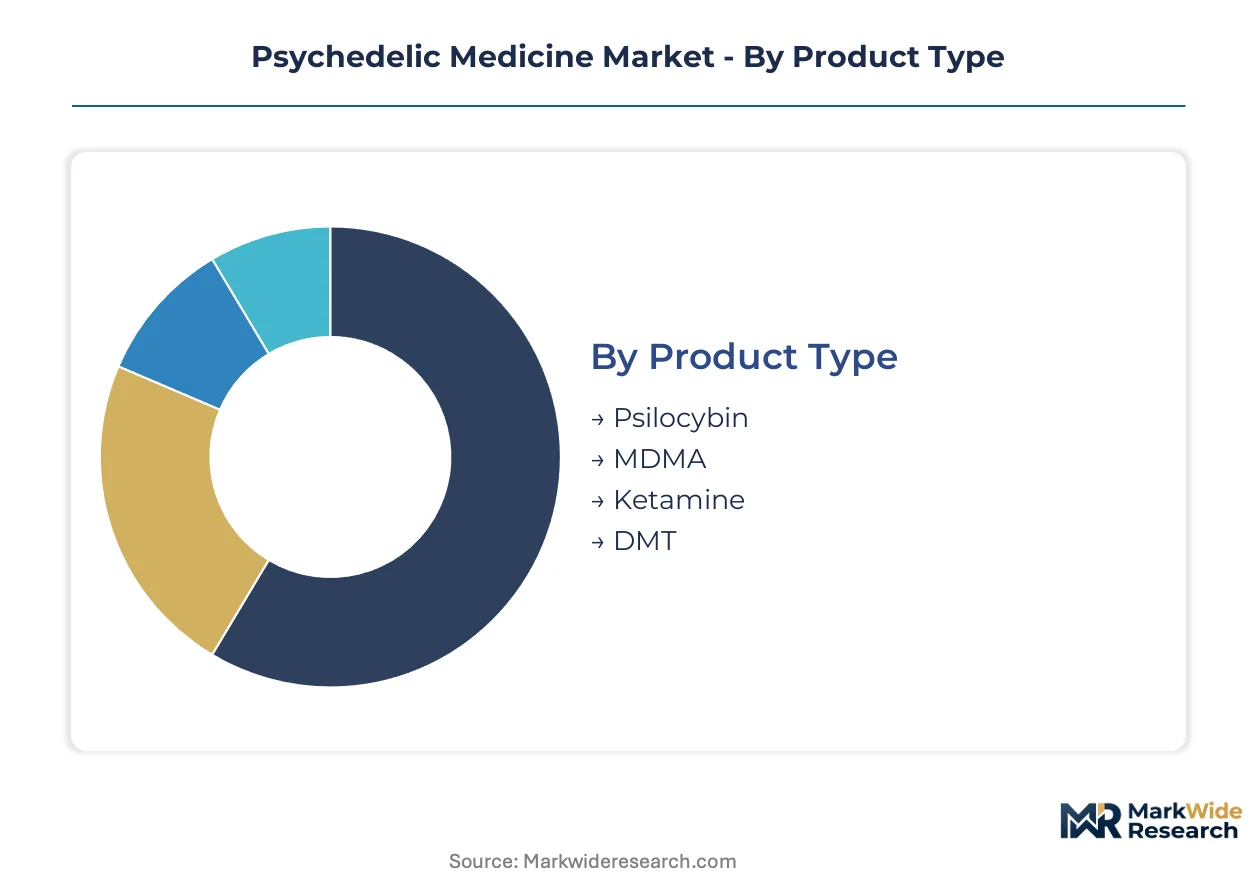
Psychedelic medicine market segmentation reveals how compound pharmacology, clinical infrastructure, and reimbursement pathways intersect to determine commercial viability. Each dimension shapes capital allocation decisions across manufacturing, site certification, and prescriber training investments.
Product Type:
Channel-mix dynamics concentrate high-touch compounds in academic medical centers while scalable molecules penetrate outpatient networks.
- Psilocybin:Synthetic tryptamine engineered for four-to-six-hour duration enables single-session protocols. Demand concentrates in Compass Pathways' trial network across the United States and United Kingdom, where FDA breakthrough designation accelerates site activation. Therapist training standardization remains the binding constraint on expansion velocity.
- MDMA:Empathogen with established PTSD efficacy signals requires specialized cardiovascular monitoring infrastructure. MAPS Public Benefit Corporation anchors manufacturing through contracted GMP facilities in the United States, with European distribution pending EMA rolling review outcomes. Abuse potential scheduling debates threaten outpatient channel access.
- Ketamine:NMDA antagonist already cleared via REMS protocols drives immediate revenue recognition for intravenous infusion centers.
- DMT:Rapid onset profile suits compressed session formats, attracting venture investment into inhalation delivery technologies.
Psilocybin dominates installed base. DMT is where expansion concentrates.
Application:
Cost tier stratification separates premium reimbursed indications from self-pay experimental protocols.
- Depression:Treatment-resistant depression commands the deepest reimbursement infrastructure, with ketamine clinics in the United States validating prior authorization pathways. Academic medical centers at Johns Hopkins and NYU Langone anchor psilocybin Phase III enrollment, compressing time-to-label for serotonergic alternatives.
- PTSD:Military and veteran health systems in the United States drive concentrated demand activation, with VA cooperative studies providing regulatory credibility. MDMA-assisted therapy targets this indication exclusively in initial filings, leveraging existing prescriber relationships within federal health networks.
- Anxiety:Generalized anxiety disorder programs occupy earlier clinical stages, with MindMed's LSD-derived compounds targeting this expansion indication.
- Substance Use Disorder:Opioid and alcohol dependence applications remain investigator-initiated, lacking pivotal trial funding.
Depression dominates installed base. PTSD is where expansion concentrates.
End User:
Customer type fragmentation separates institutional purchasers with capital budgets from reimbursement-dependent operators.
- Clinics:Specialized ketamine infusion centers in California, New York, and Texas aggregate self-pay demand through direct-to-consumer marketing. These operators prioritize compounds with existing REMS clearance, deferring psilocybin investment until scheduling resolution.
- Research Institutions:Academic medical centers command DEA Schedule I licenses and IRB infrastructure that contract research organizations cannot replicate. Johns Hopkins, Imperial College London, and University of Zurich anchor investigator-initiated trials with non-dilutive funding.
- Hospitals:Integrated health systems in the United States pilot psychedelic-assisted psychotherapy within psychiatric departments, leveraging existing EHR and billing infrastructure.
- Health Centers:Federally qualified health centers represent prospective access expansion targets for Medicaid-eligible populations.
Clinics dominate installed base. Hospitals are where expansion concentrates.
Delivery Mode:
Maturity gradients separate established intravenous infrastructure from developmental oral and inhalation formats.
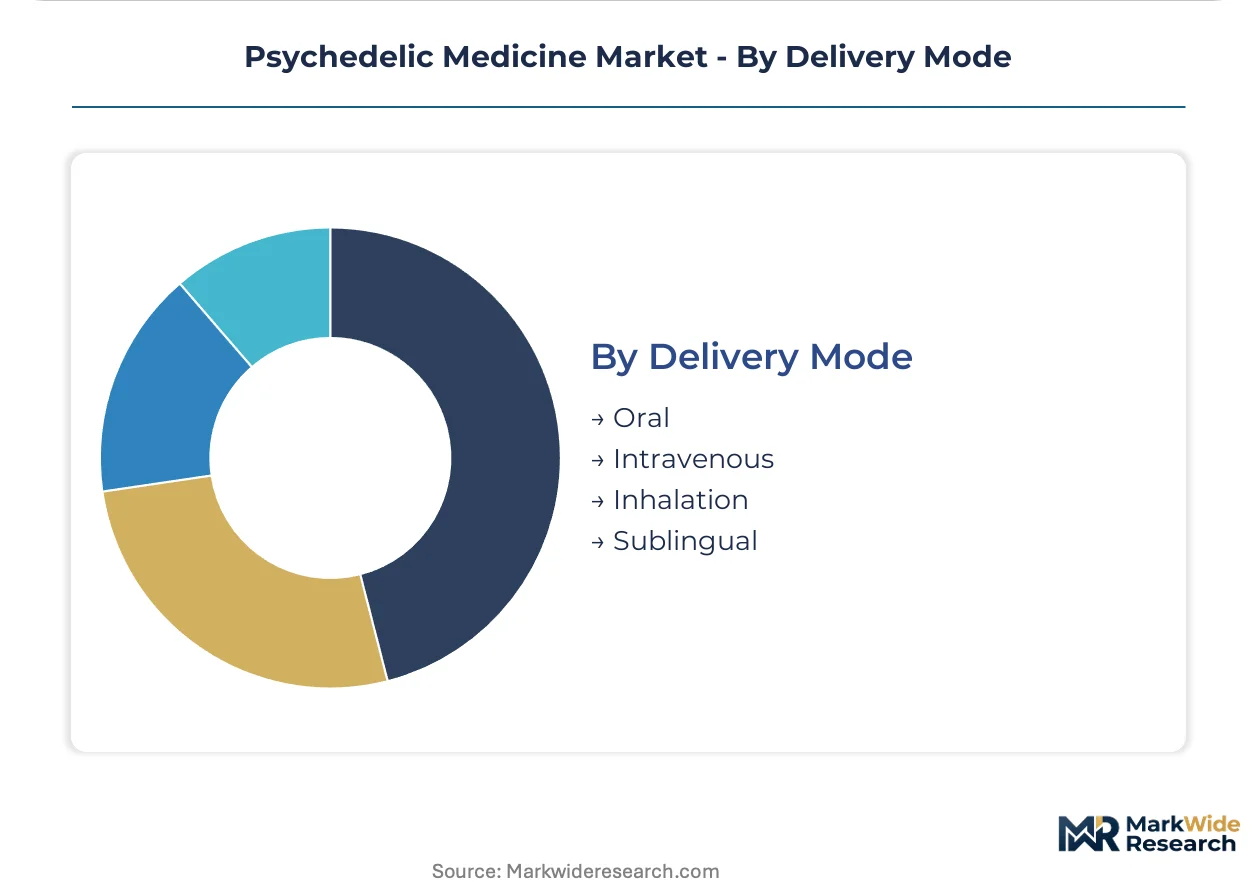
- Intravenous:Ketamine infusion protocols leverage existing anesthesia and pain management infrastructure, with REMS-mandated monitoring requirements limiting site expansion to hospital-affiliated settings. United States reimbursement codes for intravenous administration provide immediate revenue visibility.
- Oral:Synthetic psilocybin capsules enable decentralized administration, though FDA guidance on set-and-setting standardization remains pending. Compass Pathways' centralized therapist training academy addresses protocol fidelity concerns across distributed sites.
- Inhalation:DMT vaporization technologies target session compression, with device development partnerships in the Netherlands and Germany advancing regulatory pre-submissions.
- Sublingual:LSD analog films and troches occupy preclinical optimization, with bioavailability concerns delaying clinical entry.
Intravenous dominates installed base. Oral is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough designations for psilocybin and MDMA have concentrated clinical development infrastructure in the United States, while EMA rolling review pilots and national psychedelic research programs in the Netherlands and Germany are accelerating European site activation.
United States
Specialized ketamine clinics in California, New York, and Texas validate reimbursement pathways for serotonergic interventions. FDA REMS protocols for intravenous ketamine infusion mandate cardiovascular monitoring requirements that limit site expansion to hospital-affiliated settings. Johns Hopkins and NYU Langone anchor psilocybin Phase III enrollment in Baltimore and Manhattan, compressing time-to-label for synthetic tryptamine alternatives.
United Kingdom
Imperial College London commands DEA-equivalent Schedule I licensing through the Home Office and anchors investigator-initiated trials with non-dilutive funding. The Medicines and Healthcare products Regulatory Agency (MHRA) has established an innovation office to streamline psychedelic therapy submissions. London's South Kensington cluster concentrates Compass Pathways' European trial coordination and therapist training academy operations.
Netherlands
Truffle-derived psilocybin retreats in Amsterdam and Utrecht operate in regulatory gray zones that attract medical tourism demand ahead of formal pharmaceutical approval. The Dutch Health and Youth Care Inspectorate (IGJ) participates in EMA parallel consultations for synthetic psilocybin dossiers. Eindhoven-based device development partnerships advance DMT vaporization technologies for compressed session formats.
Germany
Federal Ministry of Health funding for psychedelic psychotherapy research supports academic medical centers in Berlin and Heidelberg. The Federal Institute for Drugs and Medical Devices (BfArM) coordinates with EMA on rolling review submissions from sponsors with existing FDA breakthrough designations. Bavaria's Munich cluster hosts GMP manufacturing facilities for MDMA clinical supply.
Australia
The Therapeutic Goods Administration (TGA) authorized psychiatrist-prescribed psilocybin for treatment-resistant depression in 2023, creating the first regulated commercial pathway outside clinical trials. Demand concentrates in Melbourne and Sydney where specialized clinics integrate psychotherapy with compound administration. University of Queensland researchers anchor investigator-initiated trials for DMT derivatives in Brisbane.
Psychedelic Medicine Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that fragments across compound classes and therapeutic modalities. The upper tier commands DEA Schedule I manufacturing infrastructure and centralized therapist training capabilities that create structural moats against replication. Three archetypes dominate: synthetic biology platforms engineering novel tryptamines, clinical-stage developers with FDA breakthrough designations, and diversified pharmaceutical incumbents with existing psychiatric portfolios. Competitive moves concentrate on strategic partnerships for GMP manufacturing scale and geographic licensing arrangements for protocol delivery.
Within the clinical-stage developer tier, Compass Pathways and MindMed occupy distinct therapeutic positioning archetypes, while Atai Life Sciences exemplifies portfolio diversification across multiple compounds and indications. Johnson & Johnson and Jazz Pharmaceuticals represent pharmaceutical incumbents leveraging existing CNS infrastructure and prescriber relationships to anchor ketamine-derived revenue streams ahead of serotonergic compound approvals.
| Leading Market Players |
|---|
| Compass Pathways |
| Atai Life Sciences |
| MindMed |
| Cybin |
| Beckley Psytech |
| GH Research |
| Delix Therapeutics |
| Johnson & Johnson |
| Jazz Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Synthetic psilocybin substitution for naturally-derived compounds redraws manufacturing geography toward GMP-certified facilities in the United States and Germany while compressing per-dose economics through batch standardization. This input transition simultaneously elevates quality premiums for pharmaceutical-grade supply and erodes artisanal extraction margins in unregulated retreat markets.
Pricing Analysis
Price spreads between United States academic medical centers and European trial sites reflect DEA licensing scarcity and REMS-mandated monitoring infrastructure. Three-tier pricing structure across GMP-certified, research-grade, and compounded formulations separates institutional purchasers from self-pay clinic operators. Cost compression in compounded ketamine vials intensifies as generic IV supply saturates infusion center networks. Hospital-affiliated settings exhibit lowest price sensitivity; independent clinics in California and Texas face margin pressure from patient acquisition costs.
Supply Chain Analysis
Inventory lead times for Schedule I compounds extend nine to eighteen months due to DEA quota allocation cycles and batch-release testing protocols. Manufacturing concentrates in the United States, Germany, and the United Kingdom where controlled-substance infrastructure meets EMA and FDA inspection standards. Active pharmaceutical ingredient supply draws from specialized synthetic biology platforms and contract GMP facilities in Bavaria and North Carolina. Single-source vulnerability concentrates in MDMA precursor chemicals subject to international narcotics control. Distribution runs through hospital-affiliated specialty pharmacies and direct-to-site clinical trial depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The psychedelic medicine market is emerging from a capital-intensive trough as FDA breakthrough designations trigger reimbursement infrastructure buildout and institutional capital re-entry. This cyclical recovery rests on regulatory validation compressing the gap between experimental protocols and commercial pharmaceutical standards.
For Market Incumbents: Compound manufacturing capabilities through backward integration into synthetic biology platforms, securing captive supply of tryptamine precursors against DEA quota constraints. Anchor therapist training academies as proprietary infrastructure to defend against service commoditization by generic entrants. Prioritize EMA rolling review submissions to capture European pricing premiums before competitor site activation. For New Entrants and Emerging Players: Differentiate on rapid-onset DMT derivatives for outpatient session compression, bypassing infusion-center infrastructure requirements that ketamine incumbents control. Target Australia and the Netherlands where TGA authorization and regulatory gray zones enable revenue recognition ahead of FDA scheduling resolution. Pursue device-development partnerships for inhalation delivery technologies to establish platform control. For Investors and Strategic Acquirers: Capital is best deployed toward clinical-stage developers with FDA breakthrough designations and centralized therapist training infrastructure rather than single-molecule bets. Long-term viability hinges on reimbursement pathway clarity across Medicaid and commercial payers. Watch FDA advisory committee deliberations on abuse potential scheduling as the critical inflection signal for valuation step-changes.| Strategic Initiative | Industry Significance |
|---|---|
| Centralized Therapist Training Academy | Compass Pathways' London-based academy standardizes protocol fidelity across distributed Phase III sites. |
| EMA Rolling Review Submission | Parallel consultations in the Netherlands and Germany compress regulatory lag between FDA and European approvals. |
| GMP Manufacturing Scale-Up | Bavaria-based facilities anchor MDMA clinical supply for MAPS Public Benefit Corporation's PTSD program. |
| Digital Phenotyping Integration | Biometric monitoring platforms objectify response prediction for dosing optimization in investigator-initiated trials. |
| Reimbursement Strategy Development | Prior authorization pathway validation at Johns Hopkins and NYU Langone anchors commercial payer negotiations. |
Research Methodology
The analysis maps synthetic psilocybin, MDMA, ketamine, and DMT derivative pipelines, each validated through clinical trial investigators, regulatory affairs specialists at FDA and EMA, formulary directors at major payers, and ketamine clinic operators. Primary interviews with drug development executives and hospital procurement managers combined with secondary validation through FDA breakthrough therapy designations, EMA rolling review pilot documentation, ClinicalTrials.gov enrollment data, and TGA authorization records. Bottom-up site activation counts and top-down capital deployment tracking triangulate market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models compound type, application indication, end-user category, and delivery mode segmentation dimensions. CAGRs derive from site expansion velocity, therapist training throughput constraints, and scheduling resolution scenarios. Forecast inputs incorporate DEA licensing approval timelines, REMS protocol expansion rates, and EMA parallel pathway adoption patterns.
Material uncertainties — FDA advisory committee scheduling recommendations, DEA rescheduling timelines, and commercial payer coverage determinations — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway acceleration and reimbursement infrastructure buildout. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Neuroendocrine Carcinoma Treatment Market
Specialty Medicine
Combined Immune Deficiency (CID) Market
Specialty Medicine
Acrocallosal Syndrome Therapeutics Market
Specialty Medicine
Intramedullary Osteosarcoma Treatment Market
Specialty Medicine
Asia-Pacific Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Vascular Dementia Treatment Market
Specialty Medicine
Global Breast Cancer Therapeutics Market
Specialty Medicine
Aarskog Syndrome Treatment Market
Specialty Medicine
Hermansky Pudlak Syndrome Therapeutics Market
Specialty Medicine
Head and Neck Cancer Therapeutics Market
Specialty Medicine
Global Anal Fistula Treatment Market
Specialty Medicine
Perennial Allergic Rhinitis Market
Specialty Medicine
Global Addison's Disease Treatment Market
Specialty Medicine
Meningitis Treatment Market
Specialty Medicine
Hypertrophic Cardiomyopathy (HCM) Therapeutics Market
Specialty Medicine
Scleritis Market