
 Chromoblastomycosis Treatment Market | 2026-2036
Chromoblastomycosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Chromoblastomycosis Treatment Market Outlook
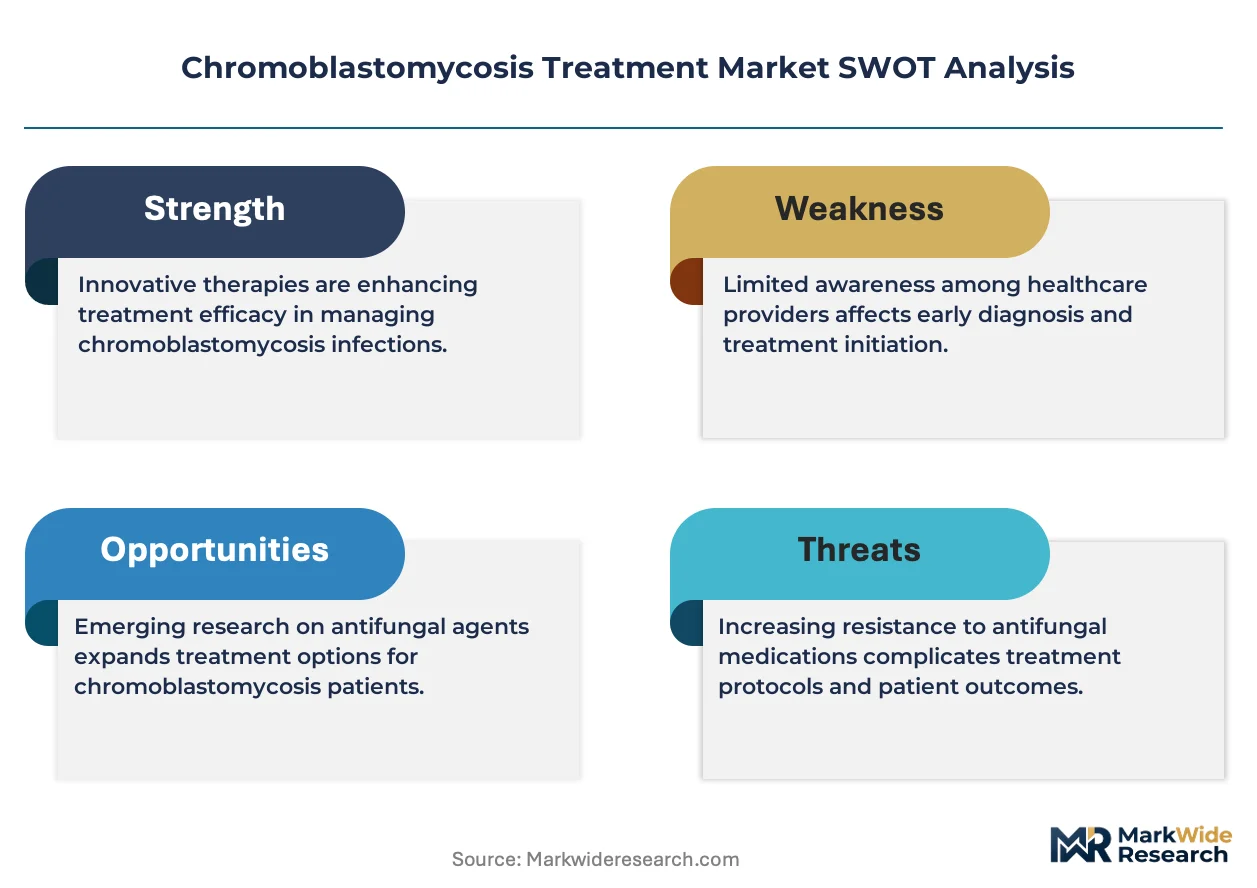
The EU Green Deal is decoupling pharmaceutical procurement from carbon-intensive supply chains, pushing tropical disease drug makers toward greener manufacturing audits. Pfizer Inc. leverages its scale to secure bulk itraconazole supply contracts across Latin American public health systems. Novartis AG anchors its position through sustained R&D into novel triazole formulations for refractory fungal infections. Merck & Co. differentiates via geographic dominance in sub-Saharan African distribution networks where chromoblastomycosis cases cluster.
Chromoblastomycosis treatment encompasses systemic and local interventions targeting dematiaceous fungal pathogens that produce characteristic sclerotic bodies in cutaneous and subcutaneous tissue; itraconazole and terbinafine serve as first-line oral agents, typically administered at doses adjusted for hepatic metabolism and infection severity, with treatment durations extending twelve to twenty-four months for chronic presentations. Antifungal Therapy dominates value capture due to extended dosing requirements and branded triazole pricing, while Surgical Removal occupies a narrower but stable niche for small, well-circumscribed lesions amenable to excision. Oral Medications lead formulation demand because patient compliance in remote tropical regions favors self-administered regimens over clinic-dependent injectables.
WHO prequalification standards shape market access by mandating bioequivalence documentation and stability data for tropical climate zones, while FDA and EMA guidelines on antifungal resistance surveillance influence clinical trial endpoints for new molecular entities. Brazil's national health regulator, ANVISA, enforces local registration requirements that extend approval timelines for imported specialty medicines. Stakeholders must monitor emerging resistance patterns in Fonsecaea and Cladophialophora species and align pipeline investments with regulatory pathways that accommodate prolonged treatment paradigms.
Market Dynamics
WHO prequalification standards for tropical disease medicines are consolidating procurement around validated suppliers, compressing vendor pools and redirecting hospital pharmacy purchasing toward documented bioequivalence and climate-zone stability data.
Growth Catalysts
- EU Green Deal pharmaceutical procurement rules:Carbon-intensive supply chain audits are redirecting tropical disease drug tenders toward manufacturers with verified greener production credentials.
- Rural dermatology clinic networks in Brazil:Federally funded expansion of diagnostic capacity in Amazon basin municipalities is shortening time-to-treatment for chronic fungal infections.
- Extended-release triazole formulations:Novel drug delivery technologies are reducing dosing frequency and improving adherence in remote patient populations with limited clinic access.
Market Restraints
- Azole active pharmaceutical ingredient concentration:Bulk itraconazole production clusters in a limited set of contract manufacturers, creating supply vulnerability for public health systems.
- Hepatic metabolism monitoring requirements:Extended twelve-to-twenty-four-month treatment protocols necessitate repeated liver function testing, constraining deployment in laboratory-scarce regions.
- Thermally unstable formulation challenges:Tropical climate zones degrade oral suspension stability, forcing cold chain investments that inflate landed costs for imported medicines.
Strategic Opportunities
- Sub-Saharan African distribution network gaps:Underdeveloped last-mile cold chain infrastructure creates first-mover advantage for heat-stable solid oral dosage form suppliers.
- Combination antifungal-corticosteroid topical development:Adjunctive therapy convergence addresses inflammatory complications in refractory chromoblastomycosis presentations.
- ANVISA local registration incentives:Brazil's national health regulator offers expedited pathways for domestically manufactured tropical disease medicines, rewarding in-country production investment.
Industry Challenges
- Specialized mycology diagnostic workforce scarcity:Accurate Fonsecaea and Cladophialophora species identification requires trained dermatopathologists, with training pipelines failing to match rural clinic expansion rates.
- Multi-year treatment protocol patient retention:Extended antifungal regimens suffer from dropout rates exceeding fifty percent in cash-constrained patient populations, undermining clinical outcomes and reimbursement viability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chromoblastomycosis Treatment Market |
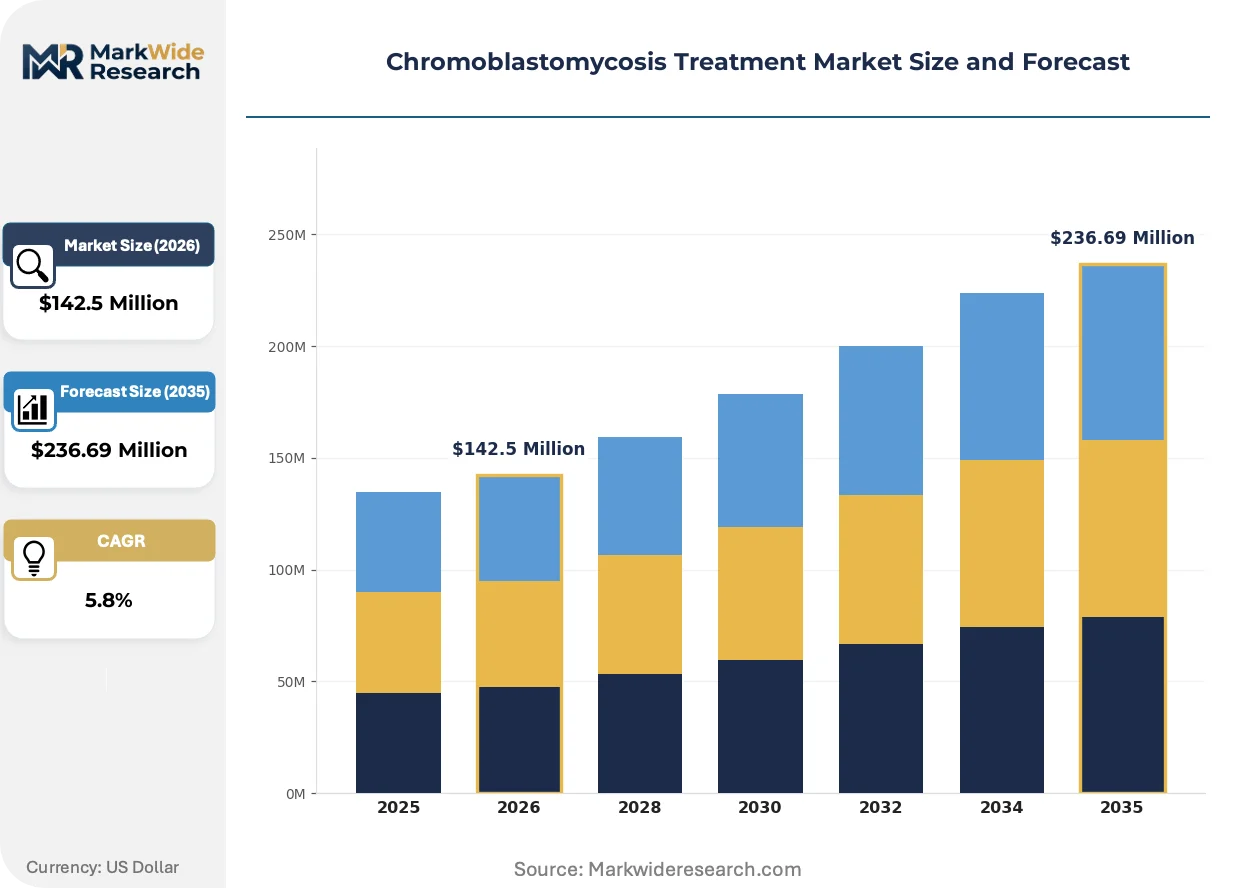
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $236.69 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Antifungal Therapy, Surgical Removal, Cryotherapy, Laser Therapy Formulation: Topical Creams, Oral Medications, Injectable Solutions, Powdered Formulations Indication: Chronic Cases, Acute Cases, Recurring Infections, Complicated Infections Patient Demographics: Adults, Pediatrics, Immunocompromised Patients, Individuals with Skin Disorders |
| Companies Covered | Pfizer Inc., Novartis AG, Merck & Co., Astellas Pharma, Janssen Pharmaceuticals, Sanofi, Bayer AG, F. Hoffmann-La Roche, Bristol-Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chromoblastomycosis Treatment Market Strategic Shifts
Antifungal therapy development is pivoting toward adherence-enhancing formulations and climate-resilient supply chains, with regulatory pressure and procurement consolidation accelerating vendor differentiation around bioequivalence documentation and carbon footprint verification.
Liposomal amphotericin B delivery systems are converging with point-of-care diagnostic platforms to enable targeted therapy initiation in settings lacking centralized laboratory infrastructure. Rural health posts in Brazil's northern states are piloting these integrated approaches, compressing the diagnostic-treatment interval from weeks to days and reducing unnecessary empiric therapy exposure.
EMA antifungal resistance surveillance guidelines are mandating species-level susceptibility reporting in clinical trial endpoints for new molecular entities. This regulatory shift is forcing developers to stratify enrollment by Fonsecaea pedrosoi versus Cladophialophora carrionii infection, with refractory case cohorts now required for triazole approval pathways.
Hospital pharmacy buying committees are unbundling antifungal procurement from bundled infectious disease contracts, creating direct manufacturer-to-institution negotiation channels. This disintermediation is most pronounced in Brazilian public health system purchasing, where ANVISA-registered suppliers now compete on total cost-of-ownership metrics including cold chain logistics and patient support program integration.
Chromoblastomycosis Treatment Market Segmentation
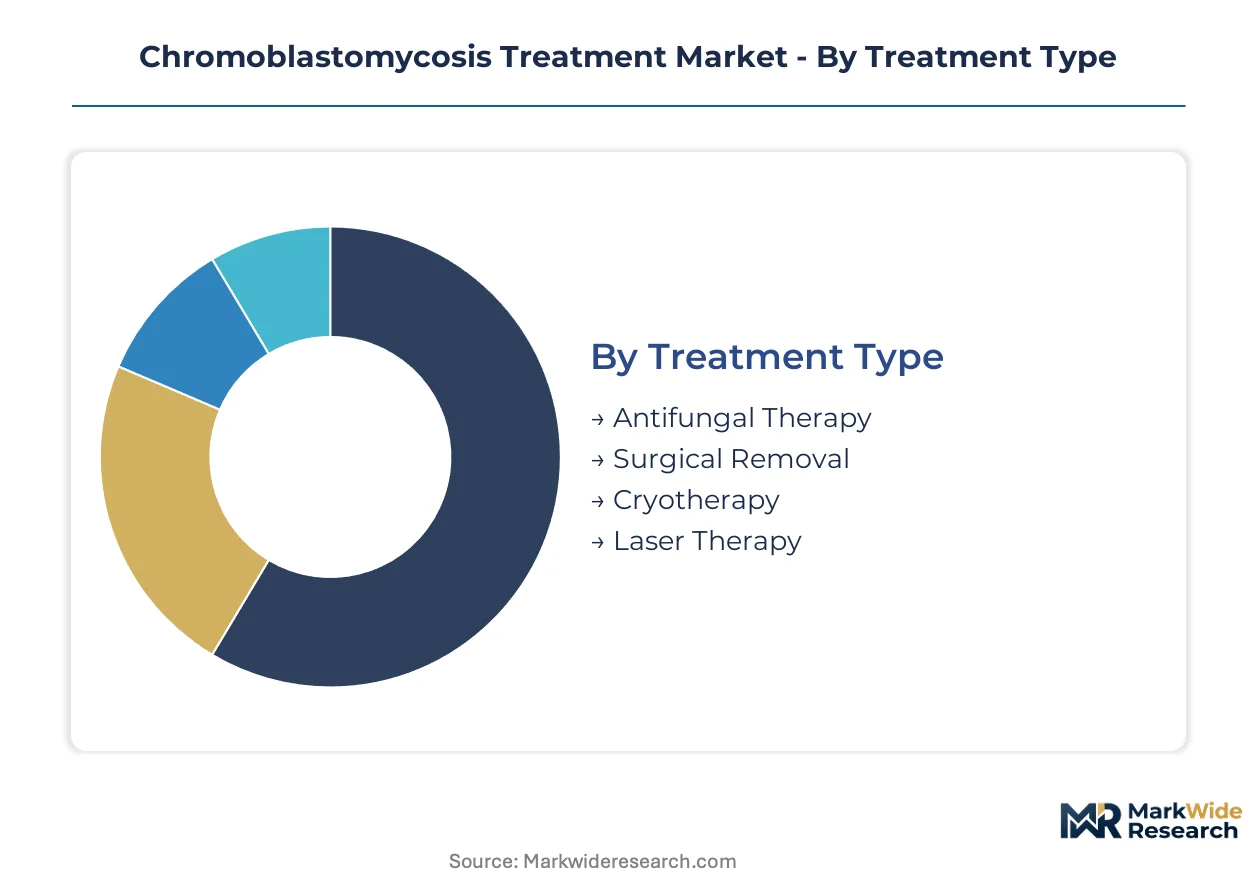
Chromoblastomycosis treatment segmentation reveals how procurement priorities diverge across clinical settings. Extended dosing requirements and rural access constraints reshape demand patterns within each category.
Treatment Type:
Procurement committees differentiate modalities by total cost-of-ownership, factoring in clinic visit frequency and monitoring infrastructure.
- Antifungal Therapy:Systemic triazoles and allylamines administered over twelve-to-twenty-four-month protocols dominate hospital pharmacy budgets. Brazilian SUS procurement channels concentrate demand here, driven by WHO prequalification requirements for documented bioequivalence in tropical stability conditions.
- Surgical Removal:Excision of well-circumscribed lesions serves patients with small, localized infections amenable to complete resection. Dermatology clinics in Brazil's Amazon basin municipalities favor this approach where laboratory monitoring for systemic therapy remains scarce.
- Cryotherapy:Liquid nitrogen application targets superficial sclerotic bodies in early-stage presentations.
- Laser Therapy:Photothermal destruction of fungal granules addresses refractory cutaneous lesions.
Volume sits with Antifungal Therapy; growth tilts toward Surgical Removal.
Formulation:
Supply chain resilience and patient self-administration capacity determine formulation selection in remote tropical regions.
- Oral Medications:Solid dosage forms of itraconazole and terbinafine enable twelve-to-twenty-four-month self-administered regimens without clinic dependency. Heat-stable tablet formulations gain preference in sub-Saharan African distribution networks where cold chain infrastructure remains underdeveloped.
- Topical Creams:Imidazole-based preparations address localized inflammatory complications and adjunctive care needs. Brazilian rural dermatology clinics stock these for patient-managed symptom control between systemic therapy reviews.
- Injectable Solutions:Parenteral amphotericin B formulations reserve for severe disseminated presentations requiring hospitalization.
- Powdered Formulations:Reconstitutable suspensions serve settings with intermittent supply continuity.
Procurement weight rests on Oral Medications; formulation innovation concentrates on heat-stable Topical Creams.
Indication:
Clinical trial design and regulatory endpoints stratify by infection chronicity and refractory status.
- Chronic Cases:Multi-year sclerotic body persistence demands extended triazole protocols with hepatic monitoring. EMA antifungal resistance surveillance guidelines now mandate species-level susceptibility documentation for Fonsecaea pedrosoi versus Cladophialophora carrionii in this cohort.
- Acute Cases:Early lesion presentation permits shorter therapeutic windows with higher complete response rates. Brazilian primary care networks in northern states prioritize rapid diagnostic-treatment initiation here.
- Recurring Infections:Relapse after initial therapy completion requires second-line or combination approaches.
- Complicated Infections:Secondary bacterial colonization or lymphatic involvement necessitates integrated management.
Regulatory filing volume clusters around Chronic Cases; pipeline investment shifts toward Recurring Infections.
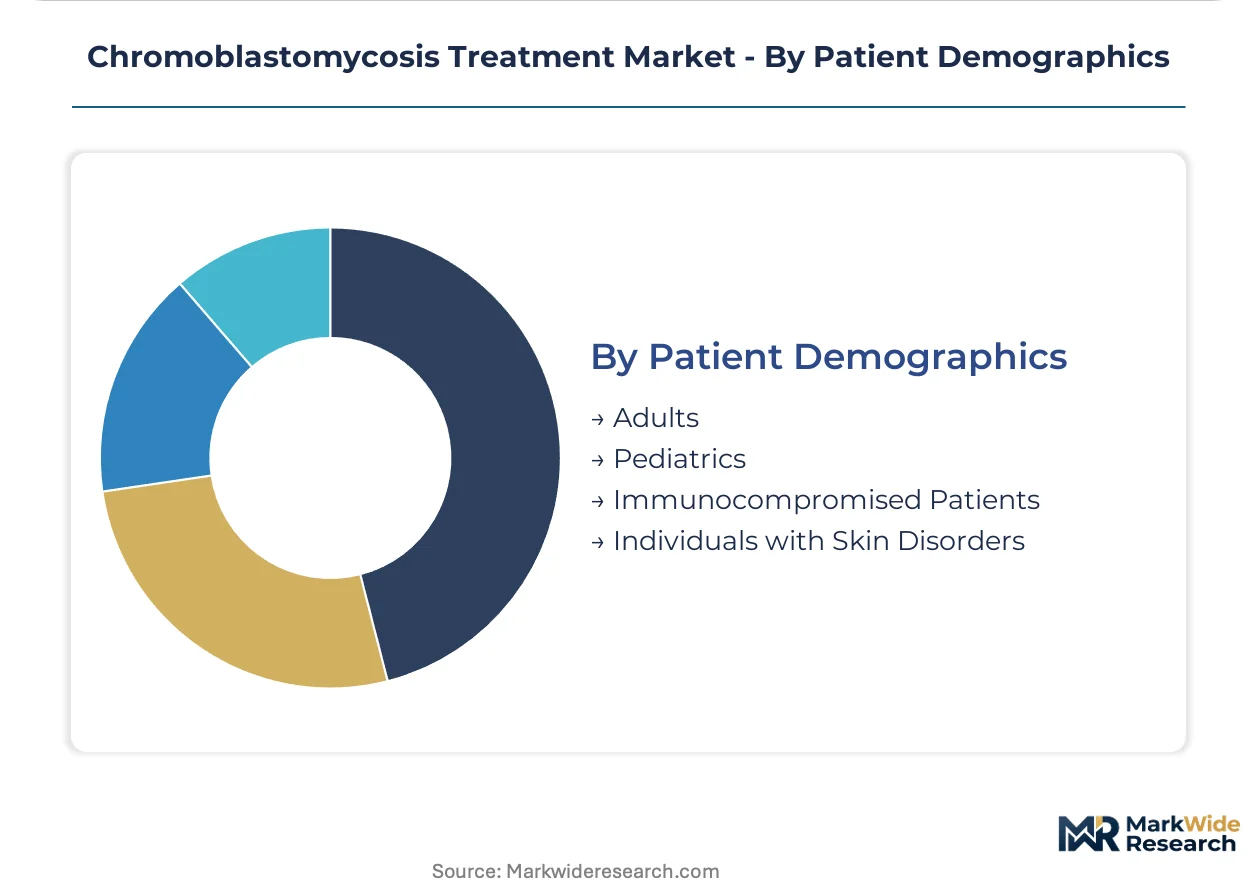
Patient Demographics:
Therapeutic indexing and dosing algorithms adjust across age, immune status, and comorbidity profiles.
- Adults:Agricultural workers in endemic tropical zones constitute the primary prevalence pool. Brazilian rural dermatology clinic expansion targets this demographic with point-of-care diagnostic platforms.
- Immunocompromised Patients:HIV co-infection and transplant immunosuppression amplify dissemination risk and mortality. Sub-Saharan African treatment guidelines prioritize rapid itraconazole initiation in this subgroup.
- Pediatrics:Dosing weight-band adjustments and formulation palatability constrain therapeutic options.
- Individuals with Skin Disorders:Pre-existing dermatoses complicate lesion recognition and therapeutic response assessment.
Service delivery capacity concentrates on Adults; unmet need expands fastest among Immunocompromised Patients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of itraconazole active pharmaceutical ingredient concentrates in China and India, while patient consumption clusters in Brazil and sub-Saharan Africa where rural dermatology networks manage extended treatment protocols. This geographic disconnect shapes cold chain logistics investments and regulatory filing priorities across tropical disease programs.
Brazil
Federally funded SUS procurement channels drive itraconazole volume through ANVISA-registered suppliers, with hospital pharmacy committees unbundling antifungal contracts from infectious disease bundles. The EU Green Deal pharmaceutical procurement rules are pressuring Brazilian tender processes to incorporate carbon footprint verification for imported medicines. Amazon basin municipalities in Pará and Amazonas states pilot point-of-care diagnostic platforms that compress diagnostic-treatment intervals from weeks to days.
India
Contract manufacturers in Hyderabad and Ahmedabad supply bulk azole APIs to Latin American public health systems under WHO prequalification standards. CDSCO stability requirements for tropical climate zones align with export documentation demands from Brazil and African regulators. Gujarat-based production clusters face EU Green Deal audits that redirect procurement toward verified greener manufacturing credentials.
South Africa
Sub-Saharan distribution networks anchor regional access to heat-stable oral formulations, with provincial health departments managing twelve-to-twenty-four-month treatment adherence programs. The country's national pharmaceutical regulator enforces bioequivalence documentation that mirrors WHO prequalification standards. KwaZulu-Natal and Eastern Cape rural clinics serve as last-mile delivery points where cold chain gaps favor solid dosage forms over reconstitutable suspensions.
Mexico
Northern border states and Mexico City metro hospitals participate in Pan American Health Organization pooled procurement for antifungal medicines, with COFEPRIS registration requirements extending approval timelines for specialty tropical disease products. Dermatology residency programs in Guadalajara and Monterrey address workforce scarcity in mycology diagnostics. Federal expansion of rural health posts in Chiapas and Oaxaca targets agricultural worker populations in endemic zones.
Germany
EMA antifungal resistance surveillance guidelines emanating from Frankfurt influence clinical trial endpoint design for triazole developers worldwide, mandating species-level susceptibility reporting for Fonsecaea and Cladophialophora. Bavaria-based pharmaceutical packaging specialists supply climate-zone stability testing services to tropical disease drug makers. REACH compliance requirements for azole manufacturing intermediates shape supplier qualification processes for export-oriented API producers.
Chromoblastomycosis Treatment Market Competitive Environment
The competitive structure tilts toward diversified pharmaceutical conglomerates with established tropical disease portfolios and geographic scale. Tier-one players leverage bulk supply contracts and WHO prequalification status to secure hospital pharmacy procurement channels, while mid-tier specialists concentrate on heat-stable formulation development. Strategic moves center on backward integration into API production and partnership networks for last-mile distribution in laboratory-scarce regions.
Among diversified pharmaceutical conglomerates, Pfizer Inc., Novartis AG, and Merck & Co. occupy positions that exemplify scale-driven competitive archetypes. Pfizer represents the bulk supply contract model, securing multi-year agreements with Latin American public health systems. Novartis anchors the sustained R&D investment pattern, with novel triazole formulations targeting refractory fungal presentations. Merck & Co. sits within the geographic dominance archetype, leveraging sub-Saharan African distribution infrastructure where chromoblastomycosis case clusters concentrate. These three companies collectively illustrate how procurement consolidation around WHO prequalification standards rewards documented bioequivalence and climate-zone stability capabilities.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| Merck & Co. |
| Astellas Pharma |
| Janssen Pharmaceuticals |
| Sanofi |
| Bayer AG |
| F. Hoffmann-La Roche |
| Bristol-Myers Squibb |
| Others |
Value Chain & Pricing Dynamics
Azole active pharmaceutical ingredient spot prices in Indian and Chinese bulk chemical markets cascade through contract manufacturing tiers into stratified hospital pharmacy procurement bands across Latin American and African public health systems. This input-cost transmission mechanism concentrates pricing power among WHO-prequalified suppliers with validated tropical stability documentation.
Pricing Analysis
Treatment completion rates serve as the value-based pricing anchor, with Brazilian SUS procurement committees weighting total cost-of-ownership metrics against clinical endpoint achievement. Three-tier pricing structure across premium, standard, and economy levels separates patented extended-release formulations from generic triazoles and locally compounded alternatives. Cost compression in the economy tier is intensifying because ANVISA local registration incentives reward domestic manufacturing investment. Cash-constrained rural patient populations exhibit highest price sensitivity, while immunocompromised cohorts in tertiary hospital settings demonstrate lowest elasticity due to limited therapeutic alternatives.
Supply Chain Analysis
WHO prequalification certification gates access to Brazilian and sub-Saharan African procurement channels, filtering supplier pools to documented bioequivalence holders. Bulk itraconazole API production draws from Hyderabad, Ahmedabad, and selected Zhejiang province manufacturing clusters. Supply chain risk centers on single-source vulnerability for heat-stable solid dosage form production. Distribution runs through provincial health department warehouses to last-mile rural dermatology clinics in Amazon basin municipalities and KwaZulu-Natal districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API manufacturing capacity constraints in validated tropical stability facilities prop pricing premiums for qualified suppliers, creating a supply-constrained market structure favoring incumbent consolidation over new capacity entry.
For Market Incumbents: Deepen backward integration into azole API production to secure supply continuity against Indian and Chinese contract manufacturer concentration risk. Expand heat-stable formulation R&D partnerships with Brazilian domestic manufacturers to capture ANVISA expedited registration pathways. Threat of emerging heat-stable topical combination therapies from mid-tier specialists demands accelerated pipeline investment in adherence-enhancing delivery technologies. For New Entrants and Emerging Players: EU Green Deal pharmaceutical procurement rules in European tender processes open a window for carbon-verified manufacturing entrants to displace legacy suppliers in Pan American Health Organization pooled procurement. Target sub-Saharan African distribution network gaps where cold chain infrastructure underdevelopment favors heat-stable solid oral dosage form specialists. Go-to-market angle: direct provincial health department contracting in South Africa's Eastern Cape and KwaZulu-Natal bypassing traditional distributor markups. For Investors and Strategic Acquirers: Distressed-cycle entries favor Brazilian domestic manufacturing assets with ANVISA registration infrastructure and established SUS procurement relationships. Five-to-ten year viability framing centers on consolidation of fragmented regional formulation capacity into integrated tropical disease medicine platforms. Signal to watch: Fonsecaea and Cladophialophora species resistance surveillance data triggering EMA guideline revisions and accelerated triazole development timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Stable Formulation Development | ANVISA registration pathways reward domestic Brazilian production investment with expedited approval timelines. |
| WHO Prequalification Pursuit | Documented bioequivalence and tropical stability data unlocks SUS and PAHO procurement channel access. |
| Point-of-Care Diagnostic Integration | Compressed diagnostic-treatment intervals in Amazon basin municipalities reduce unnecessary empiric therapy exposure. |
| Carbon Footprint Verification | EU Green Deal pharmaceutical procurement rules redirect tropical disease tenders toward greener manufacturing credentials. |
| Extended-Release Triazole R&D | Novel drug delivery technologies reduce dosing frequency and improve adherence in remote patient populations. |
Study Parameters
Document review covered WHO prequalification databases, ANVISA registration filings, and EMA antifungal resistance surveillance guidelines, complemented by interviews with hospital pharmacy procurement managers, tropical disease drug development executives, regulatory affairs leads at Brazilian and South African manufacturers, and formulary directors at Latin American public health systems. Secondary validation drew from ClinicalTrials.gov endpoints, SUS procurement disclosure records, and CDSCO stability requirement documentation. Bottom-up patient volume estimates and top-down pharmaceutical expenditure data were triangulated to establish market sizing.
Segment-level value and volume outputs were generated across treatment modality, formulation type, indication severity, and patient demographic dimensions over the projection horizon. CAGRs were derived from regression analysis of historical procurement volume trends and projected rural clinic expansion rates. Forecast inputs incorporated hepatic metabolism monitoring infrastructure deployment timelines and species-level susceptibility reporting requirements in clinical trial design.
The model assumes a particular technology adoption path for extended-release triazole formulations; alternative pathways for liposomal amphotericin B delivery systems would alter the outlook. Forecasts reflect assumptions around patient retention in twelve-to-twenty-four-month treatment protocols and regulatory alignment between WHO, FDA, and EMA stability standards. A model refresh is warranted upon material change in azole API manufacturing concentration or EMA antifungal resistance surveillance guideline revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Mental Retardation Treatment Market
Specialty Medicine
Desmoid Tumor Market
Specialty Medicine
Polycystic Kidney Disease Treatment Market
Specialty Medicine
Diverticulitis Disease Market
Specialty Medicine
Phenylketonuria Therapeutics Market
Specialty Medicine
Advance Renal Cell Carcinoma Therapeutics Market
Specialty Medicine
Toxic Epidermal Neurolysis Market
Specialty Medicine
Global Phenylketonuria Treatment Market
Specialty Medicine
US Actinic Keratosis Treatment Market
Specialty Medicine
Intramedullary Osteosarcoma Treatment Market
Specialty Medicine
Global Dry Eye Syndrome Treatment Market
Specialty Medicine
Global Constipation Treatment Market
Specialty Medicine
Multiple Endocrine Neoplasia Market
Specialty Medicine
Post-Traumatic Stress Disorder Treatment Market
Specialty Medicine
China Ulcerative Colitis Market
Specialty Medicine
Asia-Pacific Sports Medicine Market