
 Global Pharmaceutical Grade Sodium Chloride Market | 2026-2036
Global Pharmaceutical Grade Sodium Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pharmaceutical Grade Sodium Chloride Market Intelligence
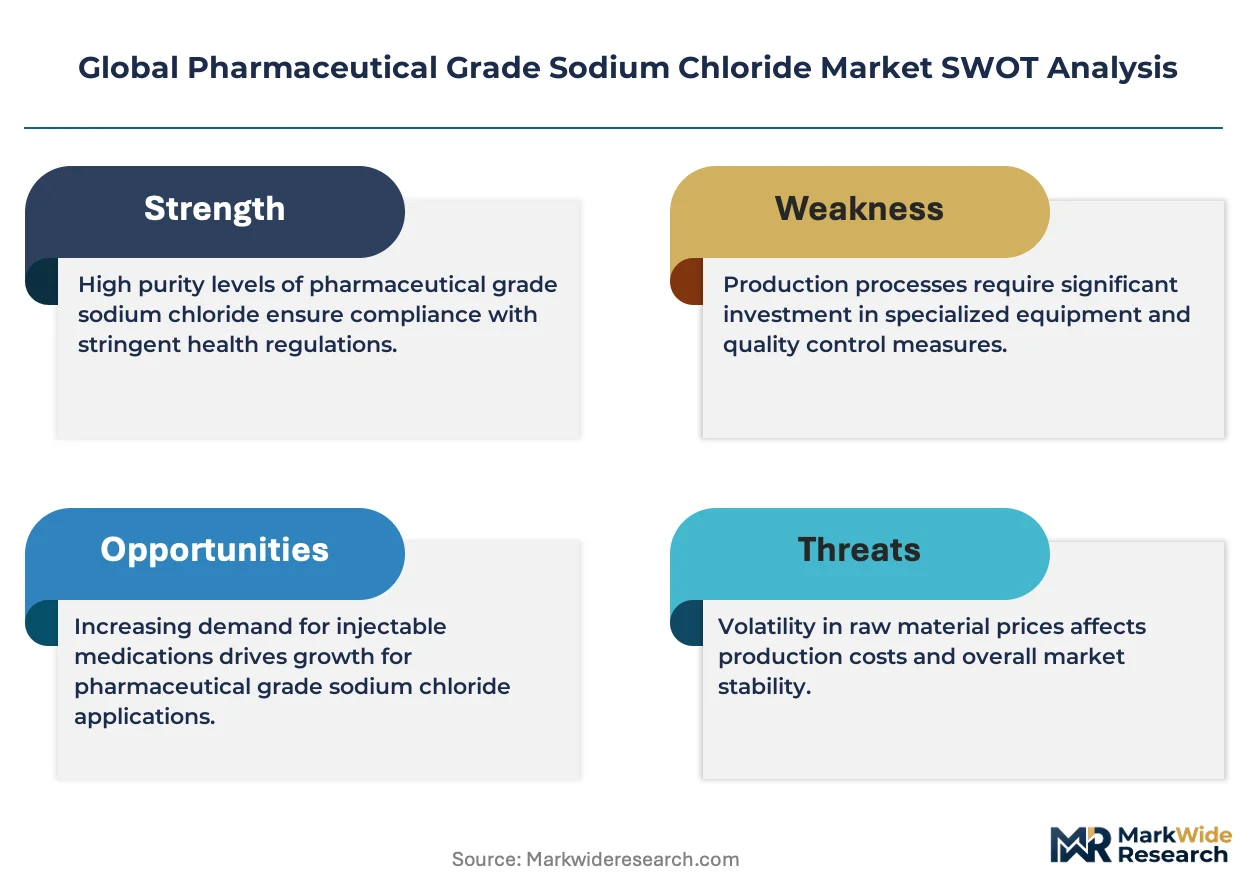
Maintenance contracts for electrolyte calibration and buffer preparation systems is consolidating around suppliers who bundle technical support with bulk salt supply. AkzoNobel leverages its integrated chlor-alkali network to anchor European hospital procurement. Tata Chemicals competes on cost-adjusted purity for Asian generic injectable manufacturers. Südwestdeutsche Salzwerke AG specializes in small-batch EP-certified production for compounding pharmacies.
Pharmaceutical grade sodium chloride denotes a highly purified sodium chloride product meeting pharmacopeial standards for endotoxin limits, heavy metal content, and microbial contamination, typically manufactured through controlled evaporation or recrystallization processes for use as an active pharmaceutical ingredient or excipient in parenteral and ophthalmic formulations. Injection Grade material commands premium positioning due to pyrogen-free certification burdens, while Dialysis Solutions applications are expanding fastest as home-based renal therapy programs multiply across health systems. Eye Drops formulations represent a mature margin pool where brand loyalty and preservative compatibility testing create switching costs for manufacturers.
FDA enforces USP-NF monograph compliance for all sodium chloride destined for injectable use, while EMA's MDR and REACH frameworks impose traceability and impurity disclosure obligations on European suppliers. India's CDSCO mandates BIS certification alongside pharmacopeial alignment for import and domestic sale of pharmaceutical salts. Stakeholders must monitor evolving pharmacopeial harmonization talks between USP, EP, and JP standards to anticipate reformulation and requalification costs.
Market Dynamics
Hospital procurement consolidation and the EU's MDR purity documentation mandates are compressing supplier margins while rewarding integrated chlor-alkali operators who bundle technical support with bulk pharmaceutical salt supply.
Growth Catalysts
- Home-based renal therapy expansion:Dialysis solutions demand from health systems decentralizing chronic kidney care is pulling pyrogen-free sodium chloride volumes into ambulatory settings.
- REACH traceability mandates:ECHA's impurity disclosure obligations for European medical device-grade salts are disqualifying commodity suppliers and opening share for certified pharmaceutical-grade producers.
- India's pharmaceutical manufacturing corridor:Concentrated injectable generic production around Hyderabad and Ahmedabad is creating localized demand clusters for cost-adjusted high-purity salt.
Market Restraints
- Energy-intensive evaporation costs:Natural gas and electricity input volatility directly compresses margins for recrystallization-dependent producers without captive power generation.
- Supply concentration in European chlor-alkali networks:AkzoNobel's integrated coastal production anchors hospital procurement, limiting second-source options for buyers seeking supply security.
- Pharmacopeial harmonization friction:Divergent endotoxin testing protocols between USP, EP, and JP standards force dual qualification runs and inventory segmentation.
Strategic Opportunities
- Compounding pharmacy specialization:Small-batch EP-certified production for sterile preparation facilities represents underserved volume with premium pricing power.
- CDSCO import certification alignment:India's BIS-pharmacopeial convergence for domestic salt sale creates first-mover advantage for suppliers pre-qualifying under unified standards.
- Ophthalmic preservative compatibility testing:Brand loyalty in mature eye drops markets creates switching-cost barriers that lock in qualified sodium chloride suppliers against generic substitution.
Industry Challenges
- Analytical chemist scarcity:Pyrogen testing and heavy metal assay expertise shortages delay batch release timelines and inflate quality-control headcount costs.
- Legacy ERP integration with serialization:Track-and-trace mandates for pharmaceutical excipients force expensive middleware deployment to connect plant-floor systems with regulatory reporting portals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pharmaceutical Grade Sodium Chloride Market |
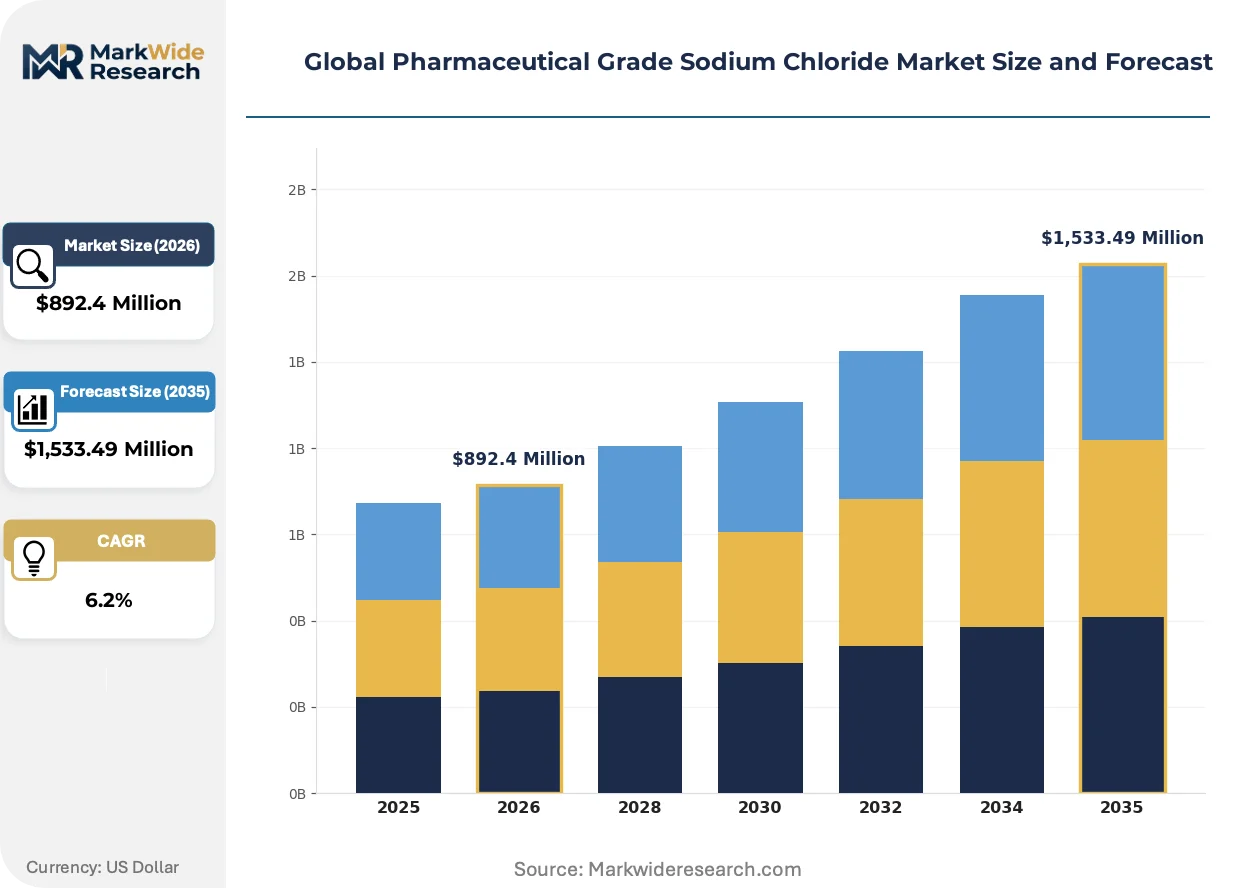
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,533.49 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Grade, Injectable, Ophthalmic Grade, Food Grade, USP, BP Application: Intravenous Therapy, Dialysis Solutions, Eye Drops, Wound Care, IV Fluids, Nasal Spray End User: Hospitals, Pharmacies, Clinics, Diagnostic Laboratories, Ambulatory Centers, Nursing Homes Packaging Type: Vials, Ampoules, Plastic Bottles, Glass Bottles, Sachets, Bulk Containers |
| Companies Covered | Morton Salt, AkzoNobel, K+S Aktiengesellschaft, Nouryon, Cargill, Südwestdeutsche Salzwerke AG, Salinen Austria AG, Tata Chemicals, Dominion Salt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pharmaceutical Grade Sodium Chloride Market Strategic Shifts & Innovations
Continuous manufacturing technologies and real-time release testing protocols are compressing batch cycle times while pharmacopeial harmonization talks create temporary regulatory arbitrage windows for agile suppliers.
Membrane cell chlor-alkali technology is expanding into pharmaceutical-grade sodium chloride production, replacing mercury and diaphragm cell methods with lower-impurity brine processing. European hospital procurement groups are adopting this output for IV solution manufacturing to preempt REACH substance restrictions. The technology is expanding into premium injection-grade positioning as pyrogen-free certification burdens intensify.
EMA's updated MDR framework imposes documentary evidence requirements for heavy metal content and microbial contamination across medical device-grade salt supply chains. Suppliers must now maintain batch-specific certificates of analysis accessible to notified bodies for unannounced audits. German compounding pharmacies and dialysis solution blenders face the steepest compliance recertification timelines.
Maintenance contract bundling now dominates electrolyte calibration and buffer preparation system procurement, with technical support hours traded against bulk salt volume commitments. Asian generic injectable manufacturers are displacing spot purchases with multi-year agreements that embed on-site analytical training. This pattern concentrates most visibly in India's pharmaceutical manufacturing corridor around Hyderabad.
Global Pharmaceutical Grade Sodium Chloride Market Segmentation
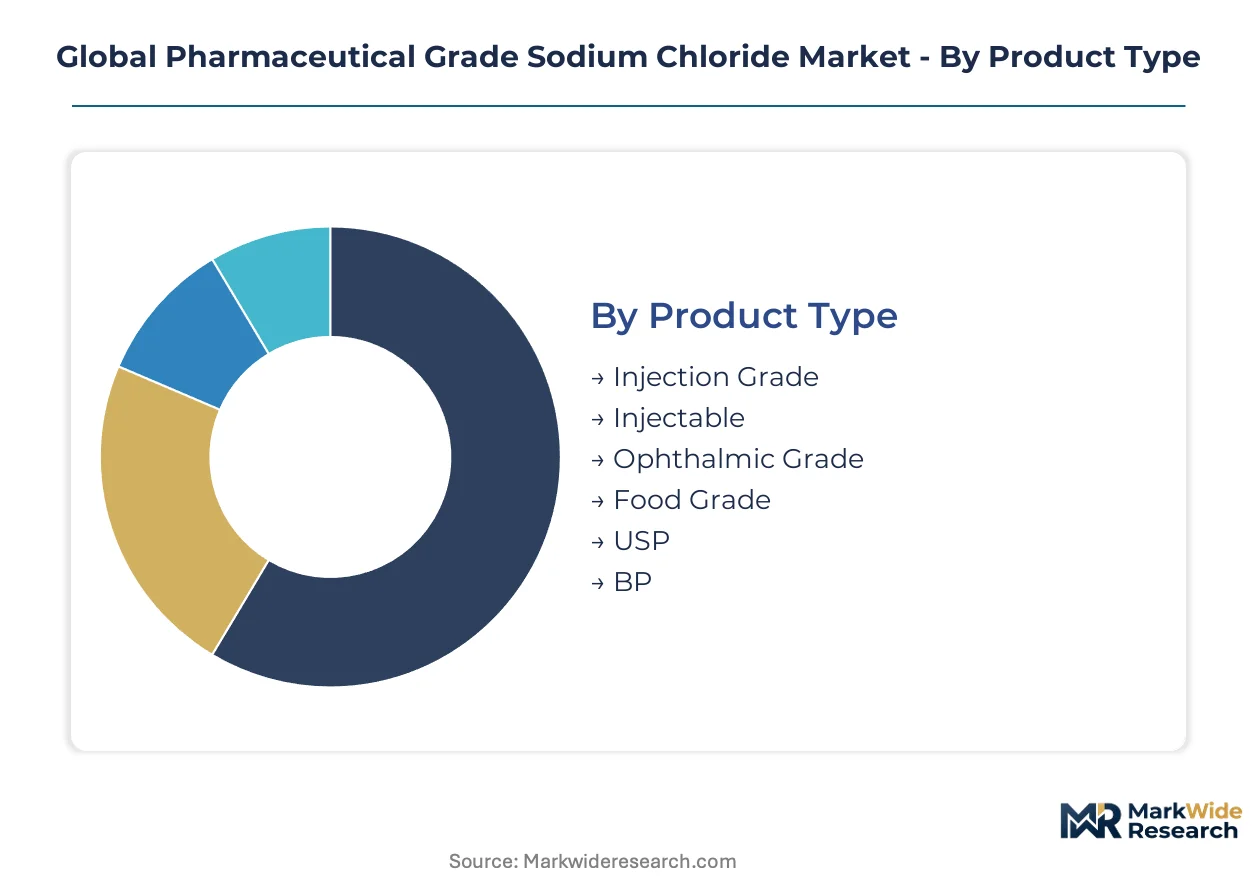
Pharmaceutical grade sodium chloride supply chains fragment sharply across purity tiers and sterility requirements. Each segment carries distinct pyrogen-testing burdens, packaging constraints, and procurement channel preferences that reshape supplier economics.
Product Type:
Supply concentration in European chlor-alkali networks favors operators with integrated membrane cell technology and captive brine processing.
- Injection Grade:Pyrogen-free certification demands endotoxin limits below 0.5 EU/g and sterile filtration protocols. Hospital procurement groups in Germany and the Netherlands anchor demand as IV fluid manufacturing consolidates around multi-year technical support contracts.
- Ophthalmic Grade:Particulate matter specifications below 10μm and preservative compatibility testing dominate qualification. Brand loyalty in Japanese and US eye drop formulations creates switching-cost barriers that lock qualified suppliers into long-term agreements.
- Injectable:General parenteral applications with moderate sterility requirements serve compounding pharmacies and regional IV blenders.
- Food Grade:Lower purity thresholds exclude this material from parenteral use but capture excipient demand in oral solid dosage manufacturing.
- USP:United States Pharmacopeia alignment governs FDA-regulated production with heavy metal and microbial contamination documentation.
- BP:British Pharmacopoeia standards apply to Commonwealth markets and former colonial supply chains with distinct assay protocols.
Injection Grade absorbs the bulk of installed capacity; Ophthalmic Grade is expanding most quickly.
Application:
Cost tier differentiation separates high-volume commodity contracts from premium pyrogen-free supply with embedded technical services.
- Dialysis Solutions:Bicarbonate and acetate buffer systems require ultra-low aluminum content below 10μg/L. Home-based renal therapy programs in Italy and Spain are pulling pyrogen-free volumes into ambulatory settings as health systems decentralize chronic kidney care.
- Intravenous Therapy:Large-volume parenterals demand endotoxin-controlled sodium chloride for electrolyte restoration and fluid resuscitation. Hospital upgrading of infusion capabilities across India's Hyderabad-Ahmedabad corridor is concentrating procurement around suppliers bundling bulk salt with calibration maintenance.
- Eye Drops:Preservative compatibility and tonicity matching dominate formulation requirements in mature margin pools.
- Wound Care:Irrigation solutions require sterile saline with lower documentation burdens than injectable grades.
- IV Fluids:Standard electrolyte replacement products serve emergency medicine and surgical recovery protocols.
- Nasal Spray:Isotonic formulations for respiratory and vaccine delivery applications require particulate control below ophthalmic thresholds.
Intravenous Therapy commands the largest revenue footprint; Dialysis Solutions is climbing the fastest as home therapy multiplies.
End User:
Customer type determines packaging format preferences, batch size requirements, and the depth of analytical documentation demanded.
- Hospitals:Central pharmacy compounding and direct IV fluid manufacturing drive bulk container procurement with just-in-time delivery requirements. European hospital groups are consolidating contracts around integrated chlor-alkali operators who embed technical support hours against volume commitments.
- Pharmacies:German and Swiss compounding pharmacies require small-batch EP-certified production with batch-specific certificates of analysis accessible for unannounced audits.
- Clinics:Outpatient infusion centers prefer pre-filled syringes and ready-to-use bags over bulk processing.
- Diagnostic Laboratories:Buffer preparation and reagent manufacturing consume pharmaceutical-grade salt at lower purity tiers than parenteral applications.
- Ambulatory Centers:Same-day surgical facilities drive demand for single-dose packaging and reduced handling protocols.
- Nursing Homes:Long-term care hydration therapy uses standard IV fluids with less stringent documentation than acute care settings.
Hospitals absorb the bulk of installed capacity; Pharmacies is gaining share fastest as compounding specialization deepens.
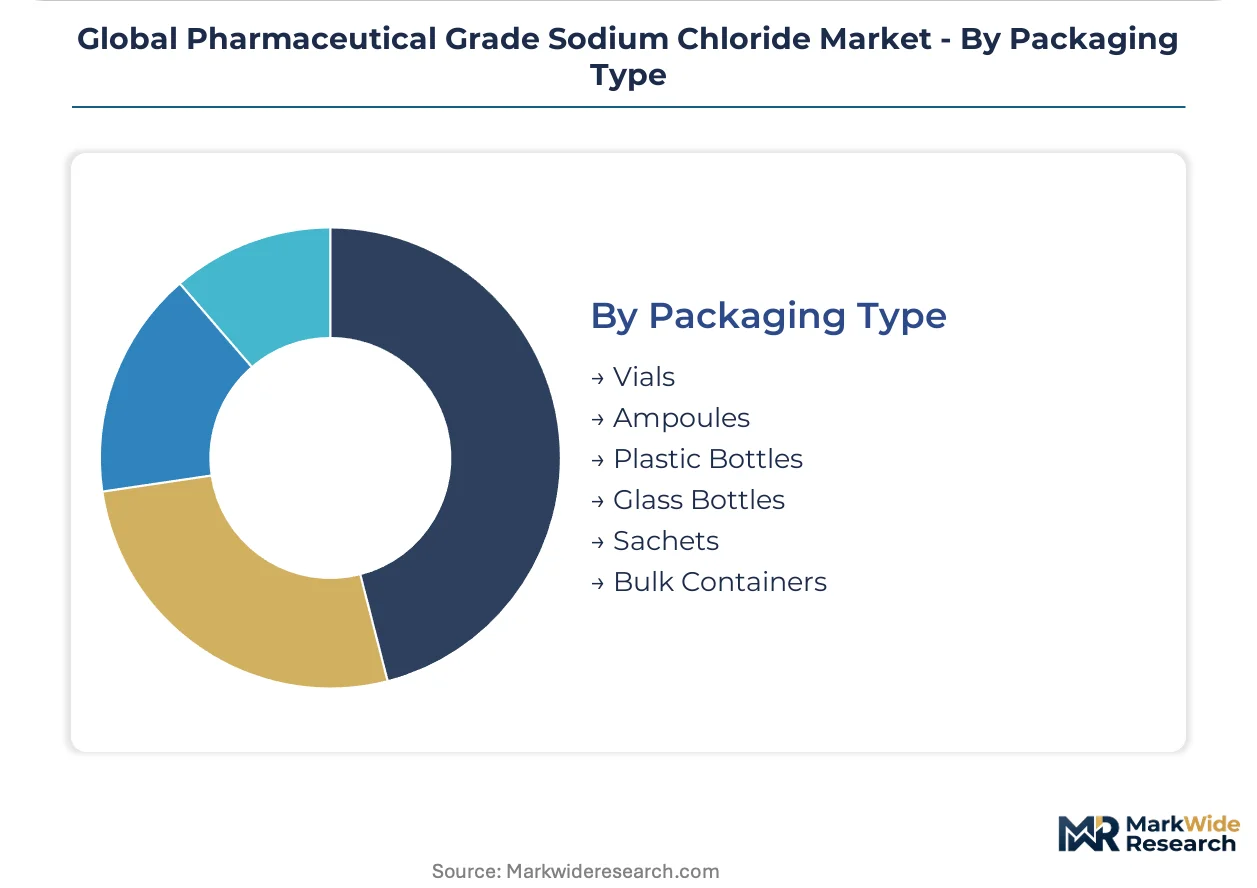
Packaging Type:
Volume scale and sterility maintenance requirements dictate material selection across glass, polymer, and bulk handling systems.
- Bulk Containers:25kg to 1000kg pharmaceutical-grade totes serve IV fluid manufacturers and dialysis solution blenders with in-house sterile processing. India's generic injectable corridor around Hyderabad is displacing spot purchases with multi-year agreements embedding on-site analytical training.
- Plastic Bottles:Blow-fill-seal technology for ophthalmic and nasal applications requires extractables and leachables testing. US and Japanese packaging converters dominate this segment with validated polymer supply chains.
- Vials:Sterile powder presentation for reconstitution in hospital pharmacy settings.
- Ampoules:Single-dose glass presentation for emergency medicine and field deployment.
- Glass Bottles:Traditional presentation for preservative-containing formulations requiring inert headspace.
- Sachets:Unit-dose powder for oral rehydration and wound irrigation in resource-limited settings.
Bulk Containers absorb the bulk of installed capacity; Plastic Bottles is expanding most quickly as blow-fill-seal technology spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European chlor-alkali networks generate the bulk of pharmaceutical-grade output, while Asian demand clusters concentrate around injectable manufacturing corridors. Consumption gravity is shifting toward decentralized renal therapy programs and compounding pharmacy specialization.
Germany
Hospital procurement consolidation and dialysis solution blending anchor sodium chloride demand. EMA's MDR framework imposes documentary evidence requirements for heavy metal content and microbial contamination. The Rhine-Ruhr industrial corridor hosts membrane cell chlor-alkali operations serving European compounding pharmacies.
United States
FDA-enforced USP-NF monograph compliance governs all injectable-grade material, driving pyrogen-free certification investments. The country's national pharmaceutical regulator maintains strict endotoxin testing protocols. Bulk container procurement concentrates around Midwestern IV fluid manufacturers upgrading infusion capabilities.
India
CDSCO-mandated BIS certification alongside pharmacopeial alignment creates dual compliance burdens for domestic and import salt. The pharmaceutical manufacturing corridor around Hyderabad and Ahmedabad concentrates injectable generic production. Localized demand clusters favor suppliers bundling technical support with bulk salt volume commitments.
Japan
PMDA alignment with pharmacopeial standards governs ophthalmic grade material for preservative-compatible eye drop formulations. METI oversight ensures traceability for medical device-grade salts. The Kanto region around Tokyo anchors brand-loyal procurement patterns in mature ophthalmic markets.
Switzerland
Swissmedic requirements for EP-certified production support small-batch sterile preparation facilities. German-speaking compounding pharmacies across the border source from Alpine saltworks with batch-specific certificates of analysis. The Basel pharmaceutical cluster drives premium-grade demand for parenteral applications.
Global Pharmaceutical Grade Sodium Chloride Market Key Industry Players
Top-tier vendors anchor European hospital procurement through integrated chlor-alkali networks, while mid-tier specialists occupy compounding pharmacy and regional IV blender niches. The structure rewards backward integration into captive brine processing and membrane cell technology. Three archetypes dominate: integrated chemical conglomerates with coastal production assets, family-owned saltworks with EP-certified small-batch capabilities, and Asian cost-adjusted purity suppliers. Capacity expansion and maintenance contract bundling represent the dominant competitive moves.
Within the integrated chemical conglomerate tier, AkzoNobel and Nouryon exemplify operators leveraging coastal chlor-alkali infrastructure to anchor multi-year hospital procurement agreements. Among family-owned specialists with certified small-batch capabilities, Südwestdeutsche Salzwerke AG occupies a position serving German and Swiss compounding pharmacies. At the Asian cost-adjusted purity end, Tata Chemicals represents suppliers competing for generic injectable manufacturer volume around India's pharmaceutical corridor. These three anchors illustrate how geographic production assets and certification scope determine competitive positioning.
| Leading Market Players |
|---|
| Morton Salt |
| AkzoNobel |
| K+S Aktiengesellschaft |
| Nouryon |
| Cargill |
| Südwestdeutsche Salzwerke AG |
| Salinen Austria AG |
| Tata Chemicals |
| Dominion Salt |
| Others |
Cost & Logistics Intelligence
Membrane cell chlor-alkali technology is displacing legacy mercury and diaphragm methods, simultaneously lowering impurity burdens in pharmaceutical-grade brine processing and concentrating production economics around coastal operators with captive power and integrated evaporation assets. This technological transition tightens supply concentration while compressing unit costs for qualified output.
Pricing Analysis
Margin tightening in Injection Grade material reflects pyrogen-free certification burdens and endotoxin testing protocol fragmentation between USP, EP, and JP standards. Three-tier pricing structure across premium pyrogen-free, standard injectable, and technical-grade levels separates hospital procurement contracts from compounding pharmacy spot purchases. Cost-down pressure on Asian generic manufacturers accelerates because CDSCO-mandated BIS certification adds dual compliance overhead. Regional IV blenders in India's Hyderabad corridor exhibit highest price sensitivity; European hospital groups bundling technical support with volume commitments show lowest.
Supply Chain Analysis
Freight cost volatility for bulk pharmaceutical-grade totes is amplifying procurement localization around manufacturing corridors. Supply concentrates in Germany, the Netherlands, and India; captive brine processing in coastal chlor-alkali networks feeds from natural gas, electricity, and membrane cell electrolyzer inputs. Single-source vulnerability intensifies as AkzoNobel's integrated European production anchors hospital procurement with limited qualified second sources. Distribution runs through direct long-term offtake agreements with IV fluid manufacturers and dialysis solution blenders rather than spot commodity markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated chlor-alkali operators as EMA's MDR purity documentation mandates and energy cost volatility force smaller recrystallization-dependent producers toward exit.
For Market Incumbents: To counter margin compression from energy-intensive evaporation costs, deepen backward integration into captive power generation and membrane cell technology refresh. Anchor hospital procurement through multi-year maintenance contracts bundling technical support hours against bulk salt volume commitments.
For New Entrants and Emerging Players: Capture compounding pharmacy specialization in German and Swiss markets where small-batch EP-certified production commands premium positioning with underserved volume. Penetrate through pre-qualification under India's converging BIS-pharmacopeial standards before competitors consolidate first-mover advantage.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of family-owned saltworks with certified small-batch capabilities and established EP audit trails. Long-term viability favors targets with membrane cell technology and coastal brine access over legacy evaporation-dependent operators. Watch EMA-CDSCO regulatory convergence talks as inflection indicator for reformulation-driven requalification demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Cell Technology Upgrade | Lowers heavy metal contamination for REACH-compliant medical device-grade output. |
| Long-term Supply Agreement | Locks hospital procurement consolidation through embedded calibration maintenance services. |
| Backward Integration into Captive Power | Insulates margin from natural gas and electricity input volatility in recrystallization. |
| EP Certification Investment | Opens compounding pharmacy segment with batch-specific audit documentation. |
| Joint Venture in Indian Corridor | Captures localized demand from Hyderabad-Ahmedabad generic injectable manufacturing. |
Research Approach
Trade databases, pharmacopeial monograph repositories, and chlor-alkali industry association filings formed the secondary backbone, cross-referenced against primary interviews with plant managers at European membrane cell operators, procurement leads at Indian generic injectable manufacturers, hospital pharmacy directors in Germany and the Netherlands, and regulatory affairs specialists navigating MDR compliance. Bottom-up volume modeling from application-specific consumption rates and top-down validation against installed chlor-alkali capacity enabled triangulation.
Bottom-up segmentation across grade tier, end-use application, packaging format, and regional production hub generated volume and value outputs across the projection horizon. CAGRs derived from regression against healthcare infrastructure investment cycles, renal therapy decentralization rates, and pharmacopeial harmonization progress. Forecast inputs incorporated energy cost scenarios for evaporation-dependent producers and REACH substance restriction timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pharmacopeial standard convergence, membrane cell technology diffusion rates, and regulatory audit intensity shifts. Forecasts reflect documented assumptions about hospital procurement consolidation velocity and home-based renal therapy program expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Global Ibuprofen Market
Pharmaceutical Ingredients
Pharmaceutical Indicator Strips Market
Pharmaceutical Ingredients
Amphetamine Drug Market
Pharmaceutical Ingredients
Pharmaceuticals Grade Sodium Bicarbonate Market
Pharmaceutical Ingredients
Pharmaceutical Suspension Market
Pharmaceutical Ingredients
Calcium Gluconate Market
Pharmaceutical Ingredients
Pharmaceutical Desiccants Market
Pharmaceutical Ingredients
Active Pharmaceutical Ingredient for Cancer Market
Pharmaceutical Ingredients
Albumin (As Excipient) Market
Pharmaceutical Ingredients
Pharmaceutical Grade Amino Acid Market
Pharmaceutical Ingredients
Saudi Arabia Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Global Aspirin Market
Pharmaceutical Ingredients
Zinc Bacitracin Market
Pharmaceutical Ingredients
Germany Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Pharmaceutical Thermal Analysis Market
Pharmaceutical Ingredients
Cox 2 Inhibitors Market