
 Cox 2 Inhibitors Market | 2026-2036
Cox 2 Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Cox 2 Inhibitors Market Outlook
The capital-intensity divergence between large-cap innovators and mid-tier generics manufacturers is unwinding competitive stability in Cox 2 inhibitors. Pfizer leverages its legacy formulation expertise to sustain brand loyalty in the celecoxib segment. Jiangsu Hengrui Pharma anchors its position through cost-optimized manufacturing scale, while Dr. Reddy's competes aggressively on price across emerging markets.
Cox 2 inhibitors are selective cyclooxygenase-2 enzyme blockers synthesized through multi-step organic chemistry involving pyrazole ring construction, formulated to suppress prostaglandin synthesis without gastric COX-1 inhibition. Their primary purpose centers on chronic inflammatory pain management where gastrointestinal tolerability limits traditional NSAID use. The oral delivery mode dominates volume due to patient convenience and established reimbursement pathways, while the arthritis therapy area represents the most mature margin pool despite etoricoxib gaining traction in regions with favorable cardiovascular risk profiles. Transdermal formulations remain nascent but attract R&D investment where hepatic metabolism concerns restrict oral dosing.
The FDA maintains stringent cardiovascular outcome surveillance through post-market safety mandates, while the EMA's pharmacovigilance framework shapes European prescribing thresholds for agents with elevated thrombotic risk. India's CDSCO imposes bioequivalence standards on domestic manufacturers that constrain rapid generic substitution. Stakeholders must monitor evolving cardiovascular safety databases and regional reimbursement recalibrations to align portfolio priorities with shifting risk-benefit thresholds.
Market Dynamics
FDA cardiovascular safety mandates are compressing prescribing latitude for legacy Cox 2 inhibitors while redirecting R&D investment toward transdermal delivery systems that bypass hepatic first-pass metabolism.
Growth Catalysts
- Aging demographics in the United States:Chronic osteoarthritis prevalence among adults over 65 sustains volume demand for gastrointestinal-sparing analgesics in rheumatology clinics.
- EMA pharmacovigilance framework refinement:Risk stratification protocols in Europe enable differentiated prescribing for etoricoxib where cardiovascular profiles permit.
- Pyrazole synthesis optimization:Continuous flow chemistry methods reduce active pharmaceutical ingredient production costs for generic manufacturers.
Market Restraints
- Cardiovascular outcome liability:Post-market surveillance requirements from FDA impose sustained clinical trial burdens on manufacturers.
- API supply concentration:China dominates intermediate chemical production for pyrazole ring construction, exposing formulators to geopolitical supply disruptions.
- Traditional NSAID substitution:Proton pump inhibitor co-therapy erodes the gastrointestinal tolerability advantage of selective Cox 2 blockade.
Strategic Opportunities
- Transdermal formulation development:Patch-based delivery addresses hepatic metabolism concerns in elderly polypharmacy patients.
- India's domestic market expansion:CDSCO bioequivalence standards create protected windows for local manufacturers before full generic substitution.
- Pain management protocol integration:Multimodal arthritis care pathways in Japan incorporate Cox 2 inhibitors within METI-supported chronic disease frameworks.
Industry Challenges
- Cardiovascular safety signal detection:Pharmacovigilance teams must parse real-world evidence databases to satisfy FDA post-market mandates.
- Formulation scale-up complexity:Transdermal patch manufacturing requires specialized equipment and excipient sourcing beyond oral solid dose capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cox 2 Inhibitors Market |
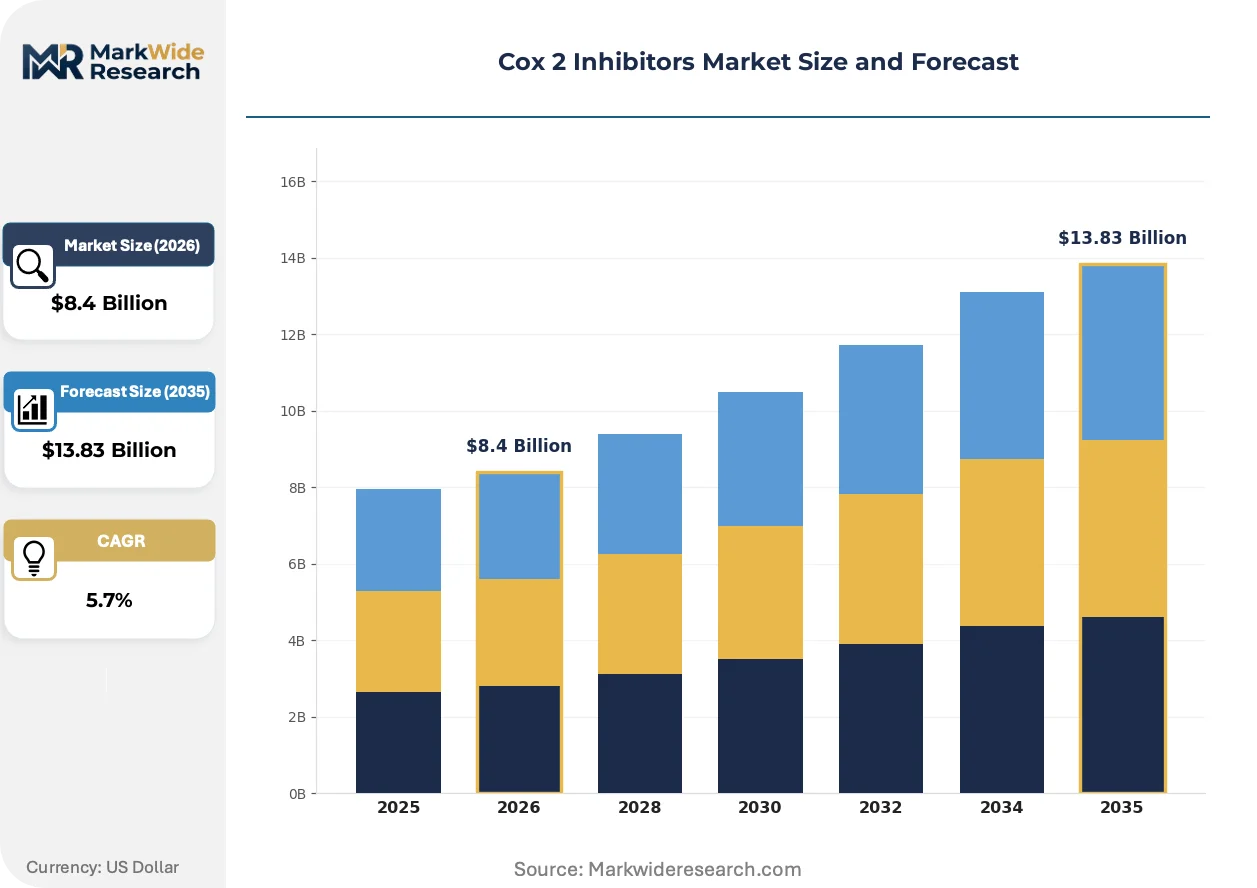
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Celecoxib, Rofecoxib, Etoricoxib, Valdecoxib Therapy Area: Arthritis, Pain Management, Gynecological Disorders, Cardiovascular Delivery Mode: Oral, Injectable, Transdermal, Topical End User: Hospitals, Clinics, Homecare, Pharmacies |
| Companies Covered | Novartis, Pfizer, Bayer, Merck, AbbVie, Jiangsu Hengrui Pharma, Cadila Pharmaceuticals, Dr. Reddy's, CrystalGenomics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cox 2 Inhibitors Market Strategic Shifts
Delivery technology diversification and regulatory risk stratification are bifurcating the Cox 2 inhibitor landscape between legacy oral formulations and next-generation transdermal systems.
Transdermal patch technology is supplanting oral tablets in geriatric pain management where polypharmacy and hepatic impairment complicate systemic dosing. Rheumatology practices in Japan and Germany are piloting patch protocols for osteoarthritis patients with compromised liver function. This modality shift is compressing the addressable market for conventional oral solids while opening premium pricing tiers for formulation innovators.
REACH chemical safety registration in Europe is tightening scrutiny on residual solvents in pyrazole synthesis intermediates. Manufacturers must reformulate purification steps or source alternative suppliers to maintain EMA market authorization. Generic producers in India face particular compliance pressure as CDSCO aligns domestic standards with European chemical safety benchmarks.
Hospital formulary committees are consolidating purchasing authority through centralized procurement platforms that favor sole-source contracts with demonstrated cardiovascular safety databases. This concentration is displacing fragmented physician-directed prescribing in the United States, where integrated delivery networks now control therapeutic category access. Rheumatology clinics within these networks face restricted Cox 2 inhibitor choice unless manufacturers provide institution-specific outcome data.
Cox 2 Inhibitors Market Segmentation
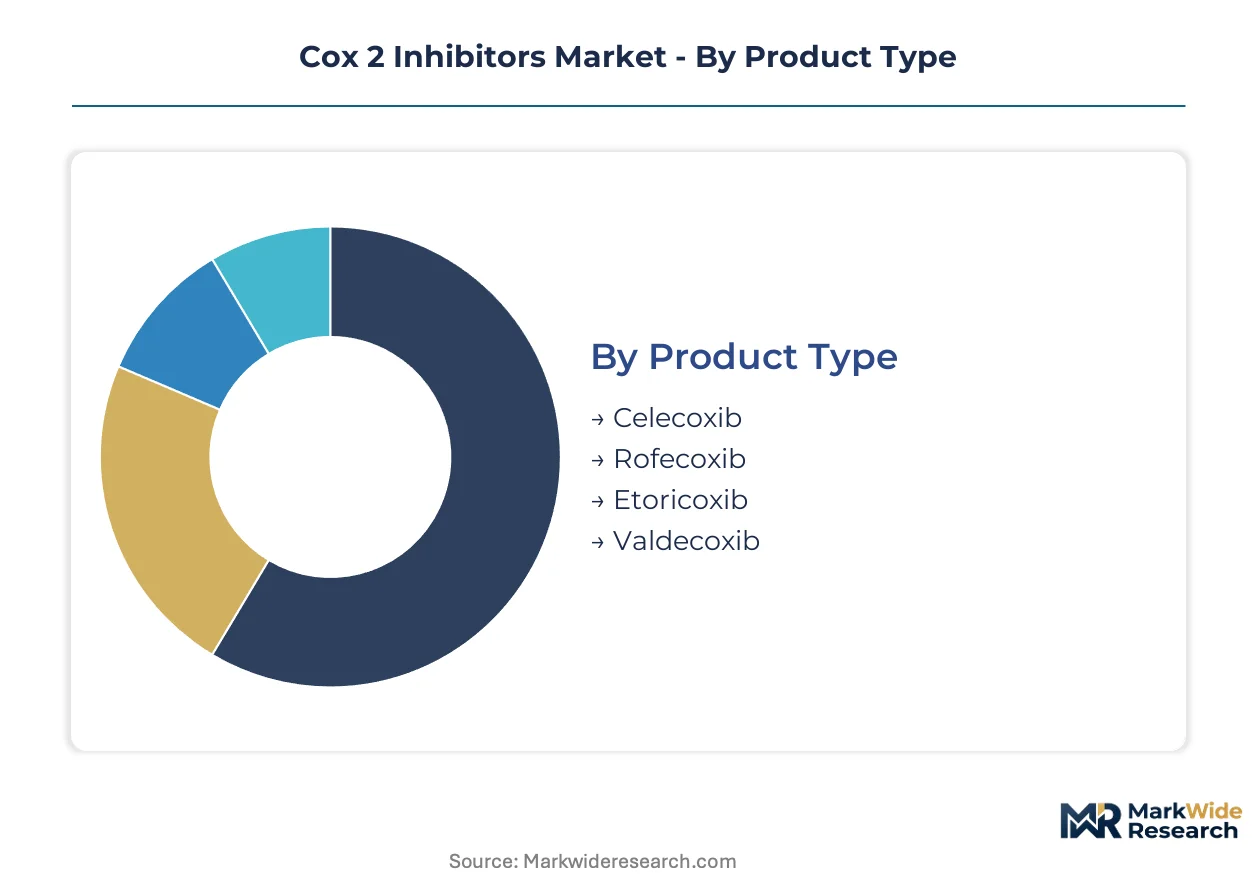
Channel configuration for Cox 2 inhibitors diverges sharply across product generations, with legacy oral formulations flowing through retail pharmacy networks while next-generation transdermal systems penetrate hospital formularies. Rheumatology clinics and integrated delivery networks now gatekeep therapeutic access, making end-user channel mapping essential for portfolio positioning.
Product Type:
Hospital procurement channels favor etoricoxib and celecoxib with established cardiovascular safety databases, while retail pharmacies handle legacy rofecoxib and valdecoxib volumes where prescribing latitude persists.
- Celecoxib:Pyrazole-ring COX-2 selective inhibitor with sulfonamide substitution pattern. Rheumatology clinics in the United States concentrate demand for osteoarthritis protocols where FDA cardiovascular labeling permits continued use. Pfizer's formulation expertise sustains brand loyalty against generic substitution.
- Etoricoxib:Biphenyl-substituted pyrazole derivative with extended half-life enabling once-daily dosing. German and Japanese rheumatology practices drive adoption where EMA and PMDA pharmacovigilance frameworks permit differentiated risk stratification.
- Rofecoxib:Furanone-based COX-2 inhibitor withdrawn from major markets retains niche presence in specific regulatory jurisdictions with localized safety assessments.
- Valdecoxib:Amide-substituted pyrazole compound with rapid onset characteristics serves acute pain indications in hospital settings where injectable co-formulations exist.
By volume, celecoxib leads through pharmacy channel dominance. By growth pace, etoricoxib is climbing the fastest in European and Asian hospital systems.
Therapy Area:
Cost tier stratification separates chronic disease management from acute intervention, with arthritis commanding premium pricing and cardiovascular applications requiring outcome-based contracting.
- Arthritis:Osteoarthritis and rheumatoid arthritis maintenance therapy represents the mature revenue base where gastrointestinal-sparing profiles justify Cox 2 selection over traditional NSAIDs. United States rheumatology clinics sustain volume leadership through aging demographic demand.
- Pain Management:Post-surgical and chronic non-malignant pain applications concentrate in hospital discharge protocols and homecare transitions where oral convenience drives adherence.
- Gynecological Disorders:Dysmenorrhea and endometriosis-related pain management in specialized clinic settings where hormonal co-therapy complicates NSAID selection.
- Cardiovascular:Thrombotic risk mitigation protocols in perioperative settings where selective COX-2 inhibition reduces platelet dysfunction compared to non-selective alternatives.
Arthritis commands the largest absolute spend. Pain management applications are gaining share fastest through multimodal protocol integration.
Delivery Mode:
Manufacturing scale and margin structure favor oral solids, while transdermal development attracts R&D investment where hepatic metabolism concerns create pricing power.
- Oral:Tablet and capsule formulations dominate commercial volumes through established bioequivalence pathways and patient convenience. Generic manufacturers in India leverage continuous flow chemistry to compress API costs for solid dose production.
- Transdermal:Patch-based delivery systems bypass first-pass hepatic metabolism for elderly polypharmacy patients with compromised liver function. Japanese and German pilot programs demonstrate feasibility in rheumatology settings.
- Injectable:Parenteral formulations serve perioperative and acute care hospital settings where rapid onset and nil-per-os status predominate.
- Topical:Cream and gel preparations target localized joint inflammation with reduced systemic exposure, penetrating pharmacy retail channels for early-stage osteoarthritis self-management.
Oral delivery holds volume leadership across all geographies. Transdermal systems show the steepest expansion trajectory through geriatric-focused development pipelines.
End User:
Customer type concentration is shifting from fragmented physician prescribing toward centralized hospital formulary control, with homecare emerging as a channel for chronic disease maintenance.
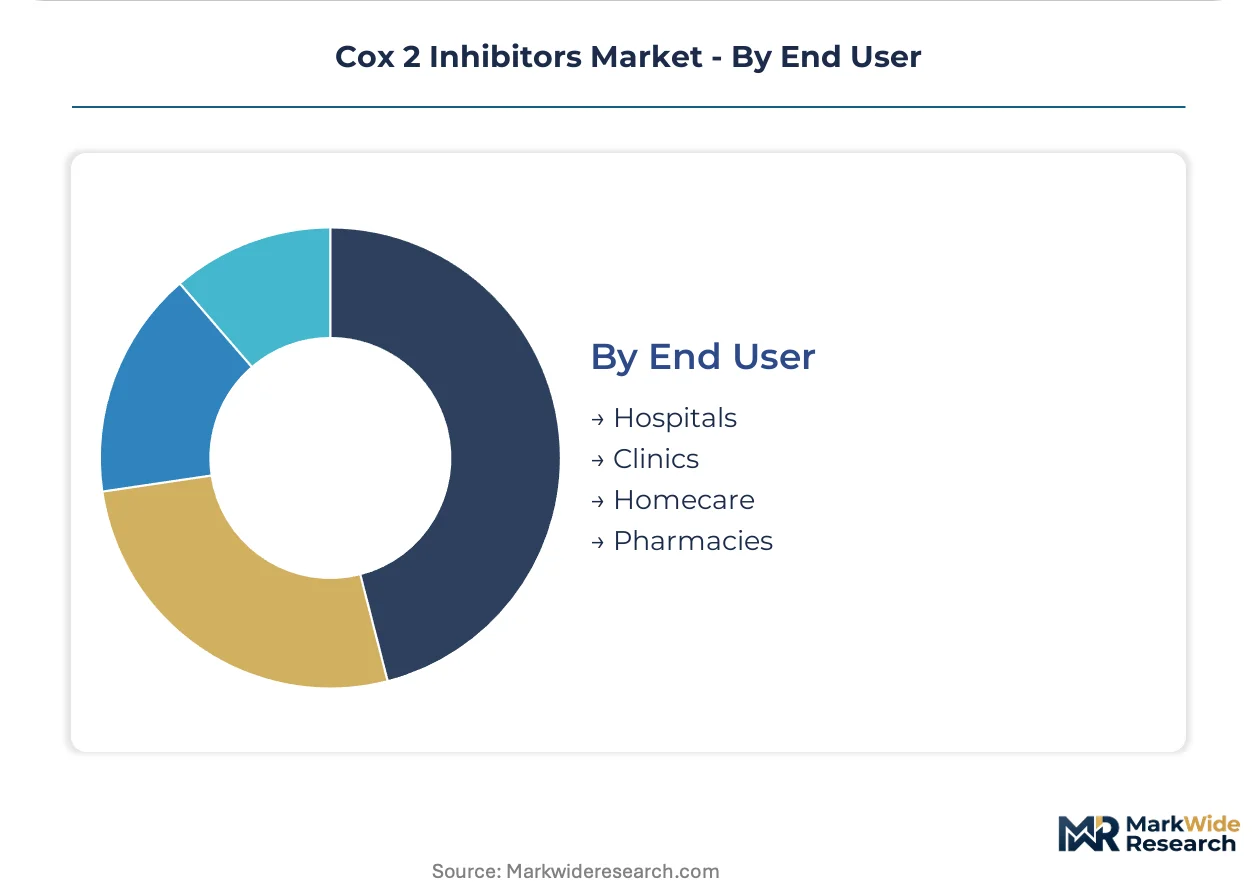
- Hospitals:Integrated delivery networks and centralized procurement platforms consolidate purchasing authority through sole-source contracts demanding cardiovascular outcome databases. Formulary committees in United States health systems now gatekeep Cox 2 inhibitor access.
- Clinics:Rheumatology and pain management specialty practices retain prescribing autonomy in fee-for-service reimbursement environments, particularly in European outpatient settings.
- Homecare:Long-term oral maintenance therapy for chronic osteoarthritis patients transitions to residential and visiting nurse settings where adherence monitoring becomes critical.
- Pharmacies:Retail and mail-order channels handle refill volumes for stable chronic patients, with generic substitution rates highest in this segment.
Hospitals lead by prescription value through formulary concentration. Homecare is expanding most quickly through aging-in-place policy incentives and chronic disease management program growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Prescribing patterns for Cox 2 inhibitors diverge sharply by geography, with the United States favoring celecoxib maintenance therapy while Germany and Japan pilot transdermal protocols for hepatic-impaired elderly patients.
United States
Aging demographics and chronic osteoarthritis prevalence sustain volume demand for gastrointestinal-sparing analgesics in rheumatology clinics. FDA cardiovascular safety labeling requirements compress prescribing latitude for legacy formulations while redirecting investment toward delivery innovation. Integrated delivery networks in Texas and Florida now control formulary access through centralized procurement platforms demanding outcome databases.
Germany
Rheumatology practices drive etoricoxib adoption where EMA pharmacovigilance frameworks permit differentiated risk stratification for patients with favorable cardiovascular profiles. REACH chemical safety registration tightens scrutiny on residual solvents in pyrazole synthesis intermediates, forcing manufacturers to reformulate purification steps. The Baden-Württemberg pharmaceutical cluster hosts formulation specialists advancing continuous flow chemistry methods for API cost reduction.
Japan
METI-supported chronic disease frameworks incorporate Cox 2 inhibitors within multimodal arthritis care pathways for aging populations. PMDA pharmacovigilance protocols shape prescribing thresholds for agents with elevated thrombotic risk, favoring agents with established safety databases. Kanto region rheumatology clinics pilot patch-based delivery systems for patients with compromised liver function.
India
Domestic market expansion accelerates as CDSCO bioequivalence standards create protected windows for local manufacturers before full generic substitution. Cost-optimized manufacturing scale anchors competitive positioning for exporters targeting emerging markets. The Hyderabad-Visakhapatnam pharmaceutical corridor concentrates API production and formulation development for pyrazole-ring inhibitors.
China
Intermediate chemical production for pyrazole ring construction dominates global supply, exposing formulators to geopolitical disruption risks. NMPA market authorization pathways align with international cardiovascular safety benchmarks while domestic demand concentrates in urban hospital systems. The Yangtze River Delta hosts the principal manufacturing clusters for COX-2 selective inhibitor raw materials.
Cox 2 Inhibitors Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with multinational pharmaceutical conglomerates leveraging legacy formulation expertise against mid-tier generics manufacturers competing on cost-optimized scale. The market structure compresses into two primary competitive vectors: brand loyalty sustained through clinical data investment versus price-driven substitution enabled by continuous flow chemistry advances. Strategic archetypes include patent-protected innovators, bioequivalence-focused generic houses, and regional API-to-formulation integrators. Dominant competitive moves encompass transdermal delivery partnerships and sole-source hospital contracts demanding cardiovascular outcome databases.
Among integrated pharmaceutical conglomerates, Pfizer and Novartis occupy positions exemplifying the innovation-driven archetype through sustained investment in formulation differentiation and regulatory compliance infrastructure. Jiangsu Hengrui Pharma represents the cost-optimized manufacturing tier, anchoring competitive positioning through scale advantages in API production and emerging market penetration. Dr. Reddy's sits within the aggressive generic substitution segment, competing on price across regulatory jurisdictions with streamlined bioequivalence pathways.
| Leading Market Players |
|---|
| Novartis |
| Pfizer |
| Bayer |
| Merck |
| AbbVie |
| Jiangsu Hengrui Pharma |
| Cadila Pharmaceuticals |
| Dr. Reddy's |
| CrystalGenomics |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory buffers for pyrazole-ring intermediates now separate price-stable manufacturers from exposed formulators, concentrating purchasing power among hospital formulary committees that command sole-source contracts while compressing margins for fragmented retail pharmacy suppliers.
Pricing Analysis
Long-term offtake agreements dominate hospital procurement channels where integrated delivery networks lock in cardiovascular outcome-backed suppliers, while spot purchasing persists in retail pharmacy segments. Three-tier pricing structure across premium, standard, and economy levels reflects FDA safety database depth, EMA REACH compliance status, and bioequivalence certification tier. Cost compression in generic oral solids is intensifying because Indian manufacturers deploy continuous flow chemistry to undercut legacy formulations. Retail pharmacy buyers exhibit highest price sensitivity, whereas hospital formulary committees prioritize outcome documentation over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes inflate inbound logistics costs for pyrazole intermediate shipments, forcing European formulators to absorb margin erosion or reformulate purification steps. China, India, and Germany anchor global supply for COX-2 selective inhibitor raw materials, with the Yangtze River Delta and Hyderabad-Visakhapatnam corridor hosting principal manufacturing clusters. API production draws from specialized pyrazole ring construction, sulfonamide substitution chemistry, and biphenyl derivative synthesis. Single-source vulnerability concentrates in Chinese intermediate supply, exposing formulators to geopolitical disruption. Distribution runs through hospital centralized procurement platforms, retail pharmacy networks, and emerging homecare channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Cox 2 inhibitor market is recovering from cyclical patent cliff pressures as transdermal delivery innovation and aging demographic demand restore pricing power to formulation specialists.
For Market Incumbents: Consolidate cardiovascular outcome databases to defend hospital formulary positions against generic substitution. Pfizer and Novartis should deepen backward integration into pyrazole API production to offset Chinese supply concentration risk. EMA pharmacovigilance compliance investment remains essential to maintain premium pricing in European rheumatology clinics.
For New Entrants and Emerging Players: CDSCO bioequivalence fast-track pathways offer protected market windows before full generic substitution erodes margins. Target transdermal patch development for hepatic-impaired elderly populations in Japan and Germany where pricing power persists. Partner with Japanese METI-supported chronic disease frameworks to secure reimbursement pathway access.
For Investors and Strategic Acquirers: Long-term, this sits as a specialty pharmaceutical consolidation play because formulation differentiation and regulatory compliance infrastructure create durable moats against pure-price competition. Acquisition targets should demonstrate established cardiovascular safety databases and hospital formulary penetration. Watch FDA post-market surveillance mandate intensity as the inflection signal for R&D cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Transdermal Formulation Development | Patch-based delivery bypasses hepatic metabolism for elderly polypharmacy patients in Japanese rheumatology clinics. |
| Cardiovascular Outcome Database Investment | Hospital formulary committees demand institution-specific safety data for sole-source contract eligibility. |
| Continuous Flow Chemistry Scale-Up | Indian manufacturers compress pyrazole API production costs to undercut legacy solid-dose competitors. |
| EMA REACH Compliance Reformulation | Residual solvent scrutiny forces purification step redesign to maintain European market authorization. |
| Integrated Delivery Network Partnership | Texas and Florida health systems consolidate purchasing authority through centralized procurement platforms. |
Study Parameters
A spread of perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors converged on the working assumptions underlying this analysis. Primary interviews with rheumatology clinic administrators and pharmaceutical manufacturing specialists were cross-validated against FDA cardiovascular safety filings, EMA pharmacovigilance databases, ClinicalTrials.gov outcome records, and CDSCO bioequivalence submissions. Bottom-up prescription volume modeling and top-down therapeutic category spend analysis were triangulated to anchor projections.
Segmentation dimensions modeled include product type, therapy area, delivery mode, and end-user channel across the analysis window. CAGRs were derived from patient population growth trajectories, reimbursement pathway evolution, and regulatory approval velocity. Forecast inputs incorporated aging demographic projections, osteoarthritis prevalence curves, and hospital formulary consolidation patterns.
Decision-makers should treat outputs as directional under stable FDA cardiovascular surveillance intensity and continued EMA pharmacovigilance framework refinement; material deviation in regulatory stringency would warrant model refresh. Practitioners should keep alternative scenarios live as transdermal delivery technology maturation and generic substitution velocity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Lidocaine Hydrochloride Market
Pharmaceutical Ingredients
Europe Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Synthetic Small Molecule API Market
Pharmaceutical Ingredients
Scopolamine Market
Pharmaceutical Ingredients
Immunosuppressants Market
Pharmaceutical Ingredients
Albumin (As Excipient) Market
Pharmaceutical Ingredients
Epcam Antagonists Market
Pharmaceutical Ingredients
Histamine H2-Receptor Antagonists Market
Pharmaceutical Ingredients
Pharmaceutical Excipients for Taste Masking Market
Pharmaceutical Ingredients
Folinic Acid Market
Pharmaceutical Ingredients
Quinoline Market
Pharmaceutical Ingredients
Global Active Pharmaceutical Ingredients CDMO Market
Pharmaceutical Ingredients
Silver Sulfadiazine Market
Pharmaceutical Ingredients
MEK Inhibitors Market
Pharmaceutical Ingredients
Fixed-Dose Combination Drugs Market
Pharmaceutical Ingredients
Moxifloxacin Hcl (CAS 186826-86-8) Market