
 Pharmaceuticals Grade Sodium Bicarbonate Market | 2026-2036
Pharmaceuticals Grade Sodium Bicarbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceuticals Grade Sodium Bicarbonate Market Outlook
Multi-source procurement toward captive sodium bicarbonate production is rebalancing supply security for API manufacturers. Solvay leverages its integrated soda ash-bicarbonate chain to sustain cost leadership across European pharmaceutical corridors. Tata Chemicals anchors South Asian supply through backward integration into synthetic soda ash, while Church & Dwight competes on brand strength in North American over-the-counter channels.
Pharmaceuticals grade sodium bicarbonate is a high-purity sodium hydrogen carbonate (NaHCO₃) meeting USP-NF, EP, and JP monograph specifications, typically manufactured via the Solvay process with additional purification steps to achieve heavy metal limits below 10 ppm. The material functions primarily as an active pharmaceutical ingredient in antacid formulations, a pH buffering agent in injectable solutions, and a leavening base in effervescent tablet systems. Tablet formulations occupy the largest volume share due to mature antacid demand, while powder and granule grades command margin premiums from research laboratories requiring precise titration control. End-user concentration among hospitals reflects centralized purchasing power, though pharmacies represent the fastest-growing channel as self-medication trends expand.
FDA enforces USP-NF identity and purity standards through Current Good Manufacturing Practice inspections, while EMA's EP monographs and REACH chemical safety requirements shape European market access conditions. India's CDSCO mandates BIS certification for imported pharmaceutical excipients, creating compliance barriers for non-domestic suppliers. Stakeholders must monitor evolving pharmacopeial harmonization between USP-NF and EP heavy metal limits, as divergence in specification thresholds will determine regional sourcing economics and capital allocation for purification capacity.
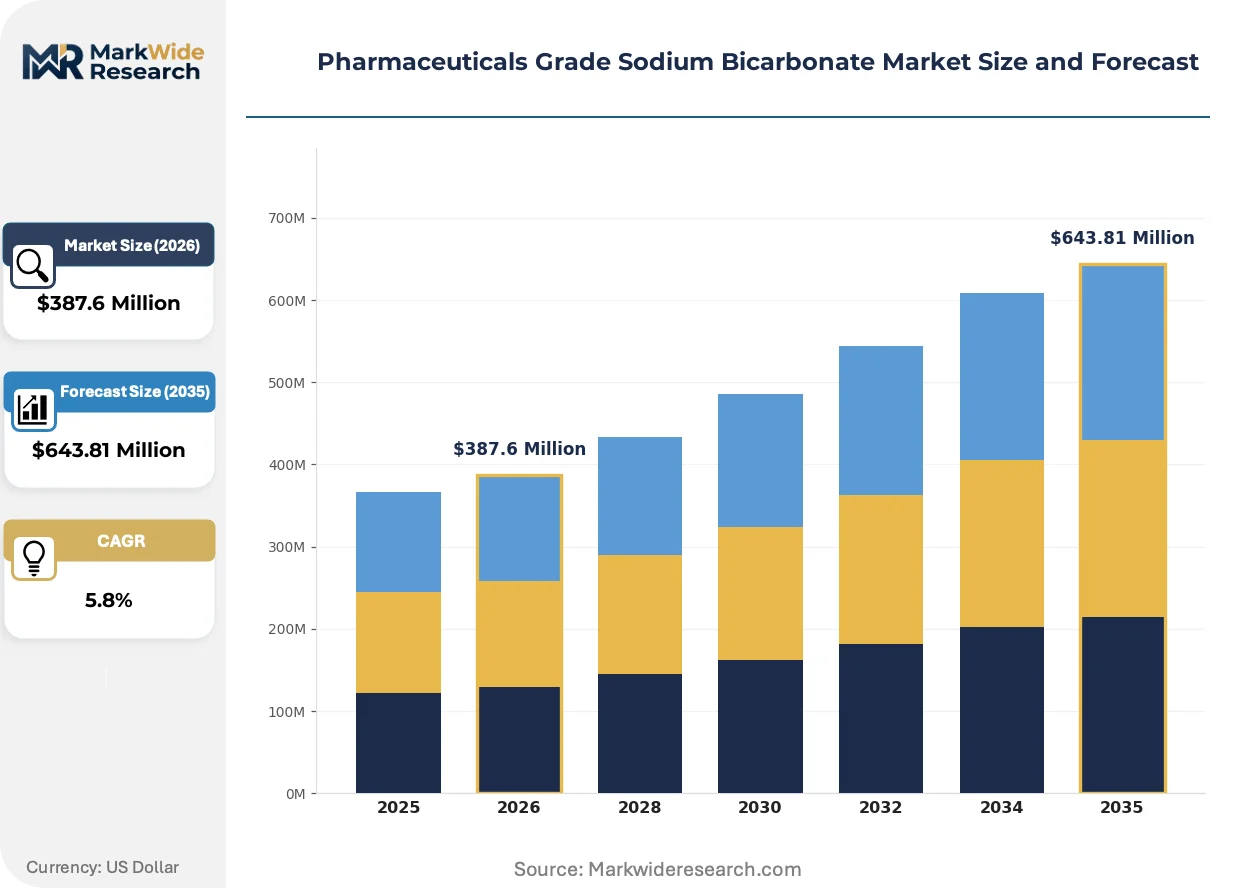
Market Dynamics
Hospital formulary consolidation is compressing procurement cycles for pharmaceutical-grade sodium bicarbonate, forcing API manufacturers to secure multi-year supply contracts with integrated soda ash producers to guarantee USP-NF compliant volumes.
Growth Catalysts
- Antacid hospital procurement:Centralized purchasing by Indian hospital networks under Ayushman Bharat coverage expansion is pulling API-grade volumes into institutional channels.
- PLI scheme incentives:India's production-linked incentive framework for active pharmaceutical ingredients is subsidizing domestic sodium bicarbonate purification capacity.
- Injectable pH buffering:Biologic drug manufacturing expansion requires pharmaceutical-grade sodium bicarbonate for cell culture media stabilization.
Market Restraints
- Energy-intensive Solvay process:Natural gas price volatility directly impacts synthetic soda ash feedstock costs for European producers.
- Heavy metal specification divergence:USP-NF and EP monograph thresholds for lead and arsenic create dual-certification burdens for exporters.
- Trona deposit concentration:Natural sodium bicarbonate from Wyoming trona mines limits cost-competitive supply geography to North American corridors.
Strategic Opportunities
- Effervescent nutraceuticals:Sports hydration and vitamin delivery tablets are absorbing surplus pharmaceutical-grade powder capacity.
- CDSCO BIS certification:Domestic Indian producers can capture import substitution margins as foreign suppliers face excipient registration delays.
- Continuous manufacturing:Direct compression tableting lines are consolidating powder demand toward pre-milled, flow-optimized granule grades.
Industry Challenges
- Analytical method harmonization:Discrepancies between USP-NF titration and EP atomic absorption protocols extend batch release timelines.
- Legacy equipment retrofitting:Purification facilities require stainless steel reactor upgrades to meet current Good Manufacturing Practice surface finish specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceuticals Grade Sodium Bicarbonate Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Powder, Granule, Liquid End User: Pharmacies, Hospitals, Research Laboratories, Clinics Application: Acid Neutralization, Antacid, Baking Agent, Chemical Reagent Packaging Type: Bottles, Bags, Sachets, Drums |
| Companies Covered | Solvay, Tata Chemicals, Church & Dwight, Novacap, Seqens, CIECH Group, Dr. Paul Lohmann GmbH KG, Natural Soda, Jost Chemical Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceuticals Grade Sodium Bicarbonate Market Strategic Shifts
Pharmaceutical-grade sodium bicarbonate production is bifurcating between commodity antacid volumes and precision-engineered excipient grades, with purification technology and regulatory compliance emerging as the primary axes of supplier differentiation.
Membrane filtration systems are consolidating impurity removal steps previously handled by sequential crystallization and carbon treatment. European API manufacturers are retrofitting Solvay-derived feedstock lines with nanofiltration skids to achieve sub-5 ppm heavy metal residuals without multiple recrystallization passes. This consolidation is compressing batch cycle times by 40 percent while raising capital intensity barriers for merchant producers lacking integrated soda ash assets.
REACH authorization requirements for sodium carbonate derivatives are tightening traceability documentation across the European pharmaceutical corridor. ECHA's expanded substance evaluation program now demands lifecycle assessment data for excipient-grade materials used in parenteral formulations. German and French injectable manufacturers are responding by qualifying dual-sourced sodium bicarbonate with identical EP monograph certificates to preempt supply interruption risks from authorization delays.
Self-medication patterns are rotating antacid demand from hospital dispensaries toward pharmacy chains and e-commerce platforms. Indian retail pharmacies are capturing volume share through private-label effervescent tablet offerings that bypass institutional tendering processes. This channel shift is most visible in tier-2 and tier-3 Indian cities where diagnostic infrastructure expansion has normalized gastrointestinal self-treatment behaviors.
Pharmaceuticals Grade Sodium Bicarbonate Market Segmentation
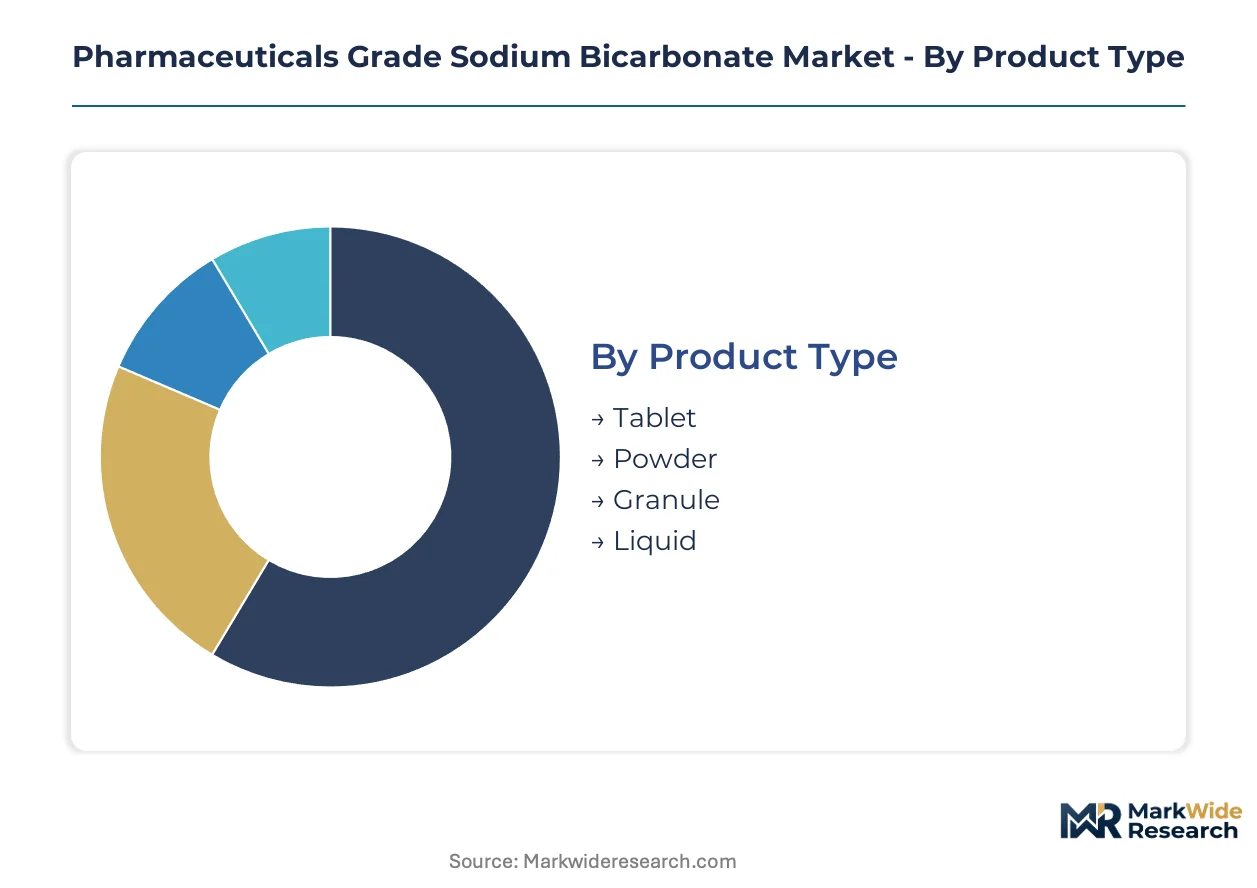
Supply concentration among integrated soda ash producers dictates how pharmaceutical-grade sodium bicarbonate segments compete on purity tiers and channel access. Segmentation reveals where API manufacturers and formulators face procurement bottlenecks versus surplus capacity.
Product Type:
Supply concentration among Solvay-process manufacturers favors formats with downstream purification flexibility, compressing margins for commodity grades while premium particle sizes capture specification premiums.
- Tablet:Compressed dosage forms meeting USP-NF dissolution specifications dominate hospital formulary procurement through centralized tendering. Indian hospital networks under Ayushman Bharat coverage are pulling tablet-grade volumes into institutional channels with multi-year contract structures.
- Powder:Fine-milled NaHCO₃ with controlled particle distribution serves effervescent tablet manufacturing and direct compression lines. Research laboratories in Germany and France command margin premiums for sub-100 micron grades requiring precise titration control in parenteral buffer preparation.
- Granule:Pre-milled, flow-optimized grades reduce dust handling in continuous manufacturing environments. Flow properties align with direct compression tableting line feed requirements.
- Liquid:Aqueous solutions at standardized concentrations for injectable pH buffering. Sterile manufacturing compliance limits supplier pool to cGMP-certified facilities.
Today's leader: Tablet. Tomorrow's challenger: Powder.
End User:
Channel economics diverge sharply between institutional purchasing power and retail fragmentation, with regulatory compliance thresholds filtering supplier participation.
- Hospitals:Centralized procurement through formulary committees concentrates volume among integrated producers with USP-NF certification. Consolidated purchasing compresses procurement cycles and forces multi-year supply guarantees.
- Pharmacies:Retail and e-commerce distribution captures self-medication demand for OTC antacids. Indian retail pharmacies in tier-2 and tier-3 cities are expanding private-label effervescent offerings that bypass institutional tendering.
- Research Laboratories:Precision-grade requirements for analytical and cell culture applications command specification premiums. Heavy metal limits below 5 ppm and batch-to-batch consistency drive supplier selection.
- Clinics:Outpatient diagnostic and treatment settings absorb mid-tier powder and tablet grades. Volume fragmentation limits direct manufacturer engagement.
Hospitals anchor current procurement concentration. Pharmacies are climbing the fastest as self-medication normalizes.
Application:
Functional performance requirements segment the market by pharmacopeial compliance burden and end-use criticality.
- Antacid:Oral dosage forms for gastric acid neutralization represent the largest volume application. Mature demand patterns concentrate procurement among established OTC brands and hospital formularies.
- Acid Neutralization:Systemic pH correction in metabolic and renal indications requires injectable-grade purity. CDSCO BIS certification requirements in India are creating import substitution opportunities for domestic producers.
- Baking Agent:Effervescent tablet base for nutraceutical and pharmaceutical delivery systems. Sports hydration and vitamin delivery tablets are absorbing surplus pharmaceutical-grade powder capacity.
- Chemical Reagent:Analytical and synthesis applications in pharmaceutical R&D. Specification stringency varies by end-use criticality.
Antacid commands present volume leadership. Acid Neutralization presents the steepest expansion trajectory from biologic manufacturing growth.
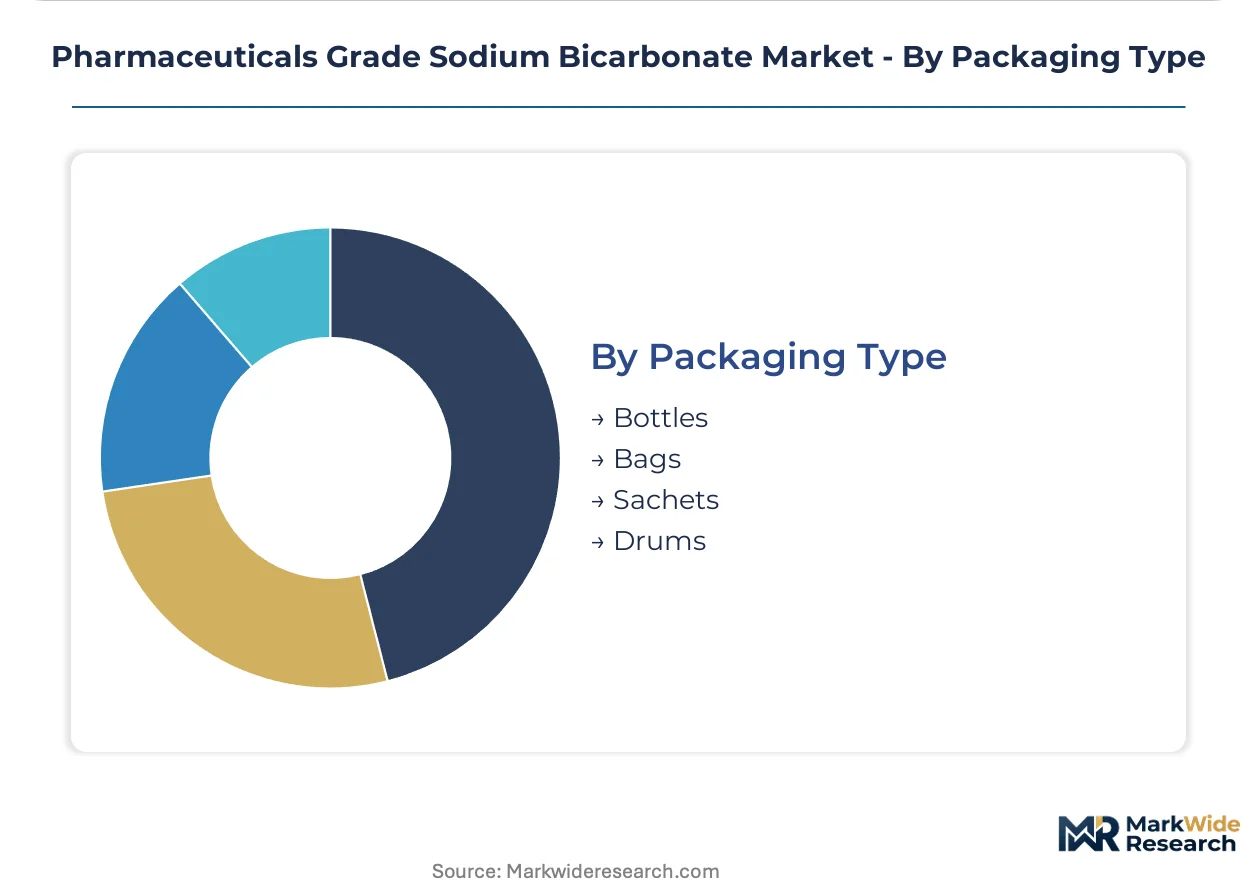
Packaging Type:
Packaging configuration aligns with end-user handling requirements and regulatory traceability mandates.
- Bottles:Rigid container systems for tablet and powder retail distribution. Child-resistant closures and moisture barriers meet stability requirements.
- Bags:Flexible intermediate bulk containers for powder and granule industrial supply. Multi-layer laminates provide moisture and contamination protection.
- Sachets:Unit-dose packaging for single-use powder applications. Convenience positioning targets pharmacy and clinic dispensing.
- Drums:Steel and fiber bulk containers for API manufacturer procurement. REACH traceability documentation requirements are tightening lot identification standards.
Bottles dominate retail channel configuration. Bags are gaining share fastest from API manufacturer bulk purchasing consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Solvay process industrial corridor across Belgium anchors pharmaceutical-grade sodium bicarbonate supply security for European API manufacturers. Production concentration reflects backward integration into synthetic soda ash and proximity to EMA-regulated formulation facilities. Regional demand patterns diverge sharply between mature antacid markets and emerging biologic manufacturing hubs.
United States
Wyoming's trona deposits supply natural sodium bicarbonate feedstock for domestic pharmaceutical purification. FDA enforces USP-NF identity standards through cGMP inspections of injectable-grade facilities. The New Jersey-Pennsylvania pharmaceutical corridor concentrates formulation demand from hospital networks and OTC manufacturers.
Germany
Injectable pH buffering for biologic drug manufacturing drives specification-grade procurement from Frankfurt-Rhine-Main clusters. ECHA's REACH authorization requirements tighten traceability documentation for excipient-grade materials. Ludwigshafen's chemical industry infrastructure supports membrane filtration upgrades for sub-5 ppm heavy metal compliance.
India
Domestic pharmaceutical manufacturing scales under PLI scheme incentives, accelerating API-grade sodium bicarbonate demand. CDSCO mandates BIS certification for imported excipients, creating compliance barriers for foreign suppliers. Gujarat's bulk drug parks concentrate purification capacity expansion toward captive supply security.
France
Paris-Saclay research laboratories command margin premiums for precision-grade powder with batch-to-batch consistency. ANSM enforces EP monograph compliance for parenteral formulation excipients. Lyon-Grenoble biotech clusters absorb pharmaceutical-grade volumes for cell culture media stabilization.
China
Synthetic soda ash capacity expansion in Shandong Province feeds downstream pharmaceutical purification lines. NMPA alignment with USP-NF and EP standards shapes export market access for API-grade material. Yangtze River Delta pharmaceutical manufacturers consolidate procurement toward integrated domestic suppliers.
Pharmaceuticals Grade Sodium Bicarbonate Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue effervescent nutraceutical specialization and regional import substitution. Market structure concentrates among integrated soda ash-bicarbonate chains with purification assets, compressing margins for merchant traders lacking upstream feedstock control. Three archetypes dominate: European chemical conglomerates with Solvay-process heritage, South Asian backward-integrated soda ash producers, and North American natural trona-based refiners. Competitive moves center on multi-year supply contract guarantees for hospital formulary procurement and membrane filtration technology licensing for heavy metal reduction.
Among European chemical conglomerates, Solvay and Seqens exemplify the integrated archetype with captive soda ash-bicarbonate chains. Tata Chemicals anchors South Asian supply through synthetic soda ash integration, while Church & Dwight occupies North American OTC channel positioning. Dr. Paul Lohmann GmbH KG represents the precision-grade specialist tier serving research laboratory and injectable formulation demand. These three archetypes reflect how purification technology access and regulatory certification breadth determine competitive positioning across hospital, pharmacy, and research end-use channels.
| Leading Market Players |
|---|
| Solvay |
| Tata Chemicals |
| Church & Dwight |
| Novacap |
| Seqens |
| CIECH Group |
| Dr. Paul Lohmann GmbH KG |
| Natural Soda |
| Jost Chemical Co. |
| Others |
Value Chain & Pricing Dynamics
Hospital formulary consolidation under India's Ayushman Bharat scheme is compressing procurement timelines and forcing API manufacturers toward multi-year supply guarantees, which elevates contract premiums for USP-NF certified volumes while squeezing spot-market liquidity for merchant grades.
Pricing Analysis
Natural gas price pass-through from the Solvay process anchors cost structures for synthetic soda ash-derived material, with European producers facing sharper volatility than Wyoming trona-based competitors. Three-tier pricing structure across premium, standard, and economy levels separates membrane-filtered sub-5 ppm heavy metal grades from conventional USP-NF compliant material and technical-grade feedstock. Cost compression in standard-tier tablet grades is intensifying because Indian domestic capacity expansion under PLI incentives is eroding import premiums. Hospital procurement committees demonstrate lowest price sensitivity due to formulary compliance requirements, while research laboratories command specification premiums with limited volume leverage.
Supply Chain Analysis
Pharmaceutical-grade sodium bicarbonate supply rests on synthetic soda ash capacity concentrated in Belgium, India, and China, with natural trona refining limited to Wyoming-based operations in the United States. Key inputs span ammonia brine feedstock, thermal energy for calcination, and stainless steel reactor infrastructure for cGMP surface finish compliance. Single-source vulnerability runs through European membrane filtration technology licensors who control sub-5 ppm heavy metal purification systems. Distribution runs through drum-format bulk supply to API manufacturers and bottle-configuration retail channels for pharmacy OTC sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
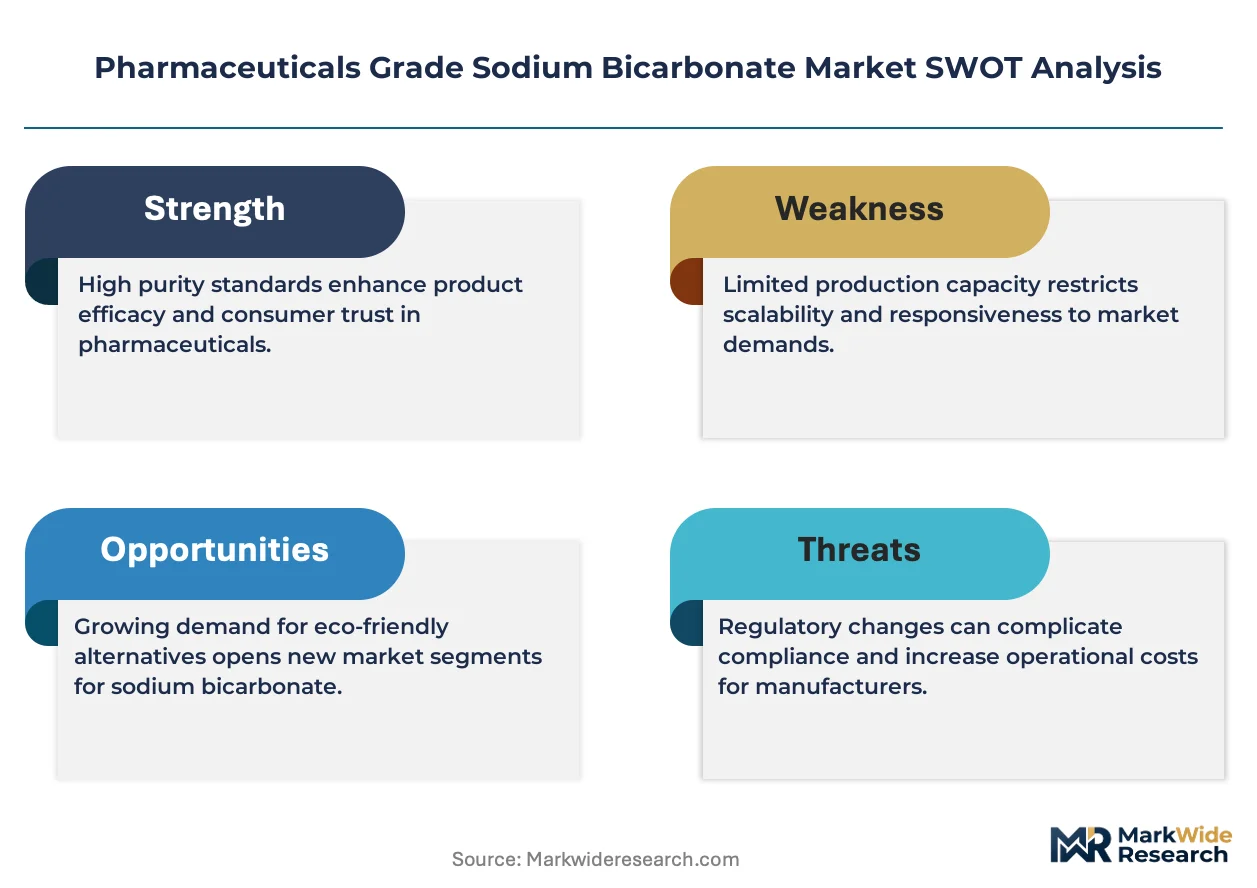
This market functions as a regulatory compounder where CDSCO's BIS certification mandate for imported excipients is accelerating domestic capacity investment and reshaping procurement economics for foreign suppliers.
For Market Incumbents: Deepen backward integration into synthetic soda ash to secure feedstock cost control against natural gas volatility, while expanding membrane filtration licensing to Indian joint venture partners to preempt local competitor scale-up. The priority lever centers on qualifying dual-source EP monograph certificates ahead of ECHA authorization delays.
For New Entrants and Emerging Players: The price-point gap between premium injectable-grade and economy tablet-grade material offers white-space entry for mid-tier powder specialists serving effervescent nutraceutical manufacturers. Target tier-2 Indian cities where pharmacy private-label expansion bypasses institutional tendering. Lead with CDSCO BIS certification speed as the go-to-market angle against import registration delays.
For Investors and Strategic Acquirers: Asymmetric upside sits with precision-grade specialists possessing membrane filtration assets and dual pharmacopeial certification breadth. Long-term viability hinges on 5-10 year contract structures with hospital networks rather than spot-market exposure. Watch for EMA-CDSCO pharmacopeial harmonization on heavy metal limits as the inflection signal for regional sourcing economics reversal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Soda Ash | Tata Chemicals and Solvay anchor cost leadership through captive feedstock control. |
| Membrane Filtration Technology Licensing | European licensors capture margin premiums from Indian PLI-subsidized capacity expansion. |
| Dual Pharmacopeial Certification Investment | Simultaneous USP-NF and EP compliance preempts supply interruption from authorization divergence. |
| Long-term Hospital Formulary Contracts | Ayushman Bharat procurement consolidation rewards multi-year supply guarantee providers. |
| CDSCO BIS Certification Acceleration | Domestic Indian producers capture import substitution margins from foreign registration delays. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pharmaceutical plant managers, CDSCO regulatory affairs leads, hospital formulary directors, and API procurement specialists with secondary validation from FDA cGMP inspection records, EMA EP monograph databases, CDSCO BIS certification registries, and Indian customs excipient import data. Bottom-up volume modeling triangulated against top-down soda ash capacity assessments.
Historical reference periods anchored the projection framework across the analysis window, with segmentation dimensions spanning grade tier (tablet/powder/granule/liquid), end-use channel (hospital/pharmacy/research laboratory/clinic), application function (antacid/acid neutralization/baking agent/chemical reagent), and regional production hub. CAGRs derived from regression analysis of procurement volume trends against PLI scheme disbursement schedules and hospital network expansion targets.
Caveats apply where natural gas price volatility, REACH authorization delays, or CDSCO regulatory enforcement shifts could materially shift the outlook. A small set of triggers—pharmacopeial heavy metal limit harmonization, membrane filtration technology licensing terms, and Indian domestic capacity commissioning schedules—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Ferrous Succinate Market
Pharmaceutical Ingredients
Global Chlorpheniramine Maleate Market
Pharmaceutical Ingredients
Acetaminophen API Market
Pharmaceutical Ingredients
Vitamins and Derivatives Market
Pharmaceutical Ingredients
Global Fibrate Drugs Market
Pharmaceutical Ingredients
Hyaluronic Acid Raw Material Market
Pharmaceutical Ingredients
Originator Small Molecule Drug Market
Pharmaceutical Ingredients
Nortriptyline Hydrochloride Market
Pharmaceutical Ingredients
Albumin (As Excipient) Market
Pharmaceutical Ingredients
Fosfomycin Trometamol Powder Market
Pharmaceutical Ingredients
Global Barbiturate Drugs Market
Pharmaceutical Ingredients
Small Molecule Drug Discovery Market
Pharmaceutical Ingredients
Pharmaceutical Suspension Market
Pharmaceutical Ingredients
Mrna Synthesis Raw Materials Market
Pharmaceutical Ingredients
Immunosuppressants Market
Pharmaceutical Ingredients
Diclofenac Sodium API Market