
 Albumin (As Excipient) Market | 2026-2036
Albumin (As Excipient) Market Size, Share, and Industry Trends Forecast 2026-2036
Albumin (As Excipient) Market Outlook
European plasma fractionation capacity is decoupling from traditional pharmaceutical excipient supply chains as specialized producers build dedicated albumin purification lines. CSL Behring leverages its vertically integrated plasma collection network across Germany and Switzerland to sustain cost advantages in human serum albumin production. Grifols S.A. anchors its position through large-scale fractionation infrastructure in Spain that supplies contract manufacturers across Southern Europe. Baxter International Inc. competes by controlling cold-chain logistics for temperature-sensitive albumin shipments to North American formulation sites.
Albumin as excipient denotes highly purified plasma-derived or recombinant protein used to stabilize therapeutic proteins, extend half-life, and reduce immunogenicity in parenteral formulations, typically meeting specifications of 96% purity or higher with endotoxin levels below established pharmacopeial thresholds. Human serum albumin dominates current supply volumes due to established fractionation infrastructure and regulatory familiarity, while recombinant albumin represents the fastest-expanding category as cell-culture expression systems achieve cost parity and eliminate viral safety concerns inherent to plasma sourcing. The injectable delivery mode occupies the largest share of formulation demand, though lyophilized presentations are gaining traction for biologics requiring extended shelf stability.
The FDA enforces Current Good Manufacturing Practice requirements for excipient qualification that directly shape supplier auditing burdens and documentation standards for albumin used in drug products. EMA's revised guideline on excipients in the context of the EU Medical Device Regulation creates additional compliance layers for albumin employed in combination products. The International Council for Harmonisation Q3D guideline on elemental impurities further constrains raw material sourcing specifications. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP monographs to anticipate qualification testing redundancies that could alter total cost of ownership for multi-regional product registrations.
Market Dynamics
Plasma fractionation capacity constraints are compressing supply elasticity for pharmaceutical-grade albumin as biopharmaceutical formulation complexity escalates. FDA's tightened excipient purity guidelines are forcing qualification protocol overhauls that favor suppliers with captive plasma collection networks.
Growth Catalysts
- EMA's revised excipient guideline under EU Medical Device Regulation:Combination product manufacturers must source higher-purity albumin grades, pulling premium supply toward European formulation houses.
- Cell-culture expression systems:Recombinant albumin production is eliminating viral clearance burdens and expanding contract manufacturing options for parenteral biologics.
- Lyophilized presentation demand:Biologics requiring extended shelf stability are driving excipient volumes toward freeze-dried formulations in North American and European markets.
Market Restraints
- Plasma collection concentration:Germany, Spain, and the United States control the majority of fractionation feedstock, creating geographic supply vulnerability.
- ICH Q3D elemental impurity thresholds:Raw material sourcing specifications now require expensive metal detection and removal infrastructure.
- Recombinant albumin cost structure:Mammalian cell-culture production remains capital-intensive versus established plasma fractionation economics.
Strategic Opportunities
- Indian biopharmaceutical contract manufacturing:CDSCO's expanding GMP inspection capacity is attracting formulation work that requires excipient localization.
- Single-use bioreactor convergence:Disposable manufacturing systems are reducing cross-contamination risks for recombinant albumin production campaigns.
- Japan's regenerative medicine pipeline:PMDA's accelerated approval pathways for cell therapies are creating novel stabilizer demand in the Asia-Pacific region.
Industry Challenges
- Pharmacopeial harmonization gaps:Divergent USP, EP, and JP monograph requirements force redundant qualification testing for multi-regional registrations.
- Cold-chain infrastructure capex:Temperature-sensitive albumin shipments require validated logistics investments that strain mid-tier distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Albumin (As Excipient) Market |
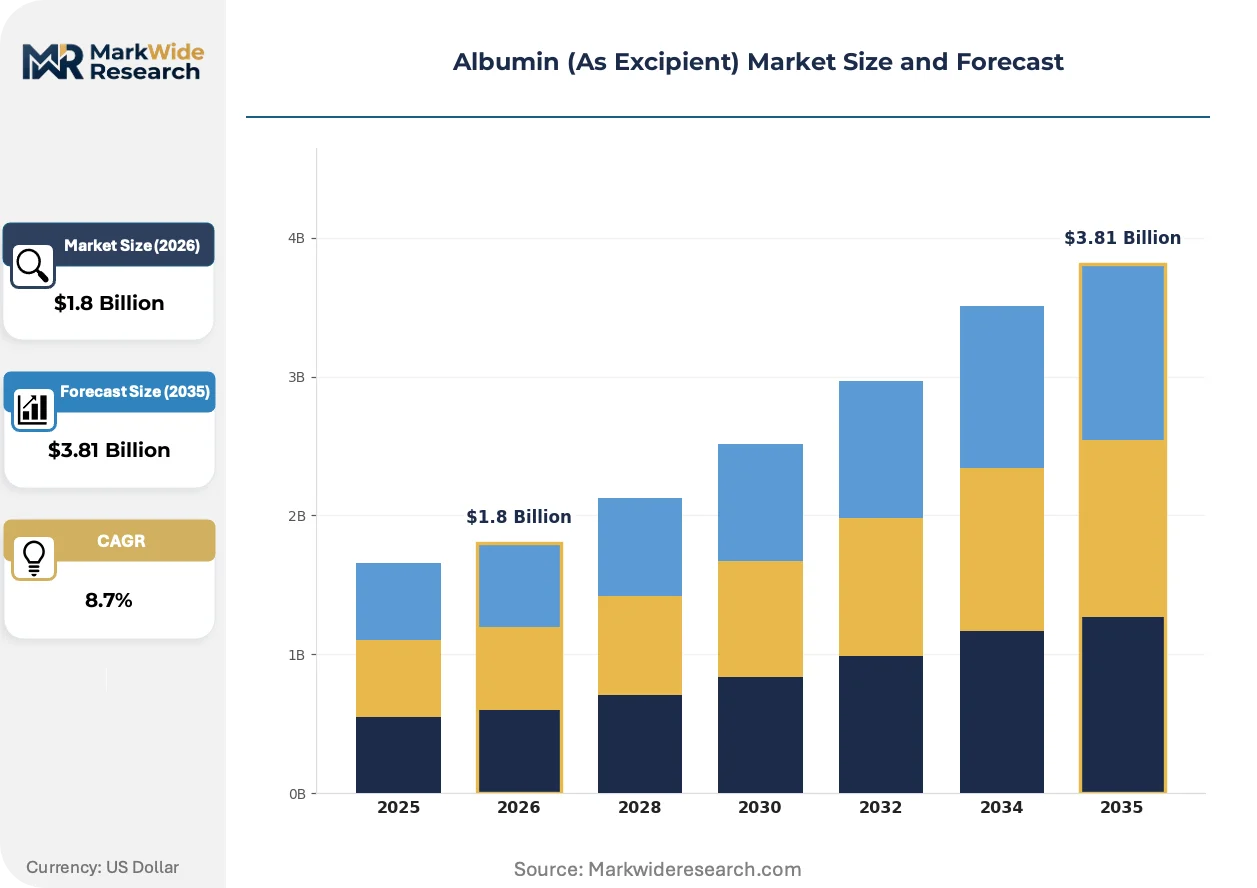
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Human Serum Albumin, Bovine Serum Albumin, Recombinant Albumin, Modified Albumin Delivery Mode: Injectable, Lyophilized, Oral, Intravenous Application: Biopharmaceuticals, Diagnostics, Drug Formulation, Therapeutics End User: Pharmaceutical Companies, Research Institutions, Contract Manufacturers, Healthcare Providers |
| Companies Covered | CSL Behring, Grifols S.A., Octapharma AG, Baxter International Inc., Merck KGaA, Takeda Pharmaceutical Company Limited, Biotest AG, InVitria Inc., Albumedix A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Albumin (As Excipient) Market Strategic Shifts
Biopharmaceutical manufacturing technology is compressing traditional excipient supply hierarchies through recombinant production advances and regulatory harmonization pressures. These shifts are redistributing competitive advantage toward suppliers with integrated quality systems.
Continuous processing technology for recombinant albumin is converging with single-use bioreactor platforms to enable flexible, small-batch production that matches personalized medicine scale requirements. Contract manufacturers in Switzerland and Singapore are adopting these integrated systems to serve orphan drug formulations. The technology is converging with quality-by-design protocols to reduce validation timelines for new excipient grades.
REACH authorization requirements for process chemicals used in plasma fractionation are forcing European suppliers to substitute legacy purification reagents. ECHA's 2024 updated guidance on substances of very high concern is extending compliance burdens to secondary suppliers of filter membranes and chromatography resins. German fractionators are responding by qualifying alternative solvent systems ahead of sunset date deadlines.
Formulation houses are consolidating excipient supplier panels to reduce audit burden and secure volume commitments. Large biopharmaceutical companies in the United States are executing multi-year supply agreements that lock in albumin purity specifications and freeze pricing. This concentration is most visible among parenteral protein manufacturers serving the oncology and immunology therapeutic areas.
Albumin (As Excipient) Market Segmentation
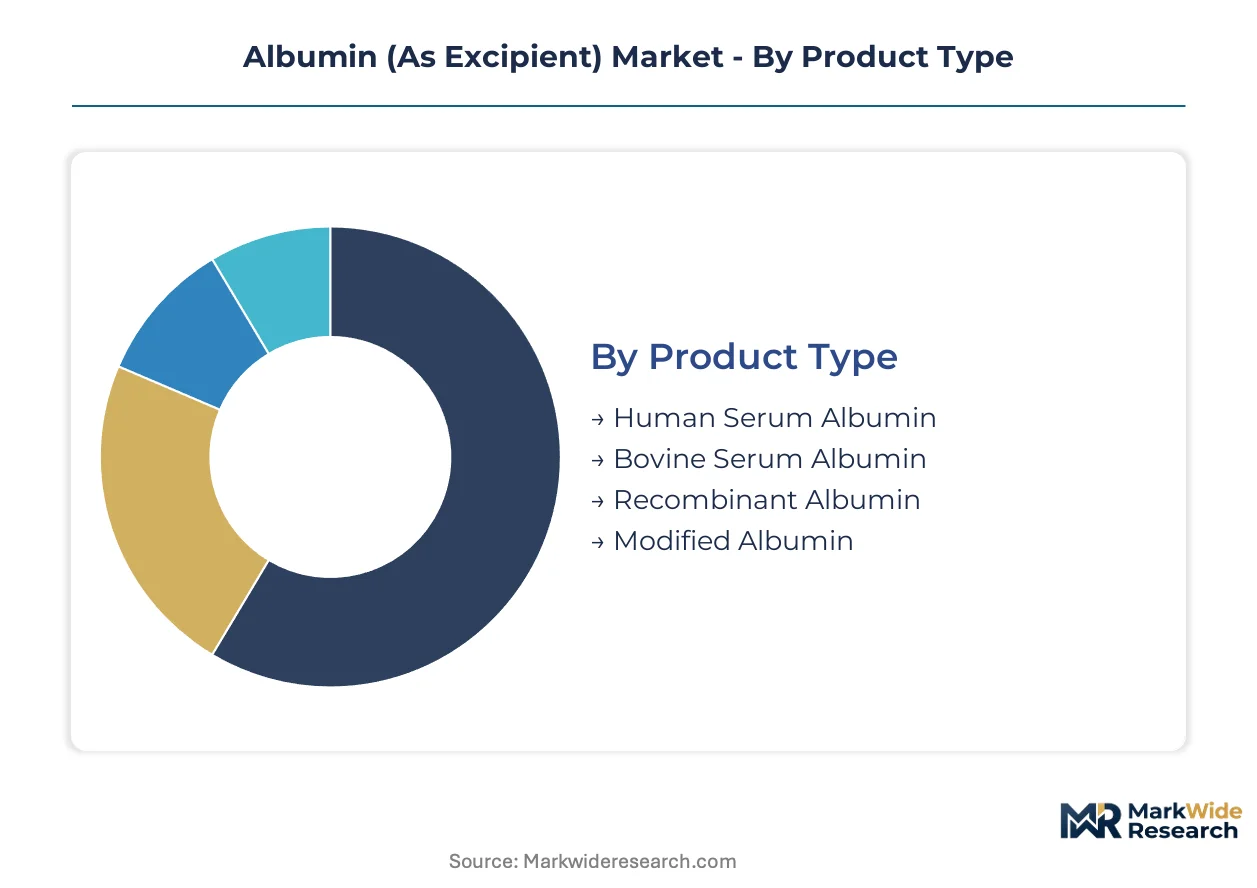
Excipient-grade albumin segmentation reflects divergent purification economics, regulatory qualification burdens, and formulation performance requirements. Manufacturers configure sourcing strategies across plasma-derived and recombinant categories based on viral safety tolerance, cost constraints, and therapeutic protein stability needs.
Product Type:
Customization intensity varies sharply across this spectrum, from commodity plasma fractions to engineered recombinant grades requiring cell-line development investment.
- Human Serum Albumin:Plasma-derived protein meeting 96% purity thresholds with established viral clearance documentation dominates current formulation volumes. German and Spanish fractionation facilities supply CSL Behring and Grifols captive networks serving European biopharmaceutical manufacturers facing EMA tightened excipient guidelines.
- Recombinant Albumin:Yeast or mammalian cell-culture expression eliminates plasma sourcing constraints and viral validation burdens. Singapore and Switzerland contract manufacturers adopt single-use bioreactor platforms to produce small-batch grades for orphan drug formulations under PMDA and FDA accelerated pathways.
- Bovine Serum Albumin:Animal-derived alternative with restricted pharmaceutical use due to TSE transmission concerns; diagnostic applications absorb residual demand.
- Modified Albumin:PEGylated or conjugated variants engineered for extended half-life stabilization in complex parenteral biologics.
Leading the category by volume: Human Serum Albumin. Growing fastest: Recombinant Albumin.
Delivery Mode:
Cost tier stratification separates cold-chain-dependent liquid formulations from capital-intensive lyophilized presentations requiring specialized excipient grades.
- Injectable:Liquid parenteral formulations demand endotoxin-controlled albumin with validated cold-chain logistics; Baxter International controls North American temperature-sensitive distribution infrastructure.
- Lyophilized:Freeze-dried presentations require ultra-low moisture albumin specifications for biologics with extended shelf stability mandates; oncology and immunology therapeutic areas drive specification tightening.
- Intravenous:Large-volume infusion applications utilize standard pharmacopeial grades with established USP-NF monograph compliance.
- Oral:Minimal excipient penetration due to albumin denaturation in gastrointestinal conditions; limited to specialized delivery research.
Highest volume concentration: Injectable. Steepest specification escalation: Lyophilized.
Application:
Application segmentation tracks margin differentiation between high-value biopharmaceutical stabilization and commoditized diagnostic binding functions.
- Biopharmaceuticals:Therapeutic protein stabilization, half-life extension, and immunogenicity reduction in monoclonal antibody and cell therapy formulations absorb premium excipient grades.
- Drug Formulation:Generic parenteral manufacturing utilizes standard pharmacopeial albumin with consolidated supplier panel arrangements locking multi-year purity specifications.
- Diagnostics:Immunoassay blocking and protein standard applications tolerate lower purity tiers with reduced regulatory documentation burdens.
- Therapeutics:Direct albumin infusion products for hypoproteinemia represent distinct regulatory category with separate fractionation allocation.
Revenue concentration centers: Biopharmaceuticals. Procurement standardization advancing: Drug Formulation.
End User:
Customer type segmentation reveals procurement capability gaps between integrated pharmaceutical manufacturers and outsourced formulation dependencies.
- Pharmaceutical Companies:Internal formulation groups at large biopharmaceutical firms execute direct supplier audits and multi-year excipient agreements with locked pricing structures.
- Contract Manufacturers:CDMOs serving mid-tier biotech sponsors face amplified qualification burdens from consolidated supplier panels and EMA EU MDR compliance layers.
- Research Institutions:Academic and preclinical facilities utilize non-GMP albumin grades with reduced documentation requirements for early-stage protein characterization.
- Healthcare Providers:Hospital pharmacy compounding absorbs minimal excipient volumes outside specialized infusion preparation settings.
Supply negotiation leverage concentrates: Pharmaceutical Companies. Fastest audit burden escalation: Contract Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plasma collection infrastructure anchors geographic supply patterns for pharmaceutical-grade albumin. Fractionation capacity concentrates in Germany, Spain, Switzerland, and the United States, with emerging production nodes in Singapore and Japan serving Asia-Pacific formulation demand.
Germany
CSL Behring operates vertically integrated plasma collection networks across Hesse and Bavaria, supplying European biopharmaceutical manufacturers with captive fractionation output. EMA's revised excipient guidelines under the EU Medical Device Regulation force higher-purity sourcing commitments from Frankfurt-area formulation houses. Marburg hosts one of Europe's largest dedicated albumin purification facilities serving contract manufacturers.
Spain
Grifols S.A. anchors Southern European supply through large-scale fractionation infrastructure in Barcelona and Madrid serving regional CDMOs. REACH authorization deadlines for legacy purification solvents are accelerating reagent substitution programs among Catalan producers. The Basque Country cluster specializes in diagnostic-grade albumin with reduced documentation burdens.
Switzerland
Swissmedic's stringent GMP enforcement attracts high-value recombinant albumin production for orphan drug formulations. Basel-based contract manufacturers adopt single-use bioreactor platforms to serve PMDA and FDA accelerated approval pathways. Zug concentrates headquarters operations for plasma-derived protein trading and quality certification.
United States
FDA's tightened excipient purity guidelines reshape supplier qualification protocols for North American parenteral biologics manufacturers. Baxter International controls cold-chain logistics infrastructure distributing temperature-sensitive shipments to formulation sites in Massachusetts and California. The Research Triangle Park cluster in North Carolina hosts specialized albumin stabilization research for monoclonal antibody applications.
Japan
PMDA's accelerated approval pathways for cell therapies generate novel stabilizer demand from Tokyo and Osaka formulation houses. Domestic plasma collection constraints force reliance on imported pharmaceutical-grade albumin for regenerative medicine applications. The Kansai region concentrates contract manufacturing organizations serving Asia-Pacific biologics sponsors.
Albumin (As Excipient) Market Competitive Environment
Global majors compete with regional champions across plasma fractionation capacity and recombinant production technology. Market structure tilts toward consolidated supply among vertically integrated plasma collectors, with emerging competition from cell-culture specialists. Three archetypes dominate: captive plasma fractionators with collection network control, recombinant protein specialists leveraging single-use platforms, and diversified life-science conglomerates with excipient distribution reach. Competitive moves concentrate on multi-year supply agreements locking purity specifications and geographic expansion of fractionation feedstock access.
Within the plasma-derived tier, CSL Behring and Grifols S.A. exemplify integrated collection-to-fractionation models. Baxter International occupies a position bridging cold-chain logistics control with excipient distribution reach. Among recombinant specialists, Albumedix A/S represents yeast-expression platforms eliminating viral clearance burdens for parenteral biologics manufacturers.
| Leading Market Players |
|---|
| CSL Behring |
| Grifols S.A. |
| Octapharma AG |
| Baxter International Inc. |
| Merck KGaA |
| Takeda Pharmaceutical Company Limited |
| Biotest AG |
| InVitria Inc. |
| Albumedix A/S |
| Others |
Value Chain & Pricing Dynamics
Cell-culture expression systems for recombinant albumin are compressing cost differentials between plasma-derived and engineered production methods while simultaneously redistributing supply concentration toward contract manufacturing nodes in Singapore and Switzerland. This technological transition enables smaller-batch, higher-purity output that commands premium positioning against legacy fractionation economics.
Pricing Analysis
Extended viral clearance documentation and cold-chain logistics warranties are bundled into pharmaceutical-grade contracts while research-grade albumin ships unbundled with minimal qualification support. Pricing stratifies across premium, standard, and economy tiers differentiated by endotoxin thresholds and pharmacopeial certification levels. Cost compression in the plasma-derived segment is intensifying because REACH authorization deadlines are forcing solvent substitution investments. Contract manufacturers exhibit the highest price sensitivity due to consolidated supplier panel pressures, while integrated biopharmaceutical companies lock multi-year agreements with frozen pricing structures.
Supply Chain Analysis
FDA and EMA qualification gating restricts approved supplier pools to fractionators with documented viral clearance and elemental impurity controls. Feedstock concentration centers on Germany, Spain, and the United States, with emerging recombinant capacity in Switzerland and Singapore. Production draws from human plasma collection networks, yeast expression cell banks, and chromatography resin purification systems. Single-source vulnerability runs through captive plasma collection networks controlled by vertically integrated majors. Distribution runs through validated cold-chain logistics partnerships serving parenteral formulation sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recombinant albumin production is displacing plasma-derived supply for parenteral biologics as cell-culture systems achieve cost parity and eliminate viral safety documentation burdens. Formulation houses are consolidating supplier panels around integrated quality systems that compress qualification timelines.
For Market Incumbents: Hedge plasma fractionation exposure by qualifying recombinant albumin supply agreements with Singapore and Switzerland contract manufacturers before cell-culture economics fully converge. Deepen upstream control over plasma collection networks in Germany and Spain to defend feedstock access against emerging recombinant competitors. Prioritize EMA EU MDR compliance investments to maintain European formulation house relationships. For New Entrants and Emerging Players: The gap between premium recombinant grades and economy plasma-derived tiers creates white-space for mid-purity albumin targeting diagnostic and research applications with reduced documentation requirements. Penetrate the Indian CDMO segment where CDSCO's expanding GMP inspection capacity is attracting formulation work requiring excipient localization. Deploy single-use bioreactor platforms to serve orphan drug sponsors under FDA and PMDA accelerated approval pathways. For Investors and Strategic Acquirers: Exit pathways concentrate in cell-culture specialists with validated yeast or mammalian expression systems and established pharmacopeial dossiers. Long-term viability favors recombinant production technology over plasma fractionation given regulatory trajectory toward viral safety elimination. Monitor ICH Q3D elemental impurity threshold enforcement as an inflection indicator for raw material sourcing cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Production Scale-Up | Yeast-expression platforms eliminate viral clearance burdens for parenteral biologics manufacturers. |
| Plasma Collection Network Expansion | CSL Behring and Grifols deepen captive feedstock control across German and Spanish territories. |
| EMA EU MDR Compliance Investment | Higher-purity sourcing commitments from Frankfurt-area formulation houses reshape supplier qualification. |
| Single-Use Bioreactor Adoption | Swiss and Singapore contract manufacturers enable flexible small-batch production for orphan drugs. |
| Multi-Year Supply Agreement Execution | Large US biopharmaceutical companies lock albumin purity specifications and freeze pricing structures. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with plasma fractionation executives, biopharmaceutical formulation scientists, CDMO procurement leads, and regulatory affairs specialists provided operational validation. FDA 483 observations, EMA inspection reports, USP monograph revisions, and plasma industry association statistics supplied quantitative benchmarks. Bottom-up volume modeling across product type, delivery mode, and application segments triangulated against top-down market sizing from fractionation capacity disclosures.
Granularity-level modeling tracked recombinant versus plasma-derived production economics, lyophilized versus liquid formulation requirements, and biopharmaceutical versus diagnostic application margins across the projection horizon. CAGRs were derived from segment-level volume trajectories and purity-grade pricing differentials. Forecast inputs incorporated REACH authorization timelines, ICH Q3D implementation schedules, and PMDA accelerated approval pathway expansion for cell therapies.
Underlying measurement precision varies by segment; recombinant albumin and lyophilized delivery modes carry tighter precision than plasma-derived and intravenous categories due to newer production data availability. Forecasts reflect assumptions regarding pharmacopeial harmonization progress and plasma collection volume stability. A model refresh is warranted upon material change in FDA excipient purity guideline enforcement intensity or ECHA REACH sunset date acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Lipids Active Pharmaceutical Ingredient Market
Pharmaceutical Ingredients
Global Tizanidine Market
Pharmaceutical Ingredients
Folinic Acid Market
Pharmaceutical Ingredients
Large Molecule Drug Substance CDMO Market
Pharmaceutical Ingredients
Global Barbiturate Drugs Market
Pharmaceutical Ingredients
Calcium Gluconate Market
Pharmaceutical Ingredients
Pemetrexed Market
Pharmaceutical Ingredients
Zinc Bacitracin Market
Pharmaceutical Ingredients
Piperacillin Sodium API Market
Pharmaceutical Ingredients
Kitasamycin Market
Pharmaceutical Ingredients
Ferrous Succinate Market
Pharmaceutical Ingredients
Asia-Pacific Pharmaceutical Glycerine Market
Pharmaceutical Ingredients
Calcium Folinate for Injection Market
Pharmaceutical Ingredients
Sennosides Market
Pharmaceutical Ingredients
Histamine H2-Receptor Antagonists Market
Pharmaceutical Ingredients
Cyclooxygenase 2 Inhibitor Market