
 Electrolyte Additives for Lithium Ion Battery Market | 2026-2036
Electrolyte Additives for Lithium Ion Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Electrolyte Additives for Lithium Ion Battery Market Insights
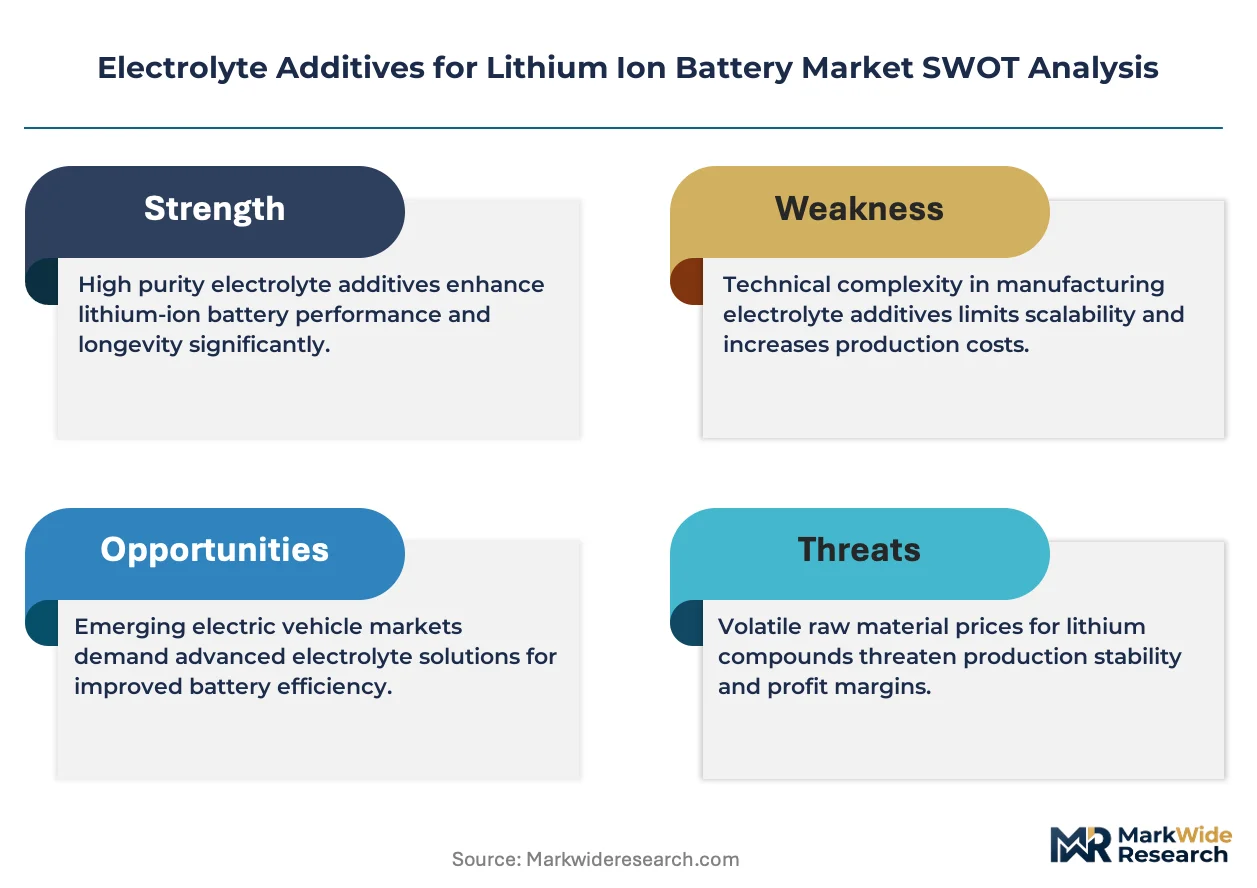
UN 38.3 lithium-ion battery transport certification is bifurcating the supplier base into qualified and non-qualified tiers. Nippon Shokubai leverages its integrated precursor synthesis to sustain premium positioning in vinylene carbonate derivatives. ENCHEM anchors its additive supply through captive electrolyte blending capacity in South Korea. Shenzhen Capchem competes on scale, operating multi-ton production lines serving domestic battery manufacturers.
Electrolyte additives for lithium ion batteries comprise organic compounds—typically carbonate-based film-forming agents, flame retardants, and wetting modifiers—dosed at 1-5 weight percent to stabilize solid-electrolyte interphase formation and extend cycle life above 1000 charge cycles. Their primary purpose is to suppress thermal runaway, reduce impedance growth, and enable high-voltage cathode operation in commercial cells. Additive Compounds command the deepest margin pools due to formulation complexity and patent-protected synthesis routes, while Electric Vehicles absorbs the dominant volume share as OEMs specify custom electrolyte packages. Solid-State Electrolytes in the Delivery Mode dimension represents the fastest-growing structural category, though Liquid Coatings retains manufacturing scale advantages through 2030.
FDA oversight of battery materials in medical devices, EPA hazard classification rules for fluorinated compounds, and China's MEE emissions standards for chemical manufacturing collectively tighten material disclosure and purity thresholds. REACH registration requirements in Europe further constrain which additive chemistries gain market access. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border supply chains.
Market Dynamics
High-voltage cathode chemistries above 4.4V are forcing additive formulators to redesign film-forming agents that prevent electrolyte oxidation without sacrificing ionic conductivity. This voltage escalation is compressing the performance window between off-the-shelf additives and custom-engineered solutions.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases is accelerating demand for non-fluorinated flame retardant additives in European battery gigafactories.
- Solid-state battery prototyping:Dry electrode coating processes require novel wetting modifiers compatible with sulfide and oxide ceramic electrolytes.
- South Korean cathode supply chains:Integrated precursor-to-cell manufacturing in Gwangju and Pohang clusters is creating captive demand for just-in-time additive delivery.
Market Restraints
- Fluoroethylene carbonate feedstock concentration:Three Chinese chemical conglomerates control over 80% of refined fluoroethylene carbonate precursor output, creating single-source vulnerability.
- REACH registration costs:Novel additive chemistries face EUR 200,000-500,000 registration fees plus 18-month evaluation timelines that freeze formulation innovation.
- Lithium hexafluorophosphate price volatility:The benchmark lithium salt's 300% price swing between 2021 and 2023 has compressed additive blending margins by forcing pass-through contracts.
Strategic Opportunities
- India PLI scheme:Cell manufacturing incentives are attracting electrolyte formulators to Gujarat and Tamil Nadu, creating first-mover advantage in an underdeveloped additives market.
- Silicon-anode compatibility:Pre-lithiation additives that stabilize solid-electrolyte interphase on expanding silicon particles represent unmet technical white space.
- Direct-to-gigafactory distribution:Bulk additive storage and on-site blending services bypass traditional electrolyte compounder intermediaries.
Industry Challenges
- Electrochemical modeling talent scarcity:Battery manufacturers are poaching additive R&D chemists with computational solid-state physics backgrounds, extending product development cycles.
- UN 38.3 certification backlog:Transport safety testing queues at accredited laboratories now exceed 14 weeks, delaying new additive package commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrolyte Additives for Lithium Ion Battery Market |
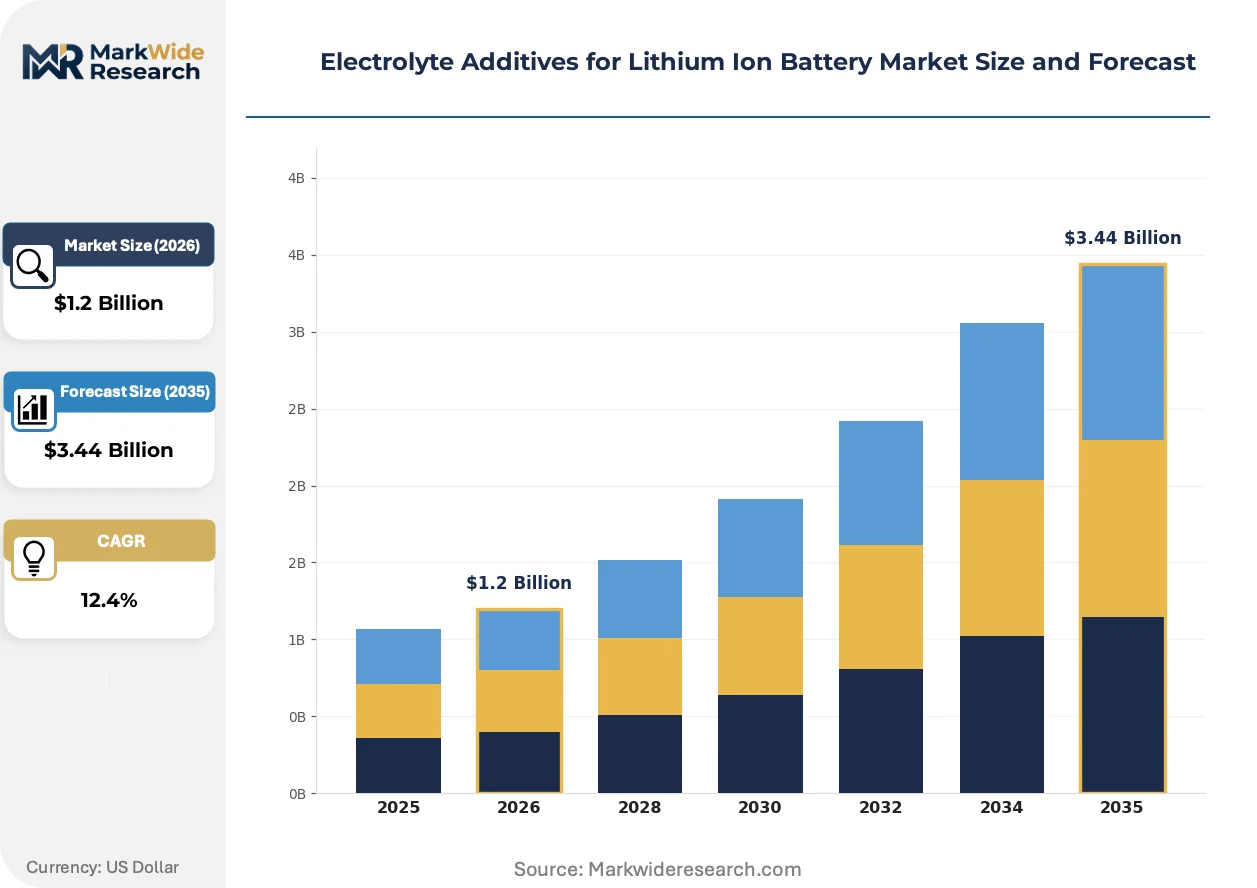
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $3.44 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conductive Salts, Solvents, Electrolyte Formulations, Additive Compounds Application: Electric Vehicles, Consumer Electronics, Energy Storage Systems, Industrial Applications Delivery Mode: Liquid Coatings, Solid-State Electrolytes, Gaseous Transitions, Hybrid Systems End User: OEMs, Battery Manufacturers, Research Institutions, End Consumers |
| Companies Covered | Nippon Shokubai, Fujian Chuangxin Science and Technology, Tinci Materials, Shida Shinghwa Advanced Material, Suzhou Cheerchem Advanced Material, Shenzhen Capchem, Shanghai Chemspec, ENCHEM, Chunbo Fine Chem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrolyte Additives for Lithium Ion Battery Market Trends and Innovations
Additive architectures are fragmenting into application-specific portfolios rather than universal performance packages. Formulators now engineer distinct chemistries for high-nickel cathodes versus silicon-anode systems rather than seeking compromise solutions.
Localized high-concentration electrolyte systems are miniaturizing the additive-to-salt ratio while maintaining interphase stability. These formulations reduce total additive loading from 5 weight percent to 2-3 percent without sacrificing cycle life. Cell manufacturers in Japan and South Korea are qualifying these lean designs for next-generation 4680 cylindrical formats. The technology is miniaturizing additive volume requirements per kilowatt-hour of battery capacity.
China's GB 38031-2020 battery safety standard mandates nail penetration and overcharge tests that exceed UN 38.3 baselines. Domestic cell producers are specifying additive packages with dual-function film-forming and flame-retardant properties to guarantee compliance. This regulatory layering is bifurcating the supplier base into China-certified and export-only tiers.
Cell manufacturers are consolidating their electrolyte supply base from six to two qualified vendors per gigafactory to simplify accountability. This concentration is displacing spot-market additive purchases with multi-year offtake agreements indexed to lithium carbonate prices. The shift is most pronounced in European battery plants where OEMs demand single-source traceability for carbon accounting disclosures.
Electrolyte Additives for Lithium Ion Battery Market Segmentation
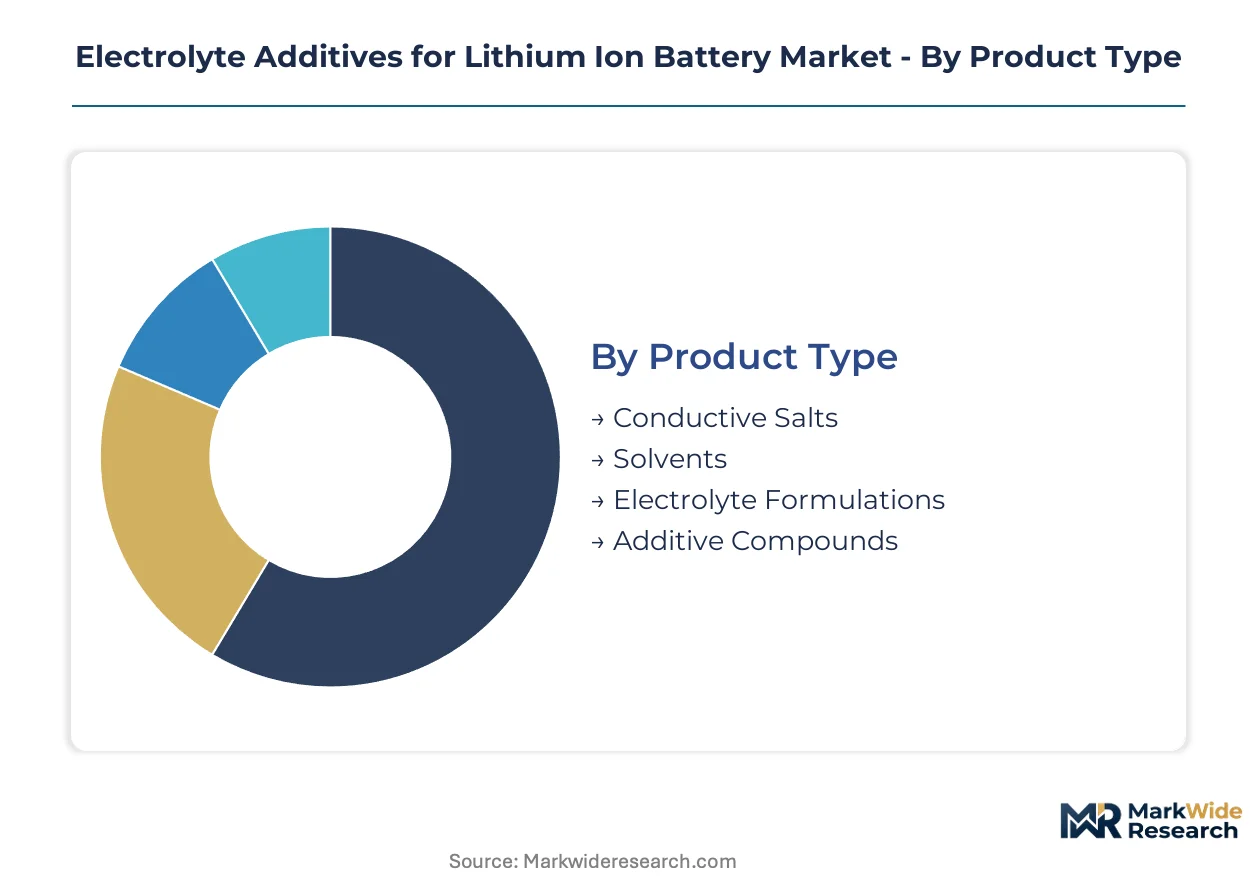
Additive procurement patterns diverge sharply across cell formats and cathode chemistries. Formulators must align product architectures with distinct voltage windows, thermal management requirements, and certification standards governing each segment.
Product Type:
Domestic production concentrates on commodity solvents and conductive salts, while additive compounds remain import-dependent for most non-Chinese cell manufacturers.
- Additive Compounds:Patent-protected film-forming agents and flame retardants synthesized through multi-step organic routes. South Korean cathode producers specify these packages for high-nickel cells bound for European OEMs facing F-Gas Regulation compliance.
- Electrolyte Formulations:Pre-blended salt-solvent-additive mixtures qualified to specific cell designs. Chinese battery manufacturers source these domestically under GB 38031-2020 safety mandates that diverge from UN 38.3 export requirements.
- Conductive Salts:Lithium hexafluorophosphate and lithium bis(fluorosulfonyl)imide supply the ionic conductivity baseline.
- Solvents:Ethylene carbonate and dimethyl carbonate carriers form the formulation bulk.
Additive Compounds commands the established base. The steepest expansion runs through Electrolyte Formulations.
Application:
Volume concentration follows cathode procurement geography, with electric vehicle demand clustering near integrated precursor-to-cell corridors.
- Electric Vehicles:OEM-specified custom packages for 4680 cylindrical and prismatic formats. Japanese and South Korean cell plants qualify lean 2-3 weight percent additive loadings to maximize energy density.
- Energy Storage Systems:Long-cycle-life formulations prioritizing calendar aging stability over power density. Installations in India under the PLI scheme are creating captive demand for phosphate-iron-lithium compatible additives.
- Consumer Electronics:Compact cell formats requiring low-viscosity wetting modifiers.
- Industrial Applications:Heavy-duty cycle formulations for material handling and grid backup.
Electric Vehicles anchors procurement volume. Energy Storage Systems is climbing the fastest as grid-scale deployments accelerate.
Delivery Mode:
Manufacturing scale advantages currently favor liquid systems, though solid-state prototyping is redirecting R&D investment toward ceramic-compatible architectures.
- Liquid Coatings:Established wet-blending infrastructure serving cylindrical and pouch cell lines. South Korean electrolyte compounders operate multi-ton batch reactors feeding Gwangju and Pohang manufacturing clusters.
- Solid-State Electrolytes:Sulfide and oxide ceramic systems requiring novel wetting modifiers for dry electrode processes. Japanese cell manufacturers are qualifying these for next-generation formats.
- Hybrid Systems:Gel polymer intermediates bridging liquid and solid architectures.
- Gaseous Transitions:Vapor-phase deposition routes for thin-film solid-state cells.
Liquid Coatings retains manufacturing dominance. Solid-State Electrolytes shows the steepest trajectory as prototyping scales toward commercial qualification.
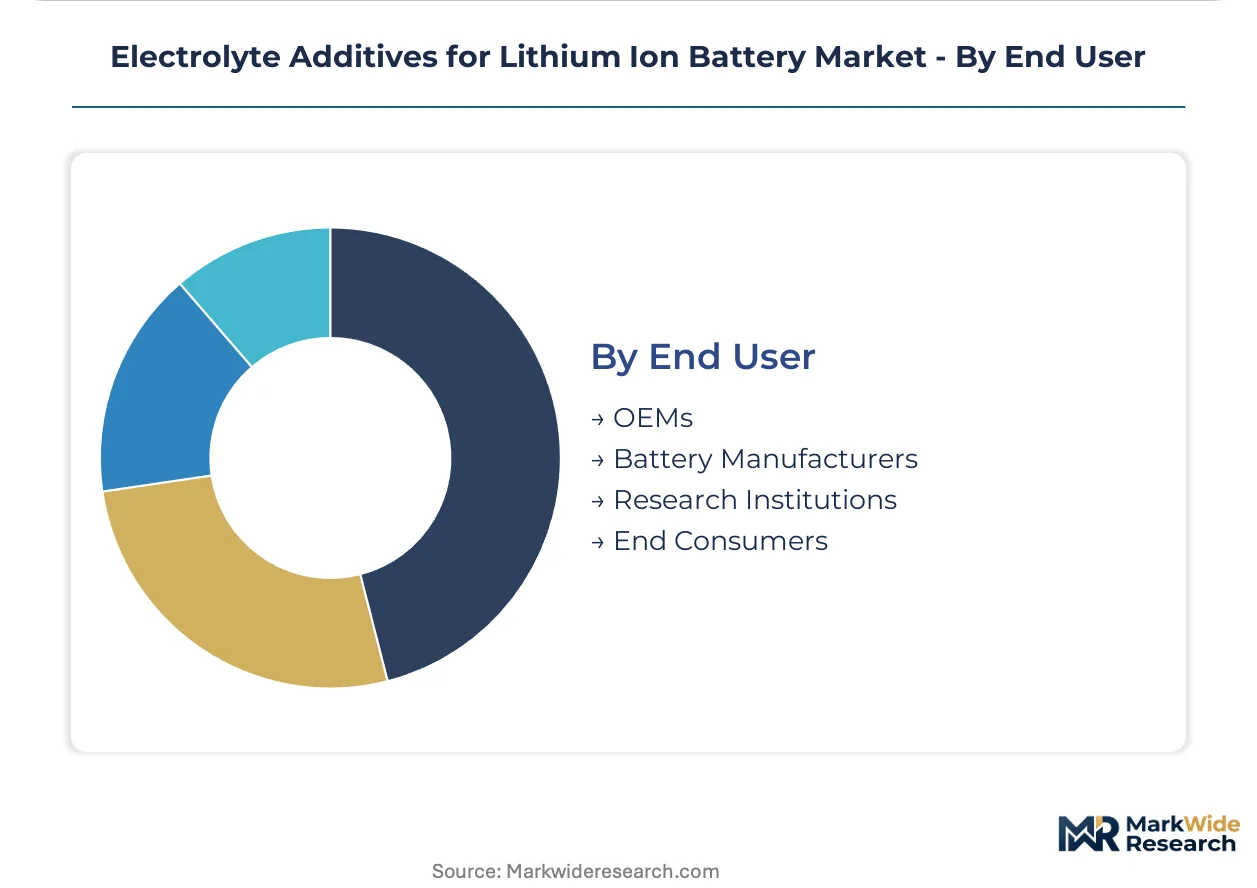
End User:
Procurement accountability is consolidating toward battery manufacturers as OEMs reduce qualified vendor counts per gigafactory.
- Battery Manufacturers:Direct additive specification for in-house electrolyte blending. European plants are mandating single-source traceability to satisfy carbon accounting disclosures.
- OEMs:Custom package design for captive cell production. Automotive manufacturers in Germany and South Korea are recruiting electrochemical modeling talent to internalize formulation decisions.
- Research Institutions:Small-batch qualification samples for next-chemistry screening.
- End Consumers:Replacement electrolyte for aftermarket repair segments.
Battery Manufacturers control procurement flow. OEMs are gaining specification influence fastest as vertical integration into cell production advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Battery cell manufacturers in China, South Korea, and Japan command the dominant procurement volumes, with European and North American markets expanding electrolyte additive demand through localized gigafactory buildouts. OEM specification power is shifting toward integrated precursor-to-cell corridors.
China
Domestic cell producers drive additive demand through GB 38031-2020 safety mandates that exceed UN 38.3 baselines. MEE emissions standards tighten purity thresholds for fluorinated compound manufacturing. The Yangtze River Delta cluster around Shanghai and Suzhou concentrates multi-ton production lines serving CATL and BYD supply chains.
South Korea
Integrated cathode-to-cell manufacturing in Gwangju and Pohang creates captive demand for just-in-time additive delivery. MFDS chemical registration requirements align with REACH-equivalent disclosure standards. ENCHEM anchors regional supply through captive electrolyte blending capacity feeding LG Energy Solution and Samsung SDI facilities.
Japan
Automotive OEMs internalize formulation decisions through recruited electrochemical modeling talent. METI battery technology roadmaps prioritize solid-state prototyping requiring novel wetting modifiers. Kanto and Kansai manufacturing belts host Nippon Shokubai's integrated precursor synthesis for vinylene carbonate derivatives.
Germany
European OEMs mandate single-source traceability for carbon accounting disclosures in cell supply agreements. EU F-Gas Regulation phases down fluorinated greenhouse gases, accelerating non-fluorinated flame retardant qualification. The North Rhine-Westphalia and Bavaria industrial corridors attract electrolyte formulators serving Tesla and Volkswagen gigafactories.
United States
IRA production tax credits incentivize domestic cell manufacturing, drawing additive suppliers to co-locate with emerging gigafactories. EPA hazard classification rules for fluorinated compounds constrain import chemistry options. The Midwest manufacturing belt around Michigan and Ohio concentrates qualification activity for 4680 cylindrical formats.
Electrolyte Additives for Lithium Ion Battery Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates and specialized electrolyte compounders rather than diversified materials giants. The supplier base bifurcates between UN 38.3-certified qualified tiers and export-constrained domestic players. Three strategic archetypes dominate: integrated precursor producers with patent-protected synthesis routes, captive electrolyte blenders with just-in-time delivery infrastructure, and scale-driven commodity manufacturers serving price-sensitive procurement. Competitive moves concentrate on backward integration into lithium salt supply and geographic co-location with cathode production clusters.
Within the integrated precursor tier, Nippon Shokubai occupies a position exemplifying premium additive positioning through synthesis control. Shenzhen Capchem and ENCHEM represent contrasting scale and integration archetypes, with the former anchoring multi-ton domestic production and the latter sitting within South Korea's captive blending ecosystem. Fujian Chuangxin Science and Technology and Tinci Materials exemplify Chinese chemical specialists navigating GB standard compliance for internal market supply.
| Leading Market Players |
|---|
| Nippon Shokubai |
| Fujian Chuangxin Science and Technology |
| Tinci Materials |
| Shida Shinghwa Advanced Material |
| Suzhou Cheerchem Advanced Material |
| Shenzhen Capchem |
| Shanghai Chemspec |
| ENCHEM |
| Chunbo Fine Chem |
| Others |
Pricing and Supply Chain Analysis
Multi-ton batch reactor utilization rates in South Korean electrolyte compounding facilities anchor regional cost structures and compress price floors for additive packages serving Gwangju and Pohang manufacturing clusters. This scale concentration simultaneously elevates barriers for non-integrated formulators while forcing lithium carbonate-indexed contract terms across procurement tiers.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate procurement relationships between additive suppliers and European battery gigafactories. Pricing stratifies across UN 38.3-certified premium tiers, GB 38031-2020-compliant domestic tiers, and non-certified commodity tiers based on transport certification status and cathode compatibility depth. Cost compression in standard-grade film-forming agents is intensifying because fluoroethylene carbonate feedstock volatility forces pass-through adjustments. Energy storage system integrators exhibit the highest price sensitivity due to thin project margins, while automotive OEMs tolerate premium positioning for custom high-voltage packages.
Supply Chain Analysis
Just-in-time additive delivery preferences prevail among South Korean cathode-to-cell integrated manufacturers, while Chinese producers maintain strategic stockpiles against fluoroethylene carbonate supply disruptions. Raw material flows draw from Chinese fluoroethylene carbonate refiners, Japanese vinylene carbonate precursor synthesis, and South Korean captive electrolyte blending capacity. Single-source vulnerability in fluorinated compound feedstocks creates structural exposure to MEE emissions enforcement actions. Distribution runs through electrolyte compounder intermediaries in liquid coating systems, with direct-to-gigafactory bulk storage emerging for qualified additive packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state battery prototyping represents a technological inflection accelerating demand for ceramic-compatible wetting modifiers, while EU F-Gas Regulation phases down fluorinated flame retardants and reshapes formulation investment priorities across the analysis window.
For Market Incumbents: Consolidate backward integration into lithium hexafluorophosphate supply to offset salt price volatility compressing blending margins. Deepen captive electrolyte capacity in South Korean and German manufacturing corridors to defend against direct-to-gigafactory distribution models displacing traditional compounder intermediaries. Prioritize UN 38.3 certification maintenance as transport testing backlogs extend commercialization timelines for non-qualified competitors. For New Entrants and Emerging Players: Lead with silicon-anode pre-lithiation additive development as unmet technical white space with limited incumbent patent coverage. Target India's PLI scheme corridors in Gujarat and Tamil Nadu as underdeveloped electrolyte markets lacking qualified domestic supply. Pursue direct bulk storage partnerships with emerging gigafactories to bypass established electrolyte compounder channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated precursor producers with patent-protected synthesis routes over pure-play formulators facing feedstock volatility. Long-term viability rests on qualification timelines for solid-state ceramic-compatible architectures. The signal to watch is dry electrode coating process adoption rates at Japanese and South Korean prototyping facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Salt Supply | Captive lithium hexafluorophosphate production insulates margins from benchmark price volatility. |
| Direct-to-Gigafactory Bulk Storage Partnership | On-site additive blending services bypass electrolyte compounder intermediaries in European battery corridors. |
| Non-Fluorinated Flame Retardant Qualification | EU F-Gas Regulation compliance unlocks procurement access at German and Swedish gigafactories. |
| Solid-State Wetting Modifier Development | Sulfide and oxide ceramic compatibility addresses dry electrode coating requirements in Japanese prototyping. |
| India PLI Scheme Manufacturing Footprint | Gujarat and Tamil Nadu cell incentives create first-mover advantage in underdeveloped additive markets. |
Research Methodology
Initial hypotheses were tested against primary input from electrolyte R&D directors, cathode procurement managers at battery manufacturers, UN 38.3 certification laboratory technicians, and fluorinated compound plant engineers, then refined through secondary validation. Bottom-up and top-down triangulation drew from customs trade data for carbonate solvent flows, SEC filings of listed chemical conglomerates, MEE emissions disclosure records, and REACH registration databases. Primary fieldwork concentrated on additive specification decisions at integrated precursor-to-cell facilities in China, South Korea, and Japan.
Variance decomposition across product type, application, delivery mode, and end-user dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by cathode chemistry adoption curves and gigafactory commissioning schedules. Modeled inputs incorporated lithium carbonate price correlation coefficients, solid-state battery prototype qualification timelines, and F-Gas Regulation phase-down compliance deadlines.
The analysis sits within stated boundaries; outcomes outside sustained electric vehicle production scaling or abrupt fluorinated compound regulatory bans would require recalibration. Forecasts assume continued lithium-ion dominance in automotive applications and stable REACH registration cost structures for novel chemistries. Revision becomes warranted when solid-state battery commercialization timelines accelerate beyond current prototyping phases.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Binding Agents Market
Additives
Global Calcium Formate Market
Additives
Dipotassium Guanylate Market
Additives
Octane Improver Fuel Additives Market
Additives
Paint Additives Market
Additives
Europe UV Stabilizers Market
Additives
Ultraviolet Light Stabilizer Market
Additives
Citrate Ester Market
Additives
Diamino Stilbene Disulfonic Acid (DASDA) Market
Additives
Crystal Growth Modifier Market
Additives
Zinc Dialkyldithiophosphates Additive Market
Additives
Potassium Nitrate Market
Additives
Global UV Stabilizers Market
Additives
North America Phosphate Esters Market
Additives
Encapsulated Citric Acid Market
Additives
Sodium Citrate Dihydrate Market