
 Calcium Gluconate Market | 2026-2036
Calcium Gluconate Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Gluconate Market Intelligence
The shift toward non-GMO and alternative starch sources for glucose fermentation is consolidating supply chains around specific agricultural inputs. Jungbunzlauer Suisse AG leverages its extensive fermentation capabilities to maintain a strong market position. Meanwhile, Global Calcium Private Limited specializes in the production of various mineral salts, including high-purity calcium gluconate for pharmaceutical use. Fresenius Kabi dominates the injectable-grade segment, focusing on finished pharmaceutical formulations for hospital settings.
Calcium gluconate is the calcium salt of gluconic acid, produced commercially through the fermentation of glucose or via electrochemical oxidation. It functions as a highly bioavailable source of calcium for therapeutic use and as a sequestrant and firming agent in food processing. The injectable product type commands a premium due to stringent purity and sterility requirements for applications in hospitals. In contrast, oral tablets and powders drive market volume, primarily for dietary supplementation and over-the-counter sales through pharmacies.
Regulatory frameworks from the US FDA, the European Medicines Agency (EMA), and China's NMPA dictate quality standards for pharmaceutical-grade material. These regulations, along with food additive rules from bodies like the EFSA and Japan's PMDA, create significant barriers to entry and define product specifications. Future competitive advantage will depend on navigating these diverse international standards while managing production costs for different grades.
Market Dynamics
The market's central dynamic is the conflict between rising global purity mandates for pharmaceuticals, led by the FDA and EMA, and the commodity-driven economics of its agricultural glucose feedstock, which is sourced via fermentation. This tension defines investment in both process technology and supply chain control.
Growth Catalysts
- Fortification Mandates:Policies in developing nations requiring calcium in staple foods like flour expand baseline demand for food-grade material.
- Pharmaceutical Use:The critical role of injectable calcium gluconate in treating acute hypocalcemia ensures stable demand from hospitals.
- Non-GMO Sourcing:Consumer demand for non-GMO products is creating new supply chains around alternative feedstocks like tapioca for glucose fermentation.
Market Restraints
- Input Cost Volatility:Glucose prices, tied to corn and other agricultural commodity markets, introduce significant cost instability into production.
- Regulatory Burden:Securing and maintaining pharmaceutical-grade certification from agencies like the EMA and FDA is a costly, multi-year process.
- Substitution Risk:In food applications, lower-cost salts like calcium carbonate can substitute for calcium gluconate, limiting its price ceiling.
Strategic Opportunities
- Animal Nutrition:Formulating high-bioavailability calcium gluconate into specialized feeds for poultry and swine represents a significant growth vector.
- Geographic Expansion:Dietary supplement markets in Southeast Asia and Latin America remain underpenetrated, offering new channels for oral-grade products.
- Process Innovation:Developing novel fermentation strains or electrochemical processes could drastically lower production costs and environmental footprint.
Industry Challenges
- Harmonization Gaps:Divergent purity and testing standards between the US Pharmacopeia, European Pharmacopoeia, and China's NMPA complicate global export strategies.
- Sterile Manufacturing:Building and operating aseptic production lines for injectable-grade material requires substantial capital investment and specialized expertise.
- Supply Chain Traceability:Documenting and verifying non-GMO status from the farm-level feedstock through the entire production process is operationally complex.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Gluconate Market |
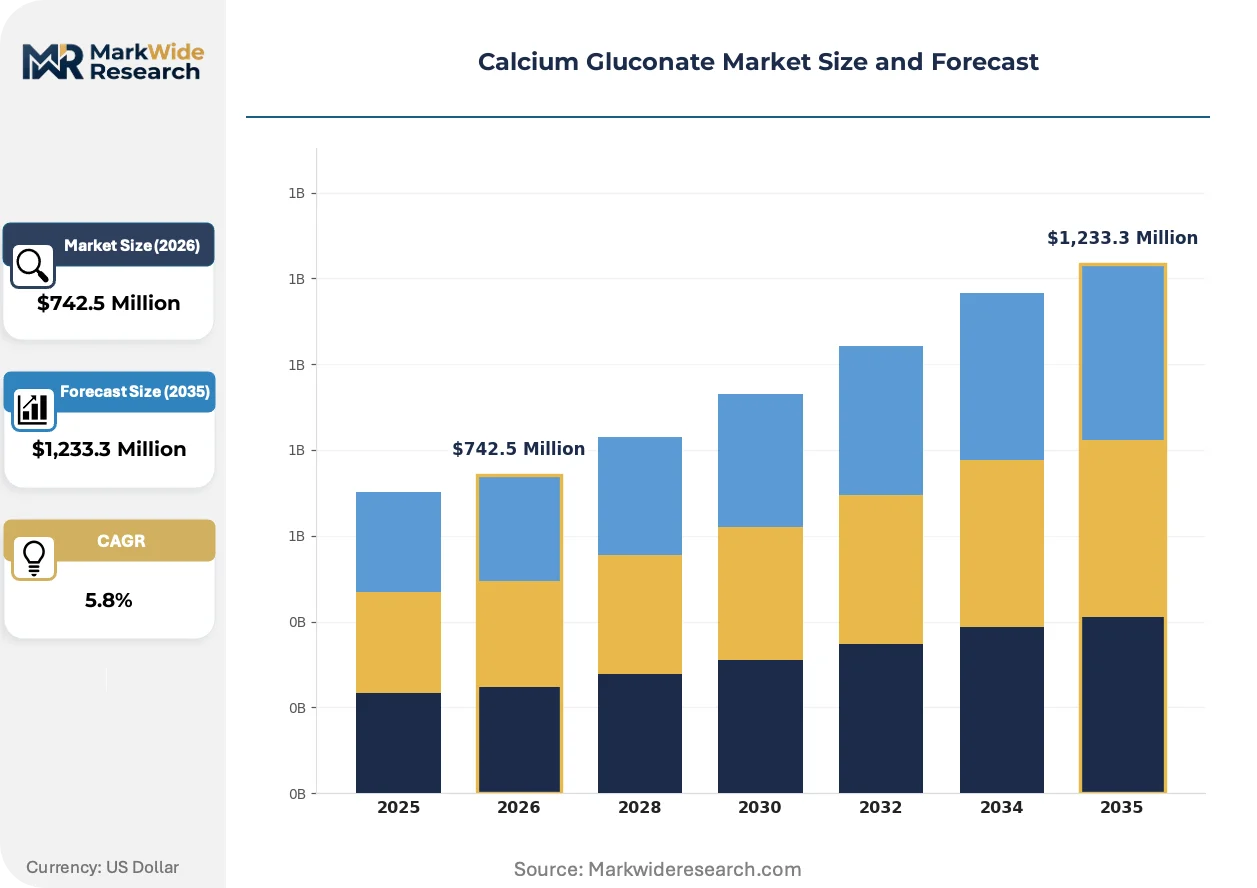
| Market Size in 2026 | $742.5 Million |
| Market Size in 2035 | $1,233.3 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Oral Tablets, Oral Powder, IV Solution Therapy Area: Cardiovascular, Orthopedic, Neurological, Dietary Supplementation End User: Hospitals, Clinics, Pharmacies, Homecare Distribution Channel: Direct Sales, Wholesalers, Online Retail, Drugstore |
| Companies Covered | Jungbunzlauer Suisse AG, Corbion N.V., BASF SE, Pfizer Inc., Spectrum Chemical Manufacturing Corp., Global Calcium Private Limited, Fresenius Kabi, Baxter International, Koninklijke DSM N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Gluconate Market Strategic Shifts & Innovations
Market evolution is shaped by the parallel pursuits of ultimate purity for medical use and cost efficiency in raw material conversion. Process innovations in fermentation and purification are central to navigating this dual pressure from global food and drug regulators.
Advanced membrane filtration and chromatography define the leading edge of purification technology. Pharmaceutical manufacturers of injectable-grade products are rapidly adopting these systems to meet exacting sterility requirements. This technology is integrating higher purity specifications directly into the production workflow, compressing validation timelines and reducing dependence on post-processing.
Europe's European Food Safety Authority (EFSA) enforces strict criteria on nutrient sources in food additives. This policy compels manufacturers to submit extensive bioavailability and safety data, creating a high barrier for new market entrants. The food processing segment is most affected, increasingly sourcing from suppliers with established EFSA-approved dossiers to mitigate compliance risk.
A definitive shift toward 'clean label' ingredients is altering sourcing behavior for food and supplement brands. This disrupts procurement from conventional corn-based glucose streams, creating preference for suppliers using non-GMO starches like tapioca or potato. The trend is most pronounced in the North American and European organic food and nutraceutical sectors.
Calcium Gluconate Market Segmentation
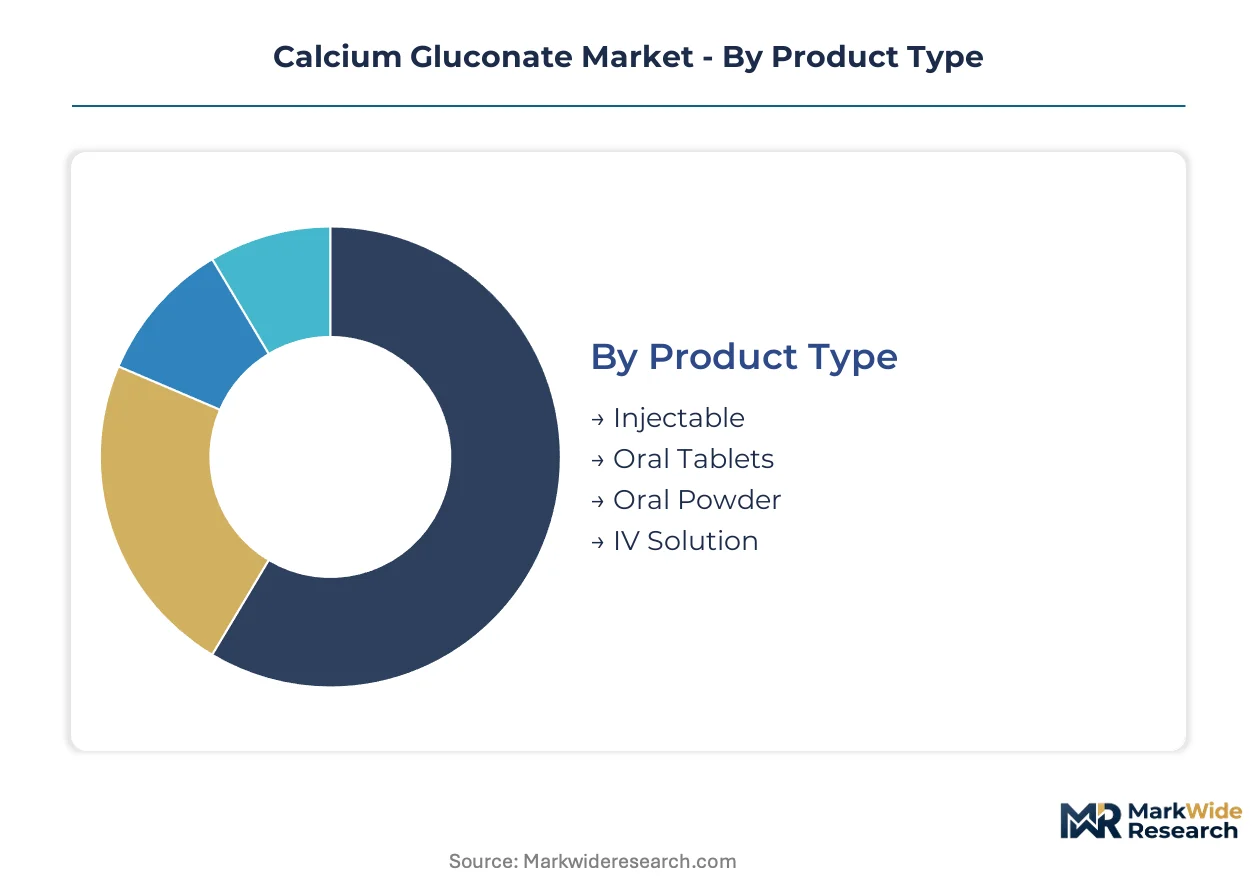
The Calcium Gluconate market segmentation provides a granular view of product forms, therapeutic applications, end-use environments, and distribution methods. Understanding these distinctions helps stakeholders identify specific demand pockets and tailor product development and market entry strategies.
Product Type:
The product type segmentation highlights how different formulations of calcium gluconate are either replacing older treatment methods or upgrading existing delivery systems.
- Injectable:This form provides a sterile, high-purity solution for rapid intravenous administration, critical for treating acute hypocalcemia and magnesium toxicity in hospital settings. Stringent regulatory standards from the US FDA and Europe's EMA govern its production and approval.
- Oral Tablets:These solid dosage forms offer convenient administration for chronic calcium supplementation and dietary fortification, primarily targeting consumers through pharmacies and over-the-counter sales channels. Manufacturers often focus on high bioavailability for these products.
- Oral Powder:This versatile form allows for flexible dosing, often used in pediatric or geriatric populations where swallowing tablets is difficult.
- IV Solution:Pre-mixed intravenous solutions facilitate direct administration in clinical environments, reducing preparation time and minimizing contamination risks.
Oral Tablets sits at the top of the volume ranking, with Injectable climbing the fastest.
Therapy Area:
Therapy area delineation captures the diverse medical and nutritional applications driving calcium gluconate demand across patient populations.
- Dietary Supplementation:This segment involves the use of calcium gluconate for general health, bone density maintenance, and calcium deficiency prevention in the broader consumer market. Demand is strong in North America and Western Europe due to health awareness.
- Orthopedic:Calcium gluconate supports bone formation and healing processes, finding application in the management of osteoporosis, fractures, and other musculoskeletal conditions. Hospitals and specialized clinics drive this demand.
- Cardiovascular:Used to manage electrolyte imbalances, calcium gluconate supports cardiac function in specific cardiovascular conditions.
- Neurological:This application involves calcium gluconate's role in nerve impulse transmission and muscle contraction, relevant for certain neurological disorders.
Dietary Supplementation accounts for the largest share of market consumption, while Orthopedic applications show robust expansion.
End User:
End user segmentation reflects the distinct procurement channels and patient care settings for calcium gluconate products.
- Hospitals:These institutions are primary consumers of injectable and IV solution forms for acute care, emergency medicine, and critical patient management. Procurement often involves large-volume contracts with pharmaceutical suppliers like Fresenius Kabi.
- Pharmacies:Pharmacies serve as key retail points for oral tablets and powders, catering to individual consumers seeking dietary supplements and over-the-counter calcium products. This channel is critical for market volume.
- Clinics:Outpatient clinics and specialized medical practices utilize calcium gluconate for specific patient treatments and minor procedures.
- Homecare:This segment includes patients who self-administer calcium gluconate, often for long-term dietary support or chronic condition management.
Hospitals represent a high-value segment due to specialized product requirements, whereas Pharmacies command significant volume.
Distribution Channel:
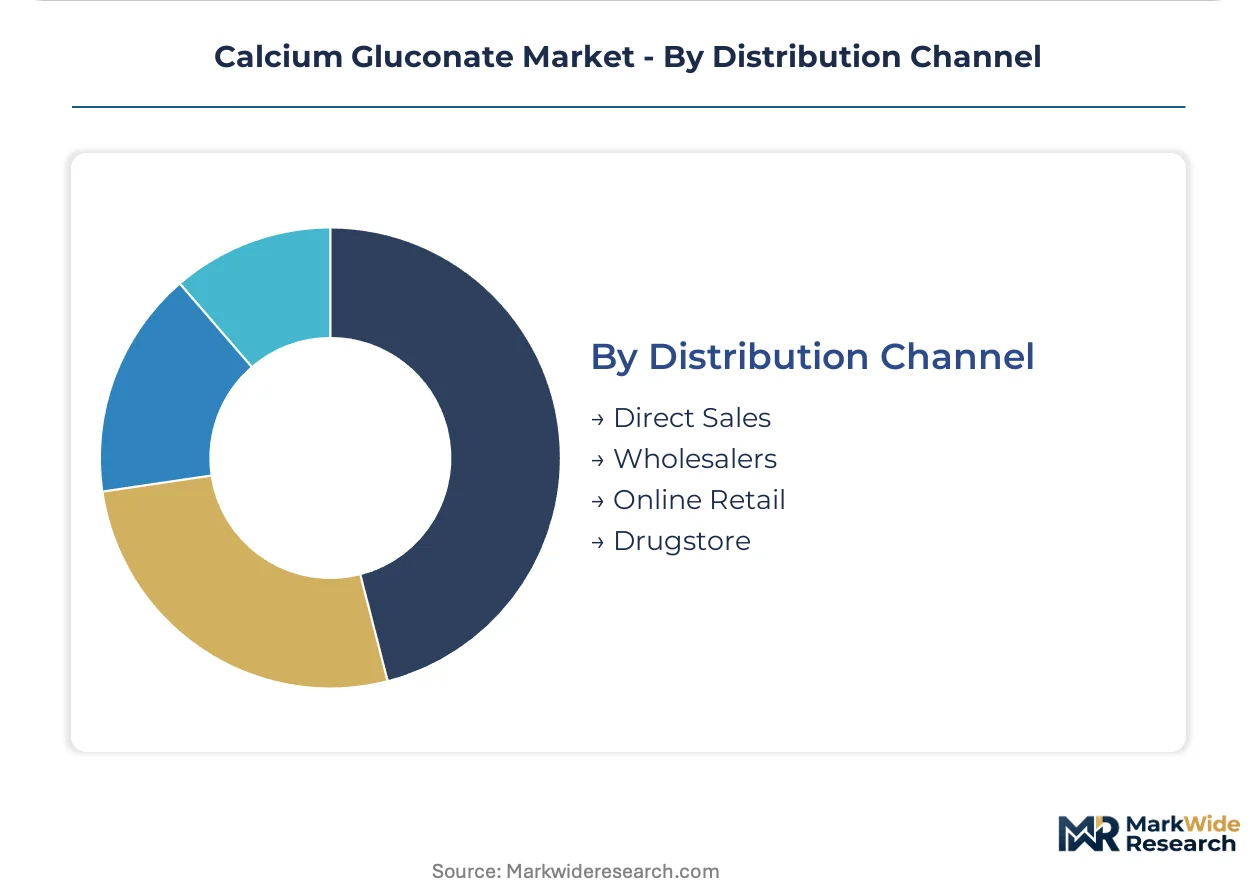
Distribution channel analysis illustrates how calcium gluconate products reach end consumers, highlighting key logistical and sales pathways.
- Wholesalers:These entities manage bulk distribution of calcium gluconate to hospitals, pharmacies, and food processors, acting as central hubs in the supply chain. They handle large volumes for both pharmaceutical and food-grade material.
- Drugstore:Drugstores, including large retail chains, offer direct consumer access to oral calcium gluconate products, particularly dietary supplements. This channel benefits from high foot traffic and consumer convenience.
- Direct Sales:Manufacturers engage in direct sales for specialized pharmaceutical grades or large-volume industrial clients, ensuring specific product requirements are met.
- Online Retail:E-commerce platforms provide a growing channel for dietary supplements and other oral forms, offering convenience and broader product selection to consumers.
Wholesalers remain central to large-scale product movement, with Online Retail demonstrating accelerated growth in consumer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's robust pharmaceutical and food processing industries underpin significant calcium gluconate demand. This concentration reflects strategic investments in domestic production and a large consumer base. Global regulatory trends influence manufacturing practices across all key regions.
China
Demand for calcium fortification in food and pharmaceuticals drives consumption. China's NMPA sets stringent quality standards for pharmaceutical-grade material. The Yangtze River Delta region hosts significant pharmaceutical manufacturing and food processing hubs.
United States
Dietary supplementation and acute hypocalcemia treatment ensure consistent product uptake. The US FDA mandates purity and safety for both pharmaceutical and food applications. Biopharmaceutical clusters in Boston and California develop advanced formulations.
Germany
High-purity calcium gluconate for injectable products finds strong demand in hospitals. The European Medicines Agency (EMA) oversees rigorous approval processes for medical products. Pharmaceutical production centers in Bavaria and North Rhine-Westphalia serve European markets.
Japan
Food fortification and an aging population requiring bone health support increase calcium gluconate use. Japan's PMDA regulates pharmaceutical and food additive standards. Major food and pharmaceutical companies operate in the Kanto region.
India
Expanding dietary supplement markets and a growing pharmaceutical sector fuel product demand. India's CDSCO establishes guidelines for drug manufacturing and quality control. Pharmaceutical manufacturing clusters in Hyderabad and Gujarat boost local production capabilities.
Calcium Gluconate Market Key Industry Players
Process innovation dominates the current landscape, with companies investing in advanced manufacturing techniques. The market structure features a tiered approach, encompassing raw material producers, specialized ingredient suppliers, and finished product manufacturers. Key archetypes include large-scale chemical producers, niche pharmaceutical ingredient specialists, and integrated healthcare solution providers. Geographic expansion and strategic partnerships remain crucial competitive moves for market participants.
Specialists in fermentation technology include Jungbunzlauer Suisse AG, which leverages extensive capabilities to maintain its market position. Global Calcium Private Limited, an India-based entity, exemplifies producers focused on high-purity mineral salts for pharmaceutical applications. Fresenius Kabi, a Germany-based company, anchors the injectable-grade segment, providing finished pharmaceutical formulations for hospital settings. These companies represent distinct strategic approaches within the calcium gluconate value chain.
| Leading Market Players |
|---|
| Jungbunzlauer Suisse AG |
| Corbion N.V. |
| BASF SE |
| Pfizer Inc. |
| Spectrum Chemical Manufacturing Corp. |
| Global Calcium Private Limited |
| Fresenius Kabi |
| Baxter International |
| Koninklijke DSM N.V. |
| Others |
Cost & Logistics Intelligence
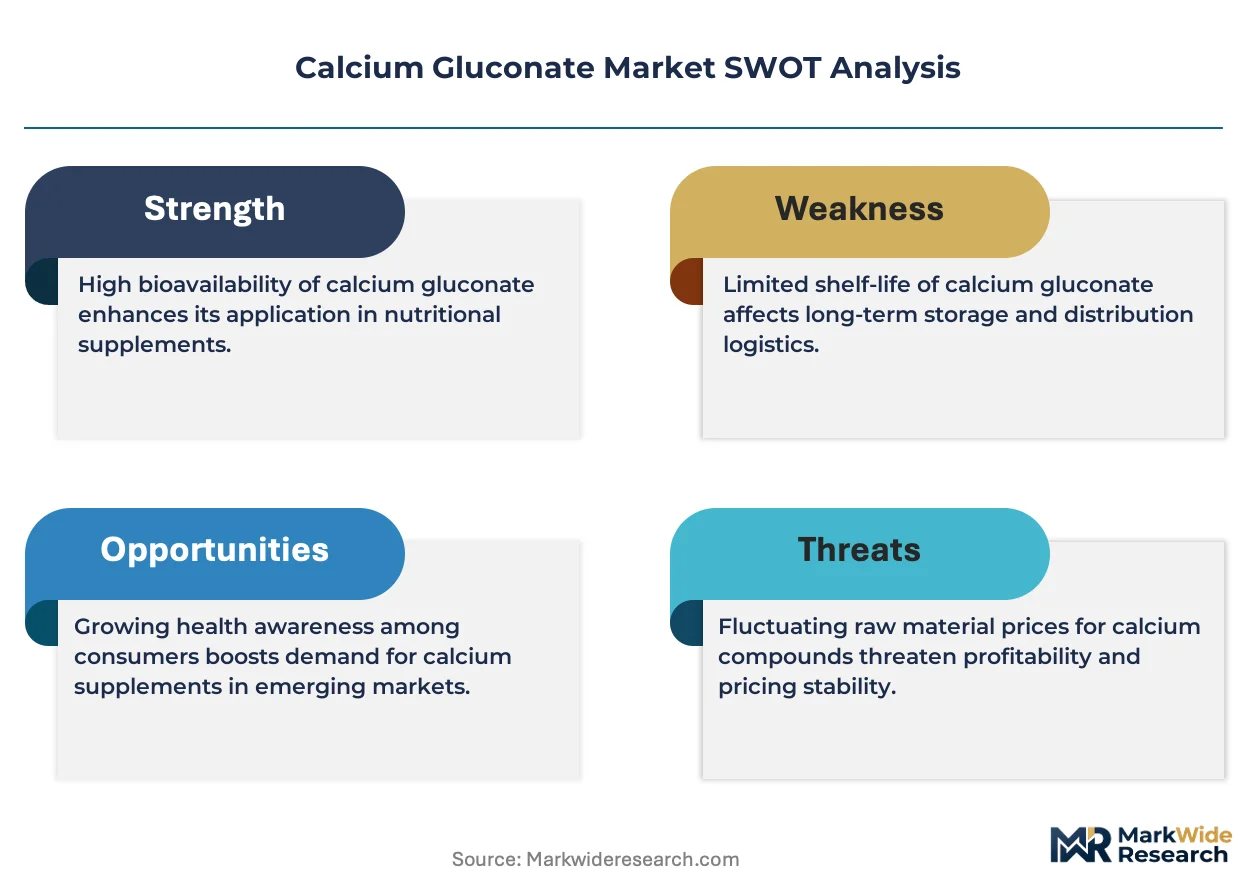
Agricultural glucose feedstock prices, tied to global commodity markets, directly influence the cost structure and pricing tiers for calcium gluconate across pharmaceutical and food-grade applications. This volatility creates significant challenges for manufacturers managing long-term supply contracts.
Pricing Analysis
Input cost pass-through from glucose feedstock to finished calcium gluconate products drives a contract-based pricing model for large-volume buyers. Price differentiation occurs based on quality grade, with injectable-grade material commanding a significant premium due to stringent purity and sterility requirements. Pricing pressure stems from the commodity nature of food-grade material, where lower-cost alternatives like calcium carbonate exist. Food processing and dietary supplement manufacturers represent the most price-sensitive segments, while hospitals purchasing injectable products are less sensitive.
Supply Chain Analysis
Reverse logistics for calcium gluconate generally involve minimal returns, focusing instead on quality control and batch recall procedures for non-compliant products. Geographic supply concentration for calcium gluconate production largely centers in China and India, which are major producers of active pharmaceutical ingredients. The supply chain depends heavily on glucose from corn or tapioca, creating a dependency on agricultural markets. Commodity price volatility for glucose feedstock represents a primary structural risk. Downstream distribution runs through a combination of wholesalers for bulk materials and direct sales for specialized pharmaceutical grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Calcium Gluconate market functions as a late-cycle quality story, with a demand-shift toward premium specifications driven by stringent pharmaceutical regulatory mandates. This trend favors manufacturers with advanced purification capabilities.
For Market Incumbents: Anchor market position by investing in advanced purification technologies like membrane filtration and chromatography to meet evolving global purity standards. Deepen vertical integration into specialized non-GMO feedstock sourcing to mitigate input cost volatility and meet 'clean label' demand. Consolidate market share through strategic acquisitions of smaller, specialized producers with strong regulatory dossiers, especially in Europe and the United States. Navigate the threat of substitution in food applications by emphasizing superior bioavailability and functional benefits.
For New Entrants and Emerging Players: China's NMPA establishing clearer guidelines for pharmaceutical excipients opens a window for specialized regional producers to enter the domestic market. Target underpenetrated dietary supplement markets in Southeast Asia and Latin America with oral-grade products, emphasizing local distribution partnerships. Focus on niche applications like animal nutrition, formulating high-bioavailability calcium gluconate into specialized feeds. A go-to-market angle could involve offering transparent non-GMO sourcing and robust bioavailability data for food and supplement brands.
For Investors and Strategic Acquirers: Consolidation pressure builds where high capital expenditure for sterile manufacturing and complex regulatory compliance create barriers for smaller players. Long-term viability over a 5-10 year window favors entities with robust R&D in fermentation and purification processes. Target acquisition archetypes include specialized mineral salt producers with established pharmaceutical-grade certifications or companies with proprietary non-GMO glucose fermentation technologies. A signal to watch is the increasing stringency of global pharmacopeial standards, indicating a shift towards higher-value, specialized production.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Purification | Enhances product purity for injectable-grade applications, meeting stringent regulatory requirements from the FDA and EMA. |
| Expand Non-GMO Sourcing | Addresses 'clean label' consumer demand, particularly in North American and European nutraceutical sectors. |
| Target Animal Nutrition Segment | Unlocks a significant growth vector by formulating high-bioavailability calcium gluconate for specialized feeds. |
| Strengthen Regulatory Compliance | Mitigates market entry barriers and ensures global export capabilities across diverse purity standards. |
| Geographic Market Penetration | Captures new demand in underpenetrated dietary supplement markets like Southeast Asia and Latin America. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region informing the market landscape. The research methodology combines in-depth primary interviews with industry stakeholders and rigorous secondary validation. Key stakeholders interviewed included regulatory affairs leads, hospital procurement managers, R&D directors at pharmaceutical companies, and food processing specialists. Secondary data sources comprised FDA filings, EMA submissions, customs and trade data, and relevant industry association reports. A multi-layered approach involving bottom-up and top-down triangulation ensured data accuracy.
Rate-of-change decomposition framed the analytical framework across the analysis window, capturing shifts in market dynamics. The study modeled segmentation dimensions including product type, therapy area, end-user, distribution channel, and specific regulatory grades. Compound Annual Growth Rates (CAGRs) were derived through a comprehensive analysis of historical market trends, technological advancements, and projected demand drivers. Key industry-specific forecast inputs included new fortification mandates in developing nations and the expanding availability of non-GMO feedstocks.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of extreme input cost volatility or sudden regulatory shifts. Forecasts reflect assumptions regarding economic stability and continued health awareness. Practitioners should monitor global commodity prices for glucose and evolving regional pharmaceutical regulations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Global Tizanidine Market
Pharmaceutical Ingredients
United Kingdom Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Pharma-Grade Magnesium Trisilicate Market
Pharmaceutical Ingredients
Fosfomycin Trometamol Powder Market
Pharmaceutical Ingredients
Hyaluronic Acid Raw Material Market
Pharmaceutical Ingredients
Topical Drugs Market
Pharmaceutical Ingredients
China Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Europe Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Taxifolin Market
Pharmaceutical Ingredients
Calcium Folinate for Injection Market
Pharmaceutical Ingredients
Fipronil Market
Pharmaceutical Ingredients
Small-Molecule Injectable Drugs Market
Pharmaceutical Ingredients
Small-Molecule Injectable Market
Pharmaceutical Ingredients
Epcam Antagonists Market
Pharmaceutical Ingredients
Zinc Bacitracin Market
Pharmaceutical Ingredients
Diosmin API Market