
 Heparin Sodium API Market | 2026-2036
Heparin Sodium API Market Size, Share, and Industry Trends Forecast 2026-2036
Heparin Sodium API Market Insights
Chinese bulk heparin manufacturers is shifting capacity toward value-added intermediates as cost pressures mount on raw porcine intestine supply. Shenzhen Hepalink Pharmaceutical leverages backward integration into crude heparin sourcing to secure margin control. Pfizer sustains formulation dominance in North American and European hospital networks through long-term supply agreements. Changzhou Qianhong Biopharma anchors the competitive landscape with dedicated low molecular weight heparin R&D facilities.
Heparin Sodium API comprises sulfated glycosaminoglycan polymers extracted from porcine intestinal mucosa, with unfractionated forms averaging molecular weights of 15,000 daltons and low molecular weight variants ranging 4,000 to 6,000 daltons; these compounds function as anticoagulants by accelerating antithrombin III inhibition of thrombin and Factor Xa. Low molecular weight heparin commands the largest revenue share due to predictable pharmacokinetics and reduced monitoring requirements in outpatient settings. Unfractionated heparin retains critical use in cardiovascular surgery and dialysis where rapid reversibility with protamine sulfate remains essential. Subcutaneous delivery dominates outpatient administration, while intravenous routes persist in acute hospital settings.
The US FDA enforces heparin-specific identity testing through nuclear magnetic resonance and capillary electrophoresis protocols, while China's NMPA mandates sourcing documentation from approved slaughterhouses to prevent adulteration. The EMA's revised GMP guidelines for biological APIs now require enhanced viral safety validation for heparin sodium starting materials. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and ChP standards, as divergence in potency assays and impurity thresholds directly shapes cross-border registration timelines and manufacturing location decisions.
Market Dynamics
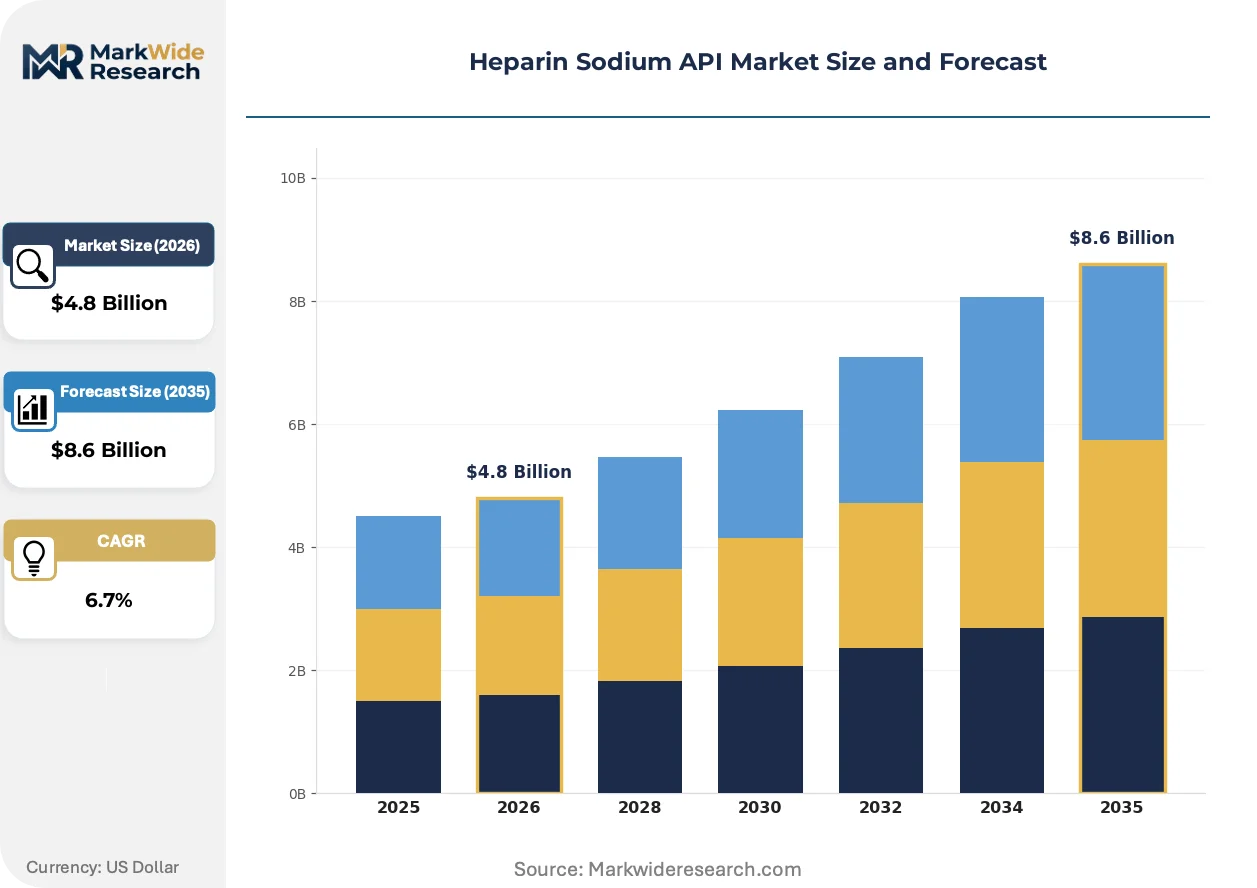
Pharmacovigilance tightening by the FDA and EMA has transformed heparin API sourcing from a commodity procurement exercise into a traceability-intensive compliance operation, forcing manufacturers to rebuild supply chain documentation infrastructure from slaughterhouse to finished vial.
Growth Catalysts
- Surgical volume normalization:Hospital systems in the United States, Germany, and Japan are restocking anticoagulant formularies as elective cardiovascular procedures return to pre-pandemic scheduling intensity.
- REACH-aligned impurity thresholds:The ECHA's evolving standards for nitrosamine and oversulfated chondroitin sulfate detection are accelerating replacement of legacy manufacturing lines with chromatography-enhanced purification systems.
- Low molecular weight heparin outpatient migration:Enoxaparin and dalteparin protocols are displacing unfractionated heparin in ambulatory anticoagulation clinics, expanding addressable patient populations beyond acute care settings.
Market Restraints
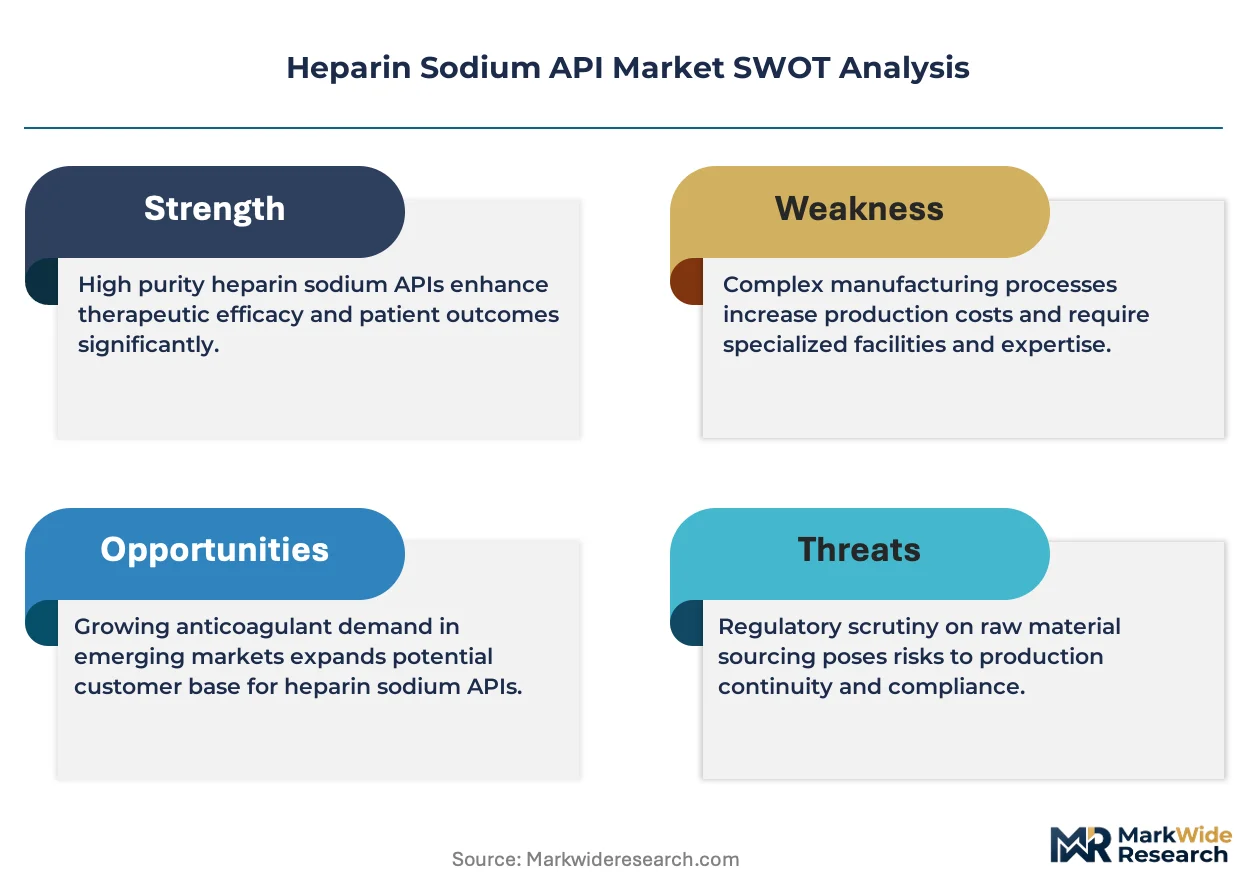
- Porcine intestine supply volatility:Crude heparin feedstock prices fluctuate with African swine fever cycles and Chinese livestock policy shifts, compressing margin predictability for non-integrated API manufacturers.
- China-centric extraction concentration:Over 70% of global crude heparin originates from Chinese slaughterhouse networks, creating single-source vulnerability that no alternative geography can currently offset at scale.
- Protamine sulfate dependency:Unfractionated heparin retains surgical indispensability due to reversible anticoagulation, locking formulation economics to a declining molecular weight segment despite clinical preference shifts.
Strategic Opportunities
- Biosimilar enoxaparin penetration in India:CDSCO's streamlined abbreviated approval pathway for complex generics is attracting API manufacturers to establish local formulation partnerships ahead of patent cliff expirations.
- Closed-loop heparinoid recycling:Captive recovery of heparin from spent dialysate streams is modularizing into viable supplementary feedstock for non-injectable applications, reducing virgin porcine dependence.
- EMA's biological API GMP revision:Enhanced viral safety validation requirements for starting materials are creating first-mover advantage for manufacturers with documented slaughterhouse-to-API chain of custody systems.
Industry Challenges
- Nuclear magnetic resonance spectroscopy competency gaps:FDA-mandated identity testing protocols require specialized analytical chemists that contract manufacturing organizations struggle to recruit and retain at competitive compensation levels.
- Cross-pharmacopeial assay harmonization delays:Divergent potency specifications between USP, EP, and ChP standards force redundant batch testing and registration dossier duplication, extending time-to-market for multinational suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heparin Sodium API Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Molecular Weight Heparin, Unfractionated Heparin, Biosimilar Heparin, Heparinoids End User: Hospitals, Outpatient Clinics, Ambulatory Surgical Centers, Research Laboratories Application: Cardiovascular, Orthopedic Surgery, General Surgery, Renal Disorders Delivery Mode: Intravenous, Subcutaneous, Topical, Others |
| Companies Covered | Pfizer, Bioibérica, Shenzhen Hepalink Pharmaceutical, Changzhou Qianhong Biopharma, Qingdao Jiulong Biopharmaceutical, Yantai Dongcheng Pharmaceutical, Hebei Changshan Biochemical Pharmaceutical, Dongying Tiandong Pharmaceutical, Nanjing King-friend Biochemical Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heparin Sodium API Market Trends and Innovations
Continuous processing and real-time release testing are displacing batch-oriented heparin manufacturing, compressing cycle times from weeks to days while tightening coefficient of variation on anticoagulant potency. These shifts are reconfiguring capital deployment patterns across API supply tiers.
Membrane-based fractionation systems are modularizing low molecular weight heparin production by enabling inline depolymerization with precise molecular weight targeting. Mid-scale API manufacturers in South Korea and Italy are adopting these skid-mounted units to bypass fixed-column chromatography investments. The technology is modularizing competitive entry barriers, allowing regional players to achieve pharmacopeial-grade output without billion-liter fermentation footprints.
The FDA's heparin-specific testing guidance issued after 2008 contamination events now mandates capillary electrophoresis and NMR fingerprinting for all imported API lots. This regulatory architecture has forced Chinese exporters to establish US-based testing laboratories or risk detention without physical examination holds. European hospital procurement networks are now requiring equivalent documentation, extending compliance costs across Atlantic supply routes.
Hospital buying consortiums in the United States are consolidating anticoagulant tenders into multi-year sole-source agreements with penalty clauses for supply interruption. This concentration is displacing fragmented spot purchasing that historically allowed generic API suppliers to arbitrage regional price differentials. The shift is most visible in cardiovascular service line management at integrated delivery networks in Texas and Florida, where formulary lock-in now spans three to five year horizons.
Heparin Sodium API Market Segmentation
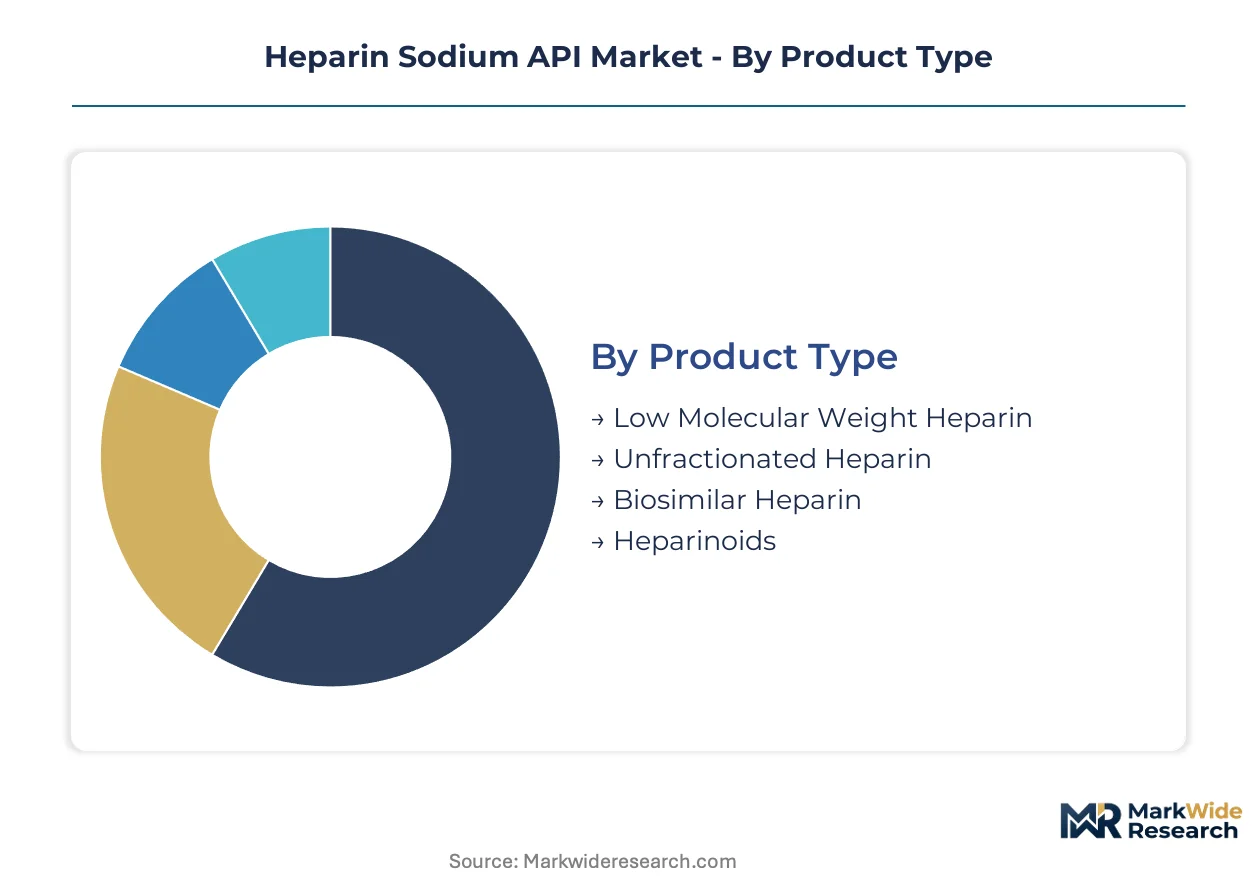
Heparin Sodium API procurement decisions pivot on molecular weight specifications, regulatory compliance tiers, and end-use administration protocols. Segmentation reveals how formulation economics fragment across acute care versus outpatient settings, with purity grades and delivery modes determining margin structures for API suppliers.
Product Type:
Hospital formulary committees prioritize pharmacokinetic predictability and reversal protocols when selecting heparin molecular weight categories for therapeutic protocols.
- Low Molecular Weight Heparin:Sulfated glycosaminoglycan polymers averaging 4,000 to 6,000 daltons enable predictable anticoagulation without routine monitoring. Outpatient anticoagulation clinics in the United States and Germany are standardizing enoxaparin and dalteparin protocols for deep vein thrombosis prophylaxis, displacing unfractionated alternatives where rapid reversibility is not critical.
- Unfractionated Heparin:Native polysaccharide chains averaging 15,000 daltons retain surgical indispensability due to immediate neutralization with protamine sulfate. Cardiovascular operating rooms and dialysis centers across Japan and Texas maintain dedicated inventory for procedures requiring minute-to-minute anticoagulation control.
- Biosimilar Heparin:Complex generic versions of originator LMWH molecules are penetrating price-sensitive hospital systems through abbreviated approval pathways.
- Heparinoids:Synthetic and semi-synthetic anticoagulant analogues serve niche indications where porcine-derived products face religious or clinical contraindications.
Volume sits with Unfractionated Heparin in acute surgical settings; growth tilts toward Low Molecular Weight Heparin as ambulatory protocols expand.
End User:
Procurement scale and inventory turnover velocity separate institutional buyers, with integrated delivery networks consolidating purchasing power through multi-year tender agreements.
- Hospitals:Acute care institutions command the largest API volumes through cardiovascular service lines and emergency anticoagulation protocols. United States integrated delivery networks in Florida and Texas are locking three to five year sole-source agreements with penalty clauses for supply interruption, displacing fragmented spot purchasing.
- Outpatient Clinics:Ambulatory anticoagulation management programs are migrating from hospital-based infusion centers to standalone facilities. Medicare reimbursement shifts in the United States are accelerating this decentralization, expanding addressable patient populations beyond traditional acute care footprints.
- Ambulatory Surgical Centers:Same-day procedure facilities require rapid-turnover anticoagulant inventory with streamlined reversal protocols.
- Research Laboratories:Academic and commercial R&D operations consume specialized heparin grades for cell culture and assay development applications.
Hospitals anchor current procurement volumes; outpatient clinics are climbing the fastest as care delivery decentralizes.
Application:
Surgical specialization and procedure reimbursement rates determine heparin consumption intensity across therapeutic areas.
- Cardiovascular:Coronary artery bypass grafting, valve replacement, and percutaneous coronary intervention procedures consume high-dose unfractionated heparin for cardiopulmonary bypass anticoagulation. German and Japanese hospital systems are restocking formularies as elective procedure schedules normalize to pre-pandemic intensity.
- Orthopedic Surgery:Total joint arthroplasty and hip fracture repair protocols mandate extended venous thromboembolism prophylaxis with LMWH. Outpatient rehabilitation centers are extending injection courses beyond hospital discharge, expanding API demand into post-acute settings.
- General Surgery:Abdominal and oncologic procedures require intermediate-duration anticoagulation with flexible reversal options.
- Renal Disorders:Hemodialysis circuits depend on unfractionated heparin anticoagulation for extracorporeal blood processing.
Cardiovascular applications dominate value capture; orthopedic surgery is gaining share fastest as joint replacement volumes rise.
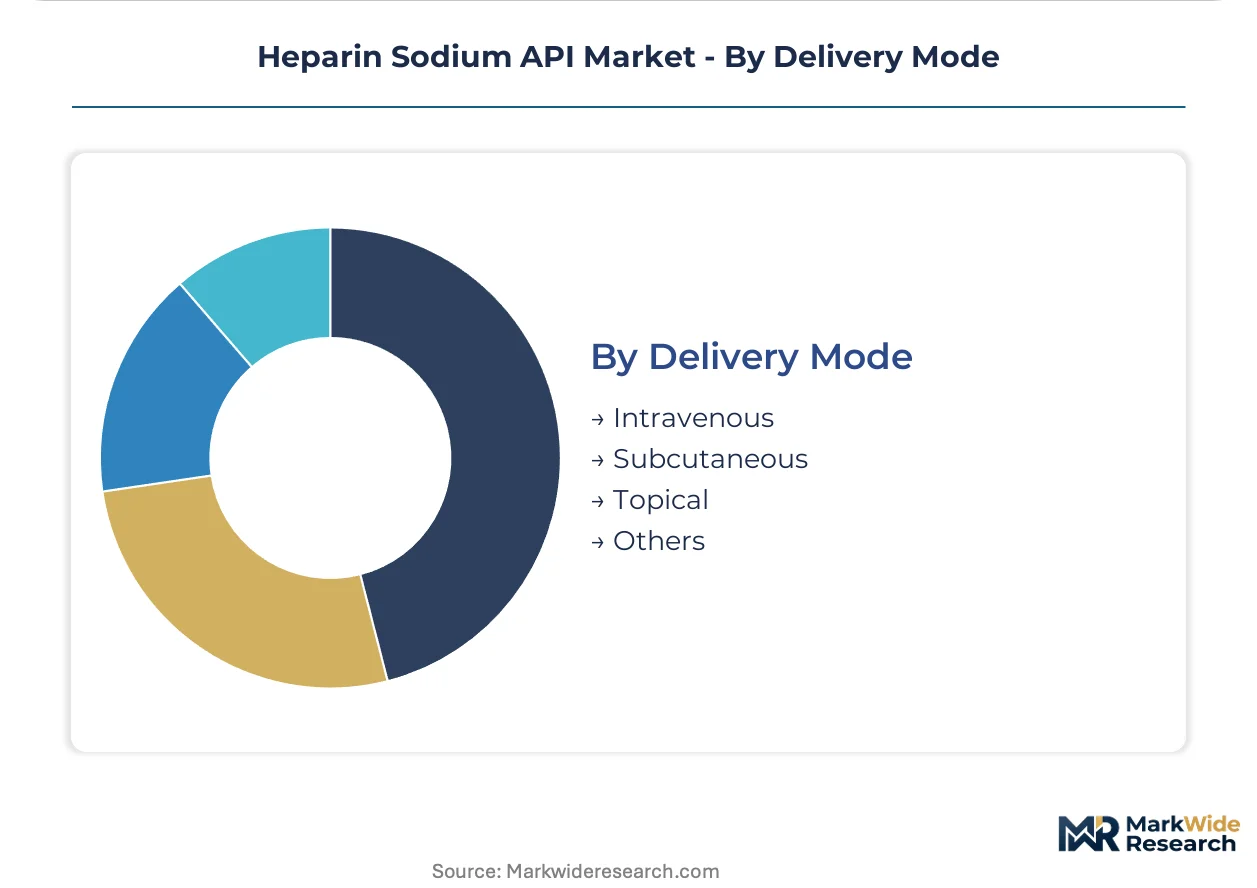
Delivery Mode:
Administration route selection balances onset speed, patient compliance, and healthcare worker training requirements across care settings.
- Intravenous:Direct vascular administration enables immediate anticoagulation with continuous titration for critical care scenarios. Emergency departments and operating rooms maintain dedicated infusion protocols with weight-based dosing algorithms.
- Subcutaneous:Depot injection into abdominal adipose tissue sustains therapeutic anticoagulation without vascular access. Home health nursing services and self-instruction programs are expanding LMWH administration beyond clinical facilities.
- Topical:Heparinoid creams and gels address superficial thrombophlebitis and cosmetic bruising indications with limited systemic absorption.
- Others:Inhalation and intra-articular experimental routes remain investigational for specialized anticoagulant and anti-inflammatory applications.
Subcutaneous delivery commands outpatient expansion; intravenous routes retain acute care lock-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Porcine intestine sourcing concentrates in Chinese slaughterhouse networks, with downstream API purification and formulation distributed across North American, European, and Asia-Pacific pharmaceutical manufacturing clusters. Regulatory divergence between FDA, EMA, and NMPA standards shapes where finished vial production locates.
United States
Hospital systems in Texas and Florida consolidate anticoagulant procurement through multi-year sole-source agreements with penalty clauses for supply interruption. FDA enforces heparin-specific identity testing through nuclear magnetic resonance and capillary electrophoresis protocols. The Greater Boston corridor hosts specialized analytical laboratories serving import testing requirements for Chinese API lots.
China
Domestic manufacturers capture expanding shares of downstream formulation supply as NMPA mandates sourcing documentation from approved slaughterhouses. Shenzhen and Changzhou anchor the Yangtze River Delta heparin manufacturing cluster, with dedicated low molecular weight heparin R&D facilities. Backward integration into crude heparin sourcing secures margin control against African swine fever price volatility.
Germany
Hospital systems restock cardiovascular formularies as elective procedures normalize to pre-pandemic scheduling intensity. EMA's revised GMP guidelines for biological APIs require enhanced viral safety validation for starting materials. The Rhine-Ruhr industrial corridor concentrates formulation finishing capacity for European hospital networks.
Japan
Cardiovascular operating rooms and dialysis centers maintain dedicated unfractionated heparin inventory for procedures requiring minute-to-minute anticoagulation control. PMDA aligns pharmacovigilance requirements with FDA contamination-prevention standards. The Kansai region around Osaka hosts specialized API importers with documented slaughterhouse-to-API chain of custody systems.
India
CDSCO's streamlined abbreviated approval pathway for complex generics attracts API manufacturers to establish local formulation partnerships ahead of patent cliff expirations. Biosimilar enoxaparin penetration accelerates in price-sensitive hospital systems. The Mumbai-Pune pharmaceutical belt concentrates contract manufacturing capacity for injectable anticoagulant exports.
Heparin Sodium API Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biosimilar penetration and regional formulation partnerships. The market structure consolidates around vertically integrated Chinese crude heparin extractors, multinational formulation specialists with hospital network lock-in, and mid-scale regional manufacturers adopting modular purification technology. Three archetypes dominate: backward-integrated Chinese API suppliers, North American-European formulation incumbents with long-term supply agreements, and biosimilar-focused complex generic specialists. Competitive moves concentrate on M&A for traceability infrastructure and strategic partnerships for slaughterhouse sourcing documentation.
Among China-based extractors, Shenzhen Hepalink Pharmaceutical and Changzhou Qianhong Biopharma exemplify the backward-integrated archetype with captive crude heparin supply chains. Pfizer occupies a position within the multinational formulation tier, anchoring hospital network relationships in North American and European markets. These three represent distinct competitive vectors: upstream raw material security, downstream institutional channel control, and the bridging biosimilar opportunity in emerging markets.
| Leading Market Players |
|---|
| Pfizer |
| Bioibérica |
| Shenzhen Hepalink Pharmaceutical |
| Changzhou Qianhong Biopharma |
| Qingdao Jiulong Biopharmaceutical |
| Yantai Dongcheng Pharmaceutical |
| Hebei Changshan Biochemical Pharmaceutical |
| Dongying Tiandong Pharmaceutical |
| Nanjing King-friend Biochemical Pharmaceutical |
| Others |
Pricing and Supply Chain Analysis
Membrane-based fractionation systems are compressing production cycle times from weeks to days while simultaneously concentrating API manufacturing among mid-scale specialists with capital-light purification skids. This technology shift redraws cost economics away from billion-liter fermentation footprints toward modular chromatography units, tightening margin structures for legacy batch manufacturers while expanding geographic supply dispersion.
Pricing Analysis
Regulatory compliance documentation now bundles with API lots as a non-negotiable service component, with unbundled testing certificates commanding premium spreads. Three-tier pricing structure across USP-grade, EP-grade, and research-grade specifications separates hospital procurement contracts from spot laboratory purchases. Cost compression in standard-grade heparin is intensifying because Chinese manufacturers are absorbing traceability infrastructure investments to maintain European market access. Research laboratories exhibit highest price sensitivity due to discretionary purchasing volumes, while integrated delivery networks lock in least-sensitive pricing through multi-year sole-source agreements with penalty-backed supply guarantees.
Supply Chain Analysis
Captive recovery of heparin from spent dialysate streams is emerging as a reverse-logistics channel for non-injectable applications, reducing virgin porcine dependence. Raw material supply concentrates in Chinese slaughterhouse networks, with downstream purification capacity distributed across the United States, Germany, and India. Crude heparin feedstock, sodium hydroxide reagents, and chromatography resin columns constitute critical input dependencies. Single-source vulnerability in Chinese porcine intestine sourcing creates structural risk that alternative geographies cannot offset at scale. Distribution runs through pharmaceutical wholesaler networks to hospital formularies and direct API supply contracts to formulation manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Crude heparin feedstock constraints from African swine fever cycles and Chinese livestock policy shifts prop pricing power toward backward-integrated manufacturers with captive slaughterhouse sourcing.
For Market Incumbents: Anticipate biosimilar enoxaparin penetration in Indian and Southeast Asian hospital systems by securing CDSCO pre-submission meetings and local formulation partnerships ahead of abbreviated approval pathway maturation. Reinforce traceability infrastructure investments to satisfy EMA's revised GMP viral safety validation requirements, creating first-mover documentation advantage that spot-market competitors cannot replicate. Prioritize long-term supply agreement renewals with United States integrated delivery networks in cardiovascular-intensive states to lock in volume commitments before procurement consolidation peaks. For New Entrants and Emerging Players: Direct-to-hospital digital procurement platforms offer a channel route to bypass incumbent wholesaler markups and establish direct formulary relationships with ambulatory surgical centers and standalone anticoagulation clinics. Target outpatient clinic expansion in Medicare-reimbursed United States markets where care delivery decentralization is accelerating fastest. Penetrate biosimilar enoxaparin white space through abbreviated regulatory pathways in price-sensitive hospital systems, positioning on total cost-of-therapy metrics rather than originator equivalence alone. For Investors and Strategic Acquirers: Exit pathways concentrate in backward-integrated Chinese API suppliers with documented slaughterhouse-to-finished-vial chain of custody systems and established FDA import testing laboratory relationships. Long-term viability over the next decade hinges on regulatory compliance infrastructure rather than extraction scale alone. Acquisition targets should demonstrate NMR spectroscopy competency and capillary electrophoresis capability in-house. Watch for EMA-USP pharmacopeial harmonization progress as the signal indicating accelerated cross-border registration timelines and manufacturing location arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crude Heparin Sourcing | Shenzhen Hepalink Pharmaceutical's captive slaughterhouse supply secures margin control against African swine fever price volatility. |
| EMA Biological API GMP Compliance Investment | Enhanced viral safety validation documentation creates first-mover advantage for hospital procurement network access. |
| CDSCO Abbreviated Approval Pathway Engagement | Streamlined complex generic regulations attract API manufacturers to establish Indian formulation partnerships ahead of patent cliffs. |
| Continuous Processing Technology Adoption | Real-time release testing compresses cycle times and tightens potency variation coefficients for competitive manufacturing economics. |
| Hospital System Sole-Source Agreement Lock-in | Multi-year tenders with penalty clauses displace fragmented spot purchasing and secure volume commitments across cardiovascular service lines. |
Research Methodology
EMA regulatory filings, FDA heparin-specific guidance documents, and NMPA sourcing documentation requirements formed the secondary backbone for traceability infrastructure cost modeling and compliance timeline assessment. Primary interviews with API manufacturing executives, hospital formulary directors, regulatory affairs specialists, and pharmaceutical procurement managers at integrated delivery networks validated secondary assumptions on tender consolidation patterns and testing competency gaps. Customs trade data on crude heparin import volumes and pharmaceutical API export flows provided cross-reference points for supply concentration analysis. Bottom-up segmentation modeling across molecular weight categories, delivery modes, and end-user institutions combined with top-down market sizing triangulation to produce volume and value estimates.
Historical trendline analysis of surgical procedure normalization patterns, anticoagulant formulary restocking cycles, and pharmacovigilance enforcement intensity informed projection frameworks across the analysis window. Segmentation dimensions modeled include molecular weight specification, regulatory compliance tier, end-user institution type, application area, and geographic regulatory cluster. CAGRs were derived from procedure volume recovery trajectories, outpatient migration rates for low molecular weight heparin protocols, and biosimilar penetration assumptions in price-sensitive markets. Industry-specific forecast inputs incorporated African swine fever cycle modeling for crude heparin feedstock pricing and EMA-USP pharmacopeial harmonization progress indicators.
The model holds under continued surgical volume normalization and stable Chinese livestock policy; deviation in African swine fever resurgence severity or abrupt NMPA slaughterhouse approval restrictions would shift feedstock pricing assumptions and API margin structures. Forecasts reflect documented assumptions on regulatory compliance cost trajectories and procurement consolidation patterns. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Global Granisetron Market
Pharmaceutical Ingredients
Rizatriptan Market
Pharmaceutical Ingredients
Global High Potency Active Pharmaceutical Ingredient (HPAPI) Market
Pharmaceutical Ingredients
Taxifolin Market
Pharmaceutical Ingredients
Calcium Folinate for Injection Market
Pharmaceutical Ingredients
Lipids Active Pharmaceutical Ingredient Market
Pharmaceutical Ingredients
Folinic Acid Market
Pharmaceutical Ingredients
Antibiotics API Market
Pharmaceutical Ingredients
Pharmaceutical Excipients for Taste Masking Market
Pharmaceutical Ingredients
Small-Molecule Injectable Market
Pharmaceutical Ingredients
Oral Transmucosal Drugs Market
Pharmaceutical Ingredients
Pharmaceutical Fine Chemicals Market
Pharmaceutical Ingredients
Chlorzoxazone Market
Pharmaceutical Ingredients
Moxifloxacin Hcl (CAS 186826-86-8) Market
Pharmaceutical Ingredients
Fipronil Market
Pharmaceutical Ingredients
Nortriptyline Hydrochloride Market