
 Global Aspirin Market | 2026-2036
Global Aspirin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aspirin Market Foresight
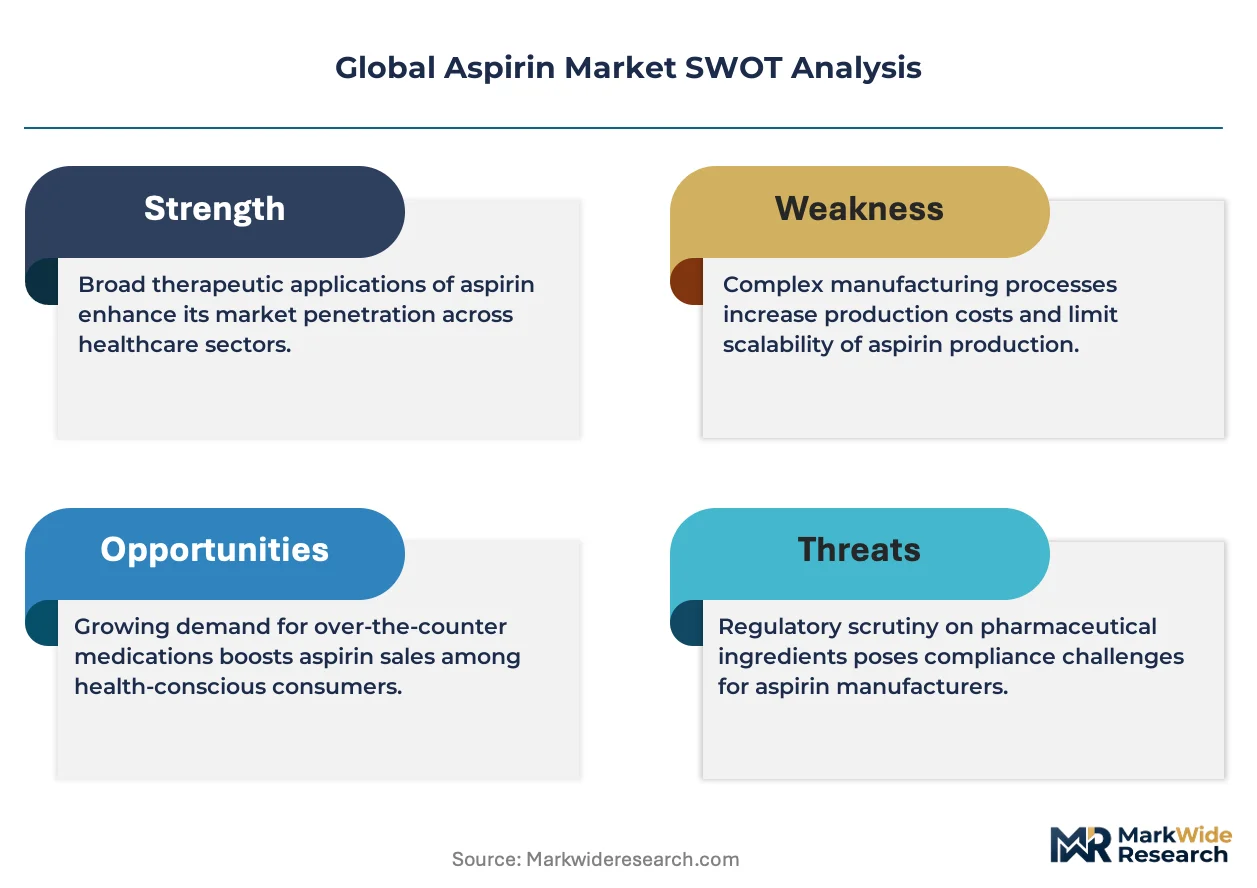
The capital-intensity divergence between API synthesis and finished-dose manufacturing is collapsing as Chinese producers integrate backward into acetylsalicylic acid production. Bayer AG leverages century-old brand equity and vertical control over salicylic acid supply chains to sustain premium positioning in European and North American pharmacies. Zhenjiang Gaopeng Pharmaceutical Co. Ltd. anchors the bulk API export trade, competing on cost-adjusted purity grades that meet USP and EP monographs. Sun Pharmaceutical Industries Ltd. differentiates through dual-market registration strategies that navigate both regulated and emerging economy approval pathways.
Aspirin, or acetylsalicylic acid, is a non-steroidal anti-inflammatory drug synthesized through acetylation of salicylic acid with acetic anhydride, typically yielding 99.0-100.5% purity under USP standards; its primary commercial purpose spans analgesic, antipyretic, and antiplatelet therapeutic applications across prescription and over-the-counter channels. Enteric-coated formulations command disproportionate margin pools in the product type dimension as gastroprotection justifies price premiums in chronic cardiovascular regimens. The cardiovascular disease application segment leads volume consumption due to guideline-endorsed secondary prevention protocols, while home care end users represent the fastest-growing channel as self-administration of low-dose protocols expands. Tablet formulation dominance persists, though powder and liquid variants capture pediatric and geriatric niches where swallowing difficulties drive formulation switching.
The FDA regulates aspirin as both an OTC monograph drug and prescription antiplatelet therapy, with label revisions directly constraining marketing claims and dosing recommendations for cardiovascular indications. EMA's Committee for Medicinal Products for Human Use periodically reassesses bleeding-risk benefit ratios, influencing prescriber behavior across EU member states and shaping reimbursement thresholds for prophylactic use. China's NMPA accelerates generic consistency evaluation requirements, tightening bioequivalence standards that filter domestic manufacturers and elevate quality benchmarks for export-oriented production. Stakeholders must monitor evolving antithrombotic guideline revisions from cardiology societies and corresponding regulatory label restrictions that could abruptly resegment prescription versus OTC demand.
Market Dynamics
The aspirin market's structural transformation hinges on API manufacturing consolidation in China, where backward integration into salicylic acid production is collapsing traditional cost hierarchies between bulk chemical suppliers and finished-dose formulators.
Growth Catalysts
- Cardiovascular prophylaxis protocols:Aging patient pools in Germany, Japan, and the United States expand chronic low-dose regimens endorsed by cardiology societies.
- NMPA generic consistency evaluation:China's tightened bioequivalence standards elevate quality benchmarks, filtering substandard domestic manufacturers and opening export pathways for compliant producers.
- Enteric-coated formulation demand:Gastroprotection requirements in long-term antiplatelet therapy justify premium pricing and extend product lifecycles in pharmacy channels.
Market Restraints
- Acetic anhydride input volatility:Petrochemical feedstock fluctuations and energy costs squeeze margins for non-integrated acetylsalicylic acid producers.
- Bleeding-risk regulatory friction:EMA's Committee for Medicinal Products for Human Use periodically reassesses risk-benefit ratios, constraining prescriber enthusiasm for primary prevention.
- Anticoagulant substitution threat:Direct oral anticoagulants displace aspirin in specific stroke-prevention protocols, narrowing addressable indications.
Strategic Opportunities
- Home care channel expansion:Self-administration of low-dose protocols accelerates as Brazil and Indonesia broaden primary care drug access programs.
- Pediatric formulation white space:Powder and liquid variants capture geriatric and pediatric niches where swallowing difficulties drive switching from tablets.
- Dual-market registration strategies:Simultaneous navigation of USP/EP monograph compliance and emerging economy approval pathways unlocks volume scale.
Industry Challenges
- Salicylic acid purification expertise scarcity:Captive production of pharmaceutical-grade feedstock demands process chemistry capabilities concentrated among legacy European and Chinese specialists.
- Label revision response latency:FDA antiplatelet guideline updates require rapid reformulation of marketing claims and dosing recommendations, compressing planning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aspirin Market |
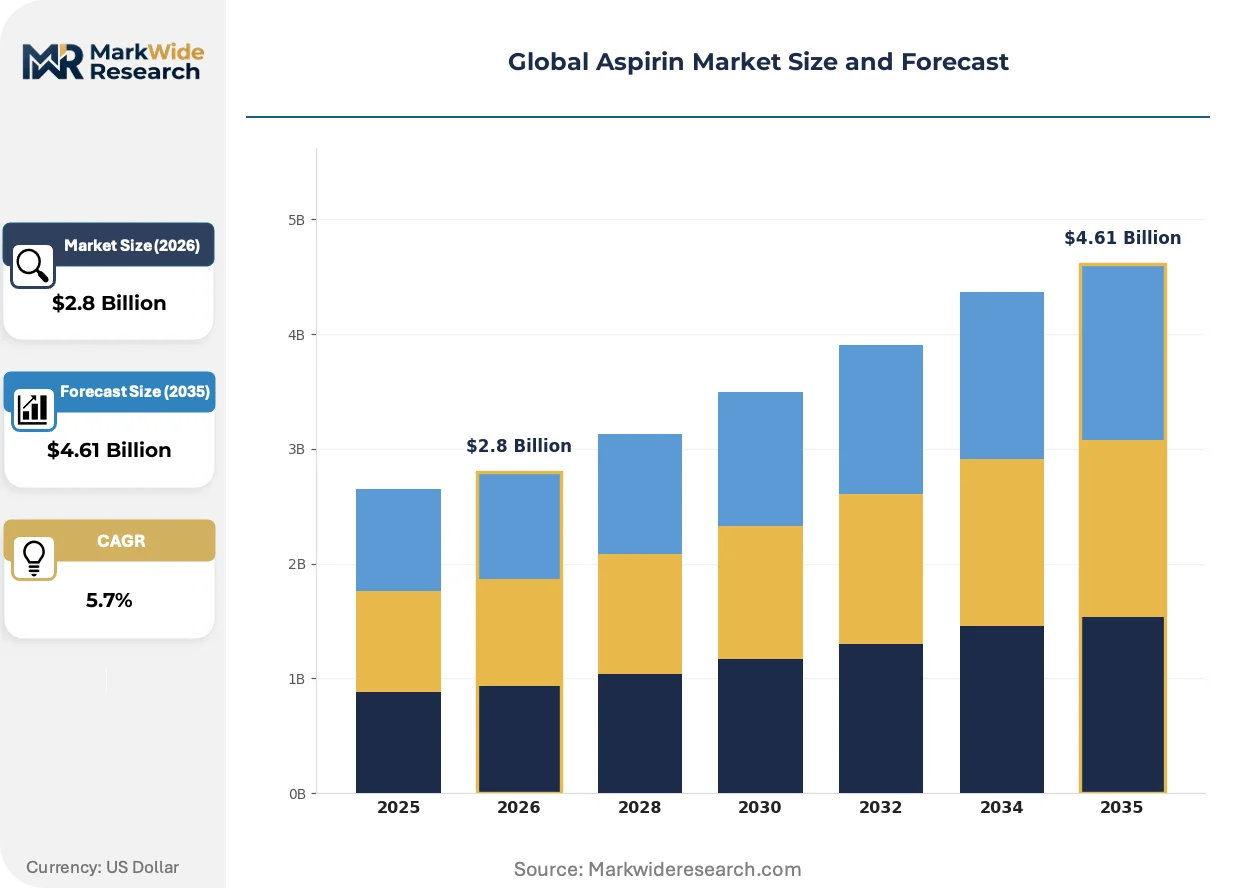
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Aspirin, Buffered Aspirin, Dispersible Aspirin, Enteric-Coated Aspirin, Chewable Aspirin Application: Cardiovascular Disease, Pain Relief, Anti-Inflammatory, Fever Reduction, Stroke Prevention End User: Hospitals, Pharmacies, Clinics, Home Care, Research Laboratories Formulation: Tablet, Capsule, Powder, Granule, Liquid |
| Companies Covered | Allegiant Health, Mayne Pharma Group Limited, Bayer AG, Sun Pharmaceutical Industries Ltd., Bal Pharma Limited, Cardinal Health, Perrigo Company plc, Zhenjiang Gaopeng Pharmaceutical Co. Ltd., Par Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aspirin Market Shifts & Advancements
Continuous manufacturing technologies and precision coating systems are compressing batch-to-batch variability while enabling real-time quality verification, fundamentally altering how aspirin API integrates into downstream formulation workflows.
Micro-dosing tablet technologies is miniaturizing dosage precision for cardiovascular prophylaxis, allowing manufacturers to achieve tighter assay uniformity in low-strength products. Cardiology practices in the United States and Germany are adopting these formats for personalized antiplatelet regimens. The technology is miniaturizing equipment footprints in contract manufacturing facilities, reducing capital barriers for regional formulators.
REACH registration requirements for acetylsalicylic acid intermediates are tightening documentation burdens on European API importers, forcing supply chain requalification. German and French pharmaceutical manufacturers are accelerating dual-sourcing strategies to mitigate authorization delays. The regulation most acutely affects mid-volume formulators lacking in-house regulatory affairs capacity.
Direct-to-pharmacy distribution models are disintermediating traditional wholesale layers in emerging markets, compressing working capital cycles for manufacturers. Hospital and retail pharmacy chains in India and Southeast Asia negotiate volume commitments that bypass regional distributors. This channel shift is most visible in urban clusters where pharmacy consolidation has created buyer concentration.
Global Aspirin Market Segmentation
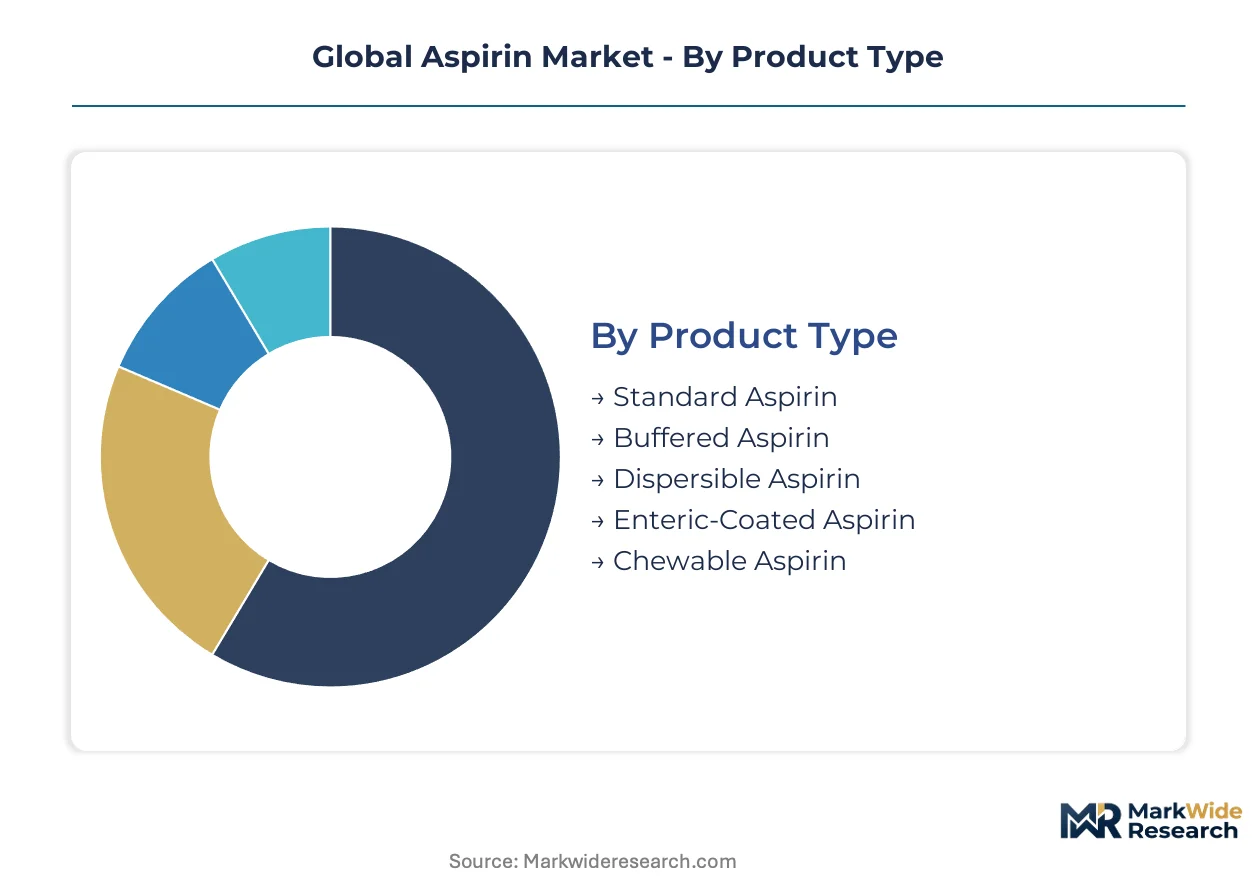
Aspirin's therapeutic versatility fragments demand across formulation technologies, care settings, and clinical protocols. Manufacturers must align production assets with the gastroprotection requirements of chronic cardiovascular regimens and the accessibility priorities of self-administered pain management.
Product Type:
Domestic production of standard and buffered variants dominates mature markets, while enteric-coated and dispersible formats drive export-led growth into Asia-Pacific and Latin American pharmacy channels.
- Standard Aspirin:Immediate-release acetylsalicylic acid without protective coatings remains the cost baseline for acute pain and fever indications. Demand concentrates in Indian and Indonesian retail pharmacies where price sensitivity shapes procurement decisions.
- Enteric-Coated Aspirin:Polymer-barrier formulations delay gastric release until intestinal pH triggers dissolution, essential for daily antiplatelet protocols. German and Japanese cardiology practices prescribe these formats disproportionately to mitigate bleeding complications in elderly populations.
- Buffered Aspirin:Antacid-admixed compositions neutralize gastric acidity for patients with documented dyspepsia. US pharmacy chains stock these as mid-tier alternatives between standard and enteric-coated options.
- Dispersible Aspirin:Rapid-disintegration tablets dissolve in water for patients with swallowing difficulties. Brazilian and Mexican distributors favor this format for community health programs targeting geriatric adherence.
- Chewable Aspirin:Flavored, low-strength tablets facilitate pediatric dosing and emergency cardiac protocols. US emergency medical services carry these for suspected myocardial infarction first response.
Enteric-coated formats hold the largest share; momentum sits with dispersible variants gaining traction in emerging market primary care expansion.
Application:
Volume distribution follows regulatory label expansions, with cardiovascular indications commanding chronic dosing schedules while pain and fever applications drive episodic, high-unit consumption.
- Cardiovascular Disease:Low-dose antiplatelet therapy for secondary prevention of myocardial infarction and unstable angina requires indefinite daily administration. US and German prescribing guidelines endorse 75-100 mg regimens, creating stable demand baselines for contract manufacturers.
- Stroke Prevention:Ischemic stroke prophylaxis in atrial fibrillation patients previously dependent on aspirin now competes with direct oral anticoagulants. Japanese neurologists maintain aspirin preference for low-risk patients unsuitable for novel anticoagulant costs.
- Pain Relief:Acute analgesia for headache, dental pain, and musculoskeletal complaints generates high transaction volumes with minimal prescription oversight. Indian and Nigerian retail markets move substantial tonnage through informal pharmacy networks.
- Anti-Inflammatory:Rheumatoid arthritis and osteoarthritis management has ceded ground to selective COX-2 inhibitors and biologics. Remaining demand clusters in regions with restricted access to newer therapeutic classes.
- Fever Reduction:Antipyretic use in viral illness competes directly with paracetamol and ibuprofen in pediatric and adult populations. Seasonal influenza patterns in temperate climates create predictable demand spikes.
Cardiovascular disease anchors volume consumption; stroke prevention exhibits the steepest expansion trajectory as aging demographics extend prophylactic candidate pools.
End User:
Procurement authority is shifting from institutional formularies toward retail pharmacy buyers and direct-to-consumer channels as self-medication protocols proliferate.
- Home Care:Self-administered low-dose regimens for cardiovascular prophylaxis bypass clinical supervision once therapy is initiated. Brazilian and Indonesian government programs now subsidize take-home supplies for stable coronary patients.
- Hospitals:Acute care settings manage perioperative antiplatelet decisions and emergency loading doses for acute coronary syndromes. German hospital pharmacists coordinate with cardiology departments to maintain dual-antiplatelet therapy continuity.
- Pharmacies:Community and retail dispensaries represent the dominant fulfillment node for both OTC and prescription aspirin across all major markets. Chain consolidation in the US and UK has concentrated purchasing power among fewer buyers.
- Clinics:Primary care and specialty outpatient facilities initiate chronic therapy and manage dose adjustments based on bleeding events. India's Jan Aushadhi generic program channels substantial volume through public health clinics.
- Research Laboratories:Preclinical and clinical trial supply for antiplatelet mechanism studies and novel combination therapies. Academic medical centers in Switzerland and the Netherlands consume specialized analytical grades.
Pharmacies retain the largest share; home care gains share fastest as decentralized chronic disease management protocols expand.
Formulation:
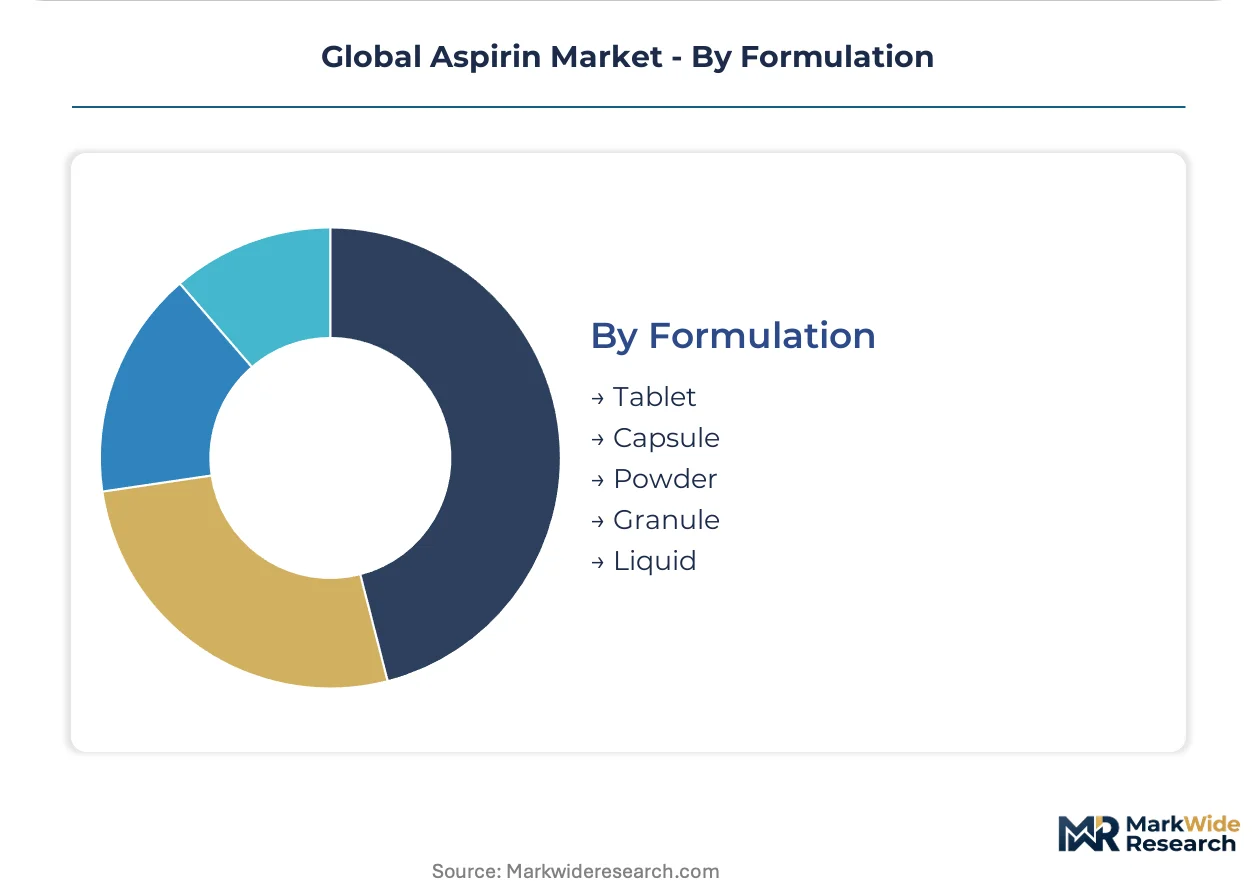
Manufacturing asset allocation reflects the tension between high-speed tablet compression economies and specialized liquid or powder production for swallowing-impaired populations.
- Tablet:Compressed dosage forms dominate production volumes due to packaging efficiency, stability profiles, and patient familiarity. Chinese and Indian contract manufacturers operate dedicated high-speed lines for 81 mg and 325 mg strengths.
- Liquid:Aqueous suspensions and solutions serve pediatric populations and geriatric patients with dysphagia. UK and Australian regulatory frameworks require specific stability testing for liquid aspirin given hydrolysis sensitivity.
- Capsule:Gelatin or HPMC shells containing granules or powder offer taste masking and dose flexibility. Niche positioning in US compounding pharmacies for customized strength requirements.
- Powder:Bulk acetylsalicylic acid for extemporaneous compounding or effervescent preparation. Japanese home care settings utilize sachet formats for precise titration in elderly patients.
- Granule:Intermediate processing form for subsequent tableting or direct-to-patient sachet packaging. German manufacturers employ fluid-bed granulation to improve compressibility and content uniformity.
Tablets command the largest share; liquid formulations climb the fastest as geriatric and pediatric accessibility requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany and Switzerland commands premiums three to four times above export parity from Chinese API hubs. This asymmetry reflects divergent regulatory stringency, brand equity accumulation, and distribution channel control across mature versus emerging pharmaceutical markets.
United States
FDA label revisions for antiplatelet therapy drive prescription-to-OTC channel shifts among chronic cardiovascular patients. The Agency's ongoing updates to bleeding-risk warnings constrain primary prevention marketing claims. Cardinal Health and McKesson distribution networks concentrate purchasing leverage in the Northeast and Midwest pharmacy corridors.
Germany
EMA reassessments of aspirin risk-benefit ratios shape prescriber behavior across Bavarian and North Rhine-Westphalian cardiology practices. REACH registration requirements for acetylsalicylic acid intermediates tighten documentation burdens on API importers. Heidelberg and Frankfurt pharmaceutical clusters accelerate dual-sourcing strategies to mitigate supply authorization delays.
China
NMPA generic consistency evaluation requirements filter substandard domestic manufacturers while elevating quality benchmarks for export-oriented production. Government health initiatives broaden primary care drug access in rural provinces. Zhenjiang and Shandong industrial zones scale active pharmaceutical ingredient output to capture expanding Asia-Pacific demand.
Japan
PMDA oversight maintains stringent bioequivalence standards for enteric-coated formulations prescribed in geriatric antiplatelet protocols. Aging demographics expand the addressable patient pool for secondary cardiovascular prevention. Osaka and Tokyo pharmaceutical manufacturing bases specialize in precision coating technologies for low-dose chronic regimens.
Brazil
ANVISA regulatory pathways govern import registration for API-dependent finished-dose formulators serving Latin American markets. Government-subsidized primary care programs channel aspirin through public health clinics in São Paulo and Minas Gerais. Direct-to-pharmacy distribution models disintermediate traditional wholesale layers in urban pharmacy consolidation zones.
Global Aspirin Market Competitive Landscape
Concentration sits with century-old brand equity holders and vertically integrated API specialists. The market structure tiers across premium-priced heritage pharmaceuticals, cost-optimized generic manufacturers, and bulk chemical exporters. Three archetypes dominate: legacy innovators commanding pharmacy shelf space, emerging-market scale players leveraging regulatory arbitrage, and Chinese API-integrated formulators compressing cost structures. Competitive moves center on backward integration into salicylic acid production and dual-market registration strategies spanning regulated and emerging economy approval pathways.
Within the heritage pharmaceutical tier, Bayer AG exemplifies brand-anchored premium positioning sustained through vertical control over salicylic acid supply chains. Sun Pharmaceutical Industries Ltd. occupies a position bridging regulated and emerging economy markets through dual-registration capabilities. Zhenjiang Gaopeng Pharmaceutical Co. Ltd. anchors the bulk API export trade, competing on cost-adjusted purity grades meeting USP and EP monographs.
| Leading Market Players |
|---|
| Allegiant Health |
| Mayne Pharma Group Limited |
| Bayer AG |
| Sun Pharmaceutical Industries Ltd. |
| Bal Pharma Limited |
| Cardinal Health |
| Perrigo Company plc |
| Zhenjiang Gaopeng Pharmaceutical Co. Ltd. |
| Par Pharmaceutical |
| Others |
Supply & Pricing Matrix
Ninety-day inventory cycles for pharmaceutical-grade salicylic acid determine margin capture across the aspirin value chain, linking Zhenjiang API stockpiles to German finished-dose pricing premiums. This lead-time band concentrates negotiating leverage among backward-integrated Chinese producers while forcing non-integrated formulators into spot-market exposure.
Pricing Analysis
The customization-premium spread between enteric-coated cardiovascular formulations and standard analgesic tablets reaches fourfold multiples in European pharmacy channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by coating technology and bioequivalence certification tier. Pricing pressure stems from NMPA generic consistency evaluation requirements compressing margins for substandard producers. Hospital procurement committees in Germany exhibit lowest price sensitivity; Indian retail pharmacy chains show highest.
Supply Chain Analysis
Acetic anhydride procurement from Shandong petrochemical clusters constitutes a chokepoint for non-integrated acetylsalicylic acid manufacturers. API production concentrates in China, India, and Germany; salicylic acid feedstock draws from Chinese phenolic resin byproduct streams and European dedicated synthesis. Supply chain risk centers on REACH registration authorization delays for acetylsalicylic acid intermediates. Distribution runs through Cardinal Health and McKesson networks in the United States, direct-to-pharmacy models in Brazil, and Jan Aushadhi public channels in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aspirin sits in early-cycle expansion as cardiovascular prophylaxis protocols penetrate Indonesian and Brazilian primary care systems previously dependent on acute intervention models.
For Market Incumbents: Shield market position by deepening captive salicylic acid production capabilities before NMPA bioequivalence standards filter marginal competitors. Acquire precision coating technology specialists in Japan to defend against direct oral anticoagulant substitution in stroke prevention. Prioritize dual-antiplatelet therapy continuity programs with German hospital pharmacists to lock in chronic regimen adherence. For New Entrants and Emerging Players: Anchor in Brazilian government-subsidized primary care expansion where ANVISA registration pathways favor API-dependent formulators with local distribution partnerships. Target dispersible tablet formats for geriatric community health programs in Mexico and Southeast Asia. Pursue direct-to-pharmacy distribution models that bypass wholesale markups in consolidated urban pharmacy zones. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across continuous manufacturing technology adoption, compressing barriers for regional formulators. Five-to-ten year viability favors acquirers of NMPA-certified Chinese API producers with existing USP/EP monograph compliance. Watch FDA antiplatelet guideline revision timing as the critical signal for prescription-to-OTC demand resegmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Salicylic Acid | Zhenjiang and Shandong producers collapse cost hierarchies through captive phenolic resin feedstock control. |
| Precision Coating Technology Acquisition | Osaka and Tokyo specialists enable gastroprotection premiums in Japanese and German cardiology markets. |
| Dual-Market Registration Strategy | Sun Pharmaceutical navigates FDA and NMPA pathways simultaneously to unlock volume scale. |
| Direct-to-Pharmacy Distribution | São Paulo and Jakarta urban consolidation creates buyer concentration bypassing traditional wholesale layers. |
| Pediatric Formulation Development | Liquid and powder variants capture dysphagia-driven switching in UK and Australian geriatric populations. |
Research Methodology
Cross-validation between API manufacturer production disclosures and hospital procurement database trends anchors the qualitative findings in this aspirin market assessment. Primary interviews with regulatory affairs leads at NMPA-certified producers, formulary directors at German cardiology practices, and procurement managers at Indian Jan Aushadhi clinics combine with secondary validation from FDA filings, EMA reassessment documents, and customs trade data. Bottom-up volume triangulation against top-down therapeutic indication sizing ensures segmentation integrity.
Sensitivity analysis across bioequivalence standard adoption rates and antiplatelet guideline revision scenarios frames the projection envelope. The analytical framework models product type, application indication, end-user channel, and regional regulatory cluster dimensions throughout the forecast period. CAGRs derive from patient pool epidemiology, dosing regimen persistence, and channel shift elasticity. Forecast inputs include NMPA generic consistency evaluation completion rates and REACH registration authorization timelines.
Material uncertainties — EMA bleeding-risk reassessment outcomes, acetic anhydride feedstock volatility, and direct oral anticoagulant label expansions — sit outside the modeled envelope. Forecasts reflect documented assumptions about guideline persistence and regulatory pathway stability. Practitioners should keep alternative scenarios live as cardiology society antithrombotic protocol revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Vitamins and Derivatives Market
Pharmaceutical Ingredients
Rizatriptan Market
Pharmaceutical Ingredients
Pharmaceutical Propellants Market
Pharmaceutical Ingredients
Tranexamic Acid API Market
Pharmaceutical Ingredients
Pharma-Grade Magnesium Trisilicate Market
Pharmaceutical Ingredients
Scopolamine Market
Pharmaceutical Ingredients
Oral Doxycycline Hyclate Market
Pharmaceutical Ingredients
Biologic Excipients Market
Pharmaceutical Ingredients
Pharmaceutical Grade Beta-Alanine Market
Pharmaceutical Ingredients
Cox 2 Inhibitors Market
Pharmaceutical Ingredients
Transdermal Drugs Market
Pharmaceutical Ingredients
Antibiotics API Market
Pharmaceutical Ingredients
Global Tacrolimus Market
Pharmaceutical Ingredients
Calcium Folinate for Injection Market
Pharmaceutical Ingredients
Active Ingredients Market
Pharmaceutical Ingredients
Asia-Pacific Dipeptide Peptidase 4 (DPP-4) Inhibitors Market