
 Saudi Arabia Active Pharmaceutical Ingredients (API) Market | 2026-2036
Saudi Arabia Active Pharmaceutical Ingredients (API) Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Active Pharmaceutical Ingredients (API) Market Analytics
Multi-source API procurement is expanding across Saudi pharmaceutical supply chains as manufacturers reduce import dependency. Saudi Chemical Co. leverages its chemical distribution network to anchor raw material access for domestic synthesis. SPIMACO sustains vertical integration through its dedicated Addwaeih API Plant, controlling critical production stages in-country. Tabuk Pharmaceutical Manufacturing Co. competes on specialized antibiotic intermediates, differentiating against standardized generic imports.
Active pharmaceutical ingredients constitute the biologically active components in drug formulations, synthesized through chemical or biotechnological processes with defined purity thresholds typically exceeding ninety-nine percent and specified impurity profiles under ICH Q3A guidelines. Their primary purpose is to deliver therapeutic efficacy within finished dosage forms across cardiovascular, oncology, and infectious disease treatments. Generic APIs dominate current volume flows, though biologics represent the fastest-expanding margin pool as monoclonal antibody demand accelerates within Saudi oncology protocols. Specialty chemicals and high-potency intermediates concentrate value capture, with cardiovascular therapy APIs sustaining the largest installed prescription base across the Kingdom's hospital networks.
SFDA enforces GMP alignment with ICH Q7 guidelines for active substance manufacture, while the Saudi Food and Drug Authority's bioequivalence requirements shape import substitution incentives for locally produced APIs. The National Transformation Program's pharmaceutical localization mandates, administered through the Ministry of Investment, condition market access and procurement preferences on domestic manufacturing presence. Stakeholders must monitor evolving pharmacovigilance reporting obligations and API master file submission protocols as regulatory convergence with PIC/S standards advances.
Market Dynamics
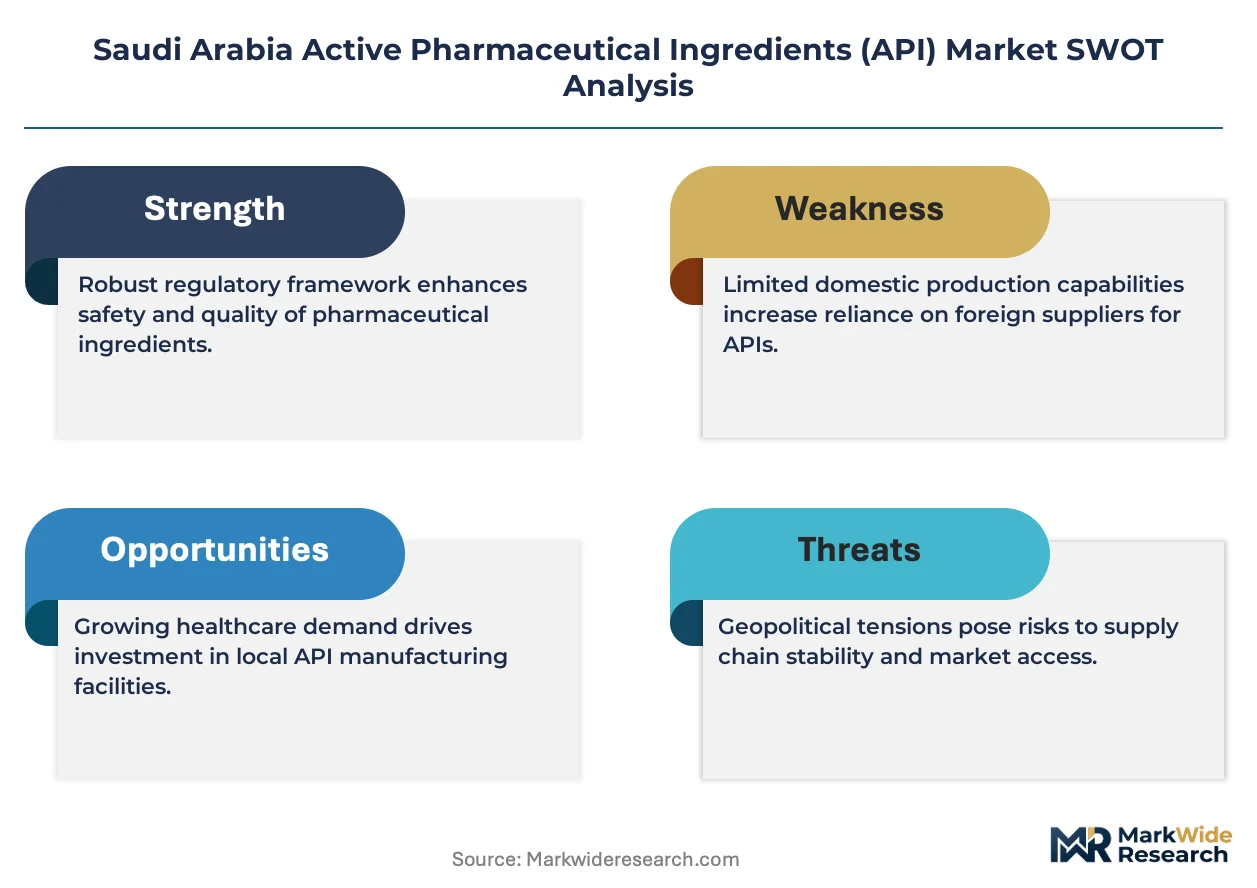
Saudi Arabia's API sector faces intensifying pressure from Vision 2030 localization mandates, which are compressing import timelines while domestic synthesis capacity lags demand growth. SFDA quality convergence with PIC/S standards is simultaneously raising compliance thresholds for both local manufacturers and foreign suppliers seeking market access.
Growth Catalysts
- Vision 2030 Pharmaceutical Localization:The National Transformation Program mandates progressive domestic sourcing quotas for public procurement, creating guaranteed offtake for local API producers. Hospital networks in Riyadh and Jeddah must now document local content percentages.
- SFDA-PIC/S Alignment:Regulatory harmonization with international GMP standards is accelerating foreign technology transfer partnerships. European and Indian manufacturers are establishing technical collaboration agreements to maintain market access.
- Biologics Infrastructure:Monoclonal antibody manufacturing capabilities are expanding in King Abdullah Economic City's biotech zones. Cold-chain fermentation facilities are attracting specialized workforce migration from established Asian biotech hubs.
Market Restraints
- Feedstock Import Dependency:Critical starting materials for antibiotic synthesis remain concentrated in Chinese and Indian chemical parks. Saudi manufacturers face 60-90 day supply lead times for fermentation media and specialized solvents.
- Specialized Talent Scarcity:Industrial-scale bioprocess engineers and analytical method developers command premium compensation packages. Local universities produce insufficient graduates with cGMP manufacturing experience.
- Capital Equipment Lead Times:Stainless steel bioreactors and isolator systems for high-potency compounds require 18-24 month delivery schedules from European vendors. Project timelines extend beyond financing covenant periods.
Strategic Opportunities
- Red Sea Corridor Export Hub:Saudi Arabia's geographic position offers API transshipment advantages to East African and Levantine markets. MENA regulatory alignment initiatives are reducing duplicate registration burdens.
- Continuous Flow Chemistry Adoption:Modular microreactor platforms are enabling smaller-batch, higher-flexibility production for oncology APIs. This technology convergence reduces solvent waste and accelerates process validation.
- Public-Private Partnership Models:The Ministry of Investment's pharmaceutical sector incentives include land allocation and utility subsidies for integrated API-to-dosage-form facilities. Joint ventures with technology holders secure process know-how transfer.
Industry Challenges
- SFDA Master File Submission Complexity:API registration dossiers require extensive impurity characterization and stability data. Smaller manufacturers lack in-house regulatory affairs capacity to navigate evolving documentation requirements.
- Legacy Quality System Upgrades:Existing chemical synthesis operations must retrofit facilities for ICH Q7 compliance. Computerized system validation for electronic batch records demands significant IT infrastructure investment.
- Skilled Technician Retention:Experienced fermentation operators and QC analysts receive competitive offers from Gulf neighbors. Training programs at Saudi universities require 2-3 year maturation before producing job-ready graduates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Active Pharmaceutical Ingredients (API) Market |
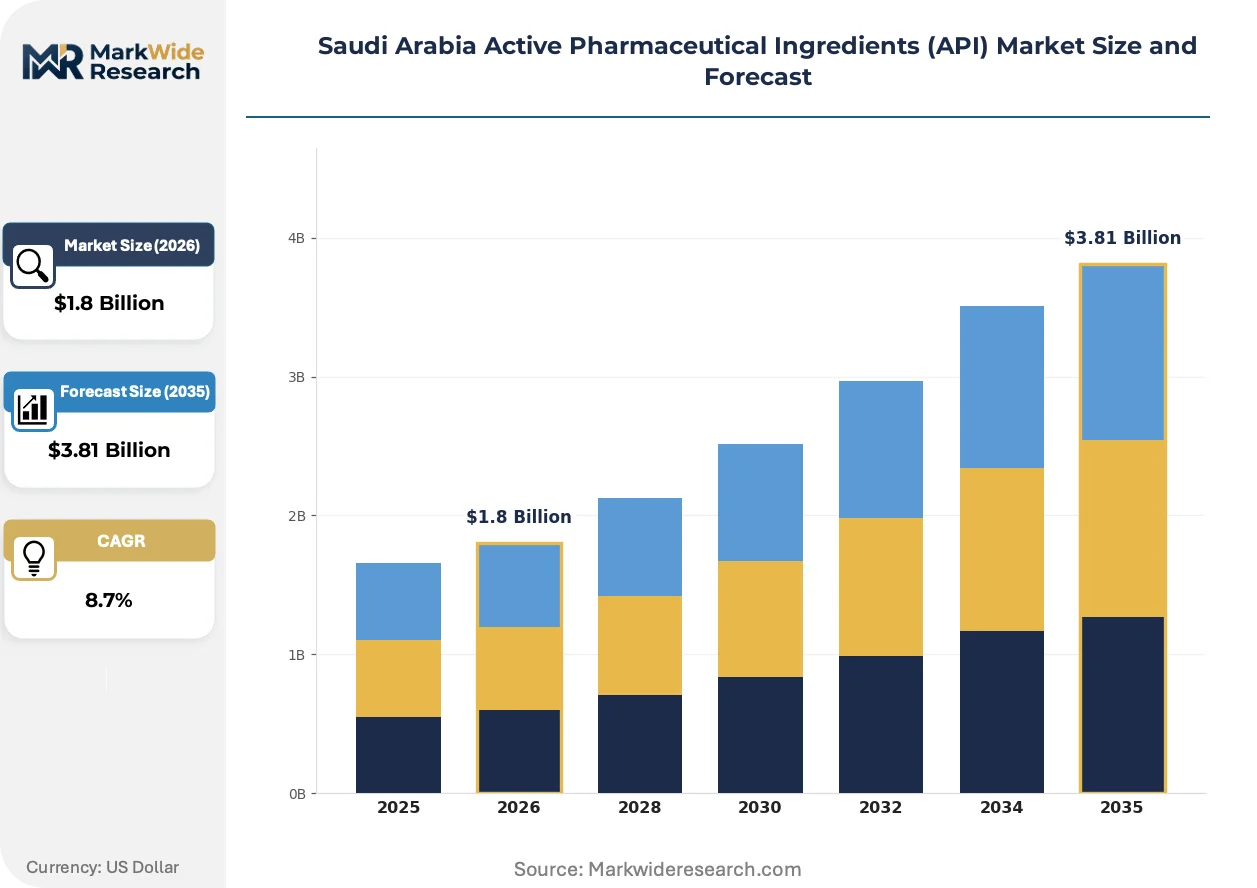
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Generic APIs, Specialty Chemicals, Intermediates Therapy Area: Cardiovascular, Oncology, Neurology, Antibiotics Form: Solid, Liquid, Semi-solid, Gas End User: Pharmaceutical Companies, Contract Manufacturers, Research Institutions, Hospitals |
| Companies Covered | Saudi Chemical Co., Riyadh Pharma, Saudi Pharmaceutical Industries & Medical Appliances Corp (SPIMACO), Julphar Gulf Pharmaceutical Industries, Hikma Pharmaceuticals, Tabuk Pharmaceutical Manufacturing Co., Sudair Pharmaceutical Co., SPIMACO Addwaeih API Plant, Jamjoom Pharmaceuticals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Active Pharmaceutical Ingredients (API) Market Evolving Landscape
Continuous processing technologies and regulatory data harmonization are compressing traditional API development timelines. Saudi manufacturers are adopting modular platforms to balance localization requirements against capital constraints.
Continuous flow chemistry is modularizing batch pharmaceutical synthesis into interconnected unit operations. Domestic manufacturers in Riyadh's industrial clusters are piloting microreactor systems for cardiovascular API intermediates. This technology is modularizing quality control into inline PAT analytics, reducing offline testing bottlenecks and accelerating release timelines.
SFDA's implementation of ICH Q3D elemental impurity guidelines is forcing reformulation of established metal catalyst processes. Manufacturers must resubmit dossiers with revised specification limits and validated purification steps. High-volume generic APIs face the steepest compliance costs, favoring producers with dedicated analytical development teams.
Hospital procurement consortia are consolidating API sourcing decisions through centralized tendering platforms. The Ministry of Health's unified purchasing system is displacing fragmented hospital-level contracting for essential medicines. Oncology and infectious disease therapeutic categories show the most visible concentration, with single-supplier agreements replacing multi-vendor arrangements.
Saudi Arabia Active Pharmaceutical Ingredients (API) Market Segmentation
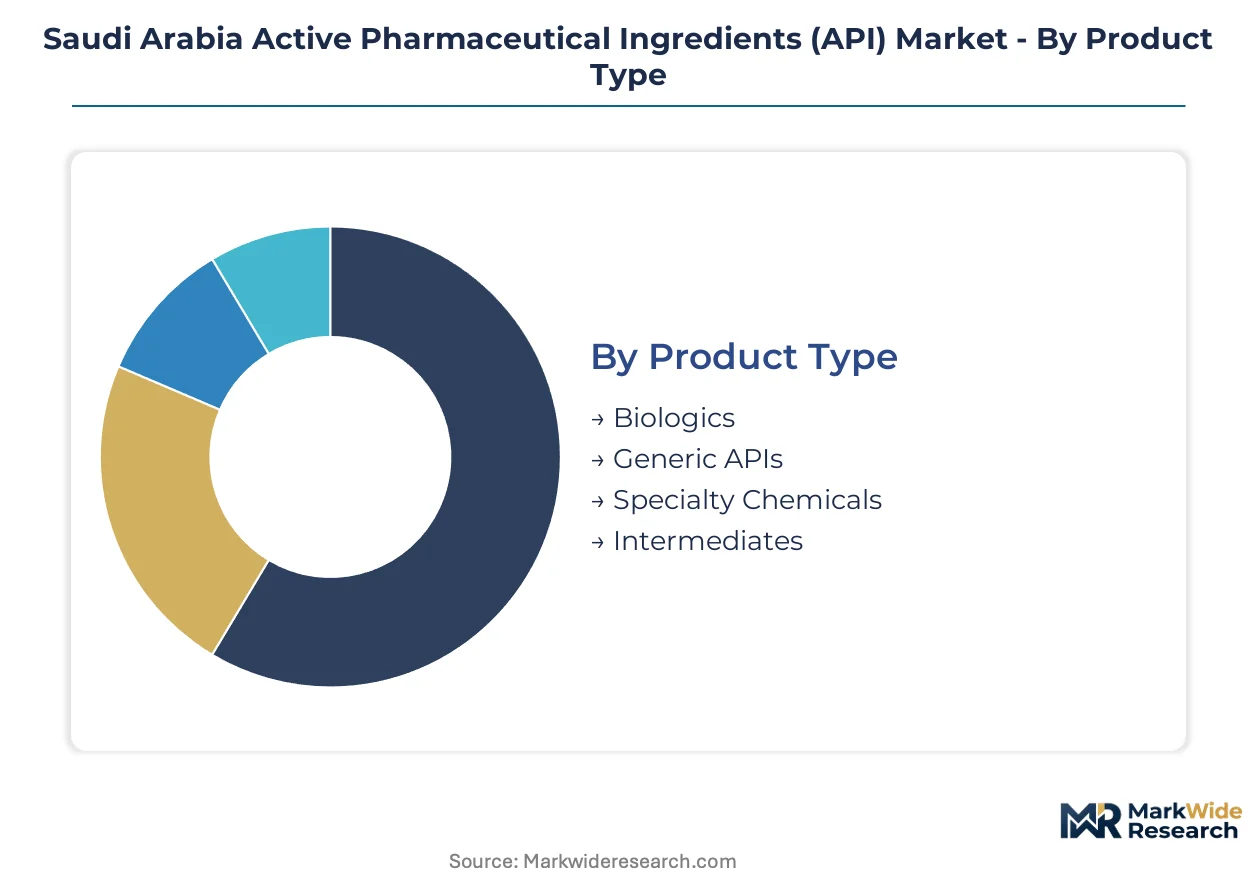
Segmentation in Saudi Arabia's API market exposes how regulatory pathways, manufacturing complexity, and end-use requirements fragment procurement strategies across the Kingdom's pharmaceutical supply chain. Each dimension reveals distinct compliance burdens and localization incentives that shape competitive positioning.
Product Type:
SFDA certification intensity varies sharply across product types, with biologics requiring extensive cell-line characterization and viral safety documentation while generic APIs navigate abbreviated bioequivalence pathways.
- Biologics:Recombinant proteins and monoclonal antibodies manufactured through mammalian or microbial fermentation demand cold-chain infrastructure and specialized containment facilities. Demand concentrates in King Abdullah Economic City's biotech zones as oncology treatment protocols expand within Saudi hospital networks. The SFDA mandates extensive viral clearance validation and real-time stability monitoring for these products.
- Generic APIs:Small-molecule compounds with established pharmacopeial monographs dominate volume flows through Riyadh's pharmaceutical industrial clusters. These products face compressed margins but benefit from streamlined registration through the SFDA's bioequivalence reference standards. Domestic manufacturers prioritize cardiovascular and antibiotic generics to meet National Transformation Program localization quotas.
- Specialty Chemicals:High-potency intermediates for oncology synthesis require isolator technology and containment infrastructure.
- Intermediates:Penultimate chemical precursors feed into downstream API finishing operations, with antibiotic building blocks commanding particular attention from Tabuk-based manufacturers.
Generic APIs sit at the top of the volume ranking, with biologics climbing the fastest.
Therapy Area:
Cost tier differentiation separates mass-market chronic disease treatments from premium oncology and neurology compounds requiring specialized manufacturing environments.
- Cardiovascular:Statins, beta-blockers, and antihypertensive APIs constitute the largest installed prescription base across Saudi Arabia's Ministry of Health hospital networks. These products sustain high-volume, low-margin production economics that favor continuous processing adoption in Riyadh's industrial clusters.
- Oncology:Cytotoxic APIs and targeted therapy intermediates command premium pricing and require high-containment manufacturing infrastructure. Demand accelerates within specialized cancer centers in Jeddah and Riyadh as treatment protocols align with international oncology guidelines.
- Neurology:Central nervous system APIs face complex formulation challenges and extended bioequivalence study timelines.
- Antibiotics:Beta-lactam and macrolide APIs remain critical for infectious disease management, with domestic manufacturers targeting penicillin and cephalosporin intermediates for import substitution.
Cardiovascular commands the largest addressable patient population, while oncology gains share fastest through specialized hospital procurement channels.
Form:
Manufacturing maturity and supply chain complexity stratify across physical states, with solids dominating established production and liquids requiring more sophisticated handling infrastructure.
- Solid:Crystalline powders and granulated intermediates constitute the predominant API format for oral dosage manufacturing, with tableting-grade specifications driving quality requirements in domestic facilities.
- Liquid:Solution and suspension APIs for parenteral formulations demand aseptic processing capabilities and specialized container closure systems.
- Semi-solid:Cream and ointment bases for dermatological applications require specialized emulsification equipment and stability testing protocols.
- Gas:Inhalation anesthetics and medical gas APIs occupy a niche segment with stringent purity and cylinder filling requirements.
Solid APIs anchor production volume, with liquid formats expanding most quickly through injectable therapy demand.
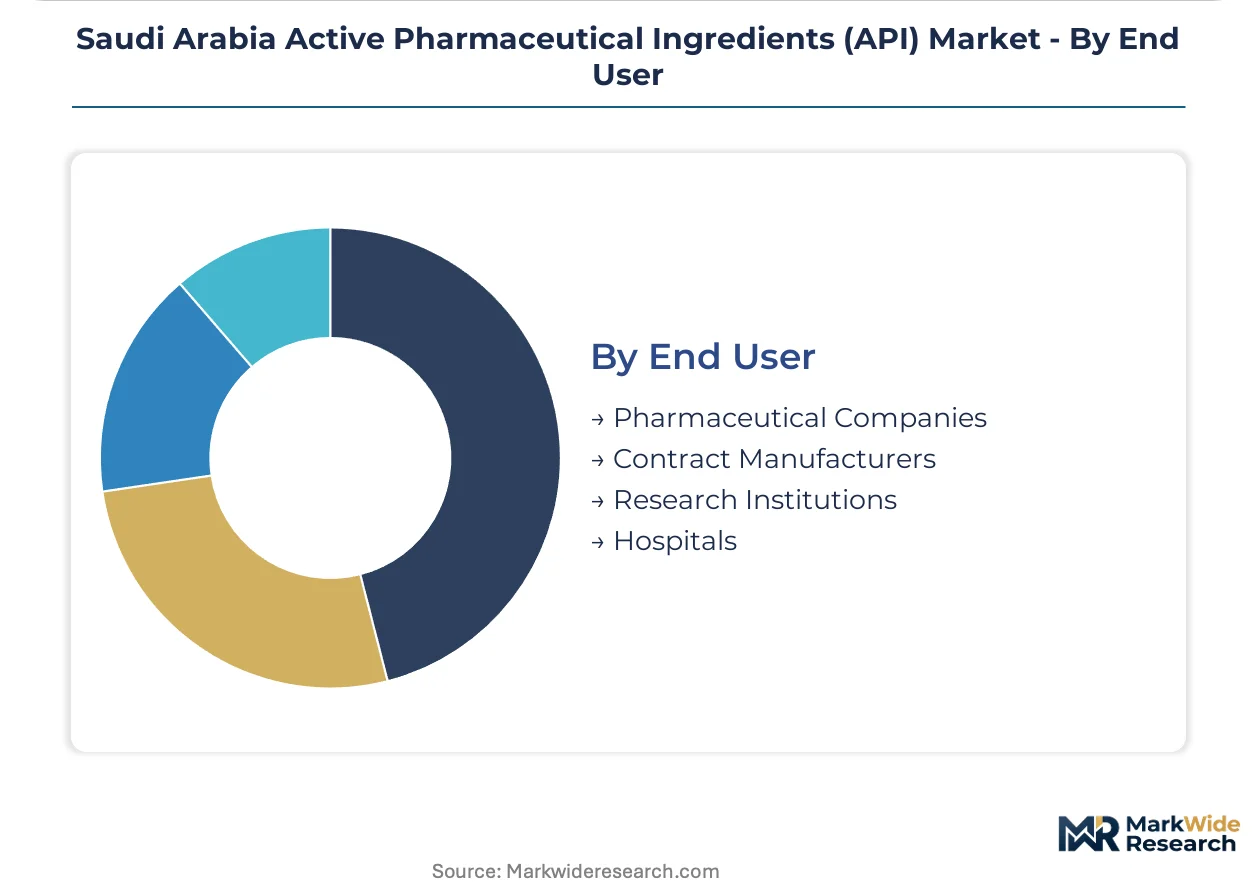
End User:
Customer type determines procurement scale and technical specification intensity, with pharmaceutical companies driving standardization while research institutions demand flexible batch sizes.
- Pharmaceutical Companies:Integrated manufacturers like SPIMACO and Tabuk Pharmaceutical Manufacturing Co. source APIs for captive formulation operations, prioritizing vertical control over critical supply chains. These buyers negotiate long-term supply agreements with documented local content percentages to satisfy Vision 2030 procurement mandates.
- Contract Manufacturers:CDMO facilities in Jeddah's emerging biotech zones purchase APIs on behalf of international clients, requiring dual regulatory compliance with SFDA and origin-country standards.
- Research Institutions:Academic medical centers and clinical trial organizations procure small-batch APIs for investigator-initiated studies and bioequivalence research.
- Hospitals:Ministry of Health consolidated purchasing platforms increasingly direct API sourcing decisions through centralized tendering for essential medicines.
Pharmaceutical companies dominate procurement volume, with contract manufacturers expanding most rapidly through biologics outsourcing agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions where cost-of-compliance gaps favor local manufacturing over import dependency. Saudi Arabia's API sector attracts investment as SFDA alignment with PIC/S standards narrows the regulatory distance to European markets while maintaining lower operational costs than Western manufacturing bases.
Riyadh
Riyadh anchors domestic API synthesis through King Salman Park's pharmaceutical industrial cluster and SPIMACO's integrated operations. The National Transformation Program channels procurement preferences toward manufacturers documenting local content percentages above mandated thresholds. King Abdullah Financial District's logistics infrastructure supports just-in-time feedstock delivery to synthesis facilities.
Eastern Province
Jubail's petrochemical complex supplies critical solvents and reagent-grade chemicals for antibiotic intermediate production. Saudi Aramco's downstream integration enables captive sourcing of fermentation media precursors that otherwise face 60-90 day import lead times. The King Fahd Industrial Port facilitates bulk chemical receiving for Tabuk Pharmaceutical Manufacturing Co.'s regional distribution network.
Jeddah
Jeddah's emerging biotech zones concentrate monoclonal antibody manufacturing capabilities targeting oncology protocols. King Abdullah Economic City's cold-chain infrastructure attracts bioprocess engineering talent from Asian hubs. The Red Sea port position offers transshipment advantages to East African markets seeking MENA-regulatory-aligned APIs.
Western Region
Makkah Province hospital procurement consortia drive demand for cardiovascular and diabetes APIs through Ministry of Health consolidated tendering platforms. Taif's altitude supports temperature-sensitive chemical synthesis operations requiring reduced cooling loads. Local manufacturers compete for essential medicines contracts against Indian and Chinese generic suppliers.
Saudi Arabia Active Pharmaceutical Ingredients (API) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biologics specialization and continuous processing technology partnerships. Market structure consolidates around integrated pharmaceutical companies with captive API operations, while contract manufacturers fragment the outsourced synthesis segment. Three archetypes dominate: vertically integrated domestic conglomerates, regional generics specialists, and technology-licensing joint ventures. Capacity expansion and strategic technology transfer agreements constitute the dominant competitive moves as foreign manufacturers secure market access through local partnerships.
Among Saudi-based integrated manufacturers, Saudi Chemical Co. and SPIMACO anchor the upstream chemical distribution and API synthesis tiers respectively. Tabuk Pharmaceutical Manufacturing Co. occupies a position within the specialized antibiotics intermediate segment. These entities exemplify the localization-driven competitive dynamic where Vision 2030 procurement mandates condition market access on demonstrated domestic manufacturing presence.
| Leading Market Players |
|---|
| Saudi Chemical Co. |
| Riyadh Pharma |
| Saudi Pharmaceutical Industries & Medical Appliances Corp (SPIMACO) |
| Julphar Gulf Pharmaceutical Industries |
| Hikma Pharmaceuticals |
| Tabuk Pharmaceutical Manufacturing Co. |
| Sudair Pharmaceutical Co. |
| SPIMACO Addwaeih API Plant |
| Jamjoom Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Bioprocess engineer scarcity in King Abdullah Economic City widens the spread between premium biologics pricing and economy-tier generic APIs, as labor-cost differentials compound with cold-chain infrastructure requirements to stratify procurement tiers across Saudi hospital networks.
Pricing Analysis
Distributor margins for imported APIs compress pricing power at the hospital procurement tier, where Ministry of Health consolidated tendering enforces volume-scale discounts. Three-tier pricing structure across premium biologics, standard generics, and economy-tier antibiotics separates products by SFDA certification intensity and viral clearance validation requirements. Pricing pressure stems from Indian and Chinese generic exporters competing on bioequivalence reference standards. Public hospital procurement platforms exhibit highest price sensitivity, while specialized oncology centers accept premium tiering for high-containment manufactured intermediates.
Supply Chain Analysis
Single-source vulnerability sits with Chinese fermentation media suppliers, where 60-90 day lead times for antibiotic synthesis precursors tether Saudi manufacturers to distant chemical parks. Critical starting materials draw from India, China, and specialty European vendors for high-potency oncology intermediates. Kharj-based chemical distributors and Jubail petrochemical complexes feed downstream synthesis operations, though reagent-grade solvents remain import-dependent. Tariff exposure through Red Sea shipping lanes compounds logistics risk for temperature-sensitive biologics. Distribution runs through Saudi Chemical Co.'s anchored distribution network into Riyadh and Jeddah pharmaceutical clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's API market offers margin expansion through continuous flow chemistry adoption, which reduces solvent waste and validation timelines while enabling premium pricing for oncology intermediates manufactured under ICH Q7 alignment.
For Market Incumbents: To counter Indian generic exporters capturing Ministry of Health tender volume, SPIMACO and Tabuk Pharmaceutical Manufacturing Co. should deepen backward integration into penicillin and cephalosporin intermediates while securing dedicated analytical development teams for ICH Q3D elemental impurity compliance. Capacity addition in King Abdullah Economic City's biotech zones anchors biologics margin pools against commoditization pressure. For New Entrants and Emerging Players: The 40-60% price-point gap between premium monoclonal antibodies and economy-tier cardiovascular generics creates entry space for modular microreactor platforms targeting mid-tier oncology APIs. Jeddah's emerging CDMO facilities represent the most penetrable geography, with contract manufacturing for European technology holders offering validated go-to-market positioning through dual SFDA-PIC/S compliance. For Investors and Strategic Acquirers: European and Indian pharmaceutical manufacturers seeking PIC/S-aligned market access are the most active acquirers in this space, driving joint venture premiums for domestic synthesis capabilities. Targets with dedicated API master file submission capacity and existing SFDA bioequivalence dossiers command strategic value. The signal to watch is Ministry of Investment land allocation announcements for integrated API-to-dosage-form facilities, which indicate public-private partnership momentum and guaranteed offtake commitment.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Chemistry Adoption | Modular microreactor platforms in Riyadh clusters reduce solvent waste and accelerate oncology API validation timelines. |
| SFDA-PIC/S Alignment Investment | Regulatory harmonization secures European technology transfer partnerships and maintains market access for foreign suppliers. |
| Biologics Infrastructure Buildout | Cold-chain fermentation facilities in King Abdullah Economic City attract specialized workforce migration from Asian hubs. |
| Backward Integration into Intermediates | Captive penicillin and cephalosporin precursor production reduces 60-90 day Chinese import lead time exposure. |
| Public-Private Partnership Formation | Ministry of Investment land allocation and utility subsidies secure joint venture positioning for integrated manufacturing. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with SFDA regulatory affairs leads, pharmaceutical plant managers at SPIMACO and Tabuk facilities, Ministry of Health procurement officers, and bioprocess engineering directors at King Abdullah Economic City with secondary validation against SFDA master file submission databases, Saudi Customs import records, and National Transformation Program pharmaceutical sector incentive disclosures. Bottom-up capacity assessments and top-down procurement flow analysis triangulated market sizing.
Segment-weighting applied therapy area, product type, and manufacturing form dimensions across the projection horizon, with cardiovascular, oncology, and infectious disease categories receiving distinct growth coefficients. CAGRs derived from installed prescription base analysis, hospital procurement tender aggregation, and biologics protocol adoption curves. Forecast inputs incorporated Vision 2030 localization quota enforcement timelines and SFDA-PIC/S convergence implementation phases.
The model assumes a particular technology adoption path; alternative pathways for continuous flow chemistry modularization would alter the outlook if European equipment vendor delivery schedules extend beyond financing covenant periods or if fermentation media precursor sourcing diversifies to regional petrochemical integration faster than projected. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Large Molecule Drug Substance CDMO Market
Pharmaceutical Ingredients
Fixed-Dose Combination Drugs Market
Pharmaceutical Ingredients
Folinic Acid Market
Pharmaceutical Ingredients
Fosfomycin Trometamol Powder Market
Pharmaceutical Ingredients
Global Dexamethasone Market
Pharmaceutical Ingredients
Pharmaceutical Glycerine Market
Pharmaceutical Ingredients
Calcium Citrate Market
Pharmaceutical Ingredients
Pharmaceutical Excipients for Taste Masking Market
Pharmaceutical Ingredients
Small-Molecule Injectable Drugs Market
Pharmaceutical Ingredients
Celecoxib API Market
Pharmaceutical Ingredients
Sennosides Market
Pharmaceutical Ingredients
Antibiotics API Market
Pharmaceutical Ingredients
Global Active Pharmaceutical Ingredients CDMO Market
Pharmaceutical Ingredients
Calcium Gluconate Market
Pharmaceutical Ingredients
North America Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
MEK Inhibitors Market