
 Injection Mold Hot Runners Market | 2026-2036
Injection Mold Hot Runners Market Size, Share, and Industry Trends Forecast 2026-2036
Injection Mold Hot Runners Market Insights
Medical device contract manufacturers is reorganizing procurement priorities toward hot runner systems that deliver tighter cavity-to-cavity balance and reduced validation cycles. Husky Injection Molding Systems Ltd. leverages its integrated controller-to-nozzle architecture to dominate high-cavitation medical applications. Mold-Masters anchors North American demand through its extensive service technician network and rapid spare parts fulfillment. Yudo Group competes aggressively on valve gate customization for Asian electronics molders seeking sub-second cycle times.
Injection mold hot runners are thermally managed manifold assemblies that deliver molten polymer directly to mold cavities without solidified sprue or runner waste, typically operating at temperatures between 200°C and 400°C depending on resin chemistry, with nozzle tip orifices precision-machined to 0.5mm tolerances for micro-molding applications. Valve gate technology leads unit shipments due to its ability to eliminate vestige on cosmetic surfaces demanded by consumer electronics and automotive interior buyers. Indirect heating configurations sustain margin pools in large automotive bumper and dashboard molds where thermal uniformity across wide manifold spans determines part dimensional stability. Direct heating is displacing legacy approaches in thin-wall packaging as processors seek faster color change cycles and reduced energy consumption per million shots.
The US FDA's quality system regulation for medical device manufacturing components shapes validation documentation requirements that hot runner suppliers must provide for mold qualification protocols. REACH restrictions on bisphenol-A and phthalate-containing compounds in the EU are forcing resin reformulations that demand revised heater and thermocouple material compatibility testing. China's GB standards for food-contact plastics and SAMR product quality enforcement create parallel certification tracks for suppliers serving multinational brand owners with dual-region production footprints. Stakeholders must monitor how polymer recycling mandates in multiple jurisdictions alter melt rheology assumptions embedded in existing hot runner flow simulation software and nozzle design libraries.
Market Dynamics
Valve gate technology is compressing cycle times across automotive and electronics molding, while REACH chemical compliance and China's GB standards force simultaneous heater material redesigns and validation protocol overhauls.
Growth Catalysts
- Automotive lightweighting mandates:Tier-one suppliers in Germany's Stuttgart corridor are specifying hot runners for interior component consolidation, eliminating secondary assembly steps.
- REACH chemical restrictions:ECHA's bisphenol-A and phthalate limitations are accelerating resin reformulations that require new thermocouple compatibility testing, expanding supplier service revenue.
- Medical device validation:FDA quality system regulations for mold qualification protocols are locking in hot runner specifications with documented cavity-to-cavity balance performance.
Market Restraints
- Copper and nickel price volatility:Heater element raw material swings compress margin pools for manifold manufacturers without captive metal sourcing.
- Precision machining concentration:Swiss and German tooling clusters control sub-micron nozzle tip production, creating supply bottlenecks for high-cavitation medical molds.
- Legacy mold retrofit limitations:Cold runner-to-hot runner conversions face dimensional constraints in existing press tie-bar spacing, blocking upgrade paths.
Strategic Opportunities
- India packaging expansion:Food-contact plastics growth under FSSAI enforcement is creating first-time hot runner demand among domestic thin-wall container molders.
- Polymer recycling mandates:EU Green Deal recycled content targets are forcing melt rheology recalibration, opening nozzle design software upgrade cycles.
- Integrated controller architectures:Convergence of IoT temperature monitoring with predictive maintenance algorithms enables premium pricing for connected manifold systems.
Industry Challenges
- Thermal simulation expertise gaps:Mold flow analysis specialization for recycled resin viscosity curves remains scarce among regional service technician networks.
- Dual-region certification timelines:Simultaneous FDA and NMPA qualification documentation extends medical mold validation cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Injection Mold Hot Runners Market |
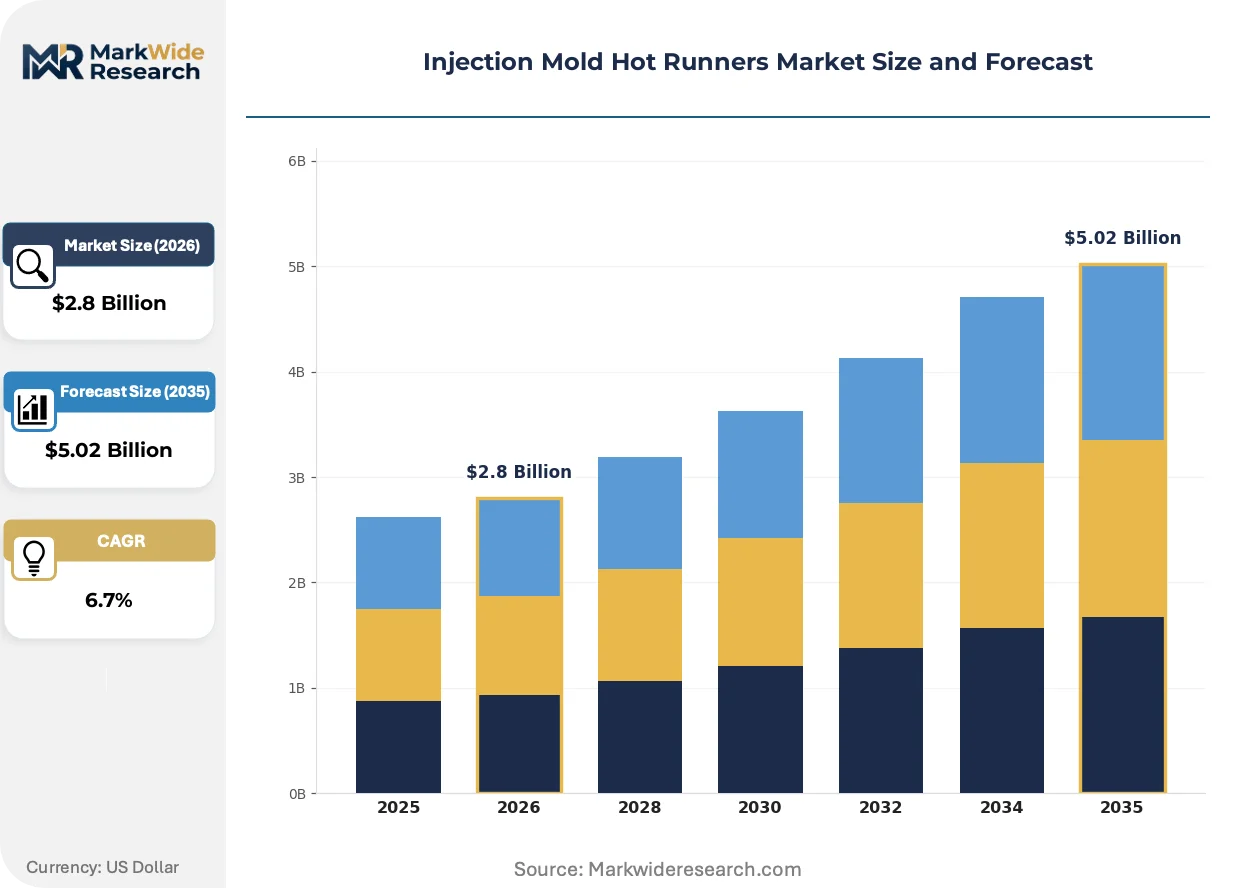
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Valve Gate, Open Gate, Hybrid, Coil, Cartridge Technology: Direct Heating, Indirect Heating, Electrical, Hydraulic, Pneumatic Application: Consumer Goods, Electronics, Packaging, Construction, Aerospace End User: Injection Molders, Tool Makers, Plastics Processors, Contract Manufacturers |
| Companies Covered | Husky Injection Molding Systems Ltd., Mold-Masters, Yudo Group, Synventive Molding Solutions, INCOE Corporation, HASCO Hasenclever GmbH + Co KG, EWIKON Heißkanalsysteme GmbH, GÜNTHER Heisskanaltechnik GmbH, Milacron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Injection Mold Hot Runners Market Trends and Innovations
Electrification of heating elements, regulatory chemical compliance, and buyer consolidation are restructuring how hot runner systems are specified, validated, and serviced across end-use verticals.
Direct heating architectures with embedded coil elements are supplanting external cartridge configurations in thin-wall packaging applications. European dairy and food container molders are adopting these systems for sub-90-second color change cycles. The technology is compressing energy consumption per million shots and enabling smaller processors to compete on multi-SKU flexibility.
REACH restrictions on halogenated flame retardants and heavy metal stabilizers are forcing heater sheath material substitutions. ECHA's substance of very high concern listings now cover several legacy thermocouple alloys. Medical and food-contact molders in the EU and exporting Asian suppliers are accelerating validation of ceramic-insulated alternatives to maintain market access.
Medical device contract manufacturers are consolidating supplier relationships around single-source validation partnerships. This behavior is displacing fragmented procurement across multiple hot runner vendors for different mold programs. The shift concentrates most visibly in Minnesota and Massachusetts clusters where FDA inspection frequency rewards documented process continuity.
Injection Mold Hot Runners Market Segmentation
Hot runner procurement patterns diverge sharply between domestic contract manufacturers serving regional automotive clusters and export-oriented molders supplying multinational electronics brands. Specification requirements for cavity balance, thermal uniformity, and validation documentation vary by end-use vertical, creating distinct segment performance profiles.
Type:
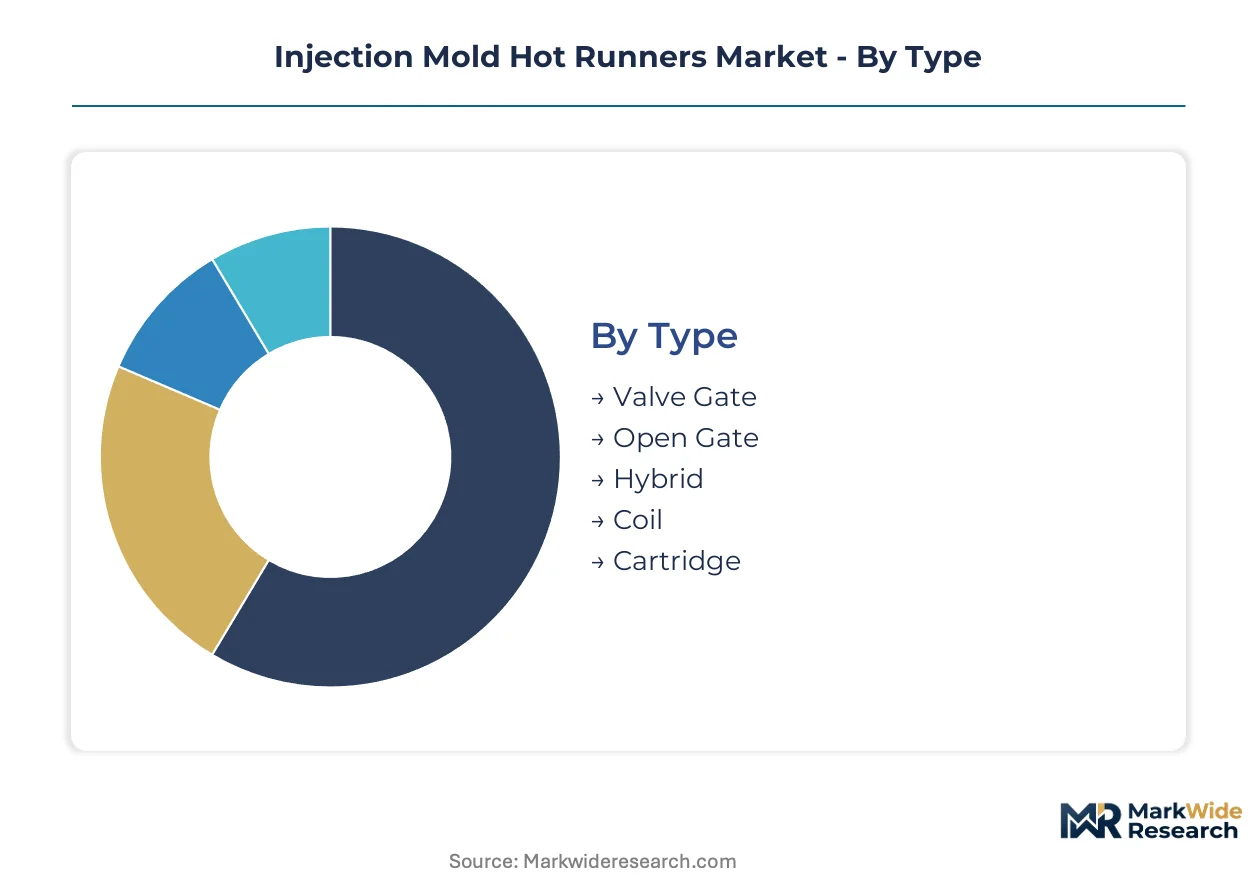
Valve gate systems dominate export-led demand from Asian electronics molders seeking cosmetic-grade surface finishes, while open gate configurations sustain domestic replacement cycles in established automotive supply corridors.
- Valve Gate:Precision-machined pin mechanisms eliminate vestige marks on visible surfaces. Demand concentrates among Chinese and South Korean electronics molders supplying consumer device housings where cosmetic standards reject any gate residue. Cycle time compression below two seconds drives specification priority.
- Open Gate:Simpler thermal tip designs deliver molten polymer through fixed orifices. German automotive interior specialists in Stuttgart specify these for structural components where surface aesthetics are secondary to material flow consistency and maintenance accessibility.
- Hybrid:Combines valve and open gate nozzles within single manifold assemblies for multi-cavity family molds. Tool makers serving medical device contract manufacturers favor this flexibility for validation-standardized production platforms.
- Coil:Embedded heating elements wrap manifold channels for uniform thermal distribution. Plastics processors in India's emerging packaging sector adopt these for first-time hot runner conversions from cold runner legacy systems.
- Cartridge:Replaceable heater inserts simplify field maintenance and reduce downtime. Contract manufacturers with limited in-house thermal engineering capacity specify these for operational risk mitigation.
Valve gate commands the established base. The steepest expansion runs through hybrid configurations serving medical validation requirements.
Technology:
Cost tier stratification separates premium direct heating architectures from standard indirect configurations, with actuation method selection determining aftermarket service revenue potential.
- Direct Heating:Embedded coil elements contact molten polymer directly, eliminating thermal lag. European dairy packaging molders deploy these for sub-90-second color change cycles that enable multi-SKU production economics.
- Indirect Heating:External cartridge heaters transfer thermal energy through manifold walls. Large automotive bumper molds in Germany require this approach for dimensional stability across wide manifold spans exceeding 800mm.
- Electrical:Solid-state controllers deliver precise temperature regulation with IoT connectivity. Electronics molders seeking predictive maintenance integration specify these for connected factory architectures.
- Hydraulic:Pressurized oil systems actuate valve gate pins with high closing force. Construction component molders processing glass-filled engineering resins specify these for wear resistance.
- Pneumatic:Compressed air drives pin actuation with faster response times. Cleanroom medical device manufacturers prefer these for contamination control and reduced fluid leak risk.
Indirect heating retains the installed base. The steepest expansion runs through electrical systems with integrated controller architectures.
Application:
Volume concentration in packaging and electronics masks margin dispersion, with aerospace and medical-adjacent consumer goods commanding premium specification tiers.
- Consumer Goods:Personal care and household product housings demand cosmetic surface quality. Valve gate penetration is highest here due to visible part aesthetics requirements.
- Electronics:Smart device and laptop chassis molding requires micro-precision nozzle tips. Asian contract manufacturers drive specification intensity for sub-0.5mm tolerance repeatability.
- Packaging:Thin-wall food containers and dairy products dominate unit shipment volumes. European and Indian processors prioritize energy efficiency and rapid color change capability.
- Construction:Pipe fittings and structural connectors tolerate lower cosmetic standards. Open gate systems sustain margin pools through standardized manifold configurations.
- Aerospace:Interior cabin components and structural brackets require flame-retardant resin compatibility. REACH chemical restrictions on halogenated compounds force heater material recertification.
Packaging commands the established base. The steepest expansion runs through electronics applications demanding precision micro-molding capability.
End User:
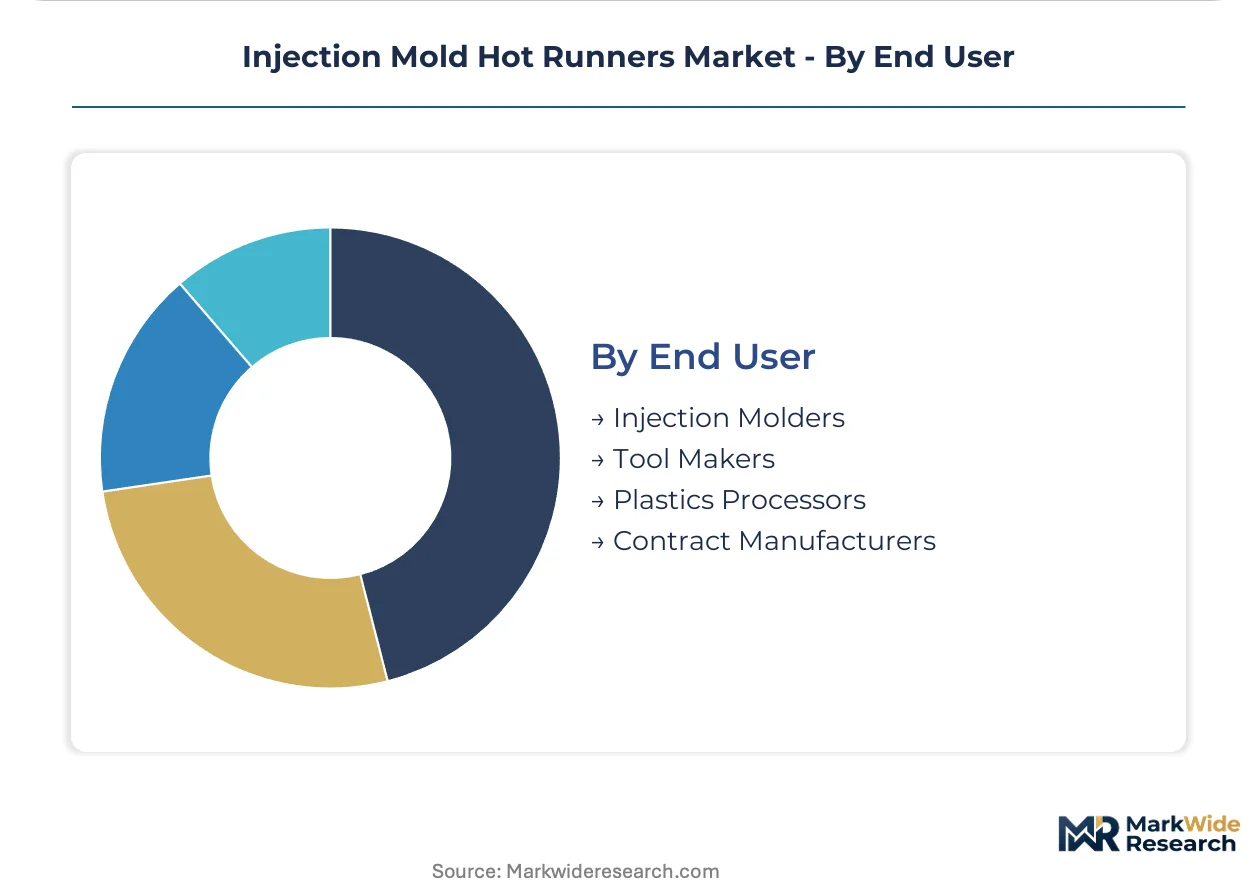
Customer type determines procurement sophistication, with injection molders driving specification and contract manufacturers consolidating supplier relationships around single-source validation partnerships.
- Injection Molders:Captive production facilities with dedicated press lines specify integrated controller-to-nozzle architectures. These buyers prioritize cavity-to-cavity balance documentation for process validation.
- Tool Makers:Independent mold builders serving multiple end-use verticals require flexible manifold configurations. Their procurement emphasizes rapid spare parts fulfillment and service technician network density.
- Plastics Processors:Compounders and resin suppliers with downstream molding operations focus on material compatibility testing. REACH and GB standard compliance drives heater sheath material selection.
- Contract Manufacturers:Medical device specialists in Minnesota and Massachusetts clusters are consolidating vendor relationships. FDA quality system regulation compliance rewards documented process continuity from single suppliers.
Injection molders command the established base. The steepest expansion runs through contract manufacturers consolidating validation-standardized supply relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube inland waterway corridor underwrites Germany's dominance in precision tooling logistics, while China's high-speed rail network enables just-in-time component delivery across the Yangtze manufacturing belt.
Germany
Automotive lightweighting mandates from Stuttgart OEMs are accelerating hot runner adoption for interior component consolidation. REACH chemical restrictions on bisphenol-A force heater sheath material recertification across the supply base. The precision tooling cluster around Stuttgart and Frankfurt anchors European demand for valve gate systems with sub-micron tolerances.
China
Electronics contract manufacturers in Dongguan and Shenzhen are specifying micro-precision nozzles for consumer device housings. GB standards on plastic product quality and SAMR enforcement create dual certification tracks for export-oriented molders. The Pearl River Delta concentration drives specification intensity for sub-second cycle times.
United States
Medical device contract manufacturers in Minnesota and Massachusetts are consolidating supplier relationships around single-source validation partnerships. FDA quality system regulations for mold qualification protocols lock in documented cavity-to-cavity balance requirements. The Twin Cities cluster rewards process continuity with intensified FDA inspection frequency.
India
Domestic thin-wall container molders are executing first-time hot runner conversions under FSSAI food-contact plastics enforcement. The country's packaging sector expansion creates demand for coil-based heating configurations with simplified maintenance protocols. Gujarat and Maharashtra industrial corridors concentrate emerging procurement from plastics processors.
South Korea
Electronics molders supplying smartphone and laptop chassis are driving specification intensity for micro-molding nozzle tips. MFDS medical device regulations and export compliance requirements parallel FDA validation documentation standards. The Gyeonggi-Seoul manufacturing belt concentrates demand for sub-0.5mm tolerance repeatability.
Injection Mold Hot Runners Market Competitive Landscape
Listed leaders compete with private specialists across integrated controller architectures and service network density. The vendor base stratifies into three tiers: multinational systems integrators with captive software capabilities, regional specialists with dense technician networks, and component fabricators focused on nozzle tip precision machining. Strategic moves concentrate on validation partnership consolidation with medical device contract manufacturers and predictive maintenance algorithm development for IoT-connected manifold systems.
Within the integrated systems tier, Husky Injection Molding Systems Ltd. and Mold-Masters occupy positions defined by controller-to-nozzle architecture dominance and North American service density respectively. Yudo Group represents the Asian specialist archetype competing on valve gate customization velocity. These three anchors illustrate how geographic origin and organizational structure map to distinct competitive positioning vectors across medical, automotive, and electronics end-use verticals.
| Leading Market Players |
|---|
| Husky Injection Molding Systems Ltd. |
| Mold-Masters |
| Yudo Group |
| Synventive Molding Solutions |
| INCOE Corporation |
| HASCO Hasenclever GmbH + Co KG |
| EWIKON Heißkanalsysteme GmbH |
| GÜNTHER Heisskanaltechnik GmbH |
| Milacron |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation agreements with German precision tooling clusters lock in both heater element supply access and eighteen-month price visibility for tier-one automotive suppliers. These contracts insulate manifold manufacturers from copper and nickel spot volatility while committing buyers to minimum volume thresholds that sustain Swiss nozzle tip production lines.
Pricing Analysis
Volume-discount tiering structures separate premium medical-grade systems with FDA validation documentation from standard automotive configurations and economy packaging units. Three-tier pricing stratification across certification levels reflects divergent thermocouple material costs and aftermarket service bundling intensity. Cost compression in economy tiers intensifies as Indian packaging processors enter first-time procurement cycles with limited technical specification capacity. Contract manufacturers in Minnesota and Massachusetts clusters exhibit lowest price sensitivity due to single-source validation partnership requirements.
Supply Chain Analysis
Switzerland and Germany anchor sub-micron nozzle tip precision machining for high-cavitation medical molds. Heater sheath production draws from Austrian and Italian specialty metal suppliers with REACH-compliant alloy certifications. Single-source vulnerability concentrates in Swiss carbide insert fabrication for micro-molding orifices below 0.5mm tolerance. Distribution runs through regional service technician networks with captive spare parts inventory positioned near Stuttgart, Dongguan, and Minneapolis industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Injection mold hot runners sit in early-cycle expansion as polymer recycling mandates across multiple jurisdictions force melt rheology recalibration and nozzle design software upgrade cycles.
For Market Incumbents: Secure validation partnership consolidation with medical device contract manufacturers in Minnesota and Massachusetts before FDA inspection frequency intensifies supplier switching costs. Deepen backward integration into ceramic-insulated thermocouple production to offset REACH-driven material substitution delays. Lock in captive supply of Swiss-machined nozzle tips through exclusive offtake arrangements with Stuttgart-area precision tooling clusters. For New Entrants and Emerging Players: Lead with coil-based heating configurations targeting India's FSSAI-driven packaging sector expansion in Gujarat and Maharashtra industrial corridors. India's thin-wall container molders executing first-time hot runner conversions represent the most penetrable buyer segment due to limited legacy equipment retrofit constraints. Establish rapid spare parts fulfillment partnerships with domestic Indian service networks as primary go-to-market anchor. For Investors and Strategic Acquirers: Regional specialists with dense technician networks and rapid spare parts fulfillment capabilities present acquisition targets with durable aftermarket revenue streams. Long-term viability hinges on IoT-connected manifold system penetration and predictive maintenance algorithm monetization. Watch for inflection signals in medical device contract manufacturer consolidation velocity around single-source validation partnerships.| Strategic Initiative | Industry Significance |
|---|---|
| Validation Partnership Consolidation | FDA quality system regulation compliance locks in multi-year supply relationships with documented cavity-to-cavity balance performance. |
| Ceramic-Insulated Thermocouple Certification | REACH substance of very high concern listings on legacy alloys force heater material recertification for EU market access. |
| IoT Controller Architecture Development | Integrated temperature monitoring with predictive maintenance algorithms enables premium pricing for connected manifold systems. |
| India Service Network Expansion | FSSAI food-contact plastics enforcement drives first-time hot runner demand among domestic thin-wall container molders. |
| Polymer Recycling Software Upgrade | EU Green Deal recycled content targets force melt rheology recalibration and nozzle design library updates. |
Research Methodology
Cross-validation between primary interviews with hot runner system procurement managers at tier-one automotive suppliers and secondary validation through customs trade data and SEC filings anchors the qualitative findings. Mold flow analysis specialists, medical device contract manufacturing quality directors, and plastics processor maintenance engineers provided operational perspective. Technical documentation from ECHA REACH substance listings, FDA quality system regulation guidance, and China's GB standards on plastic product quality supplied regulatory boundary conditions. Bottom-up shipment data triangulates against top-down end-use vertical spending patterns.
Sensitivity analysis around copper and nickel price volatility scenarios and medical device validation timeline compression informs the analytical framework across the projection horizon. Segmentation dimensions include gate type, heating technology configuration, end-use application, and customer procurement sophistication tier. CAGR derivation rests on installed base replacement cycles and penetration rate assumptions for emerging geographies. Industry-specific inputs incorporate polymer recycling mandate implementation schedules and precision machining capacity constraints in Swiss and German tooling clusters.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement intensity or abrupt raw material supply disruptions would require recalibration. Forecasts reflect documented assumptions regarding cavity-to-cavity balance specification trends and thermal simulation software adoption curves. Recalibration cycles align with material shifts in regulatory chemical restriction listings and polymer recycling content target revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
North America Medical Plastics Extrusion Market
Industrial Materials
Battery Separator Materials Market
Industrial Materials
Global Plastic Fasteners Market
Industrial Materials
Investment Casting Market
Industrial Materials
Industrial Strainers Market
Industrial Materials
Global Medical Plastics Extrusion Market
Industrial Materials
Noise Reduction Plastic Gear Market
Industrial Materials
Cork Material Market
Industrial Materials
Industrial Couplings Market
Industrial Materials
Saudi Arabia Industrial Insulation Market
Industrial Materials
Paint Knife Market
Industrial Materials
United States Ceramic Roller Bearings Market
Industrial Materials
Steel Cord Market
Industrial Materials
Petrochemical Fasteners Market
Industrial Materials
Ribbed Smoke Sheet Market
Industrial Materials
Polycarbonate Panels Market