
 North America Vinyl Chloride Monomer Market | 2026-2036
North America Vinyl Chloride Monomer Market Size, Share, and Industry Trends Forecast 2026-2036
North America Vinyl Chloride Monomer Market Intelligence
Modular supply arrangements for vinyl chloride monomer are realigning how construction and automotive buyers contract for volume. LyondellBasell Industries leverages its integrated Gulf Coast footprint to offer bundled chlor-alkali and VCM supply packages. Formosa Plastics Group anchors its North American position through backward integration into ethylene and chlorine production. Westlake Corporation competes by sustaining high-capacity utilization across its Louisiana and Kentucky manufacturing complexes.
Vinyl chloride monomer is an organochlorine compound with the formula C₂H₃Cl, produced industrially via thermal dehydrochlorination of ethylene dichloride at temperatures exceeding 400°C; it serves as the essential precursor for polyvinyl chloride resin manufacturing across building materials, consumer goods, and industrial applications. Polymer grade VCM dominates volume flows due to its direct feed into suspension and emulsion PVC processes for pipe and sheet extrusion. Specialty vinyl segments differentiate through higher purity specifications serving medical film and electrical coating applications where residual impurity thresholds fall below 50 ppm. The Pipes application anchors value capture given its structural link to municipal water infrastructure and residential construction cycles.
The US EPA enforces National Emission Standards for Hazardous Air Pollutants at chlor-alkali and VCM production facilities, while OSHA mandates workplace exposure limits for vinyl chloride at 1 ppm averaged over an eight-hour shift. State-level regulators in Texas and Louisiana layer additional permitting requirements on coastal petrochemical complexes, constraining greenfield expansion timelines. Canada’s PMRA evaluates residual monomer thresholds in PVC food-contact applications under the Pest Control Products Act, creating cross-border product standard divergence. Stakeholders must monitor how cumulative regulatory load affects capital deployment decisions across the US-Canada production base.
Market Dynamics
Integrated chlor-alkali complexes along the US Gulf Coast are consolidating feedstock access and emission compliance costs into fewer operational footprints, forcing buyers to renegotiate long-term offtake terms around bundled chemical supply rather than discrete VCM procurement.
Growth Catalysts
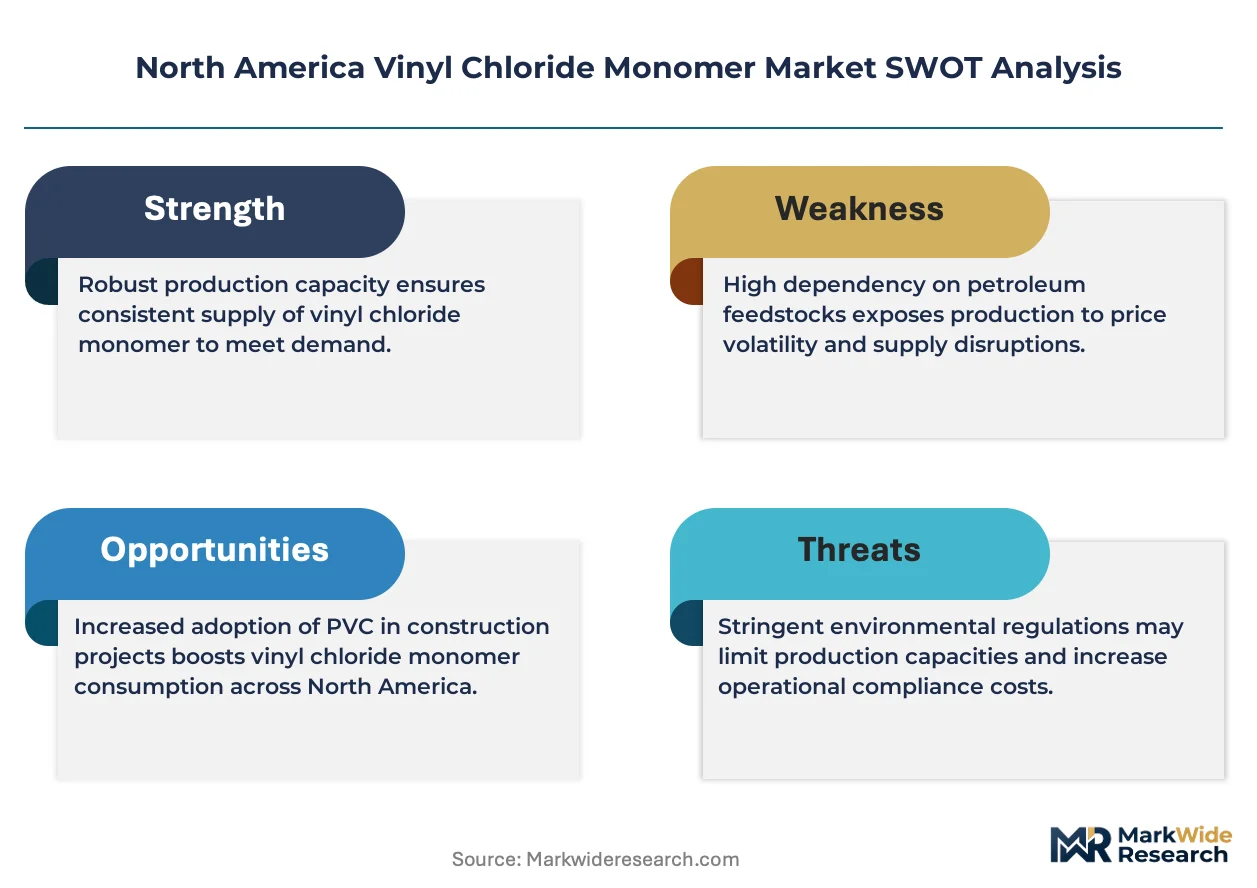
- EPA NESHAP tightening:Stricter air toxics thresholds at production facilities are accelerating capital deployment toward cleaner thermal dehydrochlorination processes, expanding addressable capacity for compliant producers.
- Municipal water infrastructure:Federal funding cycles for pipe replacement are pulling polymer-grade VCM into large-diameter PVC extrusion contracts across Texas and Louisiana procurement offices.
- Ethylene feedstock proximity:Crackers concentrated in the Gulf Coast petrochemical corridor are compressing delivered cost structures for EDC precursors.
Market Restraints
- Chlorine supply concentration:Three integrated producers control the majority of captive chlorine output, exposing buyers to coordinated maintenance outage schedules.
- Residual monomer thresholds:Health Canada's PMRA evaluates stricter limits on VCM traces in food-contact PVC than US FDA equivalents, fragmenting cross-border product qualification.
- Caustic soda co-production economics:Chlor-alkali margins tied to caustic demand volatility transmit directly to VCM cost floors, compressing producer flexibility during cyclical downturns.
Strategic Opportunities
- Medical-grade purity specifications:Specialty vinyl segments serving film and electrical coating applications command premium positioning where residual impurities fall below 50 ppm thresholds.
- OSHA exposure mandate alignment:Workplace limit enforcement at 1 ppm averaged over eight-hour shifts is differentiating certified producers in liability-sensitive buyer evaluations.
- Automotive interior substitution:PVC compounds displacing leather and thermoplastic olefins in seating and trim applications are opening incremental VCM offtake channels.
Industry Challenges
- Process safety engineering scarcity:Specialized expertise in high-temperature EDC cracking and VCM purification unit operation commands compensation premiums that inflate fixed cost structures.
- Legacy control system integration:Digital emissions monitoring upgrades required for EPA compliance are colliding with decades-old distributed control architectures at coastal complexes.
- Permitting timeline compression:Louisiana and Texas state environmental review processes for capacity modifications are extending project sanction-to-startup intervals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Vinyl Chloride Monomer Market |
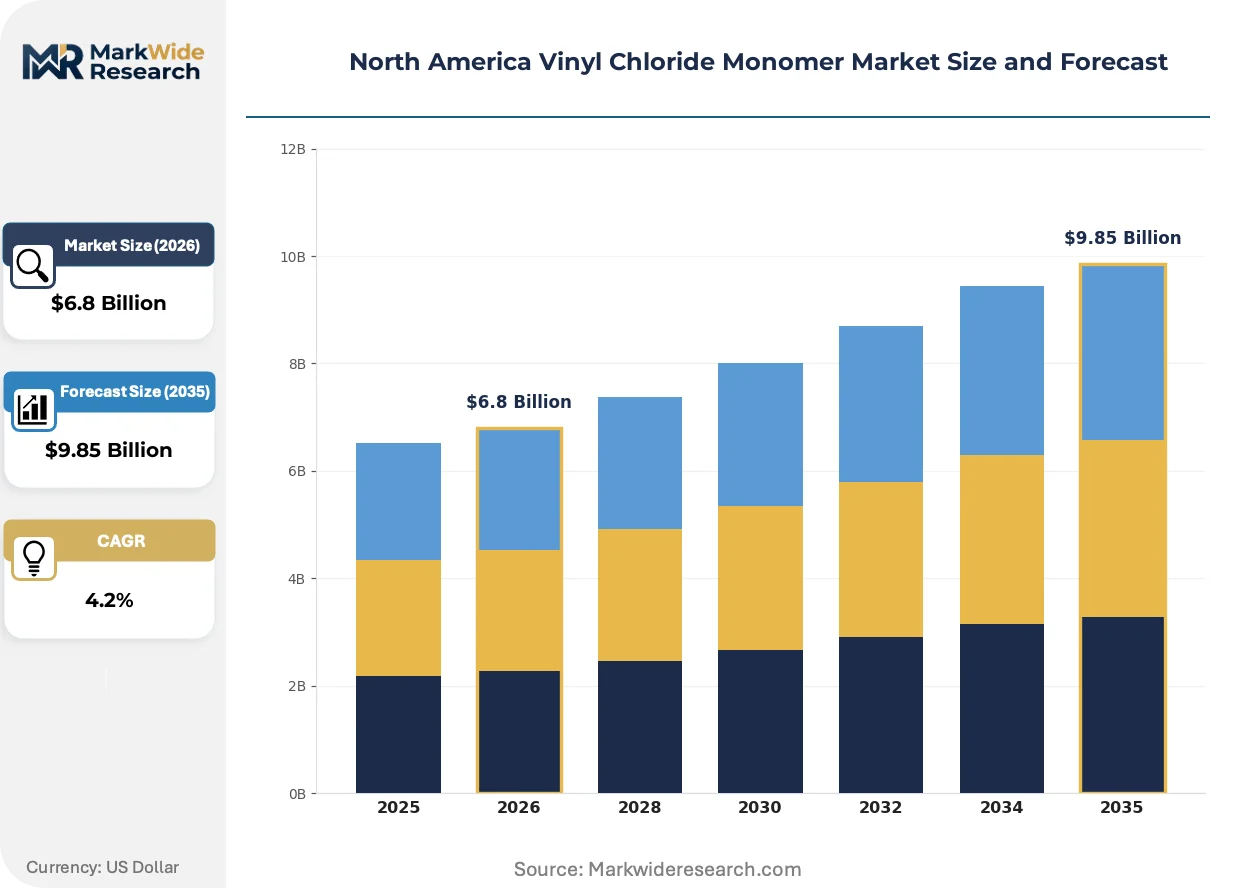
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Grade, Technical Grade, PVC Resin, Specialty Vinyl Application: Pipes, Sheets, Films, Coatings End User: Construction, Automotive, Packaging, Electrical Distribution Channel: Direct Sales, Distributors, Retail, Online |
| Companies Covered | LyondellBasell Industries, Formosa Plastics Group, Westlake Corporation, Nova Chemical, LG Chem, Occidental Chemical Corporation, BASF, Shin-Etsu Chemical, Olin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Vinyl Chloride Monomer Market Strategic Shifts & Innovations
Process intensification and emission control technologies are compressing the capital efficiency frontier for VCM production, while demand-side contracting models are migrating toward integrated chemical supply bundles.
Oxychlorination catalyst advances are absorbing incremental chlorine efficiency gains into single-train capacity expansions. Producers with existing Gulf Coast infrastructure are retrofitting these systems to avoid greenfield permitting delays. The technology is absorbing capital that would otherwise flow to new site development, entrenching incumbent positional advantages.
The US EPA's updated National Emission Standards for Hazardous Air Pollutants are forcing continuous monitoring upgrades across thermal dehydrochlorination units. Chlor-alkali facilities must now deploy real-time fenceline detection systems with quarterly reporting obligations. Coastal Texas complexes are responding by consolidating operations onto fewer, larger permitted footprints rather than distributing capacity across multiple sites.
Construction sector buyers are consolidating procurement authority into centralized supply chain functions that negotiate multi-year chlor-alkali-VCM-PVC bundles rather than discrete monomer spot purchases. Regional distributors serving residential pipe extruders are losing volume to direct mill relationships. Louisiana and Kentucky manufacturing corridors exhibit the most advanced bundle contracting penetration.
North America Vinyl Chloride Monomer Market Segmentation
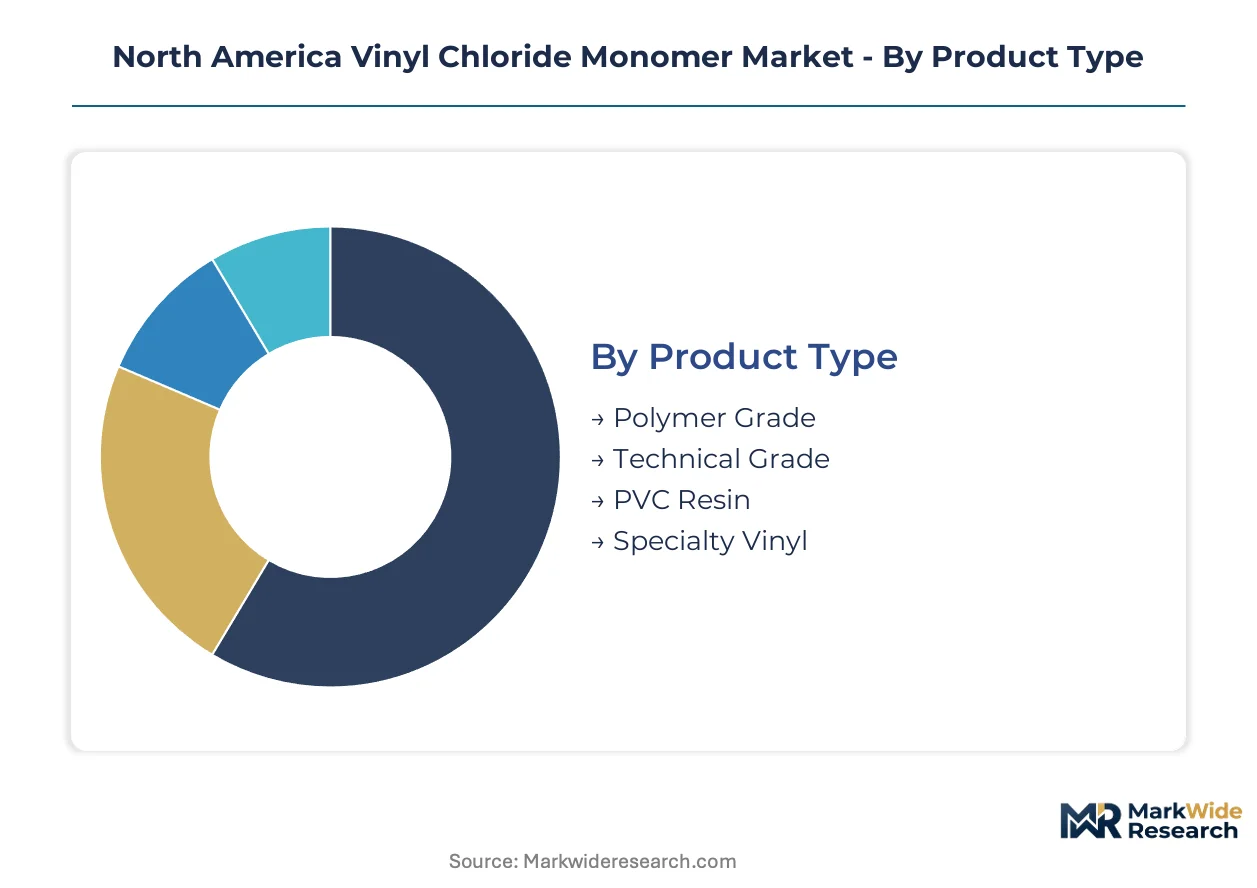
VCM procurement patterns diverge sharply across purity grades and end-use specifications, with regulatory thresholds dictating contract structures. Buyers segment their supplier base by certification burden rather than commodity pricing alone.
Product Type:
Polymer grade commands the most stringent EPA and OSHA compliance documentation, while specialty vinyl segments require Health Canada PMRA clearance for cross-border medical applications.
- Polymer Grade:Suspension-process feedstock with residual impurity ceilings above 100 ppm serves municipal water pipe extruders across Texas and Louisiana. Federal infrastructure funding cycles are pulling volume into large-diameter PVC contracts where thermal stability specifications dominate procurement checklists.
- Specialty Vinyl:Ultra-purity specifications below 50 ppm residual monomer serve medical film and electrical coating applications. Health Canada's PMRA evaluates stricter VCM trace limits than US FDA equivalents, fragmenting product qualification for cross-border suppliers.
- Technical Grade:Intermediate purity tier serves industrial adhesive and sealant compounders with less demanding thermal processing windows.
- PVC Resin:Captive intermediate product moving directly from VCM units to integrated polymerization trains without merchant market exposure.
Leading the category by volume: Polymer Grade. Growing fastest: Specialty Vinyl.
Application:
Application selection determines whether buyers contract for spot monomer or bundled chlor-alkali-VCM-PVC supply packages.
- Pipes:Structural PVC extrusion for municipal water infrastructure anchors value capture. Federal replacement funding cycles across Texas and Louisiana procurement offices are consolidating demand into multi-year direct mill relationships rather than distributor spot purchases.
- Films:Medical and food-contact flexible packaging requires the strictest residual monomer thresholds. FDA and Health Canada divergence on VCM trace limits forces dual-track product qualification.
- Sheets:Construction-grade rigid panels for roofing and siding applications.
- Coatings:Electrical insulation and automotive underbody protection compounds.
Dominant by contract value: Pipes. Steepest expansion trajectory: Films.
End User:
End-user concentration along the Gulf Coast petrochemical corridor determines logistics economics and emission compliance bundling.
- Construction:Infrastructure-grade PVC demand concentrates in integrated procurement functions negotiating chlor-alkali-VCM-PVC bundles. Louisiana and Kentucky manufacturing corridors exhibit the most advanced bundle contracting penetration.
- Automotive:Interior seating and trim substitution away from leather and thermoplastic olefins is opening incremental VCM offtake channels requiring OSHA workplace limit certification at 1 ppm.
- Packaging:Food-contact film extruders navigating FDA-Health Canada regulatory divergence.
- Electrical:Wire insulation and cable jacketing compounds with flame-retardant additive requirements.
Highest volume concentration: Construction. Most rapid demand shift: Automotive.
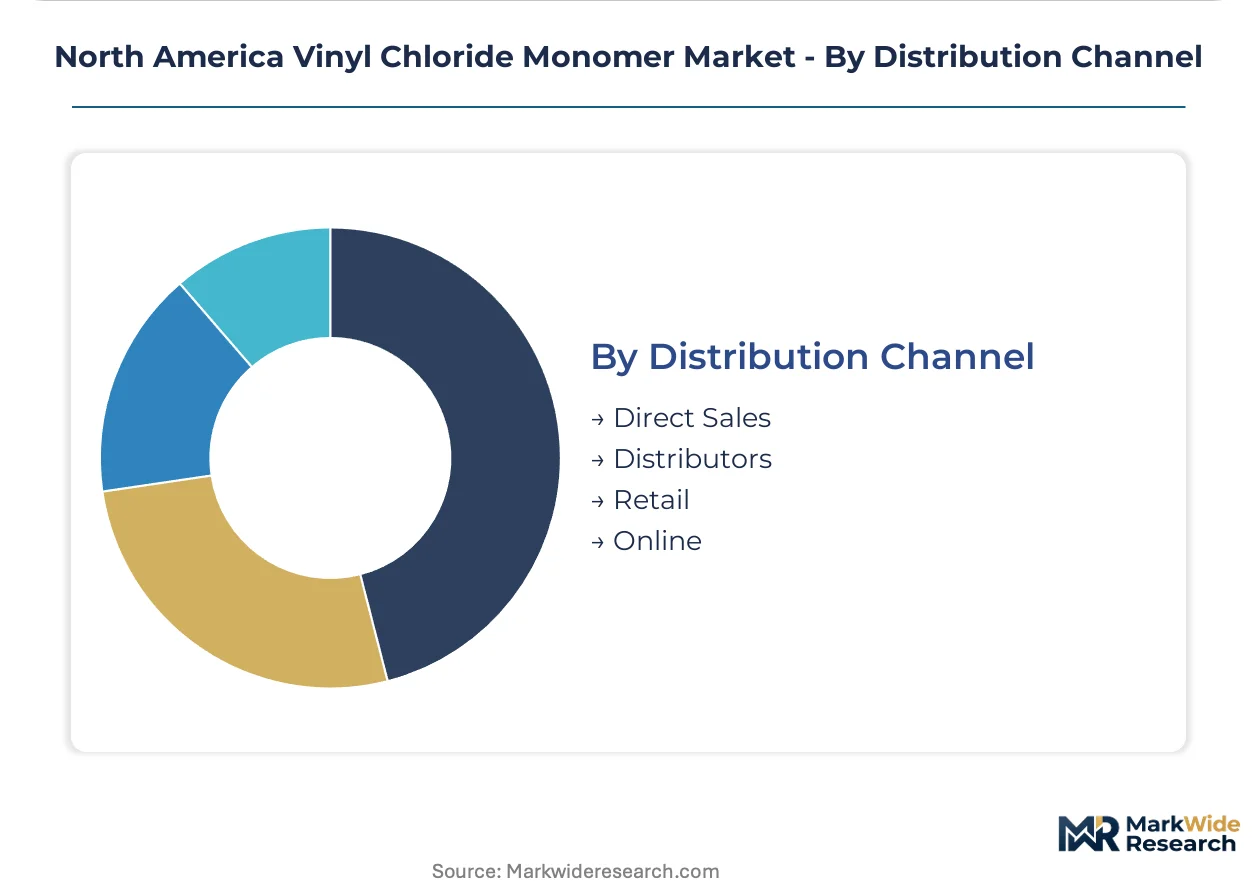
Distribution Channel:
Channel selection reflects buyer scale and integration depth rather than geographic coverage alone.
- Direct Sales:Large construction and automotive compounders negotiate multi-year offtake agreements with Gulf Coast producers. Regional distributors serving residential pipe extruders are losing volume to these direct mill relationships.
- Distributors:Smaller extruders and compounders without integrated procurement functions rely on inventory-buffered supply.
- Retail:Limited to small-volume maintenance and repair applications.
- Online:Emerging channel for technical documentation and specification-grade product sourcing.
Primary volume flow: Direct Sales. Channel under most pressure: Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates along the US Gulf Coast while consumption spreads across construction corridors in the US South and Canadian industrial heartlands. Mexican import demand bridges the gap between concentrated supply and dispersed end-use applications.
United States
Federal infrastructure funding cycles are accelerating PVC pipe procurement across Texas and Louisiana water districts. The US EPA enforces National Emission Standards for Hazardous Air Pollutants at chlor-alkali complexes with quarterly fenceline monitoring obligations. The Gulf Coast petrochemical corridor from Houston to Lake Charles anchors integrated VCM-PVC production with direct ethylene cracker feedstock access.
Canada
Municipal water infrastructure replacement programs in Ontario and Quebec are sustaining polymer-grade VCM demand for pressure pipe extrusion. Health Canada's PMRA evaluates stricter residual monomer thresholds in food-contact PVC than US FDA equivalents, fragmenting cross-border product qualification. The Sarnia-Lambton chemical valley in Ontario hosts downstream PVC compounding operations serving Great Lakes construction markets.
Mexico
Residential construction expansion in Mexico City and Monterrey metro areas is pulling imported PVC resin and derivative VCM demand. Mexico's federal environmental regulator SEMARNAT layers state-level permitting on coastal petrochemical zones, constraining greenfield chlor-alkali development. The Altamira petrochemical complex on the Tamaulipas coast processes imported ethylene derivatives for domestic pipe and film extrusion.
Texas Gulf Coast
Texas water development board funding cycles are consolidating municipal pipe procurement into multi-year direct mill contracts rather than distributor spot purchases. The Texas Commission on Environmental Quality imposes additional air permitting requirements on coastal petrochemical modifications, extending project timelines. The Houston Ship Channel cluster integrates ethylene crackers, EDC units, and VCM trains with deepwater export terminal access.
Louisiana Industrial Corridor
Industrial construction and chemical plant expansion projects are sustaining technical-grade VCM demand for adhesive and sealant applications. The Louisiana Department of Environmental Quality has extended environmental review timelines for capacity modifications at existing chlor-alkali sites. The Lake Charles-Baton Rouge manufacturing corridor exhibits the most advanced bundle contracting penetration for chlor-alkali-VCM-PVC integrated supply.
North America Vinyl Chloride Monomer Market Key Industry Players
The competitive structure tilts toward integrated petrochemical conglomerates with captive chlor-alkali capacity. Three producers control the majority of captive chlorine output, exposing buyers to coordinated maintenance outage schedules. The market organizes around two strategic archetypes: Gulf Coast-integrated majors with backward ethylene control, and Asian-headquartered multinationals with regional compounding networks. Dominant competitive moves include capacity consolidation onto fewer permitted footprints and multi-year bundle contracting with construction sector buyers.
Among North American-integrated producers, LyondellBasell Industries occupies a position exemplifying the Gulf Coast archetype with its Houston-area chlor-alkali-to-PVC complex. Formosa Plastics Group represents the Asian multinational model with regional compounding and distribution infrastructure. Westlake Corporation anchors the high-utilization manufacturing tier across Louisiana and Kentucky production sites.
| Leading Market Players |
|---|
| LyondellBasell Industries |
| Formosa Plastics Group |
| Westlake Corporation |
| Nova Chemical |
| LG Chem |
| Occidental Chemical Corporation |
| BASF |
| Shin-Etsu Chemical |
| Olin Corporation |
| Others |
Cost & Logistics Intelligence
Federal infrastructure funding cycles for municipal water pipe replacement are compressing procurement timelines and forcing suppliers to pre-position inventory, which concentrates pricing power with Gulf Coast producers holding integrated chlor-alkali-VCM-PVC complexes.
Pricing Analysis
Cost-down pressure on polymer-grade VCM accelerates because construction buyers are consolidating procurement into multi-year chlor-alkali-VCM-PVC bundles rather than discrete monomer spot purchases. Three-tier pricing structure across specialty, polymer, and technical grades separates medical-film purity specifications from municipal pipe feedstock. Price differentiation traces to EPA NESHAP compliance documentation and OSHA workplace limit certification at 1 ppm. Municipal pipe extruders exhibit highest price sensitivity due to federal funding cycle dependency, while medical film compounders accept premium positioning for sub-50 ppm residual monomer thresholds.
Supply Chain Analysis
Regional distribution centers in Houston and Lake Charles anchor hub-and-spoke patterns serving extrusion corridors across Texas, Louisiana, and Kentucky. Production concentrates in the United States, with Canadian compounding operations in Sarnia-Lambton and Mexican import demand through Altamira. Raw material dependencies include ethylene from Gulf Coast crackers, chlorine from captive chlor-alkali units, and EDC from integrated oxychlorination trains. Single-source vulnerability runs through three producers controlling majority captive chlorine output. Distribution runs through direct mill relationships with large construction compounders, bypassing regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chlorine supply concentration among three integrated producers props pricing and creates durable margin structures for compliant operators.
For Market Incumbents: Anticipate coordinated maintenance outage schedules from rival producers and pre-negotiate interruptible supply clauses with automotive compounders seeking OSHA-certified VCM. Defend position by accelerating EPA-compliant thermal dehydrochlorination retrofits ahead of NESHAP enforcement timelines and securing captive ethylene access through cracker joint ventures along the Houston Ship Channel. For New Entrants and Emerging Players: Specialty vinyl medical film extruders navigating FDA-Health Canada regulatory divergence represent the most penetrable buyer archetype. Target this segment with dual-certification compliance packages and technical documentation support that incumbent commodity producers underinvest in. Establish beachhead through toll manufacturing arrangements with existing chlor-alkali operators to bypass greenfield permitting barriers. For Investors and Strategic Acquirers: The window for entry favors distressed chlor-alkali assets with stranded ethylene integration in Louisiana and Kentucky. Long-term viability hinges on emission-compliant capacity consolidation onto fewer permitted footprints rather than distributed operations. Monitor EPA fenceline monitoring enforcement intensity as the signal for accelerated industry rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene | Gulf Coast cracker joint ventures compress delivered cost structures for EDC precursors. |
| EPA NESHAP Compliance Retrofit | Continuous monitoring upgrades differentiate certified producers in liability-sensitive buyer evaluations. |
| Medical-Grade Certification Investment | Dual FDA-Health Canada clearance opens premium positioning in cross-border medical film applications. |
| Long-term Supply Agreement | Multi-year chlor-alkali-VCM-PVC bundles lock in construction sector volume through federal funding cycles. |
| Capacity Consolidation | Fewer permitted footprints reduce regulatory compliance burden and accelerate project sanction-to-startup intervals. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with plant managers at chlor-alkali complexes, procurement leads at PVC pipe extruders, distribution channel partners serving construction corridors, and technical R&D directors in specialty vinyl applications. Bottom-up volume estimates triangulated against top-down capacity assessments across the US Gulf Coast petrochemical corridor.
Segmentation granularity modeled purity grades, end-use applications, and regional production hubs at the state-cluster level. CAGRs derived from production capacity deployment schedules, feedstock cost trajectory assumptions, and demand elasticity estimates across municipal infrastructure funding cycles. Industry-specific forecast inputs included EPA enforcement intensity projections and chlorine-causality soda co-production margin sensitivities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to federal infrastructure appropriation volatility and state-level environmental review timeline extensions. Outputs reflect documented assumptions around ethylene feedstock availability and chlor-alkali capacity utilization rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Acetochlor Market
Bulk Chemicals
Global Plastics Market
Bulk Chemicals
Ammonium Sulfate Market
Bulk Chemicals
Benzotrifluoride Market
Bulk Chemicals
Bistrifluoromethanesulfonimide Lithium Market
Bulk Chemicals
Zinc Gluconate Granules Market
Bulk Chemicals
Ferrous Oxalate Market
Bulk Chemicals
United States Calcium Chloride Market
Bulk Chemicals
Europe Lipids Market
Bulk Chemicals
Global Nitrite Market
Bulk Chemicals
China Starch and Starch Derivatives Market
Bulk Chemicals
Sulfur Market
Bulk Chemicals
Aniline Market
Bulk Chemicals
Battery Grade Lithium Chloride Market
Bulk Chemicals
Gypsum-Free Lactic Acid Market
Bulk Chemicals
Crude Tall Oil Derivative Market