
 Global Ibuprofen Market | 2026-2036
Global Ibuprofen Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ibuprofen Market Outlook
China is reconfiguring bulk ibuprofen API supply dynamics through expanded fermentation and chemical synthesis capacity in Shandong and Zhejiang provinces. BASF leverages its integrated intermediate-to-API pipeline to sustain cost advantages across European and Asian formulation networks. Granules India Limited anchors South Asian supply through dedicated ibuprofen granulation facilities serving regulated and semi-regulated markets. Dr. Reddy's Laboratories Ltd competes on USFDA-certified API volumes, positioning its Hyderabad complex as a strategic hub for North American generics procurement.
Ibuprofen is a propionic acid-derived nonsteroidal anti-inflammatory drug with a molecular weight of 206.29 g/mol, manufactured through Boots synthesis or subsequent catalytic hydrogenation routes, primarily indicated for analgesic, antipyretic, and anti-inflammatory therapeutic applications. Tablets dominate prescription and OTC channels due to manufacturing scalability and patient familiarity, while Liquid Form captures pediatric and geriatric segments where swallowing difficulties limit solid dosage adoption. E-commerce distribution is displacing traditional pharmacy reliance in direct-to-consumer markets, though hospital and clinic procurement through wholesale channels retains margin concentration for bulk contract volumes.
The FDA enforces current Good Manufacturing Practice standards and nitrosamine impurity limits that shape API sourcing decisions for US-bound ibuprofen, while the EMA's REACH protocols and the EU Green Deal chemical sustainability frameworks constrain solvent use and waste profiles across European manufacturing. India's CDSCO aligns with ICH Q3D elemental impurity guidelines under its revised Schedule M requirements, tightening compliance burdens for domestic API exporters. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and IP standards to anticipate qualification costs and geographic sourcing shifts.
Market Dynamics
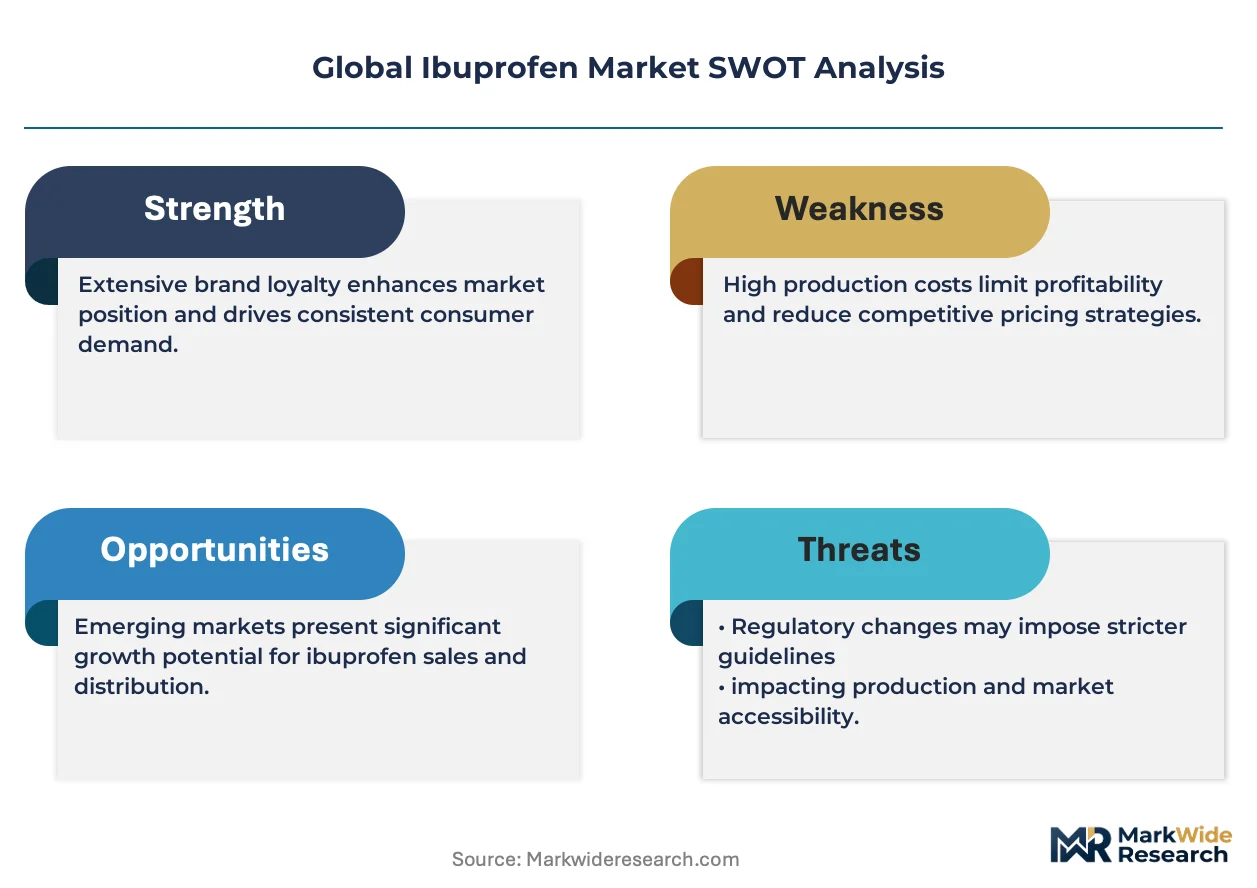
FDA nitrosamine impurity mandates are compressing API supplier margins and forcing wholesale purification infrastructure upgrades across contract manufacturing networks serving North American and European formulation demand.
Growth Catalysts
- Hospital pain management protocol expansion:Emerging health systems in Brazil and Saudi Arabia are broadening formulary inclusion of prescription-strength ibuprofen for post-surgical recovery pathways.
- REACH solvent restriction compliance:European Green Deal chemical sustainability frameworks are accelerating adoption of aqueous-based synthesis routes that reduce waste disposal liabilities.
- Pediatric liquid formulation demand:Geriatric swallowing difficulty and pediatric dosing precision requirements are pulling capacity investment toward non-solid dosage production lines.
Market Restraints
- API supply concentration risk:Shandong and Zhejiang provinces in China control disproportionate fermentation and chemical synthesis capacity, creating single-geography vulnerability.
- Paracetamol substitution pressure:Primary care prescribing guidelines in multiple jurisdictions favor acetaminophen for fever management in specific patient populations.
- ICH Q3D elemental impurity testing costs:Heavy metal detection protocols impose qualification burdens that disqualify smaller API batches from regulated market entry.
Strategic Opportunities
- Indian bulk drug park incentives:Production-linked incentive schemes and dedicated pharmaceutical zones in Andhra Pradesh and Gujarat are drawing multinational API capacity relocation.
- E-commerce direct-to-consumer channel maturation:Platform logistics integration is enabling OTC ibuprofen bypass of traditional wholesale pharmacy distribution in urban Indian and Southeast Asian markets.
- Continuous manufacturing technology convergence:Flow chemistry integration with real-time release testing is compressing batch cycle times and qualification overhead for export-oriented facilities.
Industry Challenges
- Pharmacopeial harmonization complexity:Divergent USP, EP, and IP monograph specifications for dissolution and impurity profiles force duplicate stability studies and documentation.
- Specialized analytical chemistry talent scarcity:Nitrosamine-specific detection methodology and forced degradation study design require skill sets concentrated in limited regulatory markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ibuprofen Market |
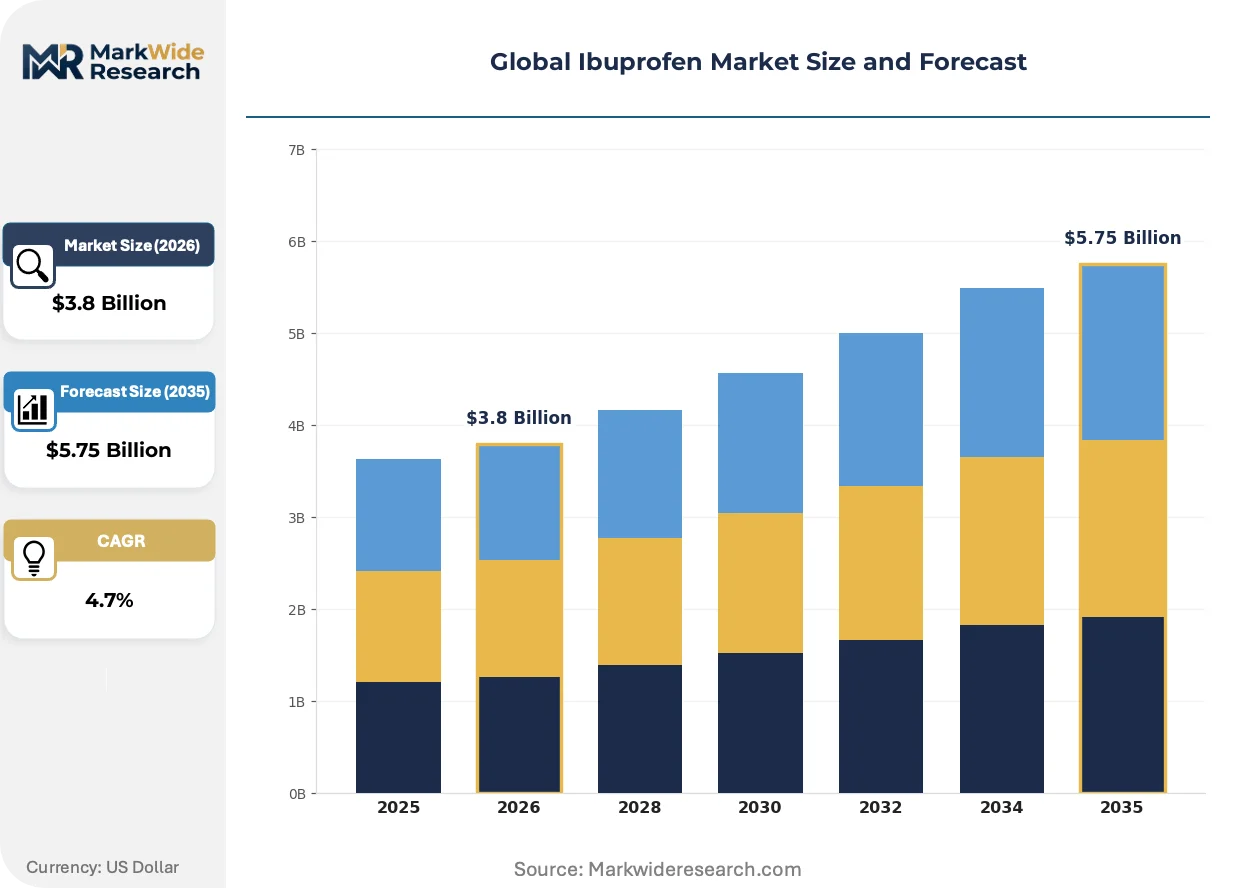
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Liquid Form, Topical Gel End User: Pharmacies, Hospitals, Clinics, Online Retailers Packaging Type: Blister Packs, Bottles, Sachets, Jars Distribution Channel: Direct Sales, Wholesalers, Retail Stores, E-commerce |
| Companies Covered | BASF, IOL Chemicals and Pharmaceuticals Limited, SI Group, Granules India Limited, Sino-US Zibo Xinhua-Perrigo Pharmaceutical Co., Ltd, Dr. Reddy's Laboratories Ltd, Solara Active Pharma Sciences Limited, Shasun, Shandong Xinhua Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ibuprofen Market Strategic Shifts
Digital batch record systems and process analytical technology are compressing quality assurance timelines while regulatory data integrity requirements harden documentation standards across GMP environments.
Process analytical technology (PAT) with inline spectroscopic monitoring is virtualizing traditional offline quality control laboratory functions. European formulation manufacturers adopting these systems report reduced batch release cycle times. This virtualization is compressing the competitive advantage of legacy quality assurance staffing models.
EMA nitrosamine risk assessment mandates and subsequent ICH M7(R2) guideline updates are forcing API sponsors to submit comprehensive structure-activity relationship documentation. Manufacturers now face retrospective validation obligations for historically approved products. Oral solid dosage facilities serving EU markets are prioritizing tertiary amine scavenging process modifications.
Direct hospital contracting for generic analgesic bundles is displacing traditional wholesale distributor intermediation in North American institutional procurement. Integrated delivery networks in the United States are consolidating annual ibuprofen volumes into single-source agreements with API-integrated generic sponsors. This concentration is most visible in tertiary care systems with captive specialty pharmacy operations.
Global Ibuprofen Market Segmentation
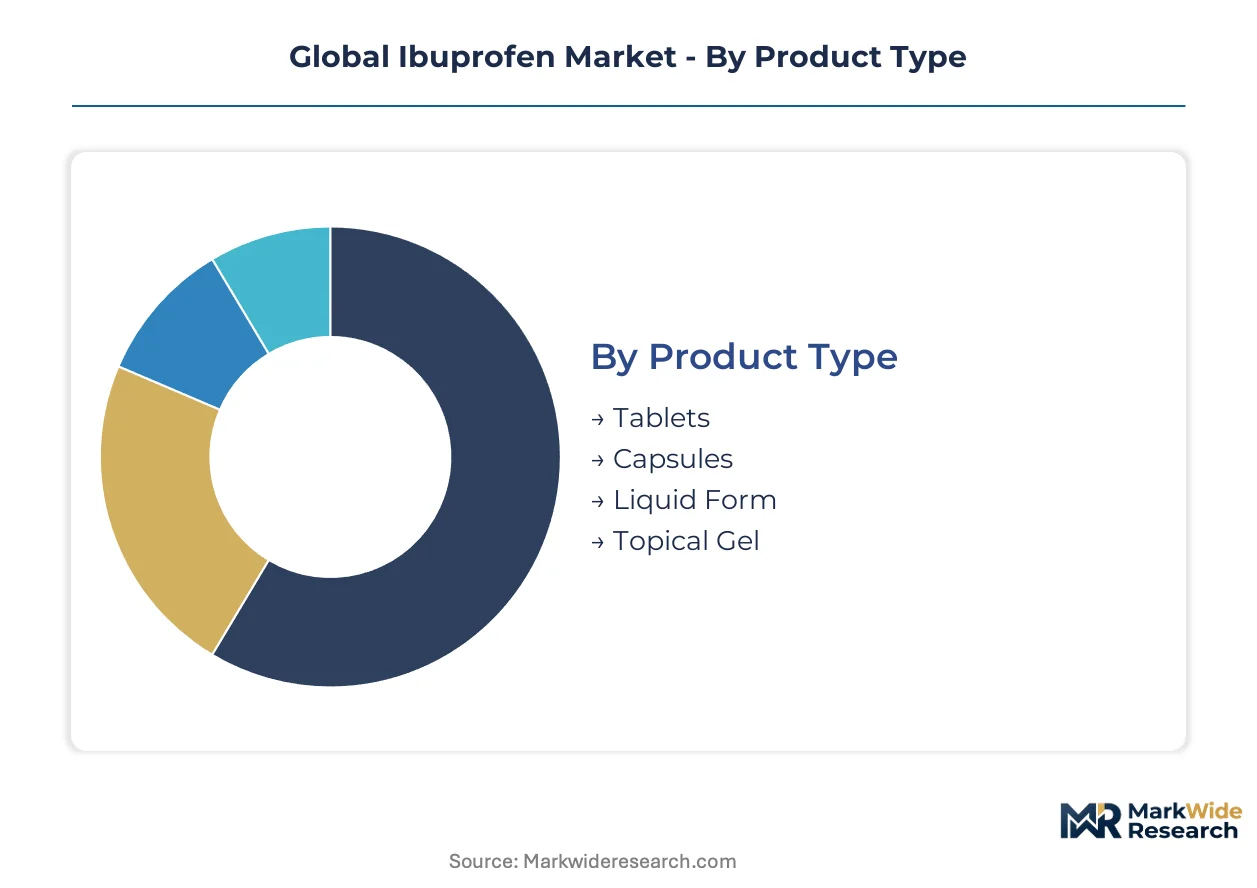
Ibuprofen's therapeutic versatility spans acute pain, chronic inflammation, and fever management, creating distinct demand profiles across dosage forms, institutional buyers, and distribution pathways. Each segmentation dimension reflects divergent margin structures, regulatory burdens, and supply chain configurations that shape competitive positioning.
Product Type:
Use-case spectrum stretches from immediate-release acute pain management to extended-duration chronic therapy, with formulation choice dictating manufacturing complexity and patient compliance economics.
- Tablets:Compressed solid dosage forms dominate prescription and OTC channels through manufacturing scalability and established bioequivalence pathways. Hospital procurement in Brazil and Saudi Arabia concentrates here for post-surgical pain protocols.
- Liquid Form:Suspensions and syrups address pediatric dosing precision and geriatric swallowing difficulties where solid dosage adoption fails. Capacity investment is pulling toward non-solid production lines in India and Southeast Asia.
- Capsules:Gelatin or HPMC shells offer taste masking and modified-release potential for chronic anti-inflammatory regimens.
- Topical Gel:Transdermal delivery limits systemic exposure for localized musculoskeletal complaints, with EMA REACH solvent restrictions shaping formulation chemistry.
The dominant share belongs to Tablets, while Liquid Form is closing the gap fastest.
End User:
Cost tier stratification separates high-volume institutional contracting from fragmented retail prescription fulfillment.
- Hospitals:Integrated delivery networks in the United States consolidate annual volumes into single-source API-integrated agreements. Direct hospital contracting is displacing wholesale distributor intermediation in North American institutional procurement.
- Online Retailers:Platform logistics integration enables OTC bypass of traditional wholesale pharmacy distribution in urban Indian and Southeast Asian markets.
- Pharmacies:Community and chain retail maintain formulary depth for prescription-strength regimens with pharmacist counseling requirements.
- Clinics:Outpatient facilities prioritize rapid-turnover analgesic dispensing for acute injury and minor surgical recovery.
Hospitals capture the volume concentration, yet Online Retailers are expanding most quickly.
Packaging Type:
Patient adherence and supply chain integrity requirements drive material selection across regulated and semi-regulated markets.
- Blister Packs:Unit-dose aluminum-PVC configurations satisfy FDA child-resistant and senior-friendly mandates while enabling compliance tracking.
- Bottles:High-density polyethylene containers serve high-count OTC replenishment cycles with desiccant integration for humidity protection.
- Sachets:Single-use foil laminates support travel-size and sample distribution in emerging markets with limited cold chain infrastructure.
- Jars:Bulk polypropylene containers supply institutional repackaging operations and compounding pharmacy requirements.
Blister Packs lead regulated market penetration, though Bottles retain cost advantage at scale.
Distribution Channel:
Margin capture concentrates in channels controlling patient access and formulary placement decisions.
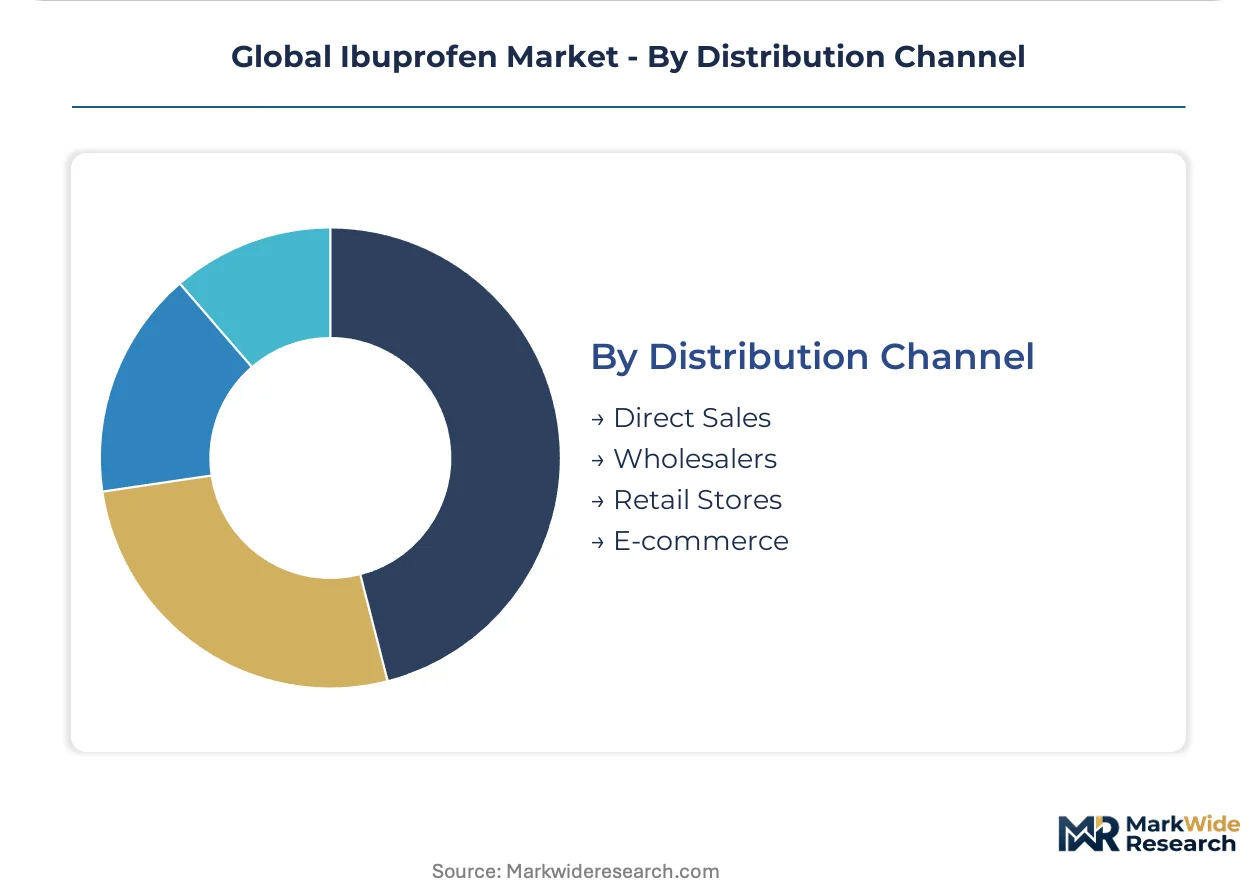
- E-commerce:Direct-to-consumer platforms compress pharmacy reliance through last-mile logistics integration and subscription replenishment models.
- Wholesalers:Three-tier distribution networks retain relevance for hospital and clinic procurement of bulk generic volumes with invoice-level chargeback administration.
- Direct Sales:API-integrated generic sponsors contract directly with integrated delivery networks, eliminating intermediary margin extraction.
- Retail Stores:Brick-and-mortar pharmacy chains maintain impulse purchase visibility and pharmacist consultation access for first-line analgesic selection.
Wholesalers anchor institutional volume flow, while E-commerce gains share fastest in consumer-direct segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai Yangshan Deep Water Port anchors Asia-Pacific API distribution, handling fermentation-derived bulk ibuprofen shipments bound for formulation facilities across three continents. This maritime infrastructure underwrites China's dominance in intermediate chemical exports while enabling just-in-time replenishment for European and North American generic manufacturers.
China
Shandong and Zhejiang provinces concentrate fermentation and chemical synthesis capacity serving global API demand. NMPA's tightened nitrosamine impurity surveillance compels facility upgrades at Zibo Xinhua-Perrigo's Shandong complex, where captive intermediate production integrates with finished API output for regulated market export.
United States
Integrated delivery networks in Texas and California consolidate annual ibuprofen volumes through direct hospital contracting. FDA's current Good Manufacturing Practice enforcement and nitrosamine testing mandates reshape sourcing decisions, with Houston and Philadelphia corridor distributors managing wholesale chargeback administration for institutional procurement.
India
Andhra Pradesh and Gujarat bulk drug park incentives draw multinational API capacity relocation through production-linked incentive schemes. CDSCO's alignment with ICH Q3D elemental impurity guidelines tightens compliance burdens for Hyderabad-based exporters serving North American generics procurement.
Germany
BASF's Ludwigshafen integrated intermediate-to-API pipeline sustains cost advantages across European formulation networks. EMA REACH solvent restrictions and EU Green Deal chemical sustainability frameworks accelerate aqueous-based synthesis adoption, reducing waste disposal liabilities for Rhine-Neckar cluster manufacturers.
Brazil
Emerging health systems in São Paulo and Rio de Janeiro broaden formulary inclusion of prescription-strength ibuprofen for post-surgical recovery pathways. ANVISA's pharmacopeial convergence with USP and EP standards elevates qualification costs for API imports, favoring suppliers with pre-validated documentation packages.
Global Ibuprofen Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the value chain. The ibuprofen API sector exhibits tiered consolidation around fermentation-scale producers and formulation-integrated generic sponsors. Three archetypes dominate: multinational chemical conglomerates with captive intermediate pipelines, Indian contract manufacturers leveraging bulk drug park incentives, and China-based fermentation specialists serving semi-regulated markets. Competitive moves concentrate on backward integration into key starting materials and geographic capacity relocation to jurisdictions with favorable regulatory arbitrage.
Among German chemical conglomerates, BASF exemplifies the integrated-platform archetype through its Ludwigshafen intermediate-to-API pipeline. Indian specialists Granules India Limited and Dr. Reddy's Laboratories Ltd occupy positions within the contract-manufacturing tier, with the former anchoring South Asian granulation supply and the latter representing USFDA-certified API export capability. Shandong Xinhua Pharmaceutical sits within China's fermentation-specialist cluster, reflecting the geographic concentration of bulk chemical synthesis capacity.
| Leading Market Players |
|---|
| BASF |
| IOL Chemicals and Pharmaceuticals Limited |
| SI Group |
| Granules India Limited |
| Sino-US Zibo Xinhua-Perrigo Pharmaceutical Co., Ltd |
| Dr. Reddy's Laboratories Ltd |
| Solara Active Pharma Sciences Limited |
| Shasun |
| Shandong Xinhua Pharmaceutical |
| Others |
Value Chain & Pricing Dynamics
Shandong province's fermentation capacity concentration grants Zibo Xinhua-Perrigo and Shandong Xinhua Pharmaceutical substantial leverage over API contract pricing for North American and European formulation networks. This geographic clustering compresses margins for downstream buyers while forcing qualification investments that stratify supplier tiers.
Pricing Analysis
FDA nitrosamine impurity mandates dictate the pricing tier structure across the ibuprofen API sector, separating USFDA-certified suppliers from semi-regulated market providers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Pricing pressure stems from ICH Q3D elemental impurity testing costs that disqualify smaller batches. Hospital procurement through integrated delivery networks demonstrates lowest price sensitivity, while contract manufacturers serving emerging markets face acute margin compression.
Supply Chain Analysis
Export-control restrictions on specialized analytical equipment and forced degradation study protocols constrain technology transfer to emerging API producers. Supply concentrates in China, India, and Germany, with fermentation-derived intermediates drawing from petrochemical feedstocks and catalytic hydrogenation catalysts. Single-source vulnerability persists in Shandong-Zhejiang corridor concentration. Distribution runs through Shanghai Yangshan Deep Water Port for maritime bulk shipment to formulation facilities across three continents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in nitrosamine testing and validation documentation are expanding faster than commodity API production, creating recurring-revenue layers for technical service providers.
For Market Incumbents: Insulate market position through backward integration into key starting materials and captive intermediate production at Ludwigshafen or Hyderabad complexes. Paracetamol substitution pressure in primary care guidelines and Chinese fermentation overcapacity threaten margin stability. Prioritize EMA REACH-compliant aqueous synthesis certification to capture European Green Deal procurement preferences. For New Entrants and Emerging Players: Pursue white-space opportunities in pediatric liquid formulation capacity and real-time release testing technology integration. Southeast Asian e-commerce direct-to-consumer channels offer the most penetrable entry point with platform logistics partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because API supplier margins are compressing toward integrated-platform economics. Target acquisition candidates with USFDA-certified facilities and existing nitrosamine validation packages. Watch for CDSCO enforcement intensity shifts as the inflection signal for Indian export competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Intermediates | BASF's Ludwigshafen pipeline demonstrates cost advantages through captive supply of propionic acid derivatives. |
| Continuous Manufacturing Technology Adoption | Flow chemistry integration with PAT systems compresses batch cycle times for export-oriented Indian facilities. |
| Regulatory Certification Investment | USFDA and EMA dual certification opens integrated delivery network contracting in North American hospital systems. |
| Aqueous Synthesis Route Transition | REACH solvent restriction compliance reduces waste disposal liabilities for Rhine-Neckar cluster manufacturers. |
| E-commerce Platform Partnership | Direct-to-consumer channel maturation in urban Indian markets bypasses traditional wholesale pharmacy distribution. |
Study Parameters
A standing panel of API manufacturing executives, regulatory affairs specialists, hospital procurement managers, and pharmaceutical distribution channel heads provided ongoing calibration throughout the study period. Primary interview data combined with secondary validation from FDA filings, EMA assessment reports, CDSCO notifications, and customs trade records. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates across the analysis window.
Scenario-bracketing framed the analytical approach across dosage form, end-user institution type, and regional regulatory cluster segmentation. CAGRs derived from production capacity expansion timelines, formulary inclusion protocols, and patent expiration waves. Nitrosamine impurity surveillance intensity and pharmacopeial harmonization progress served as key forecast inputs throughout the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in currency exchange rates, energy input costs, or maritime freight indices would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and capacity utilization rates. Material shifts in FDA nitrosamine mandate scope or Chinese environmental enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Tiapride Hydrochloride API Market
Pharmaceutical Ingredients
Histamine H2-Receptor Antagonists Market
Pharmaceutical Ingredients
Non-Steroidal Anti-Inflammatory Drugs (Nsaids) Market
Pharmaceutical Ingredients
Global Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Chlorzoxazone Market
Pharmaceutical Ingredients
Global Chlorpheniramine Maleate Market
Pharmaceutical Ingredients
Small-Molecule Injectable Drugs Market
Pharmaceutical Ingredients
Large Molecule Drug Substance CDMO Market
Pharmaceutical Ingredients
Taxifolin Market
Pharmaceutical Ingredients
Furosemide Market
Pharmaceutical Ingredients
Global Small Molecule API Market
Pharmaceutical Ingredients
Growth Hormone Inhibiting Hormone Drugs Market
Pharmaceutical Ingredients
Synthetic Lethality-Based Drugs and Targets Market
Pharmaceutical Ingredients
Sennosides Market
Pharmaceutical Ingredients
Quinoline Market
Pharmaceutical Ingredients
Metformin Hydrochloride API Market