
 Amphetamine Drug Market | 2026-2036
Amphetamine Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Amphetamine Drug Market Insights
Adult psychiatric practices is bifurcating demand away from pediatric-only prescribing networks as clinicians expand amphetamine-based therapy to working-age patients with late-diagnosed attention disorders. Teva Pharmaceuticals dominates extended-release formulation manufacturing through captive production of active pharmaceutical ingredients. Novartis AG anchors its position via Sandoz with deep generic portfolios across European and North American distribution channels. Amneal Pharmaceuticals competes aggressively on price in immediate-release tablet segments.
Amphetamine drugs comprise synthetic phenethylamine compounds, primarily dextroamphetamine and mixed amphetamine salts, formulated as controlled-release matrices or rapid-dissolve tablets for central nervous system stimulation. These compounds function by increasing synaptic dopamine and norepinephrine availability to improve executive function and wakefulness in clinically diagnosed patients. Tablets and capsules command the largest volume share due to established reimbursement pathways, while liquid solutions represent the fastest-expanding form category as pediatric and geriatric populations seek swallowing alternatives. The ADHD therapy area generates the dominant revenue stream, though narcolepsy applications attract premium pricing for orphan-disease positioning.
The US FDA enforces strict REMS protocols and DEA Schedule II quotas that directly constrain production volumes and wholesale distribution eligibility for amphetamine manufacturers. European EMA standards under the Falsified Medicines Directive mandate serialization and anti-tampering packaging that elevates compliance costs for cross-border suppliers. China's NMPA maintains separate approval tracks for imported versus domestically manufactured psychostimulants, creating divergent market access timelines. Stakeholders must monitor evolving digital health integration requirements and telemedicine prescribing regulations that could reshape patient access models.
Market Dynamics
The DEA's annual production quota system for Schedule II controlled substances functions as the dominant structural force constraining supply elasticity, with quota allocations directly capping manufacturer output regardless of prescription demand fluctuations.
Growth Catalysts
- Adult ADHD diagnostic expansion:Psychiatric practices in the United States are extending stimulant therapy to working-age patients with late-diagnosed attention disorders, broadening the addressable patient base beyond pediatric populations.
- Telemedicine prescribing frameworks:Post-pandemic regulatory accommodations for remote psychiatric consultations have reduced geographic access barriers for patients in rural and underserved metropolitan areas.
- Liquid formulation development:Pediatric and geriatric populations seeking swallowing alternatives are accelerating demand for oral solutions, creating volume growth in a historically tablet-dominated category.
Market Restraints
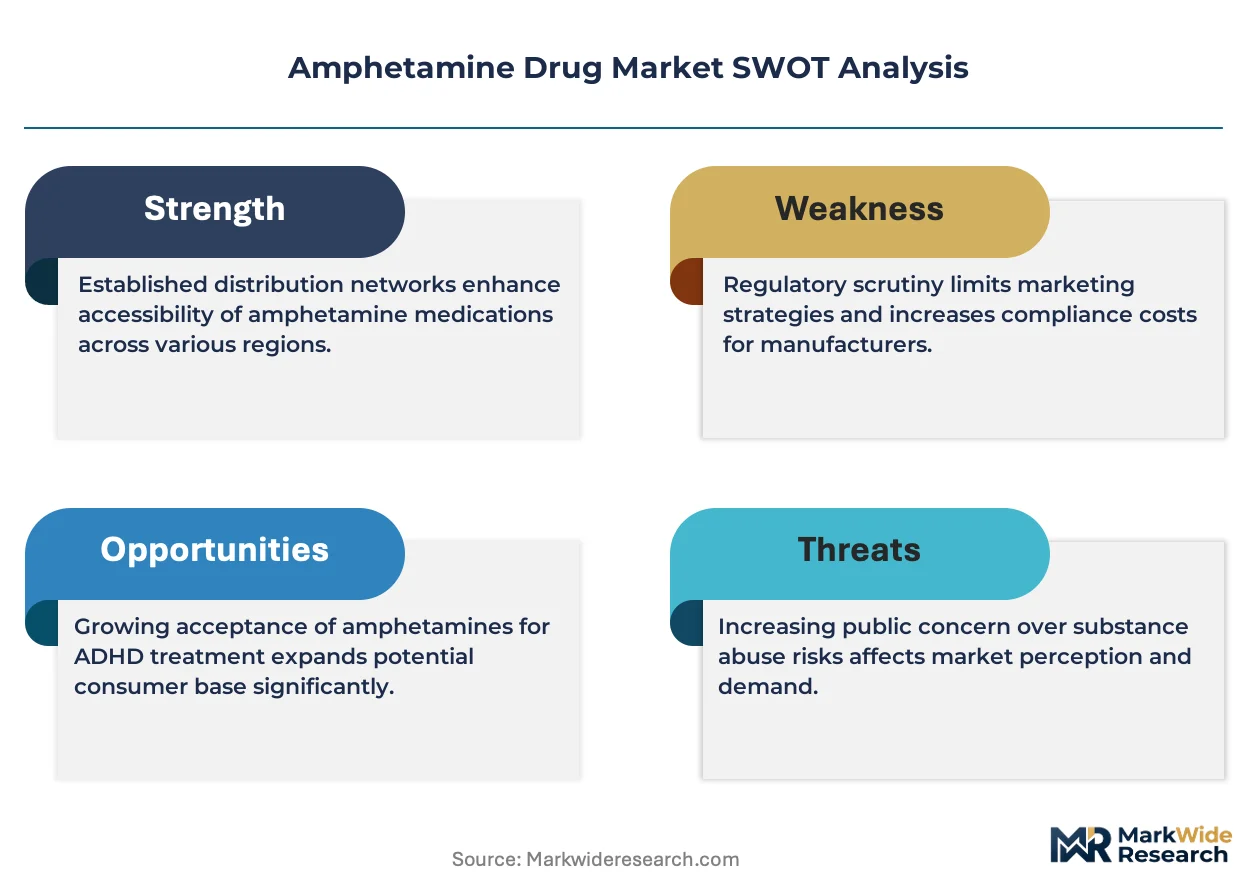
- DEA quota rigidity:The Drug Enforcement Administration's annual aggregate production limits for amphetamine salts prevent manufacturers from scaling output in response to prescription backlogs or inventory shortages.
- Active pharmaceutical ingredient concentration:Captive production of dextroamphetamine and mixed amphetamine salts concentrates among a limited number of specialized chemical manufacturers, creating single-source vulnerability.
- Generic substitution pressure:Immediate-release tablet commoditization erodes branded formulation margins as pharmacy benefit managers mandate therapeutic substitution at the point of dispensing.
Strategic Opportunities
- Digital therapeutics integration:FDA breakthrough device designation pathways for prescription digital therapeutics paired with pharmacotherapy create combination product opportunities requiring novel regulatory strategies.
- Narcolepsy orphan positioning:Premium pricing for wakefulness-promoting indications in narcolepsy patients offers margin protection unavailable in the volume-driven ADHD segment.
- Extended-release formulation innovation:Matrix-controlled release technologies enabling once-daily dosing improve adherence metrics and support differentiation in reimbursement negotiations.
Industry Challenges
- REMS compliance complexity:The FDA's Risk Evaluation and Mitigation Strategy for stimulant medications imposes distribution, prescriber certification, and patient monitoring burdens that elevate operational overhead.
- Serialization infrastructure investment:The Falsified Medicines Directive mandates unit-level traceability systems requiring capital deployment for packaging line upgrades across European distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amphetamine Drug Market |
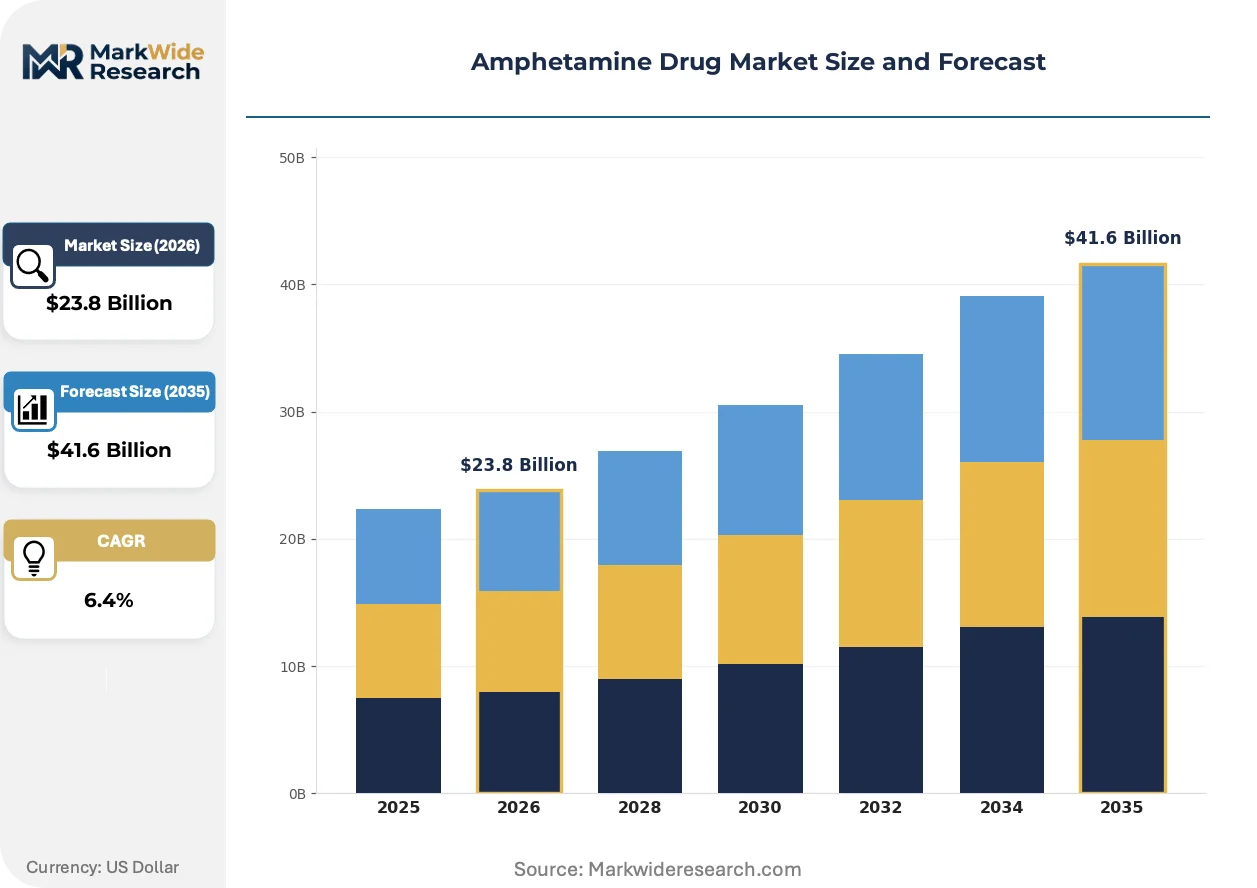
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $41.6 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Form: Tablets, Capsules, Liquid Solutions, Injections Therapy Area: ADHD, Narcolepsy, Obesity, Depression End User: Hospitals, Clinics, Homecare, Pharmacies Administration Route: Oral, Intravenous, Subcutaneous, Transdermal |
| Companies Covered | Teva Pharmaceuticals, Novartis AG, MilliporeSigma, Amneal Pharmaceuticals, Viatris, Sandoz, Takeda Pharmaceutical, Lannett, Camber Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amphetamine Drug Market Trends and Innovations
Pharmaceutical manufacturing is converging with digital health infrastructure, creating new modalities for patient adherence monitoring and prescriber accountability that reshape competitive differentiation beyond molecular composition.
Prodrug technologies for stimulant delivery are fragmenting traditional formulation hierarchies by enabling abuse-deterrent properties through enzymatic conversion mechanisms. Pediatric psychiatrists and addiction medicine specialists are adopting these platforms at accelerating rates in response to diversion concerns. The structural consequence is compressing market share for conventional immediate-release tablets while elevating development costs for market entry.
EMA enforcement of the Falsified Medicines Directive is tightening cross-border supply chain verification requirements for scheduled substances. Serialization mandates and anti-tampering packaging specifications are elevating compliance expenditures for manufacturers distributing into European markets. Wholesale distributors are consolidating supplier relationships to reduce audit complexity, favoring larger integrated manufacturers over specialized regional players.
Patient acquisition patterns are rotating toward direct-to-consumer mental health platforms that bundle diagnostic assessment with medication management. Traditional psychiatric practices and retail pharmacy channels face disintermediation as telehealth-integrated services capture prescription initiation. This shift is most visible in United States metropolitan markets where employer-sponsored mental health benefits subsidize platform subscriptions.
Amphetamine Drug Market Segmentation
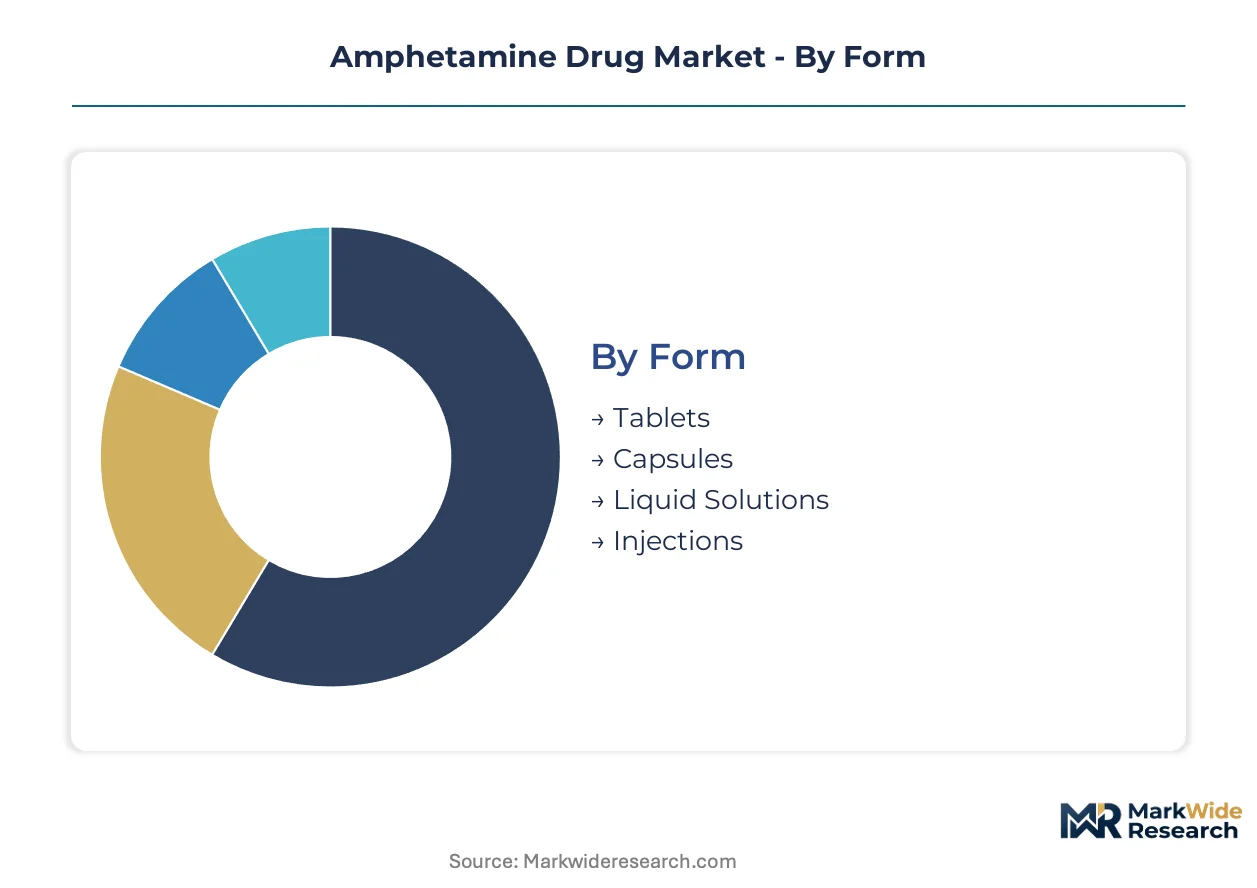
Amphetamine drug segmentation reveals how regulatory constraints, patient demographics, and reimbursement pathways fragment commercial opportunity across formulation types and care settings. Understanding these divisions exposes where DEA quotas, FDA REMS requirements, and prescriber certification rules concentrate or limit market access.
Form:
Regulatory differentiation shapes manufacturing investment and distribution eligibility across solid and liquid delivery systems, with DEA Schedule II controls applying unevenly to abuse-deterrent formulations versus conventional tablets.
- Tablets:Immediate-release and extended-release compressed matrices dominate prescription volumes through established pharmacy benefit manager reimbursement tiers. DEA production quotas constrain supply elasticity for these high-volume forms, with manufacturers Teva and Amneal competing on DEA quota allocation efficiency.
- Capsules:Gelatin or HPMC shells enable multiparticulate controlled-release technologies that improve adherence in adult ADHD populations. Novartis leverages Sandoz distribution networks to push capsule formulations through European serialization requirements under the Falsified Medicines Directive.
- Liquid Solutions:Oral suspensions address pediatric and geriatric swallowing difficulties, expanding fastest among populations excluded from tablet-dominated protocols.
- Injections:Parenteral amphetamine salts serve institutional settings with strict diversion controls, limited by DEA distribution tracking mandates.
Established volume favors tablets; emerging adoption favors liquid solutions.
Therapy Area:
Cost tier stratification separates mass-market attention disorder treatment from orphan-disease premium positioning, with reimbursement codes and prescriber specialization creating divergent margin profiles.
- ADHD:The dominant indication spans pediatric through adult populations, with diagnostic expansion in working-age patients driving prescription growth. FDA REMS protocols and state prescription drug monitoring programs impose compliance burdens that elevate operational overhead for high-volume prescribers.
- Narcolepsy:Orphan-disease designation enables premium pricing for wakefulness-promoting therapies in smaller patient populations. Jazz Pharmaceuticals and other specialists target this segment with higher-margin formulations protected from generic substitution pressure.
- Obesity:Limited approved indications for amphetamine-based anorectics face restrictive DEA scheduling that constrains prescriber eligibility.
- Depression:Off-label and adjunctive use in treatment-resistant cases occupies a regulatory gray zone with inconsistent reimbursement.
Volume concentration sits with ADHD; margin protection sits with narcolepsy.
End User:
Customer type fragmentation tracks prescriber certification requirements and diversion control stringency, with institutional versus retail channel access governed by distinct DEA registration tiers.
- Hospitals:Inpatient psychiatric units and emergency departments administer amphetamines under closed-formulary controls with integrated pharmacy oversight. These settings manage DEA Schedule II inventory through automated dispensing cabinets that reduce diversion risk.
- Clinics:Outpatient psychiatric practices represent the primary prescription initiation point for adult ADHD diagnoses, with telemedicine platforms now capturing share through remote prescriber certification.
- Homecare:Direct-to-patient delivery models face DEA registration barriers that limit growth despite patient convenience advantages.
- Pharmacies:Retail and specialty pharmacy networks operate under DEA distributor quotas and state-level prescription monitoring program integration requirements.
Prescription initiation concentrates in clinics; fulfillment infrastructure anchors in pharmacies.
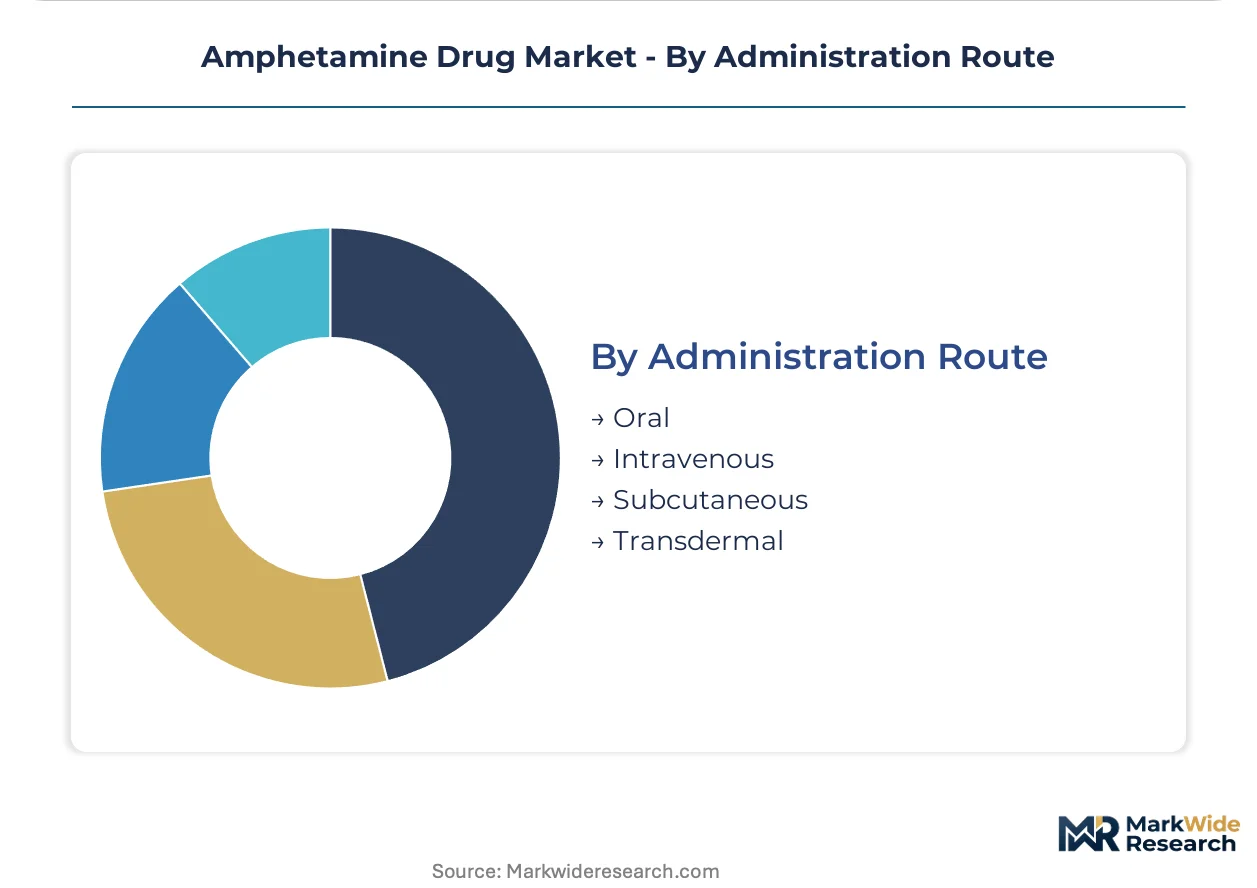
Administration Route:
Supply concentration for active pharmaceutical ingredients and finished dosage forms creates divergent market access timelines, with oral solid manufacturing capacity tightening faster than alternative delivery technologies.
- Oral:Tablets, capsules, and solutions constitute the overwhelming majority of dispensed amphetamines, supported by decades of bioequivalence data and abbreviated new drug application pathways for generics. Captive dextroamphetamine production at Teva and limited API suppliers concentrates supply risk.
- Intravenous:Hospital-restricted parenteral formulations serve acute agitation and research protocols, with manufacturing complexity limiting entrant competition.
- Subcutaneous:Depot injection development for long-acting ADHD therapy remains pre-commercial, constrained by FDA combination product review timelines.
- Transdermal:Patch-based delivery systems for pediatric populations have faced FDA rejection over absorption variability, leaving the route underdeveloped despite patient preference research.
Commercial maturity favors oral administration; pipeline innovation targets subcutaneous depot alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Adult ADHD diagnostic expansion concentrates prescription demand in markets with established psychiatric infrastructure and permissive telemedicine frameworks. Regulatory divergence across DEA, EMA, and NMPA jurisdictions fragments manufacturing compliance burdens and distribution eligibility.
United States
Working-age patients with late-diagnosed attention disorders drive prescription volume expansion beyond pediatric populations. The DEA's annual production quota system caps manufacturer output regardless of demand fluctuations. Teva Pharmaceuticals anchors extended-release formulation supply from its North American manufacturing base.
Germany
EMA serialization mandates under the Falsified Medicines Directive elevate compliance costs for cross-border amphetamine distribution. Psychiatric practices in Berlin and Munich extend stimulant therapy to adult populations following diagnostic protocol updates. Sandoz leverages established distribution networks to navigate unit-level traceability requirements.
United Kingdom
NHS reimbursement pathways for ADHD therapies concentrate demand in specialist mental health trusts across London and the Southeast. The MHRA enforces import licensing distinct from EMA centralized procedures for controlled substances. Telemedicine prescribing accommodations post-pandemic reduce geographic access barriers in rural regions.
China
NMPA maintains separate approval tracks for imported versus domestically manufactured psychostimulants, creating divergent market access timelines. Shanghai and Beijing psychiatric centers pilot digital therapeutics integration with pharmacotherapy. Domestic API production capacity remains constrained by dual-use chemical monitoring protocols.
Canada
Health Canada harmonizes Schedule II controls with DEA frameworks while maintaining independent production quota allocations. Ontario and Quebec psychiatric practices adopt adult diagnostic criteria expanding addressable patient populations. Provincial prescription monitoring programs impose dispensing tracking requirements that elevate operational overhead.
Amphetamine Drug Market Competitive Landscape
Player mix skews toward integrated pharmaceutical conglomerates with captive API production and established DEA quota allocations. Market access concentrates among manufacturers with historical Schedule II registration and REMS compliance infrastructure. Three strategic archetypes dominate: vertically integrated API-to-tablet producers, generic portfolio specialists leveraging distribution scale, and orphan-disease focused premium formulators. Competitive moves center on extended-release formulation patent extensions and telemedicine platform partnerships for patient acquisition.
Within the integrated producer tier, Teva Pharmaceuticals and Novartis AG occupy positions defined by captive dextroamphetamine manufacturing and deep generic portfolios. Amneal Pharmaceuticals exemplifies the price-competitive immediate-release specialist archetype. These three anchors sit within a vendor base where DEA quota efficiency and REMS operational maturity determine distribution eligibility more than molecular differentiation.
| Leading Market Players |
|---|
| Teva Pharmaceuticals |
| Novartis AG |
| MilliporeSigma |
| Amneal Pharmaceuticals |
| Viatris |
| Sandoz |
| Takeda Pharmaceutical |
| Lannett |
| Camber Pharmaceuticals |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between DEA-registered manufacturers and institutional pharmacy buyers lock in both API access and price visibility across multi-year horizons, insulating contracted volumes from spot-market volatility in Schedule II controlled substances.
Pricing Analysis
Cost-plus contracts with DEA quota indexation dominate procurement between API manufacturers and finished dosage form producers. Price differentiation rests on formulation complexity and REMS certification tier, with extended-release matrices commanding premiums over immediate-release commoditized tablets. Pricing pressure stems from generic substitution mandates by pharmacy benefit managers eroding branded margins. Hospital systems exhibit lowest price sensitivity due to formulary lock-in, while retail pharmacies face highest sensitivity from reimbursement compression.
Supply Chain Analysis
The United States and Israel anchor dextroamphetamine API production through Teva's captive manufacturing network. Supply chains draw from phenylpropanolamine precursors sourced through specialized chemical intermediaries, with gelatin capsule shells and controlled-release polymers as secondary inputs. Single-source vulnerability concentrates in DEA-registered API facilities facing quota allocation rigidities. Distribution runs through DEA-licensed wholesale distributors with serialized tracking infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adult ADHD diagnostic expansion fragments demand across late-diagnosed working-age patients, telemedicine-integrated platforms, and pediatric-to-geriatric formulation needs—creating service-layer niches underserved by incumbent volume-focused models.
For Market Incumbents: Fortify DEA quota allocation efficiency through backward integration into API production and REMS compliance automation. Incumbents should deepen prescriber certification infrastructure to defend against telemedicine platform disintermediation, while expanding liquid formulation capacity to capture pediatric and geriatric swallowing-alternative demand. For New Entrants and Emerging Players: Telemedicine-integrated medication management platforms represent the most penetrable service gap, where incumbents under-serve remote patient acquisition and adherence monitoring. New entrants should target employer-sponsored mental health benefits in United States metropolitan markets, deploying direct-to-consumer diagnostic bundling as the primary go-to-market angle. For Investors and Strategic Acquirers: Orphan-disease focused premium formulators with narcolepsy positioning and abuse-deterrent prodrug pipelines offer the strongest acquisition target archetype for long-term viability. Investors should monitor FDA breakthrough device designation pathways for prescription digital therapeutics as the signal indicating inflection in combination product regulatory strategies.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Compliance Automation | Reduces operational overhead for high-volume prescribers under FDA stimulant protocols. |
| Liquid Formulation Development | Captures pediatric and geriatric populations excluded from tablet-dominated reimbursement pathways. |
| Telemedicine Platform Partnership | Secures patient acquisition channels as direct-to-consumer mental health platforms disintermediate traditional psychiatry. |
| Abuse-Deterrent Prodrug Investment | Addresses diversion concerns through enzymatic conversion mechanisms favored by addiction medicine specialists. |
| European Serialization Infrastructure | Enables cross-border distribution under EMA Falsified Medicines Directive unit-level traceability mandates. |
Research Methodology
Operator-level perspectives from DEA-registered manufacturers, formulary directors at pharmacy benefit managers, and regulatory affairs specialists anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through FDA REMS documentation, DEA aggregate production quota publications, and EMA centralized procedure filings for controlled substances. Bottom-up prescription volume modeling and top-down therapeutic class expenditure analysis provided triangulation across the analysis window.
Sensitivity analysis tested forecast outputs against DEA quota allocation scenarios, generic substitution rate variations, and telemedicine regulatory accommodation shifts. The analytical framework segmented by formulation type, therapy area, and prescriber channel across the projection horizon. CAGRs derived from historical prescription trajectory analysis and diagnostic expansion modeling, with inputs including adult ADHD prevalence studies and narcolepsy orphan-disease epidemiology.
Underlying assumptions cover DEA scheduling continuity, REMS protocol stability, and telemedicine prescribing framework persistence, with deviation risk concentrated in quota policy reforms and digital therapeutic reimbursement decisions. Recalibration cycles align with material shifts in DEA aggregate production determinations and FDA combination product guidance updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Encapsulated Salicylic Acid Market
Pharmaceutical Ingredients
Originator Small Molecule Drug Market
Pharmaceutical Ingredients
Calcium Citrate Market
Pharmaceutical Ingredients
Medicinal Chemistry for Drug Discovery Market
Pharmaceutical Ingredients
Moxifloxacin Hcl (CAS 186826-86-8) Market
Pharmaceutical Ingredients
Co-Crystal Ingredient Market
Pharmaceutical Ingredients
Antibiotics API Market
Pharmaceutical Ingredients
Oridonin Market
Pharmaceutical Ingredients
Antibiotics Active Pharmaceutical Ingredient (API) Market
Pharmaceutical Ingredients
Pharmaceutical Glycerin Based Products Market
Pharmaceutical Ingredients
United Kingdom Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Pharmaceutical Grade Beta-Alanine Market
Pharmaceutical Ingredients
Synthetic Small Molecule API Market
Pharmaceutical Ingredients
Pharma-Grade Magnesium Trisilicate Market
Pharmaceutical Ingredients
India Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Global Active Pharmaceutical Ingredients (API) Market