
 Chemical Pulp Market | 2026-2036
Chemical Pulp Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Pulp Market Outlook
A widening capital-intensity gap between integrated kraft operators and merchant sulfite suppliers is rotating competitive advantage toward scale chemistry assets. BASF SE leverages its global specialty chemicals footprint to supply pulp mill process chemicals across multiple continents. Kemira anchors its position through proprietary bleaching chemistries that reduce effluent loads for European and North American customers. Buckman competes via microbial control solutions tailored to high-consistency oxygen delignification stages.
Chemical pulp denotes wood fiber mass liberated through chemical digestion, typically using white liquor sodium hydroxide and sodium sulfide in kraft processes at 160-180°C cooking temperatures, yielding cellulose-rich furnish for paper, board, and regenerated fiber applications. Bleached kraft pulp commands the largest value share within product type segments, sustained by tissue and premium printing paper specifications that require high brightness and low lignin content. Unbleached pulp occupies stable volume positions in linerboard and corrugating medium where strength properties outweigh whiteness requirements, while sulfite pulp retains niche margins in textile viscose and specialty cellulose derivative markets.
EPA effluent limitation guidelines in the United States and REACH chemical registration requirements in Europe constrain bleaching chemistry choices, pushing mills toward elemental chlorine-free and totally chlorine-free sequences. The EU Green Deal carbon border adjustments will reshape trade flows for imported pulp from high-emission production regions. Stakeholders must monitor regulatory parity between domestic and import compliance costs when locating new chemical recovery investments.
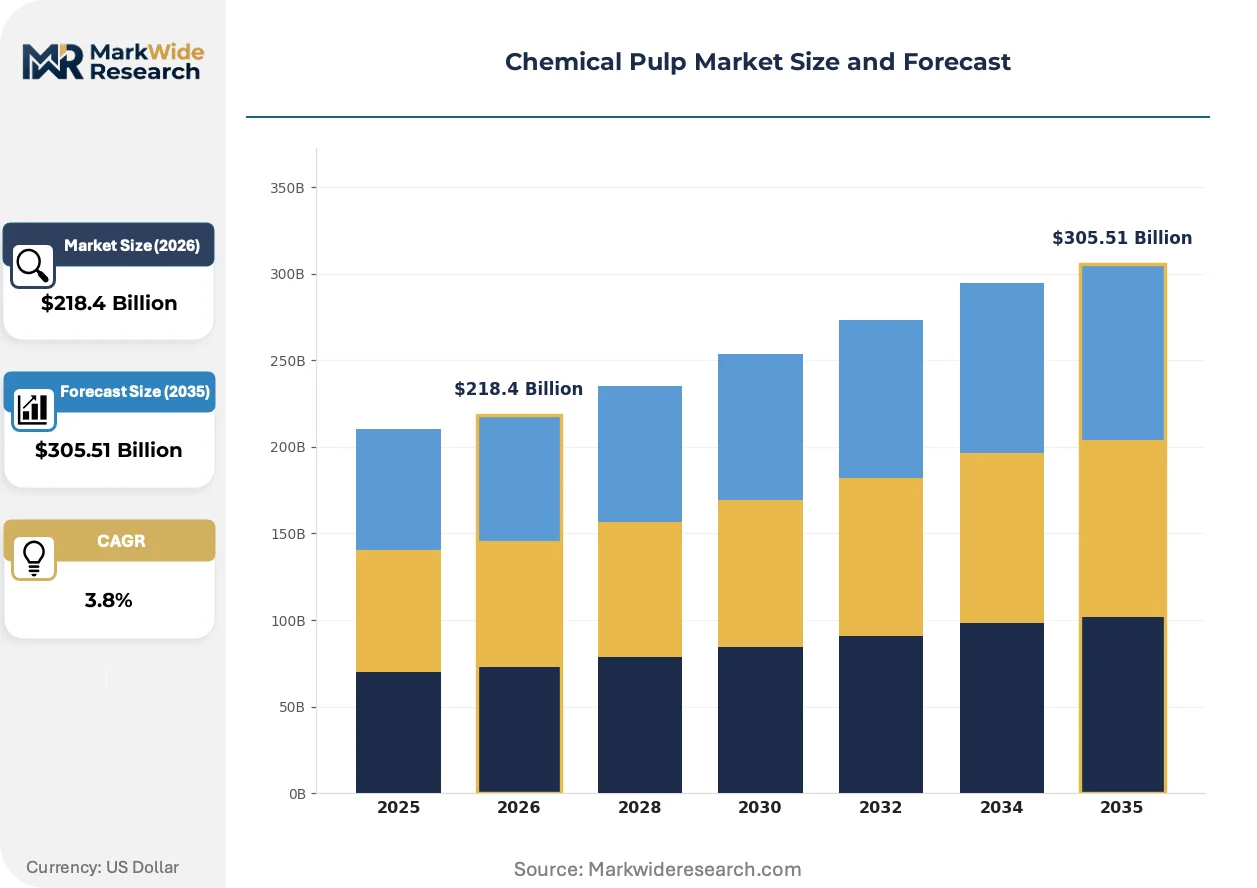
Market Dynamics
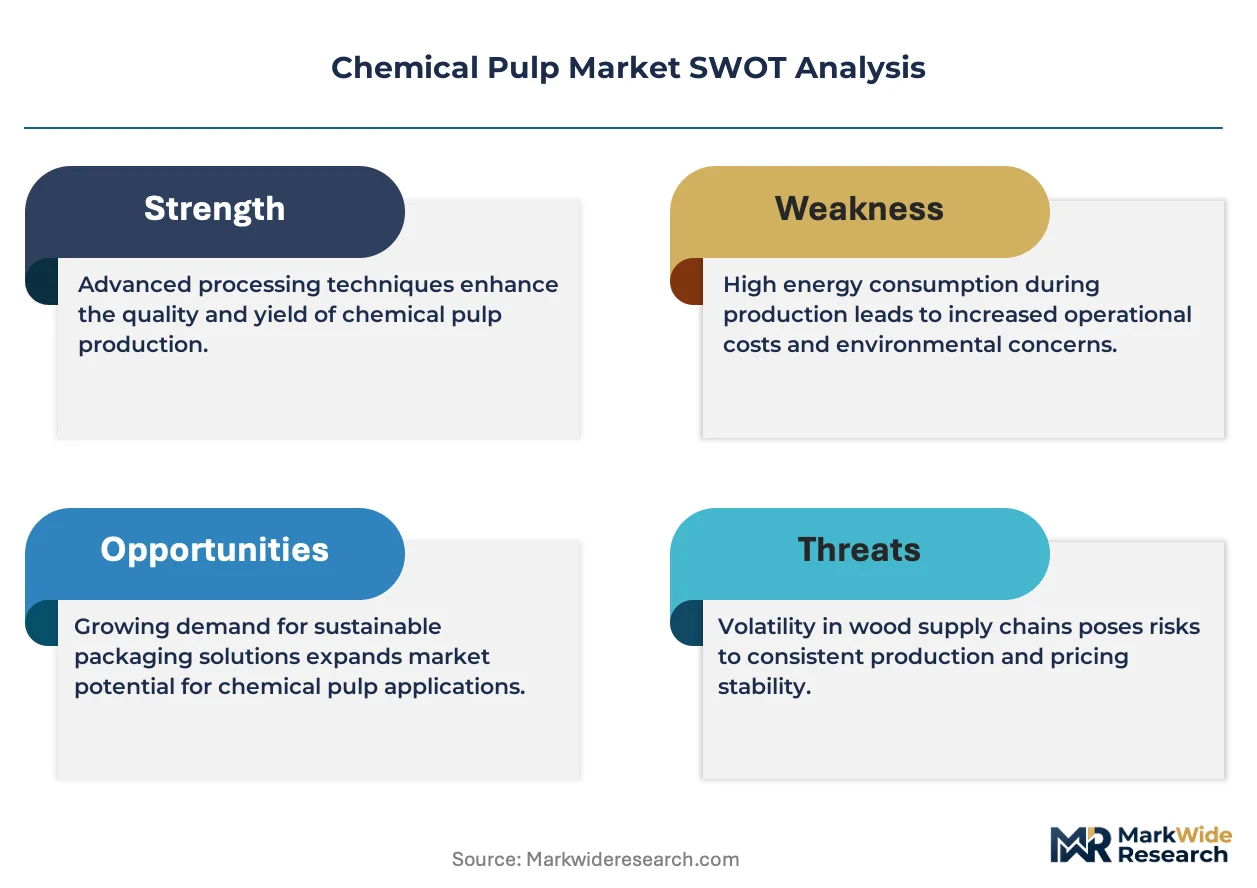
Capital recovery cycles for kraft mill chemical systems are compressing as EU carbon border adjustments force emission-intensive producers to front-load decarbonization investments or lose export competitiveness.
Growth Catalysts
- EU Green Deal carbon border mechanisms:Import tariffs on high-emission pulp are redirecting capacity investment toward Nordic and Iberian mills with integrated biomass energy recovery.
- Specialty food-contact packaging:Bleached hardwood pulp specifications for liquid carton and molded fiber trays are expanding specification volumes from dairy and beverage brand owners.
- Eucalyptus fiber cost structures:Brazilian plantation-to-port supply chains are delivering landed cost advantages for Asian tissue and viscose producers.
Market Restraints
- White liquor chemical input volatility:Sodium hydroxide and sodium sulfide prices track energy-intensive chlor-alkali production, squeezing kraft mill margin stability.
- Bleaching sequence compliance costs:REACH registration requirements for chlorine dioxide alternatives are extending qualification timelines for European mills.
- Mechanical pulp substitution in newsprint:Thermomechanical pulping retains cost advantages in declining publication grades, capping chemical pulp volume recovery.
Strategic Opportunities
- Indian tissue and hygiene expansion:Per-capita consumption gaps versus Southeast Asian benchmarks support greenfield bleached kraft capacity targeting domestic tissue converters.
- Textile viscose feedstock certification:CanopyStyle and FSC chain-of-custody requirements are creating premium pricing tiers for verified sustainable dissolving pulp.
- Black liquor gasification integration:Convergence of biomass boiler retrofits with carbon capture equipment is opening project finance structures for net-negative emission claims.
Industry Challenges
- Recovery boiler engineering talent scarcity:Specialized welding and pressure vessel expertise for high-temperature smelt systems is concentrating among retiring cohorts in Finland and Sweden.
- Elemental chlorine-free sequence retrofit complexity:Legacy multi-stage bleaching plants face extended downtime risks when integrating ozone or peroxide stages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Pulp Market |
| Market Size in 2026 | $218.4 Billion |
| Market Size in 2035 | $305.51 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bleached Pulp, Unbleached Pulp, Kraft Pulp, Sulfite Pulp End Use Industry: Paper Production, Packaging, Textile, Chemical Products Form: Sheets, Rolls, Slurries, Bales Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | BASF SE, Kemira, Dow Chemical Company, Clariant, AkzoNobel, Buckman, SNF Group, Ecolab, Nouryon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Pulp Market Strategic Shifts
Process intensification and emission accounting transparency are redefining competitive advantage in chemical pulp manufacturing, with technology adopters separating from legacy asset operators.
Advanced oxidation processes for effluent color removal are miniaturizing footprint requirements for closed-loop water systems. Nordic mills are retrofitting compact catalytic wet oxidation units to meet tightened EPA and MEE discharge limits. This technology compression is enabling brownfield capacity expansion on constrained mill sites without greenfield permitting timelines.
REACH chemical authorization procedures are restricting per- and polyfluoroalkyl substance use in pulp mill process aids. The industrial consequence is accelerated qualification of silicone-based defoamers and fluorine-free greaseproofing chemistries. European packaging-grade producers are most affected, with several mills completing multi-year substitution programs ahead of sunset dates.
Buyers are consolidating annual pulp volume commitments into multi-year direct contracting with integrated producers, bypassing traditional merchant traders. This channel compression is most visible among Asian tissue converters securing bleached eucalyptus kraft from Brazilian mill direct sales offices. The shift is displacing spot market liquidity and compressing price discovery transparency in regional benchmarks.
Chemical Pulp Market Segmentation
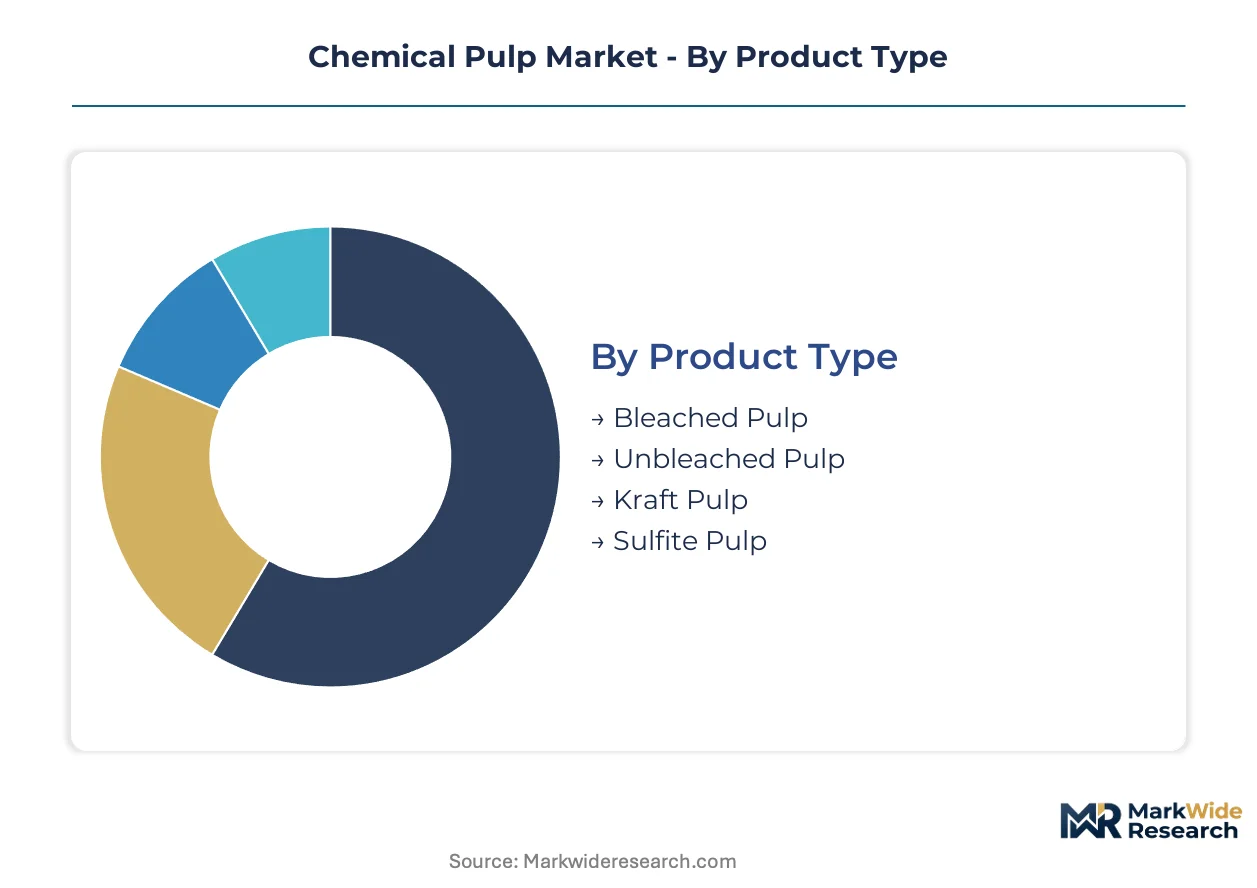
Chemical pulp segmentation tracks how fiber specifications, physical formats, and procurement channels align with distinct buyer economics. Channel selection varies sharply by segment—integrated mills favor direct contracting while merchant traders handle spot volumes for smaller converters.
Product Type:
Channel-mix patterns diverge sharply: bleached grades flow predominantly through direct mill contracts to tissue and printing paper producers, while unbleached and specialty pulps retain more distributor intermediation for regional packaging converters.
- Bleached Pulp:Cellulose fiber refined through multi-stage bleaching sequences to achieve brightness specifications above 88% ISO. Tissue manufacturers in India and Southeast Asia concentrate procurement through multi-year direct agreements with Brazilian eucalyptus suppliers, driven by brand-owner requirements for food-contact compliance and optical uniformity.
- Kraft Pulp:Alkaline-cooked fiber using sodium hydroxide and sodium sulfide white liquor at 160-180°C, yielding superior tear strength and fiber length retention. Linerboard producers across the US Gulf Coast and Nordic regions anchor consumption through integrated mill systems, constrained by chemical recovery capital intensity and EPA effluent limitation compliance costs.
- Unbleached Pulp:Retains native lignin content for strength-critical applications in corrugating medium and industrial packaging grades.
- Sulfite Pulp:Acid-cooked specialty fiber commanding niche margins in textile viscose and cellulose derivative markets where purity specifications outweigh yield economics.
Bleached pulp dominates installed base. Kraft pulp is where expansion concentrates.
End Use Industry:
Margin tiers separate commodity paperboard from certified specialty applications, with sustainability premiums concentrated in food-contact and textile feedstock segments.
- Paper Production:Tissue, printing, and writing grades consume the majority of bleached hardwood and softwood furnish. Asian converters in Indonesia and China drive volume through direct mill relationships, constrained by FSC chain-of-custody documentation requirements for European export markets.
- Packaging:Liquid carton and molded fiber tray specifications are expanding fastest among dairy and beverage brand owners demanding renewable barrier coatings. Nordic and Iberian mills capture premium positioning through integrated biomass energy recovery and EU Green Deal carbon border adjustment compliance.
- Textile:Dissolving pulp for viscose staple fiber requires high alpha-cellulose content and low hemicellulose contamination.
- Chemical Products:Cellulose derivatives including ethers, esters, and microcrystalline cellulose demand sulfite-processed specialty grades.
Paper production retains volume leadership. Packaging is expanding most quickly.
Form:
Logistics economics and customer handling infrastructure determine format selection, with bulk ocean shipments favoring bales and just-in-time converters preferring regional sheet or roll supply.
- Bales:Standard 250-kg compressed units for ocean freight and warehouse storage. Brazilian export terminals and Nordic port facilities concentrate infrastructure investment here, driven by intermodal transfer efficiency and Asian tissue mill receiving equipment standardization.
- Rolls:Continuous sheet wound for high-speed converting operations. European cartonboard integrators in Germany and Benelux specify roll delivery to minimize slitting waste and align with inline printing press feed systems.
- Sheets:Cut-to-size formats for specialty paper merchants and smaller packaging converters lacking roll handling capacity.
- Slurries:Pumpable fiber suspensions for integrated pulp-to-paper operations with shared water systems.
Bales dominate installed base. Rolls is where expansion concentrates.
Distribution Channel:
Customer scale and specification complexity reshape channel structure—large volume buyers internalize procurement while fragmented converters rely on distributor technical service.
- Direct Sales:Mill-to-converter contracting for annual volume commitments above 50,000 tonnes. Brazilian bleached eucalyptus kraft producers have established direct sales offices in Shanghai, Jakarta, and Mumbai, displacing traditional merchant traders and compressing spot market price discovery transparency.
- Distributors:Regional inventory and technical service for mid-sized packaging converters and specialty paper producers. North American distributors concentrate warehousing near Chicago and Atlanta rail hubs, constrained by working capital requirements for multi-grade stocking.
- Online Sales:Digital platforms for spot volume and trial quantities among smaller buyers.
- Retailers:Limited to consumer-facing specialty paper products rather than industrial pulp volumes.
Direct sales dominates installed base. Distributors retain defensive positioning in regional specialty grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances are tilting toward Brazilian eucalyptus suppliers and Nordic integrated mills as carbon border adjustments reshape competitive access. Asian tissue converters are locking in multi-year direct contracts to secure landed cost advantages. Regulatory divergence between EPA effluent limits and EU Green Deal mechanisms is fragmenting qualification requirements across destination markets.
Brazil
Eucalyptus plantation-to-port supply chains deliver bleached hardwood pulp to Asian tissue and viscose producers at sustained cost advantages. ANVISA food-contact compliance requirements align with FSC chain-of-custody certifications demanded by European dairy packaging brand owners. São Paulo state anchors industrial concentration, with mill direct sales offices in Shanghai and Jakarta displacing traditional merchant trading channels.
United States
Gulf Coast linerboard producers anchor unbleached kraft consumption through integrated mill systems serving corrugated packaging demand. EPA effluent limitation guidelines constrain bleaching sequence choices, pushing mills toward elemental chlorine-free retrofits. The Pacific Northwest retains specialty sulfite capacity for textile viscose feedstock, constrained by recovery boiler engineering talent scarcity.
Sweden
Nordic integrated mills capture premium positioning through biomass energy recovery and EU Green Deal carbon border adjustment compliance. REACH chemical registration requirements for chlorine dioxide alternatives extend qualification timelines for bleaching chemistry substitutions. The Stockholm-Uppsala corridor concentrates black liquor gasification pilot projects integrating carbon capture equipment.
China
Domestic tissue converters drive bleached eucalyptus kraft imports through direct mill relationships with Brazilian suppliers. MEE discharge limits for effluent color removal are accelerating adoption of compact catalytic wet oxidation retrofits. The Yangtze River Delta clusters packaging-grade production facing REACH-equivalent chemical authorization pressures for export-oriented output.
India
Per-capita tissue and hygiene consumption gaps versus Southeast Asian benchmarks support greenfield bleached kraft capacity targeting domestic converters. BIS standards for food-contact packaging grades are tightening specification requirements for liquid carton furnish. Maharashtra and Gujarat host emerging mill projects constrained by working capital requirements for chemical recovery system investments.
Chemical Pulp Market Competitive Environment
Concentration sits with diversified chemical conglomerates and specialty process chemical suppliers rather than pulp producers themselves. The vendor base spans three tiers: integrated kraft operators with captive chemical systems, merchant sulfite specialists serving niche derivative markets, and third-party chemical suppliers licensing bleaching and microbial control technologies. Strategic moves center on multi-year direct contracting bypassing traditional traders and portfolio diversification into fluorine-free process aids ahead of REACH sunset dates.
Within the specialty chemical supplier tier, BASF SE anchors global supply relationships across multiple continents through its diversified chemicals footprint. Kemira occupies a position exemplifying proprietary bleaching chemistry providers focused on effluent reduction for European and North American mill customers. Buckman represents the microbial control specialization vector, with solutions targeting high-consistency oxygen delignification stages. These three entities collectively illustrate how competitive advantage rotates toward scale chemistry assets and regulatory compliance capabilities.
| Leading Market Players |
|---|
| BASF SE |
| Kemira |
| Dow Chemical Company |
| Clariant |
| AkzoNobel |
| Buckman |
| SNF Group |
| Ecolab |
| Nouryon |
| Others |
Value Chain & Pricing Dynamics
Mill-scale recovery boiler capacity in Brazil and the Nordic region anchors cost floors for bleached kraft pulp, concentrating pricing power among integrated operators with captive biomass energy systems. Asian tissue converters absorb landed cost premiums through multi-year direct contracts that bypass volatile spot markets.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with pricing stratifying across FSC-certified premium, elemental chlorine-free standard, and unbleached economy tiers. Price differentiation rests on certification grade and volume scale, with REACH compliance timelines compressing margins for European mills. Cost compression in standard grades is intensifying because sodium hydroxide and sodium sulfide input volatility tracks energy-intensive chlor-alkali production. Small regional packaging converters exhibit highest price sensitivity, while multinational tissue brands prioritize supply security over unit cost.
Supply Chain Analysis
Panama Canal transit constraints periodically disrupt eucalyptus pulp flows from Brazilian Atlantic ports to Asian converters, exposing inventory carrying cost spikes. Geographic supply concentrates in Brazil, Sweden, and Finland, with raw material dependencies centering on plantation-grown hardwood fiber, white liquor chemicals, and chlorine dioxide alternatives. Single-source vulnerability sits with specialized recovery boiler engineering expertise concentrated among retiring cohorts in Nordic countries. Distribution runs through mill-direct sales offices in Shanghai and Jakarta for volume buyers, while regional distributors serve mid-sized converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chemical pulp market functions as a regulatory-moat industry where EU Green Deal carbon border entrenchment and REACH chemical authorization timelines protect incumbent positions. Switching costs for tissue and packaging converters are substantial given multi-year qualification protocols for food-contact compliance.
For Market Incumbents: Secure backward integration into plantation fiber supply through long-term eucalyptus concession agreements in São Paulo state. Deepen captive chemical recovery capacity to isolate margin stability from sodium hydroxide price volatility. Prioritize black liquor gasification retrofits ahead of EU carbon border adjustment enforcement to defend export competitiveness against high-emission import competitors.
For New Entrants and Emerging Players: Differentiate on CanopyStyle-certified dissolving pulp for textile viscose feedstock, where sustainability premiums remain underexploited. Target Indian tissue converters facing per-capita consumption expansion gaps, leveraging BIS food-contact standard alignment as entry qualification. Pursue direct mill relationships with domestic converters rather than merchant trader intermediation to capture channel compression value.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated kraft operators with biomass energy recovery and carbon capture pilot integration. Long-term viability hinges on regulatory compliance asset bases rather than commodity scale alone. Watch black liquor gasification project finance structures as inflection signal for net-negative emission claims capability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Fiber | Long-term eucalyptus concessions in Brazil lock in cost advantages against spot fiber markets. |
| Black Liquor Gasification Retrofit | Carbon capture integration opens project finance for EU Green Deal carbon border compliance. |
| CanopyStyle Certification Investment | Premium pricing tiers for verified sustainable dissolving pulp attract textile brand commitments. |
| Direct Sales Office Expansion | Mill-to-converter contracting in Shanghai and Jakarta compresses merchant trader margins. |
| Elemental Chlorine-Free Sequence Upgrade | REACH authorization timelines for chlorine dioxide alternatives protect compliant European assets. |
Study Parameters
Operator-level perspectives from kraft mill plant managers, tissue converter procurement leads, bleaching chemical R&D directors, and recovery boiler engineering specialists anchored the qualitative base. Secondary validation drew from customs trade data, SEC 10-K filings of integrated pulp producers, ANVISA food-contact registration databases, and FSC chain-of-custody audit reports. Bottom-up volume modeling and top-down macroeconomic triangulation reconciled segment-level outputs.
Sensitivity analysis across the analysis window tested input assumptions for white liquor chemical price volatility, EU carbon border adjustment implementation pace, and Brazilian real exchange rate fluctuation. Segmentation dimensions modeled include bleaching sequence tier, end-use industry, distribution channel format, and regional production hub regulatory cluster. CAGRs were derived from installed capacity utilization trajectories and substitution elasticity estimates for mechanical pulp in packaging applications.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or abrupt REACH authorization acceleration would require recalibration. Practitioners should keep alternative scenarios live as carbon border adjustment mechanisms and black liquor gasification technology maturation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Sawn Wood Market
Paper Products
Pigmented Paper Market
Paper Products
Base Paper Market
Paper Products
Filtration Paper Market
Paper Products
Inkjet Papers and Films Market
Paper Products
Europe Coated Paper Market
Paper Products
Latex-Saturated Paper Market
Paper Products
Uncoated Fine Paper Market
Paper Products
Leatheroid Paper Market
Paper Products
BPA Free Thermal Paper Market
Paper Products
Chemical Cellulose Market
Paper Products
Coated Wood Free Papers Market
Paper Products
Reprographic Paper Market
Paper Products
Insulation Paper Market
Paper Products
North America Thermal Paper Market
Paper Products
Global Kraft Paper Market