
 Dissolving Pulp Market | 2026-2036
Dissolving Pulp Market Size, Share, and Industry Trends Forecast 2026-2036
Dissolving Pulp Market Analytics
Textile spinners and nonwoven producers is collapsing as the dominant buyer archetype in dissolving pulp offtake, with pharmaceutical excipient and food casing segments capturing incremental volume. Sappi Limited leverages its Southern African woodfiber plantations to anchor premium specialty grades. Lenzing AG sustains vertical integration from pulp to branded cellulosic fibers, locking in captive demand. Rayonier Inc competes through its US Southeast timberland base, controlling cost-advantaged hardwood supply.
Dissolving pulp consists of high-alpha cellulose wood pulp processed through prehydrolysis kraft or acid sulfite methods, typically achieving cellulose purity above 90 percent for conversion into regenerated fibers and cellulose derivatives. Its primary purpose serves as the feedstock for viscose, lyocell, and acetate textile fibers plus pharmaceutical and food-grade cellulose ethers. Bleached dissolving pulp dominates current value generation due to its suitability for premium textile applications, while specialty dissolving pulp commands the densest margin pools from pharmaceutical and technical cellulose buyers. Unbleached variants occupy a narrowing niche in certain paper and packaging derivatives where brightness specifications remain relaxed.
The EU Green Deal and REACH framework constrain European pulp sourcing through mandatory chain-of-custody certification and chemical discharge limits, while China's MEE enforces wastewater standards on domestic dissolving pulp mills that reshape regional cost structures. FDA and EMA pharmaceutical-grade cellulose monographs further segment market access between food-contact and excipient-qualified supply tiers. Stakeholders must monitor regulatory divergence between forestry sustainability mandates and pharmaceutical purity standards when committing to capacity expansion or long-term offtake agreements.
Market Dynamics
Textile spinners' procurement of high-alpha cellulose feedstock is accelerating as lyocell capacity expands, while the EU Green Deal's chain-of-custody mandates reshape forest certification requirements across European supply bases.
Growth Catalysts
- EU Green Deal certification mandates:Mandatory chain-of-custody documentation under the EU Green Deal is compelling European viscose producers to source verified sustainable pulp, tightening supply relationships with certified plantation operators.
- China's viscose staple fiber expansion:Domestic capacity additions for regenerated cellulose fibers are concentrating demand for bleached dissolving pulp within Chinese coastal manufacturing clusters.
- Lyocell process adoption:Solvent-spinning technology for lyocell fibers is eliminating carbon disulfide emissions from traditional viscose production, attracting environmental compliance-focused textile brands.
Market Restraints
- Hardwood supply concentration:Cost-advantaged eucalyptus and southern pine fiber concentrates in Brazil and the US Southeast, creating geographic dependency for competitive pulp grades.
- Prehydrolysis kraft energy intensity:The dominant dissolving pulp production method requires substantial steam and chemical inputs, exposing margins to volatile natural gas and caustic soda pricing.
- REACH chemical discharge limits:European ECHA enforcement on adsorbable organic halogens and wastewater parameters elevates compliance costs for mills serving EU textile customers.
Strategic Opportunities
- Pharmaceutical excipient qualification:FDA and EMA monographs for microcrystalline cellulose and croscarmellose sodium create premium pricing tiers for GMP-certified dissolving pulp supply.
- Food casing cellulose ethers:Underpenetrated demand for methylcellulose and hydroxypropyl methylcellulose in processed food applications offers volume expansion beyond textile feedstock.
- India's technical textile push:PLI scheme incentives for man-made fiber production are stimulating greenfield dissolving pulp offtake agreements with domestic viscose investors.
Industry Challenges
- Pharmaceutical-grade certification timelines:FDA excipient qualification and IPEC-PQG GMP compliance require 18-36 month validation cycles, delaying margin capture from specialty grades.
- Prehydrolysis reactor retrofit complexity:Converting existing paper-grade kraft capacity to dissolving pulp specifications demands precise control of hemicellulose removal, stretching engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dissolving Pulp Market |
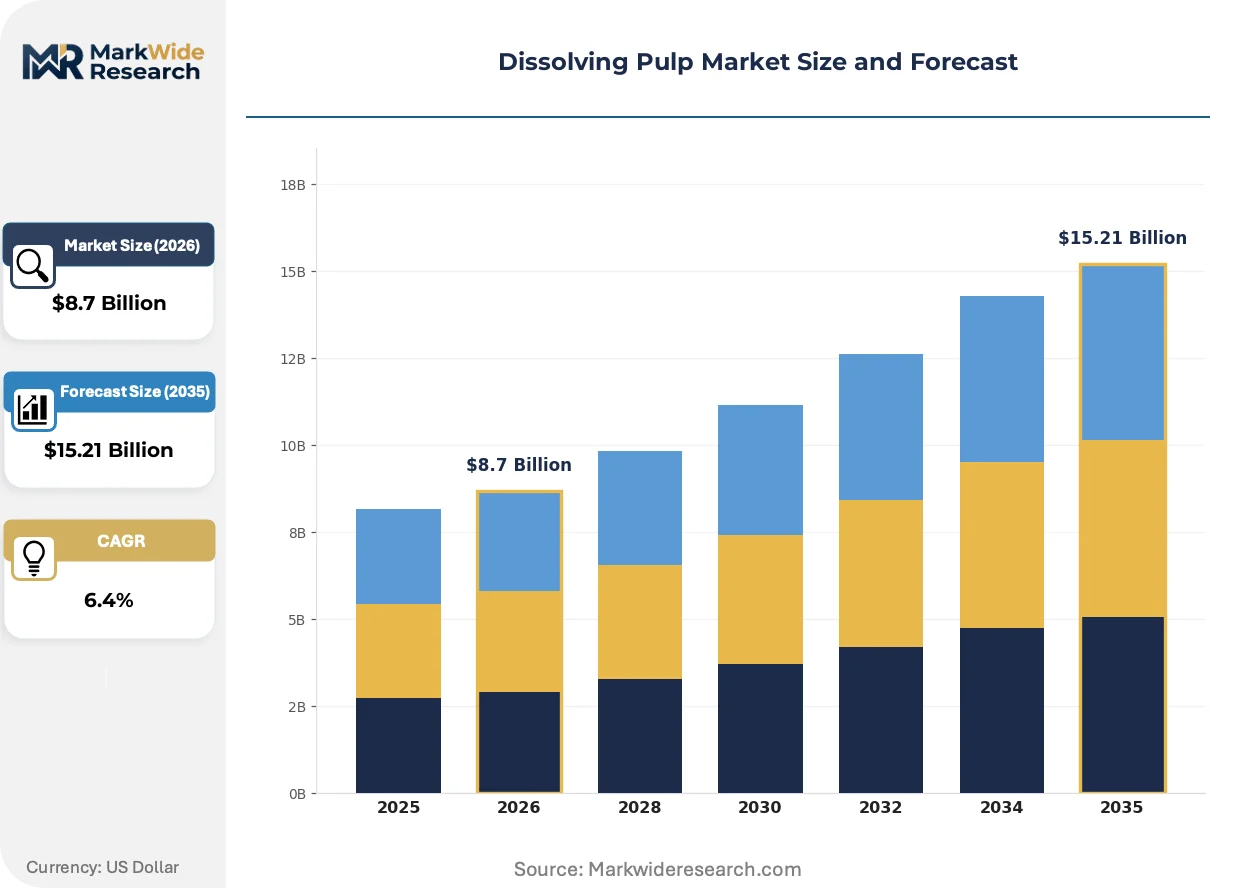
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Dissolving Pulp, Bleached Dissolving Pulp, Unbleached Dissolving Pulp, Specialty Dissolving Pulp End Use Industry: Textiles, Pharmaceuticals, Food Industry, Paper Production Geographical Application: Asia Pacific, North America, Europe, Latin America Distribution Channel: Direct Sales, Online Sales, Wholesale Distributors, Retail Sales |
| Companies Covered | Sappi Limited, Bracell Limited, Lenzing AG, Rayonier Inc, Aditya Birla Group, Nippon Paper Industries Co., Ltd., Sun Paper Group, Shandong Huatai Paper Co., Ltd., Tembec Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dissolving Pulp Market Evolving Landscape
Process chemistry advances and regulatory stringency are fragmenting production methodologies, while end-use buyers restructure procurement relationships around carbon accounting and traceability verification.
Prehydrolysis kraft technology is bifurcating the competitive landscape between commodity viscose feedstock and specialty pharmaceutical-grade supply. European textile houses are accelerating adoption of TCF and ECF bleaching sequences to meet ZDHC MRSL conformance. This technological divergence is compressing margins for undifferentiated dissolving pulp while enabling dense margin pools for certified specialty grades.
REACH authorization requirements for carbon disulfide and sodium hydroxide are tightening discharge parameters for European viscose producers. The industrial consequence is accelerated capital deployment toward closed-loop lyocell solvent recovery systems. Chinese MEE wastewater standards on chemical oxygen demand and adsorbable organic halogens are forcing domestic dissolving pulp mills toward membrane bioreactor upgrades or supply base relocation.
Textile brand carbon accounting mandates are restructuring procurement relationships from spot purchasing toward multi-year offtake agreements with verified forest certification. The segment being disrupted is commodity viscose staple fiber sourcing through traditional chemical traders. This pattern is most visible in Nordic and German apparel supply chains where Higg Index FEM scoring and Science Based Targets initiative commitments require pulp origin documentation.
Dissolving Pulp Market Segmentation
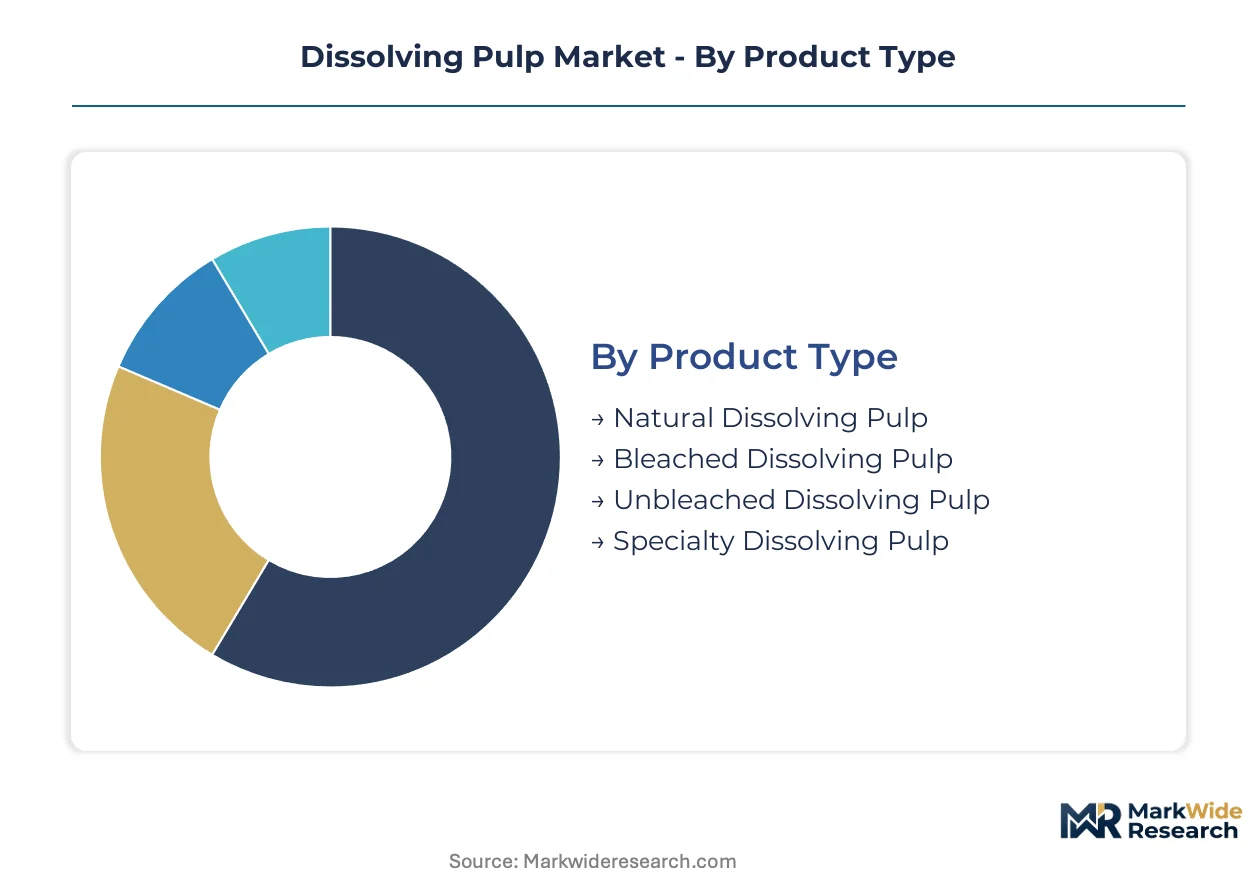
Dissolving pulp flows through sharply differentiated channels based on purity grades and end-use certification requirements. Pharmaceutical and food-grade segments command dedicated supply chains with audit documentation, while textile feedstock moves through volume-focused procurement networks.
Product Type:
Channel access varies dramatically by grade: bleached and specialty pulps flow through qualified supplier programs with chain-of-custody documentation, while unbleached variants move through commodity paper chemical distributors.
- Bleached Dissolving Pulp:High-alpha cellulose exceeding 90% purity processed through TCF or ECF bleaching sequences. Textile spinners in China's Jiangsu and Zhejiang provinces are consolidating procurement through multi-year offtake agreements with certified plantation operators to satisfy EU Green Deal documentation requirements.
- Specialty Dissolving Pulp:Pharmaceutical-grade and food-contact variants meeting FDA and EMA monograph specifications for microcrystalline cellulose and cellulose ether derivatives. GMP-certified supply commands dedicated distribution through excipient-qualified distributors with 18-36 month qualification timelines restricting channel entry.
- Natural Dissolving Pulp:Minimally processed wood cellulose retaining native lignin content for specific technical applications.
- Unbleached Dissolving Pulp:Lower brightness grades serving paperboard and packaging derivatives where optical properties remain secondary to structural performance.
By volume, bleached dissolving pulp leads. By growth pace, specialty grades are expanding most quickly.
End Use Industry:
Margin structures diverge sharply across applications, with pharmaceutical and food segments capturing premium pricing through certification barriers while textiles compete on scale economies.
- Textiles:Viscose staple fiber, lyocell, and modal production consuming the majority of dissolving pulp volume. Lyocell solvent-spinning technology is eliminating carbon disulfide emissions and attracting ZDHC MRSL-compliant brand procurement from Nordic and German apparel supply chains.
- Pharmaceuticals:Excipient-grade microcrystalline cellulose, croscarmellose sodium, and tablet binder applications. FDA and EMA GMP requirements create insulated pricing tiers with validated supplier relationships.
- Food Industry:Methylcellulose and hydroxypropyl methylcellulose for processed food casings and stabilizers.
- Paper Production:Niche applications in specialty paperboard where cellulose derivatives provide wet strength or barrier properties.
Textiles dominate tonnage. Pharmaceuticals deliver the steepest margin expansion trajectory.
Geographical Application:
Production concentration in specific timber basins shapes regional supply security, with eucalyptus plantations in Brazil and southern pine forests in the US Southeast anchoring cost-competitive supply.
- Asia Pacific:China's MEE wastewater enforcement on chemical oxygen demand and adsorbable organic halogens is forcing domestic mill upgrades or supply relocation to Indonesian and Vietnamese coastal manufacturing clusters.
- Europe:EU Green Deal chain-of-custody mandates and REACH chemical discharge limits are tightening forest certification requirements and elevating compliance costs for viscose producers.
- North America:US Southeast hardwood supply supports cost-advantaged production serving domestic textile and pharmaceutical customers.
- Latin America:Brazilian eucalyptus plantations provide fiber base for export-oriented dissolving pulp capacity.
Asia Pacific leads volume consumption. Europe is climbing fastest on regulatory-premium grade demand.
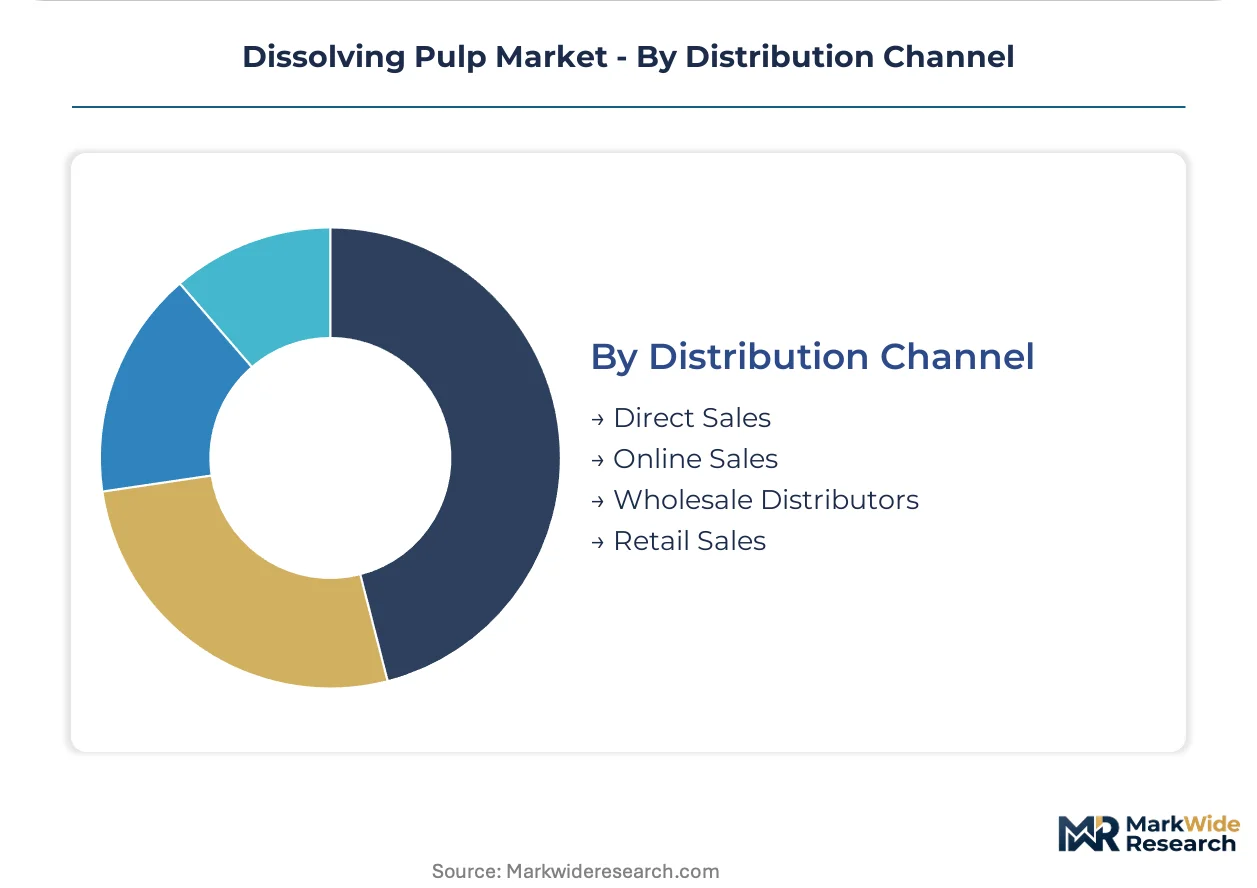
Distribution Channel:
Customer scale and certification requirements determine channel selection, with direct relationships dominating pharmaceutical supply and wholesale networks serving fragmented textile processors.
- Direct Sales:Long-term offtake agreements with verified forest certification documentation required by Higg Index FEM scoring and Science Based Targets initiative commitments. Major textile brands and pharmaceutical manufacturers bypass intermediaries for supply security.
- Wholesale Distributors:Chemical traders and paper industry distributors handling commodity bleached grades for smaller viscose staple fiber producers without qualified supplier status.
- Online Sales:Limited to standardized technical grades with published specifications for research and specialty chemical buyers.
- Retail Sales:Minimal presence confined to small-volume specialty cellulose for artisan and laboratory applications.
Direct sales capture the majority of value. Wholesale distributors retain volume relevance in commodity grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian eucalyptus pulp exports flow predominantly to Chinese coastal manufacturing clusters, establishing a dominant south-to-east trade corridor that anchors global dissolving pulp logistics.
China
Domestic viscose staple fiber capacity expansions in Jiangsu and Zhejiang provinces are concentrating bleached dissolving pulp demand within coastal manufacturing clusters. MEE wastewater enforcement on chemical oxygen demand and adsorbable organic halogens is forcing mill upgrades or supply relocation to Indonesian and Vietnamese processing facilities. Qingdao and Shanghai ports now handle the majority of imported dissolving pulp arrivals for textile conversion.
United States
US Southeast hardwood supply supports cost-advantaged production serving domestic pharmaceutical and textile customers. EPA discharge permits under the Clean Water Act constrain mill effluent parameters, elevating compliance investments for facilities serving FDA-qualified excipient markets. Georgia and Florida timberland bases anchor hardwood fiber supply for prehydrolysis kraft operations.
Germany
EU Green Deal chain-of-custody mandates are compelling viscose producers to source certified sustainable pulp with verified plantation documentation. ECHA REACH enforcement on adsorbable organic halogens tightens wastewater discharge limits for mills serving European textile customers. The Ruhr industrial region maintains specialized cellulose ether processing capacity for pharmaceutical and food-grade derivatives.
Brazil
Eucalyptus plantation harvesting cycles provide fiber base for export-oriented dissolving pulp capacity targeting Asian textile markets. IBAMA environmental licensing requirements govern plantation expansion and mill discharge parameters. São Paulo state hosts the densest concentration of bleached dissolving pulp production facilities serving international offtake agreements.
India
PLI scheme incentives for man-made fiber production are stimulating greenfield dissolving pulp offtake agreements with domestic viscose investors. CDSCO pharmaceutical-grade cellulose monographs create compliance pathways for excipient-qualified supply expansion. Gujarat and Maharashtra industrial corridors are emerging as primary locations for imported pulp processing and downstream fiber conversion.
Dissolving Pulp Market Competitive Landscape
Listed leaders compete with private specialists across plantation ownership and captive fiber supply. The vendor base concentrates around timberland-anchored producers with backward integration into pulp processing, creating tiered competition between scale-driven commodity suppliers and certification-focused specialty operators. Three archetypes dominate: plantation-integrated majors, textile-captive fiber producers, and pharmaceutical-grade specialists. Capacity expansion and multi-year offtake agreements with verified forest certification represent the dominant competitive moves reshaping procurement relationships.
Among plantation-integrated majors, Sappi Limited exemplifies the African timberland-anchored archetype with Southern African woodfiber bases, while Bracell Limited occupies a position within the Brazilian eucalyptus supply tier. Lenzing AG represents the textile-captive model with in-house production of branded cellulosic fibers locking in dedicated pulp demand. These three companies anchor the competitive structure across distinct geographic and vertical positioning vectors.
| Leading Market Players |
|---|
| Sappi Limited |
| Bracell Limited |
| Lenzing AG |
| Rayonier Inc |
| Aditya Birla Group |
| Nippon Paper Industries Co., Ltd. |
| Sun Paper Group |
| Shandong Huatai Paper Co., Ltd. |
| Tembec Inc. |
| Others |
Value Network & Pricing Analysis
Prehydrolysis kraft capacity utilization above 85 percent in Brazilian and US Southeast mills establishes floor pricing for bleached dissolving pulp grades. This scale concentration enables plantation-integrated producers to absorb caustic soda and natural gas volatility while marginal operators face margin compression.
Pricing Analysis
Lyocell solvent-spinning technology commands 15-20 percent premiums over conventional viscose feedstock due to ZDHC MRSL compliance and carbon accounting traceability. Three-tier pricing structure across pharmaceutical-grade, textile-premium, and commodity-standard levels reflects FDA and EMA certification barriers versus volume-scale spot purchasing. Cost compression in commodity bleached grades is intensifying because Chinese MEE wastewater enforcement is forcing domestic mill upgrades or supply relocation. Pharmaceutical excipient buyers exhibit the lowest price sensitivity due to 18-36 month GMP qualification timelines, while smaller viscose staple fiber producers remain highly sensitive to delivered-cost fluctuations.
Supply Chain Analysis
Strategic stockpiling of hardwood fiber dominates procurement behavior among European textile spinners facing EU Green Deal chain-of-custody mandates. Supply concentrates in Brazil, the US Southeast, and South Africa, with eucalyptus and southern pine fiber anchoring cost-competitive production. Prehydrolysis kraft operations draw from caustic soda, sulfur, and lime inputs with energy-intensive steam requirements. Single-source vulnerability from Brazilian port congestion or IBAMA licensing delays threatens Asian textile supply security. Distribution runs through long-term offtake agreements with certified plantation operators for major brands, while wholesale chemical traders serve fragmented viscose processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among lyocell-capable textile spinners and pharmaceutical excipient manufacturers, fragmenting procurement leverage across smaller viscose staple fiber producers.
For Market Incumbents: Secure multi-year offtake agreements with Higg Index FEM-verified forest certification to lock in brand procurement commitments ahead of EU Green Deal documentation deadlines. Defend margin position by accelerating captive lyocell capacity conversion, as solvent-spinning technology eliminates carbon disulfide emissions and attracts ZDHC MRSL-compliant buyers. Backward integration into Southern African or Brazilian plantation harvesting cycles insulates fiber cost exposure from spot pulp volatility. For New Entrants and Emerging Players: FDA excipient qualification fast-tracks offer the most penetrable entry path, as 18-36 month GMP validation cycles create incumbent stickiness but also supply gaps during qualification transitions. Target Indian PLI scheme beneficiaries in Gujarat and Maharashtra industrial corridors, where man-made fiber incentives are stimulating greenfield viscose investment without established pulp relationships. Lead with food-grade cellulose ether applications, as methylcellulose and hydroxypropyl methylcellulose demand in processed food casings remains underpenetrated relative to textile feedstock saturation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among plantation-integrated majors with captive textile brand relationships spanning multi-year offtake structures. Five-to-ten year viability favors timberland-anchored producers with backward integration into prehydrolysis kraft processing, as hardwood supply concentration intensifies geographic moats. Acquisition targets should display GMP-certified pharmaceutical-grade capacity or verified FSC/PEFC chain-of-custody documentation. The signal to watch is Chinese MEE enforcement intensity, as accelerated wastewater standard tightening would force domestic mill consolidation and redirect import demand toward certified foreign suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Multi-year offtake contracts with EU Green Deal documentation satisfy Higg Index FEM scoring requirements for Nordic apparel brands. |
| Backward Integration | Captive eucalyptus or southern pine plantations insulate Brazilian and US Southeast mills from hardwood fiber spot price volatility. |
| Green Manufacturing Transition | Lyocell solvent-spinning conversion eliminates carbon disulfide emissions and attracts ZDHC MRSL-compliant textile procurement. |
| Capacity Expansion | Prehydrolysis kraft additions in Indonesian and Vietnamese coastal clusters bypass Chinese MEE wastewater enforcement constraints. |
| Joint Venture | Indian PLI scheme partnerships with domestic viscose investors secure preferential offtake from man-made fiber capacity additions. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with textile spinning procurement directors, pharmaceutical excipient quality managers, dissolving pulp plant engineers, and forest certification auditors. Secondary validation drew from customs and trade flow databases, EU ECHA REACH enforcement disclosures, FDA drug master file listings, and SEC 10-K filings from listed plantation-integrated producers. Bottom-up capacity and consumption estimates were triangulated against top-down trade corridor analysis across Brazilian export terminals and Chinese port arrivals.
Across the analysis window, volume and value projections were modeled by product grade tier, end-use industry application, regional production hub, and certification status dimension. CAGRs were derived from segment-level demand elasticity coefficients and capacity utilization trajectories. Forecast inputs included lyocell capacity expansion pipelines, EU Green Deal implementation timelines, and Chinese MEE enforcement intensity indices.
Underlying assumptions cover sustained EU Green Deal chain-of-custody mandate adherence, stable Brazilian eucalyptus plantation harvesting cycles, and gradual Chinese wastewater standard convergence toward OECD benchmarks, with deviation risk concentrated in regulatory enforcement timing and hardwood fiber supply disruptions from IBAMA licensing delays. Revision becomes warranted when MEE enforcement intensity crosses thresholds forcing accelerated domestic mill closures or when lyocell capacity additions outpace dissolving pulp qualification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Sanitary Paper Products Market
Paper Products
Paper Dry Strength Agents Market
Paper Products
Bleached Hardwood Kraft Pulp Market
Paper Products
Paper Machinery Market
Paper Products
Inlay Paper Market
Paper Products
Paper Machine Systems Market
Paper Products
Heat Transfer Paper Market
Paper Products
Paper Goods Market
Paper Products
Carbonless Paper Market
Paper Products
Insulation Paper Market
Paper Products
Pharma Grade Paper Market
Paper Products
Glassine Paper Market
Paper Products
Paper Glass Market
Paper Products
Filtration Paper Market
Paper Products
Global Thin Papers Market
Paper Products
Graphic Paper Market