
 Ceramic Paper Market | 2026-2036
Ceramic Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Paper Market Intelligence
Performance specification for high-purity alumina-based papers is decoupling from the cost-driven commodity segment, which is dominated by standard ceramic fiber products. Morgan Advanced Materials specializes in engineered thermal products for extreme environments. Saint-Gobain leverages its vast material science portfolio to serve diverse industrial applications. Unifrax competes with a focus on high-temperature fiber insulation solutions for manufacturing and automotive end users.
Ceramic paper is a lightweight refractory material manufactured from high-purity refractory fibers, such as alumina-silica, bound with a minimal amount of organic binder. It exhibits low thermal conductivity, excellent thermal shock resistance, and flexibility, making it an effective high-temperature insulation and gasketing material. Within applications, demand from the aerospace components sector for heat shields and insulation wraps is growing faster than mature fire protection uses. Product types based on ceramic fiber remain the largest category by volume, while alumina-based papers command higher prices for specialized uses.
Product standards are influenced by regulations governing material safety and energy efficiency, including Europe's REACH regulation on chemical substances and OSHA guidelines in the United States on workplace exposure to refractory ceramic fibers. Aerospace applications require adherence to stringent certifications set by bodies like the FAA in the US and the EASA in Europe. Future material selection will hinge on balancing thermal performance requirements against evolving health and environmental regulations on fiber-based materials.
Market Dynamics
The market's central dynamic is the divergence between performance-driven and cost-driven segments, a split intensified by stringent aerospace requirements and tightening health regulations like REACH and OSHA guidelines on fiber exposure, forcing producers to innovate beyond standard materials.
Growth Catalysts
- Fire Safety Regulations:The EU's Construction Products Regulation and similar mandates in other regions create requirements for certified, non-combustible insulation in commercial buildings and infrastructure, directly benefiting ceramic paper sales for fire-stopping applications.
- Aerospace Component Demand:The aerospace industry's pursuit of lighter and more fuel-efficient aircraft drives demand for ceramic paper in heat shields, engine insulation, and thermal gaskets, where its low weight and high-temperature resistance are critical.
- Advanced Manufacturing Growth:Expansion in high-temperature industrial processes, particularly in German automotive and Japanese electronics manufacturing, requires sophisticated thermal management solutions, increasing the use of specialized alumina-based papers.
Market Restraints
- Input Cost Volatility:The price of high-purity alumina, a key raw material for premium-grade papers, is subject to fluctuations that can compress margins for manufacturers, particularly those serving specialized aerospace and electronics markets.
- Health and Safety Scrutiny:Regulatory bodies like OSHA in the US are imposing stricter workplace exposure limits for refractory ceramic fibers (RCFs), increasing compliance costs and driving some end-users to seek alternative insulation materials.
- Substitution from Alternative Materials:In less demanding applications, ceramic paper faces competition from lower-cost insulation materials like fiberglass and mineral wool, which can meet the thermal requirements for many commercial and industrial uses.
Strategic Opportunities
- Electric Vehicle Batteries:The growing need for thermal management solutions in electric vehicle battery packs to prevent thermal runaway presents a significant opportunity for ceramic paper as a lightweight, fire-resistant separator and insulation material.
- Bio-Soluble Fiber Development:Investing in the development and commercialization of high-performance, bio-soluble ceramic fibers can create a new product category that meets demanding thermal specifications while mitigating health and environmental concerns.
- Industrialization in Southeast Asia:As countries like Vietnam and Indonesia expand their steel, petrochemical, and glass manufacturing sectors, there is a rising need for new high-temperature furnace and kiln insulation, opening new geographic markets.
Industry Challenges
- Aerospace Certification Hurdles:Gaining material qualification for aerospace applications involves extensive and costly testing to meet stringent standards set by bodies like the FAA and EASA, creating a high barrier to entry for new or smaller suppliers.
- Performance Standardization Gaps:A lack of universally accepted standards for testing and reporting thermal conductivity and shock resistance across different product grades complicates material selection for engineers and procurement managers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Paper Market |
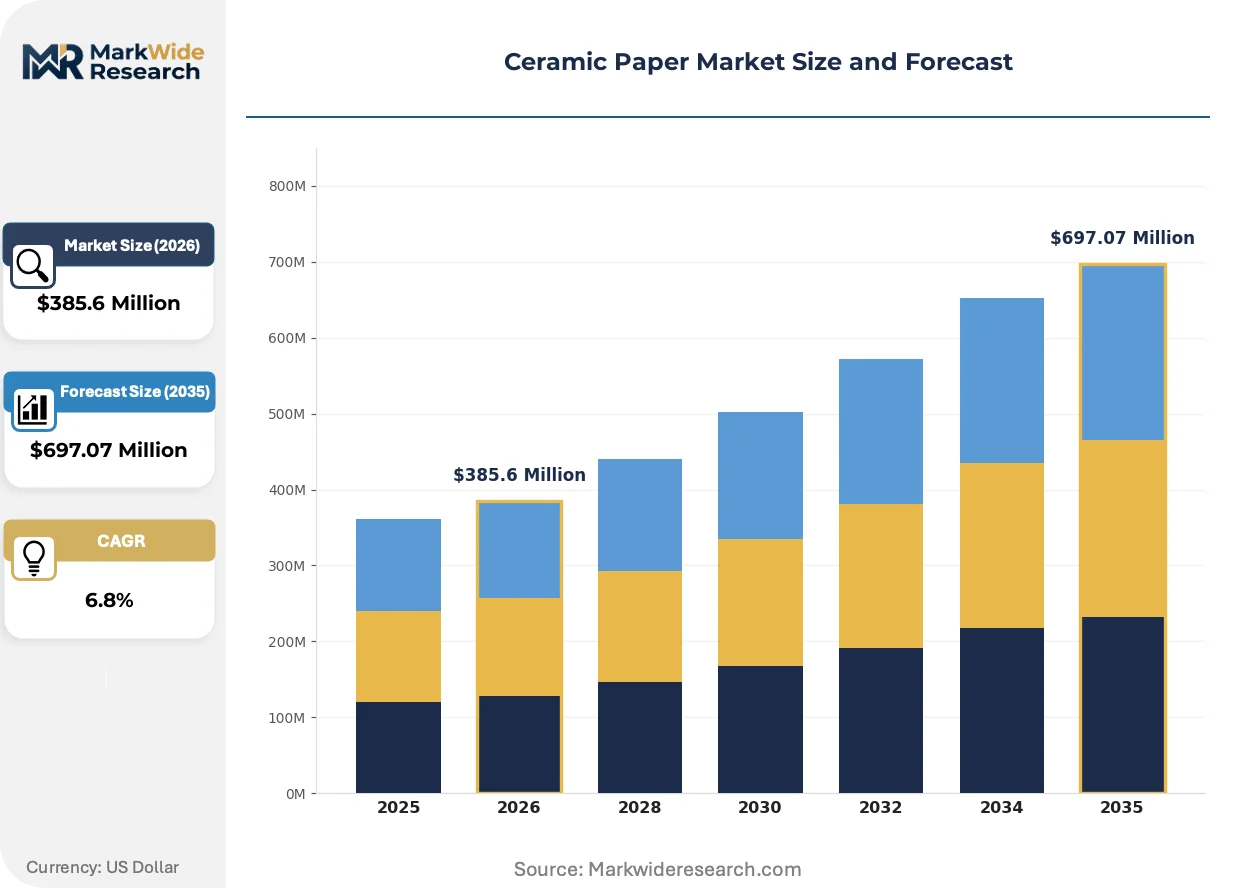
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Silicate, Ceramic Fiber, Alumina, Others Application: Insulation, Fire Protection, Automotive Parts, Aerospace Components End User: Construction, Manufacturing, Aerospace, Automotive Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | 3M, Kyocera, Ibiden, CeramTec, Saint-Gobain, Morgan Advanced Materials, CoorsTek, Zircar Refractories, Unifrax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Paper Market Strategic Shifts & Innovations
Material science advancements are focused on enhancing thermal insulation properties while improving the health and safety profile of ceramic fibers. This evolution is driven by parallel demands from high-tech sectors for performance and from regulators for greater product safety and sustainability.
Nanofiber technology is enhancing the thermal insulation capabilities of ceramic papers, allowing for thinner and lighter products with superior performance. The aerospace and microelectronics industries are early adopters, driven by the need for effective thermal management in compact spaces. This advanced material science is converging with thermal modeling software to enable the design of highly precise, application-specific insulation components.
Europe's REACH regulation continues to place scrutiny on chemical substances, including certain binders and refractory fibers used in ceramic paper production. This regulatory pressure accelerates industry investment in alternative formulations, such as alkaline earth silicate (AES) fibers, that offer comparable performance with an improved safety profile. The industrial furnace and metal treatment sectors are most affected, prompting a re-evaluation of insulation specifications for new equipment and retrofits.
End-users are shifting their purchasing criteria from upfront cost to a total-system performance model, particularly for industrial insulation. This change in procurement behavior favors suppliers that can provide documented evidence of energy savings, reduced downtime, and longer material lifespan. The trend is most prominent in the North American petrochemical sector, where energy efficiency directly impacts operational profitability and compliance with environmental targets.
Ceramic Paper Market Segmentation
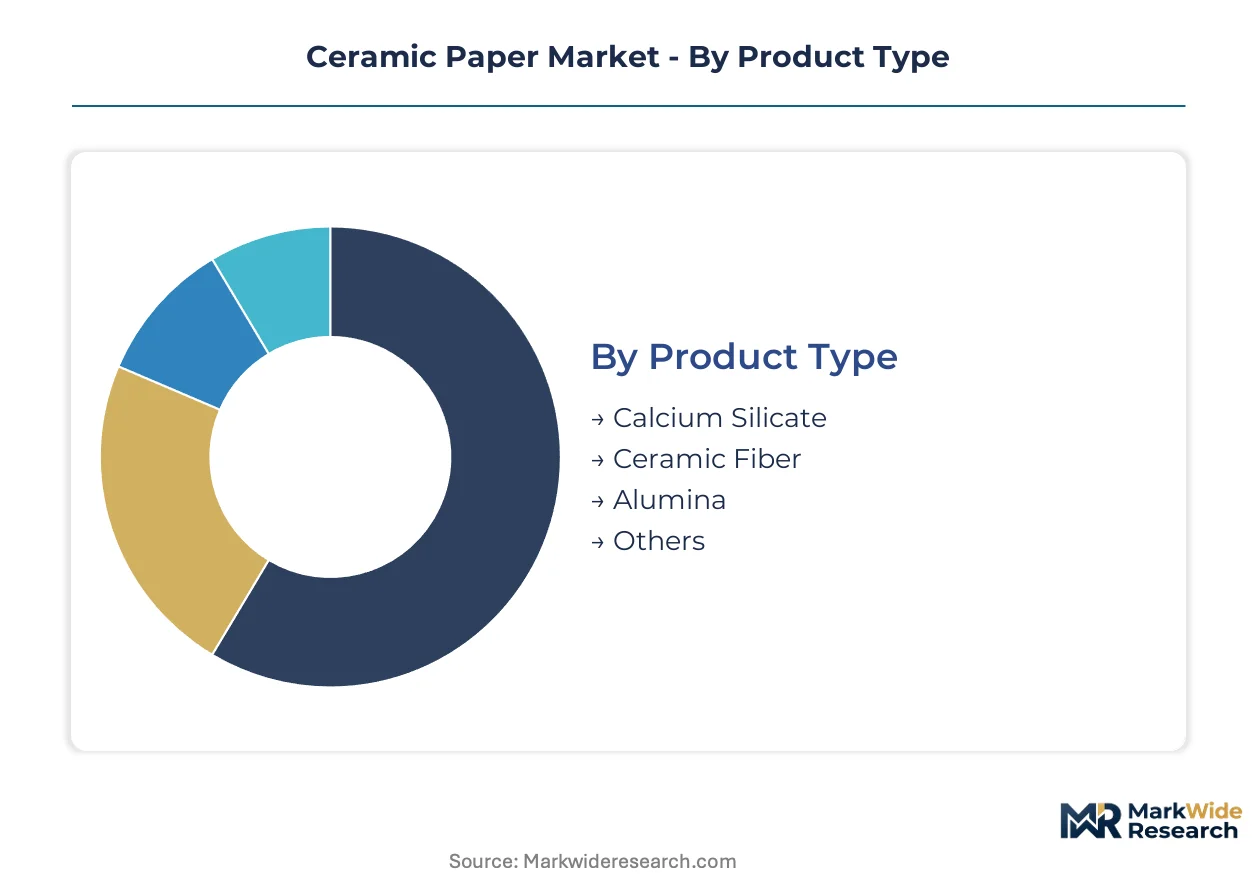
The ceramic paper market's structure reflects diverse material compositions and varied end-use requirements. Understanding these segments clarifies the interplay between performance specifications, cost sensitivities, and regulatory compliance across different industry verticals. This analysis highlights areas of concentrated demand and future growth trajectories.
Product Type:
Product types in ceramic paper range from widely integrated commodity solutions to highly specialized materials for embedded high-performance systems.
- Ceramic Fiber:This lightweight refractory material, often alumina-silica based, offers low thermal conductivity and flexibility. Demand concentrates in mature fire protection uses and industrial furnace insulation, where cost-effectiveness is a primary driver.
- Alumina:This high-purity material provides superior thermal stability and excellent electrical insulation properties for demanding applications. Its demand is strongest in aerospace components for heat shields and advanced electronics manufacturing in Germany and Japan, requiring extreme temperature resistance.
- Calcium Silicate:This segment offers good thermal insulation and mechanical strength, finding use in general industrial applications and passive fire protection systems.
- Others:This category includes niche formulations like bio-soluble fibers, addressing specific regulatory or performance demands in emerging applications.
Volume placements concentrate in Ceramic Fiber products; the faster expansion belongs to Alumina-based papers.
Application:
Applications for ceramic paper dictate specific material performance requirements and influence the overall value proposition across diverse industrial settings.
- Aerospace Components:Ceramic paper provides critical lightweight insulation and thermal management for engine compartments and heat shields in aircraft and spacecraft. Strict FAA and EASA certifications drive demand for high-performance, durable solutions in this sector.
- Insulation:This broad application encompasses thermal barriers in industrial furnaces, kilns, and high-temperature processing equipment. Energy efficiency mandates and operational cost reduction are significant drivers for improved insulation performance.
- Fire Protection:Ceramic paper serves as a non-combustible barrier in construction and marine applications, adhering to stringent fire safety regulations.
- Automotive Parts:Used for exhaust system insulation, battery thermal management in electric vehicles, and heat shields, ceramic paper contributes to vehicle safety and efficiency.
Demand for traditional Insulation applications remains stable, while Aerospace Components demonstrate dynamic growth.
End User:
End-user segments define distinct procurement patterns and specific regulatory landscapes that ultimately shape product development and sales strategies.
- Aerospace:This sector demands materials with extreme temperature resistance and lightweight properties for aircraft and spacecraft thermal management. Stringent qualification processes set by bodies like the FAA are paramount for material adoption.
- Manufacturing:Encompassing various high-temperature industrial processes, this segment utilizes ceramic paper for furnace linings, kiln insulation, and thermal gaskets. Advanced manufacturing centers in Germany and Japan are significant consumers of specialized papers.
- Construction:This segment uses ceramic paper for fire-stopping, passive fire protection, and thermal insulation in commercial buildings, driven by building codes and safety standards.
- Automotive:Ceramic paper finds application in vehicle exhaust systems, catalytic converters, and increasingly for thermal management in electric vehicle battery packs.
The Manufacturing sector provides foundational volume, while Aerospace drives material innovation and performance upgrades.
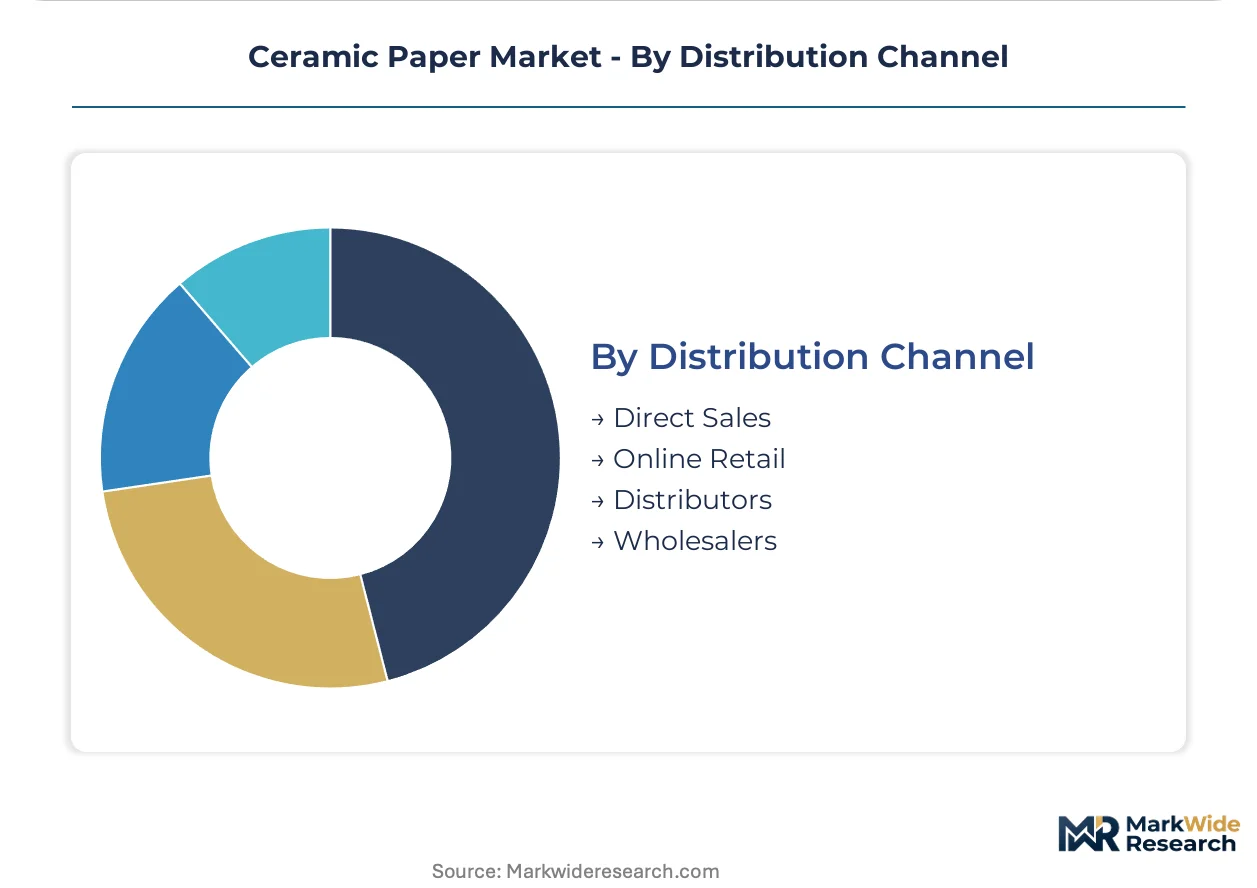
Distribution Channel:
Distribution channels reflect the market's maturity and the complexity of reaching diverse customer bases, influencing product accessibility and pricing strategies.
- Direct Sales:Manufacturers engage directly with large industrial clients, particularly for specialized or high-volume orders, allowing for customized solutions and stronger technical support. This channel is critical for aerospace and advanced manufacturing customers.
- Distributors:These intermediaries provide broader market access, serving smaller businesses and diverse regional markets with a range of ceramic paper products. They manage inventory and logistics for a fragmented customer base, especially in construction and general industrial uses.
- Online Retail:This channel caters to smaller volume purchases and niche applications, offering convenience and a wide selection of standard ceramic paper products.
- Wholesalers:Wholesalers typically supply to distributors or large retailers, handling bulk volumes of standard ceramic paper products for various industrial and construction applications.
Efficiency in Distributors supports broad market penetration, whereas Direct Sales offers specialized customer engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing hubs like those in Bavaria and the industrial corridors of Japan drive demand for high-performance ceramic papers. These regions, alongside the United States and South Korea, concentrate advanced manufacturing capabilities requiring sophisticated thermal management solutions. Stringent regulations governing fire safety and energy efficiency further shape material selection across these key markets.
United States
The United States aerospace sector, particularly around Seattle and Los Angeles, demands advanced ceramic papers for heat shields and engine insulation. FAA certifications establish rigorous material performance and safety requirements for these critical components. OSHA guidelines influence workplace exposure limits for refractory ceramic fibers in manufacturing facilities across the Midwest.
Germany
German automotive manufacturers, concentrated in regions like Bavaria and Baden-Württemberg, utilize specialized alumina-based papers for advanced thermal management. The EU's Construction Products Regulation mandates certified non-combustible insulation, boosting ceramic paper sales in commercial buildings. REACH regulation impacts the selection of chemical substances in ceramic paper production throughout Europe.
Japan
Japanese electronics manufacturing, particularly in the Kanto region, requires high-purity alumina papers for microelectronics and industrial furnaces. METI initiatives support advanced material development for energy-efficient industrial processes. JIS standards guide product specifications for ceramic materials used in high-temperature applications across the country.
South Korea
South Korea's expanding electric vehicle battery production, centered in regions like Gyeonggi and Chungcheong, seeks lightweight thermal management solutions. National safety regulations for EV battery components drive the adoption of fire-resistant ceramic paper separators. The country's shipbuilding industry also uses ceramic papers for high-temperature insulation in maritime vessels.
Ceramic Paper Market Key Industry Players
Capital-heavy producers compete with asset-light designers, creating a tiered market structure for ceramic paper solutions. This market features integrated material specialists focusing on extreme environments and niche high-performance solution providers catering to specialized aerospace needs. Volume-focused manufacturers serve broader industrial and construction applications where cost-effectiveness is primary. Dominant competitive moves include strategic partnerships for application-specific development and capacity expansion to meet growing industrial demand.
Specialists in engineered thermal products, Morgan Advanced Materials and Saint-Gobain, exemplify the premium segment for ceramic paper. Morgan Advanced Materials focuses on engineered thermal products for extreme environments, serving critical aerospace and industrial applications globally. Saint-Gobain, leveraging its vast material science portfolio, occupies a strong position in diverse industrial applications, including high-temperature insulation. Unifrax competes with a focus on high-temperature fiber insulation solutions for manufacturing and automotive end users, representing a key player in the specialized fiber segment. These companies collectively anchor the market's innovation and high-performance offerings.
| Leading Market Players |
|---|
| 3M |
| Kyocera |
| Ibiden |
| CeramTec |
| Saint-Gobain |
| Morgan Advanced Materials |
| CoorsTek |
| Zircar Refractories |
| Unifrax |
| Others |
Cost & Logistics Intelligence
Vertically integrated specialists and family-owned mid-caps define the ceramic paper market's supply behavior. This structure influences pricing discipline, particularly for high-purity alumina products.
Pricing Analysis
Performance-based pricing anchors the ceramic paper market, reflecting the critical function of thermal management. Price differentiation stems from material purity and the level of aerospace certification required. Pricing softness reflects competition from lower-cost alternatives in less demanding applications. Aerospace and advanced manufacturing end-users are least price-sensitive, while construction and general industrial buyers prioritize cost-effectiveness.
Supply Chain Analysis
Stringent material qualification for aerospace applications gates access to premium ceramic paper supply chains. Key manufacturing hubs in Germany, Japan, and the United States concentrate high-purity alumina production. Dependence on specialized refractory fibers and organic binders creates raw material dependencies. Commodity price volatility for alumina poses a structural risk. Distribution runs through direct sales channels for specialized products and distributors for broader industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ceramic paper market is fundamentally a cost-of-compliance story, where stringent regulations like the EU's REACH create a significant barrier-to-entry moat for compliant manufacturers. This regulatory landscape favors established players capable of navigating complex material safety standards.
For Market Incumbents: Anticipate continued regulatory evolution, particularly concerning refractory ceramic fibers, by proactively investing in bio-soluble fiber R&D. Diversify product portfolios to mitigate substitution threats from lower-cost alternatives in less demanding applications. Strengthen technical support for aerospace clients to reinforce market position against emerging specialized entrants.
For New Entrants and Emerging Players: Nanofiber technology offers a technology-first wedge into high-performance thermal management for electric vehicle batteries. Target underpenetrated thermal runaway protection in EV battery packs, particularly in rapidly industrializing Southeast Asian markets. A go-to-market angle focusing on lightweight, high-efficiency solutions for battery separators can capture early adopters.
For Investors and Strategic Acquirers: Increased capital expenditure in bio-soluble fiber manufacturing is the leading indicator that the market is shifting towards sustainable, high-performance solutions. The long-term viability favors specialists with robust R&D capabilities and aerospace certifications. Target acquisition archetypes include niche innovators with proprietary bio-soluble technologies or established players with strong positions in advanced manufacturing centers.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Alumina Papers | Meeting demand from advanced manufacturing centers in Germany and Japan. |
| Bio-Soluble Fiber Product Development | Mitigating health and safety scrutiny from REACH and OSHA regulations. |
| Aerospace Certification Investment | Strengthening market access for high-performance components in the US and Europe. |
| Strategic Partnership for EV Batteries | Accelerating thermal management solutions for electric vehicle battery packs. |
| Digital Integration of Thermal Modeling | Enabling precise, application-specific insulation designs for microelectronics. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, complemented by primary interviews with plant managers, aerospace engineers, procurement leads, and R&D directors. This approach combined bottom-up market sizing with top-down validation. Secondary research encompassed technical journals, company reports, and government publications from the FAA and EASA.
Market volume and value were modeled at a granular level across product type, application, end-user, and regional dimensions throughout the forecast period. Compound annual growth rates were derived from historical trends and anticipated shifts in demand drivers. Key forecast inputs included aerospace production forecasts and industrial capacity expansion plans.
Several conditions sit outside the modeled scope, including unforeseen geopolitical disruptions and rapid raw material shifts. Forecasts reflect assumptions regarding regulatory stability and technological adoption rates. A model refresh is warranted upon material change in global aerospace production or bio-soluble fiber breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Pigmented Paper Market
Paper Products
Polyester Synthetic Paper Market
Paper Products
Softwood Pulp Market
Paper Products
North America Specialty Paper Market
Paper Products
Paper Goods Market
Paper Products
Decorative Plastic and Paper Laminates Market
Paper Products
Europe Tissue and Hygiene Paper Market
Paper Products
Super Calendered Glassine Paper Market
Paper Products
Sanitary Paper Products Market
Paper Products
Medium Density Fiberboard Market
Paper Products
Pulp and Paper Market
Paper Products
Printing and Writing Papers Market
Paper Products
GCC Stone Paper Market
Paper Products
Functional and Barrier Coatings for Paper Market
Paper Products
Unbleached Softwood Kraft Pulp Market
Paper Products
Europe Medium-Density Fiberboard Market