
 LAMEA Optical Brighteners Market | 2026-2036
LAMEA Optical Brighteners Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Optical Brighteners Market Insights
Specialty detergent formulators are redrawing procurement priorities across the LAMEA Optical Brighteners Market, pulling volume toward high-performance liquid concentrates. BASF leverages its integrated stilbene precursor network to sustain cost competitiveness in Brazilian textile corridors. Clariant anchors its position through application-specific technical service teams stationed in Casablanca and São Paulo. Huntsman International LLC differentiates via backward integration into sulfonation chemistry, controlling raw material quality for African coating customers.
Optical brighteners are organic compounds, predominantly stilbene and coumarin derivatives, that absorb ultraviolet light and re-emit it as visible blue fluorescence to mask yellowing in substrates. Manufacturers synthesize these agents through sulfonation and diazotization pathways, with final formulations tuned for substrate compatibility in textiles, paper, and plastics. The textile end-user segment dominates current value generation across LAMEA, while the personal care application category records the fastest trajectory as Moroccan and South African cosmetic manufacturers adopt optical brightening agents for premium skin and hair formulations. Powder forms retain manufacturing scale advantages, though liquid concentrates capture margin pools through reduced handling costs and dosing precision.
Brazil's ANVISA and South Africa's national chemical regulator enforce registration requirements that shape product entry pathways and formulation disclosure standards for optical brighteners in consumer-facing applications. Morocco's alignment with REACH-derived import protocols forces reformulation of European-destined textile brightener shipments. Stakeholders must monitor evolving biodegradability thresholds under Latin American national chemical inventories, as these frameworks will determine which chemistries retain market access across the forecast horizon.
Market Dynamics
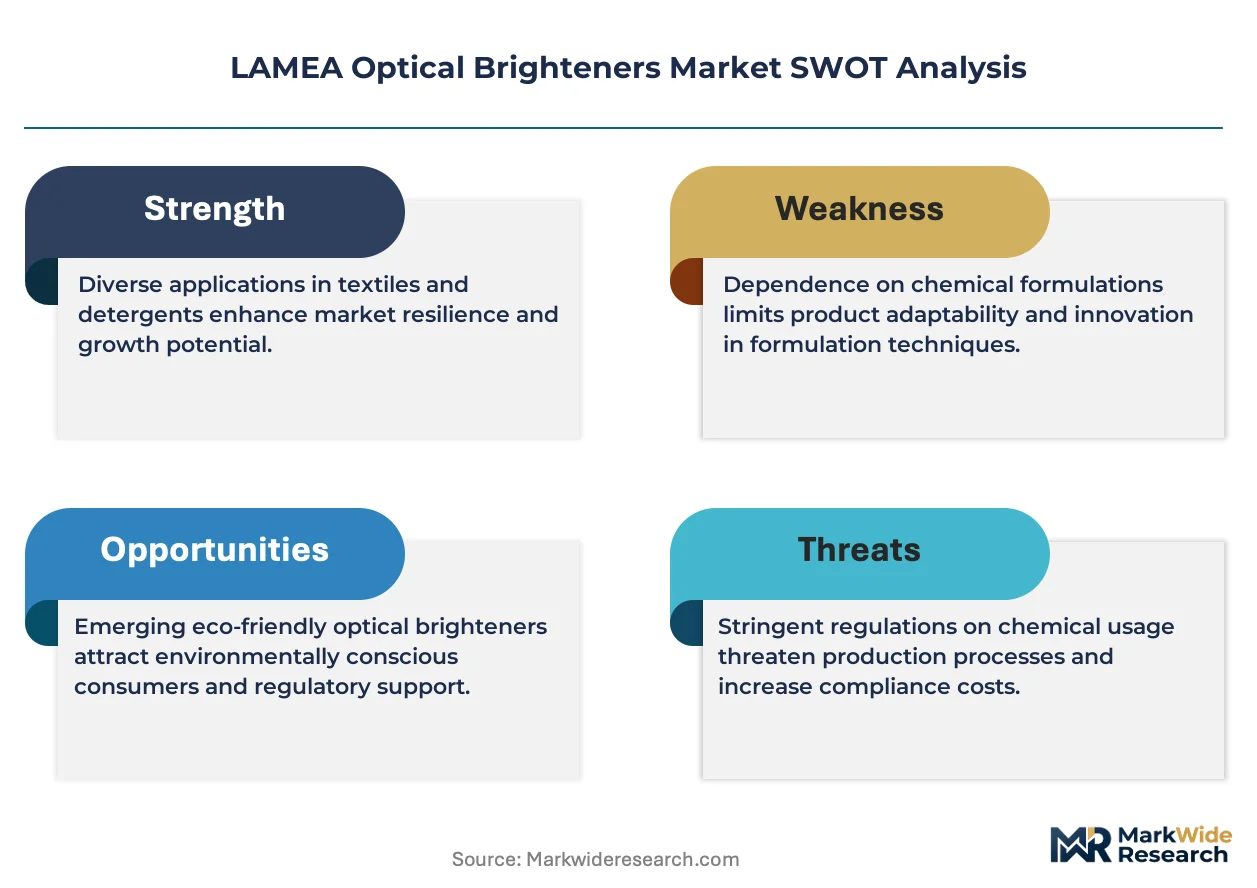
REACH-aligned import protocols across European-linked African trade corridors are forcing immediate reformulation of textile brightener shipments, compressing lead times for non-ionic chemistry transitions.
Growth Catalysts
- Export-quality whiteness mandates:Textile mills in Brazil's São Paulo industrial belt are expanding fluorescent brightening agent procurement to meet international buyer specifications for premium fabric grades.
- Personal care premiumization:Moroccan and South African cosmetic manufacturers are integrating optical brightening agents into skin and hair formulations, creating new volume pools outside traditional industrial applications.
- Liquid concentrate adoption:Specialty detergent formulators are prioritizing high-performance liquid concentrates for reduced handling costs and dosing precision in large-scale operations.
Market Restraints
- Stilbene precursor cost volatility:Sulfonation pathway feedstock prices fluctuate with petroleum-derived aromatic supply chains, squeezing margin stability for derivative manufacturers.
- Biodegradability threshold uncertainty:Latin American national chemical inventories are evolving biodegradability standards that threaten market access for legacy chemistries without reformulation investment.
- Coumarin derivative substitution:Alternative optical brightening chemistries face performance gaps in high-temperature textile processing applications.
Strategic Opportunities
- Underpenetrated African coating sector:Backward integration into sulfonation chemistry offers quality control advantages for suppliers targeting industrial coating customers in Nigeria and Kenya.
- Technical service localization:Application-specific support teams stationed in Casablanca and São Paulo can capture margin pools through formulation partnership models.
- Non-ionic formulation leadership:Early alignment with REACH-derived protocols positions suppliers for preferential access to European-destined textile shipments from North African export hubs.
Industry Challenges
- ANVISA registration timelines:Brazil's national health surveillance agency enforces extended disclosure and safety evaluation periods for optical brighteners in consumer-facing applications.
- Legacy powder-to-liquid conversion capex:Manufacturing scale advantages for powder forms create capital intensity barriers for producers seeking liquid concentrate capability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Optical Brighteners Market |
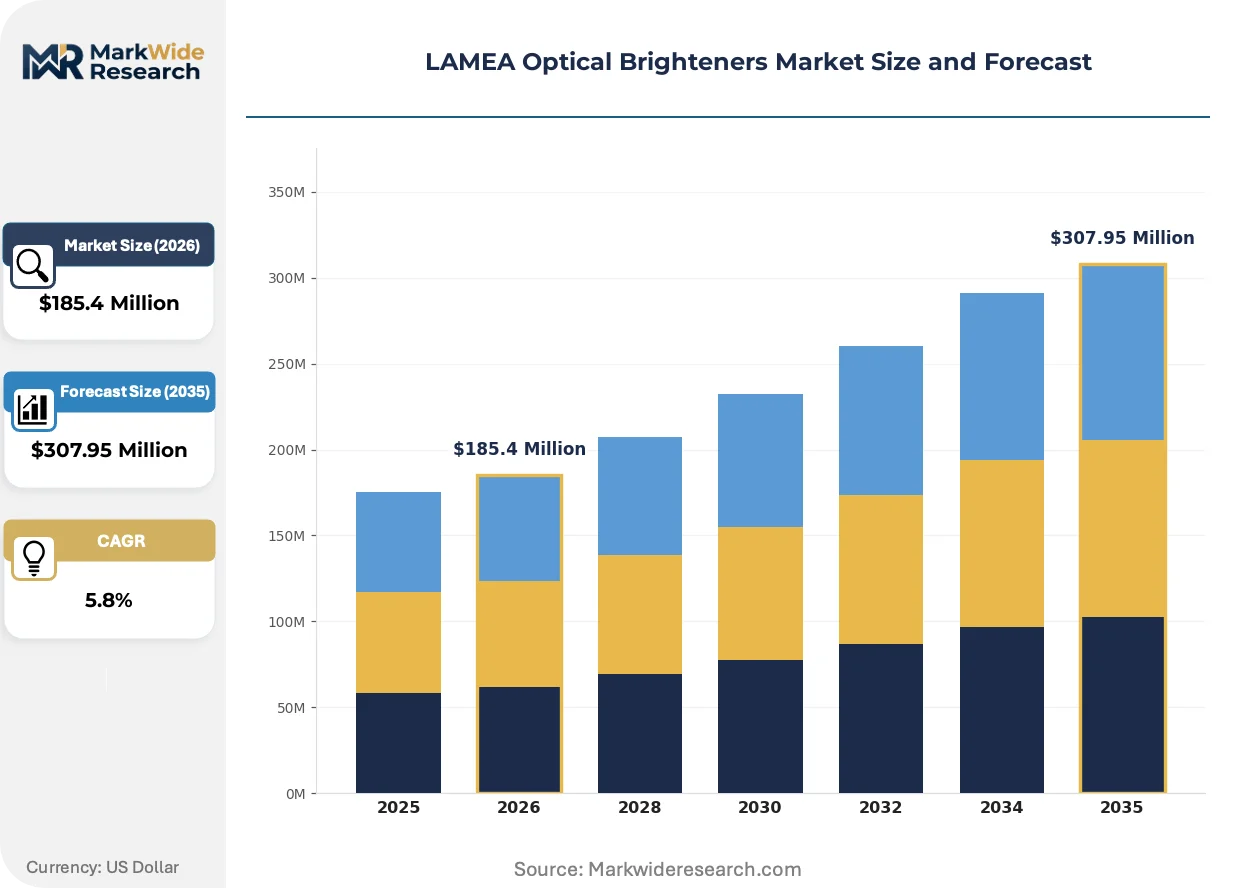
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $307.95 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluorescent Brightening Agents, Optical Brightening Agents, Synthetic Brighteners, Non-ionic Brighteners End User: Textiles, Paper & Pulp, Coatings, Detergents Application: Textile Industry, Plastic Industry, Wood Industry, Personal Care Form: Powder, Liquid, Concentrate, Granules |
| Companies Covered | BASF, Clariant, Huntsman International LLC, Archroma, Eastman Chemical Company, 3V Sigma S.p.A., Milliken & Company, Teh Fong Min International CO.LTD., Shandong Raytop Chemical Co., Ltd., Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Optical Brighteners Market Trends and Innovations
Formulation chemistry and procurement logistics are undergoing parallel transformation across LAMEA optical brightener supply chains, with regulatory alignment and performance optimization driving concurrent adaptation.
Non-ionic optical brightener formulations are displacing traditional anionic variants in textile processing applications. São Paulo-based paper and pulp processors are adopting these alternatives at accelerated pace to preempt REACH-aligned import barriers. This chemistry transition is displacing established sulfonation-dominant supply relationships and compressing reformulation cycle times for regional distributors.
Morocco's alignment with REACH-derived import protocols is reshaping entry pathways for European-destined textile brightener shipments. Industrial consequence includes mandatory disclosure standards and biodegradability documentation requirements. North African textile export corridors are responding by consolidating supplier relationships with formulators holding pre-validated non-ionic portfolios.
Buyer concentration among specialty detergent formulators is restructuring volume allocation toward direct technical partnership models. Large-scale Brazilian textile operations are bypassing traditional chemical distributors in favor of embedded formulation support agreements. This channel compression is most visible in São Paulo's industrial belt, where procurement teams prioritize dosing precision and reduced handling costs over spot-market flexibility.
LAMEA Optical Brighteners Market Segmentation
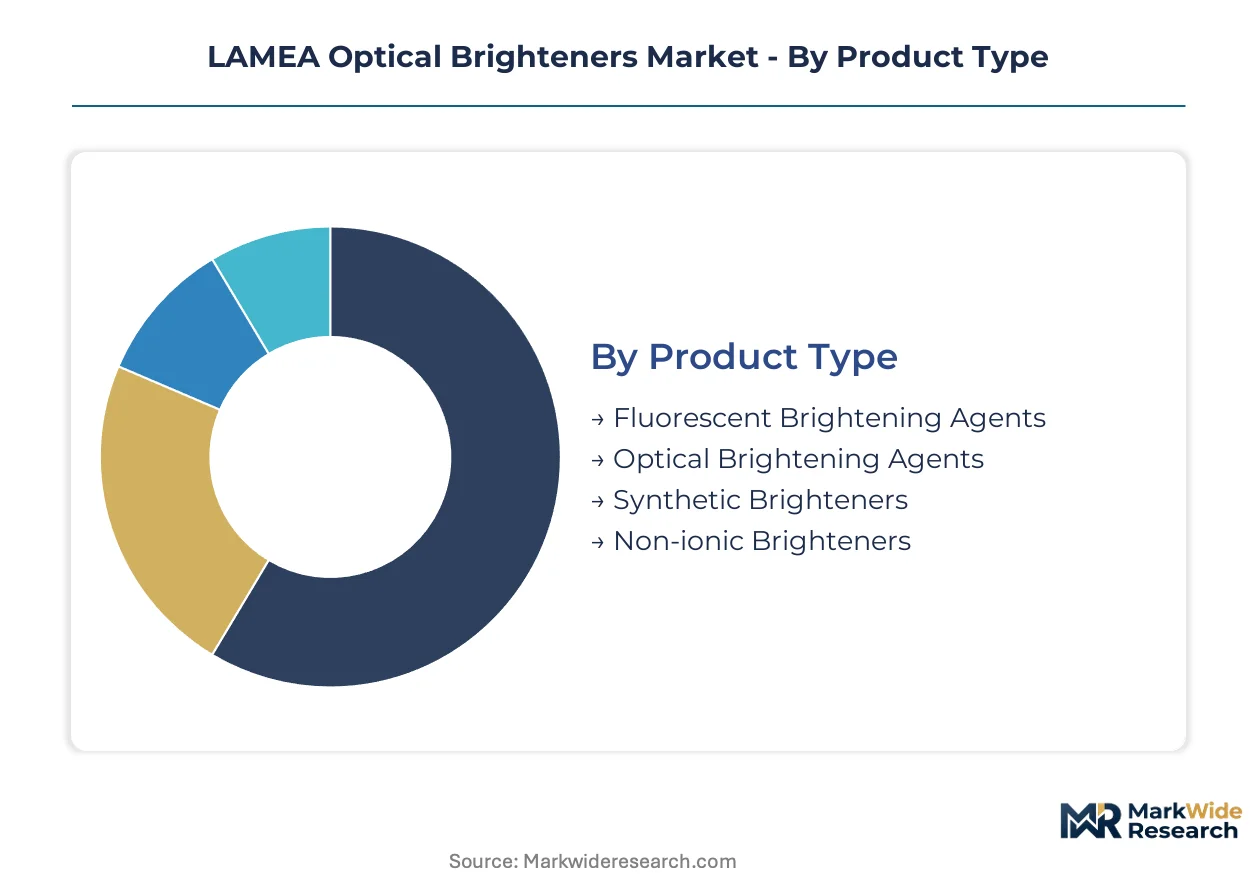
Optical brightener procurement patterns across LAMEA diverge sharply by chemistry type, substrate compatibility, and regulatory exposure. Understanding these splits reveals where formulation investments concentrate and which customer segments command technical service resources.
Product Type:
ANVISA registration timelines in Brazil and REACH-derived protocols in Morocco create divergent compliance burdens across chemistry classes, reshaping supplier portfolios.
- Fluorescent Brightening Agents:Stilbene-derived formulations dominate textile processing applications across São Paulo's industrial belt. Brazilian mills prioritize these agents for export-grade fabric whiteness specifications demanded by European buyers.
- Optical Brightening Agents:Coumarin-based variants serve paper and pulp processors seeking thermal stability in high-speed coating operations. South African manufacturers favor these chemistries for their compatibility with recycled fiber streams.
- Synthetic Brighteners:Engineered benzoxazole derivatives address niche plastics applications in Nigeria's packaging sector.
- Non-ionic Brighteners:Amphoteric formulations bypass sulfonation pathway constraints for coating customers in Kenya's construction materials segment.
Fluorescent brightening agents handle the majority of throughput; non-ionic brighteners are the fastest mover on share.
End User:
Customer concentration patterns in LAMEA reflect the region's industrial structure, with export-oriented sectors driving premium formulation demand.
- Textiles:São Paulo-based mills anchor regional consumption, deploying optical brighteners in cotton and synthetic fiber finishing to meet international buyer whiteness standards. ANVISA disclosure requirements extend procurement cycles for consumer-facing textile applications.
- Paper & Pulp:Brazilian processors in the São Paulo corridor adopt liquid concentrate formats for dosing precision in high-volume coating operations. REACH-aligned export protocols force rapid chemistry transitions for European-destined paper grades.
- Coatings:Industrial paint formulators in Casablanca and Lagos seek backward-integrated suppliers for sulfonation quality control.
- Detergents:Specialty formulators across Morocco and South Africa pull volume toward high-performance liquid concentrates for reduced handling costs.
Textiles commands the largest procurement volumes; detergents posts the steepest expansion trajectory as personal care applications multiply.
Application:
Substrate-specific performance requirements dictate formulation selection, with thermal stability and substrate compatibility determining chemistry matching.
- Textile Industry:High-temperature processing applications in Brazil's export mills demand stilbene derivatives with proven wash-fastness profiles. Non-ionic alternatives gain ground as REACH compliance hardens for European-bound shipments.
- Plastic Industry:Polymer matrix compatibility challenges concentrate demand among Nigerian and Kenyan packaging converters seeking UV-stable brightening solutions.
- Wood Industry:Panel and furniture coating applications in South Africa favor coumarin variants for their lightfastness under UV exposure.
- Personal Care:Moroccan and South African cosmetic manufacturers integrate optical brightening agents into premium skin and hair formulations, creating new volume pools outside traditional industrial channels.
Textile industry absorbs the dominant share of supply; personal care climbs the fastest as cosmetic manufacturers premiumize formulations.
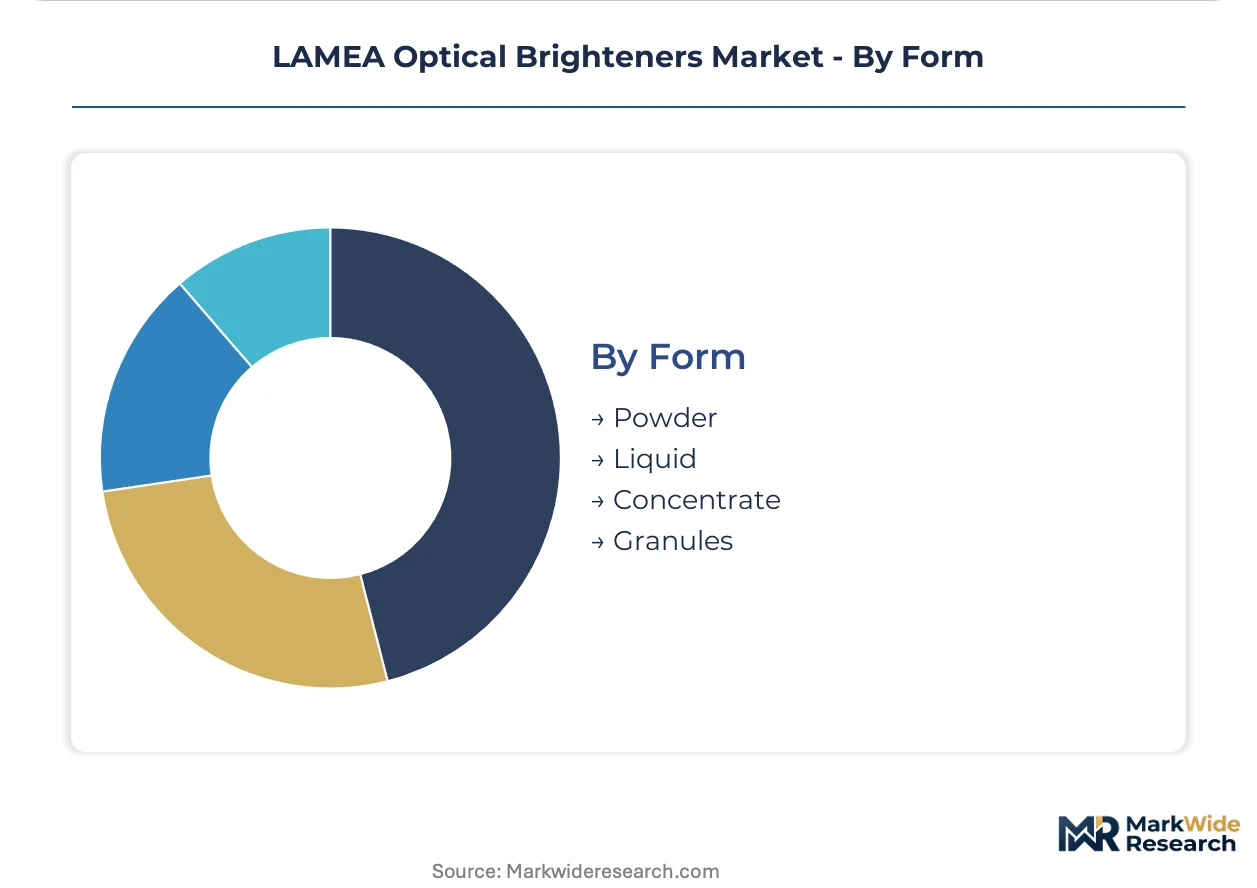
Form:
Manufacturing scale advantages and handling economics create divergent margin structures across physical formats.
- Powder:Retains manufacturing scale advantages for commodity textile applications across Brazil's interior states. Legacy production assets create capital intensity barriers for producers seeking format flexibility.
- Liquid:Concentrates capture margin pools through reduced handling costs and dosing precision in large-scale São Paulo textile and paper operations. Specialty detergent formulators prioritize this format for automated dosing systems.
- Concentrate:High-active formulations serve export-oriented mills seeking transport cost optimization for European-destined shipments.
- Granules:Dust-free handling characteristics appeal to South African coating compounders with stringent workplace exposure protocols.
Powder maintains volume leadership; liquid concentrates expand most quickly as procurement shifts toward embedded technical partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty chemical producers cluster in Brazil's industrial southeast and Morocco's Atlantic export corridor, with procurement networks radiating toward textile and paper processing hubs. São Paulo's manufacturing belt anchors volume consumption, while North African trade gateways face accelerated compliance transitions.
Brazil
São Paulo-based textile mills drive fluorescent brightening agent demand for export-grade fabric finishing. ANVISA enforces extended registration timelines for optical brighteners in consumer-facing applications, compressing product launch windows. The São Paulo industrial belt concentrates paper and pulp processors adopting liquid concentrate formats for high-volume coating operations.
Morocco
Casablanca anchors North African demand for coating-grade optical brighteners serving European export markets. REACH-derived import protocols mandate biodegradability documentation and formulation disclosure standards. Technical service teams cluster in Casablanca to support direct partnership models with textile exporters.
South Africa
Johannesburg and Durban host cosmetic manufacturers integrating optical brightening agents into premium personal care formulations. The country's national chemical regulator shapes product entry pathways through registration requirements. Recycled fiber-compatible coumarin variants dominate paper processing applications in KwaZulu-Natal.
Nigeria
Lagos-based packaging converters generate niche demand for UV-stable brightening solutions in polymer applications. The central bank's foreign exchange policies influence import timing for specialty chemical feedstocks. Industrial paint formulators in Lagos seek sulfonation-quality-controlled supply relationships.
Kenya
Nairobi construction materials processors adopt amphoteric non-ionic brighteners for coating applications. National standards bodies are developing biodegradability thresholds that will determine chemistry market access. Mombasa's port infrastructure supports regional distribution of liquid concentrate formats.
LAMEA Optical Brighteners Market Competitive Landscape
Concentration sits with integrated multinational chemical conglomerates controlling precursor supply chains and regional technical service networks. Three to five European and North American-headquartered suppliers capture the majority of value in premium formulation segments. Two strategic archetypes dominate: backward-integrated sulfonation specialists and application-technical-service-led formulators. Competitive moves center on non-ionic chemistry portfolio transitions and embedded partnership models bypassing traditional distribution.
Among European-based integrated suppliers, BASF and Clariant exemplify the precursor-control archetype through stilbene network leverage and localized technical service deployment. Huntsman International LLC occupies a position representing sulfonation chemistry integration for quality-sensitive coating applications. These three companies anchor the competitive structure through differentiated control points rather than commodity scale.
| Leading Market Players |
|---|
| BASF |
| Clariant |
| Huntsman International LLC |
| Archroma |
| Eastman Chemical Company |
| 3V Sigma S.p.A. |
| Milliken & Company |
| Teh Fong Min International CO.LTD. |
| Shandong Raytop Chemical Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between São Paulo textile mills and European chemical suppliers lock in stilbene precursor access while capping price volatility exposure. These arrangements tie Brazilian export-grade fabric producers to fixed-volume commitments that secure preferential unit economics against spot-market aromatic feedstock swings.
Pricing Analysis
Volume-discount tiering structures separate export-grade textile mills from commodity paper processors and niche coating compounders across the LAMEA market. Premium formulations command price separation through REACH-aligned non-ionic certification and embedded technical service bundling. Cost compression in standard-grade stilbene derivatives is intensifying as petroleum-derived aromatic supply chains transmit volatility downstream. Brazilian paper and pulp processors demonstrate highest price sensitivity due to thin coating-margin economics, while Moroccan personal care manufacturers show lowest sensitivity given premiumization-driven formulation budgets.
Supply Chain Analysis
Germany and China anchor global stilbene precursor production, with sulfonation pathway intermediates feeding Brazilian textile corridors and North African coating hubs. LAMEA downstream formulation draws from imported coumarin derivatives, benzoxazole building blocks, and amphoteric surfactant feedstocks. Single-source vulnerability concentrates in European-linked sulfonation chemistry for REACH-compliant non-ionic variants. Distribution runs through technical service-led direct partnerships in São Paulo and Casablanca, bypassing traditional chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-ionic formulation chemistry and localized technical service deployment represent scarce capabilities that separate premium suppliers from commodity competitors in this market. Mastery of REACH-aligned biodegradability documentation and embedded mill partnerships constitutes the critical asset gap.
For Market Incumbents: Fortify backward integration into sulfonation chemistry to control raw material quality for African coating customers facing specification tightening. Expand technical service teams in Casablanca and São Paulo to capture margin pools through formulation partnership models that bypass distributor intermediation. Defensive priority centers on preemptive non-ionic portfolio transitions before Latin American biodegradability thresholds harden. For New Entrants and Emerging Players: ANVISA fast-track certification pathways for optical brighteners in Brazilian consumer-facing applications offer entry acceleration versus extended legacy registration timelines. Target Kenya's construction materials segment with amphoteric non-ionic brighteners where national standards body thresholds remain under development. Go-to-market angle emphasizes dust-free granule formats for South African coating compounders with stringent workplace exposure protocols. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors formulators with pre-validated non-ionic portfolios and embedded textile mill relationships. Long-term viability over the next decade hinges on chemistry transition completion and technical service localization density. Acquisition target archetype: regional distributors with ANVISA registration assets and existing São Paulo mill relationships. Signal to watch: consolidation of North African textile export corridors around single-source technical partnership models.| Strategic Initiative | Industry Significance |
|---|---|
| Non-ionic Formulation Transition | REACH-aligned chemistry shifts unlock European-destined textile shipment access from Moroccan export hubs. |
| Technical Service Localization | Casablanca and São Paulo deployment captures margin pools through direct mill partnership structures. |
| Backward Integration into Sulfonation | Quality control over sulfonation chemistry secures African coating customer specifications. |
| Liquid Concentrate Capacity Addition | Automated dosing compatibility addresses specialty detergent formulator procurement priorities. |
| ANVISA Registration Asset Acquisition | Pre-cleared optical brightener portfolios compress product launch windows in Brazilian consumer applications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the LAMEA optical brighteners value chain, including textile mill procurement directors, specialty detergent formulators, paper and pulp coating engineers, and cosmetic manufacturing R&D leads. Secondary validation drew from customs and trade data, ANVISA registration filings, REACH-derived protocol documentation, and chemical industry association reports. Bottom-up volume estimates triangulated against top-down market sizing across chemistry type, substrate application, and regional production hub dimensions.
The projection horizon spans the full analysis window with segmentation modeling across fluorescent brightening agents, coumarin variants, and non-ionic formulations by textile, paper, detergent, and personal care end-uses. CAGRs were derived through regression analysis of historical precursor cost trajectories, regulatory compliance investment cycles, and export-grade whiteness specification adoption curves. Industry-specific forecast inputs incorporated ANVISA registration timeline distributions and REACH-aligned import protocol phase-in schedules.
Decision-makers should treat outputs as directional under assumptions of stable petroleum-derived aromatic feedstock availability and progressive Latin American biodegradability threshold adoption; material deviation would warrant model refresh. Specific risk factors include sudden ANVISA regulatory acceleration, REACH protocol scope expansion, or stilbene precursor supply disruption from European manufacturing hubs. Recalibration cycles align with material shifts in regional chemical inventory frameworks and textile export corridor compliance requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
High Performance Organic Pigments Market
Dyes and Pigments
Riboflavin Pigment Market
Dyes and Pigments
Water-Based Pigments Market
Dyes and Pigments
Iron Oxide Pigments Market
Dyes and Pigments
Erythrosine Market
Dyes and Pigments
Plastic Color Concentrates Market
Dyes and Pigments
Phosphorescent Pigments Market
Dyes and Pigments
North America Hair Colorants Market
Dyes and Pigments
Micronized Color Powder Market
Dyes and Pigments
Europe Hair Colorants Market
Dyes and Pigments
Photochromic Pigments Market
Dyes and Pigments
Acid Orange Market
Dyes and Pigments
Brilliant Blue FCF Colors Market
Dyes and Pigments
Fluorescent Pigments Market
Dyes and Pigments
Mulch Colorants Market
Dyes and Pigments
Photoluminescent Paints Market