
 Middle-East and Africa Paper and Paperboard Market | 2026-2036
Middle-East and Africa Paper and Paperboard Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Paper and Paperboard Market Foresight
Market Context
Saudi Arabia's industrial city expansions at Jubail and Yanbu is reconfiguring containerboard supply geography across the Red Sea basin. Arabian Packaging Co. LLC leverages integrated pulp-to-box operations in Jeddah to serve FMCG clients. International Packaging Company LLC anchors its Gulf position through specialty coating lines for pharmaceutical blister packs. Hotpack Packaging Industries LLC dominates the UAE's foodservice disposables segment with thermoformed paper-laminate hybrid production.
Technical Definition and Segment Structure
Paper and paperboard encompasses cellulose-based sheet materials exceeding 150 grams per square meter, manufactured through multi-layer Fourdrinier or cylinder mold processes for structural rigidity and printability. Corrugated board leads volume across the Middle-East and Africa, driven by agricultural export packaging from Kenya and Ethiopia and retail-ready display demand in South African supermarkets. Carton board captures premium margin pools in pharmaceutical and cosmetics applications, particularly where UAE free zone manufacturers require EU MDR-aligned serialization-ready substrates. Uncoated paper sustains publishing activity in Egypt and Nigeria, though digital substitution compresses secular growth trajectories.
Regulatory Framework and Outlook
Saudi Standards, Metrology and Quality Organization (SASO) mandates govern food-contact paperboard migration limits across Gulf Cooperation Council markets, while South Africa's Department of Forestry, Fisheries and the Environment enforces extended producer responsibility regulations for packaging waste. Egypt's General Organization for Export and Import Control applies phytosanitary certification requirements to wood-derived packaging materials entering European trade channels. Stakeholders must monitor how Kenya's National Environment Management Authority implements single-use plastic bans, as paperboard alternatives face fiber sourcing adequacy tests against domestic bagasse and imported pulp dependencies.
Market Dynamics
E-commerce fulfillment infrastructure across Saudi Arabia and the UAE is collapsing traditional corrugated supply chains into integrated pulp-to-box operations, forcing regional converters to consolidate or specialize.
Growth Catalysts
- SASO food-contact migration mandates:Gulf Cooperation Council packaging specifications are tightening substrate purity requirements, pulling premium coated board demand into Jeddah and Dubai free zones.
- Ethiopian agricultural export corridors:Flower and fresh produce cold-chain expansion is accelerating demand for moisture-resistant corrugated formats with ventilated flute structures.
- Bagasse fiber substitution:Egyptian sugar mill byproduct pulping is displacing imported kraft in Nile Delta containerboard furnishes, cutting raw material cost volatility for domestic converters.
Market Restraints
- Imported hardwood pulp dependency:Regional mills rely on Brazilian and Indonesian long-fiber supply, exposing margin structures to Baltic Dry Index freight swings and currency mismatches.
- Kenyan bagasse adequacy ceilings:Domestic fiber harvests cannot scale beyond 340,000 annual tonnes without irrigated plantation expansion, capping local containerboard output.
- EU phytosanitary certification friction:Egypt's General Organization for Export and Import Control requires heat-treatment documentation for wood-derived packaging entering European channels, adding 10-14 day clearance delays.
Strategic Opportunities
- Morocco's Atlantic port industrialization:Tangier Med zone expansion offers tariff-advantaged board conversion for European automotive component re-export packaging.
- Pharmaceutical serialization-ready substrates:UAE free zone manufacturers require EU MDR-aligned carton board with embedded security fibers and track-trace coating compatibility.
- South African extended producer responsibility credits:Department of Forestry, Fisheries and the Environment regulations create tradable waste-offset markets for integrated recyclers with post-consumer collection networks.
Industry Challenges
- Fourdrinier speed upgrade capital intensity:Aging Saudi and Egyptian cylinder mold machines require 40-60 million dollar rebuilds to match Gulf competitor throughput and grammage consistency.
- FSSC 22000 certification timelines:Food-grade board qualification for multinational FMCG accounts demands 18-24 month audit cycles that strain working capital for mid-cap converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Paper and Paperboard Market |
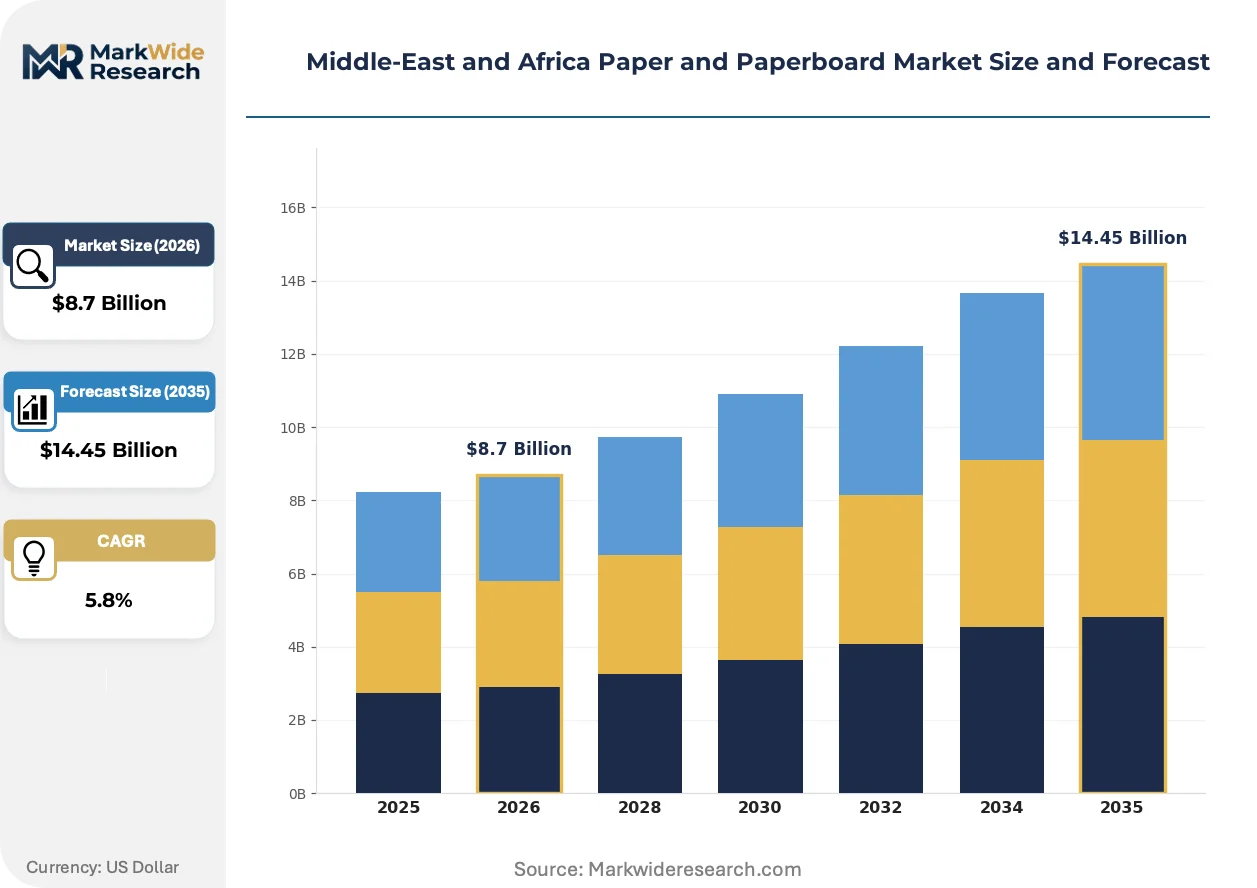
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Paper, Uncoated Paper, Carton Board, Corrugated Board End Use Industry: Packaging, Publishing, Printing, Stationery Thickness: Lightweight, Medium, Heavyweight, Ultra Heavyweight Form: Rolls, Sheets, Custom Sizes, Specialty Forms |
| Companies Covered | United Carton Industries Company (UCIC), Arabian Packaging Co. LLC, International Packaging Company LLC, Hotpack Packaging Industries LLC, Tarboosh Packaging Co. LLC, Gulf Carton Factory Company, Eastern Pak Limited, Queenex Corrugated Carton Factory, Falcon Pack, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Paper and Paperboard Market Shifts & Advancements
Digital print integration and circular economy mandates are compressing run-length economics and reshaping substrate specifications across Middle-East and Africa packaging value chains.
Water-based barrier coatings are collapsing the cost premium between polyethylene-laminated and recyclable corrugated formats. Saudi dairy and protein exporters are adopting these substrates at 15,000-tonne annual trial volumes. The shift is collapsing virgin plastic linerboard demand in Jeddah's cold-chain corridor while forcing coating chemical suppliers to localize technical service teams.
South Africa's extended producer responsibility regulations are mandating minimum recycled content thresholds in corrugated containers. The Department of Forestry, Fisheries and the Environment enforcement is diverting post-consumer fiber streams from informal collection into mill-integrated sorting facilities. Food-grade applications remain exempt, preserving virgin kraft demand in Cape Town's citrus export packaging cluster.
Consolidated buying by pan-African FMCG distributors is compressing supplier negotiation cycles from annual to quarterly frameworks. East African supermarket chains are unbundling corrugated procurement from legacy integrated converters, awarding spot contracts to Egyptian and Turkish board traders with bonded warehouse presence in Mombasa. Kenyan floriculture exporters are the most aggressive adopters, leveraging containerboard price transparency from Baltic exchange indices to arbitrage regional supply imbalances.
Middle-East and Africa Paper and Paperboard Market Segmentation
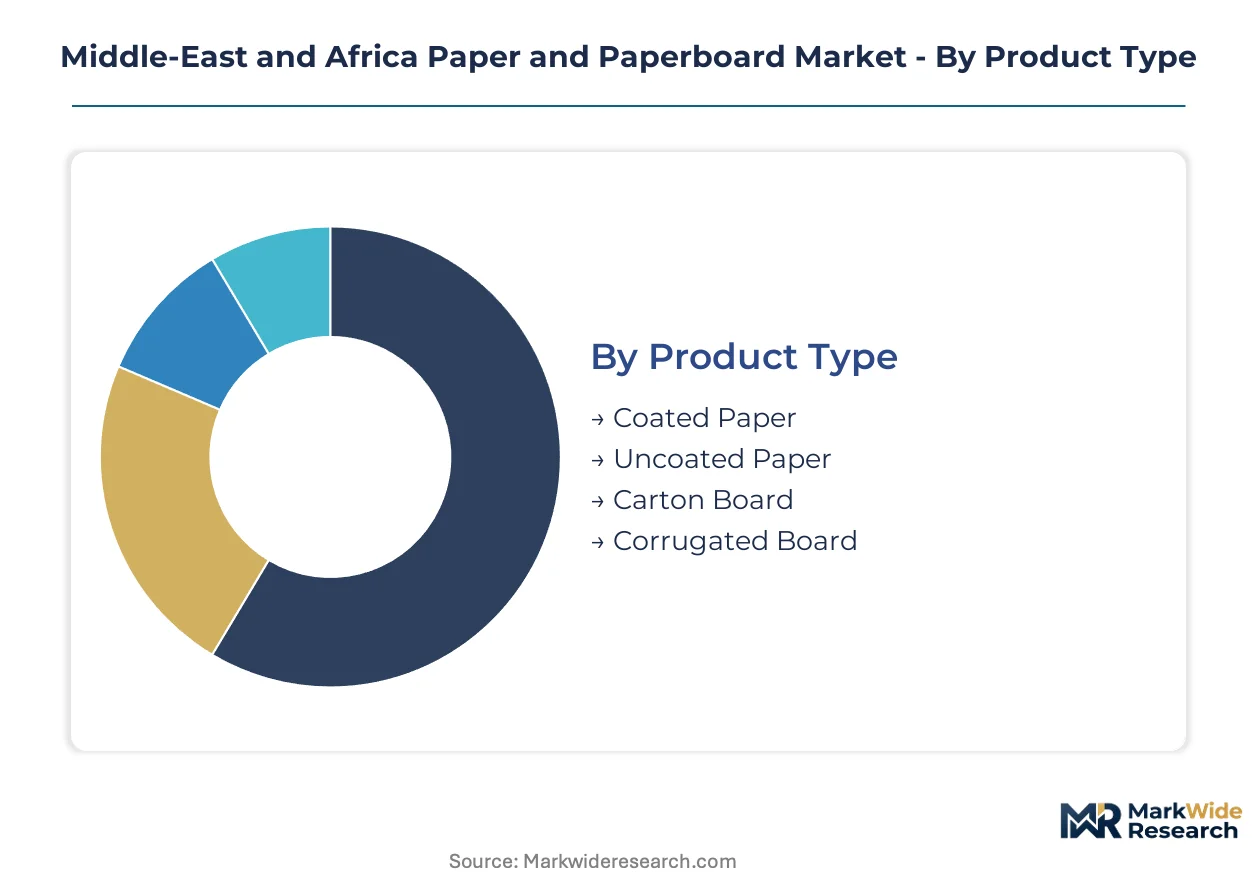
Segmentation in the Middle-East and Africa paper and paperboard market reveals how substrate specifications diverge across regulatory environments and end-use requirements. Each dimension carries distinct procurement patterns, certification burdens, and supply chain configurations that shape competitive positioning.
Product Type:
After-sales service intensity varies sharply across product categories, with food-grade and pharmaceutical substrates demanding technical support for compliance documentation and coating compatibility testing.
- Corrugated Board:Multi-flute cellulose structures engineered for stacking strength and moisture resistance in agricultural cold chains. Egyptian Nile Delta converters and Kenyan floriculture exporters drive specification intensity around ventilated flute designs and water-based barrier coatings.
- Carton Board:Premium-grade solid bleached or unbleached substrates with calibrated stiffness and printability for pharmaceutical blister packs and cosmetics packaging. UAE free zone manufacturers require EU MDR-aligned serialization-ready grades with embedded security fibers, pulling coated SBS demand into Jeddah and Dubai.
- Coated Paper:Clay or calcium carbonate surface treatments for high-resolution commercial printing, concentrated in South African retail catalog and magazine production.
- Uncoated Paper:Virgin or recycled furnish for general publishing and office applications, facing secular compression from digital substitution across Egyptian and Nigerian educational markets.
Corrugated board holds the largest share; momentum sits with carton board.
End Use Industry:
Application-driven cost tiers separate commodity packaging from regulated food-contact and pharmaceutical segments with divergent certification timelines.
- Packaging:Structural substrates for FMCG, industrial, and export cargo applications spanning corrugated containers, folding cartons, and protective wraps. Saudi dairy and protein cold-chain exporters are accelerating water-based barrier coating adoption at trial volumes exceeding 10,000 annual tonnes, collapsing virgin plastic linerboard demand in Jeddah.
- Publishing:Uncoated and lightweight coated papers for books, newspapers, and periodicals. Egyptian educational publishers and Nigerian print media sustain residual demand despite smartphone penetration compressing run lengths.
- Printing:Commercial sheet and web offset stocks for marketing collateral and direct mail. South African retail chains dominate specification setting for catalog grades.
- Stationery:Cut-size writing and copier papers for corporate and educational procurement. Bulk tenders from UAE government entities and Saudi school systems concentrate volume.
Packaging dominates absolute volume; printing faces the steepest trajectory decline.
Thickness:
Grammage specifications align with handling automation and palletization requirements across manual and mechanized fulfillment environments.
- Lightweight:Sub-200 gsm stocks for envelope windows, flexible packaging inserts, and publication interiors. Ethiopian flower export packaging favors lightweight corrugated for air freight weight optimization.
- Medium:200-400 gsm range covering standard folding cartons and single-wall corrugated. Dubai e-commerce fulfillment centers specify medium-weight board for automated case erection lines.
- Heavyweight:400-600 gsm applications in industrial drums, protective partitions, and triple-wall export containers. Cape Town citrus exporters require heavyweight kraft linerboard for ocean container stacking.
- Ultra Heavyweight:Exceeding 600 gsm for specialty applications including rigid set-up boxes and heavy-duty industrial packaging. Limited regional production capacity concentrates supply in Turkish and European imports.
Medium thickness commands the largest share; ultra heavyweight offers the steepest margin expansion.
Form:
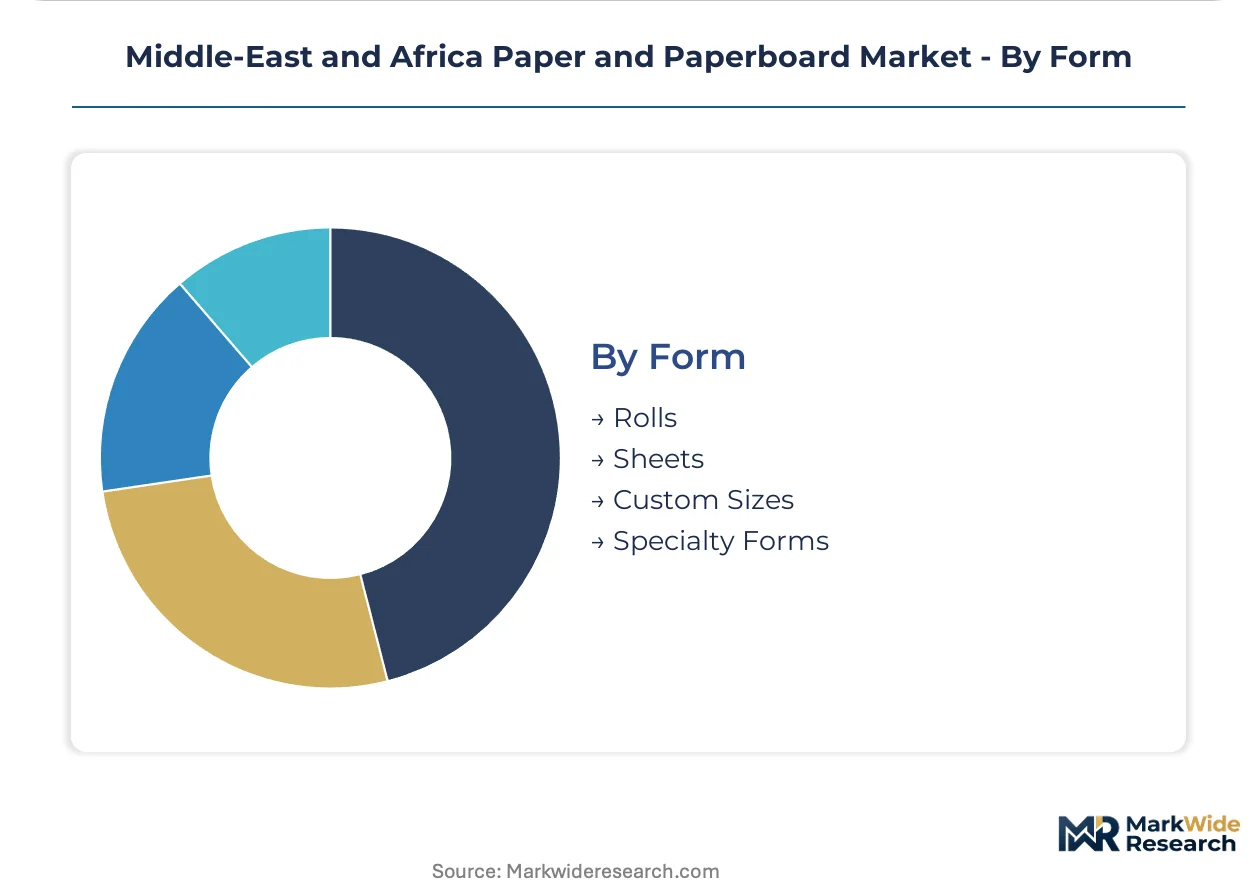
Customer type and order scale determine form factor preferences, with large converters favoring roll-fed efficiency and specialty manufacturers requiring sheeted precision.
- Rolls:Continuous web supply for high-speed corrugators, paper bag machines, and web offset presses. Integrated Saudi mills at Jubail and Yanbu ship rolls to Jeddah converters for FMCG account fulfillment.
- Sheets:Precut dimensions for sheet-fed offset, die-cutting, and manual assembly operations. Egyptian carton converters serving pharmaceutical clients specify sheeted SBS for serialization-ready blister pack cards.
- Custom Sizes:Non-standard dimensions for specialty machinery or unique packaging geometries. Moroccan automotive component suppliers in Tangier Med zone require custom-width rolls for just-in-time sequencing.
- Specialty Forms:Pre-converted items including die-cuts, windowed cartons, and adhesive-applied structures. Hotpack Packaging Industries LLC in the UAE dominates thermoformed paper-laminate hybrid production for foodservice disposables.
Rolls hold the largest share; specialty forms are climbing fastest on customization premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mills at Jubail and Yanbu anchor containerboard supply across the Red Sea basin, while Egyptian Nile Delta converters and UAE free zone manufacturers pull divergent substrate specifications. Regional procurement splits between integrated pulp-to-box operations and import-dependent sheet-fed specialists.
Saudi Arabia
SASO food-contact migration mandates tighten substrate purity requirements for dairy and protein exporters. Jubail industrial city expansions reconfigure supply geography, with integrated mills shipping rolls to Jeddah converters serving multinational FMCG accounts. Yanbu petrochemical corridor feeds captive energy costs for kraft linerboard furnishes.
United Arab Emirates
MOHAP pharmaceutical serialization standards and Dubai's circular economy mandates reshape carton board procurement. Jebel Ali and Dubai South free zones concentrate EU MDR-aligned substrate demand for blister pack and cosmetics applications. Hotpack Packaging Industries LLC exemplifies thermoformed paper-laminate hybrid production for foodservice disposables.
Egypt
Bagasse fiber substitution from Nile Delta sugar mills displaces imported kraft in containerboard furnishes. The General Organization for Export and Import Control applies phytosanitary certification to wood-derived packaging entering European trade channels. 10th of Ramadan City packaging cluster serves North African export corridors with food-grade corrugated capacity.
South Africa
The Department of Forestry, Fisheries and the Environment enforces extended producer responsibility regulations, creating tradable waste-offset markets. Cape Town citrus exporters require heavyweight kraft linerboard for ocean container stacking. Durban-Gauteng corridor concentrates post-consumer fiber collection into mill-integrated sorting facilities.
Kenya
Nairobi floriculture exporters leverage containerboard price transparency from Baltic exchange indices to arbitrage regional supply imbalances. The National Environment Management Authority implements single-use plastic bans, testing paperboard alternatives against domestic bagasse adequacy ceilings. Mombasa bonded warehouses host Egyptian and Turkish board traders awarding spot contracts to East African supermarket chains.
Middle-East and Africa Paper and Paperboard Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in substrate and coating supply. The vendor base splits between Gulf-based integrated pulp-to-box operators and Nile Delta import-dependent converters. Three archetypes dominate: captive energy-integrated mills, free zone pharmaceutical-grade specialists, and regional trading houses with bonded warehouse networks. Consolidation pressures force cylinder mold rebuilds or specialty coating line investments.
Among UAE-based packaging groups, International Packaging Company LLC and Hotpack Packaging Industries LLC occupy positions on the specialty substrate vector, while Arabian Packaging Co. LLC exemplifies integrated operations architecture. United Carton Industries Company anchors the Saudi integrated tier. These entities represent divergent strategic responses to SASO compliance burdens and circular economy procurement shifts.
| Leading Market Players |
|---|
| United Carton Industries Company (UCIC) |
| Arabian Packaging Co. LLC |
| International Packaging Company LLC |
| Hotpack Packaging Industries LLC |
| Tarboosh Packaging Co. LLC |
| Gulf Carton Factory Company |
| Eastern Pak Limited |
| Queenex Corrugated Carton Factory |
| Falcon Pack |
| Others |
Supply & Pricing Matrix
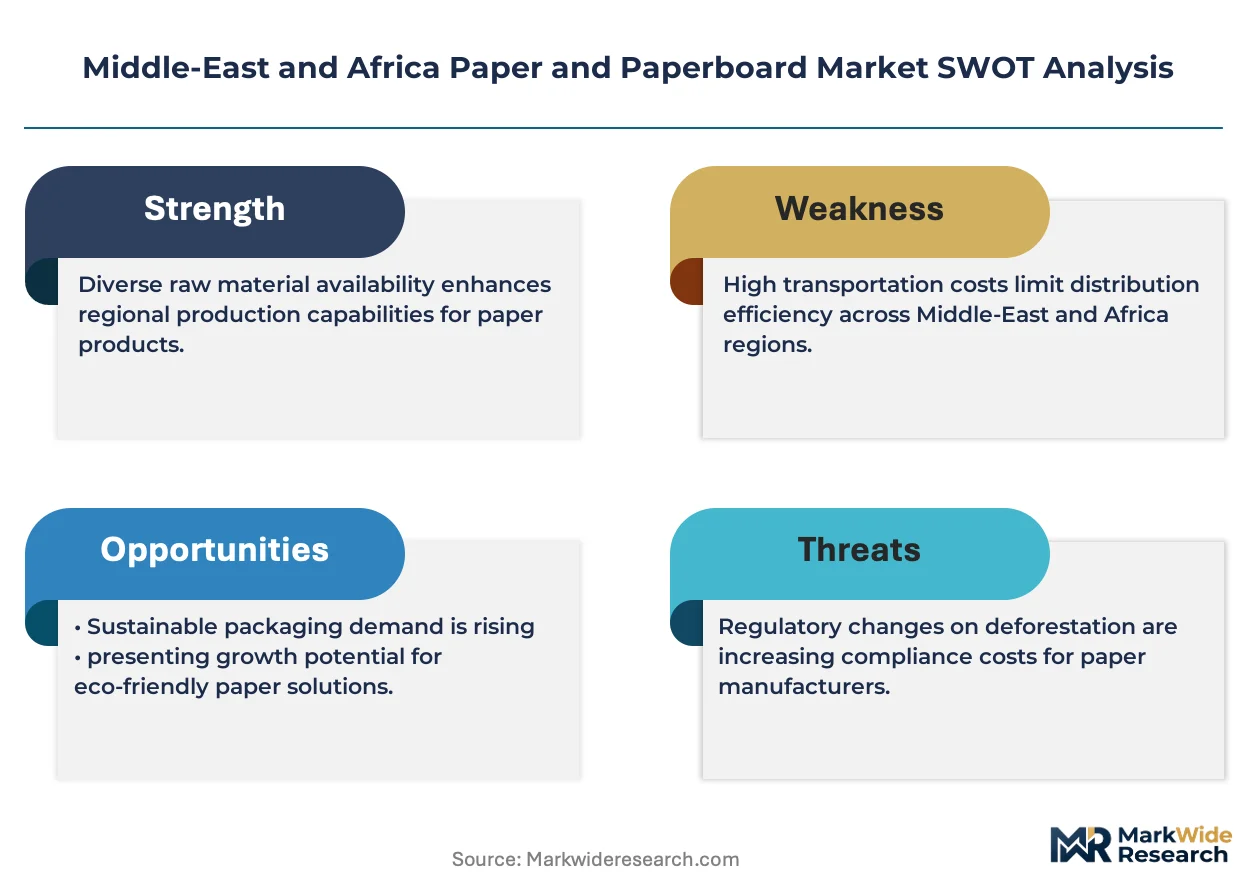
Jubail industrial city expansions concentrate kraft linerboard capacity within Saudi Arabia's Yanbu petrochemical corridor, feeding captive energy costs into regional pricing power that Egyptian and Kenyan converters cannot replicate without cylinder mold rebuilds or imported roll dependencies.
Pricing Analysis
SASO food-contact migration mandates dictate the pricing tier structure across Gulf Cooperation Council markets, separating FSSC 22000-certified board from commodity grades. Price differentiation hinges on certification level and after-sales technical support intensity, with multinational FMCG accounts paying premiums for compliance documentation. Cost compression in standard-grade corrugated is intensifying as Egyptian bagasse substitution and Turkish spot traders arbitrage regional imbalances. East African supermarket chains exhibit the highest price sensitivity, while UAE pharmaceutical free zone manufacturers prioritize serialization-ready substrate performance over unit cost.
Supply Chain Analysis
Extended payment terms from Saudi integrated mills are squeezing working capital for Nile Delta and Mombasa converters dependent on imported furnish. Supply concentrates in Saudi Arabia, Egypt, and the UAE, with raw material dependencies on Brazilian and Indonesian long-fiber pulp alongside domestic bagasse harvests. Single-source vulnerability runs through Baltic Dry Index freight exposure for hardwood pulp shipments. Distribution runs through Jeddah and Dubai free zone hubs for roll-fed corrugators, with bonded warehouses in Mombasa serving spot-contract East African demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food-grade board qualification services and coating compatibility testing represent the fastest-expanding recurring-revenue layer, outpacing substrate hardware margins as SASO compliance timelines extend customer retention cycles.
For Market Incumbents: Insulate integrated pulp-to-box positions by accelerating Fourdrinier speed upgrades at Jubail and Yanbu facilities before Egyptian converters complete cylinder mold rebuilds. Lock in FSSC 22000 certification pipelines with multinational FMCG accounts to raise switching costs against Turkish spot traders penetrating Mombasa bonded warehouses.
For New Entrants and Emerging Players: Build out water-based barrier coating technical service capabilities to capture Saudi dairy and protein exporter trials displacing polyethylene-laminated formats. Target Moroccan Tangier Med zone automotive component packaging with custom-width roll supply for just-in-time sequencing, leveraging tariff advantages against European board imports.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated recyclers with post-consumer collection networks qualifying for South African extended producer responsibility credits. Five-to-ten-year viability favors mill-integrated operators with captive energy and fiber sourcing over import-dependent sheet-fed specialists. Monitor Kenya's National Environment Management Authority single-use plastic ban enforcement velocity as inflection signal for paperboard substitution demand adequacy against bagasse supply ceilings.
| Strategic Initiative | Industry Significance |
|---|---|
| Fourdrinier Speed Upgrade Investment | Reconfigures Jubail and Yanbu throughput parity with Gulf competitor grammage consistency. |
| Water-Based Barrier Coating Localization | Captures Saudi dairy exporter trials collapsing virgin plastic linerboard demand in Jeddah. |
| FSSC 22000 Certification Pipeline Buildout | Extends customer retention cycles through 18-24 month multinational FMCG audit timelines. |
| Bagasse Fiber Integration Expansion | Displaces imported kraft volatility for Nile Delta converters serving North African export corridors. |
| Post-Consumer Collection Network Acquisition | Qualifies South African integrated recyclers for tradable waste-offset credit markets. |
Research Methodology
A standing panel of mill operations directors, corrugated converter procurement leads, FMCG packaging specification managers, and free zone pharmaceutical manufacturers provided ongoing calibration across primary interview cycles. Secondary validation drew from SASO technical regulation filings, Egyptian General Organization for Export and Import Control phytosanitary documentation, South African Department of Forestry extended producer responsibility enforcement records, and Baltic Dry Index freight data. Bottom-up volume triangulation against top-down macroeconomic drivers anchored segmentation outputs.
Scenario-bracketing across regulatory enforcement intensity, pulp freight volatility, and circular economy mandate adoption shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, end-use industry, thickness specification, and form factor, with regional regulatory cluster and certification tier as cross-cutting variables. CAGRs were derived from installed capacity trajectories, demand elasticity estimates, and substitution rate assumptions for water-based barrier coatings displacing polyethylene laminates.
Stress conditions across Brazilian and Indonesian pulp supply disruptions, Baltic Dry Index spike magnitude, and Kenyan bagasse harvest adequacy were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding SASO enforcement timelines and South African extended producer responsibility credit market liquidity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Paper Coating Materials Market
Paper Products
Europe Thermal Paper Market
Paper Products
Paper Doilies Market
Paper Products
Drum Pulper Market
Paper Products
Paper Pigment Market
Paper Products
Europe Tissue and Hygiene Paper Market
Paper Products
Inlay Paper Market
Paper Products
GCC Stone Paper Market
Paper Products
Chemical Cellulose Market
Paper Products
Liquid Paperboard Market
Paper Products
North America Medium-Density Fiberboard Market
Paper Products
Global Paper Chemical Market
Paper Products
Global Molded Pulp Products Market
Paper Products
Europe Medium-Density Fiberboard Market
Paper Products
Europe and MENA Pulp Market
Paper Products
Overlay Paper Market