
 North America Specialty Paper Market | 2026-2036
North America Specialty Paper Market Size, Share, and Industry Trends Forecast 2026-2036
North America Specialty Paper Market Intelligence
Asset-light leasing arrangements for pulp refining and coating equipment are reshaping competitive entry in specialty paper, allowing mid-scale converters to access premium-grade capacity without full capital ownership. International Paper leverages its integrated Southern US pulp network to sustain coated paper supply chains for food contact applications. Domtar Corporation anchors uncoated specialty production through Quebec and Ontario mill assets with FSC-certified fiber sourcing. Glatfelter competes in filtration and battery separator substrates where technical specifications command premium positioning.
Specialty paper denotes engineered sheet products manufactured with refined pulp blends, synthetic fibers, or functional coatings to achieve controlled porosity, moisture barrier, or print receptivity beyond commodity grades, typically ranging from 30 to 400 grams per square meter basis weight depending on end-use performance requirements. Coated paper occupies the largest value pool in North America due to its dominance in premium label and publication applications requiring uniform ink holdout. Digital paper represents the fastest-expanding category as inkjet and toner-based production printing displaces offset in short-run commercial work. Specialty board maintains mature demand in rigid packaging and display applications where caliper and stiffness specifications limit substitution risk.
US EPA recycled fiber content guidelines under the Comprehensive Procurement Preference program shape federal purchasing specifications, while FDA food contact notification requirements govern barrier coatings in direct food packaging applications. State-level extended producer responsibility frameworks in California and Maine are forcing substrate redesign for recyclability compatibility with existing municipal sorting infrastructure. Stakeholders must monitor how forthcoming FDA guidance on per- and polyfluoroalkyl substance restrictions in food packaging redirects fluorochemical-based grease barrier development toward mineral oil and bio-based alternatives.
Market Dynamics
State-level extended producer responsibility mandates are forcing substrate redesign across North American packaging supply chains, compelling mills to engineer for municipal sorting compatibility rather than performance alone.
Growth Catalysts
- EPA Recycled Content Procurement Guidelines:Federal purchasing specifications under the Comprehensive Procurement Preference program mandate minimum recycled fiber thresholds, creating guaranteed offtake for compliant specialty paper producers serving government contracts.
- Food Packaging Barrier Migration:Brands are converting from plastic to fiber-based substrates with mineral oil and bio-based grease barriers as FDA food contact notification pathways mature for direct food applications.
- Great Lakes Manufacturing Cluster:Integrated pulp-to-paper operations concentrated near freshwater resources and Midwestern consumer markets enable just-in-time delivery with reduced logistics exposure.
Market Restraints
- Pulp Input Cost Volatility:Northern bleached softwood kraft pulp pricing swings directly compress converter margins, with specialty grades unable to pass through commodity pulp movements to contract-bound customers.
- Fluorochemical Barrier Phaseout:Anticipated FDA restrictions on per- and polyfluoroalkyl substances in food contact applications strand existing grease-resistant coating investments before mineral oil alternatives achieve equivalent performance.
- Digital Substitution in Publication:Inkjet and toner-based production printing is rendering obsolete coated paper demand for short-run commercial work, compressing volume in historically dominant label and publication segments.
Strategic Opportunities
- Battery Separator Substrates:Technical specifications for filtration and energy storage applications command premium positioning, with controlled porosity engineering creating defensible specialization beyond commodity converters.
- California and Maine EPR Frameworks:First-mover substrate redesign for recyclability compatibility with existing municipal sorting infrastructure creates reference architecture for pending legislation across additional states.
- Asset-Light Equipment Leasing:Pulp refining and coating equipment leasing arrangements allow mid-scale converters to access premium-grade capacity without full capital ownership, lowering competitive entry thresholds.
Industry Challenges
- Coating Chemistry Transition Timeline:Reformulating barrier properties away from fluorochemical bases while maintaining FDA food contact compliance requires extended validation cycles that delay commercialization.
- Specialized Technical Talent Scarcity:Papermaking engineers with expertise in synthetic fiber blending and functional coating deposition command premium compensation, constraining expansion at non-integrated facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Specialty Paper Market |
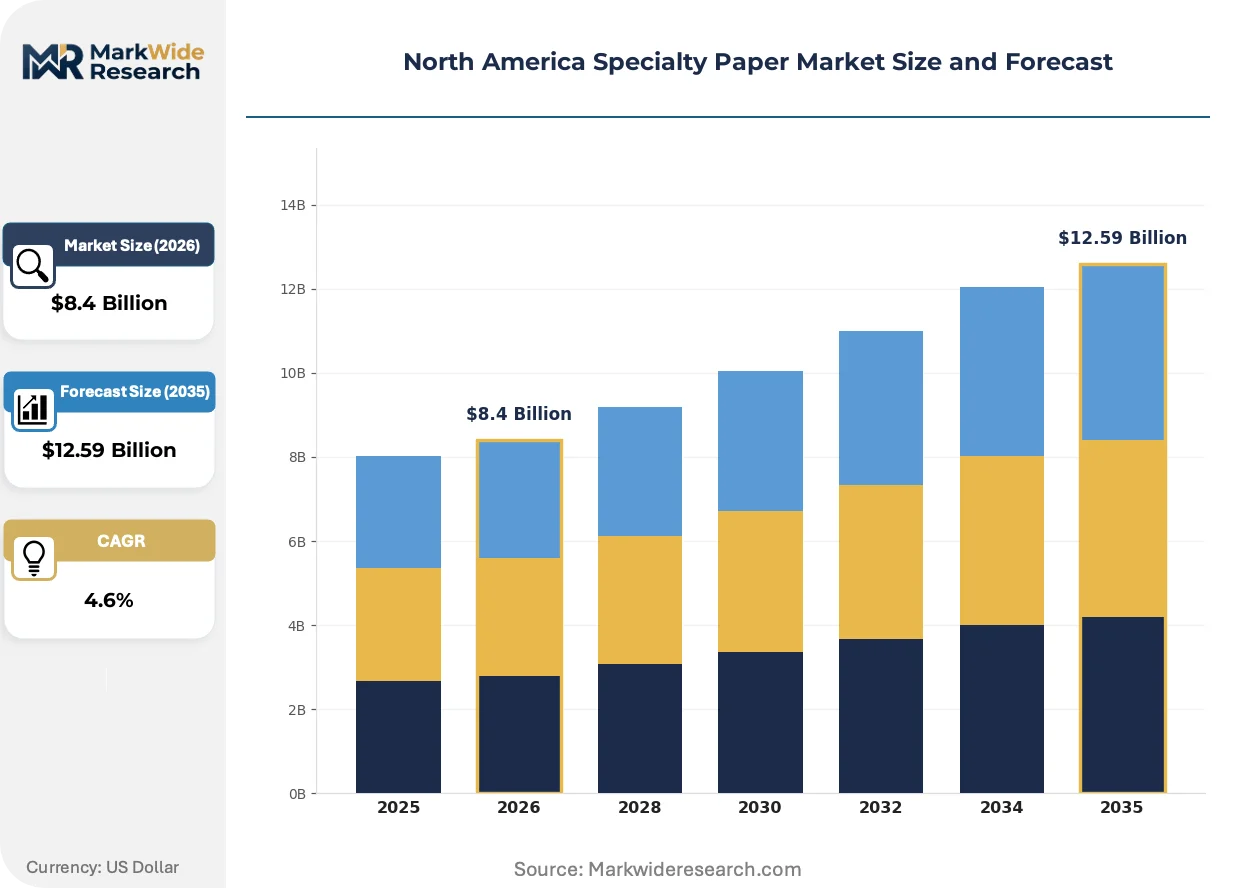
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.59 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Paper, Uncoated Paper, Specialty Board, Digital Paper End User: Packaging, Printing, Labels, Stationery Application: Graphic Arts, Food Packaging, Hygiene Products, Industrial Use Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | International Paper, Domtar Corporation, Sappi Limited, Stora Enso, WestRock Company, UPM-Kymmene Corporation, Glatfelter, Nippon Paper Industries, Georgia-Pacific, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Specialty Paper Market Strategic Shifts & Innovations
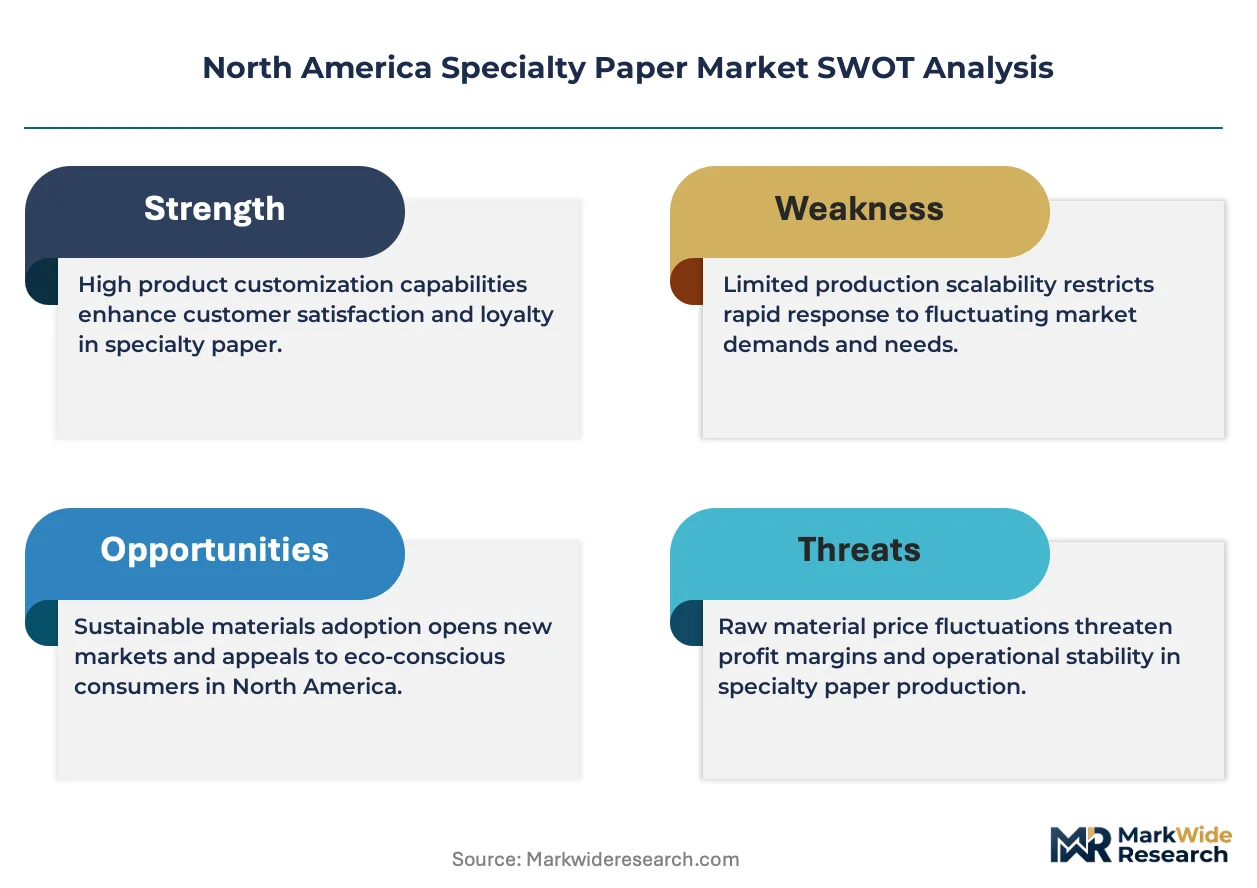
Digital production technologies and regulatory chemistry restrictions are simultaneously compressing legacy demand pools and opening engineered substrate applications in energy storage and advanced filtration.
Water-based barrier coatings with mineral oil and plant-derived alternatives are rendering obsolete fluorochemical-based grease resistance in food packaging applications. Quick-service restaurant chains and frozen food brands are accelerating qualification timelines for compliant substrates. This transition is compressing incumbent coating asset values while rewarding early movers with approved FDA food contact notifications.
US EPA recycled fiber content guidelines under the Comprehensive Procurement Preference program are reshaping federal purchasing specifications for office paper and packaging substrates. Mills serving government contracts must now certify minimum post-consumer content thresholds through third-party chain-of-custody documentation. Coated paper grades for federal publication applications face the most stringent compliance verification requirements.
Brand procurement departments are consolidating supplier relationships around vertically integrated mills with captive pulp supply and in-house coating capabilities. This concentration is displacing merchant converter relationships that lack backward integration into fiber sourcing. The shift is most visible in premium label applications where supply security and specification consistency outweigh pure price competition.
North America Specialty Paper Market Segmentation
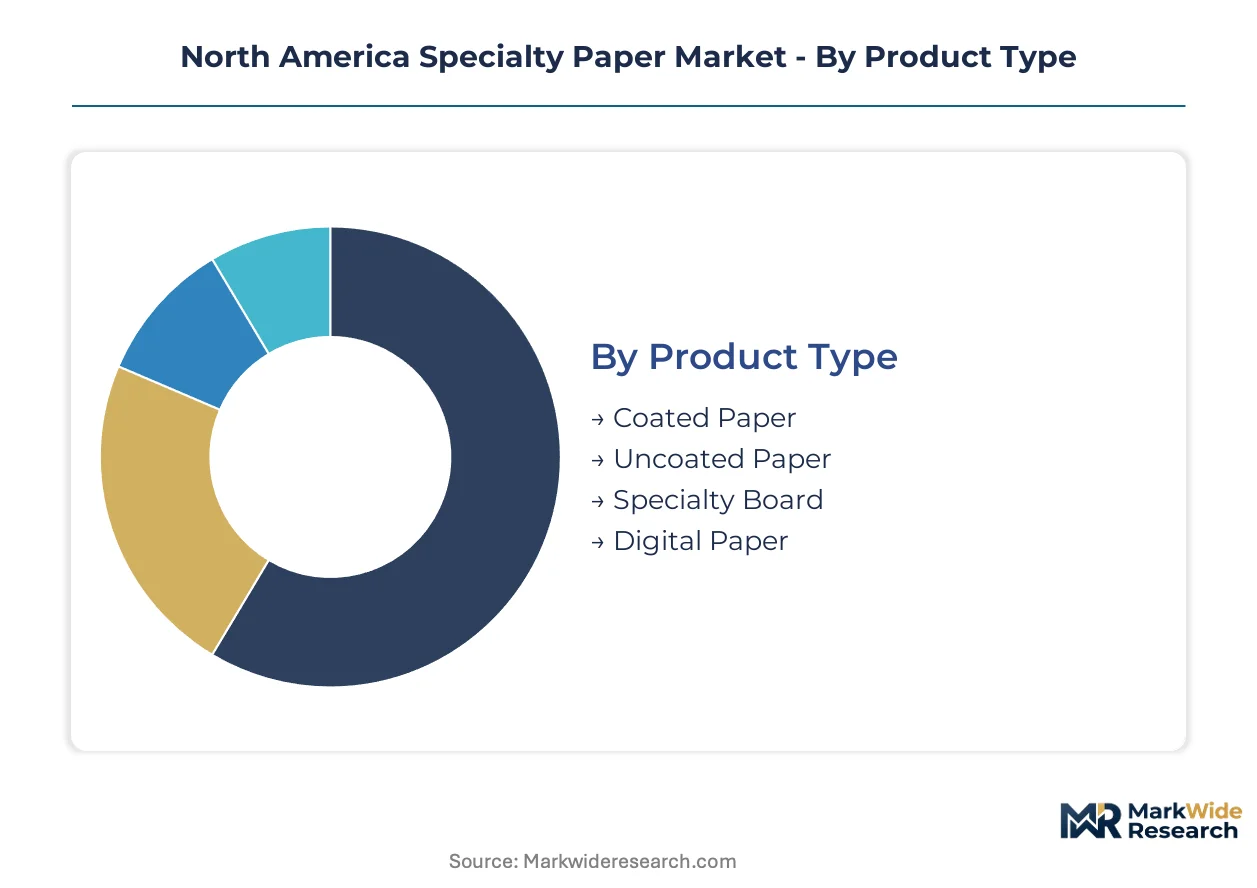
Specialty paper segmentation reveals divergent margin profiles across product architectures, with coating investments and barrier chemistry requirements creating distinct capital intensity tiers. Understanding these structural differences allows suppliers to align capacity commitments with contract duration and pricing power.
Product Type:
Inventory velocity varies dramatically across these four categories, with digital paper turning fastest on short-run commercial orders while specialty board sits longest on rigid packaging specifications.
- Coated Paper:Engineered with clay or calcium carbonate surface treatments to achieve uniform ink holdout and gloss control. Premium label and publication demand concentrates in the US Great Lakes corridor where integrated mills serve Midwestern consumer goods brands with just-in-time delivery. EPA recycled content mandates under the Comprehensive Procurement Preference program are reshaping federal contract specifications.
- Digital Paper:Manufactured with controlled moisture content and surface porosity optimized for inkjet and toner adhesion. Short-run commercial printing in Texas and California metro markets drives replacement of offset volumes, with converters prioritizing sheets certified for high-speed production equipment.
- Uncoated Paper:Refined pulp sheets without surface treatments, valued for absorbency and tactile properties in premium correspondence and archival applications.
- Specialty Board:High-caliper rigid substrates engineered for structural integrity in display and protective packaging where stiffness specifications resist plastic substitution.
Coated paper dominates installed base. Digital paper is where expansion concentrates.
End User:
Margin capture differs sharply across these demand pools, with packaging commanding premium barrier specifications while stationery operates on commodity economics.
- Packaging:Food contact applications requiring FDA-compliant grease barriers and mineral oil coatings. Quick-service restaurant chains and frozen food brands in California and Maine are accelerating qualification timelines as state EPR frameworks force substrate redesign for municipal sorting compatibility.
- Labels:Pressure-sensitive and wet-glue adhesive substrates demanding precise die-cutting performance. Beverage and personal care brand procurement departments are consolidating around vertically integrated mills with captive pulp supply.
- Printing:Commercial publication and direct mail substrates facing compression from digital substitution in short-run work.
- Stationery:Premium correspondence and writing papers where cotton fiber content and watermarking support price positioning in gift and corporate channels.
Packaging commands the highest specification premiums. Labels are climbing the fastest as brand security requirements intensify.
Application:
Technical complexity separates these use cases, with industrial filtration demanding engineered porosity while graphic arts competes on print consistency.
- Food Packaging:Direct-contact substrates requiring FDA food contact notifications for barrier coatings. The transition from fluorochemical to bio-based grease resistance is compressing incumbent asset values while rewarding early movers with approved formulations.
- Industrial Use:Battery separator and filtration media where controlled fiber orientation achieves precise porosity specifications. Technical talent scarcity in synthetic fiber blending constrains expansion at non-integrated facilities.
- Graphic Arts:Fine art and photographic printing papers where surface texture and archival stability differentiate premium positioning.
- Hygiene Products:Wipes and absorbent cores requiring wet strength resins and controlled linting properties for medical and consumer applications.
Food packaging dominates current volume. Industrial use holds the steepest expansion trajectory as energy storage manufacturing scales.
Distribution Channel:
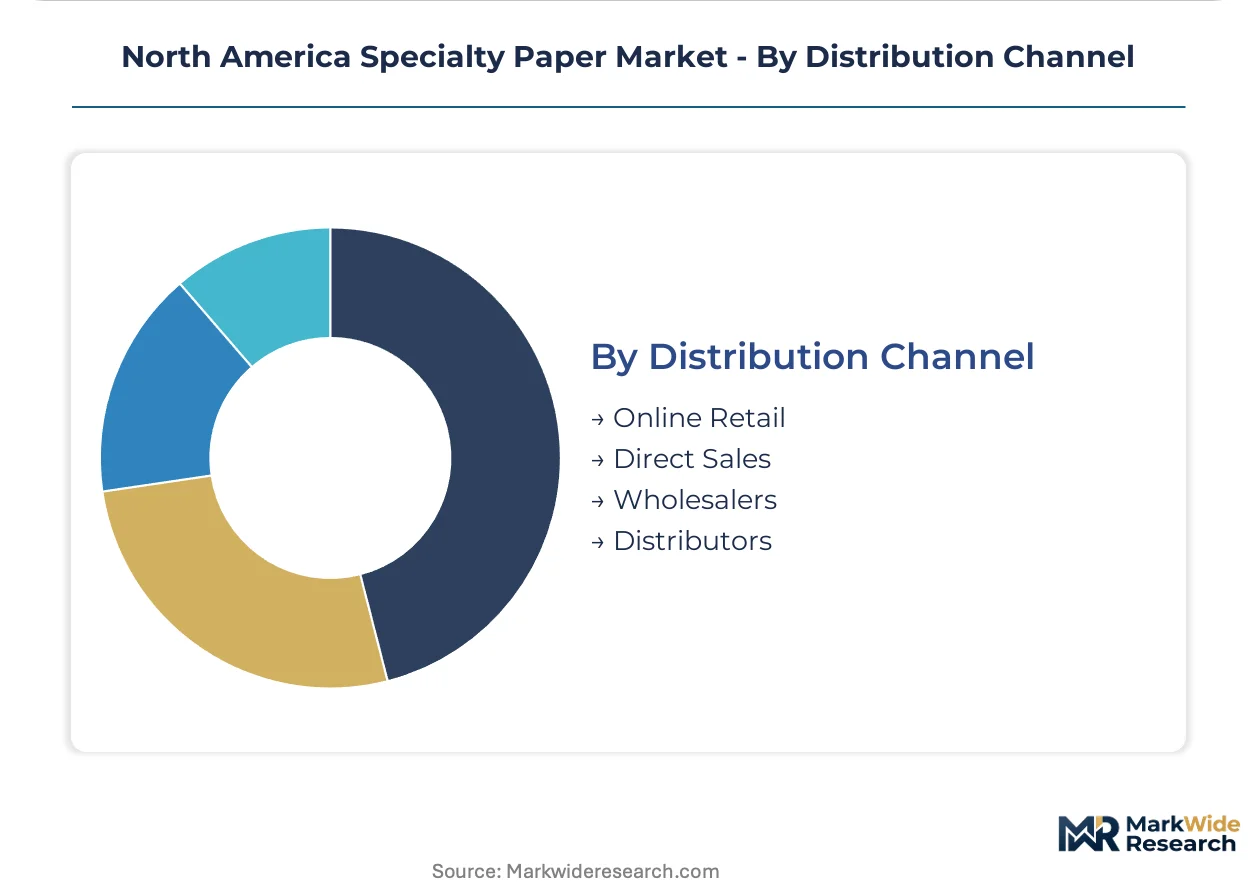
Customer scale and order fragmentation determine channel economics, with direct sales capturing large converters while online retail serves fragmented buyers.
- Direct Sales:Mill-direct relationships with national converters and brand owners seeking supply security and specification consistency. These accounts prioritize backward integration into fiber sourcing over pure price competition.
- Distributors:Regional inventory positioning for mid-scale converters requiring smaller lot sizes and technical service support.
- Wholesalers:Volume aggregation for commodity grades where specification tolerance allows multi-source procurement.
- Online Retail:E-commerce platforms serving small commercial printers and in-plant operations with standard sheet sizes and rapid fulfillment.
Direct sales anchors contract value. Online retail is gaining share fastest among entry-level converters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian mills extract premium pricing for FSC-certified specialty grades while US Great Lakes producers compete on logistics efficiency and scale. This pricing-power asymmetry shapes cross-border investment flows and capacity allocation decisions across the integrated North American market.
United States
Food packaging converters in the Midwest cluster around Chicago and Milwaukee to access Great Lakes freshwater resources and integrated pulp-to-paper operations. EPA recycled content mandates under the Comprehensive Procurement Preference program reshape federal contract specifications for coated paper grades. Wisconsin and Michigan mill assets serve quick-service restaurant chains with just-in-time barrier-coated substrates.
Canada
Quebec and Ontario anchor uncoated specialty production with captive hardwood pulp supply and certified fiber chain-of-custody documentation. Health Canada food contact regulations govern barrier coating approvals for direct food packaging applications. Domtar Corporation mill networks in the Ottawa Valley and Eastern Townships leverage hydropower integration for energy-intensive refining operations.
Mexico
Monterrey and Mexico City metro markets absorb imported specialty board for rigid packaging and display applications serving US-branded consumer goods. Mexican environmental regulator SEMARNAT enforces wastewater discharge standards for coating operations near metropolitan water supplies. Bajío Region automotive suppliers drive demand for technical filtration media in paint and coating processes.
North America Specialty Paper Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with niche specification control. The North American specialty paper market consolidates around vertically integrated pulp-to-paper operators with captive fiber supply and in-house coating capabilities. Three archetypes dominate: Great Lakes integrated mills with freshwater access, Southern US pulp network operators, and technical substrate specialists in filtration and energy storage. Competitive moves concentrate on strategic partnerships for barrier chemistry development and geographic expansion through asset-light leasing arrangements.
Among US-based integrated producers, International Paper and WestRock Company occupy positions as scale-driven platform operators with Southern pulp network leverage. Georgia-Pacific represents the private-capital archetype with flexible capacity allocation across packaging grades. Finnish-headquartered UPM-Kymmene Corporation and Stora Enso exemplify European multinationals with North American specialty paper assets positioned for bio-based material transitions.
| Leading Market Players |
|---|
| International Paper |
| Domtar Corporation |
| Sappi Limited |
| Stora Enso |
| WestRock Company |
| UPM-Kymmene Corporation |
| Glatfelter |
| Nippon Paper Industries |
| Georgia-Pacific |
| Others |
Cost & Logistics Intelligence
Canadian FSC-certified fiber concentration anchors premium pricing pools in uncoated specialty grades, while US Great Lakes integrated mills compete on logistics efficiency and scale-driven contract structures. Margin capture diverges sharply between certified sustainable substrates and commodity-coated alternatives.
Pricing Analysis
Configured-to-order pricing for FDA-compliant barrier coatings commands substantial premiums over standard uncoated grades. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Pricing pressure stems from pulp input cost volatility that converters cannot fully pass through to contract-bound customers. Quick-service restaurant chains exhibit highest price sensitivity due to consolidated procurement volumes, while battery separator substrate buyers prioritize specification consistency over unit economics.
Supply Chain Analysis
Tariff exposure between Canada and the United States dominates cross-border specialty paper trade risk calculations. Manufacturing concentrates in the United States, Canada, and Mexico with integrated pulp-to-paper operations clustering near Great Lakes freshwater resources. Northern bleached softwood kraft pulp, mineral oil barrier coatings, and synthetic fiber blends constitute critical input dependencies. Single-source vulnerability in fluorochemical alternative chemistry development threatens coating transition timelines. Distribution runs through mill-direct relationships with national converters and regional distributor networks serving mid-scale accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment in FDA food contact notifications creates substantial switching costs for qualified substrate suppliers.
For Market Incumbents: Pre-empt coating chemistry transition risks by accelerating mineral oil and bio-based barrier validation cycles before anticipated FDA restrictions strand fluorochemical investments. Secure captive pulp supply through backward integration or long-term offtake agreements to insulate margins from Northern bleached softwood kraft volatility. Domtar Corporation's Quebec hydropower integration exemplifies energy-cost positioning that competitors cannot replicate without capital-intensive mill assets. For New Entrants and Emerging Players: Build out asset-light leasing arrangements for pulp refining and coating equipment to access premium-grade capacity without full capital ownership. Target battery separator substrate applications where controlled porosity engineering commands premium positioning and technical talent scarcity constrains incumbent expansion. Pursue qualification partnerships with California and Maine food packaging converters facing accelerated EPR-driven substrate redesign timelines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed mid-scale converters lacking backward integration into fiber sourcing. Long-term viability favors vertically integrated operators with captive pulp supply and in-house coating capabilities serving government contracts under EPA recycled content mandates. Monitor FDA guidance publication timelines on per- and polyfluoroalkyl substance restrictions as inflection indicators for barrier coating asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Chemistry Transition | Early mineral oil coating validation captures FDA food contact notification precedence before fluorochemical restrictions finalize. |
| Asset-Light Capacity Access | Equipment leasing arrangements lower competitive entry thresholds for mid-scale converters seeking premium-grade production capabilities. |
| EPR-Compliant Substrate Design | California and Maine recyclability compatibility creates reference architecture for pending extended producer responsibility legislation. |
| Integrated Pulp Network Expansion | Captive fiber supply insulates margin compression from commodity pulp volatility in contract-bound customer relationships. |
| Technical Talent Acquisition | Synthetic fiber blending expertise constrains expansion at non-integrated facilities, creating scarcity premiums for qualified engineering teams. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with mill operations directors, coating chemists, food packaging procurement managers, and FDA regulatory consultants; and secondary validation against EPA Comprehensive Procurement Preference documentation, FDA food contact notification databases, state EPR legislative filings, and American Forest and Paper Association trade statistics. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic indicators produced convergent market sizing estimates.
Forecast inputs across the analysis window incorporated product type segmentation by coating architecture, end-user concentration in packaging versus publication applications, and geographic clustering around Great Lakes freshwater resources. CAGRs derived from regression analysis of historical pulp-to-paper capacity utilization and substitution elasticity parameters for plastic-to-fiber packaging transitions. Modeled variables included barrier coating qualification timelines and state-level EPR implementation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Southern US pulp network operators or European multinational bio-material specialists would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Inlay Paper Market
Paper Products
Middle-East and Africa Paper and Paperboard Market
Paper Products
Softwood Pulp Market
Paper Products
Organic Tissue Paper Market
Paper Products
Graphic Paper Market
Paper Products
Uncoated White Top Testliner Market
Paper Products
Carbonless Paper Market
Paper Products
Filtration Paper Market
Paper Products
Europe Thermal Paper Market
Paper Products
White Line Chipboard Market
Paper Products
Paper Making Machine Market
Paper Products
Polyester Synthetic Paper Market
Paper Products
Pp Synthetic Paper Market
Paper Products
Pulp Market
Paper Products
Paper Goods Market
Paper Products
Global Copier Paper Market