
 GCC Paper Products Market | 2026-2036
GCC Paper Products Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Paper Products Market Intelligence
Project finance tied to green bond issuance is rewriting competitive entry thresholds across GCC paper manufacturing. Hotpack Global leverages its integrated converting footprint to serve food service chains with consistent supply security. ENPI Group anchors its position through captive recycling streams that lower raw material volatility. Middle East Paper Company differentiates via specialty packaging grades that command premium positioning in pharmaceutical and luxury retail channels.
GCC paper products encompass engineered cellulose-based materials ranging from containerboard and folding boxboard to sanitary tissue and printing papers, typically manufactured through kraft pulping or recycled fiber repulping with basis weights from 40 gsm to 450 gsm depending on end-use performance requirements. These materials function as protective barriers, information carriers, and hygiene interfaces across commercial and consumer applications. Packaging paper dominates value generation as e-commerce fulfillment and quick-service restaurant expansion across the Gulf drive corrugated and flexible packaging consumption. Tissue represents the fastest-expanding segment as hospitality construction and healthcare infrastructure investment in Saudi Arabia and Qatar accelerate per-capita consumption convergence toward developed-market norms. Recycled fiber material streams face structural constraints from limited domestic collection infrastructure, creating margin pressure that virgin fiber and bamboo fiber alternatives partially offset through supply predictability.
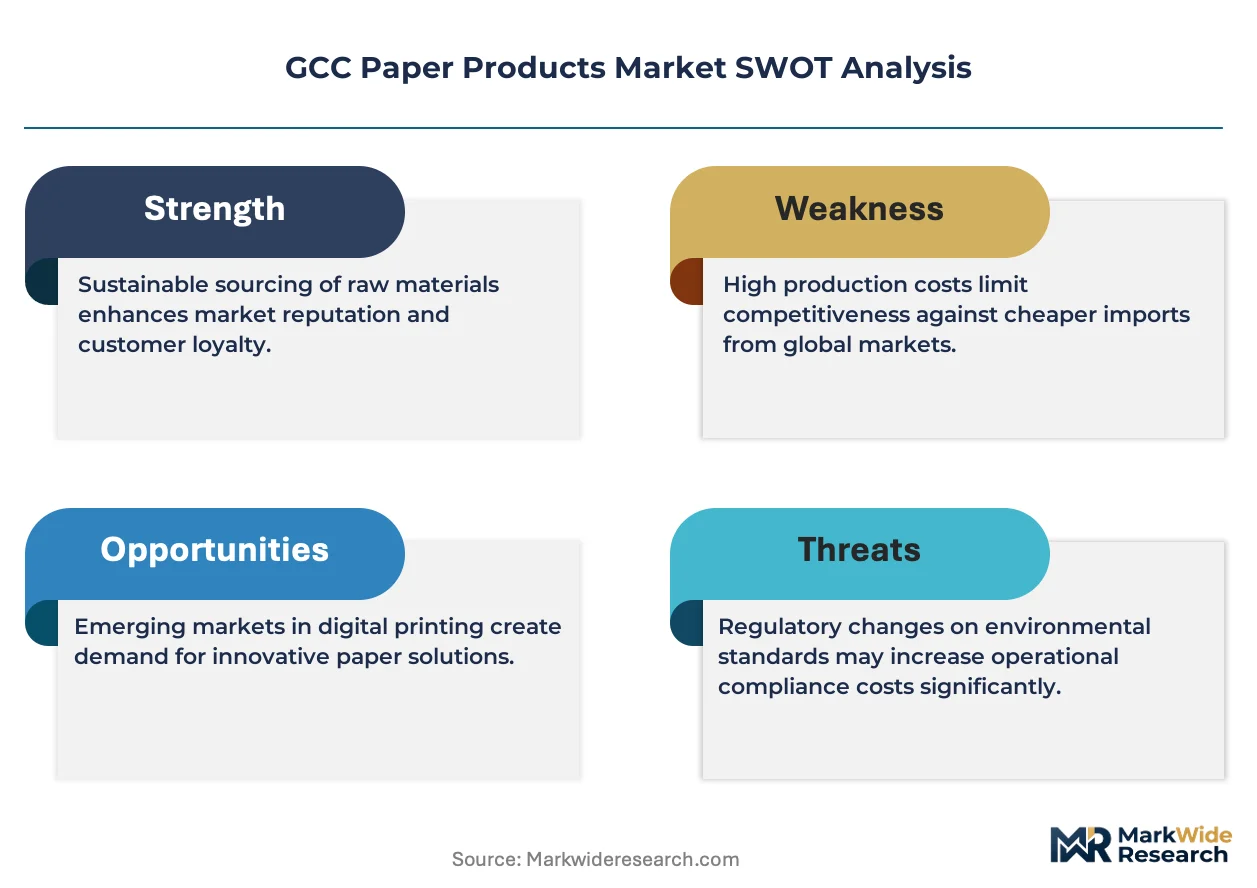
Saudi Standards, Metrology and Quality Organization (SASO) technical regulations mandate recyclability labeling and restrict heavy metal content in food-contact paper, while UAE Ministry of Climate Change and Environment circular economy policies impose post-consumer content targets on packaging supplied to government entities. Dubai Municipality and Abu Dhabi Quality and Conformity Council enforcement mechanisms intensify compliance verification through market surveillance programs. Stakeholders must monitor how GCC harmonization of extended producer responsibility schemes reshapes collection infrastructure economics and fiber sourcing strategies.
Market Dynamics
Extended producer responsibility frameworks across Saudi Arabia and the UAE are forcing food service operators to redesign packaging procurement around recyclability mandates and post-consumer content targets, compressing legacy supply chains.
Growth Catalysts
- SASO technical regulations:Mandatory recyclability labeling and heavy metal restrictions in food-contact paper accelerate compliant packaging substitution across Saudi food manufacturing.
- Quick-service restaurant expansion:Drive-thru and delivery format growth across the UAE and Qatar generates corrugated and flexible packaging pull at scale.
- Bamboo fiber pulping:Alternative fiber sourcing is virtualizing supply security for converters facing domestic recycled fiber collection gaps.
Market Restraints
- Recycled fiber scarcity:Limited domestic collection infrastructure in Saudi Arabia and Kuwait creates raw material volatility that virgin fiber premiums only partially offset.
- Energy cost concentration:Natural gas pricing exposure at integrated pulp-to-paper complexes in the Eastern Province compresses margin predictability.
- Plastic film substitution:Polypropylene and polyethylene barrier films retain cost advantages in moisture-sensitive food applications.
Strategic Opportunities
- Qatar hospitality construction:Healthcare and tourism infrastructure investment accelerates tissue consumption convergence toward developed-market per-capita norms.
- UAE circular economy policies:Post-consumer content mandates for government entity packaging create preferential sourcing channels for compliant converters.
- Pharmaceutical serialization:Track-and-trace compliance requirements in Saudi Arabia and the UAE drive specialty folding boxboard demand with integrated security features.
Industry Challenges
- Certification timeline compression:Dubai Municipality and Abu Dhabi Quality and Conformity Council market surveillance programs shorten compliance verification cycles for imported substrates.
- Skilled technician scarcity:Advanced converting equipment operation and color management expertise gaps constrain specialty packaging grade expansion.
- Legacy ERP integration:Batch-level traceability requirements for SASO compliance force reconfiguration of inventory management systems at mid-scale converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Paper Products Market |
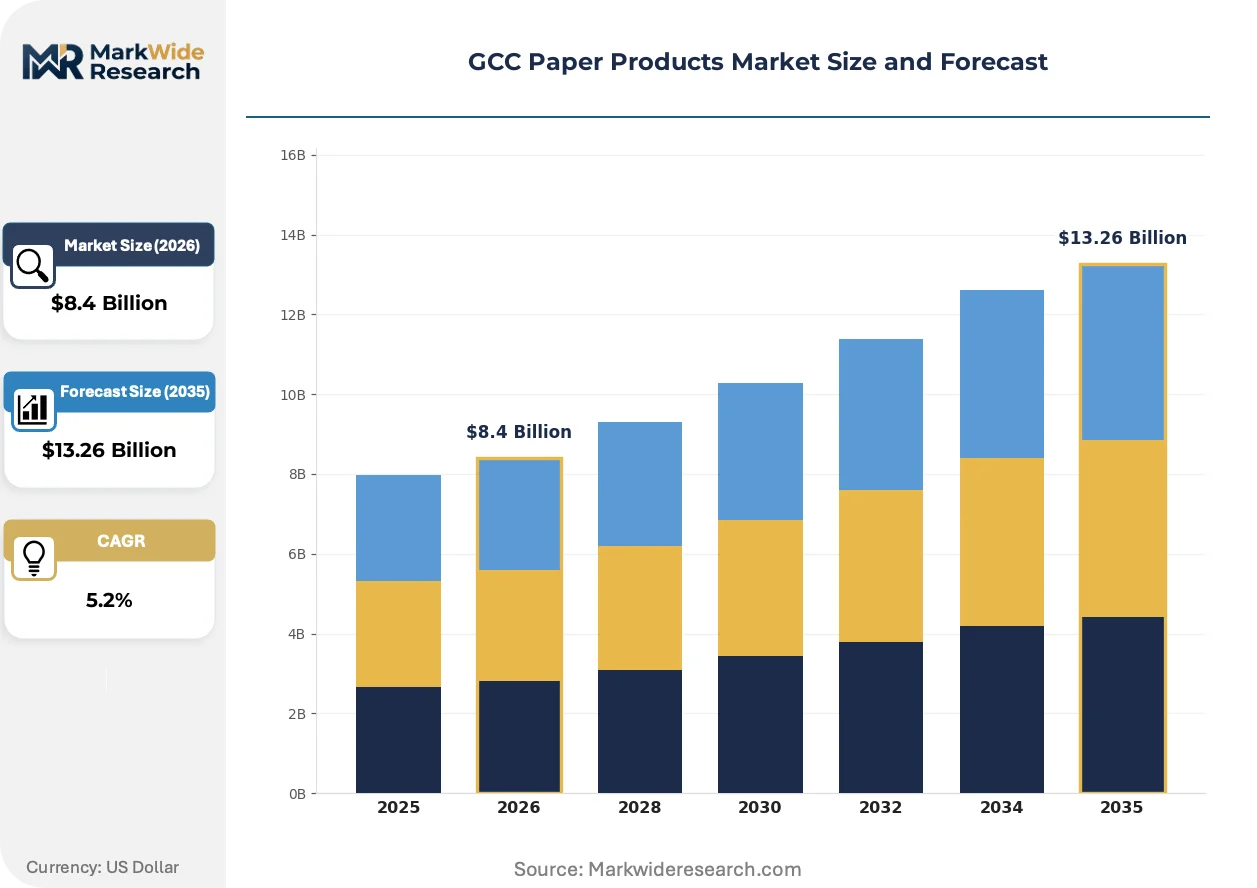
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.26 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paperboard, Tissue, Newsprint, Packaging Paper End User: Retail, Education, Healthcare, Food Service Application: Printing, Packaging, Hygiene, Stationery Material: Recycled Fiber, Virgin Fiber, Bamboo Fiber, Others |
| Companies Covered | Hotpack Global, ENPI Group, Golden Paper Cups Manufacturing, Gulf East Paper & Plastic Industries, Huhtamäki Oyj, Safeer Luxury Pack, Arkan, Middle East Paper Company, Al Kifah Paper Products, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Paper Products Market Strategic Shifts & Innovations
Digital workflow integration and regulatory data exchange requirements are compressing traditional specification-to-delivery cycles across GCC paper converting, while sustainability verification tools reshape supplier qualification protocols.
Blockchain-based chain-of-custody documentation is virtualizing fiber provenance verification for food-contact packaging. Major quick-service chains in Saudi Arabia and the UAE now mandate batch-level traceability from pulp source to finished carton. This technology is virtualizing audit costs and compressing supplier onboarding timelines from months to weeks.
SASO and UAE Ministry of Climate Change and Environment circular economy policies impose escalating post-consumer content thresholds on packaging supplied to government entities. Industrial consequence includes forced backward integration into recycling collection or long-term offtake agreements with regional recyclers. Pharmaceutical and luxury retail channels face the steepest compliance cost gradients.
Consolidated procurement by food service operators now bundles corrugated containers, flexible wraps, and foodservice disposables under single-source contracts with sustainability scorecard requirements. Regional distributors with integrated converting footprints capture volume previously fragmented across multiple suppliers. This pattern concentrates most visibly in Saudi Arabia's central industrial corridor serving Riyadh and Jeddah fulfillment networks.
GCC Paper Products Market Segmentation
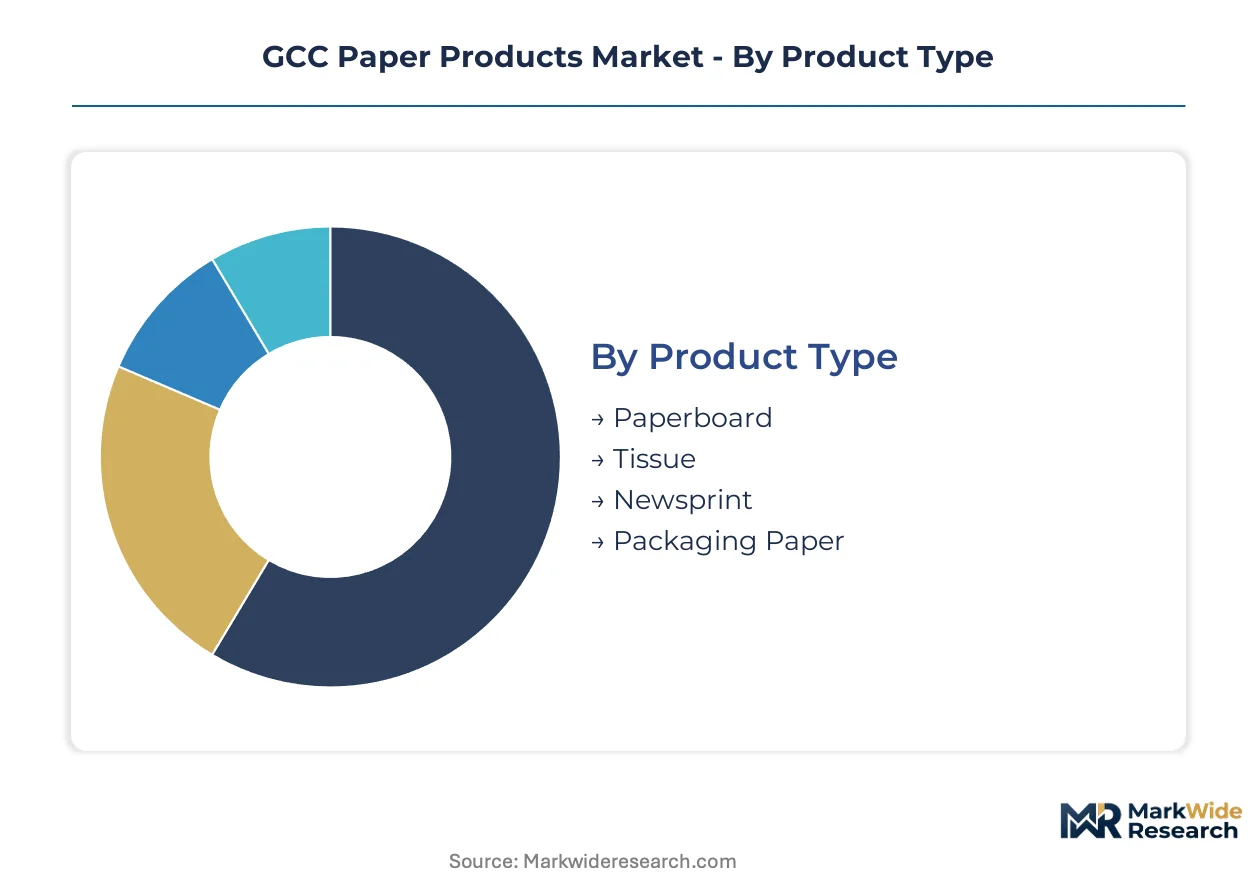
Paper product specifications diverge sharply across GCC end-uses, with food-contact compliance and moisture barrier performance driving grade selection. Segmentation clarity enables converters to align fiber sourcing and coating investments with precise customer requirements.
Product Type:
Cost tier differentiation separates commodity grades from engineered substrates commanding formulation premiums.
- Packaging Paper:Corrugated medium and linerboard grades dominate tonnage flows, with Saudi Arabia's central industrial corridor serving e-commerce fulfillment networks and quick-service restaurant supply chains. Virgin kraft pulping at integrated complexes provides predictable strength properties that recycled fiber alternatives struggle to match.
- Tissue:Facial, towel, and napkin products manufactured from virgin or recycled pulp serve hospitality and healthcare infrastructure expansion across Qatar and Saudi Arabia. Per-capita consumption is climbing toward developed-market norms as hospital and hotel construction accelerates.
- Paperboard:Folding boxboard and solid bleached sulfate grades protect pharmaceutical and luxury retail products requiring stiffness and printability.
- Newsprint:Mechanical pulp-based publication grades face structural decline as digital media displaces print circulation.
Packaging Paper commands the established base. The steepest expansion runs through Tissue.
End User:
Customer type determines compliance burden and contract structure across procurement relationships.
- Food Service:Quick-service chains and cloud kitchen operators in the UAE and Saudi Arabia mandate batch-level traceability and recyclability certification under SASO technical regulations. Consolidated procurement bundles corrugated containers, flexible wraps, and disposables under sustainability scorecard requirements.
- Healthcare:Hospitals and clinics in Qatar's new medical cities drive sterilization wrap and examination table paper consumption. Infection control protocols favor virgin fiber grades with consistent barrier properties.
- Retail:E-commerce fulfillment centers require corrugated shipping containers and protective dunnage at scale.
- Education:Workbook and copier paper demand tracks student enrollment and government procurement cycles.
Food Service captures the highest compliance intensity. Healthcare is gaining share fastest as infrastructure investment concentrates in Qatar and Saudi Arabia.
Application:
Functional requirements dictate basis weight, coating chemistry, and finishing specifications.
- Packaging:Protective and containment functions span corrugated shipping boxes, folding cartons, and flexible wraps. Moisture vapor transmission rates and grease resistance specifications vary by food-contact requirements.
- Hygiene:Absorbency and softness metrics define tissue and towel performance for hospitality and consumer markets.
- Printing:Offset and digital print compatibility requires surface smoothness and ink holdout optimization.
- Stationery:Writing and copier grades balance opacity, brightness, and runnability.
Packaging anchors volume generation. Hygiene applications are expanding most quickly alongside hospitality construction.
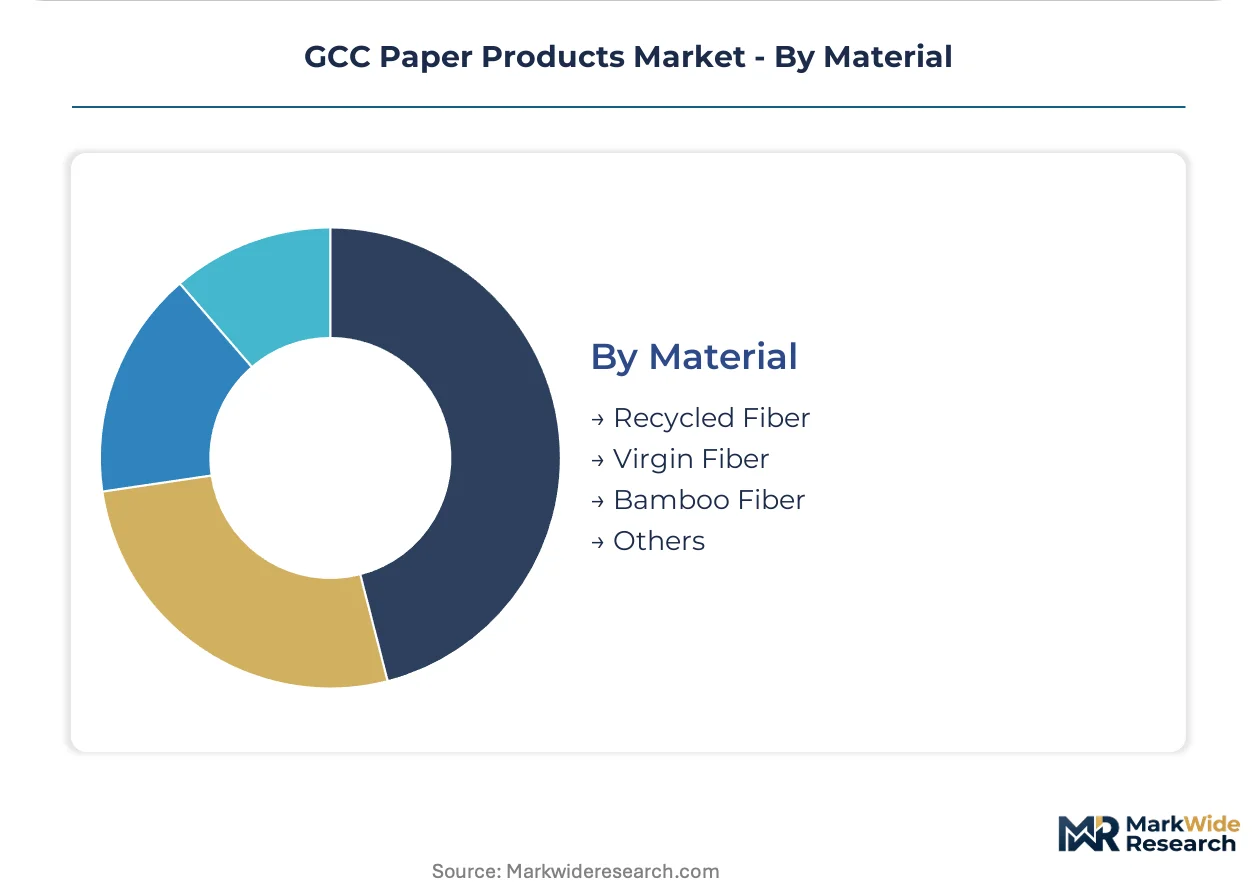
Material:
Supply concentration and collection infrastructure shape fiber economics across the Gulf.
- Virgin Fiber:Kraft pulping of softwood and hardwood delivers predictable strength and purity for food-contact and medical applications. Saudi Arabia's integrated pulp-to-paper complexes anchor regional supply security.
- Recycled Fiber:Post-consumer collection gaps in Kuwait and Saudi Arabia constrain availability, forcing converters to import baled waste paper or pay premiums for domestic supply.
- Bamboo Fiber:Alternative lignocellulosic sourcing from Asian plantation supply chains virtualizes raw material security for specialty converters.
- Others:Agricultural residue and non-wood fibers occupy niche sustainability positioning.
Virgin Fiber holds the production base. Bamboo Fiber is climbing the fastest as converters seek supply predictability beyond recycled fiber volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SASO technical regulations and UAE circular economy mandates are redrawing procurement geography across Gulf paper markets. National compliance timelines now determine where converters expand converting capacity and where distributors build inventory positions.
Saudi Arabia
Integrated pulp-to-paper complexes in the Eastern Province anchor regional virgin fiber supply for food-contact packaging. SASO recyclability labeling mandates accelerate compliant substrate substitution across Riyadh-based food manufacturing clusters. The central industrial corridor serving Jeddah fulfillment networks concentrates corrugated medium and linerboard production capacity.
United Arab Emirates
Dubai Municipality market surveillance programs compress certification timelines for imported paper substrates entering quick-service restaurant supply chains. MOHAP and Abu Dhabi Quality and Conformity Council enforcement mechanisms intensify heavy metal content verification in food-contact grades. Jebel Ali free zone logistics hubs aggregate re-export volumes to African and South Asian markets.
Qatar
Healthcare and hospitality infrastructure investment in Doha's new medical cities accelerates tissue consumption convergence toward developed-market per-capita norms. The country's national environmental regulator imposes post-consumer content thresholds on government entity packaging procurement. Industrial zone concentrations in Ras Laffan support specialty converting for pharmaceutical serialization requirements.
Kuwait
Limited domestic recycled fiber collection infrastructure forces converters to import baled waste paper or absorb virgin fiber premiums. The national standards body enforces labeling requirements that track SASO technical regulation harmonization. Shuwaikh industrial area hosts mid-scale converters serving food service and retail channels with flexible packaging grades.
Bahrain
Strategic positioning as a financial and logistics hub supports paper product re-export activity to Eastern Province and Eastern Province-adjacent markets. The national environmental regulator participates in GCC extended producer responsibility framework coordination. Sitra industrial zone concentrates converting capacity for regional quick-service restaurant chains.
GCC Paper Products Market Key Industry Players
Channel-controlling players compete with product-specialist players across procurement consolidation and sustainability verification vectors. Market structure tilts toward integrated distributors with captive converting footprints that bundle corrugated, flexible, and disposable categories under single-source contracts. Three archetypes dominate: integrated pulp-to-paper complexes with virgin fiber security, regional distributors with backward integration into recycling collection, and specialty converters serving pharmaceutical and luxury retail compliance tiers. Dominant competitive moves include strategic partnerships with quick-service chains for batch-level traceability mandates and capacity expansion in bamboo fiber pulping to virtualize supply predictability.
Among Gulf-based integrated operators, Hotpack Global and ENPI Group exemplify channel-control archetypes that leverage converting footprint scale to serve consolidated food service procurement. Middle East Paper Company occupies a specialty-tier position differentiated by pharmaceutical and luxury retail grade capabilities. Finnish-listed Huhtamäki Oyj represents the multinational fabricator archetype competing through sustainability certification portability across Gulf regulatory jurisdictions.
| Leading Market Players |
|---|
| Hotpack Global |
| ENPI Group |
| Golden Paper Cups Manufacturing |
| Gulf East Paper & Plastic Industries |
| Huhtamäki Oyj |
| Safeer Luxury Pack |
| Arkan |
| Middle East Paper Company |
| Al Kifah Paper Products |
| Others |
Cost & Logistics Intelligence
Saudi Arabia's Eastern Province integrated pulp-to-paper complexes anchor regional virgin fiber supply, translating captive kraft pulping capacity into pricing leverage over converters dependent on imported recycled fiber bales. This geographic concentration enables integrated operators to command contract premiums while mid-scale converters absorb volatility from limited domestic collection infrastructure.
Pricing Analysis
Certification level creates the primary spread across GCC paper products, with SASO-compliant food-contact grades and pharmaceutical serialization-ready boxboard commanding substantial premiums over commodity packaging tiers. Three-tier pricing structure across premium, standard, and economy levels reflects compliance burden, fiber purity, and traceability depth. Cost compression in standard-grade corrugated runs through energy pricing exposure at Eastern Province gas-fired complexes. Quick-service restaurant chains exhibit highest price sensitivity due to consolidated procurement volumes, while pharmaceutical and luxury retail channels prioritize certification assurance over unit cost.
Supply Chain Analysis
Recycled fiber scarcity between Saudi Arabia and Kuwait dominates supply chain risk, forcing converters to source baled waste paper from Asian export markets or absorb virgin fiber premiums. Raw material flows draw from Indonesian bamboo plantations, European kraft pulp producers, and regional integrated complexes. Distribution runs through Jebel Ali free zone logistics hubs aggregating re-export volumes to African and South Asian markets, with Riyadh and Jeddah fulfillment networks serving domestic e-commerce and food service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC paper markets face structural disruption as extended producer responsibility frameworks and blockchain traceability mandates rewrite supplier qualification protocols. SASO technical regulations and UAE circular economy policies are compressing legacy supply chains while rewarding backward-integrated operators.
For Market Incumbents: Build captive recycling collection moats through long-term municipal offtake agreements or in-house collection infrastructure investments. Expand converting capacity in Saudi Arabia's central industrial corridor to capture consolidated quick-service procurement bundles. Defend against bamboo fiber entrants by locking multi-year virgin pulp supply contracts with Eastern Province complexes. For New Entrants and Emerging Players: Specialty pharmaceutical packaging in Qatar's Ras Laffan industrial zone represents the most penetrable entry point given serialization compliance requirements and limited incumbent specialization. Target healthcare tissue supply to Doha's new medical cities where per-capita consumption convergence creates volume upside. Pursue sustainability certification portability as primary go-to-market angle for multinational quick-service chain qualification. For Investors and Strategic Acquirers: Long-term, this sits as a circular-economy infrastructure play because regulatory mandates for post-consumer content are structurally advantaging collection-integrated converters over pure manufacturing assets. Acquisition focus should center on mid-scale distributors with backward integration into recycling streams and established government entity supply relationships. Watch for SASO-UAE regulatory harmonization announcements as signal for accelerated consolidation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling Collection | Captures margin from domestic post-consumer fiber scarcity while meeting MOHAP content mandates. |
| Bamboo Fiber Pulping Capacity Expansion | Virtualizes supply security beyond volatile recycled fiber import dependence for specialty converters. |
| Blockchain Traceability Platform Deployment | Compresses supplier onboarding timelines from months to weeks for quick-service chain compliance. |
| Pharmaceutical Serialization Grade Investment | Captures premium positioning in Qatar and Saudi Arabia track-and-trace regulatory environments. |
| Consolidated Procurement Contract Bundling | Aggregates corrugated, flexible, and disposable volumes under single-source sustainability scorecards. |
Research Approach
Initial hypotheses were tested against primary input from paper mill operations directors, food service procurement heads, regulatory compliance officers, and recycling collection operators and refined through secondary validation against SASO technical regulation filings, UAE Ministry of Climate Change circular economy policy documents, customs trade data for pulp and recovered paper flows, and GCC industrial zone capacity disclosures. Bottom-up demand modeling across end-use segments triangulated with top-down supply capacity assessments.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by product type, end-user vertical, material fiber source, and application function. CAGRs were derived from installed capacity expansion timelines, per-capita consumption convergence patterns, and regulatory mandate implementation schedules. Forecast inputs incorporated hospitality construction pipelines in Qatar and Saudi Arabia, quick-service restaurant unit expansion plans, and extended producer responsibility framework adoption trajectories.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing, regional construction investment cycles, or Asian pulp export pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation timelines and fiber substitution elasticity. Material shifts in SASO-UAE regulatory harmonization pace or breakthroughs in domestic collection infrastructure economics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Base Paper Market
Paper Products
Latex-Saturated Paper Market
Paper Products
NCR Laser Paper Market
Paper Products
Global Paper Chemical Market
Paper Products
Metallized Paper Market
Paper Products
Asia-Pacific Thermal Paper Market
Paper Products
Recording Chart Paper Market
Paper Products
Wood Paper and Paperboard Recycling Market
Paper Products
Printing Paper Market
Paper Products
Europe Medium-Density Fiberboard Market
Paper Products
Pp Synthetic Paper Market
Paper Products
GCC Stone Paper Market
Paper Products
Paper Doilies Market
Paper Products
Thin Printing Paper Market
Paper Products
Wood-Based Sheet Materials Market
Paper Products
Graphic Paper Market