
 Paper Pigment Market | 2026-2036
Paper Pigment Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Pigment Market Analytics
Calcium carbonate is shifting from a secondary filler to a primary opacifying agent in woodfree coated grades, tightening the economics against titanium dioxide in cost-sensitive segments. Imerys leverages vertically integrated marble quarrying in Europe to anchor premium brightness supply chains. Omya AG competes through dense ground calcium carbonate networks across Asia-Pacific. Minerals Technologies Inc. specializes in precipitated calcium carbonate with controlled particle size distributions for inkjet receptive coatings.
Paper pigments comprise inorganic minerals engineered to specific particle size, brightness, and refractive index for opacity, gloss, and printability enhancement in paper substrates. Titanium dioxide delivers the highest refractive index among commercial fillers, though calcium carbonate dominates volume due to lower cost and alkaline pH buffering during papermaking. Coated paper applications capture the largest value share, while specialty paper grades for barrier packaging expand fastest as food-contact compliance requirements intensify. Dry powder forms lead procurement volumes, though liquid slurries gain share at integrated mill sites for handling efficiency and dust reduction.
EPA effluent guidelines constrain US pigment manufacturing discharge profiles, while REACH registration requirements in Europe filter non-compliant mineral importers from coating supply chains. China's MEE enforces stricter particulate emissions standards at kaolin and calcium carbonate processing facilities, elevating compliance costs for regional producers. Stakeholders must monitor how evolving extended producer responsibility frameworks for paper packaging reshape pigment specification priorities across converter and brand-owner procurement teams.
Market Dynamics
Calcium carbonate's displacement of titanium dioxide in mid-brightness coated grades is restructuring supplier economics, as integrated European marble processors capture margin from commodity TiO2 producers facing energy cost volatility.
Growth Catalysts
- EU Green Deal packaging mandates:Food-contact barrier paper specifications are tightening virgin fiber thresholds, forcing mills to load higher mineral content for opacity without sacrificing recyclability.
- India's expanding woodfree capacity:Regional paper investment clusters in Gujarat and Maharashtra are absorbing precipitated calcium carbonate slurry volumes previously exported to Southeast Asia.
- Inkjet receptive coating proliferation:High-speed production inkjet presses require controlled particle size distributions that precipitated calcium carbonate delivers more reliably than ground alternatives.
Market Restraints
- Natural gas cost volatility:Precipitated calcium carbonate calcination depends on natural gas, exposing European producers to input cost swings that ground calcium carbonate quarries avoid.
- TiO2 sulfate process concentration:Chloride-route titanium dioxide capacity concentrates in China, creating supply vulnerability for North American coated paper mills seeking chloride-grade brightness.
- Kaolin brightness ceiling:Georgia sedimentary kaolin deposits face depletion of premium brightness zones, limiting replacement options for high-end art paper specifications.
Strategic Opportunities
- Brazil's packaging conversion wave:Extended producer responsibility frameworks for corrugated and folding carton are accelerating mineral loading rates as domestic mills reduce basis weights.
- Dry-to-slurry distribution shift:Liquid calcium carbonate slurry systems at integrated mill sites eliminate pneumatic handling infrastructure, opening retrofits at mid-scale European facilities.
- Biomass calcination pilots:Precipitated calcium carbonate producers in Scandinavia are testing wood-pellet calcination to decouple from natural gas price cycles and align with EU taxonomy eligibility.
Industry Challenges
- Particle size distribution control:Precipitated calcium carbonate production requires precise carbonation reactor management, and skilled process engineers are scarce in emerging production regions.
- Food-contact migration testing:New barrier coating formulations face extended FDA and EFSA compliance timelines as regulators scrutinize nanoparticle behavior in fatty food simulants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Pigment Market |
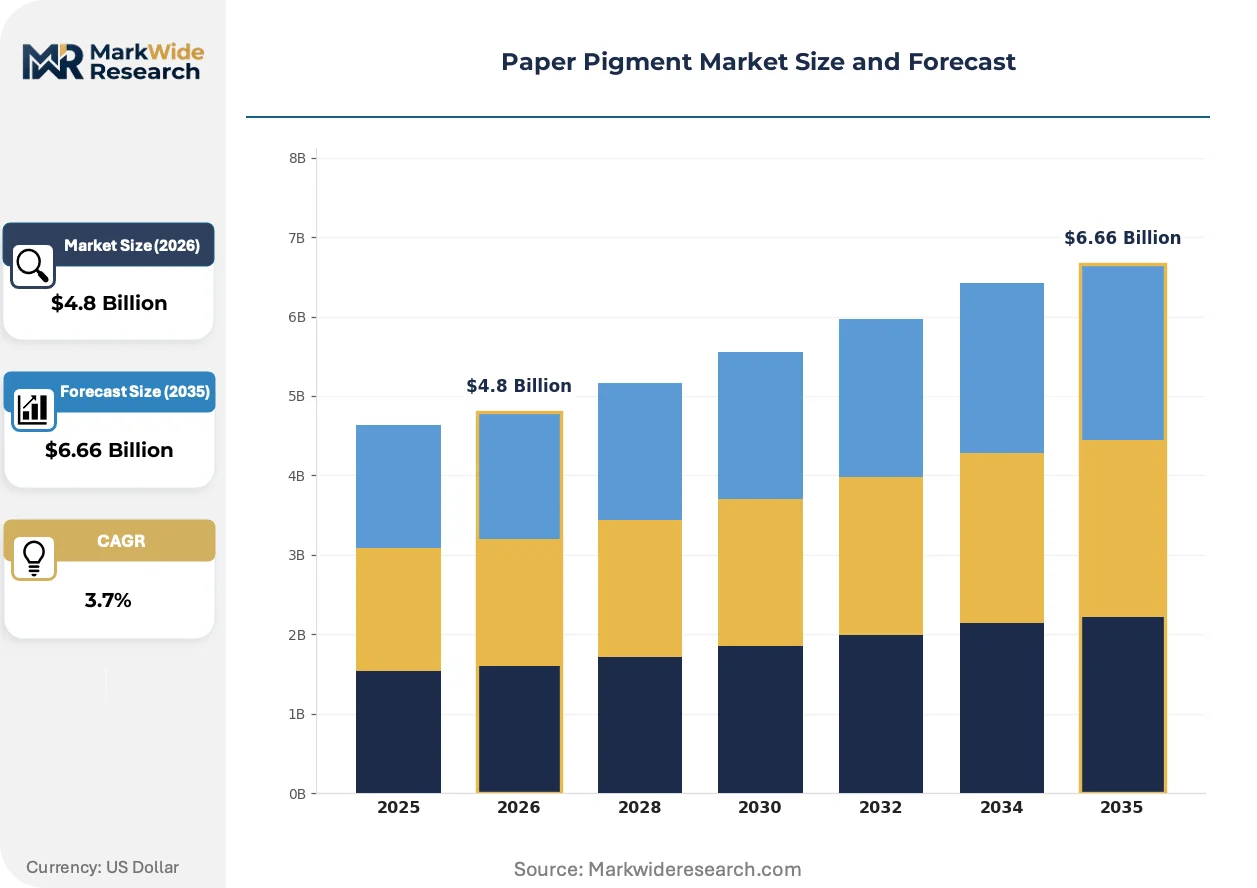
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Titanium Dioxide, Calcium Carbonate, Clay, Barium Sulfate Application: Coated Paper, Uncoated Paper, Specialty Paper, Printing Paper End User: Publishing, Packaging, Stationery, Tissue Form: Dry Powder, Liquid, Granules, Paste |
| Companies Covered | Imerys, Omya AG, Minerals Technologies Inc., BASF SE, Ashapura Group, Thiele Kaolin Company, Clariant AG, Huntsman International LLC, Kemira Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Pigment Market Evolving Landscape
Digital printing penetration and circular packaging mandates are forcing pigment suppliers to engineer for narrower specification bands while proving recyclability compatibility across multiple paper lifecycles.
On-line particle size analyzers using laser diffraction are automating precipitated calcium carbonate reactor control, enabling real-time adjustment of carbonation flow rates. Specialty paper mills in Germany and Japan have adopted closed-loop systems that cut batch-to-batch brightness variation by half. This precision is automating the displacement of off-spec inventory that previously absorbed working capital.
REACH registration requirements for imported mineral fillers are tightening impurity disclosure thresholds, filtering non-compliant kaolin and calcium carbonate sources from EU coating supply chains. Paper converters in France and Italy now require full substance dossiers from pigment suppliers. The compliance burden falls heaviest on small-volume specialty grades where registration cost amortization stretches across thinner tonnage bases.
Brand-owner sustainability scorecards are compressing pigment procurement cycles as packaging designers iterate barrier coating formulations to hit recyclability targets. Major food retailers in the United Kingdom and Netherlands now specify mineral content limits compatible with their declared fiber recovery rates. This specification volatility is most visible in folding carton applications where annual contract renegotiations have replaced multi-year supply agreements.
Paper Pigment Market Segmentation
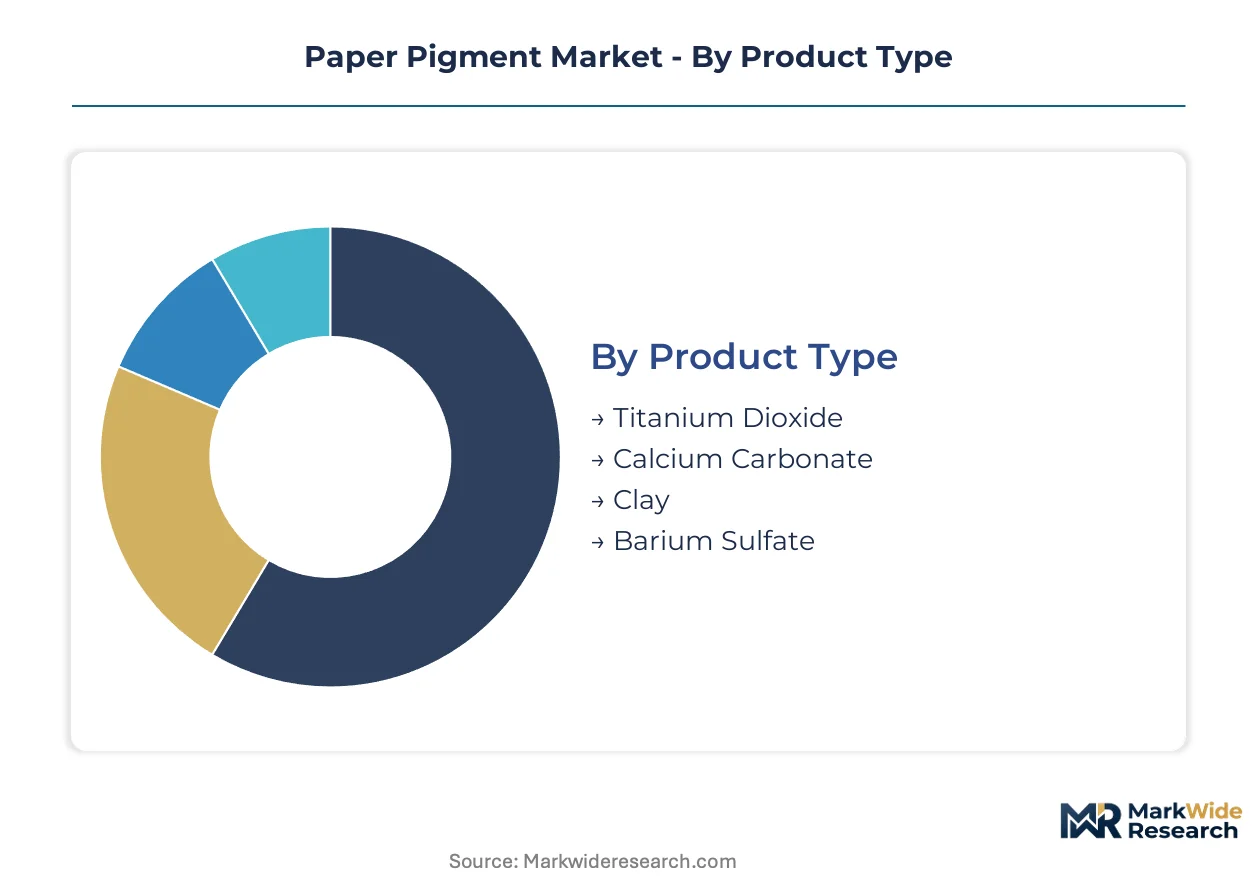
Pigment procurement patterns diverge sharply across paper grades, with coating specifications demanding engineered particle architectures that filler applications tolerate less precisely. Understanding these segment boundaries clarifies where suppliers can standardize versus where customization commands premium positioning.
Product Type:
Cost sensitivity and brightness requirements split buyers into commodity filler adopters versus premium opacifier specifiers.
- Titanium Dioxide:Rutile and anatase crystal structures deliver refractive indices above 2.5, creating maximum opacity at low loadings. North American coated paper mills specify chloride-route grades for art paper brightness, though sulfate-process volumes dominate cost-conscious packaging segments.
- Calcium Carbonate:Precipitated variants with controlled 0.5-2.0 micron particle diameters anchor inkjet receptive coatings, while ground marble products serve commodity woodfree grades. German specialty mills increasingly specify liquid slurry delivery to eliminate on-site powder handling infrastructure.
- Clay:Hydrous kaolin from Georgia sedimentary deposits retains dominance in lightweight coated publication grades despite brightness ceiling constraints.
- Barium Sulfate:Synthetic precipitated grades serve high-density packaging applications requiring X-ray detectability in food-contact specifications.
Calcium carbonate leads volumes today; titanium dioxide maintains the steepest expansion trajectory in barrier packaging specifications.
Application:
Surface treatment intensity determines mineral loading rates and particle size precision requirements.
- Coated Paper:Multiple-layer coating architectures demand stratified pigment blends—calcium carbonate in base layers for bulk, titanium dioxide in topcoats for gloss and print fidelity. Japanese art paper producers specify sub-micron particle distributions for mirror-finish calendering.
- Specialty Paper:Grease-resistant barrier coatings for fast-food packaging absorb precipitated calcium carbonate at loadings exceeding 35% by weight to compensate for reduced fiber content under EU Green Deal recyclability mandates.
- Uncoated Paper:Internal filler applications prioritize retention chemistry over surface engineering, favoring ground calcium carbonate with broader particle distributions.
- Printing Paper:Heatset web offset grades balance opacity against bulk, with clay-carbonate hybrid fillers dominating North American newsprint conversions.
Coated paper captures value concentration; specialty paper is expanding most quickly as food-contact compliance tightens.
End User:
Brand-owner sustainability scorecards versus operational cost pressures differentiate procurement behavior across verticals.
- Packaging:Folding carton converters in the Netherlands and United Kingdom now specify mineral content ceilings compatible with declared fiber recovery rates, forcing iterative formulation cycles that compress pigment contract durations.
- Publishing:Magazine and catalog producers migrate to lighter basis weights with higher mineral loading to manage postal cost structures, favoring cost-optimized ground calcium carbonate over precipitated alternatives.
- Stationery:Premium writing paper specifications retain clay-carbonate blends for tactile surface characteristics that digital substitutes cannot replicate.
- Tissue:Facial and towel grades utilize minimal pigment loading, with brightness achieved through bleaching chemistry rather than mineral addition.
Packaging dominates volume absorption; publishing represents the most price-pressured segment.
Form:
Handling infrastructure investment and dust exposure regulations determine physical state preferences.
- Dry Powder:Bagged shipments retain dominance at non-integrated converters lacking slurry storage silos, though pneumatic handling systems face escalating OSHA respirable dust compliance costs.
- Liquid:Slurry systems at integrated European mill sites eliminate powder handling entirely, with 70% solids dispersions reducing transportation cost per unit pigment.
- Granules:Compacted calcium carbonate products address dust concerns at mid-scale facilities without slurry infrastructure investments.
- Paste:High-viscosity preparations serve niche coating applications requiring precise rheology control without dilution steps.
Dry powder maintains installed base dominance; liquid slurry is gaining share fastest at greenfield integrated facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr industrial corridor anchors European precipitated calcium carbonate production, with integrated mill sites driving liquid slurry adoption rates ahead of continental averages.
Germany
Specialty paper mills in Bavaria and North Rhine-Westphalia absorb precipitated calcium carbonate slurries for barrier packaging grades. The EU Green Deal packaging sustainability directives enforce virgin fiber reduction targets, elevating mineral loading requirements. The Ruhr Valley chemical cluster hosts carbonation reactor facilities supplying liquid pigment systems to integrated paperboard producers.
China
Expanding woodfree coated paper capacity in Shandong and Guangdong provinces consumes ground calcium carbonate volumes from domestic marble quarries. The Ministry of Ecology and Environment enforces stricter particulate emissions standards at mineral processing facilities. The Yangtze River Delta paper manufacturing belt concentrates demand for high-brightness filler grades in export-oriented publication papers.
United States
Coated paper mills in Wisconsin and Maine specify chloride-route titanium dioxide for art paper brightness despite sulfate-process cost advantages. EPA effluent guidelines constrain pigment manufacturing discharge profiles at kaolin processing sites. The Georgia sedimentary kaolin belt faces depletion of premium brightness zones, limiting replacement options for high-end specifications.
India
Regional paper investment clusters in Gujarat and Maharashtra absorb precipitated calcium carbonate slurry volumes previously exported to Southeast Asia. The Bureau of Indian Standards tightens food-contact packaging material specifications for fast-food sector expansion. The Vapi industrial corridor hosts mineral processing facilities supplying barrier coating formulations to domestic folding carton converters.
Brazil
Extended producer responsibility frameworks for corrugated and folding carton accelerate mineral loading rates as domestic mills reduce basis weights. ANVISA scrutinizes food-contact migration testing timelines for new barrier coating formulations. The São Paulo state paper manufacturing cluster drives demand for calcium carbonate in lightweight packaging grades serving Mercosur export markets.
Paper Pigment Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated marble processors capture margin from commodity titanium dioxide producers facing energy cost volatility. The vendor base stratifies between vertically integrated quarry operators, specialty precipitated calcium carbonate engineers, and diversified chemical conglomerates with pigment divisions. Three archetypes define competitive positioning: European marble-based brightness suppliers, Asian ground calcium carbonate network operators, and North American precipitated calcium carbonate technology specialists. Geographic expansion and backward integration into captive raw material supply represent the dominant competitive moves.
Within the integrated quarrying tier, Imerys leverages vertically integrated marble operations to anchor premium brightness supply chains. Omya AG exemplifies the dense distribution network archetype with ground calcium carbonate positioning across Asia-Pacific markets. Minerals Technologies Inc. occupies the specialty engineering position, with controlled particle size distribution capabilities serving inkjet receptive coating specifications. These three anchors illustrate how competitive differentiation flows from raw material access, distribution density, and technical specification precision respectively.
| Leading Market Players |
|---|
| Imerys |
| Omya AG |
| Minerals Technologies Inc. |
| BASF SE |
| Ashapura Group |
| Thiele Kaolin Company |
| Clariant AG |
| Huntsman International LLC |
| Kemira Oyj |
| Others |
Value Network & Pricing Analysis
Integrated European paperboard producers concentrate procurement volumes for precipitated calcium carbonate slurries, anchoring contract-based long-term offtake structures that insulate premium brightness suppliers from spot market volatility. This buyer concentration enables marble-based processors to capture margin through volume-commitment pricing while commodity titanium dioxide producers absorb energy cost swings.
Pricing Analysis
Natural gas pass-through clauses dominate precipitated calcium carbonate contracts, exposing European producers to input cost volatility that ground calcium carbonate quarries avoid. Three-tier pricing structure across premium, standard, and economy levels separates chloride-route titanium dioxide for art paper brightness from sulfate-process grades in packaging segments. Cost compression in mid-brightness coated grades is intensifying because calcium carbonate displacement tightens TiO2 producer margins. Publishing segment buyers exhibit highest price sensitivity, while specialty barrier coating specifiers prioritize food-contact compliance over unit cost.
Supply Chain Analysis
Maritime freight rates from Chinese calcium carbonate processing hubs to Southeast Asian paper mills shape total delivered cost structures for ground filler grades. Supply concentrates in China, India, and Brazil as regional paper capacity expansion absorbs incremental pigment volumes. Production draws from marble quarrying in Europe, sedimentary kaolin deposits in Georgia, and synthetic TiO2 feedstock processing. Single-source vulnerability concentrates in chloride-route titanium dioxide capacity located in China. Distribution runs through liquid slurry pipelines at integrated European mill sites and dry powder bulk shipments to non-integrated converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on calcium carbonate's displacement of titanium dioxide in cost-sensitive segments, coupled with premium-tier positioning for inkjet receptive coatings requiring controlled particle size distributions.
For Market Incumbents: Lock in slurry infrastructure partnerships at mid-scale European facilities before dry-to-liquid conversion investments accelerate. Secure captive marble supply through quarry lease extensions in the Ruhr Valley and Bavaria to defend against emerging ground calcium carbonate exporters from Asia. Backward integration into carbonation reactor technology protects against skilled process engineer scarcity in emerging production regions. For New Entrants and Emerging Players: Begin with precipitated calcium carbonate supply to India's Gujarat and Maharashtra paper investment clusters, where Bureau of Indian Standards food-contact specifications create compliance barriers for unqualified importers. Target barrier coating formulations for fast-food packaging as the most penetrable application, leveraging extended producer responsibility framework momentum in Brazil and the Netherlands. Pursue toll-manufacturing arrangements with existing carbonation facilities to bypass capital-intensive reactor construction. For Investors and Strategic Acquirers: Specialty chemical conglomerates with pigment divisions are the most active acquirers in this space, seeking controlled particle size distribution capabilities for digital printing applications. Long-term viability hinges on EU Green Deal packaging mandate compliance and biomass calcination technology maturation. Acquisition target archetype: precipitated calcium carbonate engineers with inkjet receptive coating certifications and liquid slurry distribution infrastructure. Watch for ANVISA food-contact migration testing timeline accelerations in Brazil as inflection indicators for barrier coating formulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Marble Supply | Imerys and European quarry operators secure premium brightness zones against depletion risks. |
| Liquid Slurry Distribution Expansion | German specialty mills eliminate pneumatic handling infrastructure and reduce dust compliance costs. |
| Biomass Calcination Technology Pilot | Scandinavian producers test wood-pellet carbonation to decouple from natural gas price cycles. |
| Food-Contact Compliance Certification Investment | Barrier coating suppliers accelerate FDA and EFSA approval timelines for fatty food simulant testing. |
| Inkjet Receptive Coating Particle Engineering | Minerals Technologies Inc. anchors specifications for high-speed production inkjet press compatibility. |
Research Methodology
Direct dialogue with plant managers at integrated paper mills, procurement leads at folding carton converters, technical R&D directors at coating formulation houses, and distribution channel partners for mineral fillers grounded qualitative findings. Secondary validation drew from EPA effluent guideline filings, REACH registration databases, Chinese MEE emissions disclosures, and trade flow records from calcium carbonate and titanium dioxide customs categories. Bottom-up and top-down triangulation reconciled facility-level capacity assessments with regional demand aggregation.
Bottom-up modeling built from individual paper machine coating specifications, mineral loading rates by grade, and slurry versus dry powder procurement ratios. Segmentation dimensions included pigment chemistry, application layer, end-use vertical, and physical delivery form. CAGRs derived from regression analysis of historical capacity utilization against paper production forecasts, with inkjet press installation rates and EU packaging sustainability directive implementation timelines as key demand drivers.
Several conditions sit outside the modeled scope, including abrupt natural gas price spikes affecting precipitated calcium carbonate economics, geopolitical disruptions to chloride-route titanium dioxide feedstock flows, and unanticipated nanoparticle migration testing requirement changes by FDA or EFSA. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Specialty Paper Market
Paper Products
Greaseproof Paper Sheets Market
Paper Products
Unbleached Softwood Kraft Pulp Market
Paper Products
North America Thermal Paper Market
Paper Products
Wood-Based Sheet Materials Market
Paper Products
Pharma Grade Paper Market
Paper Products
Europe Tissue and Hygiene Paper Market
Paper Products
Thermal Paper Market
Paper Products
Paper Machinery Market
Paper Products
Glassine Paper Market
Paper Products
Paper Doilies Market
Paper Products
Printing and Writing Papers Market
Paper Products
Aramid Paper Market
Paper Products
Uncoated Fine Paper Market
Paper Products
Overlay Paper Market
Paper Products
Compressed Fiberboard Market