
 Bleached Hardwood Kraft Pulp Market | 2026-2036
Bleached Hardwood Kraft Pulp Market Size, Share, and Industry Trends Forecast 2026-2036
Bleached Hardwood Kraft Pulp Market Outlook
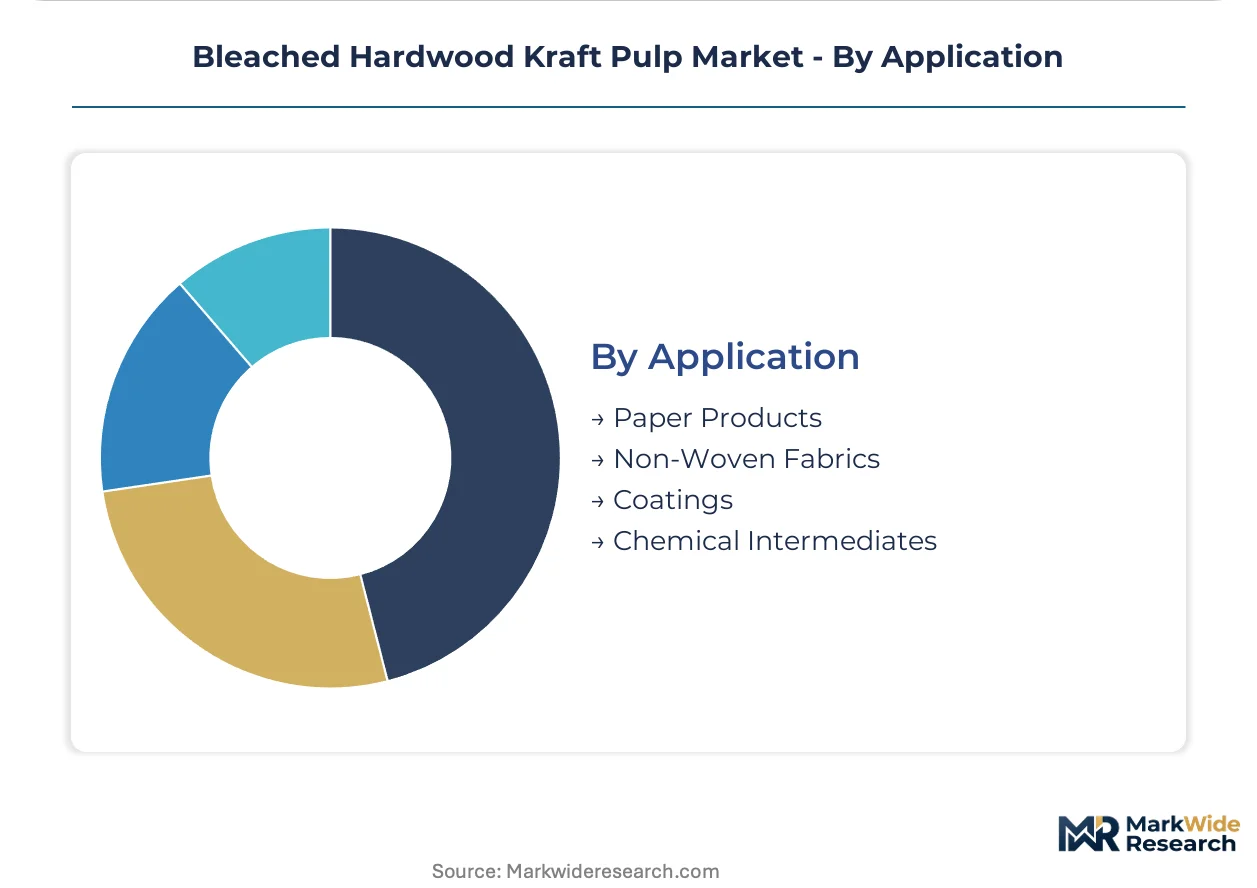
Tissue and hygiene product makers are redrawing procurement priorities for bleached hardwood kraft pulp, pulling volume away from traditional printing and writing paper mills. Suzano S.A. anchors South American supply through its integrated eucalyptus plantation network. Metsä Group differentiates via advanced bioproduct mill concepts that extract maximum value from wood feedstock. International Paper sustains North American market presence through scale advantages in chemical pulp processing.
Bleached hardwood kraft pulp consists of cellulose fibers extracted from deciduous hardwoods—predominantly eucalyptus, birch, and acacia—through the sulfate cooking process followed by multi-stage bleaching to achieve brightness levels exceeding 88% ISO; this pulp delivers superior formation, smoothness, and printability for premium paper grades and absorbent products. Specialty pulp commands margin premiums in pharmaceutical and food-contact applications where purity certifications exceed standard market pulp specifications. Dissolving pulp represents the fastest-expanding category as viscose staple fiber producers in Asia source chemically reactive cellulose for textile manufacturing.
REACH chemical registration requirements in Europe, EPA effluent limitation guidelines in the United States, and Brazil's environmental licensing framework through IBAMA collectively elevate compliance costs while favoring producers with certified sustainable forestry chains of custody. Stakeholders must monitor evolving carbon border adjustment mechanisms that threaten to reprice pulp trade flows between plantation-based and temperate-zone supply bases.
Market Dynamics
EU Deforestation Regulation traceability mandates are forcing bleached hardwood kraft pulp buyers to requalify their entire supplier base, compressing procurement timelines and favoring plantation operators with certified chain-of-custody documentation.
Growth Catalysts
- EU Green Deal compliance:Mandatory sustainability certification under EUDR is redirecting volume toward FSC- and PEFC-certified eucalyptus plantations in Brazil and Uruguay.
- Dissolving pulp demand:Viscose staple fiber producers in Indonesia and India are expanding offtake of chemically reactive cellulose for textile feedstock.
- Specialty packaging converters:Food-contact and pharmaceutical-grade pulp specifications are commanding margin premiums above standard market pulp benchmarks.
Market Restraints
- Input cost volatility:Natural gas and chemical prices for bleaching sequences create margin pressure at sulfate pulp mills.
- Supply concentration risk:Brazilian eucalyptus plantation networks control disproportionate shares of short-fiber hardwood pulp export capacity.
- Substitution threat:Mechanical pulp and recycled fiber technologies are capturing volume in lower-brightness packaging applications.
Strategic Opportunities
- Underpenetrated geography:Southeast Asian tissue producers in Vietnam and Thailand are expanding bleached hardwood kraft pulp intake for premium hygiene products.
- Regulatory tailwind:Carbon border adjustment mechanisms under EU CBAM may reprice trade flows toward plantation-based supply bases with lower embedded emissions.
- Technology convergence:Bioproduct mill concepts integrating pulp production with lignin extraction and bioenergy are capturing additional value per cubic meter of wood input.
Industry Challenges
- Certification timeline compression:EUDR due diligence system implementation requires satellite-based geolocation verification for every supply chain node.
- Capex intensity:Oxygen delignification and elemental chlorine-free bleaching upgrades demand substantial capital at legacy kraft mills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bleached Hardwood Kraft Pulp Market |
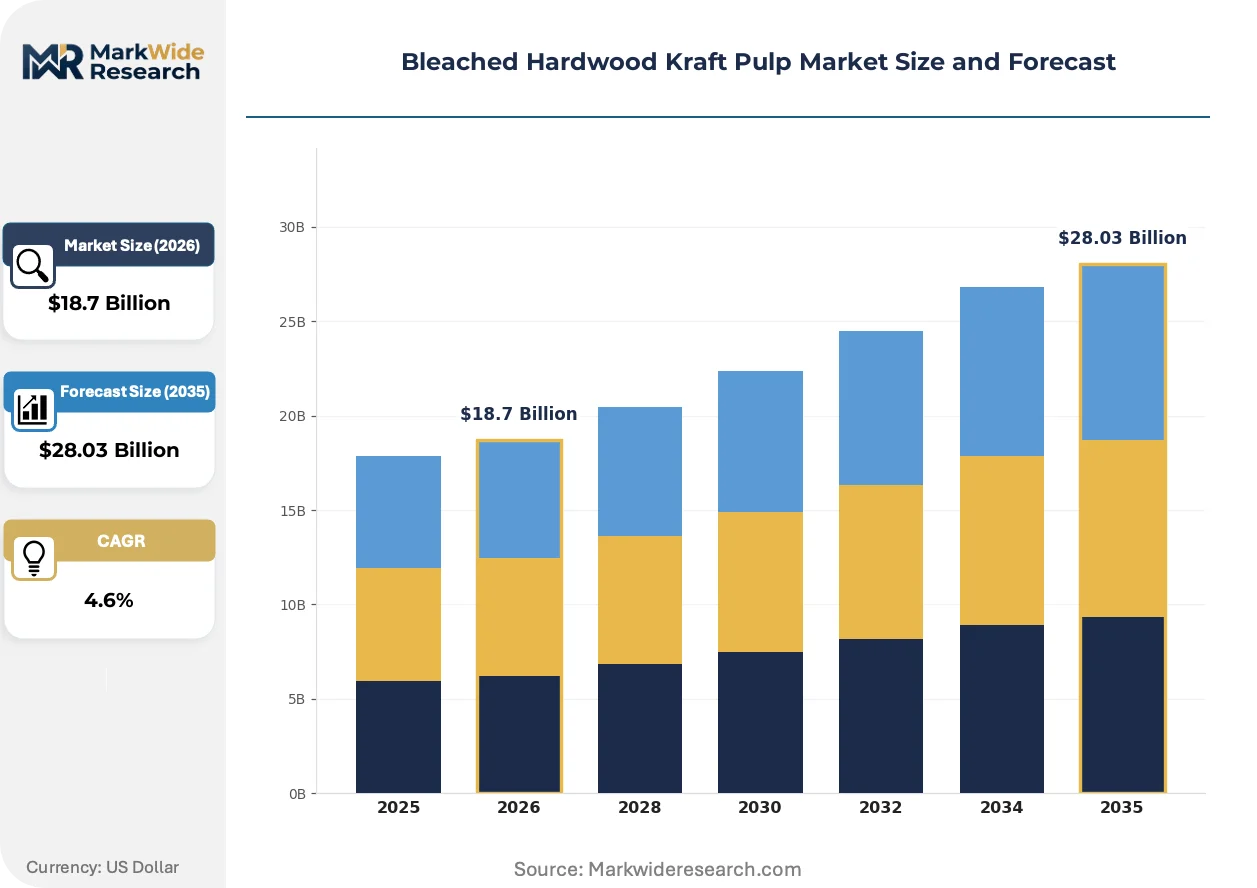
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Market Pulp, Specialty Pulp, Bleached Pulp, Dissolving Pulp End User: Packaging Industry, Paper Industry, Textile Industry, Chemical Industry Distribution Channel: Direct Sales, Distributors, Online Sales, Retail Application: Paper Products, Non-Woven Fabrics, Coatings, Chemical Intermediates |
| Companies Covered | Suzano S.A., International Paper, UPM-Kymmene Corporation, Stora Enso, Sappi, Domtar Inc., CMPC, Klabin, Metsä Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bleached Hardwood Kraft Pulp Market Strategic Shifts
Mechanical pulping and advanced fiber recycling technologies are actively reshaping competitive dynamics in lower-specification segments, while dissolving pulp chemistry innovations unlock textile-grade value streams from traditional paper pulp assets.
Enzymatic pre-treatment of hardwood chips is decomposing lignin-carbohydrate complexes prior to conventional sulfate cooking, enabling mills to reduce chemical load and improve yield. Specialty dissolving pulp producers in Brazil and South Africa are adopting these sequences at commercial scale. This technology is decomposing the traditional boundary between paper-grade and textile-grade pulp production, allowing swing capacity between product categories.
REACH chemical registration requirements through ECHA are tightening disclosure obligations for pulp mill effluent constituents and bleaching chemical residuals. Mills serving European buyers must now document full substance inventories through SCIP database entries. Dissolving pulp shipments into EU textile supply chains face the most intensive compliance scrutiny, with producers investing in third-party verification protocols.
Buyer concentration among Asian tissue and hygiene conglomerates is consolidating procurement leverage and compressing contract renewal cycles. Long-term offtake agreements are shortening from five-year to two-year terms, with price renegotiation clauses triggered by pulp index movements. This pattern is most visible in Indonesian and Chinese tissue manufacturing clusters, where integrated producers are building direct sourcing relationships with Brazilian plantation operators.
Bleached Hardwood Kraft Pulp Market Segmentation
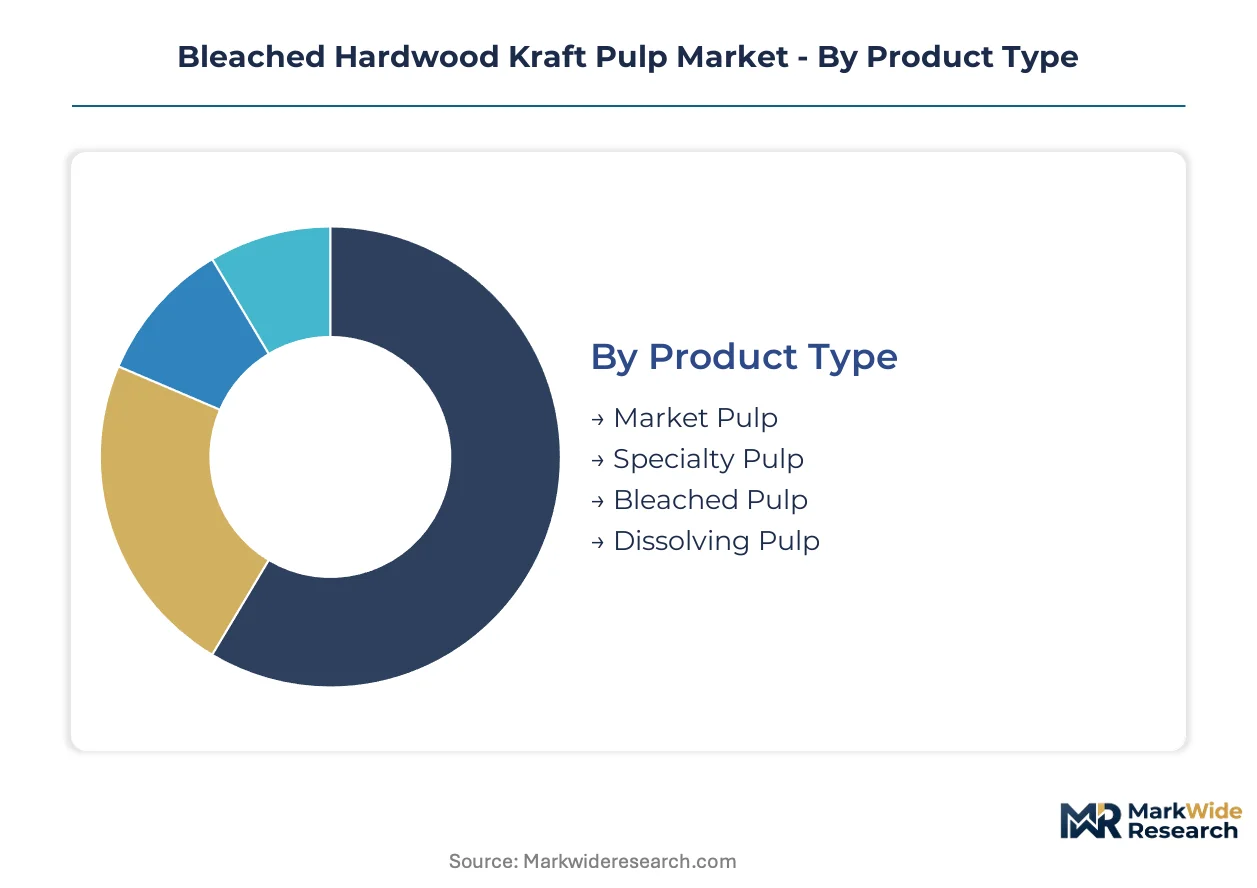
Segmentation in bleached hardwood kraft pulp reveals how margin pools shift between commodity grades and certified specialty tiers. Buyers now sort suppliers by chain-of-custody documentation rather than brightness specifications alone.
Product Type:
Margin pools concentrate in certified specialty grades where pharmaceutical and food-contact purity commands premiums above commodity benchmarks.
- Market Pulp:Standard-grade bleached hardwood kraft pulp traded on spot and contract indices, typically 88-92% ISO brightness. Tissue and hygiene manufacturers in Indonesia and Vietnam pull volume through shorter-term contracts with price renegotiation clauses tied to pulp index movements.
- Specialty Pulp:Ultra-pure grades exceeding standard brightness and cleanliness specifications for pharmaceutical excipients and food-contact applications. REACH registration requirements through ECHA intensify compliance costs, favoring producers with third-party verification protocols and documented substance inventories.
- Bleached Pulp:Conventional sulfate-process hardwood pulp meeting standard brightness thresholds for printing and writing papers.
- Dissolving Pulp:Chemically reactive cellulose for viscose staple fiber production, requiring controlled reactivity indices.
The dominant share belongs to Market Pulp, while Dissolving Pulp is closing the gap fastest.
End User:
Application requirements diverge sharply between absorbent products demanding short-fiber formation and chemical processes needing reactive cellulose feedstock.
- Packaging Industry:Food-contact and pharmaceutical-grade specifications drive specialty pulp uptake. EU Deforestation Regulation traceability mandates compress procurement timelines, redirecting volume toward FSC- and PEFC-certified plantation sources in Brazil and Uruguay.
- Paper Industry:Traditional printing and writing paper mills face volume displacement as tissue and hygiene producers expand offtake. Mills serving European buyers must document full effluent constituent inventories through ECHA's SCIP database.
- Textile Industry:Viscose staple fiber producers in India and Indonesia source dissolving pulp for textile manufacturing.
- Chemical Industry:Cellulose derivatives and ether production require controlled purity grades.
Packaging Industry holds the largest procurement volume, though Textile Industry purchasing is expanding most quickly.
Distribution Channel:
Channel economics favor direct relationships for volume buyers while distributors serve fragmented regional demand.
- Direct Sales:Long-term offtake agreements between plantation operators and integrated tissue manufacturers. Contract terms have compressed from five-year to two-year durations with index-linked price adjustments.
- Distributors:Regional stockholding intermediaries serving smaller paper mills and converters with fragmented order patterns and mixed-grade requirements.
- Online Sales:Digital procurement platforms for spot market transactions and standardized grade purchases.
- Retail:Small-volume sales to specialty converters and research institutions.
Direct Sales commands the highest volume flow, with Distributors capturing share among mid-tier converters.
Application:
End-use specifications range from formation-critical absorbent products to chemically reactive industrial feedstocks.
- Paper Products:Premium tissue and hygiene items requiring superior formation and softness from short-fiber eucalyptus pulp. Southeast Asian producers in Thailand and Vietnam are expanding intake for premium product lines.
- Non-Woven Fabrics:Medical wipes and personal care substrates demanding controlled fiber length distribution and absorbency profiles.
- Coatings:Microcrystalline cellulose and filler applications in paint and adhesive formulations.
- Chemical Intermediates:Cellulose ethers and derivatives for pharmaceutical and industrial use.
Paper Products maintains the leading application share, while Non-Woven Fabrics shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos container terminals anchor South American pulp export capacity, handling over 70% of Brazilian bleached hardwood kraft pulp shipments bound for Asian tissue manufacturers. This infrastructure underwrites Brazil's dominance in short-fiber hardwood supply chains.
Brazil
São Paulo state eucalyptus plantations supply premium short-fiber pulp to Indonesian and Vietnamese tissue converters. IBAMA environmental licensing frameworks mandate satellite-based geolocation verification for all export-bound fiber. The Triângulo Mineiro cluster in Minas Gerais state hosts integrated bioproduct mills extracting lignin alongside pulp production.
United States
Southeastern tissue and hygiene manufacturers in Georgia and Alabama expand hardwood pulp intake for premium absorbent products. EPA effluent limitation guidelines elevate compliance costs at legacy kraft mills in the region. The Pacific Northwest chemical pulp corridor around Longview, Washington sustains scale advantages in hardwood processing.
Finland
Nordic birch pulp producers serve European pharmaceutical and food-contact specialty grades demanding ultra-pure specifications. REACH chemical registration through ECHA tightens disclosure obligations for bleaching chemical residuals. The Äänekoski bioproduct mill complex anchors advanced fiber extraction technologies maximizing value per cubic meter.
China
Yangtze River Delta viscose staple fiber producers source dissolving pulp for textile manufacturing expansion. Dual carbon goals under MEE oversight pressure mills to document embedded emissions for EU-bound shipments. The Nantong port cluster handles rising hardwood pulp imports for regional non-woven fabric converters.
Indonesia
Java-based tissue conglomerates consolidate procurement leverage through direct sourcing relationships with Brazilian plantation operators. National regulations on sustainable forestry certification align with EUDR traceability requirements for European market access. The Surabaya manufacturing corridor expands bleached hardwood kraft pulp intake for premium hygiene product lines.
Bleached Hardwood Kraft Pulp Market Competitive Environment
Concentration sits with integrated plantation-to-mill operators controlling fiber supply chains from seedling to export terminal. Three structural tiers define competitive positioning: South American eucalyptus plantation networks, Nordic birch-focused bioproduct mill specialists, and North American scale-driven chemical pulp processors. Capacity expansion and backward integration into certified forestry assets represent the dominant competitive moves reshaping supply security.
Among plantation-integrated operators, Suzano S.A. and Klabin exemplify the South American archetype with captive eucalyptus fiber supply. Metsä Group anchors the Nordic specialist tier through advanced bioproduct mill concepts extracting maximum wood value. International Paper occupies the North American scale position with chemical pulp processing advantages serving domestic tissue and packaging converters.
| Leading Market Players |
|---|
| Suzano S.A. |
| International Paper |
| UPM-Kymmene Corporation |
| Stora Enso |
| Sappi |
| Domtar Inc. |
| CMPC |
| Klabin |
| Metsä Group |
| Others |
Value Chain & Pricing Dynamics
EU Deforestation Regulation traceability mandates gate both supplier qualification and price differentiation, compressing procurement timelines while widening spreads between certified and uncertified pulp grades. Buyers now pay premiums for FSC- and PEFC-documented eucalyptus fiber that satisfies EUDR due diligence requirements.
Pricing Analysis
Volume-discount tiering structures dominate contract negotiations, with three-tier pricing separating specialty pharmaceutical-grade pulp from standard tissue grades and commodity printing stock. Price differentiation rests on certification level and volume scale, where Indonesian tissue conglomerates leverage consolidated procurement to extract index-linked adjustments. Cost compression in standard market pulp is intensifying because natural gas and chemical input volatility erodes sulfate mill margins. Small regional converters show highest price sensitivity, while integrated hygiene manufacturers absorb premiums for supply security.
Supply Chain Analysis
Strategic stockpile preferences prevail among Asian tissue manufacturers buffering against Brazilian port congestion, while European buyers favor just-in-time flows enabled by Nordic birch proximity. Geographic supply concentrates in Brazil, Finland, and Uruguay, where plantation networks and bioproduct mill concepts anchor export capacity. Raw material dependencies draw from eucalyptus seedlings, sulfate cooking chemicals, and chlorine dioxide for bleaching sequences. Single-source vulnerability runs through Santos port terminals handling over two-thirds of Brazilian exports. Distribution runs through direct long-term offtake agreements for volume buyers and regional distributors serving fragmented converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Indonesian and Chinese tissue conglomerates, consolidating procurement leverage and compressing contract renewal cycles from five-year to two-year terms.
For Market Incumbents: Compound scale advantages in certified plantation networks by accelerating backward integration into seedling genetics and satellite-verified geolocation systems. Defend margin position against mechanical pulp substitution by expanding dissolving pulp swing capacity at existing kraft assets. Prioritize IBAMA licensing compliance as a barrier to uncertified competitors. For New Entrants and Emerging Players: FSC certification fast-tracks market entry by satisfying EUDR traceability requirements that incumbent suppliers struggle to document retroactively. Target Southeast Asian tissue producers in Vietnam and Thailand where premium hygiene product expansion outpaces established supplier relationships. Lead with enzymatic pre-treatment technology as a yield-enhancement differentiator against legacy sulfate cooking. For Investors and Strategic Acquirers: EU CBAM implementation reshapes the acquisition landscape by repricing trade flows toward plantation-based supply bases with lower embedded emissions. Long-term viability favors integrated operators controlling fiber from seedling to export terminal. Watch carbon border adjustment mechanism enforcement thresholds as the signal for portfolio reallocation toward Brazilian and Uruguayan assets.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Plantation Expansion | FSC- and PEFC-verified eucalyptus acreage satisfies EUDR due diligence requirements for European market access. |
| Dissolving Pulp Swing Capacity | Enzymatic pre-treatment enables mills to shift between paper-grade and textile-grade cellulose production. |
| Bioproduct Mill Integration | Lignin extraction and bioenergy co-generation capture additional value per cubic meter of wood input at Nordic complexes. |
| Direct Sourcing Relationships | Long-term offtake agreements between Brazilian plantation operators and Asian tissue manufacturers bypass distributor markups. |
| Satellite Geolocation Verification | IBAMA-mandated supply chain documentation satisfies EUDR traceability requirements for export-bound fiber shipments. |
Study Parameters
Operator-level perspectives from pulp mill technical directors, tissue manufacturer procurement leads, specialty packaging converter supply chain managers, and IBAMA licensing officers anchored the qualitative base. Primary fieldwork combined with secondary validation from customs trade data, FSC and PEFC certification registries, SEC filings of listed pulp producers, and EUDR implementation guidance documents. Bottom-up volume estimates triangulated against top-down capacity assessments across the analysis window.
Sensitivity analysis tested forecast robustness against variable input cost scenarios and regulatory implementation timelines. The modeling framework segmented by product type, end-use industry, distribution channel, and application requirements, with additional dimensioning by certification tier and regional regulatory cluster. CAGRs derived from production capacity expansion schedules, demand elasticity estimates for tissue and viscose fiber end-uses, and trade flow reconfiguration assumptions under carbon border adjustment mechanisms.
The analysis sits within stated boundaries; outcomes outside sustained EUDR enforcement, stable Brazilian environmental licensing frameworks, or continued viscose fiber demand expansion would require recalibration. Forecasts reflect documented assumptions about plantation yield improvements and bleaching chemical cost trajectories. Revision becomes warranted when EU CBAM carbon intensity thresholds cross implementation thresholds or when dissolving pulp substitution by recycled textile fiber technologies accelerates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Europe and MENA Pulp Market
Paper Products
Paper Dry Strength Agents Market
Paper Products
Acrylic Paper Market
Paper Products
Global Security Paper Market
Paper Products
Dissolving Pulp Market
Paper Products
Graphic Paper Market
Paper Products
Global Thin Papers Market
Paper Products
Glassine Paper Market
Paper Products
Global Pulp and Paper Machinery Market
Paper Products
Latex-Saturated Paper Market
Paper Products
Semi Chemical Wood Pulp Market
Paper Products
GCC Stone Paper Market
Paper Products
Billing Paper Market
Paper Products
Heat Transfer Paper Market
Paper Products
Inlay Paper Market
Paper Products
Africa Tissue Paper Market