
 Pp Synthetic Paper Market | 2026-2036
Pp Synthetic Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Pp Synthetic Paper Market Analysis
Asset-light manufacturing partnerships and third-party extrusion leasing is reconfiguring competitive entry barriers for mid-scale converters. Yupo Corporation leverages its biaxial orientation expertise to sustain premium positioning in high-durability applications. American Profol anchors North American supply through integrated cast film production, while Cosmo Films competes aggressively in Asian labelstock markets via specialized coating capabilities.
PP synthetic paper consists of extruded or biaxially oriented polypropylene film engineered to mimic cellulose paper properties, typically manufactured in thicknesses from 100 microns to 400 microns with voided or filled structures to achieve print receptivity and ink adhesion comparable to conventional substrates. Its primary purpose serves moisture-resistant, tear-proof applications across labeling, packaging, and commercial graphics where pulp-based paper degrades. The opaque and coated product type segments command the dominant margin pools due to higher barrier specifications and surface treatment requirements in premium labeling. Digital printing technology represents the fastest-growing compatibility requirement, driven by short-run customization and variable-data label production in food and logistics end uses.
FDA food-contact regulations govern polypropylene substrate migration limits in U.S. label and packaging applications, while REACH restrictions on chemical additives constrain European formulation choices for coated grades. China's GB standards and SAMR oversight enforce domestic labeling material consistency for consumer goods traceability. Stakeholders must monitor evolving extended producer responsibility frameworks and substrate recyclability certifications, as these will determine qualified supplier status in regulated procurement channels without warning.
Market Dynamics
Digital printing adoption is compressing converter economics and forcing substrate suppliers to develop lower minimum-order-quantity grades compatible with inkjet and toner systems.
Growth Catalysts
- REACH chemical restrictions:European formulation mandates for reduced additive migration are pushing converters toward pre-certified coated substrates that simplify compliance documentation.
- E-commerce logistics labeling:Moisture-resistant shipping labels for cross-border parcel networks are displacing pulp-based alternatives in sorting facilities across humid climates.
- Biaxial orientation voiding:Advanced extrusion techniques that create micro-voided structures are improving print receptivity without additional surface coating costs.
Market Restraints
- Propylene feedstock volatility:Crude oil and natural gas price swings directly compress margin pools for non-integrated film extruders.
- Asian supply concentration:Biaxial orientation capacity clusters in China and South Korea create single-source risk for premium grades.
- Cellulose paper cost floor:Mechanical pulp from Nordic and Brazilian mills retains a 40-60% cost advantage for non-durability applications.
Strategic Opportunities
- India FSSAI traceability mandates:Serialized labeling requirements for packaged foods are expanding addressable demand for tear-proof synthetic substrates.
- UV-LED ink convergence:Instant-curing digital inks paired with synthetic papers are enabling same-day label production for craft beverage microbreweries.
- Direct-to-brand e-commerce channels:Platform-native label suppliers on Alibaba and Amazon Business are bypassing traditional distributor markups.
Industry Challenges
- Color management expertise gap:Fewer pre-press technicians understand synthetic paper ink adhesion profiles versus cellulose calibration curves.
- Extended producer responsibility compliance:Divergent state-level packaging fees in California, Maine, and Oregon fragment national label procurement specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pp Synthetic Paper Market |
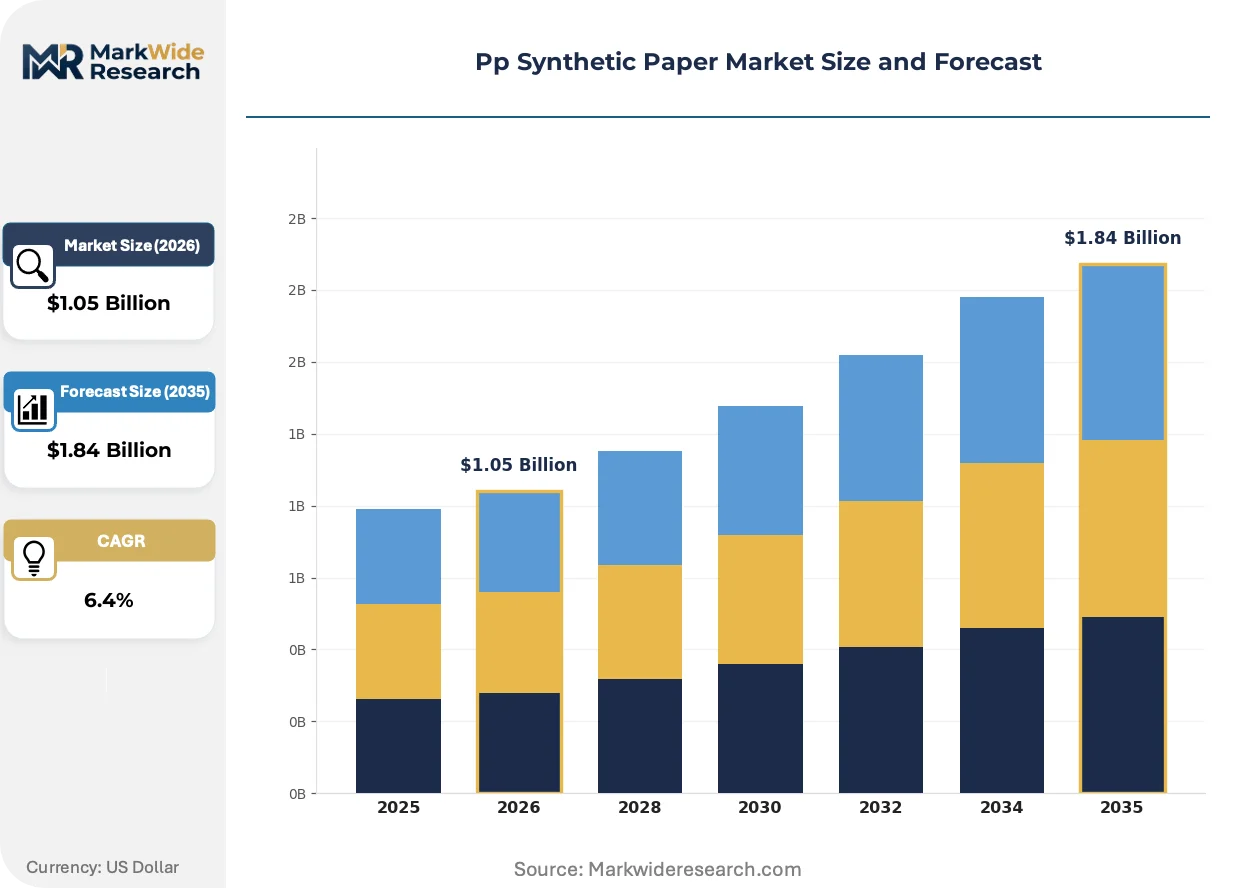
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Opaque, Transparent, Synthetic, Coated End Use: Labels, Packaging, Banners, Stationery Thickness: 100 microns, 200 microns, 300 microns, 400 microns Printing Technology: Offset, Flexographic, Digital, Screen |
| Companies Covered | Yupo Corporation, PPG Industries, DuPont, Cosmo Films, American Profol, Nan Ya Plastics Corporation, Agfa-Gevaert, Formosa Plastics Group, Seiko Epson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pp Synthetic Paper Market Emerging Trajectories
Substrate engineering is converging with digital workflow automation, compressing the traditional separation between material specification and print production planning.
Water-based barrier coatings are hybridizing with traditional solvent-based systems to meet FDA food-contact migration limits while maintaining heat-seal performance. Food processors in the refrigerated ready-meal segment are specifying these hybrid grades for direct-contact labels. The technology is hybridizing converter capital allocation, forcing simultaneous investment in aqueous and solvent coating lines.
China's GB standards for consumer goods traceability are mandating machine-readable codes on all packaged food labels. This regulatory pressure is accelerating demand for synthetic papers with guaranteed dimensional stability across humidity swings. Domestic brands are responding by pre-qualifying suppliers against SAMR audit protocols before tender participation.
Brand procurement teams are consolidating label specifications across multiple SKUs to reduce substrate variety. This behavioral compression is favoring converters with digital print capabilities that absorb short-run complexity without material changeovers. The shift is most visible in European personal care, where Unilever and L'Oréal have reduced approved substrate SKUs by half.
Pp Synthetic Paper Market Segmentation
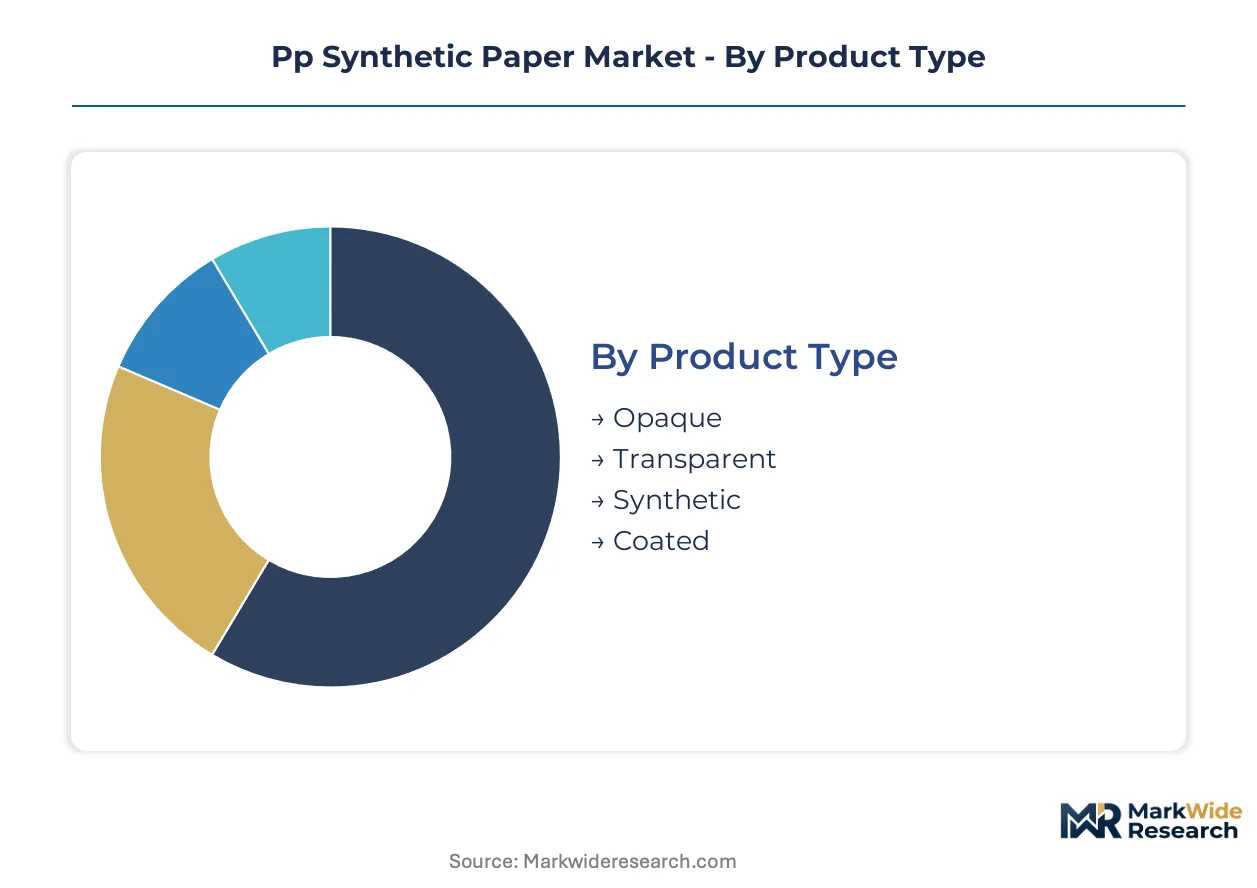
PP synthetic paper segmentation reveals divergent margin structures across substrate engineering tiers. Thickness and coating specifications determine converter equipment compatibility, while printing technology alignment dictates minimum order economics for label producers.
Product Type:
Opaque grades turn inventory fastest in food logistics applications, whereas transparent variants cycle slower due to narrower converter qualification requirements. Coated substrates command extended production lead times for surface treatment curing.
- Opaque:Voided polypropylene structures achieve print density comparable to mechanical pulp without fiber absorbency. Food and beverage brands in humid climates specify these grades for moisture-resistant shipping labels that survive condensation exposure.
- Coated:Surface-treated films receive aqueous or solvent-based primer layers to optimize ink adhesion for UV-LED and toner systems. Premium personal care labeling in Europe drives specification, where REACH-compliant additive packages simplify converter compliance documentation.
- Transparent:Non-voided biaxially oriented films with clarity grades for windowed packaging and see-through label applications.
- Synthetic:Base extruded grades without specialized surface engineering, serving cost-sensitive commercial graphics.
Opaque substrates anchor the volume base while coated grades gain share at the steepest rate.
End Use:
Application segmentation separates high-frequency replenishment categories from project-based procurement cycles. Labels and packaging operate on monthly restocking rhythms, whereas banners and stationery follow seasonal or campaign-driven purchasing.
- Labels:Pressure-sensitive and glue-applied formats dominate synthetic paper consumption. E-commerce logistics networks in China specify tear-proof, moisture-resistant shipping labels that withstand automated sorting equipment stress.
- Packaging:Flexible pouch windows, wraparound sleeves, and direct-contact food labels utilize heat-sealable coated grades. Refrigerated ready-meal processors specify hybrid water-solvent barrier coatings to meet FDA migration limits.
- Banners:Large-format outdoor and retail display applications requiring UV stability and tear resistance for extended exposure.
- Stationery:Durable tags, menus, and identification cards for hospitality and institutional environments.
Labels generate the highest shipment frequency while packaging applications show the steepest specification upgrading trajectory.
Thickness:
Calendering and extrusion throughput economics favor standardized gauge production, though specialty thicknesses command premium positioning in performance-critical applications.
- 200 microns:Mid-range voided structures balance stiffness and conformability for pressure-sensitive labelstock. This gauge dominates European personal care and pharmaceutical labeling where automated applicator compatibility is mandatory.
- 300 microns:Heavy-duty grades for rigid container labels and standalone card applications. Craft beverage microbreweries in North America specify this thickness for premium bottle labels requiring tactile rigidity.
- 100 microns:Ultra-lightweight grades for high-volume logistics labels minimizing material cost per thousand units.
- 400 microns:Maximum stiffness for banner substrates and structural packaging inserts requiring board-like performance.
200-micron specifications anchor converter volume commitments while 300-micron grades climb fastest in premium positioning segments.
Printing Technology:
Substrate-ink system compatibility determines converter capital allocation and inventory stratification. Digital workflows compress job turnaround times, while conventional methods retain cost advantages in long-run production.
- Digital:Inkjet and electrophotographic systems demand synthetic papers with controlled surface energy and toner fusing compatibility. Short-run customization for variable-data food traceability codes in India expands addressable demand under FSSAI serialization mandates.
- Flexographic:Water-based and UV-curable ink systems on rotary presses serve high-volume label production. This technology retains cost leadership in beverage and logistics applications with stable artwork requirements.
- Offset:Sheet-fed lithographic printing for commercial graphics and premium packaging with exacting color reproduction standards.
- Screen:Heavy ink deposit applications for outdoor durability and specialty industrial labeling.
Flexographic alignment anchors current installed base capacity while digital compatibility expands most quickly in converter qualification priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Label converters and brand procurement teams concentrate purchasing power in manufacturing corridors with strong logistics infrastructure and regulatory harmonization. Demand clusters track e-commerce fulfillment networks, food processing zones, and personal care manufacturing bases.
China
E-commerce logistics operators in the Yangtze River Delta and Pearl River Delta consume moisture-resistant shipping labels at scale for automated sorting facilities. SAMR enforces GB standards for consumer goods traceability that mandate machine-readable codes on all packaged food labels. Yupo Corporation maintains extrusion capacity in Zhejiang province serving domestic brand owners pre-qualifying suppliers against audit protocols.
United States
Craft beverage microbreweries in Colorado and California specify 300-micron premium bottle labels requiring tactile rigidity and UV-LED ink compatibility. FDA food-contact regulations govern polypropylene substrate migration limits in label and packaging applications. American Profol anchors North American supply through integrated cast film production in North Carolina.
Germany
Personal care manufacturers in North Rhine-Westphalia have reduced approved substrate SKUs by half, consolidating specifications across multiple product lines. REACH restrictions on chemical additives constrain European formulation choices for coated grades. Industrial clusters around Düsseldorf and Cologne host converters developing hybrid water-solvent barrier coatings for refrigerated ready-meal processors.
India
Food processors in Maharashtra and Gujarat face FSSAI serialization mandates expanding addressable demand for tear-proof synthetic substrates with guaranteed dimensional stability. Serialized labeling requirements for packaged foods are accelerating converter qualification of digital-compatible grades. Labelstock distributors in Mumbai and Ahmedabad stock 200-micron voided structures for pressure-sensitive pharmaceutical applications.
Japan
Precision electronics manufacturers in Kanto specify synthetic papers for durable identification tags surviving humidity exposure in cleanroom environments. METI guidance on packaging material recyclability influences procurement specifications for extended producer responsibility compliance. Yupo Corporation leverages biaxial orientation expertise from its Kagoshima facilities to sustain premium positioning in high-durability applications.
Pp Synthetic Paper Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where scale advantages clash with coating specialization. The market fragments between integrated film extruders owning resin-to-reel capacity and independent converters leasing third-party extrusion lines. Three archetypes dominate: biaxial orientation specialists, cast film integrators, and coating-technology licensors. Capacity expansion and strategic partnerships constitute the primary competitive moves, with asset-light manufacturing partnerships reconfiguring entry barriers for mid-scale converters.
Within the biaxial orientation tier, Yupo Corporation and Cosmo Films exemplify divergent geographic anchoring strategies. Yupo occupies a position as the archetypal Japanese specialist leveraging voiding expertise for premium durability applications. Cosmo Films represents the Asian coating-technology model competing aggressively in labelstock markets through specialized surface treatment capabilities. American Profol anchors the North American integrated cast film archetype, demonstrating how captive resin supply chains defend margin pools against propylene feedstock volatility.
| Leading Market Players |
|---|
| Yupo Corporation |
| PPG Industries |
| DuPont |
| Cosmo Films |
| American Profol |
| Nan Ya Plastics Corporation |
| Agfa-Gevaert |
| Formosa Plastics Group |
| Seiko Epson Corporation |
| Others |
Supply Flow & Price Mechanics
Zhejiang province's biaxial orientation capacity clusters anchor global premium-grade supply, concentrating pricing power among integrated extruders while forcing non-integrated converters to absorb propylene feedstock volatility through indexed contract structures. This geographic concentration shapes downstream procurement economics, with moisture-resistant label specifications commanding premium positioning against standard commercial graphics grades.
Pricing Analysis
Cost-plus contracts indexed to propylene monomer benchmarks dominate converter procurement, with pricing stratifying across premium, standard, and economy tiers based on coating complexity and FDA food-contact certification status. Price differentiation hinges on REACH-compliant additive packages and digital print compatibility, with certified coated substrates resisting downward pressure while base extruded grades face compression from Asian supply overhang. Brand procurement teams in European personal care demonstrate lowest price sensitivity due to compliance documentation requirements, whereas logistics operators in humid climates prioritize unit economics over performance specifications.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard for converter relationships with Chinese and South Korean biaxial orientation specialists, easing working capital constraints for mid-scale labelstock distributors. Raw material flows draw from Saudi Arabian and American propylene supply, South Korean resin compounding, and German coating chemical specialists. Single-source vulnerability concentrates in voided film extrusion for 200-micron pharmaceutical grades. Distribution runs through regional labelstock converters with digital print capabilities, bypassing traditional distributor markups in direct-to-brand e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as FSSAI serialization mandates and SAMR traceability requirements drive first-time synthetic paper adoption across Asian food processing corridors previously served by cellulose alternatives.
For Market Incumbents: Pre-empt coating-technology commoditization by securing captive aqueous-solvent hybrid barrier capacity in refrigerated ready-meal supply zones. Defend margin pools through backward integration into propylene resin supply or exclusive digital print workflow partnerships that lock converter qualification protocols.
For New Entrants and Emerging Players: Build out asset-light manufacturing partnerships with third-party extrusion lessors to serve Indian pharmaceutical labelstock demand under FSSAI mandates without capital-intensive biaxial orientation investment. Target 200-micron voided structures for pressure-sensitive applications in Maharashtra and Gujarat through distributor relationships with Mumbai-based label converters.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because extended producer responsibility frameworks and substrate recyclability certifications will determine qualified supplier status in regulated procurement channels. Acquisition focus should center on coating-technology licensors with REACH-compliant formulation libraries. The signal to watch is California's packaging fee implementation spreading to additional state-level frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Supply | Captive resin chains defend margin pools against feedstock volatility for North American extruders. |
| Hybrid Coating Line Investment | Simultaneous aqueous and solvent capacity meets FDA migration limits for refrigerated ready-meal processors. |
| Digital Print Workflow Partnership | Converter qualification protocols lock in substrate specification for variable-data food traceability codes. |
| REACH-Compliant Formulation Licensing | Pre-certified additive packages simplify converter compliance documentation in European personal care. |
| Asset-Light Extrusion Leasing | Third-party manufacturing partnerships reconfigure entry barriers for mid-scale converters in Asian markets. |
Methodological Framework
A standing panel of film extrusion plant managers, label converter procurement leads, brand packaging engineers, and coating chemical R&D directors provided ongoing calibration against secondary validation from customs trade data, FDA food-contact submission filings, SAMR audit protocols, and SEC 10-K disclosures from integrated resin producers. Primary interviews with logistics operators in Chinese e-commerce corridors and European personal care procurement teams combined with bottom-up shipment tracking and top-down demand modeling to establish volume baselines.
Scenario-bracketing framed projections across the analysis window, with segmentation modeling spanning product type tiers, end-use applications, thickness specifications, and printing technology compatibility. CAGRs derived from propylene feedstock cost trajectories, converter capital expenditure cycles, and regulatory implementation timelines for traceability mandates. Industry-specific inputs included biaxial orientation capacity utilization rates and digital press installation counts in target geographies.
The forecast holds incumbent behavior within observed patterns; aggressive moves by resin-integrated conglomerates or coating-technology specialists would shift outcomes. Macroeconomic deviation in propylene pricing, regulatory acceleration in extended producer responsibility, or technological disruption in cellulose barrier coatings would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Inkjet Papers and Films Market
Paper Products
Saturated Kraft Paper Market
Paper Products
Thermal Paper Market
Paper Products
Inlay Paper Market
Paper Products
North America Thermal Paper Market
Paper Products
Loose Leaf Paper Market
Paper Products
Sanitary Paper Products Market
Paper Products
Overlay Paper Market
Paper Products
Unbleached Softwood Kraft Pulp Market
Paper Products
Global Pulp and Paper Machinery Market
Paper Products
Greaseproof Paper Sheets Market
Paper Products
Pulp Market
Paper Products
Global Dye Sublimation Paper Market
Paper Products
Ceramic Paper Market
Paper Products
Pharma Grade Paper Market
Paper Products
Recording Chart Paper Market