
 Leatheroid Paper Market | 2026-2036
Leatheroid Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Leatheroid Paper Market Insights
Aftermarket refurbishment of automotive upholstery components is reshaping margin distribution across the Leatheroid Paper value chain. DuPont leverages its aramid fiber expertise to anchor premium protective covering applications. Teijin Aramid sustains Japanese technical leadership through specialized reinforcement grades. Yantai Tayho Advanced Materials dominates regional supply for furniture manufacturing customers in Shandong province.
Leatheroid Paper denotes a dense, resin-impregnated fibrous sheet engineered to simulate leather texture and durability, typically manufactured through wet-laid nonwoven processes with synthetic or natural fiber bases calendered to thicknesses between 0.3 mm and 2.0 mm. The material serves industrial and commercial markets requiring abrasion-resistant surfaces with controlled flexibility and printability. Synthetic Blend products lead volume throughput due to cost-performance ratios in automotive and furniture applications, while Reinforced grades command premium positioning in protective covering segments where tensile strength thresholds exceed 50 N/cm. Coated variants for decorative finishes represent the fastest-growing application cluster as digital printing compatibility expands substrate utility.
China's SAMR enforces GB standards governing formaldehyde emissions and flammability in interior materials, directly constraining formulation choices for Leatheroid Paper destined for automotive and furniture markets. The EPA in the United States regulates volatile organic compound thresholds through TSCA certification requirements that shape export eligibility for Asian manufacturers. ISO 4045 leather testing protocols provide cross-border quality benchmarks that buyers in European REACH jurisdictions increasingly reference in procurement specifications. Stakeholders must monitor evolving chemical restriction lists across multiple jurisdictions to preempt supply chain disruption and secure formulation compliance ahead of enforcement phase-ins.
Market Dynamics
Automotive interior refurbishment cycles are compressing from seven-year to four-year intervals, forcing Leatheroid Paper suppliers to recalibrate inventory and formulation pipelines for faster-turn synthetic upholstery replacement.
Growth Catalysts
- GB 8410 flammability mandates:China's SAMR enforcement of stricter automotive interior standards is disqualifying conventional PVC alternatives and redirecting procurement toward resin-impregnated fiber substrates that pass horizontal burn tests.
- Digital printing compatibility:UV-curable ink adhesion improvements on coated Leatheroid Paper variants are unlocking short-run decorative customization for furniture manufacturers seeking SKU proliferation without tooling costs.
- Yantai-Shenzhen production corridor:Concentrated wet-laid nonwoven capacity in these Shandong and Guangdong hubs is reducing logistics friction for export-oriented automotive tier suppliers.
Market Restraints
- Aramid fiber cost volatility:Reinforced grade margins compress when para-aramid feedstock prices spike, constraining premium positioning for protective covering applications.
- East Asian supply concentration:Over 60% of calendering capacity sits within 300 kilometers of China's eastern seaboard, exposing buyers to single-region weather and energy disruption risks.
- Polyurethane synthetic leather substitution:Cast PU films with embossed grain patterns are capturing mid-tier automotive seating contracts where abrasion resistance thresholds fall below 30,000 Martindale cycles.
Strategic Opportunities
- India furniture manufacturing:BIS certification alignment for formaldehyde emissions remains sparse among domestic Leatheroid Paper producers, creating first-mover advantage for compliant importers.
- Medical equipment protective coverings:Antimicrobial additive integration meets emerging hygiene protocols for hospital mattress and examination table surfaces.
- EU Green Deal material passports:Digital product footprint documentation requirements favor suppliers with established resin sourcing traceability and recycled fiber content verification systems.
Industry Challenges
- Wet-laid process engineering talent:Experienced technicians capable of optimizing fiber dispersion uniformity across 0.3-2.0 mm calendered thicknesses are concentrated at retiring demographics in Japanese and German equipment vendors.
- Multi-jurisdiction certification sequencing:Simultaneous pursuit of EPA TSCA, REACH SVHC screening, and GB standard compliance extends product launch timelines by 8-14 months for formulation modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leatheroid Paper Market |
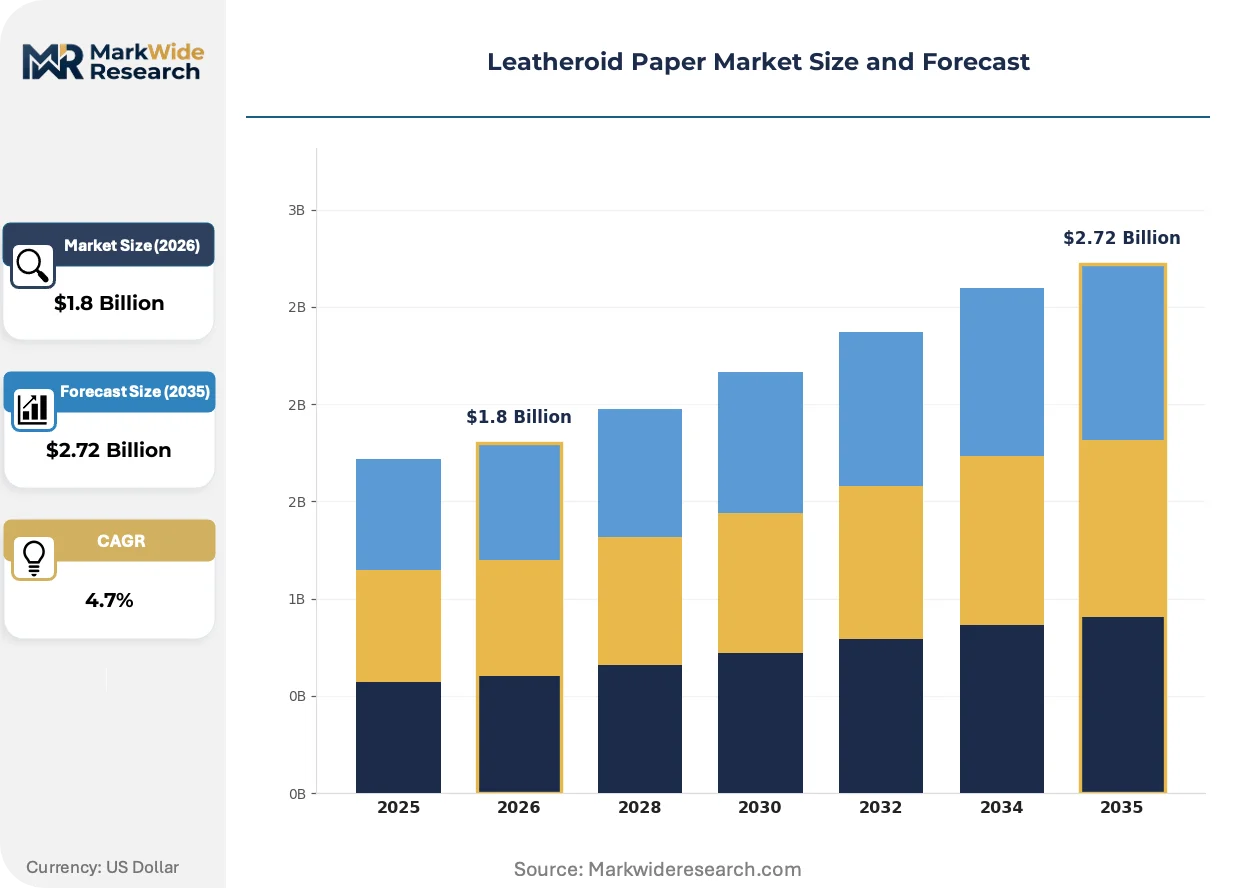
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Fiber, Synthetic Blend, Coated, Uncoated, Reinforced End Use Industry: Apparel, Furniture Manufacturing, Automotive Interiors, Bookbinding, Craftwork Application: Protective Coverings, Decorative Finishes, Packaging, Printing Substrates, Upholstery Distribution Channel: Wholesale Suppliers, Direct Manufacturers, Online Retailers, Specialty Stores, Exporters |
| Companies Covered | DuPont, Teijin Aramid, Yantai Tayho Advanced Materials, Shenzhen Longpont, SRO Aramid, Yantai Minshida Special Paper, Zhuzhou Times Fiber Pioneer Material Technology, Chaomeisi New Material, Ganzhou Longpont Material Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leatheroid Paper Market Trends and Innovations
Formulation science and regulatory telemetry are converging to redefine how Leatheroid Paper suppliers validate performance claims and secure specification lock-in across automotive and furniture verticals.
Hybrid fiber substrates combining cellulosic pulp with recycled PET staple are hybridizing traditional wet-laid manufacturing. Tier 1 automotive seating suppliers in Germany and South Korea are qualifying these materials for door panel inserts where weight reduction targets intersect with sustainability scorecard requirements. The structural consequence is compression of pure-synthetic grade pricing power in mid-tier applications.
REACH SVHC candidate list expansion is forcing reformulation of formaldehyde-based crosslinking agents. European furniture OEMs now require full material disclosure to 0.1% substance thresholds, shifting procurement preference toward suppliers with pre-certified resin systems. Protective covering segments for industrial machinery are experiencing the steepest compliance cost inflation.
Automotive aftermarket refurbishment specialists are consolidating purchasing through digital B2B platforms that bypass traditional distributor markups. North American upholstery shops now source direct from Shandong manufacturers via cross-border e-procurement channels, compressing traditional three-tier distribution structures. This disintermediation is most visible in commercial fleet vehicle interior refresh programs.
Leatheroid Paper Market Segmentation
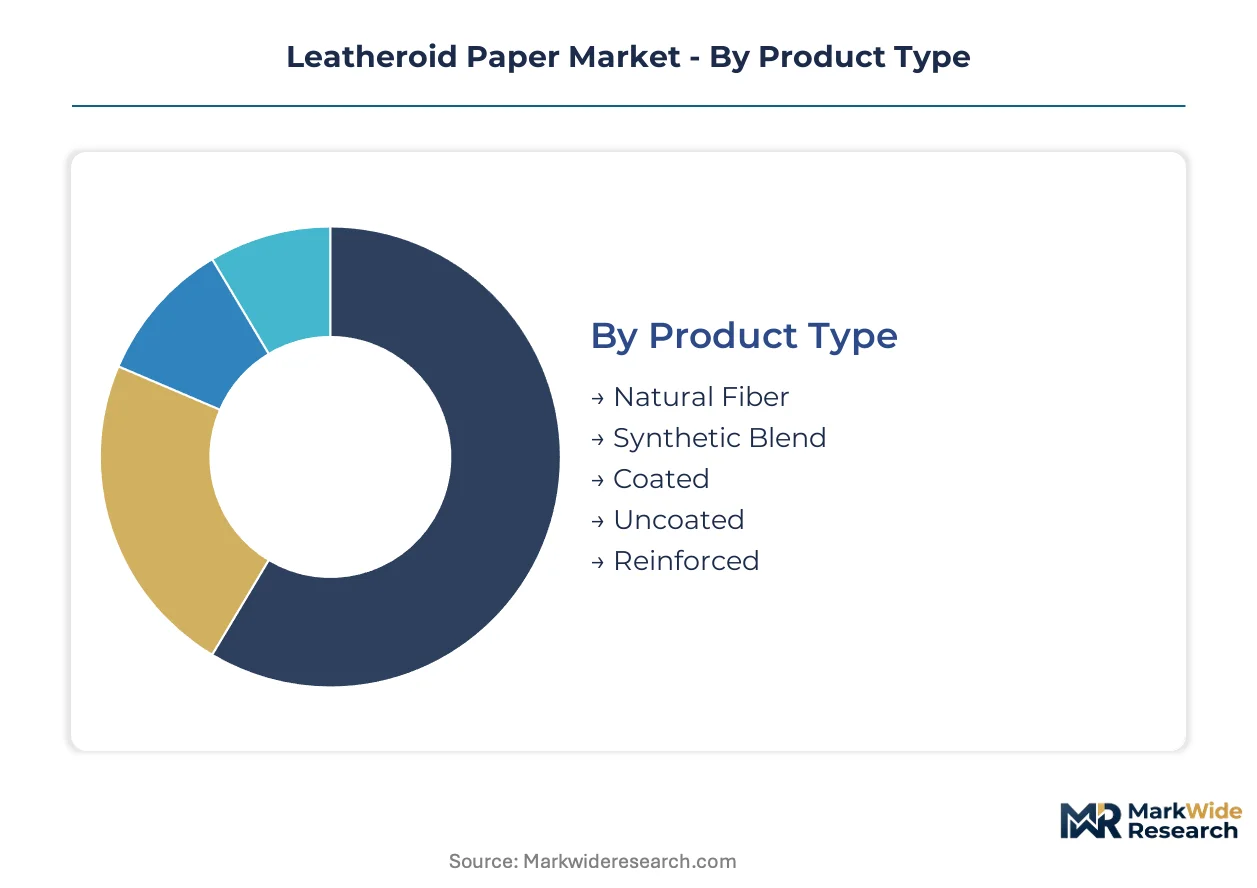
Leatheroid Paper procurement cycles vary dramatically across segments, from quarterly automotive refresh orders to decade-long industrial protective covering contracts. Understanding these velocity differentials helps suppliers align inventory positioning with cash conversion requirements.
Product Type:
Synthetic Blend grades turn inventory fastest through automotive seating programs, while Reinforced variants sit longest in specification validation queues for protective equipment.
- Synthetic Blend:Combines cellulosic pulp with PET staple fibers in wet-laid matrices optimized for 20,000-40,000 Martindale abrasion cycles. Automotive door panel and seat insert programs in Germany and South Korea drive the bulk of volume throughput as OEMs pursue sustainability scorecard compliance.
- Reinforced:Integrates para-aramid or glass fiber layers to exceed 50 N/cm tensile strength thresholds. Specification lock-in cycles stretch 18-24 months for industrial machinery protective coverings where DuPont and Teijin Aramid anchor technical validation protocols.
- Natural Fiber:Pure cellulosic substrates targeting craftwork and premium bookbinding applications with biodegradability credentials.
- Coated:UV-curable ink-receptive surfaces enabling digital print compatibility for short-run furniture decorative programs.
- Uncoated:Base grades for downstream lamination and adhesive bonding in packaging converter supply chains.
Synthetic Blend anchors the volume base while Coated variants gain share at the steepest rate.
End Use Industry:
Margin profiles stratify sharply between specification-heavy automotive contracts and fragmented craftwork purchasing.
- Automotive Interiors:GB 8410 flammability compliance and REACH SVHC screening dominate procurement criteria. Refurbishment cycle compression from seven-year to four-year intervals is forcing suppliers to recalibrate formulation pipelines for faster-turn synthetic upholstery replacement.
- Furniture Manufacturing:SKU proliferation without tooling costs drives demand for digitally printable substrates. Yantai Tayho Advanced Materials dominates regional supply for Shandong province furniture clusters.
- Apparel:Niche applications in performance accessories and vegan leather alternatives with limited volume scale.
- Bookbinding:Traditional library binding and archival restoration markets with stable but declining demand.
- Craftwork:Hobbyist and artisan purchasing through specialty retail channels with high margin but unpredictable order patterns.
Automotive Interiors commands the tightest specification requirements while Furniture Manufacturing offers the most accessible expansion pathway for compliant entrants.
Application:
Performance thresholds separate commodity upholstery from premium protective covering positioning.
- Upholstery:Abrasion resistance and flex fatigue specifications define competitive positioning in seating applications. Polyurethane synthetic leather substitution pressures mid-tier contracts where Martindale thresholds fall below 30,000 cycles.
- Protective Coverings:Tensile strength and chemical resistance specifications for industrial machinery and medical equipment surfaces. Antimicrobial additive integration is emerging as a hygiene protocol differentiator for hospital mattress applications.
- Decorative Finishes:Digital printing compatibility and grain pattern fidelity for furniture and architectural surface programs.
- Packaging:Structural rigidity and printability for luxury goods and electronics presentation boxes.
- Printing Substrates:Dimensional stability and ink holdout for commercial and security printing applications.
Upholstery generates the broadest revenue base while Protective Coverings delivers the highest per-unit margins.
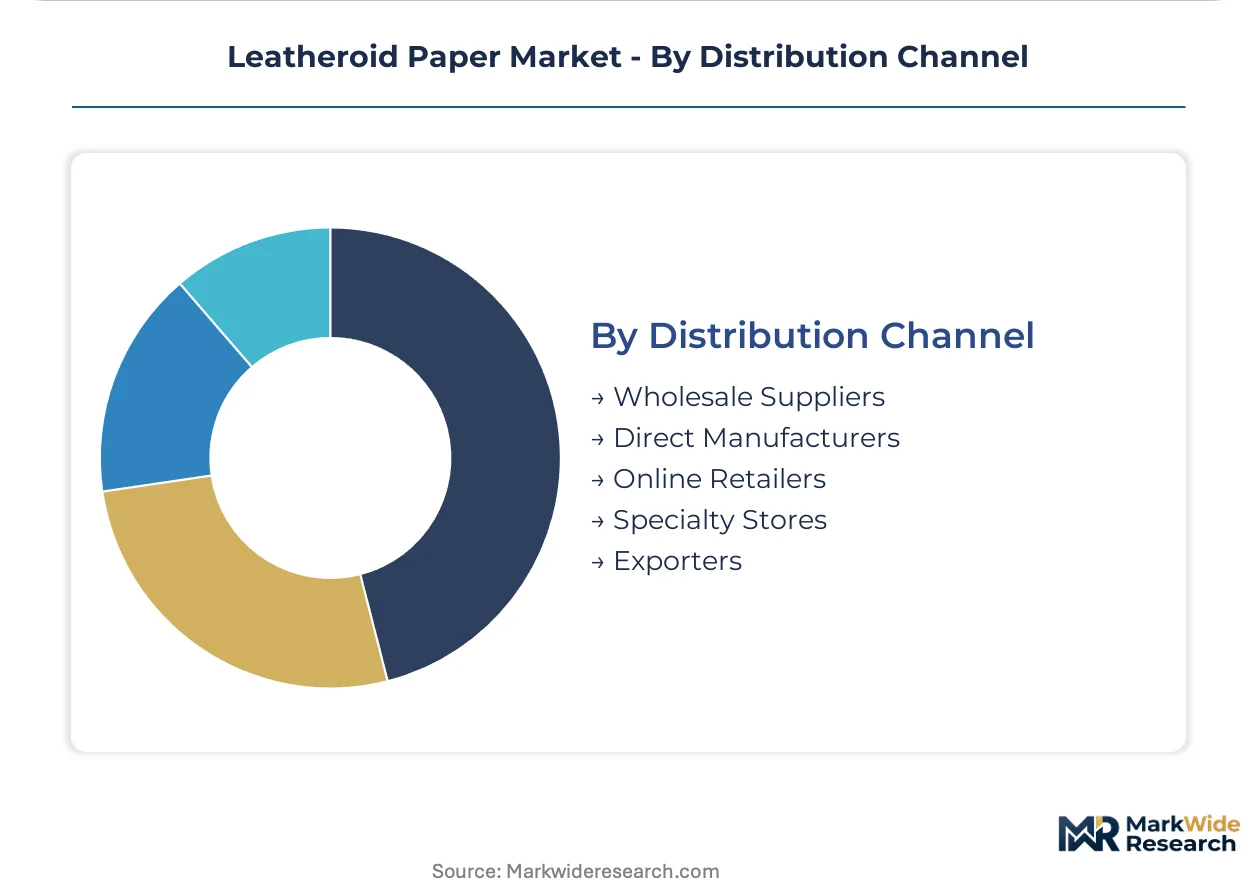
Distribution Channel:
Channel selection determines margin capture versus market access tradeoffs across customer segments.
- Direct Manufacturers:Automotive tier suppliers and large furniture OEMs bypass distributor markups through mill-direct procurement. North American upholstery shops increasingly source direct from Shandong manufacturers via cross-border e-procurement platforms.
- Wholesale Suppliers:Inventory aggregation for mid-tier converters and regional distributors serving fragmented end-user bases.
- Online Retailers:Craftwork and small-batch furniture segments with SKU breadth requirements exceeding traditional distributor capabilities.
- Specialty Stores:Artisan and restoration professionals requiring technical consultation and sample validation.
- Exporters:Consolidated logistics for REACH and EPA TSCA certification-aligned shipments to European and North American markets.
Direct Manufacturers capture the highest volume throughput while Online Retailers expand most quickly in craftwork and small-batch segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Calendering capacity clusters along China's eastern seaboard, with wet-laid nonwoven mills concentrated within 300 kilometers of Yantai and Shenzhen. This geographic density reduces logistics friction for automotive tier suppliers but concentrates weather and energy disruption exposure.
China
Automotive interior refurbishment programs and furniture manufacturing clusters drive procurement volumes. SAMR enforces GB 8410 flammability standards that disqualify conventional PVC alternatives. Yantai Tayho Advanced Materials anchors supply for Shandong province furniture manufacturers.
Germany
Tier 1 automotive seating suppliers qualify hybrid fiber substrates for door panel inserts where sustainability scorecards intersect with weight reduction targets. REACH SVHC screening requirements shape procurement specifications for resin systems. Industrial machinery protective covering demand concentrates in Baden-Württemberg manufacturing corridors.
United States
Aftermarket upholstery shops source direct from Shandong manufacturers via cross-border e-procurement platforms. EPA TSCA certification requirements constrain export eligibility for Asian manufacturers. Commercial fleet vehicle interior refresh programs compress traditional distribution structures.
Japan
Technical leadership in reinforced grades sustains specification lock-in for industrial protective coverings. METI oversees chemical substance management frameworks that align with REACH disclosure thresholds. Teijin Aramid anchors para-aramid fiber supply for premium reinforcement applications.
India
Furniture manufacturing expansion creates first-mover opportunity for BIS-certified formaldehyde-compliant imports. BIS certification alignment remains sparse among domestic producers. Maharashtra and Gujarat industrial corridors attract procurement from export-oriented automotive component suppliers.
Leatheroid Paper Market Competitive Landscape
Integrated fiber-chemical conglomerates and specialized wet-laid nonwoven fabricators split the market between premium reinforcement grades and high-volume synthetic blends. The vendor base stratifies across three tiers: multinational material science groups with aramid fiber captive supply, mid-scale Chinese producers with integrated pulp-to-calendering operations, and regional converters serving craftwork and bookbinding niches. Dominant competitive moves include geographic expansion into Indian furniture manufacturing corridors and portfolio diversification toward antimicrobial-coated variants for medical equipment surfaces.
Within the multinational tier, DuPont and Teijin Aramid occupy positions anchored by para-aramid fiber expertise and technical validation protocols. Yantai Tayho Advanced Materials exemplifies the integrated Chinese producer archetype with regional supply dominance in Shandong province furniture clusters.
| Leading Market Players |
|---|
| DuPont |
| Teijin Aramid |
| Yantai Tayho Advanced Materials |
| Shenzhen Longpont |
| SRO Aramid |
| Yantai Minshida Special Paper |
| Zhuzhou Times Fiber Pioneer Material Technology |
| Chaomeisi New Material |
| Ganzhou Longpont Material Technology |
| Others |
Pricing and Supply Chain Analysis
Yantai and Shenzhen wet-laid nonwoven capacity concentration anchors margin distribution across the Leatheroid Paper value chain, with automotive tier suppliers capturing pricing leverage through mill-direct procurement while furniture manufacturers absorb distributor markups. Para-aramid fiber cost volatility from Teijin Aramid and DuPont captive supply feeds directly into Reinforced grade premium positioning, compressing mid-tier Synthetic Blend pricing power when feedstock spikes.
Pricing Analysis
Aftermarket refurbishment revenue through commercial fleet interior refresh programs drives lifetime value capture for Shandong manufacturers selling direct to North American upholstery shops. Three-tier pricing structure across premium Reinforced, standard Synthetic Blend, and economy Natural Fiber grades reflects certification burden differentiation, with GB 8410 flammancy compliance adding cost layers. Cost compression in Synthetic Blend tiers is intensifying as polyurethane synthetic leather substitution pressures mid-tier automotive seating contracts. Furniture manufacturing buyers show highest price sensitivity due to SKU proliferation demands, while protective covering procurement for industrial machinery remains least sensitive given specification lock-in cycles.
Supply Chain Analysis
Extended payment terms from automotive tier suppliers are squeezing working capital for mid-scale Chinese producers without integrated pulp-to-calendering operations. Raw material sourcing draws from para-aramid fiber supply in Japan, cellulosic pulp from Southeast Asia, and PET staple from domestic Chinese chemical fiber producers. Single-region concentration risk concentrates in the Yantai-Shenzhen corridor where weather disruption and energy rationing threaten calendering continuity. Distribution runs through direct manufacturer channels for automotive and large furniture OEMs, with cross-border e-procurement platforms disintermediating traditional three-tier structures for aftermarket refurbishment segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to automotive interior refurbishment cycle compression from seven-year to four-year intervals, creating inventory velocity demands that favor agile formulation pipelines.
For Market Incumbents: Entrench specification lock-in through accelerated REACH SVHC pre-certification of resin systems ahead of European furniture OEM disclosure mandates. Deepen backward integration into para-aramid fiber supply through offtake agreements with Teijin Aramid or DuPont to defend Reinforced grade margins against feedstock volatility. Channel control investments in digital B2B platform partnerships will secure aftermarket refurbishment volume as North American upholstery shops bypass distributors.
For New Entrants and Emerging Players: Build out BIS-certified formaldehyde-compliant supply lines targeting Maharashtra and Gujarat furniture manufacturing corridors where domestic certification alignment remains sparse. India furniture manufacturing offers the most penetrable geography given import dependency and fragmented local production. A go-to-market angle anchored to antimicrobial additive integration for medical equipment protective coverings unlocks premium positioning without direct confrontation with established automotive supply relationships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-scale Chinese wet-laid nonwoven specialists lacking integrated calendering capacity or export certification infrastructure. Long-term viability across a 5-10 year window hinges on sustainability credential verification systems for EU Green Deal material passport compliance. The signal to watch is consolidation velocity among Shandong province furniture cluster suppliers as margin pressure forces asset sales.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH SVHC Pre-Certification Investment | European furniture OEM procurement preference shifts toward suppliers with pre-validated resin systems ahead of enforcement phase-ins. |
| Antimicrobial Additive Integration | Hospital mattress and examination table surface protocols create premium tier differentiation for protective covering segments. |
| Cross-Border E-Procurement Platform Partnership | North American upholstery shop direct sourcing from Shandong manufacturers compresses traditional distributor markups. |
| Hybrid Fiber Substrate Qualification | German and South Korean Tier 1 automotive seating suppliers prioritize sustainability scorecard alignment for door panel inserts. |
| BIS Certification Alignment for India Entry | Maharashtra and Gujarat furniture manufacturing expansion creates first-mover advantage for compliant importers against sparse domestic certification. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with wet-laid nonwoven plant managers, automotive Tier 1 supplier procurement leads, furniture manufacturing R&D directors, and aftermarket upholstery shop operators. Secondary validation drew from SAMR GB standard filings, EPA TSCA certification databases, customs trade data for resin-impregnated fiber substrates, and SEC disclosures from integrated fiber-chemical conglomerates. Bottom-up volume modeling across product grades and end-use segments was triangulated against top-down macroeconomic indicators for synthetic leather substitution elasticity.
Calibration against historical price realization patterns for para-aramid reinforced grades and Synthetic Blend automotive contracts anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, end-use industry vertical, application performance threshold, and distribution channel structure. CAGRs were derived through regression analysis of specification validation cycle compression and refurbishment interval trends, with inputs from digital printing compatibility adoption curves and flammability standard enforcement timelines.
Stress conditions across para-aramid fiber price volatility, GB standard enforcement acceleration, and polyurethane synthetic leather substitution elasticity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding certification sequencing timelines and automotive OEM sustainability scorecard weightings. Macroeconomic contraction in East Asian manufacturing clusters, regulatory fragmentation across REACH and SAMR disclosure thresholds, or breakthroughs in cast PU film abrasion resistance would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Middle-East and Africa Paper and Paperboard Market
Paper Products
Thin Printing Paper Market
Paper Products
Decorative Plastic and Paper Laminates Market
Paper Products
Cheque Paper Market
Paper Products
Paper Machinery Market
Paper Products
Liquid Paperboard Market
Paper Products
Wood-Based Sheet Materials Market
Paper Products
Paper Doilies Market
Paper Products
Printing Paper Market
Paper Products
Loose Leaf Paper Market
Paper Products
Office Printing Papers Market
Paper Products
GCC Stone Paper Market
Paper Products
Paper Coating Materials Market
Paper Products
Europe Paper Market
Paper Products
Pulp and Paper Chemicals Market
Paper Products
Greaseproof Paper Sheets Market