
 Global Organic Personal Care Ingredients Market | 2026-2036
Global Organic Personal Care Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Global Organic Personal Care Ingredients Market Intelligence
The direct-to-consumer e-commerce channel is rewriting the procurement rules for emerging personal care brands, enabling smaller players to source specialized organic ingredients. Large-scale suppliers like BASF SE leverage extensive R&D capabilities to offer certified organic compounds at scale. Meanwhile, specialists such as Croda International Plc differentiate through a focus on high-performance plant extracts and sustainable sourcing, while Evonik Industries AG positions its portfolio around bioactive compounds for advanced formulations.
Organic personal care ingredients are plant-derived or naturally occurring substances cultivated and processed without synthetic chemicals, irradiation, or genetic modification. Their primary function is to act as emollients, surfactants, and active agents in formulations, replacing petroleum-based counterparts. The skin care application segment commands the largest share, driven by consumer focus on facial treatments and anti-aging products. Within product types, plant extracts and essential oils show significant growth due to their perceived efficacy and alignment with wellness trends.
Regulatory frameworks, including the EU's REACH regulation and the US FDA's Modernization of Cosmetics Regulation Act, impose strict safety and labeling requirements. In parallel, certification standards from bodies such as COSMOS and NATRUE provide a benchmark for organic content, influencing formulation choices. Navigating the complex patchwork of international certifications and substantiating 'clean' and 'sustainable' claims remains a critical differentiator for ingredient suppliers.
Market Dynamics
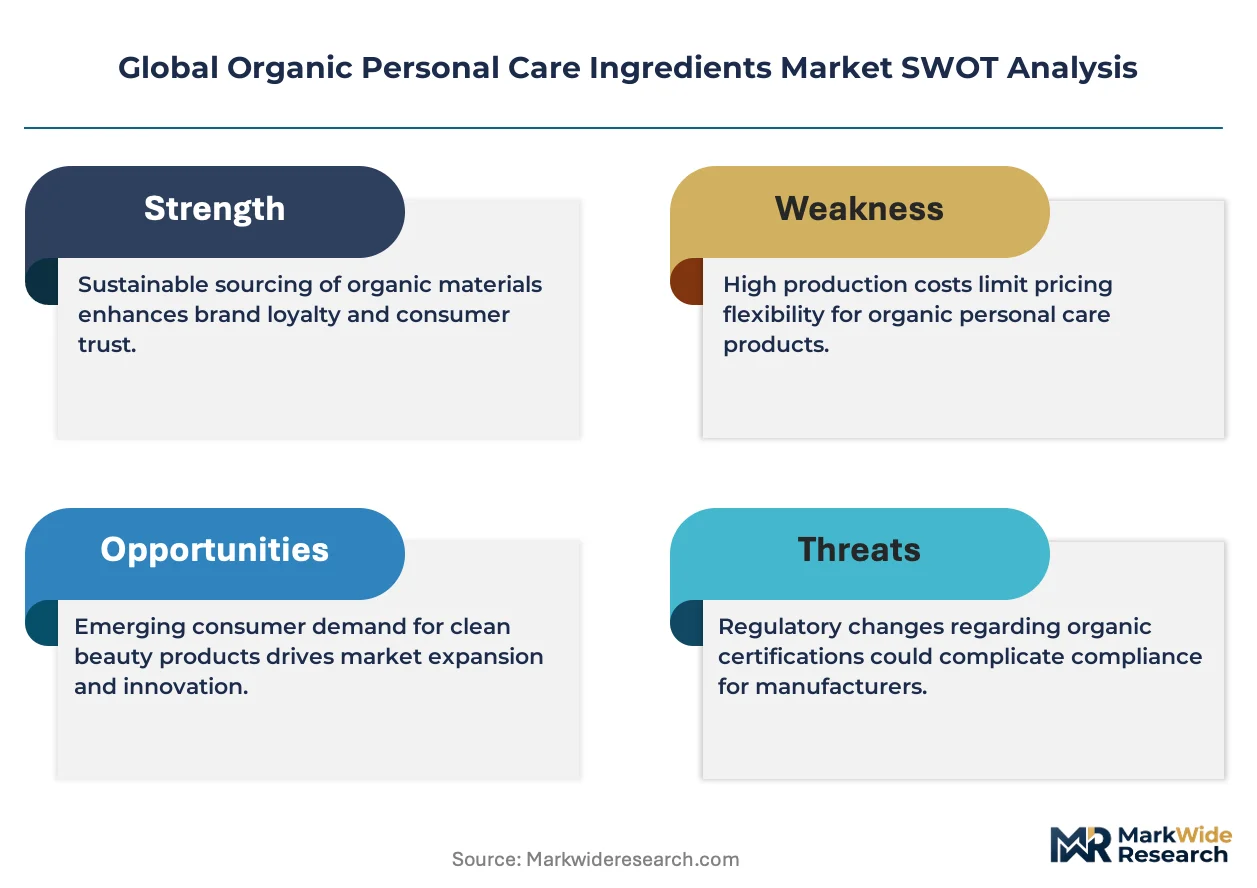
The central structural force shaping the organic personal care ingredients market is the convergence of stringent chemical safety regulations, exemplified by the EU's Green Deal, and consumer demand for ingredient transparency, compelling a definitive shift away from synthetic compounds.
Growth Catalysts
- Clean-Label Consumerism:Intensifying consumer scrutiny of product labels, particularly within the skin care and baby care segments, directly fuels demand for ingredients with certified organic and easily understandable origins over complex chemical names.
- Regulatory Substitution Mandates:Frameworks like the EU's REACH regulation and its chemical strategy are progressively restricting or banning certain petroleum-derived substances, creating a non-negotiable substitution imperative for formulators to adopt plant-based alternatives. -
- Wellness and Aromatherapy Integration:The incorporation of wellness concepts into daily personal care routines elevates the value of functional ingredients like essential oils and adaptogenic plant extracts, which are sought for their perceived therapeutic and aromatherapeutic benefits.
Market Restraints
- Agricultural Supply Volatility:The supply of key botanical raw materials is subject to climate-related disruptions such as droughts and floods, leading to unpredictable yields and price instability for high-demand ingredients like shea butter or argan oil.
- Certification and Compliance Costs:The financial and administrative burden of obtaining and maintaining multiple organic certifications, such as COSMOS and NATRUE, presents a significant barrier to entry and scale for smaller ingredient suppliers.
- Technical Performance Gaps:Certain organic ingredients, particularly natural surfactants and preservatives, face challenges in delivering the same level of performance, stability, and sensory experience as their synthetic counterparts in sophisticated formulations.
Strategic Opportunities
- Bio-fermentation for Novel Actives:Leveraging biotechnology and fermentation processes to produce nature-identical or novel bioactive compounds allows for the creation of high-potency, sustainable ingredients with consistent quality, independent of agricultural variability.
- Expansion in Men's Grooming:The underpenetrated men's personal care market represents a significant growth vector for organic ingredients that can be formulated into products emphasizing simplicity, efficacy, and natural sourcing.
- Halal-Certified Ingredients:Developing a portfolio of Halal-certified organic ingredients opens access to rapidly expanding cosmetics markets in Muslim-majority countries across the Middle East and Southeast Asia, where certification is a key purchasing driver.
Industry Challenges
- Substantiating Marketing Claims:Verifying and documenting 'sustainable', 'ethically sourced', and 'clean' claims to withstand scrutiny from regulators like the FTC and advertising standards authorities is a complex and resource-intensive operational challenge.
- Global Standards Harmonization:The lack of a single, globally recognized organic standard forces suppliers to navigate a complex patchwork of regional certifications, such as USDA Organic, COSMOS, and NATRUE, increasing compliance costs for global distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Organic Personal Care Ingredients Market |
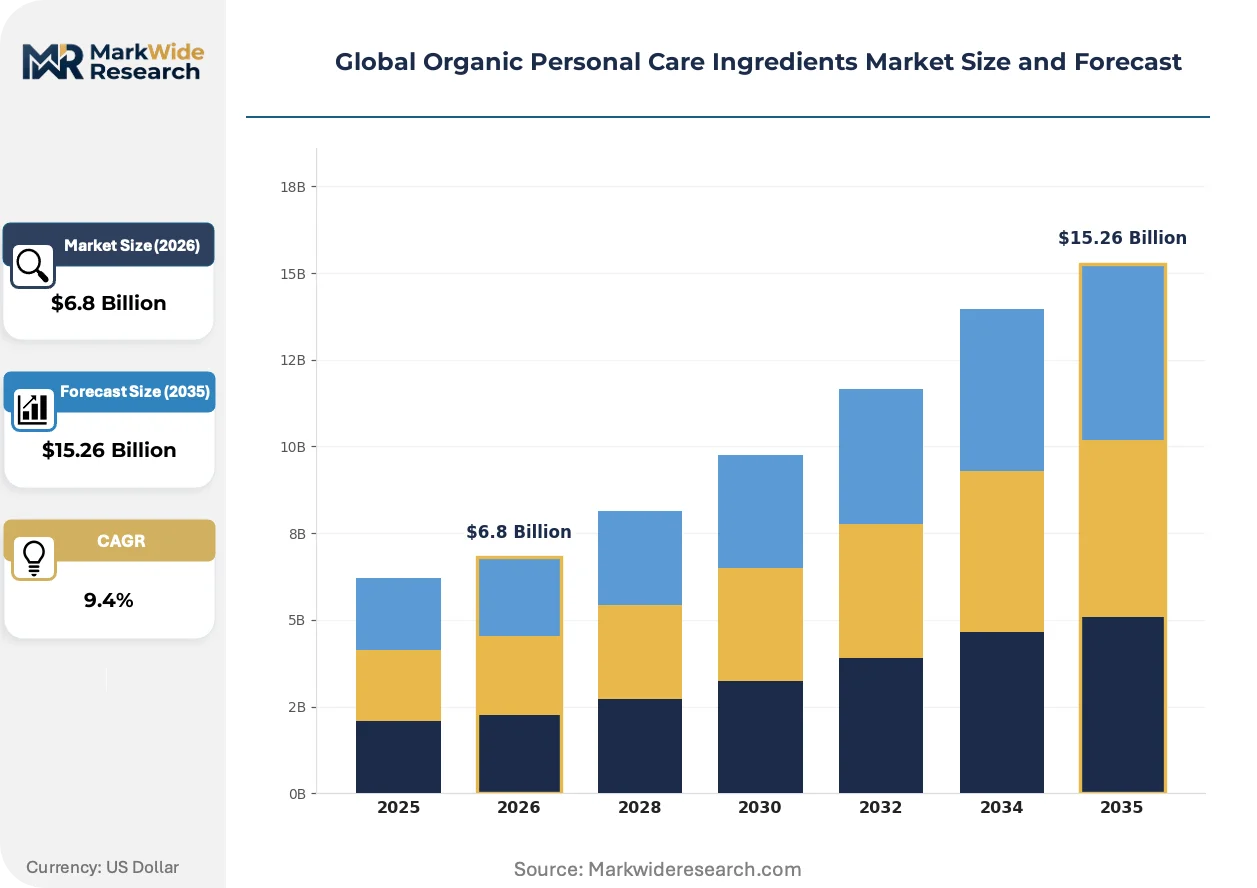
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
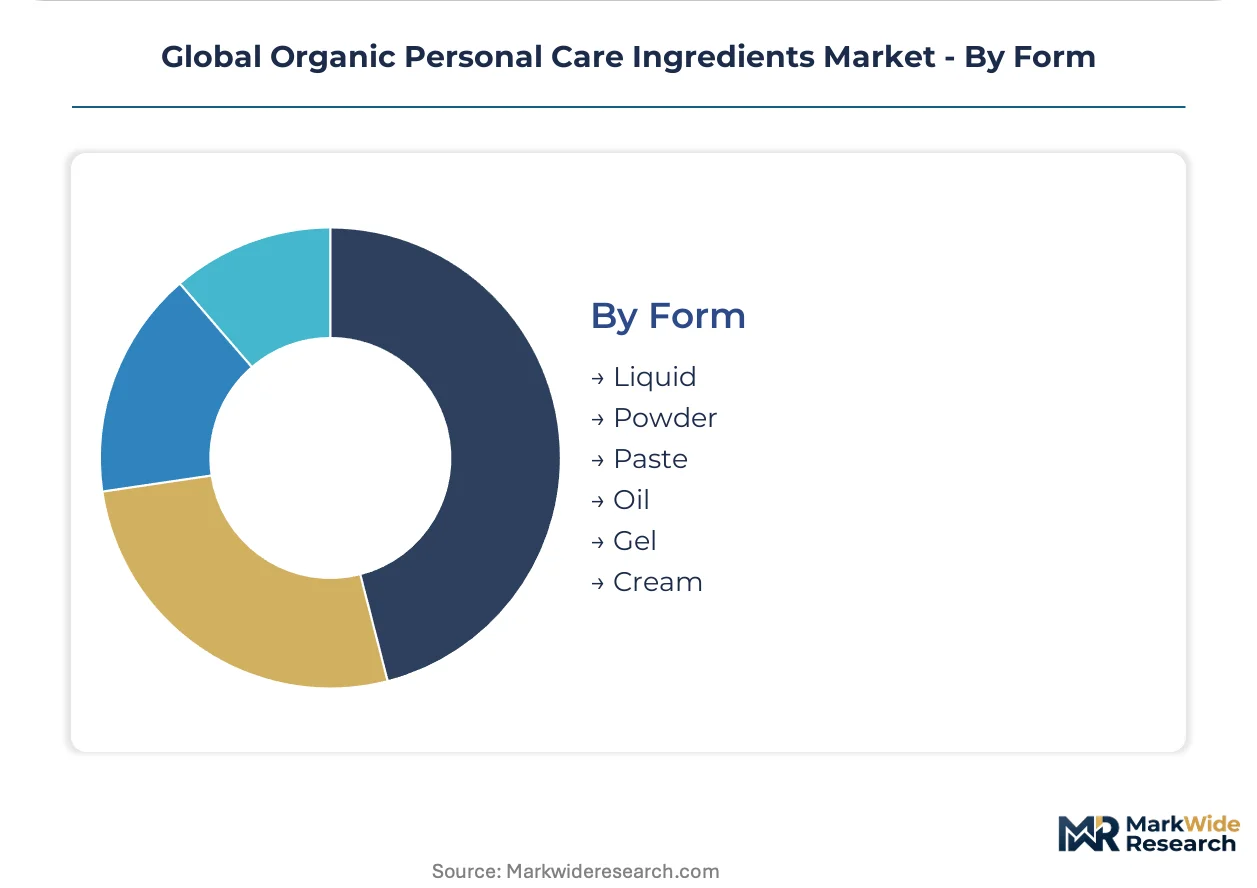
| Segmentation | Product Type: Essential Oils, Plant Extracts, Natural Emollients, Vitamins, Bioactive Compounds, Enzymes Application: Skin Care, Hair Care, Oral Care, Bath & Shower, Cosmetics, Sun Care End User: Personal Care Brands, Contract Manufacturers, Retail Chains, Salons & Spas, Dermatology Clinics Form: Liquid, Powder, Paste, Oil, Gel, Cream |
| Companies Covered | Cargill, Inc., BASF SE, Croda International Plc, The Lubrizol Corporation, Evonik Industries AG, AkzoNobel N.V., Huntsman International LLC, Clariant AG, Ashland, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Organic Personal Care Ingredients Market Strategic Shifts & Innovations
A convergence of biotechnology and regulatory tightening is defining the next generation of organic personal care ingredients. These forces are pushing the market beyond simple botanical extracts toward ingredients with validated efficacy, consistent performance, and a transparent, sustainable production history.
Advanced bioactive compounds created through lab-based methods are gaining traction. Formulators in the premium anti-aging and dermo-cosmetics sectors are adopting these ingredients. Consequently, the market is migrating from reliance on wild-harvested or traditionally cultivated plant extracts to scientifically controlled, high-potency bioactives derived from fermentation and plant cell culture, which offer a smaller environmental footprint.
The US FDA's Modernization of Cosmetics Regulation Act (MoCRA) introduces stricter federal oversight over product safety. This legislation compels ingredient suppliers to provide more robust safety substantiation data and maintain detailed records for all products sold in the United States. Suppliers of complex botanical extracts and novel bio-fermented ingredients are most affected, now facing increased investment in toxicological testing and compliance documentation.
Direct sourcing models are disrupting traditional distribution channels for organic ingredients. Emerging direct-to-consumer (D2C) brands are bypassing multi-step distributors to forge partnerships with agricultural cooperatives and individual farms. This shift, most visible in North America and Western Europe, allows brands to build compelling marketing narratives around traceability, ethical sourcing, and community impact.
Global Organic Personal Care Ingredients Market Segmentation
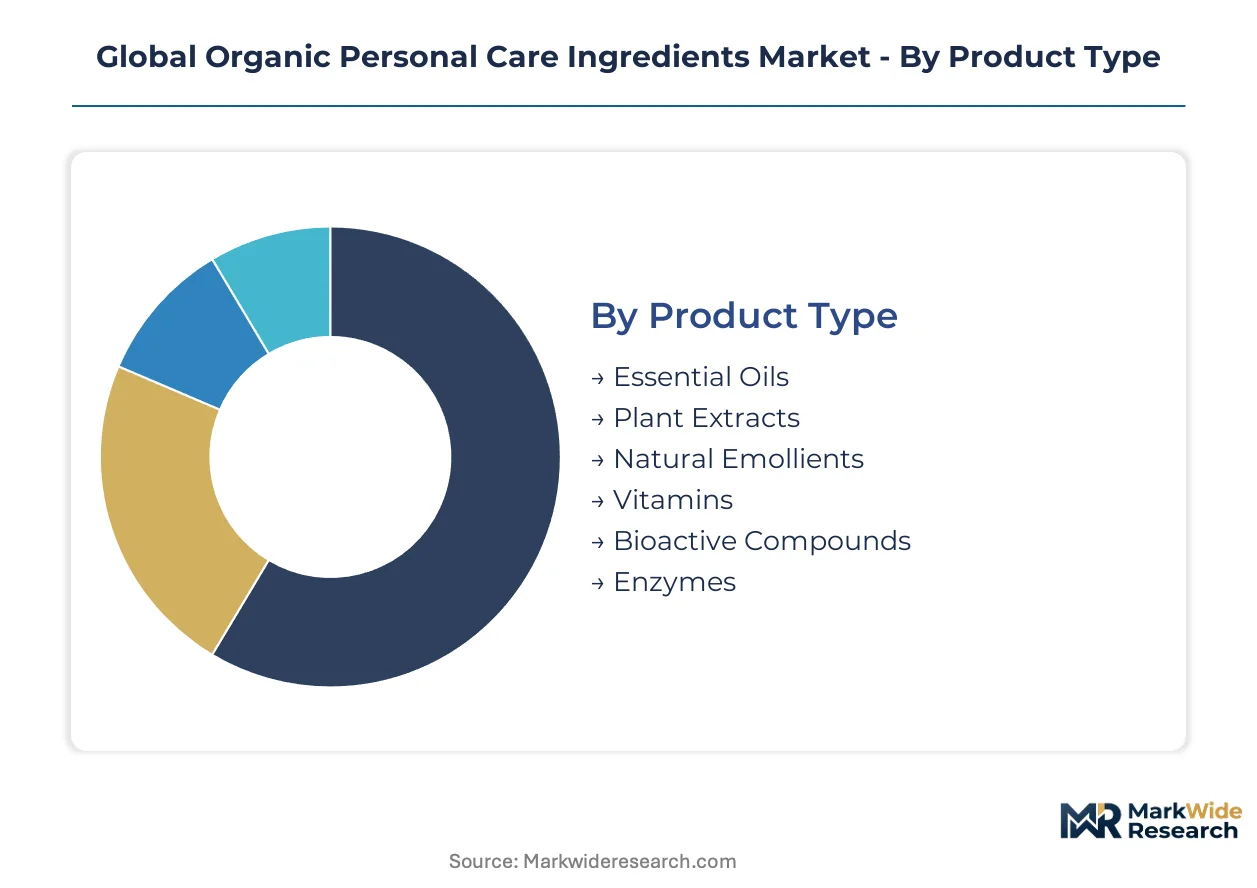
Understanding the segmentation of the global organic personal care ingredients market illuminates the varied demands and supply dynamics across product types, applications, and end-user groups. This granular view helps ingredient suppliers align their portfolio development with specific industry needs and evolving consumer preferences.
Product Type:
The maturity spectrum of organic personal care ingredients reveals a market transitioning from established botanical extracts to advanced bio-fermented compounds. Ingredient suppliers are focusing R&D on both traditional efficacy and novel biotechnological approaches.
- Essential Oils:These concentrated hydrophobic liquids contain volatile aroma compounds from plants, extracted through distillation or mechanical pressing. Demand concentrates in aromatherapy and natural fragrance applications, driven by consumer wellness trends and preference for clean labels.
- Plant Extracts:Derived from various plant parts, these ingredients offer specific functional properties like anti-inflammatory or antioxidant effects. The skin care segment, particularly anti-aging formulations, drives significant demand for high-performance plant extracts due to perceived efficacy.
- Natural Emollients:These plant-derived oils and butters soften and moisturize the skin, replacing petroleum-based alternatives.
- Vitamins:Incorporated for their antioxidant and skin-enhancing properties, vitamins like C and E are crucial for anti-aging and protective formulations.
- Bioactive Compounds:Produced through biotechnology or advanced extraction, these ingredients offer targeted physiological effects at low concentrations.
- Enzymes:Used in exfoliating and brightening products, enzymes provide gentle yet effective skin renewal benefits.
Essential Oils retains volume leadership; Bioactive Compounds holds the steepest expansion curve.
Application:
Application focus within the organic personal care ingredients market is heavily influenced by consumer spending patterns and regulatory shifts towards safer formulations.
- Skin Care:This segment includes facial treatments, moisturizers, and anti-aging products, constituting the largest share of ingredient demand. Consumer scrutiny over ingredient lists and the push for natural formulations in Europe and North America directly influence procurement.
- Hair Care:Products such as shampoos, conditioners, and styling agents increasingly integrate organic ingredients for scalp health and natural conditioning. Brands are reformulating to meet rising consumer expectations for gentle, chemical-free hair solutions.
- Oral Care:Organic ingredients like mint extracts and natural sweeteners are gaining traction in toothpastes and mouthwashes.
- Bath & Shower:Soaps, body washes, and bath additives use organic surfactants and fragrances for a natural cleansing experience.
- Cosmetics:Foundations, mascaras, and lip products incorporate organic pigments and emollients for enhanced safety and natural appeal.
- Sun Care:Mineral-based organic ingredients offer natural UV protection in sunscreens and after-sun lotions.
Skin Care applications command the highest revenue; Cosmetics applications are gaining share fastest.
End User:
The procurement patterns among different end-user segments reflect varying needs for scale, certification, and specialized ingredient functionality.
- Personal Care Brands:These companies directly formulate and market products under their own labels, often requiring a diverse range of certified organic ingredients. Smaller direct-to-consumer brands frequently source specialized ingredients for unique product lines.
- Contract Manufacturers:These firms produce personal care products for multiple brands, demanding consistent supply and technical support for various organic formulations. Their procurement often involves bulk orders of widely used organic compounds.
- Retail Chains:Private label brands from major retail chains increasingly require organic ingredients to meet consumer demand for natural products.
- Salons & Spas:Professional establishments seek high-performance organic ingredients for treatments and retail products, emphasizing natural efficacy.
- Dermatology Clinics:These clinics use specialized organic ingredients in dermo-cosmetic formulations for sensitive skin and therapeutic applications.
Personal Care Brands drive the majority of ingredient volume; Dermatology Clinics are a rapidly expanding customer type.
Form:
The physical form of organic personal care ingredients dictates their ease of integration into various product formulations and their stability during storage.
- Liquid:These ingredients, often essential oils or plant extracts, are readily incorporated into water-based or oil-based formulations. Liquid forms offer ease of blending and consistent dispersion in finished products.
- Powder:Ingredients like botanical powders or mineral pigments provide concentrated active compounds and extend shelf life, suitable for dry formulations or activated products. Powder forms are favored for stability and reduced shipping weight.
- Paste:Thick, semi-solid ingredients like natural butters or waxes provide emollient properties and structural integrity to creams and balms.
- Oil:Carrier oils and lipid-soluble extracts deliver moisturizing and nourishing benefits, forming the base for many skin and hair treatments.
- Gel:Water-based gels offer lightweight hydration and a refreshing sensory experience in various personal care applications.
- Cream:Emulsified formulations combine oil and water phases, providing rich texture and comprehensive delivery of active ingredients.
Liquid ingredients retain formulation versatility; Powder forms exhibit the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The port infrastructure of Rotterdam facilitates the distribution of diverse raw materials crucial for organic personal care ingredient manufacturing across Europe. This vital trade gateway underpins significant market activity in key European nations. Global demand also extends to critical markets in North America, Asia, and the Middle East, driven by distinct regional preferences.
Germany
German consumer demand for certified organic and clean-label personal care products drives significant ingredient procurement. The EU's REACH regulation imposes stringent chemical safety requirements, compelling formulators to adopt plant-based alternatives. The Rhine-Ruhr region, home to major chemical companies and R&D centers, drives innovation in organic compounds.
United States
Consumer preference for natural formulations, particularly in anti-aging and facial treatments, fuels demand for organic ingredients in the United States. The US FDA's Modernization of Cosmetics Regulation Act (MoCRA) mandates robust safety substantiation, impacting ingredient suppliers. California's dynamic beauty industry hub fosters product development with certified organic components.
France
France's luxury cosmetics sector and strong aromatherapy integration elevate the value of high-performance organic ingredients. The EU's COSMOS certification standards influence formulation choices for many French brands. The Cosmetic Valley cluster around Chartres and Orleans concentrates R&D and production for specialized plant extracts.
United Arab Emirates
The United Arab Emirates represents a rapidly expanding market for Halal-certified organic personal care products. ESMA (Emirates Authority for Standardization and Metrology) certification is a key purchasing driver for consumers. Dubai's free zones attract international ingredient suppliers catering to regional demand for ethically sourced materials.
Japan
Japanese consumers prioritize advanced dermo-cosmetics and biotechnology-derived active ingredients for efficacy. The PMDA (Pharmaceuticals and Medical Devices Agency) oversees safety and quality for cosmetic components. Tokyo's vibrant research institutions and beauty companies collaborate on novel bioactive compounds for sophisticated formulations.
Global Organic Personal Care Ingredients Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the organic personal care ingredients market. The market structure exhibits a tiered approach, with large chemical conglomerates offering broad portfolios alongside specialized botanical extract providers. Strategic archetypes include diversified chemical giants, niche plant-based ingredient innovators, and bio-fermentation technology leaders. Competitive moves focus on portfolio diversification through sustainable sourcing and strategic partnerships to access novel bioactive compounds.
Within the diversified chemical giant archetype, BASF SE and Evonik Industries AG exemplify scale and extensive R&D capabilities, offering certified organic compounds at volume. Croda International Plc, on the other hand, occupies a position as a specialist, differentiating through a focus on high-performance plant extracts and sustainable sourcing practices. These entities anchor distinct segments of the supply chain, from bulk ingredients to specialized, high-value bioactives. Their strategic approaches collectively define the competitive dynamics for organic ingredient suppliers serving the personal care sector.
| Leading Market Players |
|---|
| Cargill, Inc. |
| BASF SE |
| Croda International Plc |
| The Lubrizol Corporation |
| Evonik Industries AG |
| AkzoNobel N.V. |
| Huntsman International LLC |
| Clariant AG |
| Ashland, Inc. |
| Others |
Cost & Logistics Intelligence
Agricultural supply volatility for key botanical raw materials determines both pricing tier spreads and the structural shape of ingredient supply chains. Unpredictable yields from climate disruptions directly impact cost and availability for formulators.
Pricing Analysis
Volume-discount tiering defines the pricing structure for organic personal care ingredients. Price differentiation stems from certification level, quality grade, and volume scale for ingredient buyers. Pricing pressure stems from agricultural supply volatility, particularly for high-demand botanicals like argan oil. Smaller direct-to-consumer brands often exhibit higher price sensitivity compared to large personal care brands securing long-term contracts.
Supply Chain Analysis
Major chemical conglomerates and specialized ingredient processors concentrate the production capacity for organic compounds. Geographic supply concentrates in Western Europe, particularly Germany and France, alongside North America. Raw material sourcing depends on botanical raw materials and essential oils from diverse global regions. Single-source vulnerability for rare plant extracts represents a critical structural risk. Distribution runs through both traditional multi-step distributors and emerging direct sourcing models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global organic personal care ingredients market represents a high-growth disruption, driven by the convergence of biotechnology advancements and stricter regulatory mandates like the EU Green Deal.
For Market Incumbents: Build regulatory compliance moats by investing in robust safety substantiation data for novel bioactives. Large suppliers should expand certified organic portfolios and enhance traceability systems. This counters consumer scrutiny and evolving regulatory frameworks such as MoCRA. Strategic R&D in bio-fermentation offers a lever against agricultural supply volatility.
For New Entrants and Emerging Players: Establish a beachhead in underpenetrated segments like men's grooming or Halal-certified ingredients. Niche D2C brands can target consumers seeking specialized, ethically sourced organic ingredients. A compelling go-to-market angle involves transparent narratives around ingredient origin and community impact.
For Investors and Strategic Acquirers: The market sits at a transformative growth phase that favors specialized ingredient innovators with strong intellectual property. Sustained consumer demand for clean labels and regulatory pressure for natural alternatives ensure long-term growth. Acquisition targets include bio-fermentation technology leaders and plant-based extract providers. The signal to watch is progress in global organic standard harmonization.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expanding bio-fermentation facilities enhances supply consistency and reduces dependence on volatile agricultural raw materials. |
| Green Manufacturing Transition | Adopting sustainable processing methods aligns with consumer demand for eco-friendly products and EU Green Deal objectives. |
| Long-term Supply Agreement | Securing contracts for botanical raw materials stabilizes costs and ensures consistent availability for large-scale production. |
| Product Launch | Introducing novel bioactive compounds through biotechnology meets premium anti-aging and dermo-cosmetic formulation needs. |
| Distribution Channel Expansion | Developing direct sourcing partnerships allows brands to build compelling traceability narratives and community impact. |
Research Approach
A standing panel of R&D directors, procurement leads, brand managers, and regulatory affairs specialists provided ongoing calibration for market dynamics. This analysis combined insights from primary interviews with industry stakeholders and secondary validation from sources like EU REACH documents, FDA MoCRA guidelines, and COSMOS certification standards. Bottom-up and top-down triangulation ensured data integrity.
Scenario-bracketing techniques were applied to develop robust market projections across the analysis window. The framework modeled segmentation dimensions including product type, application, end-user, form, and regional regulatory compliance. Compound Annual Growth Rates were derived through regression analysis and market share projections. Consumer preference shifts for clean labels and agricultural yield forecasts served as key inputs.
Stress conditions across climate-related agricultural disruptions and unforeseen regulatory changes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions documented through extensive research. Quarterly review of ingredient pricing and certification updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
North America Prebiotic Ingredients Market
Ingredients
Corn-Based Ingredients Market
Ingredients
Global Pine Pollen Powder Market
Ingredients
Beef Concentrate Market
Ingredients
Citrus Fiber Market
Ingredients
Lactase Enzyme Market
Ingredients
Stock Cubes Market
Ingredients
Wheat Germ Oil Market
Ingredients
Pulses Ingredients Market
Ingredients
Oat Fiber Market
Ingredients
Cacao Bean Market
Ingredients
United States Gelatin Market
Ingredients
Moringa Ingredients Market
Ingredients
Insect-Based Ingredients Market
Ingredients
Global Pulse Flours Market
Ingredients
Banana Essence Market