
 Asia-Pacific Flavor and Fragrance Market | 2026-2036
Asia-Pacific Flavor and Fragrance Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Flavor and Fragrance Market Outlook
Multi-source procurement of botanical raw materials is consolidating across the Asia-Pacific flavor and fragrance supply base. Givaudan leverages its captive cultivation networks in Madagascar and Indonesia to secure vanilla and spice extracts. Huabao International Holdings anchors its position through backward integration into tobacco-flavor precursors and regional manufacturing scale in China.
Flavor and fragrance compounds comprise volatile organic molecules—esters, terpenoids, aldehydes, and phenolics—synthesized through steam distillation, solvent extraction, or microbial fermentation to impart sensory characteristics to consumer products. Essential oils and aroma compounds command premium positioning as clean-label demand intensifies across food and beverage applications. Fragrance oils dominate cosmetics and personal care revenue pools, while flavor enhancers penetrate deepest into mass-market processed food formulations across Southeast Asia.
China's SAMR enforces GB standards on food additive safety and labeling transparency, while Japan's METI governs cosmetic ingredient disclosure under its quasi-drug framework. India's FSSAI mandates contaminant limits for imported flavor raw materials, tightening market access for non-compliant suppliers. Stakeholders must monitor regulatory divergence on natural versus synthetic classification standards to anticipate reformulation costs and sourcing reconfiguration.
Market Dynamics
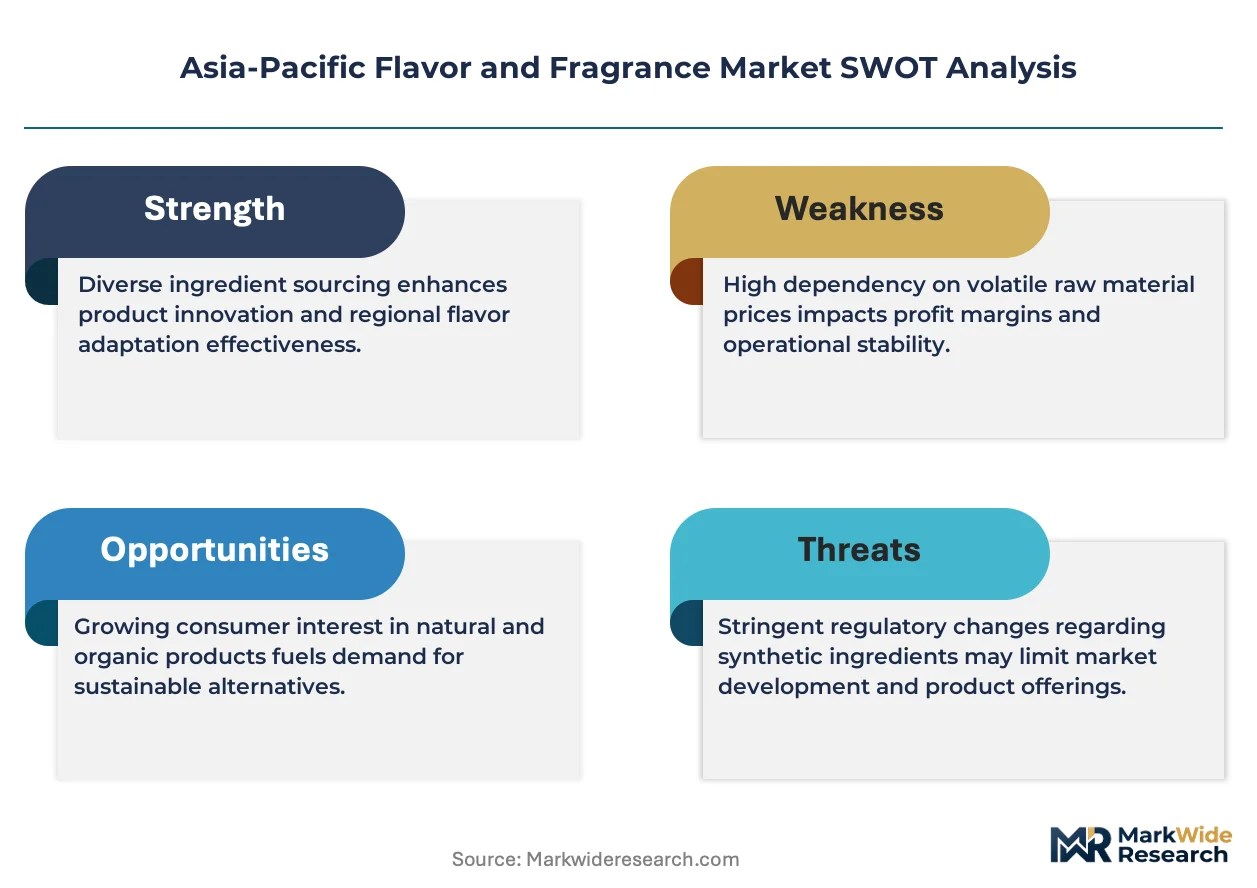
China's SAMR enforcement of GB standards on food additive safety is forcing rapid reformulation across the Asia-Pacific flavor and fragrance supply base, compressing timelines for natural ingredient substitution and reshaping procurement priorities toward compliant sourcing networks.
Growth Catalysts
- Clean-label food mandates:China's GB standards on additive disclosure accelerate demand for natural aroma compounds in processed food formulations. Reformulation investments concentrate in Shanghai and Guangzhou manufacturing clusters.
- Biotechnology fermentation:Microbial synthesis of terpenoids and esters reduces dependency on agricultural harvest volatility. South Korean cosmetic manufacturers adopt biotech-derived fragrance precursors at scale.
- Processed food expansion:Indonesia's import demand for flavor enhancers intensifies as domestic consumption of packaged noodles, snacks, and ready meals accelerates across Java and Sumatra distribution networks.
Market Restraints
- Vanilla supply concentration:Madagascar and Indonesia cultivation networks dominate natural vanilla extract supply, exposing formulators to climate-induced harvest volatility and price spikes.
- Synthetic precursor cost structure:Petrochemical-derived aldehydes and phenolics face feedstock price volatility tied to regional refinery output fluctuations and energy cost pressures.
- Regulatory fragmentation:Divergent natural-versus-synthetic classification standards between China's SAMR, Japan's METI quasi-drug framework, and India's FSSAI create compliance complexity for multi-market suppliers.
Strategic Opportunities
- Vietnam manufacturing expansion:Underdeveloped flavor compounding capacity relative to processed food demand growth creates white space for regional production facilities serving ASEAN distribution networks.
- Biotech-cultivation convergence:Integration of precision fermentation with captive botanical cultivation enables consistent supply of rare spice extracts without agricultural dependency.
- E-commerce direct procurement:Digital platforms bypass traditional distributor layers, allowing mid-sized food manufacturers in Thailand and Malaysia to access specialty aroma compounds directly.
Industry Challenges
- Flavor chemist talent scarcity:Specialized expertise in natural extraction process optimization and regulatory-compliant reformulation remains concentrated in legacy European and Japanese training pipelines.
- Cross-border certification timelines:India's FSSAI contaminant limit testing for imported raw materials extends lead times by 8-14 weeks, disrupting just-in-time manufacturing schedules.
- Legacy equipment retrofit costs:Steam distillation and solvent extraction infrastructure requires capital-intensive upgrades to handle biotech-derived feedstocks and meet evolving purity specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Flavor and Fragrance Market |
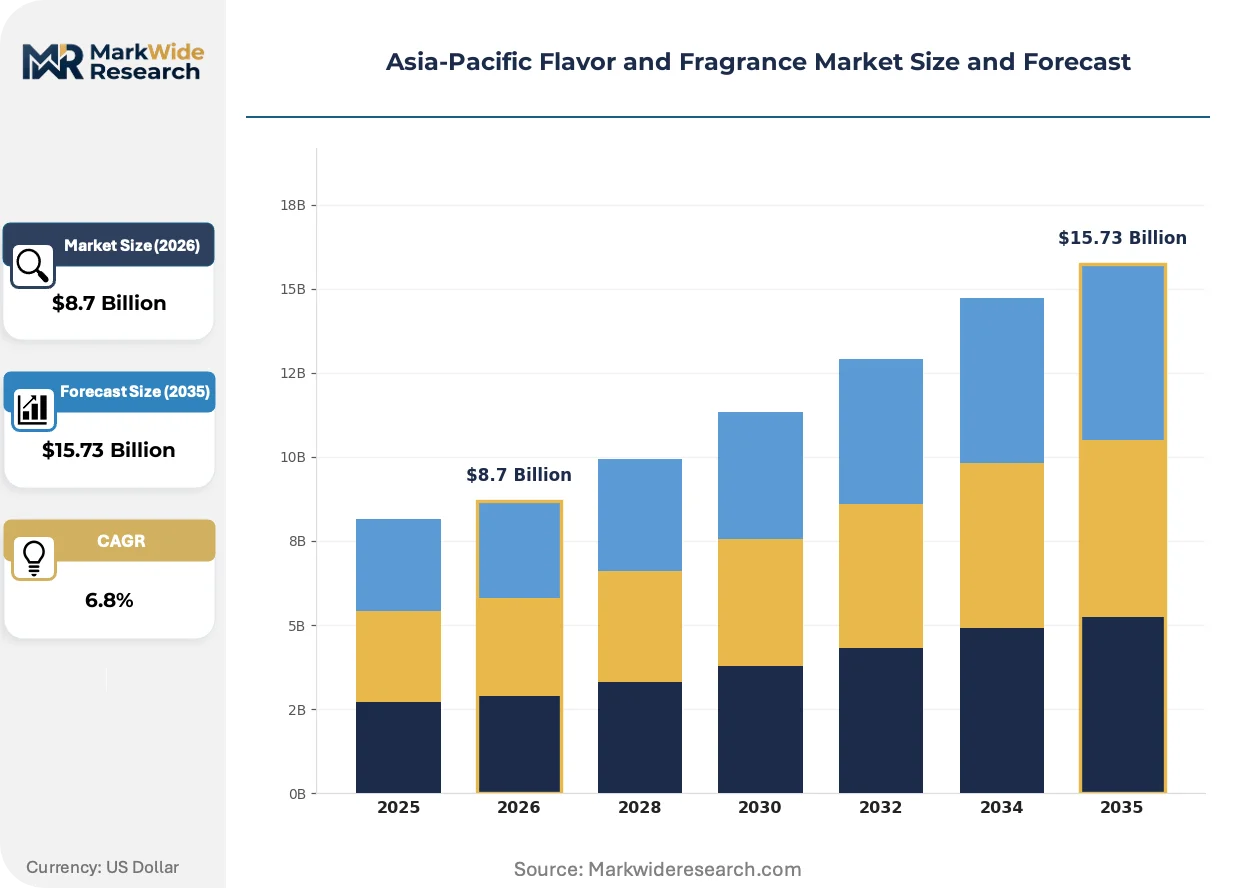
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavor Enhancers, Essential Oils, Aroma Compounds, Fragrance Oils Application: Food & Beverage, Cosmetics, Personal Care, Home Care End User: Manufacturers, Retailers, Wholesalers, Distributors Form: Liquid, Powder, Granular, Paste |
| Companies Covered | Symrise AG, Sensient Technologies Corporation, Givaudan, Huabao International Holdings, MANE, DSM-Firmenich, Takasago International Corporation, Robertet SA, International Flavors & Fragrances Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Flavor and Fragrance Market Strategic Shifts
Biotechnology platforms are compressing the traditional agriculture-to-aroma supply chain, while regulatory transparency mandates and direct procurement digitization reshape how formulators source and specify sensory ingredients across the Asia-Pacific region.
Precision fermentation of terpenoid and ester compounds is unifying the previously separate agricultural and synthetic supply chains for high-value aroma molecules. South Korean premium cosmetic brands and Japanese fragrance houses adopt biotech-derived naturals at accelerated pace. This technology is compressing the 18-24 month cultivation-to-extraction cycle into 4-6 week production runs, enabling supply security independent of harvest volatility.
Japan's METI quasi-drug framework and cosmetic ingredient disclosure rules tighten labeling transparency requirements for fragrance compounds in personal care applications. Manufacturers must now disclose full constituent lists previously protected as proprietary blends. Premium skincare segments in Tokyo and Osaka markets respond by reformulating toward simpler, declarable ingredient palettes that satisfy consumer scrutiny.
Direct platform procurement is displacing traditional distributor intermediaries for specialty aroma compounds. Mid-sized food manufacturers in Thailand, Vietnam, and Malaysia now specify custom flavor profiles through digital channels rather than regional agent networks. This behavioral shift concentrates most visibly in the ASEAN processed food sector, where formulation speed and cost transparency outweigh relationship-based sourcing preferences.
Asia-Pacific Flavor and Fragrance Market Segmentation
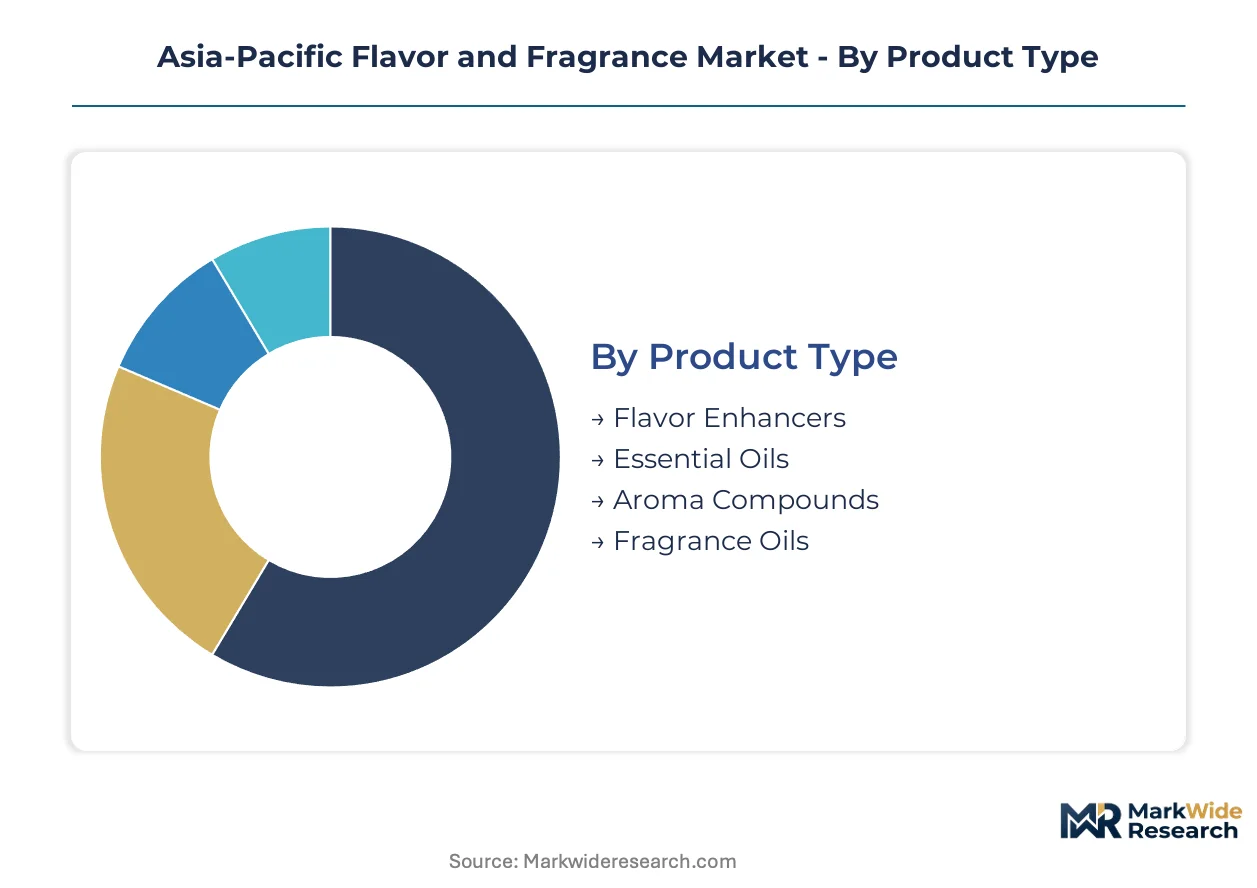
Segmentation in the Asia-Pacific flavor and fragrance market reveals how procurement priorities diverge between mass-market processed food manufacturers and premium cosmetic formulators. Understanding these splits enables suppliers to align production capacity with the distinct technical and regulatory requirements of each buyer tier.
Product Type:
Volume concentration favors commodity-grade inputs, while premium positioning concentrates in specialized extracts and biotech-derived molecules.
- Flavor Enhancers:Monosodium glutamate, nucleotides, and yeast extracts amplify savory perception in processed foods. Demand concentrates in Indonesia's instant noodle and snack manufacturing corridors, where cost-per-unit sensitivity dominates procurement decisions and drives bulk purchasing contracts.
- Essential Oils:Steam-distilled botanical extracts—peppermint, citrus, eucalyptus—carry volatile terpenoid profiles for therapeutic and aromatic applications. South Korean premium cosmetic brands absorb the highest-value grades, with clean-label mandates accelerating substitution of synthetic alternatives in Seoul and Busan formulation labs.
- Aroma Compounds:Isolated molecules including esters, aldehydes, and phenolics deliver precise sensory targeting for beverage and confectionery applications.
- Fragrance Oils:Blended synthetic and natural constituents dominate personal care and home care formulations across mass-market Southeast Asian distribution networks.
Mature deployment sits with Flavor Enhancers. Newer deployment is concentrated in Essential Oils.
Application:
Regulatory stringency separates the segments, with food safety mandates imposing stricter formulation constraints than cosmetic disclosure rules.
- Food & Beverage:Processed food, beverages, and confectionery require compliance with China's SAMR GB standards on additive safety and maximum residue limits. Reformulation investments cluster in Shanghai and Guangzhou manufacturing zones as clean-label mandates accelerate natural ingredient substitution.
- Cosmetics:Skincare, color cosmetics, and fragrances operate under Japan's METI quasi-drug framework, which mandates full constituent disclosure previously protected as proprietary blends. Premium segments in Tokyo and Osaka markets reformulate toward simpler, declarable ingredient palettes.
- Personal Care:Shampoos, soaps, and oral care products absorb mid-tier fragrance compounds across ASEAN mass-market distribution channels.
- Home Care:Detergents, air fresheners, and cleaning products utilize cost-optimized synthetic aroma blends for functional odor masking.
Food & Beverage commands the largest procurement volumes. Cosmetics represents the steepest expansion trajectory as biotech-derived naturals gain formulation share.
End User:
Supply chain length and technical specification intensity distinguish direct manufacturers from intermediary channels.
- Manufacturers:Integrated food and cosmetic producers with in-house formulation capabilities specify custom sensory profiles and maintain direct supplier relationships. These buyers concentrate in China's Yangtze River Delta and Japan's Kansai industrial belt.
- Retailers:Private-label food and personal care brands procure standardized flavor and fragrance compounds through consolidated supplier agreements for cost efficiency.
- Wholesalers:Regional distribution networks aggregate demand from mid-sized formulators across Thailand, Vietnam, and Malaysia, with e-commerce platforms displacing traditional agent relationships.
- Distributors:Specialized chemical distributors maintain inventory buffers and technical support services for smaller manufacturers lacking direct sourcing infrastructure.
Established procurement patterns favor Manufacturers. Emerging channel shifts are concentrated in Wholesalers as digital platforms compress distribution layers.
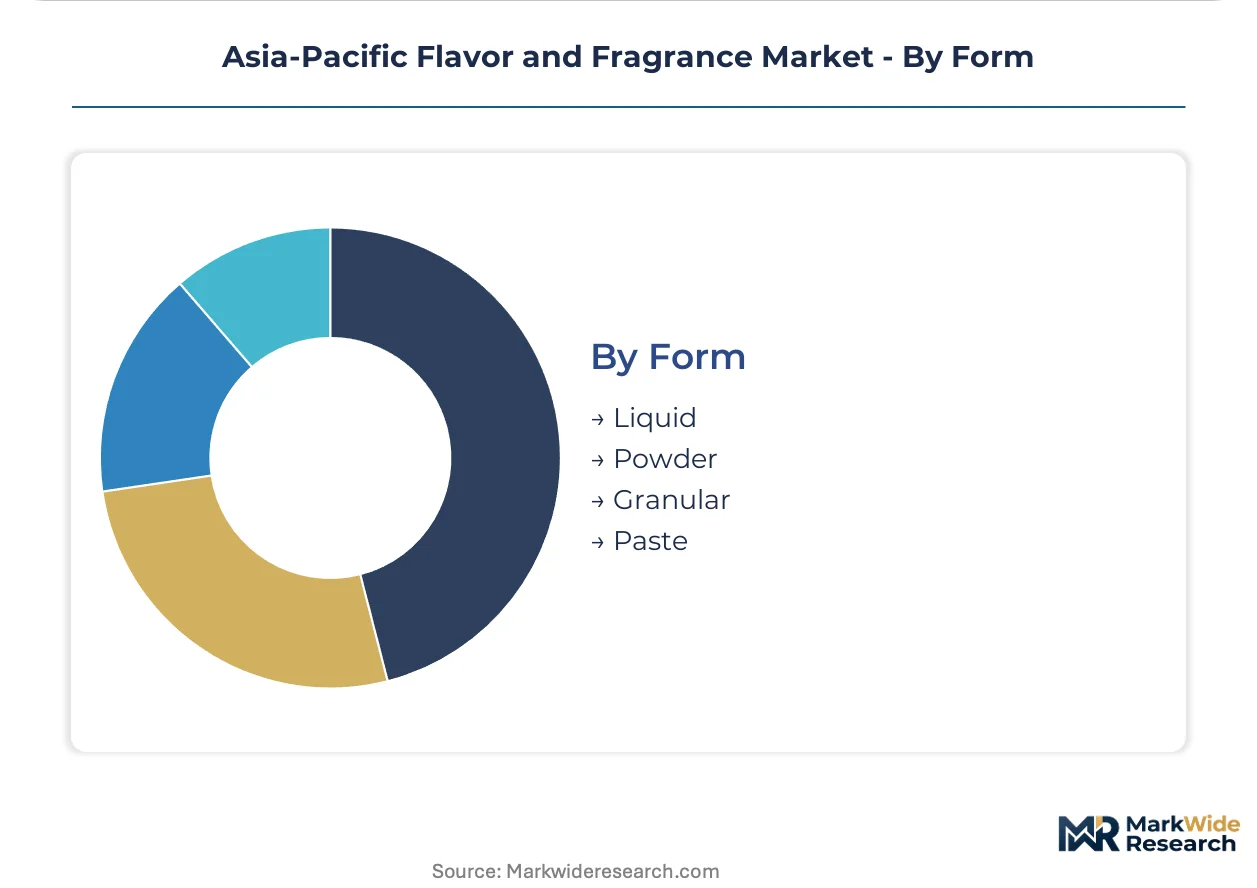
Form:
Processing compatibility and stability requirements drive selection across liquid, solid, and semi-solid delivery systems.
- Liquid:Solvent-based and oil-soluble concentrates enable precise dosing in beverage and cosmetic formulations. South Korean biotech fermentation outputs increasingly supply liquid terpenoid precursors for seamless integration into existing manufacturing lines.
- Powder:Spray-dried and encapsulated formats protect volatile compounds during high-temperature food processing. Indonesian instant noodle manufacturers specify powder formats for shelf-stable seasoning sachets distributed across Java and Sumatra.
- Granular:Free-flowing particulate forms facilitate uniform dispersion in dry food mixes and detergent applications.
- Paste:High-viscosity concentrates serve specialized confectionery and savory paste applications requiring intense localized flavor impact.
Liquid formats anchor current production infrastructure. Powder formats are gaining share fastest in Southeast Asian processed food expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Madagascar and Indonesian vanilla cultivation networks anchor raw material security for Asia-Pacific formulators, while manufacturing gravity concentrates in East Asian industrial clusters responding to divergent national regulatory frameworks.
China
Shanghai and Guangzhou manufacturing corridors absorb the bulk of reformulation investment as SAMR enforces GB standards on food additive safety and labeling transparency. The Yangtze River Delta hosts concentrated flavor compounding capacity serving domestic processed food manufacturers and export-oriented beverage producers. Dual carbon goals under MEE pressure petrochemical-derived synthetic precursor operations toward biotech alternatives.
Japan
Tokyo and Osaka premium skincare markets drive demand for declarable ingredient palettes under METI's quasi-drug framework. Kansai industrial belt maintains heritage fragrance house operations alongside precision fermentation adoption for cosmetic applications. Full constituent disclosure rules previously protected proprietary blends, now accelerating simpler formulation architectures.
South Korea
Seoul and Busan formulation labs lead biotech-derived terpenoid adoption for premium cosmetic brands seeking supply security independent of agricultural harvest cycles. MFDS cosmetic safety standards align with clean-label positioning across domestic and export markets. Domestic fermentation platforms compress cultivation-to-extraction timelines from months to weeks.
Indonesia
Java and Sumatra distribution networks concentrate import demand for flavor enhancers as packaged noodle, snack, and ready meal consumption accelerates. Captive vanilla cultivation in Sulawesi and Papua complements Madagascar sourcing for natural extract security. Processed food sector expansion outpaces domestic compounding capacity, creating procurement bottlenecks.
India
Maharashtra and Gujarat industrial corridors face extended FSSAI contaminant limit testing timelines of 8-14 weeks for imported raw materials, disrupting just-in-time manufacturing schedules. Domestic flavor chemist training pipelines remain underdeveloped relative to formulation demand growth. Import dependency for specialty aroma compounds concentrates procurement risk in Mumbai and Ahmedabad processing hubs.
Asia-Pacific Flavor and Fragrance Market Competitive Environment
Capacity expansion dominates the current landscape as suppliers position fermentation infrastructure and captive cultivation networks to secure biotech-derived feedstock streams. The vendor base stratifies across integrated multinationals with backward cultivation control, regional Chinese specialists leveraging manufacturing scale, and mid-tier ASEAN compounders serving processed food corridors. Three archetypes prevail: biotechnology-forward innovators, botanical supply chain integrators, and commodity flavor enhancer producers. Geographic expansion and strategic partnerships constitute the dominant competitive vectors as players navigate regulatory fragmentation across SAMR, METI, and FSSAI jurisdictions.
Within the biotechnology-forward tier, Givaudan and DSM-Firmenich exemplify integrated players combining precision fermentation capabilities with captive botanical networks. Huabao International Holdings occupies a position among China-based specialists with regional manufacturing scale and tobacco-flavor precursor integration. Symrise AG and Takasago International Corporation represent heritage fragrance houses adapting formulation portfolios toward declarable ingredient architectures demanded by Japanese and South Korean premium cosmetic markets.
| Leading Market Players |
|---|
| Symrise AG |
| Sensient Technologies Corporation |
| Givaudan |
| Huabao International Holdings |
| MANE |
| DSM-Firmenich |
| Takasago International Corporation |
| Robertet SA |
| International Flavors & Fragrances Inc. |
| Others |
Value Chain & Pricing Dynamics
Precision fermentation of terpenoid and ester compounds is compressing cost economics from 18-24 month cultivation cycles to 4-6 week production runs, simultaneously fragmenting pricing power away from Madagascar vanilla cultivators toward South Korean biotech platforms while concentrating supply control in fermentation-capable manufacturing clusters.
Pricing Analysis
Technical service bundling separates premium aroma compound suppliers from commodity traders, with formulation support, regulatory documentation, and stability testing included in premium contracts while economy-tier transactions remain strictly product-only. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under China's SAMR GB standards and volume scale commitments. Cost compression in economy-tier flavor enhancers is intensifying because Indonesian instant noodle manufacturers consolidate procurement through bulk purchasing contracts. Processed food manufacturers across Java and Sumatra exhibit highest price sensitivity, while South Korean premium cosmetic brands absorb premium pricing for biotech-derived naturals with minimal volume negotiation.
Supply Chain Analysis
Flavor chemist talent scarcity in Shanghai, Guangzhou, and Jakarta manufacturing corridors constrains compounding capacity expansion relative to demand growth across ASEAN processed food networks. Raw material dependencies center on Madagascar and Sulawesi vanilla cultivation, Chinese petrochemical-derived synthetic precursors, and South Korean fermentation outputs. Single-source vulnerability in natural vanilla extract exposes formulators to climate-induced harvest volatility and price spikes. Distribution runs through specialized chemical distributors maintaining inventory buffers for smaller manufacturers, with e-commerce platforms displacing traditional agent relationships in Thailand and Malaysia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's SAMR enforcement of GB standards on food additive safety and labeling transparency constructs a cost-of-compliance barrier that favors incumbent suppliers with established regulatory affairs infrastructure and captive testing capabilities.
For Market Incumbents: Anchor market position through backward integration into captive botanical cultivation networks in Madagascar and Indonesia, securing vanilla and spice extract supply independent of spot market volatility. Expand precision fermentation capacity in South Korean and Chinese manufacturing clusters to capture biotech-derived terpenoid demand from premium cosmetic formulators. Defend against emerging biotechnology specialists by accelerating proprietary strain development and locking long-term offtake agreements with Seoul and Busan formulation labs. For New Entrants and Emerging Players: The 40-60% price-point gap between Givaudan-grade premium naturals and Indonesian commodity flavor enhancers creates entry space for mid-tier biotech-cultivation hybrid suppliers. Target Vietnam's underdeveloped flavor compounding capacity relative to processed food demand growth, where domestic manufacturers currently import from Thai and Malaysian distributors. Pursue direct platform procurement relationships with mid-sized ASEAN food manufacturers seeking cost transparency and formulation speed over established distributor relationships. For Investors and Strategic Acquirers: Re-rating potential sits with biotechnology-forward innovators possessing precision fermentation capabilities and captive botanical networks, given accelerating clean-label mandates across Chinese and South Korean regulatory frameworks. Long-term viability centers on suppliers capable of serving both SAMR-compliant food formulations and METI-aligned cosmetic disclosure requirements without facility duplication. Monitor FSSAI contaminant limit testing timeline reductions as the inflection signal for India's market access liberalization and just-in-time manufacturing normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Cultivation | Madagascar and Indonesian vanilla networks secure supply against climate volatility for Asia-Pacific formulators. |
| Precision Fermentation Scale-Up | South Korean biotech platforms compress terpenoid production cycles from months to weeks for cosmetic applications. |
| Regulatory Certification Investment | GB standards compliance under SAMR creates defensible positioning in Chinese processed food manufacturing corridors. |
| Direct Platform Procurement Launch | Digital channels bypass Thai and Malaysian distributor layers for mid-sized ASEAN food manufacturer access. |
| Vietnam Manufacturing Expansion | Underdeveloped compounding capacity relative to demand growth creates white space for ASEAN distribution serving. |
Study Parameters
Trade databases, regulatory filing repositories, and industry association publications formed the secondary backbone, supplemented by primary interviews with flavor chemists, cosmetic formulation directors, processed food procurement leads, and chemical distribution channel managers. Bottom-up and top-down triangulation validated volume estimates across product type, application, and regional segments. Primary fieldwork concentrated in Shanghai, Guangzhou, Seoul, Busan, Jakarta, and Mumbai manufacturing corridors.
Bottom-up modeling aggregated individual product-line volumes across flavor enhancers, essential oils, aroma compounds, and fragrance oils, while top-down cross-checks applied macroeconomic consumption indicators and trade flow analysis. Segmentation dimensions included product type, application, end user, and form, with biotech-versus-agricultural sourcing origin as an industry-specific overlay. CAGRs were derived from regression analysis of historical consumption patterns and projected regulatory-driven substitution effects.
Inputs from SAMR regulatory bulletins, METI cosmetic ingredient disclosure updates, and FSSAI contaminant limit protocols were available through the study window; gaps in real-time fermentation platform capacity disclosures introduce uncertainty bands around biotech-derived supply projections. Forecasts reflect documented assumptions regarding clean-label mandate enforcement timelines and climate-induced agricultural harvest variability. Material deviation in SAMR GB standards implementation pace or FSSAI testing timeline normalization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Natural Food Colors and Flavors Market
Flavorings and Food Additives
Apple Essence Market
Flavorings and Food Additives
Orange Peel Extract Market
Flavorings and Food Additives
Vanillin Market
Flavorings and Food Additives
Botanical Flavors Market
Flavorings and Food Additives
Flavor Masking Agents Market
Flavorings and Food Additives
Taste Modulators Market
Flavorings and Food Additives
Blueberry Extract Market
Flavorings and Food Additives
Global Beverage Flavoring Systems Market
Flavorings and Food Additives
Sour Cream Powder Market
Flavorings and Food Additives
Food-Grade Gellan Gum Market
Flavorings and Food Additives
Browning Solutions Market
Flavorings and Food Additives
United States Food Colorants Market
Flavorings and Food Additives
Oryzanol Market
Flavorings and Food Additives
Anthocyanin Food Colors Market
Flavorings and Food Additives
Winter Melon Peel Extract Market