
 Global Pulse Flours Market | 2026-2036
Global Pulse Flours Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pulse Flours Market Outlook
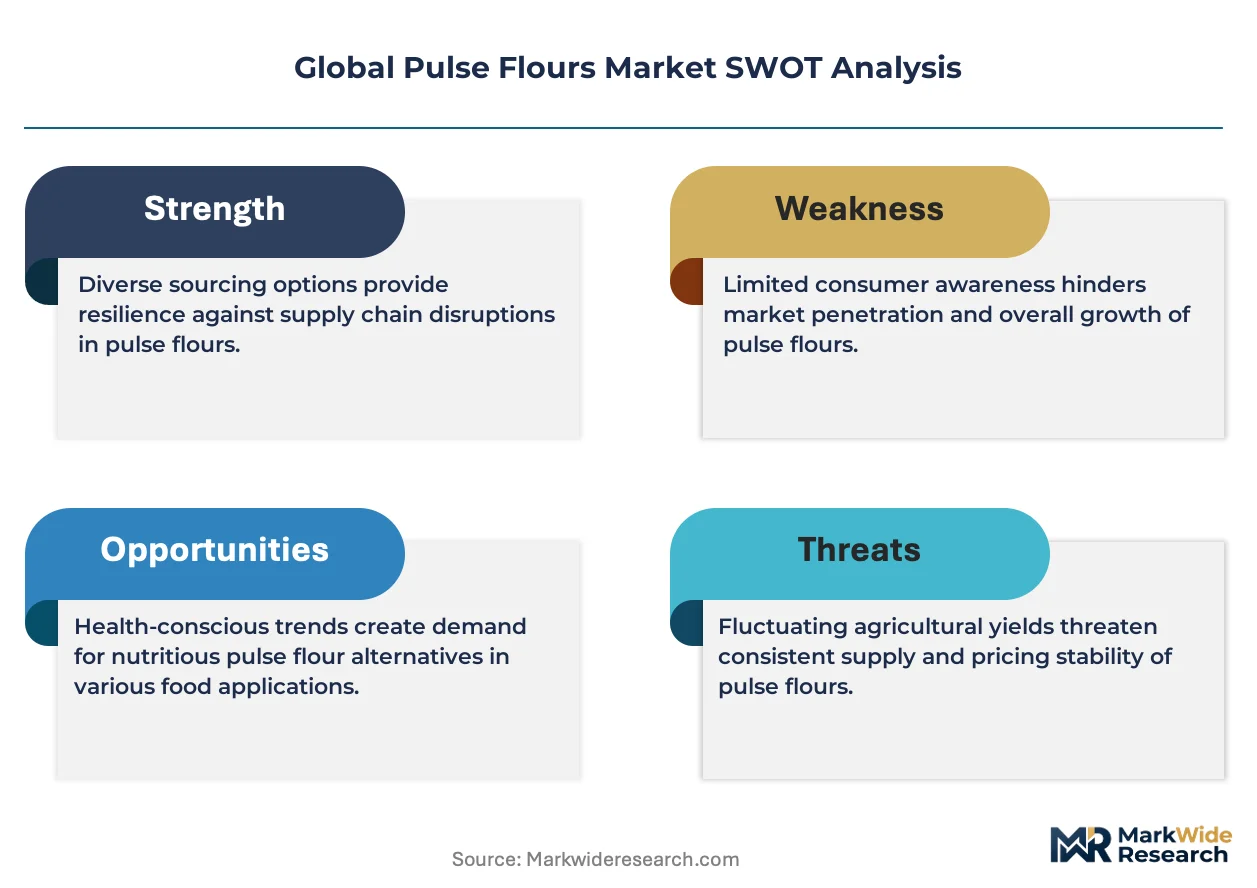
Asset-light contract milling arrangements is reconfiguring competitive entry barriers for smaller processors. Cargill Incorporated leverages its global grain handling infrastructure to secure raw pulse supply chains. Ingredion Incorporated anchors its position through specialty starch blending capabilities that enhance pulse flour functionality. The Archer-Daniels-Midland Company competes via integrated oilseed and pulse processing networks spanning multiple continents.
Pulse flours denote finely milled powders derived from dried legume seeds, typically containing 20-25% protein and exhibiting water-binding capacities between 1.5-2.5 g/g depending on source species and particle size distribution. These flours primarily serve as protein fortification agents, gluten replacement matrices, and viscosity-modifying ingredients across formulated food systems. Chickpea flour occupies the dominant volume position due to its neutral flavor profile and established supply chains across South Asian and Mediterranean origins. Pea flour represents the fastest-expanding category, driven by its allergen-friendly status and clean-label positioning within plant-based meat analog formulations. The baking application segment commands the deepest margin pools, where premium pricing attaches to certified organic and non-GMO verified pulse flour grades.
The FDA governs pulse flour safety through Food Safety Modernization Act preventive controls, while the USDA administers organic certification standards that command price premiums in North American retail channels. India's FSSAI enforces fortification standards and labeling requirements that directly shape product formulations for domestic and export markets. Stakeholders must monitor evolving protein content thresholds in regulatory definitions, as these specifications determine market access qualifications and competitive positioning across jurisdictions.
Market Dynamics
Gluten-free bakery applications are accelerating adoption among food manufacturers, while the FDA's updated labeling standards for plant-based proteins are reshaping product certification requirements across supply chains.
Growth Catalysts
- FDA Labeling Standards:The FDA's updated plant protein certification requirements are forcing manufacturers to reformulate with verified pulse flour grades, expanding demand for certified organic and non-GMO verified supply.
- India's Processing Base:Chickpea flour anchors traditional and industrial food processing in India, where FSSAI fortification standards create structured demand pull for domestic and export markets.
- Clean-Label Positioning:Pea flour's allergen-friendly status is displacing soy and wheat derivatives in plant-based meat analog formulations across North American and European retail channels.
Market Restraints
- Raw Pulse Volatility:Chickpea and yellow pea prices fluctuate with monsoon-dependent Indian harvests and Canadian prairie yields, compressing margins for processors lacking long-term supply contracts.
- Functional Limitations:Pulse flours exhibit bitter off-notes and variable water-binding capacity (1.5-2.5 g/g) that restrict inclusion rates in delicate bakery applications without expensive masking systems.
- Organic Certification Bottlenecks:USDA organic transition timelines and inspection backlogs delay market access for new entrants seeking premium pricing in North American retail.
Strategic Opportunities
- Brazilian Market Entry:ANVISA's evolving plant protein framework creates first-mover advantage for processors establishing localized milling capacity ahead of regulatory harmonization.
- Extruded Snack Applications:High-protein extruded products represent underexploited demand, with pulse flours enabling 20-25% protein claims in savory snack formats targeting gym-channel distribution.
- EU Green Deal Alignment:The EU Green Deal's protein diversification targets and farm-to-fork strategy incentivize pulse cultivation subsidies that reduce input costs for European processors.
Industry Challenges
- Specialized Milling Talent:Particle size optimization for specific applications (fine for beverages, coarse for textured products) requires expertise in air classification and hammer mill tuning that remains scarce outside established processing clusters.
- Legacy Equipment Retrofit Costs:Wheat-dominant mills face capital-intensive cleanout protocols and cross-contamination prevention systems to achieve gluten-free certification for pulse flour production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pulse Flours Market |
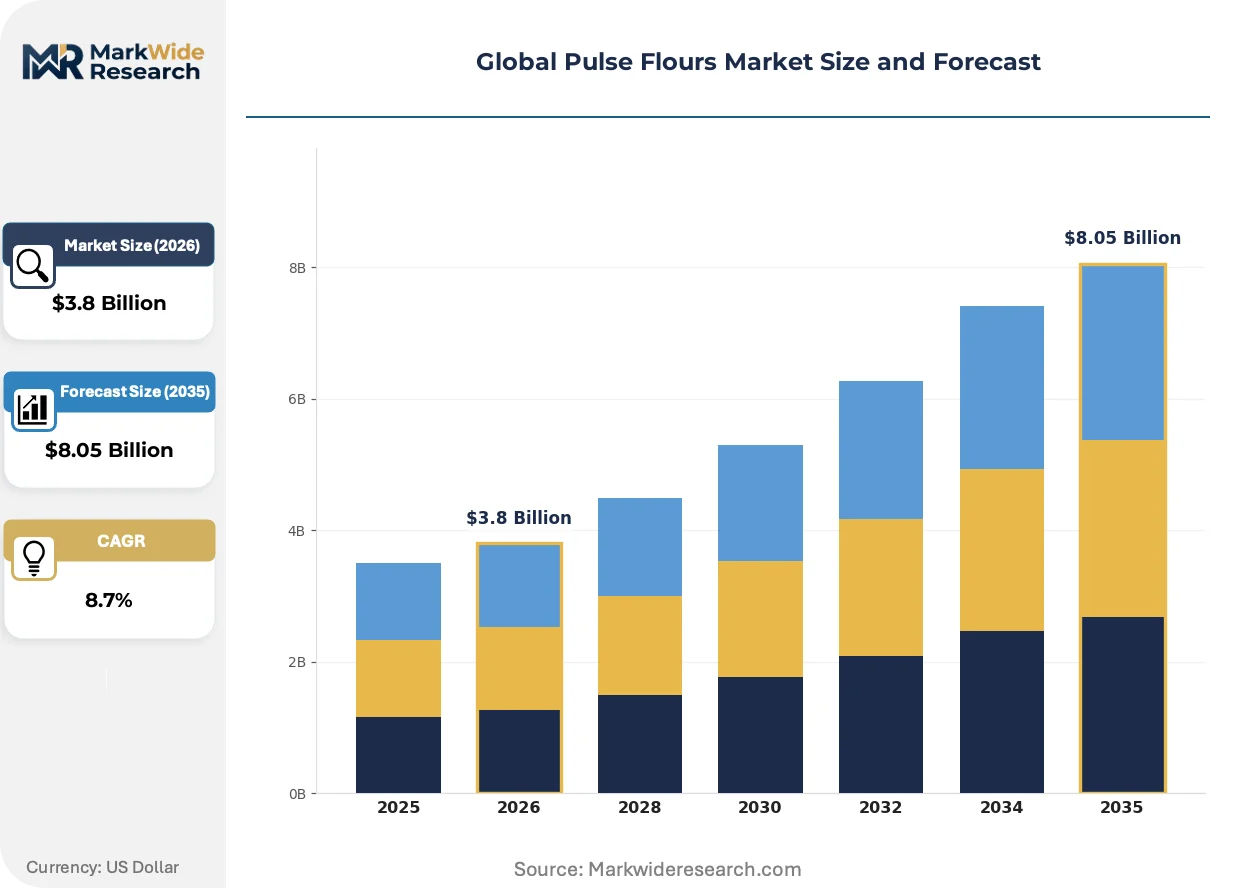
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chickpea Flour, Lentil Flour, Pea Flour, Fava Bean Flour Application: Baking, Snacks, Pasta, Soups Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service End User: Households, Food Manufacturers, Restaurants, Bakeries |
| Companies Covered | Ingredion Incorporated, Groupe Limagrain Holding SA, Cargill Incorporated, SunOpta Inc., Blue Ribbon LLC, The Archer-Daniels-Midland Company, Ardent Mills, Minsa Corporation, Bunge Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pulse Flours Market Strategic Shifts
Extrusion technology and precision fractionation are compressing the functional gap between commodity pulse flours and specialized protein isolates, altering procurement hierarchies across formulated food sectors.
Air classification systems paired with electrostatic separation are rendering obsolete traditional wet-fractionation methods for protein concentration. Plant-based meat manufacturers in the Netherlands and Germany are adopting these dry processes at commercial scale. The capital efficiency of dry fractionation is compressing entry barriers for mid-cap processors previously excluded from isolate-grade supply.
The EU's F-Gas Regulation and accompanying sustainability disclosure requirements under CSRD are mandating carbon footprint tracking across agricultural inputs. Pulse flour suppliers to European bakery and meat analog producers must now document scope 3 emissions from farm to mill. German and French buyers are responding by consolidating procurement around processors with verified lifecycle data.
Direct contracting between food manufacturers and pulse grower cooperatives is shortening traditional grain elevator intermediation. Large North American bakery chains now source identity-preserved yellow peas through Saskatchewan-based aggregators, bypassing commodity terminals. This disintermediation concentrates in the US Midwest and Canadian prairie provinces where traceability infrastructure exists.
Global Pulse Flours Market Segmentation
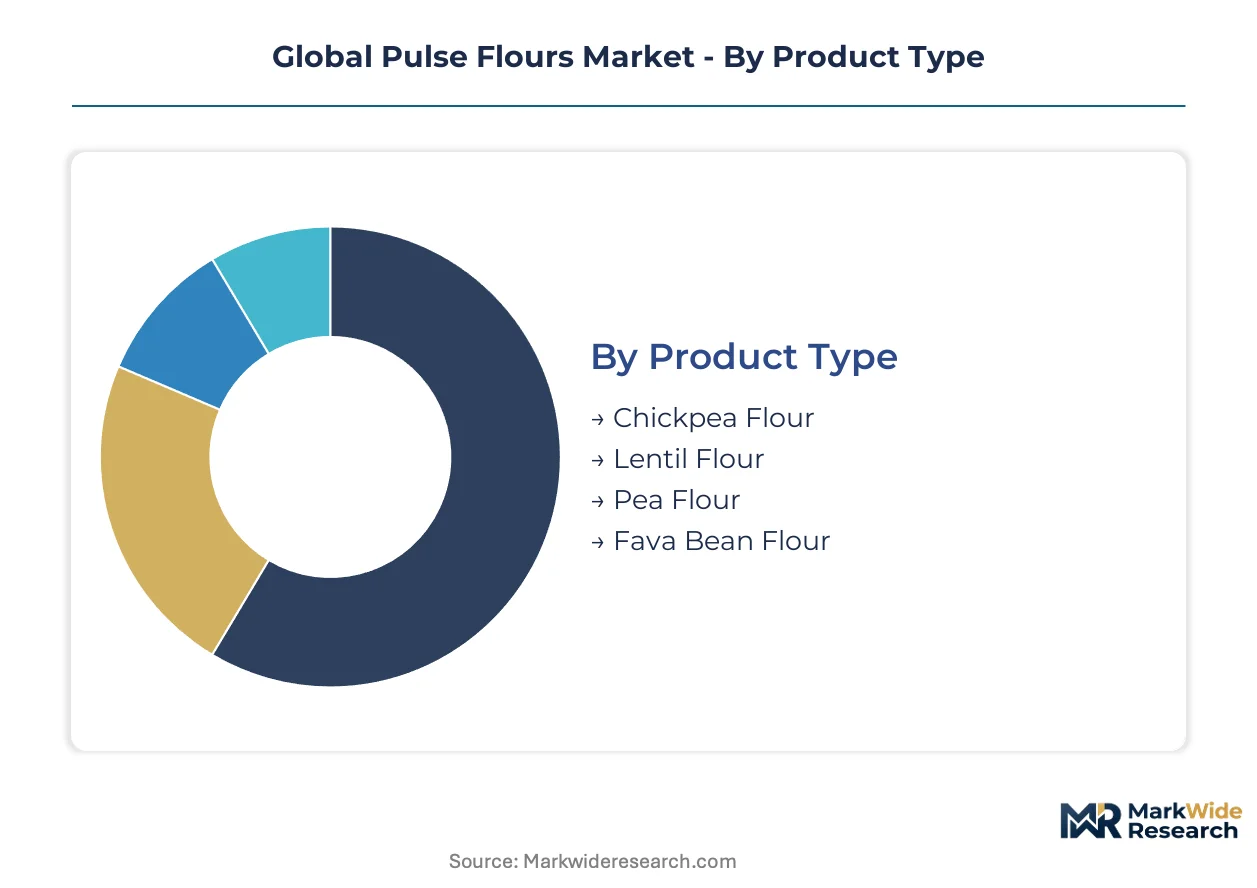
Pulse flour procurement varies sharply by segment, with protein content thresholds and particle size specifications determining supplier qualification. Manufacturers segment their portfolios to capture divergent margin pools across commodity feedstock and premium functional grades.
Product Type:
Mature categories dominate volume throughput while emerging species gain traction in clean-label formulations.
- Chickpea Flour:Finely milled powder containing 20-25% protein with neutral flavor profile and established supply chains across South Asian and Mediterranean origins. Demand concentrates in India where FSSAI fortification standards create structured demand pull for domestic and export markets.
- Pea Flour:Allergen-friendly protein source displacing soy and wheat derivatives in plant-based meat analog formulations. North American and European retail channels are absorbing supply fastest as clean-label positioning accelerates reformulation away from legacy protein sources.
- Lentil Flour:Higher fiber variant with distinct earthy notes suited to savory applications and ethnic cuisine segments.
- Fava Bean Flour:Emerging specialty grade with elevated protein concentration targeting premium nutrition bar and beverage fortification.
Chickpea flour handles the majority of throughput; pea flour is the fastest mover on share.
Application:
Cost tier differentiation separates commodity bulk sales from premium certified grades commanding price multiples.
- Baking:Gluten-free matrix applications requiring fine particle distribution below 150 microns for cake and bread formulations. Certified organic and non-GMO verified grades attach premium pricing in North American retail channels where FDA labeling standards force verified ingredient sourcing.
- Snacks:Extruded high-protein formats enabling 20-25% protein claims in savory products targeting gym-channel distribution. Netherlands and Germany manufacturers are adopting dry fractionation at commercial scale for these applications.
- Pasta:Semolina replacement in gluten-free durum wheat alternatives, with Italian and Brazilian processors leading formulation development.
- Soups:Viscosity modification and protein fortification in ready-to-serve formats, particularly across Indian and Middle Eastern product lines.
Baking commands the deepest margin pools; snacks are climbing the fastest on volume absorption.
Distribution Channel:
Customer type determines service level requirements and certification documentation intensity.
- Supermarkets:Mass retail placement requiring USDA organic verification and non-GMO Project certification for shelf positioning in North American and European stores.
- Food Service:Bulk institutional supply with specification adherence to HACCP protocols and allergen management systems for restaurant chain procurement.
- Online Retail:Direct-to-consumer channels emphasizing subscription models and specialty diet positioning.
- Specialty Stores:Health food and ethnic grocery placement with localized branding and smaller pack formats.
Supermarkets handle the majority of throughput; food service is gaining share fastest through contract consolidation.
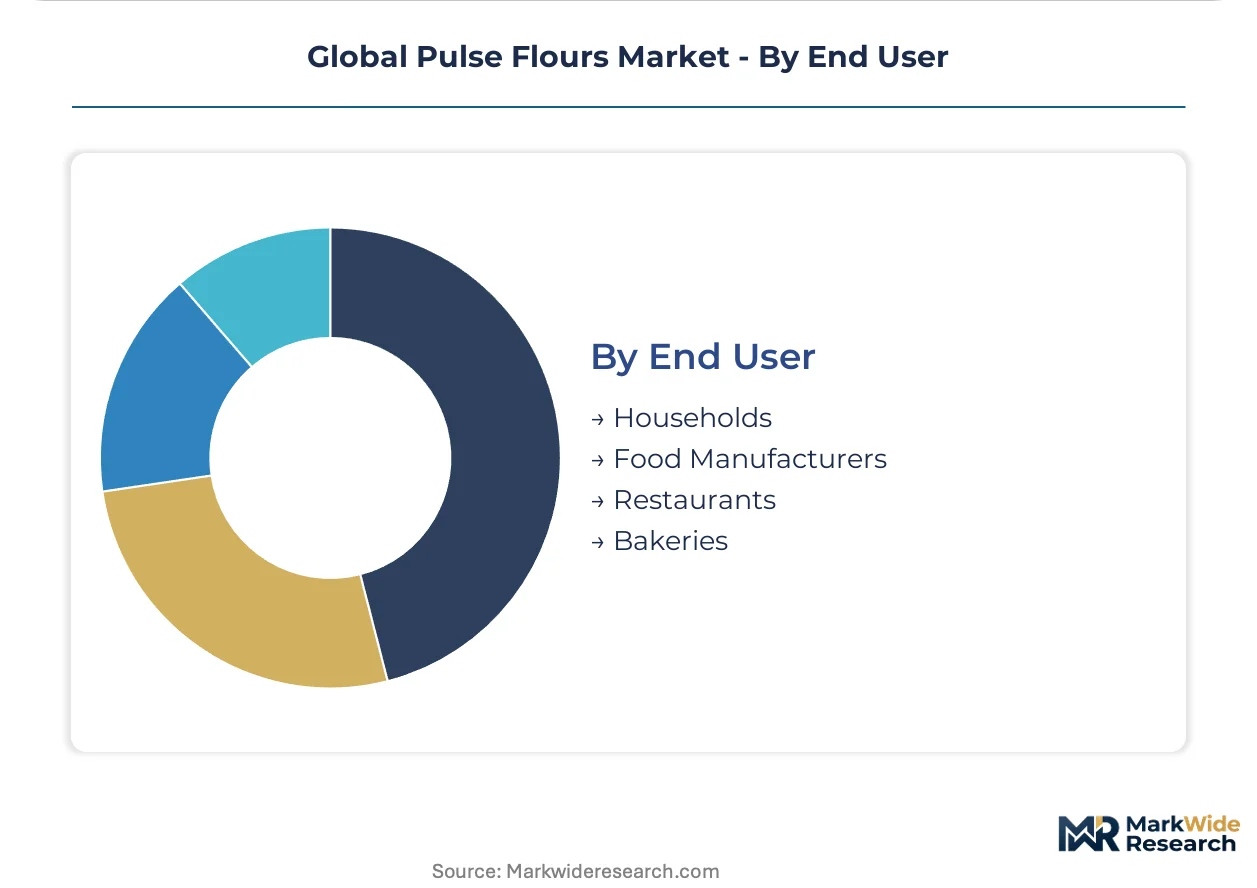
End User:
Supply concentration shapes procurement power and specification stringency across buyer categories.
- Food Manufacturers:Industrial-scale buyers with dedicated R&D teams formulating pulse flours into plant-based meat analogs, gluten-free baked goods, and extruded snacks. These stakeholders drive volume and set functional specifications that ripple through supplier tiers.
- Bakeries:Artisan and commercial operations requiring certified gluten-free supply chains with documented cleanout protocols and cross-contamination prevention systems.
- Restaurants:Menu innovation in fast-casual and fine dining segments incorporating pulse flour for protein claims and dietary accommodation.
- Households:Consumer-packaged goods purchasers influenced by clean-label marketing and ethnic cuisine preparation trends.
Food manufacturers handle the majority of throughput; bakeries are expanding most quickly on certified-grade demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented processors in India and Canada dominate international trade flows, while import-dependent European and Asian markets absorb premium grades. Trade balances reflect divergent agricultural endowments and processing capacities across major economies.
United States
Yellow pea demand from plant-based meat manufacturers drives procurement through Midwest grain elevators and Saskatchewan-based aggregators. The FDA's updated plant protein certification requirements force verified sourcing documentation for retail-grade supply. Minneapolis and Chicago anchor North American trading infrastructure for identity-preserved pulse flows.
India
Chickpea flour anchors domestic consumption and export processing for South Asian and Middle Eastern markets. FSSAI fortification standards and labeling requirements shape product formulations targeting both local retail and overseas buyers. Gujarat and Rajasthan processing clusters handle the majority of desi and kabuli chickpea milling capacity.
Germany
Bakery and meat analog manufacturers absorb certified organic pulse flours under EU Green Deal protein diversification targets. The F-Gas Regulation and CSRD sustainability disclosure requirements mandate carbon footprint documentation from farm to mill. Cologne and Hamburg processors lead dry fractionation adoption for extruded snack applications.
Brazil
ANVISA's evolving plant protein framework creates regulatory runway for localized milling investment ahead of harmonization with Mercosur standards. Domestic food manufacturers reformulate with pea and fava bean derivatives for clean-label positioning. São Paulo and Paraná agricultural zones expand pulse cultivation under federal crop diversification incentives.
Netherlands
European headquarters for multinational food manufacturers concentrate R&D procurement of functional pulse ingredients. EFSA novel food approvals and REACH compliance requirements filter supplier qualification for isolate-grade applications. Wageningen and Rotterdam clusters integrate precision fractionation technology with port logistics for intra-EU distribution.
Global Pulse Flours Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying certified grades and functional concentrates. The vendor base stratifies between multinational grain handlers with captive pulse supply and mid-cap millers focused on organic certification premiums. Three archetypes dominate: integrated agribusiness conglomerates with global origination networks, specialty ingredient platforms blending pulse starches with hydrocolloids, and regional organic processors leveraging identity-preserved contracting. Capacity expansion and backward integration into grower cooperatives constitute the primary competitive vectors.
Within the integrated agribusiness tier, Cargill Incorporated and The Archer-Daniels-Midland Company exemplify scale-driven positioning through grain handling infrastructure spanning multiple continents. Ingredion Incorporated anchors the specialty ingredient archetype, representing functionality-focused players that enhance pulse flour performance through starch blending capabilities. Among North American millers, Ardent Mills occupies a position bridging commodity supply and certified gluten-free production protocols.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Groupe Limagrain Holding SA |
| Cargill Incorporated |
| SunOpta Inc. |
| Blue Ribbon LLC |
| The Archer-Daniels-Midland Company |
| Ardent Mills |
| Minsa Corporation |
| Bunge Limited |
| Others |
Value Chain & Pricing Dynamics
Gujarat's chickpea processing clusters anchor global supply capacity, with their monsoon-dependent harvest cycles transmitting volatility directly into North American and European spot markets. This geographic concentration grants established millers with long-term grower contracts outsized leverage in price negotiations with downstream food manufacturers.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure that dominates procurement above spot-market transactions. Three-tier pricing structure across premium, standard, and economy levels separates certified organic and non-GMO verified grades from commodity feedstock, with USDA organic transition timelines and inspection backlogs compressing availability at the top tier. Cost compression in standard grades is intensifying because Indian and Canadian harvest variability forces processors to absorb margin erosion rather than pass through raw pulse volatility. Bakeries and artisan food manufacturers exhibit the highest price sensitivity due to limited formulation flexibility, while multinational plant-based meat analog producers demonstrate lowest sensitivity given their ability to reformulate across protein sources.
Supply Chain Analysis
Asset-light contract milling arrangements concentrate processing capacity among Cargill Incorporated, The Archer-Daniels-Midland Company, and Ardent Mills, with these operators controlling the majority of North American identity-preserved pulse flows. Supply draws from India, Canada, and Australia as primary origination points, with raw material dependencies centering on desi and kabuli chickpea varieties, yellow peas, and specialty lentil grades. Single-source vulnerability runs through Saskatchewan-based aggregators that bypass commodity terminals for direct contracting with food manufacturers. Distribution runs through Minneapolis and Chicago trading infrastructure for North American flows, with Rotterdam and Hamburg anchoring European import logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment around FDA plant protein certification and FSSAI fortification standards creates durable barriers against unqualified supply.
For Market Incumbents: Insulate margin pools by deepening backward integration into Saskatchewan and Gujarat grower cooperatives, securing identity-preserved supply chains that emerging competitors cannot replicate without multi-year contracting lead times. Expand certified organic milling capacity ahead of USDA inspection backlog resolution, capturing price premiums as demand outstrips verified supply. The threat of dry fractionation technology adoption by mid-cap processors demands accelerated R&D investment in precision air classification systems to maintain functional ingredient superiority. For New Entrants and Emerging Players: Build out localized milling capacity in Brazil's São Paulo and Paraná zones ahead of ANVISA regulatory harmonization, exploiting first-mover positioning before integrated agribusiness conglomerates establish regional infrastructure. Target extruded snack applications as the most penetrable segment, where gym-channel distribution demands 20-25% protein claims that pulse flours uniquely satisfy. A go-to-market angle emphasizing carbon footprint documentation aligned with EU CSRD requirements differentiates offering for German and French bakery procurement teams. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty ingredient platforms with starch blending capabilities that enhance pulse flour functionality beyond commodity milling. Long-term viability rests on consolidation of mid-cap organic processors lacking capital to scale dry fractionation adoption, with acquisition premiums attaching to verified lifecycle data infrastructure. The signal to watch is EFSA novel food approval velocity for fava bean protein concentrates, which would resegment procurement hierarchies and elevate isolate-grade supplier valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grower Cooperatives | Secures identity-preserved supply chains against raw pulse volatility from monsoon-dependent Indian harvests. |
| Certified Organic Capacity Expansion | Captures price premiums as FDA labeling standards force verified sourcing for retail-grade pulse flour. |
| Dry Fractionation Technology Adoption | Compresses entry barriers for mid-cap processors seeking isolate-grade supply parity with wet-fractionation incumbents. |
| Carbon Footprint Documentation Systems | Meets EU CSRD and F-Gas Regulation mandates that German and French buyers now require for procurement consolidation. |
| Extruded Snack Application Development | Enables 20-25% protein claims in savory formats targeting underexploited gym-channel distribution networks. |
Study Parameters
Desk research of FDA regulatory filings, FSSAI fortification standards, EU Green Deal policy documents, and trade flow databases preceded structured interviews with pulse mill operations managers, food manufacturer R&D directors, organic certification auditors, and grain elevator procurement leads. Primary fieldwork with Saskatchewan-based aggregators and Gujarat processing cluster supervisors validated secondary data on supply chain configuration. Bottom-up volume modeling across product type, application, and end-user segments was cross-checked against top-down trade statistics from customs authorities.
Assumptions around FDA plant protein certification timelines, FSSAI enforcement intensity, and EU subsidy disbursement rates were held fixed across scenarios while raw pulse yield variability and organic transition timelines were stress-tested. Segmentation dimensions modeled include product species, particle size grade, certification tier, and regional regulatory cluster. CAGRs were derived from trend extrapolation of historical procurement patterns adjusted for identified inflection drivers. Forecast inputs incorporated air classification technology adoption curves and direct contracting disintermediation rates between food manufacturers and grower cooperatives.
Stress conditions across Indian monsoon deviation ranges, Canadian prairie drought frequency, and EU import tariff trajectories were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factors including regulatory approval delays for novel pulse species and accelerated plant-based meat analog formulation shifts. Quarterly review of EFSA novel food approval queues, ANVISA regulatory harmonization progress, and organic certification inspection backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Edible Fiber Market
Ingredients
Carrot Fiber Market
Ingredients
Global Egg Yolk Oil Market
Ingredients
North America Carrageenan Market
Ingredients
Aroma Ingredients Market
Ingredients
Soluble Fibers Market
Ingredients
Zea Mays Starch Market
Ingredients
Jojoba Oil Market
Ingredients
Global Pea Protein Ingredients Market
Ingredients
Peanut Ingredients Market
Ingredients
Astragalus Root Extract Market
Ingredients
Arachidonic Acid Market
Ingredients
Baobab Powder Market
Ingredients
Medium-Chain Triglyceride (MCT) Fat Market
Ingredients
Proteose Peptone Market
Ingredients
Lupin Flour Market