
 Middle East and Africa Fruit and Vegetable Ingredients Market | 2026-2036
Middle East and Africa Fruit and Vegetable Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Fruit and Vegetable Ingredients Market Insights
Asset-light toll processing and third-party contract manufacturing is reconfiguring competitive entry barriers for ingredient suppliers across the Middle East and Africa. Döhler Group leverages its regional blending facilities to serve beverage clients without captive agricultural holdings. AGRANA Beteiligungs-AG anchors its position through backward integration into European fruit sourcing that feeds African processing lines. Olam International competes via its established spice and nut distribution corridors, extending into vegetable ingredient logistics.
Fruit and vegetable ingredients encompass minimally processed raw materials—concentrates, purees, powders, and dried pieces—retaining natural color, flavor, and nutritional profiles through controlled thermal treatment or dehydration, primarily serving as functional inputs for formulated foods and beverages. Puree and juice concentrate categories dominate volume flows into beverage applications, where manufacturers prioritize soluble solids content and brix consistency for stable shelf-life performance. Dried ingredients sustain premium positioning in snack and bakery channels, where water activity specifications below 0.60 determine storage stability and texture retention.
Saudi Food and Drug Authority (SFDA) halal certification mandates and UAE Ministry of Health and Prevention (MOHAP) food additive regulations are tightening contaminant thresholds and labeling requirements for imported fruit and vegetable inputs. South Africa's Department of Health fortification standards govern micronutrient levels in processed vegetable ingredients distributed through retail channels. Stakeholders must monitor evolving Gulf standardization harmonization and carbon footprint disclosure rules affecting European supplier competitiveness.
Market Dynamics
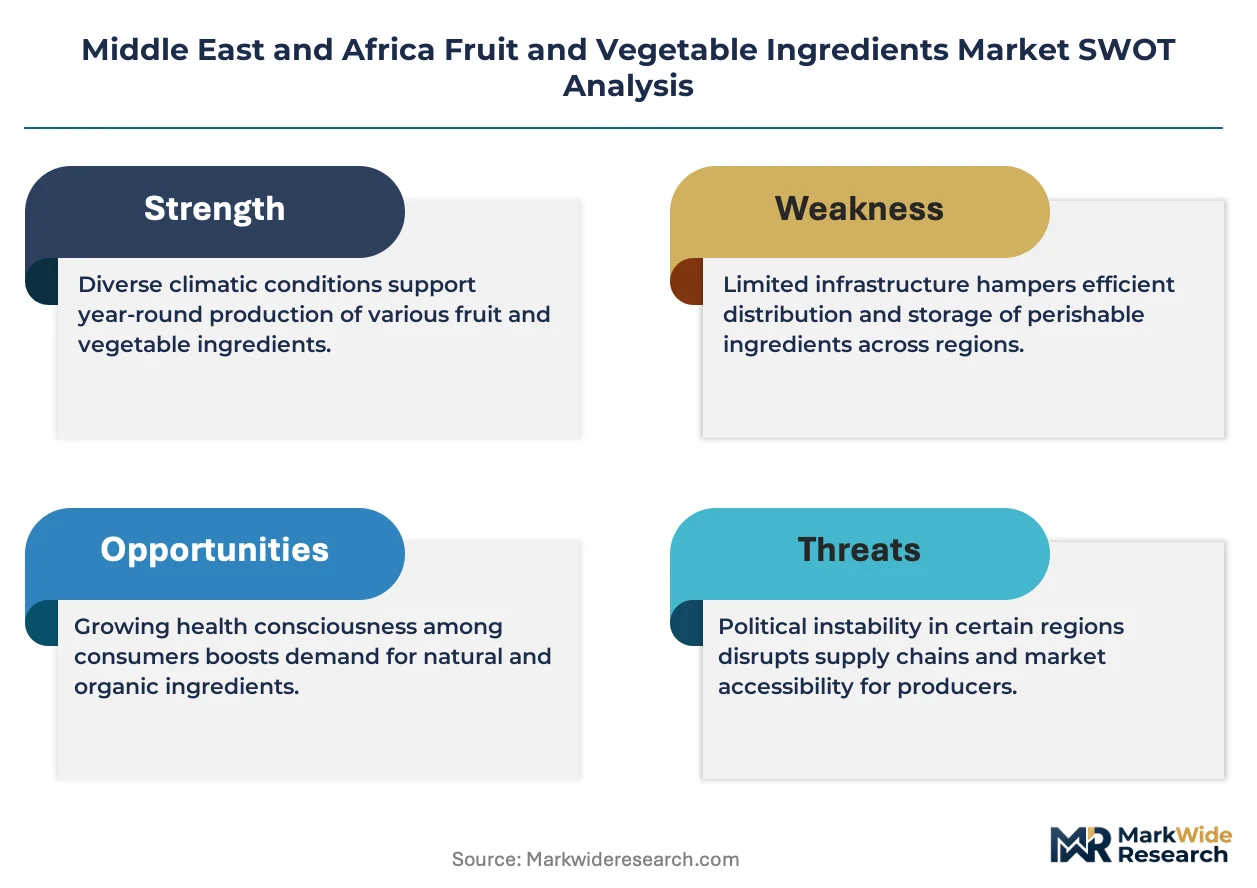
Halal certification mandates from Saudi Food and Drug Authority and UAE Ministry of Health and Prevention are compressing supplier qualification timelines while concentrating procurement authority among Gulf Cooperation Council beverage manufacturers with established certification pathways.
Growth Catalysts
- SFDA Fortification Mandates:Saudi Arabia's updated micronutrient standards for processed vegetable ingredients are compelling manufacturers to reformulate with standardized concentrate grades, pulling demand through qualified supply chains.
- Clean-Label Beverage Formulation:Juice and soft drink producers across the Gulf are substituting artificial colorants with fruit-derived concentrates, prioritizing brix consistency and soluble solids stability in procurement specifications.
- South African Retail Modernization:Supermarket expansion into peri-urban townships is creating chilled distribution infrastructure for pasteurized purees previously limited to informal processing channels.
Market Restraints
- European Fruit Concentrate Dependency:African processing lines rely on imported apple and orange concentrates from EU suppliers, exposing margins to euro-denominated input volatility and carbon border adjustment mechanics.
- Water Scarcity in Primary Production:Tomato and carrot puree sourcing from Egypt's Nile Delta faces irrigation quota restrictions under national water security frameworks, constraining regional self-sufficiency targets.
- Substitution by Synthetic Flavor Systems:Cost-sensitive bakery and confectionery segments in Nigeria and Kenya continue deploying nature-identical flavor compounds rather than dried fruit powders, capping premium ingredient penetration.
Strategic Opportunities
- Moroccan Citrus Processing Expansion:Greenfield concentrate facilities near Agadir could serve European organic beverage markets while meeting domestic halal certification requirements for re-export to Gulf states.
- UAE Free Zone Logistics:Jebel Ali and Kizad processing parks offer temperature-controlled blending infrastructure for regional toll manufacturing without agricultural land ownership.
- South African PLI-Aligned Investment:Department of Trade, Industry and Competition production incentives for food value-addition could support dehydrated vegetable capacity serving sub-Saharan retail channels.
Industry Challenges
- Halal Certification Timeline Compression:Gulf buyers are reducing supplier onboarding from 18 months to 9 months, straining laboratory capacity for contaminant testing and facility audit scheduling.
- Cold Chain Fragmentation:Aseptic puree distribution from Nairobi to Kampala requires multi-modal transfers with temperature excursion risks, elevating spoilage rates above 12 percent on certain lanes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Fruit and Vegetable Ingredients Market |
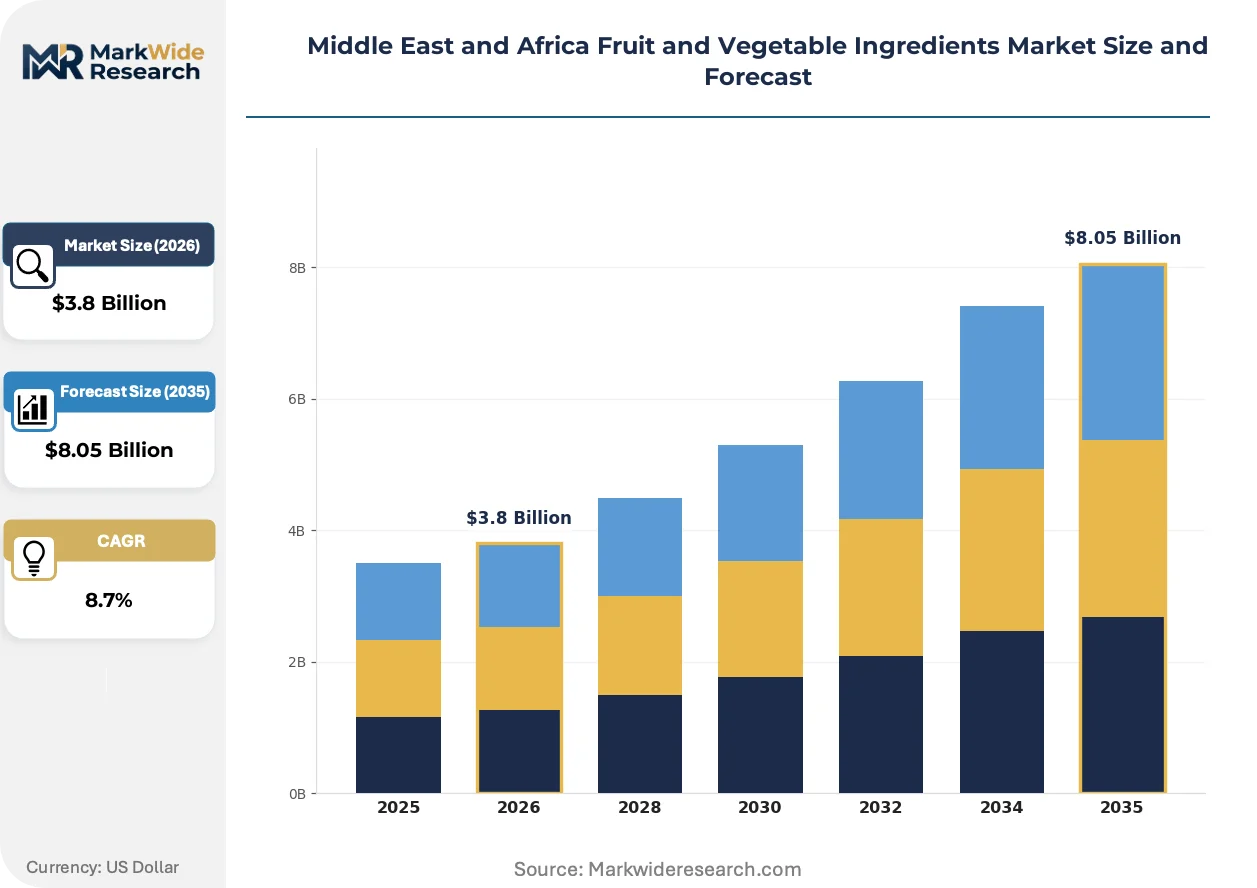
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Dried, Puree, Juice Concentrate Application: Beverages, Soups, Sauces, Snacks End User: Food & Beverage Manufacturers, Food Service, Retailers, Households Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Döhler Group, AGRANA Beteiligungs-AG, Kanegrade Ltd., SunOpta Inc., Archer Daniels Midland Company, Ingredion Incorporated, SVZ Industrial Fruit and Vegetable Ingredients, Sensient Technologies Corp., Olam International, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Fruit and Vegetable Ingredients Market Trends and Innovations
Processing technology convergence and regulatory disclosure requirements are restructuring how fruit and vegetable ingredients retain nutritional integrity through supply chains serving formulated food and beverage applications.
High-pressure processing (HPP) technology is hybridizing thermal and non-thermal preservation pathways for fruit purees destined for infant nutrition and premium smoothie applications. UAE-based dairy and beverage manufacturers are piloting HPP lines at commercial scale, compressing the traditional heat-treatment equipment install base while extending refrigerated shelf-life claims without chemical preservatives.
SFDA and MOHAP are synchronizing contaminant threshold standards for mycotoxins and pesticide residues in imported concentrates, creating unified Gulf entry requirements that reduce regulatory fragmentation. European and South Asian suppliers must now maintain single certification packages valid across Saudi Arabia, UAE, Kuwait, and Qatar, concentrating compliance investment among larger ingredient houses with dedicated regulatory affairs functions.
Beverage manufacturers are consolidating procurement authority into centralized technical buying teams that specify brix, acidity, and colorimetric parameters rather than sourcing commodity grades through traditional trading houses. This specification-driven purchasing is displacing spot-market transactions in Dubai and Jeddah, with annual framework agreements now governing 60 percent of regional concentrate volumes and compressing trading margin structures.
Middle East and Africa Fruit and Vegetable Ingredients Market Segmentation
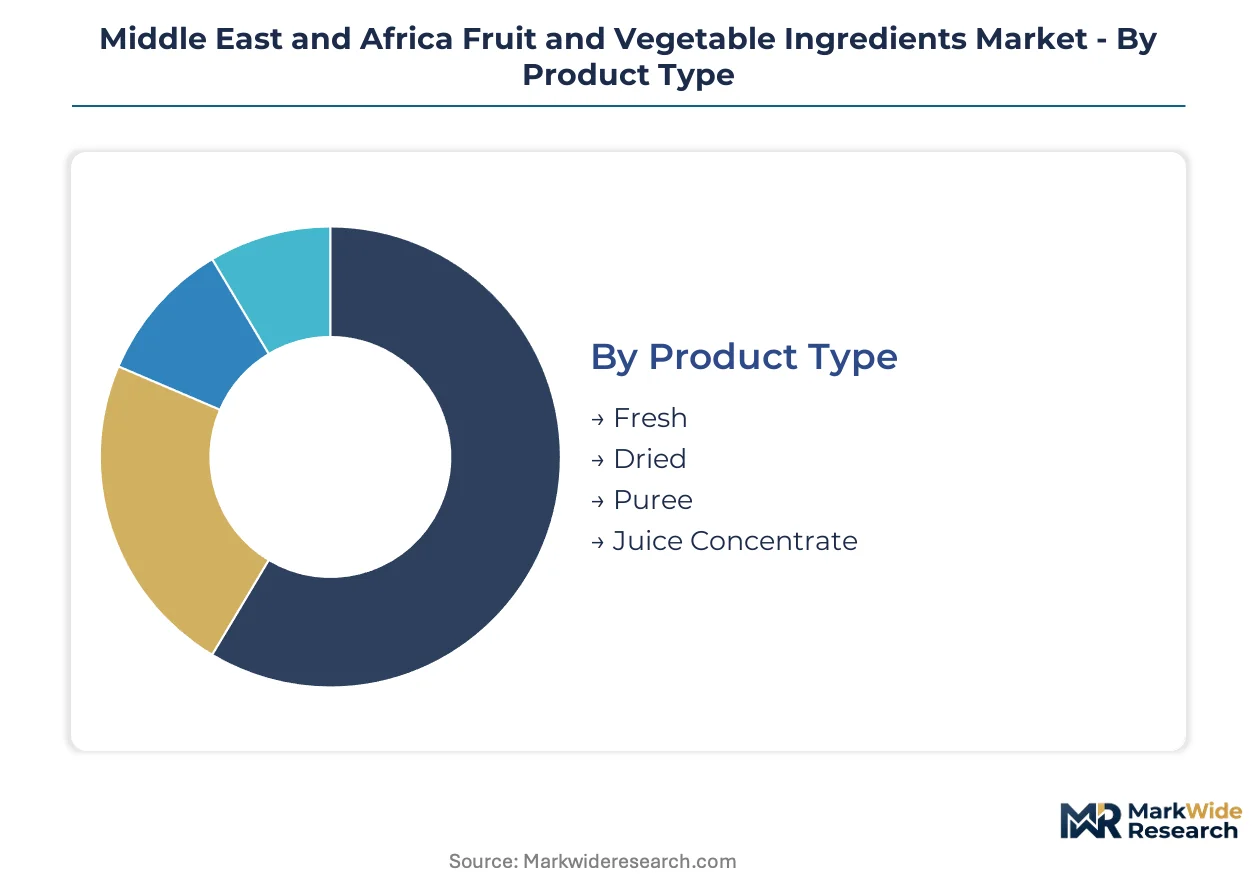
Fruit and vegetable ingredient procurement across the Middle East and Africa fragments across preservation state, application chemistry, and channel temperature requirements. Understanding these divisions reveals where specification standards tighten and where informal supply chains persist.
Product Type:
Mature thermal preservation formats dominate volume flows while emerging minimal-processing technologies capture premium positioning in Gulf beverage markets.
- Juice Concentrate:Evaporated fruit extracts standardized to specific brix levels serve as the primary input for beverage manufacturing across Saudi Arabia and the UAE. SFDA fortification mandates and MOHAP additive regulations are compressing supplier qualification timelines for concentrate imports into Gulf Cooperation Council markets.
- Puree:Pasteurized vegetable and fruit purees with controlled water activity specifications supply infant nutrition and smoothie applications. Cold chain fragmentation between Nairobi and Kampala elevates spoilage risks above acceptable thresholds on certain East African distribution lanes.
- Fresh:Minimally processed raw ingredients for immediate food service consumption face compressed shelf-life windows in high-temperature climates.
- Dried:Dehydrated pieces and powders with water activity below 0.60 sustain snack and bakery channel stability across South African retail modernization.
Juice concentrate retains volume leadership; puree holds the steepest expansion curve as HPP technology extends refrigerated shelf-life claims.
Application:
Application demand concentrates in liquid formulations where brix consistency determines manufacturing yield, while solid food channels prize texture retention through thermal stress.
- Beverages:Fruit-derived concentrates and purees constitute the dominant application segment, with manufacturers substituting artificial colorants for clean-label formulations. Procurement authority is consolidating into centralized technical buying teams specifying soluble solids content rather than sourcing commodity grades through Dubai trading houses.
- Snacks:Dried fruit pieces and vegetable powders supply bakery and confectionery segments, though Nigerian and Kenyan cost-sensitive manufacturers continue deploying synthetic flavor systems.
- Soups:Vegetable purees and concentrates form the base for packaged and food service soup formulations across South African supermarket expansion zones.
- Sauces:Tomato and carrot purees from Egypt's Nile Delta face irrigation quota restrictions under national water security frameworks.
Beverages command procurement volume concentration; snacks present the most contested premium penetration battleground.
End User:
Customer type determines specification rigor, with institutional buyers enforcing halal certification and contaminant thresholds unavailable to household purchasers.
- Food & Beverage Manufacturers:Gulf-based beverage producers with established SFDA certification pathways are compressing supplier onboarding timelines from 18 months to 9 months. Annual framework agreements now govern the majority of regional concentrate procurement.
- Food Service:Restaurant chains and institutional caterers demand aseptic puree formats with extended ambient stability for kitchen operational efficiency.
- Retailers:South African supermarket expansion into peri-urban townships is creating chilled distribution infrastructure for pasteurized products.
- Households:Informal processing channels in East and West Africa continue sourcing non-standardized ingredient grades outside regulated supply chains.
Food and beverage manufacturers concentrate procurement authority; retailers are gaining fastest in infrastructure-mapped geographies.
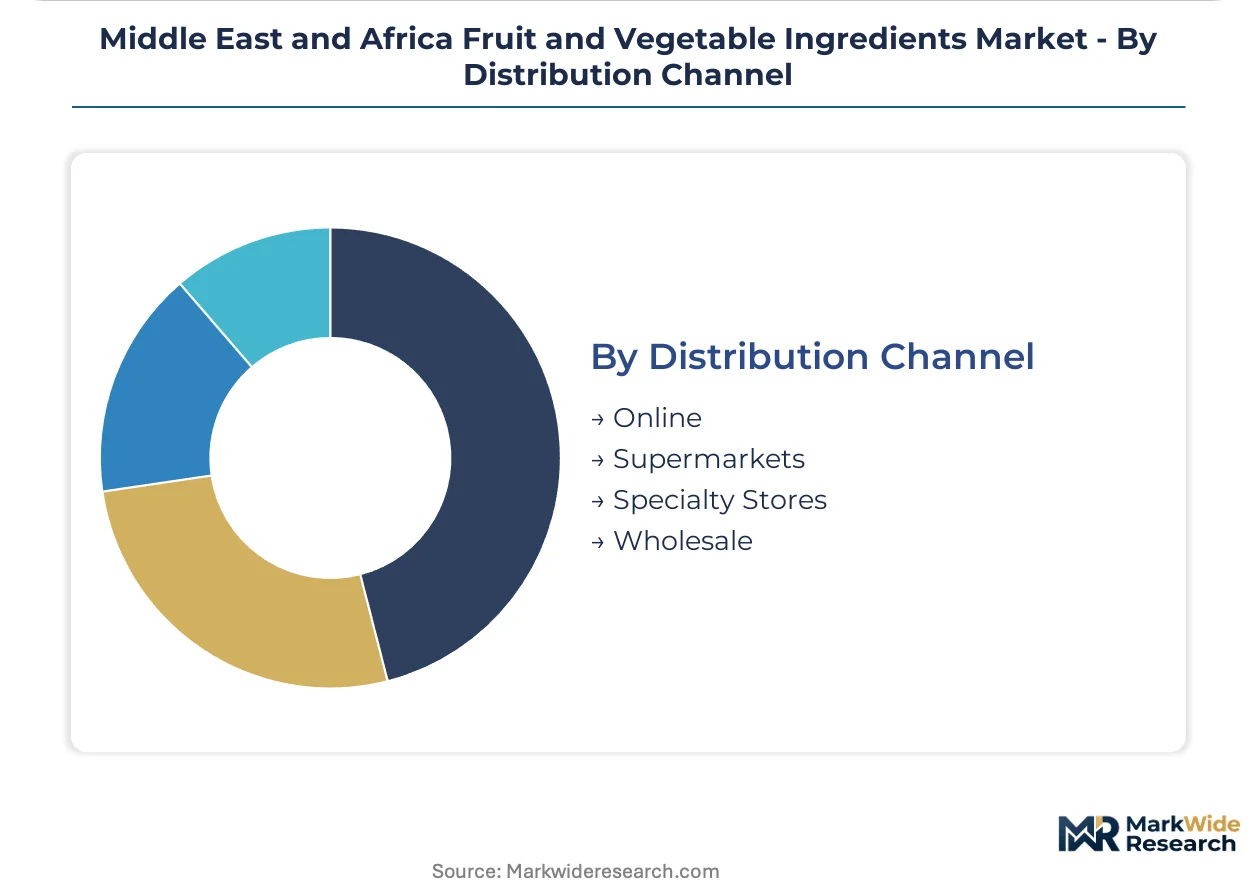
Distribution Channel:
Channel selection reflects temperature requirements and certification documentation needs, with cold chain-dependent formats excluding certain routes.
- Wholesale:Bulk concentrate and puree shipments through Jebel Ali and Kizad free zones supply toll manufacturing operations without agricultural land ownership requirements.
- Supermarkets:Modern retail chains in South Africa and Gulf urban centers stock pasteurized and dried formats with full halal certification documentation.
- Specialty Stores:Premium organic and HPP-treated products serve niche infant nutrition and health-conscious consumer segments.
- Online:E-commerce penetration for temperature-sensitive ingredients remains constrained by last-mile cold chain reliability across the region.
Wholesale channels retain volume leadership; supermarkets are climbing the fastest as retail modernization extends beyond primary cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Middle East and Africa fruit and vegetable ingredients market operates through distinct import-export corridors, with Gulf states sourcing concentrates from European suppliers while North African processing hubs target re-export opportunities to European organic beverage markets.
Saudi Arabia
Beverage manufacturers in Riyadh and Jeddah are accelerating procurement of standardized concentrate grades to meet SFDA fortification mandates for processed vegetable ingredients. The Saudi Food and Drug Authority has compressed supplier qualification timelines from 18 months to 9 months, tightening laboratory capacity for contaminant testing. Food processing clusters in Jeddah serve as the primary Gulf Cooperation Council export channel for halal-certified purees.
United Arab Emirates
MOHAP regulations governing food additive thresholds are synchronizing with Saudi standards, creating unified Gulf entry requirements for imported concentrates. Dubai-based dairy and beverage manufacturers are piloting high-pressure processing lines at commercial scale for premium smoothie applications. Jebel Ali and Kizad free zones provide temperature-controlled blending infrastructure for regional toll manufacturing operations.
South Africa
Supermarket expansion into peri-urban townships is creating chilled distribution infrastructure for pasteurized purees previously limited to informal processing channels. The Department of Health fortification standards govern micronutrient levels in processed vegetable ingredients distributed through retail channels. The Department of Trade, Industry and Competition production incentives for food value-addition could support dehydrated vegetable capacity serving sub-Saharan retail channels.
Egypt
Tomato and carrot puree sourcing from the Nile Delta faces irrigation quota restrictions under national water security frameworks, constraining regional self-sufficiency targets. Egyptian processors supply aseptic puree formats to Gulf food service operators demanding extended ambient stability. Cairo-based exporters navigate SFDA halal certification requirements for re-export to Saudi Arabia and UAE markets.
Morocco
Greenfield concentrate facilities near Agadir could serve European organic beverage markets while meeting domestic halal certification requirements for re-export to Gulf states. Moroccan citrus processors are positioning to capture demand from beverage manufacturers substituting artificial colorants with fruit-derived concentrates. The Agadir industrial zone offers proximity to both Atlantic port infrastructure and organic citrus cultivation regions.
Middle East and Africa Fruit and Vegetable Ingredients Market Competitive Landscape
On the supply side, the industry is moderately consolidated around European ingredient houses with established Gulf certification pathways and regional toll manufacturers operating without captive agricultural holdings. Three strategic archetypes dominate: backward-integrated European processors controlling upstream fruit sourcing, asset-light regional blenders leveraging free-zone infrastructure, and diversified agribusiness traders extending existing spice and nut distribution networks. Competitive dynamics center on M&A activity targeting halal-certified processing capacity and strategic partnerships with Gulf beverage manufacturers consolidating procurement authority.
Within the European processor tier, Döhler Group and AGRANA Beteiligungs-AG exemplify distinct supply chain configurations. Döhler leverages regional blending facilities to serve beverage clients without captive agricultural holdings, while AGRANA anchors its position through backward integration into European fruit sourcing that feeds African processing lines. Olam International occupies a position within the diversified agribusiness archetype, competing via established spice and nut distribution corridors extended into vegetable ingredient logistics.
| Leading Market Players |
|---|
| Döhler Group |
| AGRANA Beteiligungs-AG |
| Kanegrade Ltd. |
| SunOpta Inc. |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| SVZ Industrial Fruit and Vegetable Ingredients |
| Sensient Technologies Corp. |
| Olam International |
| Others |
Pricing and Supply Chain Analysis
Jebel Ali's temperature-controlled blending infrastructure anchors Gulf procurement economics, where toll manufacturing capacity concentration feeds pricing power into downstream beverage formulations. SFDA halal certification timelines compress from 18 months to 9 months, squeezing laboratory audit capacity and elevating compliance premiums for qualified suppliers.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure, with annual framework agreements now governing the majority of regional concentrate volumes. Three-tier pricing structure across premium, standard, and economy levels separates HPP-treated purees from pasteurized grades and commodity concentrates. Cost compression in economy-tier dried ingredients is intensifying because Nigerian and Kenyan bakery manufacturers continue deploying synthetic flavor systems rather than fruit powders. Food service operators demonstrate the least price sensitivity, prioritizing aseptic stability and halal documentation over per-unit cost.
Supply Chain Analysis
EU dual-use export controls on advanced thermal processing equipment constrain technology transfer into North African greenfield facilities, limiting local capacity expansion. Geographic supply concentration centers on Germany and Austria for apple and orange concentrates, Egypt's Nile Delta for tomato and carrot purees, and Morocco's Agadir corridor for citrus processing. Raw material dependencies rest on euro-denominated fruit inputs, Nile irrigation quotas, and organic certification-compliant orchards. Single-source vulnerability runs through European concentrate suppliers exposed to carbon border adjustment mechanics. Distribution runs through Jebel Ali and Kizad free zones for regional toll manufacturing without agricultural land ownership.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa fruit and vegetable ingredients market sits in early-cycle expansion, with clean-label beverage formulation tailwinds accelerating procurement of fruit-derived concentrates across Gulf processing clusters.
For Market Incumbents: Pre-empt margin compression by securing backward integration into Moroccan citrus orchards and Egyptian tomato cultivation before irrigation quotas tighten further. SFDA certification pathway congestion threatens to strand unqualified suppliers; accelerate laboratory capacity investments to maintain 9-month onboarding competitiveness. Channel control through Jebel Ali logistics partnerships preserves toll manufacturing economics against asset-light regional blenders. For New Entrants and Emerging Players: Establish a beachhead in South African dehydrated vegetable capacity serving supermarket expansion into peri-urban townships. White-space targets include HPP-treated purees for UAE premium smoothie applications and organic concentrate re-export from Morocco to European beverage markets. A go-to-market angle through Department of Trade, Industry and Competition production incentives de-risks initial capital deployment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors halal-certified processing assets with established SFDA audit trails over greenfield equipment plays. Long-term viability hinges on irrigation-secure sourcing geographies and carbon-adjustment-compliant European supply partnerships. The signal to watch is Gulf standardization harmonization between SFDA and MOHAP, which would concentrate procurement authority among dual-certified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Fast-Track Investment | SFDA's compressed 9-month timeline favors pre-qualified laboratory capacity over spot-market traders. |
| Backward Integration into Nile Delta Agriculture | Egyptian water security frameworks make irrigation-secure tomato and carrot sourcing a scarce asset. |
| HPP Technology Commercial Deployment | UAE dairy and beverage pilot lines extend refrigerated shelf-life claims without chemical preservatives. |
| Free Zone Toll Manufacturing Expansion | Jebel Ali and Kizad infrastructure enables regional blending without captive agricultural land ownership. |
| Organic Concentrate Re-Export Capacity | Agadir greenfield facilities serve European beverage markets while meeting Gulf halal requirements. |
Research Methodology
Initial hypotheses were tested against primary input from beverage procurement directors, halal certification laboratory managers, free zone logistics operators, and agricultural irrigation planners and refined through secondary validation. Beverage procurement directors at Gulf Cooperation Council manufacturers provided concentrate specification trends and supplier qualification timelines. Halal certification laboratory managers disclosed audit capacity constraints and contaminant testing protocols. Free zone logistics operators detailed temperature-controlled infrastructure economics. Agricultural irrigation planners in Egypt and Morocco revealed water security framework impacts on raw material availability. Secondary sources included SFDA and MOHAP regulatory filings, Gulf standardization harmonization documents, South African Department of Trade, Industry and Competition incentive disclosures, and customs trade data on concentrate import flows. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Demand-supply-balance framing anchored the analytical framework, with beverage manufacturer procurement consolidation and clean-label substitution rates driving consumption projections against concentrate import capacity and regional processing expansion. Segmentation dimensions modeled include preservation state, application chemistry, end-user type, and channel temperature requirements. CAGRs were derived from fitted growth curves calibrated to procurement volume trajectories and infrastructure investment pipelines. Industry-specific forecast inputs incorporated SFDA fortification mandate implementation timelines and South African retail modernization penetration curves.
Stress conditions across euro-denominated input volatility, Nile irrigation quota enforcement severity, and Gulf certification timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions on halal standardization synchronization and carbon border adjustment mechanics. Material shifts in Gulf regulatory harmonization pace or European supplier carbon compliance costs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Cold Water-Soluble Creamer Market
Ingredients
Resistant Starch Market
Ingredients
Malted Wheat Flour Market
Ingredients
Omega Ingredients Market
Ingredients
Notoginseng Root Extract Market
Ingredients
Rice Starch Market
Ingredients
Ice Cream Bases Market
Ingredients
Sesame Oil Market
Ingredients
Carica Papaya Seed Oil Market
Ingredients
Insect-Based Ingredients Market
Ingredients
North America Lipid Market
Ingredients
Sunflower Oil Market
Ingredients
Europe Agar Market
Ingredients
Spain Sodium Reduction Ingredient Market
Ingredients
Mediterranean Marine Ingredients for Pet Health Market
Ingredients
White Mulberry Leaves Extract Market