
 Stock Cubes Market | 2026-2036
Stock Cubes Market Size, Share, and Industry Trends Forecast 2026-2036
Stock Cubes Market Analytics
The stock cubes category is restructuring around a widening gap between premium clean-label offerings and commodity-priced conventional products, with ingredient transparency and sodium reduction becoming the fault lines. Unilever leverages its Knorr portfolio to sustain R&D investment in reduced-sodium formulations across multiple geographies. Nestle anchors its Maggi brand through deep distribution networks in Africa and South Asia, while Kraft Heinz competes in North American private-label and branded segments with manufacturing scale.
Stock cubes are compressed seasonings produced by dehydrating concentrated meat, vegetable, or seafood extracts with salt, fat, and flavor enhancers into solid or granular form, typically reconstituted in hot water to produce broth. The manufacturing process involves vacuum concentration, blending with hydrolyzed vegetable protein, and pressing or extrusion into standardized shapes with moisture content below five percent. Chicken stock cubes lead volume globally due to universal palate acceptance, while vegetable variants capture the fastest growth as plant-based diets expand among household and food manufacturer end users. Granulated and powder forms command margin premiums for their faster dissolution and dosing flexibility in restaurant and catering channels.
The FDA governs labeling and sodium disclosure for stock cubes sold in the United States, while EFSA and EU Green Deal frameworks push sodium reduction and sustainable sourcing requirements across European markets. India's FSSAI enforces additive limits and packaging standards that shape product registration timelines for multinational entrants. Stakeholders must monitor evolving clean-label thresholds and regional sodium caps to align formulation pipelines with divergent compliance landscapes.
Market Dynamics
The stock cubes market is bifurcating around sodium reduction mandates and clean-label ingredient transparency, with regulatory pressure from the EU Green Deal forcing reformulation investments that widen the competitive gap between multinational formulators and regional commodity producers.
Growth Catalysts
- EFSA sodium thresholds:The European Food Safety Authority's evolving guidance on daily sodium limits is accelerating reduced-sodium product development, creating first-mover advantages for compliant manufacturers in Western Europe.
- Urban household penetration in India:Rising nuclear family formations and working-women participation rates in Indian metropolitan areas are expanding the addressable base for branded, convenience-oriented cooking solutions.
- Plant protein hydrolysis advances:Enzymatic processing improvements for vegetable-derived umami compounds are enabling cleaner-label formulations that satisfy EFSA additive restrictions without MSG dependence.
Market Restraints
- Input cost volatility in palm oil and salt:Tropical commodity price swings directly compress gross margins for mass-market stock cube producers dependent on standardized fat and sodium inputs.
- Supply concentration in Southeast Asian hydrolyzed vegetable protein:Three Indonesian and Malaysian suppliers control the majority of HVP feedstock, creating single-source vulnerability for European and African formulators.
- Refrigerated broth substitution:Chilled liquid stock alternatives in Western European retail channels are capturing premium-positioned consumers seeking shorter ingredient lists and fresher positioning.
Strategic Opportunities
- Sub-Saharan African informal retail digitization:Mobile money-enabled distribution platforms are opening direct-to-dukkan routes that bypass traditional wholesaler markups in Kenya, Nigeria, and Ghana.
- FSSAI clean-label harmonization:India's Food Safety and Standards Authority is consolidating additive approval categories, creating regulatory clarity that rewards early reformulation investments by multinational entrants.
- Precision fermentation-derived flavor precursors:Biotechnology convergence with traditional dehydration processes promises scalable, animal-free savory bases that satisfy both vegan positioning and sodium reduction targets.
Industry Challenges
- Sensory scientist scarcity:The specialized expertise required to reformulate umami profiles without MSG or yeast extract is concentrated among a small cohort of European and Japanese flavor houses, constraining in-house R&D timelines.
- Dual certification complexity:Simultaneous organic and halal compliance for export markets requires segregated production lines that extend capital deployment cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stock Cubes Market |
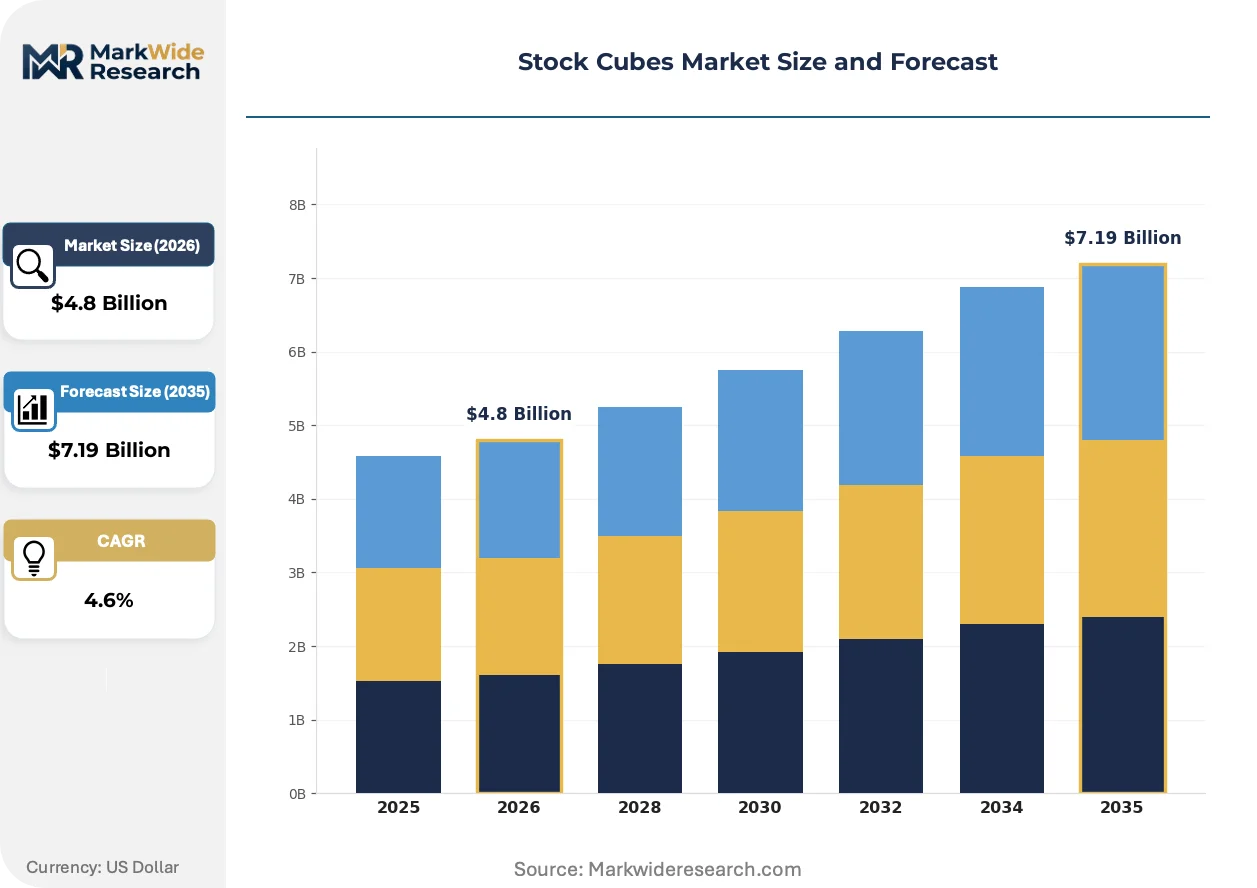
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chicken, Beef, Vegetable, Seafood Form: Granulated, Powder, Liquid, Cubes End User: Household, Restaurants, Catering Services, Food Manufacturers Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Wholesale |
| Companies Covered | Unilever (Knorr), Nestle (Maggi), Kraft Heinz, McCormick, Ariake Group, Hormel Foods, Goya Foods, Premier Foods, Imana Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stock Cubes Market Evolving Landscape
Reformulation science and distribution digitization are converging to reshape competitive positioning in stock cubes, with sodium reduction chemistry and direct-to-retail logistics emerging as the primary vectors of differentiation between heritage brands and insurgent challengers.
Spray-dried umami concentrates derived from shiitake and kombu extracts are integrating into premium stock cube formulations, replacing synthetic flavor enhancers. European and North American clean-label adopters are sourcing these inputs at triple-digit annual volume growth. The technology is integrating formerly separate supply chains for Asian botanicals and European savory manufacturing, compressing development cycles for compliant products.
EU Green Deal sustainable sourcing requirements are mandating supply chain traceability for palm-derived ingredients and packaging materials. Manufacturers must now document deforestation-free provenance and recyclable packaging compliance to maintain shelf access in German, French, and Benelux retail networks. Reduced-sodium variants face the steepest compliance burden, as reformulated products require additional stability testing under EFSA extended evaluation protocols.
Quick-commerce platforms and dark-store networks are fragmenting traditional wholesale-dominant distribution in Indian and Southeast Asian urban centers. Brand owners are building direct fulfillment relationships with Swiggy Instamart, Blinkit, and regional equivalents, displacing the multi-tier distributor model that has governed stock cube access for decades. Mumbai, Bangalore, and Jakarta metro corridors exhibit the most pronounced channel shift, with 15-minute delivery promises now standard for household grocery categories.
Stock Cubes Market Segmentation
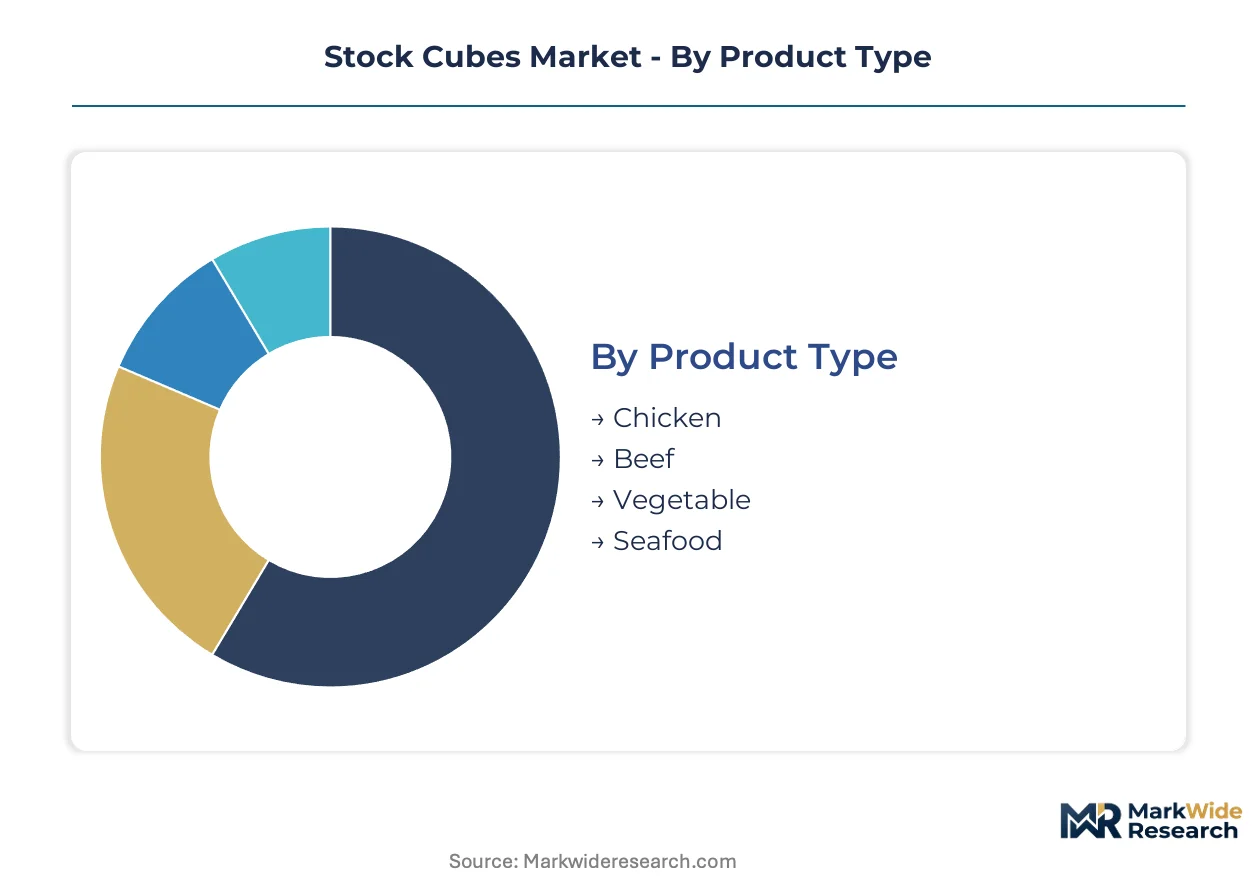
Stock cube manufacturers must align formulation pipelines with divergent certification requirements across product categories. Each segment carries distinct regulatory burdens, from EFSA sodium thresholds for conventional cubes to organic and halal compliance for premium vegetable variants.
Product Type:
Halal certification dominates beef and chicken segments across African and Middle Eastern markets, while EU Green Deal traceability requirements press hardest on seafood variants dependent on sustainable fishery inputs.
- Chicken:Universal palate acceptance drives volume leadership across Indian, Nigerian, and Brazilian household markets. Reformulation investments concentrate on reduced-sodium variants for EFSA compliance in Western Europe, where Knorr and Maggi anchor brand loyalty through heritage positioning.
- Vegetable:Plant-based diet expansion accelerates demand among European clean-label adopters and Indian urban nuclear families. Shiitake and kombu-derived umami concentrates replace MSG in premium formulations, satisfying both FSSAI additive limits and EU organic certification standards.
- Beef:Halal slaughter certification gates access to Indonesian, Malaysian, and Nigerian retail channels.
- Seafood:MSC traceability documentation now mandatory for EU shelf placement.
Chicken sits at the top of the volume ranking, with vegetable climbing the fastest.
Form:
Moisture content and dissolution speed separate margin tiers, with powder and granulated formats commanding premium positioning in foodservice channels.
- Cubes:Standardized pressing and extrusion with sub-five-percent moisture content enables ambient stability for African and South Asian informal retail. Unilever and Nestle maintain manufacturing scale advantages through dedicated cube production lines in Nigeria, Kenya, and India.
- Granulated:Faster dissolution and precise dosing flexibility capture restaurant and catering procurement in European and North American markets. Spray-dried production requires higher capital investment, limiting supplier concentration to established savory manufacturers with in-house dehydration capacity.
- Powder:Bulk packaging formats serve institutional food manufacturers in Southeast Asia.
- Liquid:Refrigerated distribution constraints restrict penetration to premium Western European retail.
Cubes dominate absolute volume, while granulated formats gain share fastest in foodservice channels.
End User:
Procurement sophistication varies sharply, from price-sensitive household bulk purchasing to specification-driven food manufacturer contracts.
- Household:Convenience-oriented cooking solutions expand with Indian urbanization and working-women labor force participation. Quick-commerce platforms fragment traditional wholesale-dominant access in Mumbai, Bangalore, and Jakarta metro corridors.
- Food Manufacturers:Ingredient transparency requirements and sodium reduction targets drive clean-label reformulation for ready-meal and soup applications. EFSA extended evaluation protocols add stability testing burdens for reduced-sodium inputs.
- Restaurants:Dosing consistency and dissolution speed prioritize granulated and powder formats.
- Catering Services:Volume procurement favors bulk cube and powder packaging.
Household consumption leads volume, with food manufacturers expanding most quickly on clean-label reformulation demand.
Distribution Channel:
Channel selection determines margin capture, with direct-to-retail digitization displacing multi-tier distributor markups in emerging markets.
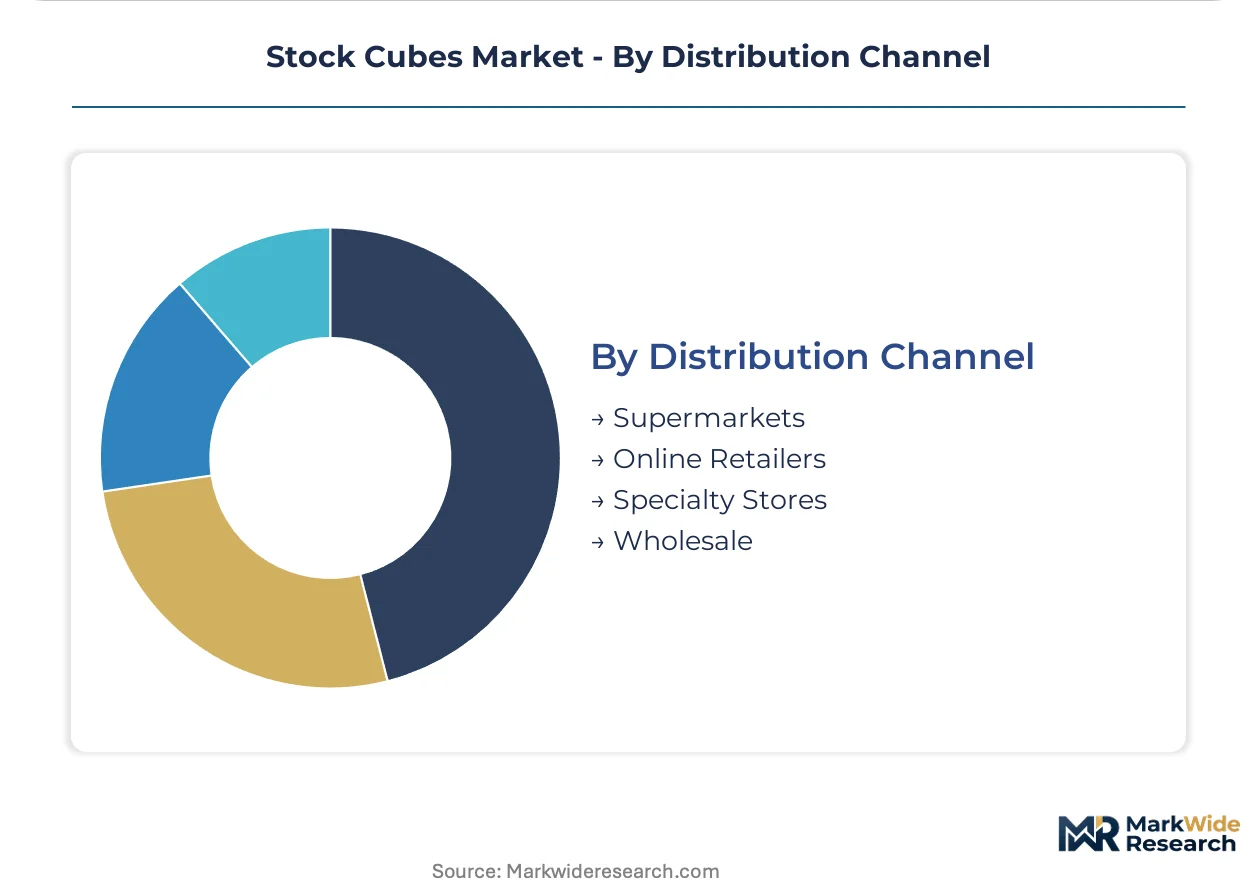
- Supermarkets:Shelf-space negotiations in German, French, and Benelux networks require EU Green Deal packaging compliance and deforestation-free palm documentation. Reduced-sodium variants face extended listing timelines under retailer sustainability scorecards.
- Online Retailers:Mobile money-enabled platforms open direct-to-dukkan routes in Kenyan, Nigerian, and Ghanaian informal retail. Swiggy Instamart and Blinkit fragmentation in Indian urban centers compresses delivery promises to fifteen minutes for household grocery categories.
- Wholesale:Traditional multi-tier distribution persists in African and Southeast Asian rural penetration.
- Specialty Stores:Organic and ethnic positioning commands premium pricing in European urban clusters.
Supermarkets retain volume leadership, with online retailers climbing fastest on quick-commerce platform expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flavor chemists and food technologists concentrate in European and Japanese metropolitan clusters, anchoring reformulation capabilities for sodium-reduced and clean-label product development.
India
Urban nuclear families and working-women labor force participation expand the addressable base for branded convenience cooking solutions. FSSAI additive limits and packaging standards shape product registration timelines for multinational entrants. Mumbai, Bangalore, and Delhi-NCR metro corridors exhibit rapid quick-commerce platform adoption, with 15-minute delivery promises now standard for household grocery categories.
Germany
Clean-label adopters and organic certification seekers drive premium positioning for vegetable-derived stock products. EU Green Deal sustainable sourcing requirements mandate supply chain traceability for palm-derived ingredients and packaging materials. The Rhine-Ruhr industrial corridor hosts concentrated savory manufacturing capacity serving Benelux and French retail networks.
United States
Food manufacturer procurement and foodservice channel demand prioritize granulated formats with faster dissolution characteristics. FDA labeling and sodium disclosure requirements govern retail shelf placement and nutritional panel specifications. Chicago and New Jersey metropolitan areas anchor North American savory ingredient production and distribution infrastructure.
Nigeria
Informal retail penetration and dukkan-level distribution sustain volume leadership for cube-format products in West African household markets. Halal slaughter certification gates access to beef and chicken segments across Muslim-majority northern states. Lagos and Kano urban clusters concentrate manufacturing scale for pan-African export supply.
Indonesia
Domestic consumption of hydrolyzed vegetable protein feedstock anchors Southeast Asian supply chain concentration for umami compound production. National halal certification requirements shape export eligibility for beef and poultry stock variants. Java-based manufacturing clusters serve regional formulators across ASEAN and African markets.
Stock Cubes Market Competitive Landscape
Top-tier vendors anchor branded portfolio scale, while private-label specialists and regional commodity producers occupy lower margin tiers. The market structure reflects consolidation around multinational savory portfolios with deep distribution networks, alongside fragmentation among single-category national champions. Three archetypes dominate: heritage brand owners with reformulation R&D capacity, scale-driven private-label manufacturers, and regional halal-certified specialists serving Islamic markets. Competitive moves concentrate on sodium reduction chemistry licensing and direct-to-retail digitization partnerships.
Within the heritage brand tier, Unilever plc and Nestle S.A. exemplify multinational scale advantages through legacy savory portfolios with decades of consumer recognition. Kraft Heinz Company occupies a position among North American packaged food conglomerates with manufacturing scale across branded and private-label segments. These three entities represent the archetype of integrated savory manufacturers with captive dehydration capacity and multi-continental distribution infrastructure.
| Leading Market Players |
|---|
| Unilever (Knorr) |
| Nestle (Maggi) |
| Kraft Heinz |
| McCormick |
| Ariake Group |
| Hormel Foods |
| Goya Foods |
| Premier Foods |
| Imana Foods |
| Others |
Value Network & Pricing Analysis
Hydrolyzed vegetable protein feedstock costs cascade through three distinct pricing tiers, with Indonesian and Malaysian supply concentration enabling premium capture for clean-label compliant manufacturers while commodity-grade producers absorb margin compression from tropical commodity volatility.
Pricing Analysis
Unbundled ingredient transparency and bundled halal certification services split pricing architecture across premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by sodium reduction compliance and organic certification status. Price differentiation hinges on EFSA additive thresholds and FSSAI packaging standards, with clean-label variants commanding substantial premiums. Cost compression in economy-tier cubes is intensifying because palm oil and salt input volatility compresses standardized product margins, while household buyers in Indian informal retail exhibit highest price sensitivity and European food manufacturers show lowest.
Supply Chain Analysis
Flavor chemist and food technologist scarcity in European and Japanese metropolitan clusters constrains reformulation capacity expansion for sodium-reduced production. Manufacturing concentrates in Indonesia, Malaysia, and India, with hydrolyzed vegetable protein, palm-derived fats, and spray-dried umami concentrates as critical inputs. Single-source vulnerability in Southeast Asian HVP feedstock creates structural risk for European and African formulators. Distribution runs through traditional multi-tier wholesale networks in African and South Asian rural markets, with quick-commerce platforms fragmenting urban access in Indian metro corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU Green Deal compliance costs in Western Europe and FSSAI harmonization benefits in India, where regulatory clarity rewards early reformulation investments.
For Market Incumbents: Deepen captive dehydration capacity in Nigerian and Kenyan manufacturing clusters to defend against refrigerated broth substitution in premium Western European channels. Anchor halal-certified production lines in Indonesia to gate regional access, while accelerating precision fermentation-derived flavor precursor R&D to offset sensory scientist scarcity constraining in-house timelines. For New Entrants and Emerging Players: Precision fermentation-derived savory bases offer a technology-first wedge into European clean-label segments where EFSA sodium thresholds and MSG restrictions create formulation bottlenecks for heritage brands. Target Sub-Saharan African mobile money-enabled distribution platforms in Kenya, Nigeria, and Ghana, where direct-to-dukkan routes bypass traditional wholesaler markups and informal retail digitization remains underpenetrated. For Investors and Strategic Acquirers: Consolidation pressure builds where dual certification complexity extends capital deployment cycles by 18-24 months for organic-halal compliance. Long-term viability favors vertically integrated manufacturers with captive HVP supply and multi-continental distribution infrastructure. Watch enzymatic plant protein hydrolysis licensing activity as inflection indicator for clean-label reformulation scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Sodium Reduction Chemistry Licensing | Enables EFSA-compliant reformulation without MSG dependence in European markets. |
| Direct-to-Retail Digitization Partnership | Opens Swiggy Instamart and Blinkit routes bypassing multi-tier Indian distribution. |
| Precision Fermentation Capacity Buildout | Delivers scalable animal-free savory bases satisfying vegan and sodium targets. |
| Halal-Certified Production Line Segregation | Gates Indonesian, Malaysian, and Nigerian retail access for beef and poultry variants. |
| Spray-Dried Umami Concentrate Integration | Replaces synthetic enhancers with shiitake and kombu extracts for clean-label positioning. |
Research Methodology
Coverage spans Western Europe, India, Sub-Saharan Africa, and Southeast Asia, with primary inputs from each region gathered through structured interviews with brand managers at multinational savory manufacturers, category buyers at German and French retail networks, supply planners at Indonesian HVP producers, and channel sales heads in Nigerian informal distribution. Secondary validation draws from EFSA additive guidance documents, FSSAI packaging standard filings, EU Green Deal traceability protocols, and customs records tracking palm oil and hydrolyzed vegetable protein trade flows. Bottom-up volume modeling triangulates against top-down expenditure estimates across household, food manufacturer, and foodservice end-use segments.
Granularity extends to product type, form factor, end-user procurement sophistication, and distribution channel structure across the projection horizon. Chicken, vegetable, beef, and seafood variants were modeled separately with sodium-reduced and conventional formulation splits. Cube, granulated, powder, and liquid formats carry distinct margin and dissolution-speed assumptions. CAGRs derive from segment-level volume builds calibrated to urbanization rates, working-women labor force participation, and quick-commerce platform penetration curves. Forecast inputs include FSSAI clean-label harmonization timelines and EFSA extended evaluation protocol adoption rates.
The model holds under stable tropical commodity pricing and sustained EU Green Deal enforcement; deviation in palm oil volatility spikes or halal certification requirement shifts would compress margin assumptions for mass-market producers. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Australia Soy Protein Market
Ingredients
Potato Fiber Market
Ingredients
Encapsulated Salt Market
Ingredients
Pea Protein Ingredients Industry Status and Prospects Professional Market
Ingredients
Soy Protein Isolate Market
Ingredients
Hibiscus Extract Market
Ingredients
Omega Ingredients Market
Ingredients
Global Edible Oil Market
Ingredients
PDO/PGI-Linked Mediterranean Ingredient Collections Market
Ingredients
South America Soy Protein Ingredients Market
Ingredients
Halal Ingredients Market
Ingredients
Lime Seed Oils Market
Ingredients
South America Fats and Oil Market
Ingredients
Gelatin Substitutes Market
Ingredients
Plant Based Ingredients Market
Ingredients
Hydrolyzed Vegetable Protein Market