
 South America Flavors and Fragrances Market | 2026-2036
South America Flavors and Fragrances Market Size, Share, and Industry Trends Forecast 2026-2036
South America Flavors and Fragrances Market Analytics
Brazil is reshaping regional supply dynamics through expanded flavor compounding capacity in its southeastern industrial corridor. Givaudan SA leverages its botanical extraction infrastructure near São Paulo to serve cosmetic and food clients with reduced lead times. Symrise AG anchors its position through deep relationships with Brazilian citrus processors, securing captive terpene supplies. Kerry Group PLC competes by specializing in savory flavor systems tailored to local palate preferences across the Mercosur trade zone.
Flavors and fragrances encompass volatile aromatic compounds—natural extracts, synthetic molecules, and essential oil distillates—formulated to impart taste or scent to consumer and industrial products, with specifications typically requiring purity thresholds above 95% and stability across pH ranges from 3.0 to 8.0. These formulations serve primary commercial purposes in food palatability enhancement, cosmetic sensorial positioning, and pharmaceutical masking applications. Natural Extracts command premium positioning as clean-label demand intensifies among Brazilian and Argentine food processors, though Fragrance Oils generate the deepest margin pools through concentration in high-end personal care. Synthetic Flavors retain volume leadership in mass-market beverage applications where cost control dominates procurement criteria.
ANVISA governs flavor additive approvals and maximum usage limits in Brazil, while Argentina's national food safety authority enforces Mercosur-aligned additive codification that shapes cross-border formulation standardization. REACH-equivalent chemical registration requirements emerging across the region are elevating compliance costs for imported synthetic aroma molecules. Stakeholders must monitor regulatory divergence between national pharmacopeias and evolving cosmetic ingredient blacklists to anticipate reformulation obligations and sourcing recalibration needs.
Market Dynamics
ANVISA's updated labeling requirements for flavor compounds are compressing formulation timelines across Brazil's processed food sector while simultaneously elevating compliance costs for imported synthetic aroma molecules.
Growth Catalysts
- Clean-label mandates:Brazilian and Argentine food processors are reformulating with natural extracts to meet consumer transparency expectations, pulling demand away from artificial alternatives.
- Mercosur trade alignment:Argentina's national food safety authority enforces standardized additive codification that reduces cross-border formulation friction and enables regional scale economies.
- Personal care cluster densification:São Paulo state's concentrated manufacturing base generates procurement efficiencies and shortens supplier lead times for fragrance oil compounds.
Market Restraints
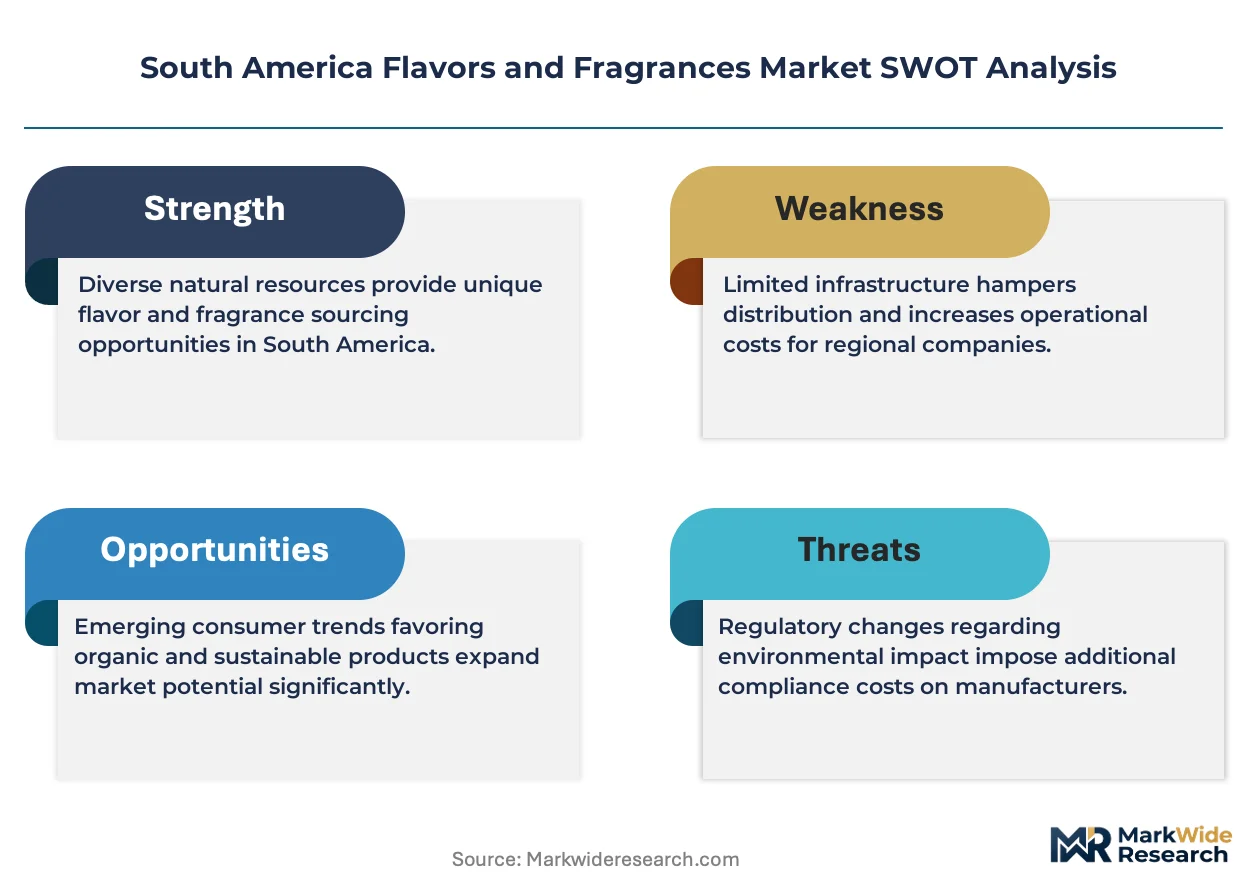
- Citrus terpene supply concentration:Brazilian orange processors control captive supplies of key fragrance feedstocks, creating bottlenecks for non-integrated compounders.
- REACH-equivalent registration costs:Emerging chemical registration requirements across South America elevate compliance burdens for imported synthetic molecules.
- Natural extract price volatility:Weather-dependent harvests of vanilla, citrus, and native botanicals generate input cost instability that squeezes processor margins.
Strategic Opportunities
- Amazonian biodiversity commercialization:Underexploited native botanicals from Brazil's northern states offer novel fragrance and flavor profiles for premium positioning.
- Clean beauty regulatory tailwinds:Expanding cosmetic ingredient blacklists across national pharmacopeias favor natural fragrance oil suppliers with established botanical extraction infrastructure.
- Direct-to-manufacturer digital platforms:Emerging B2B procurement channels are compressing distributor layers and enabling smaller flavor houses to access mid-tier food processors.
Industry Challenges
- Reformulation timeline compression:Accelerating regulatory update cycles force R&D teams to retest stability across pH ranges 3.0 to 8.0 under shortened approval windows.
- Sensory scientist scarcity:Specialized expertise in regional palate mapping—particularly for savory flavor systems tailored to Mercosur preferences—commands premium compensation and constrains expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Flavors and Fragrances Market |
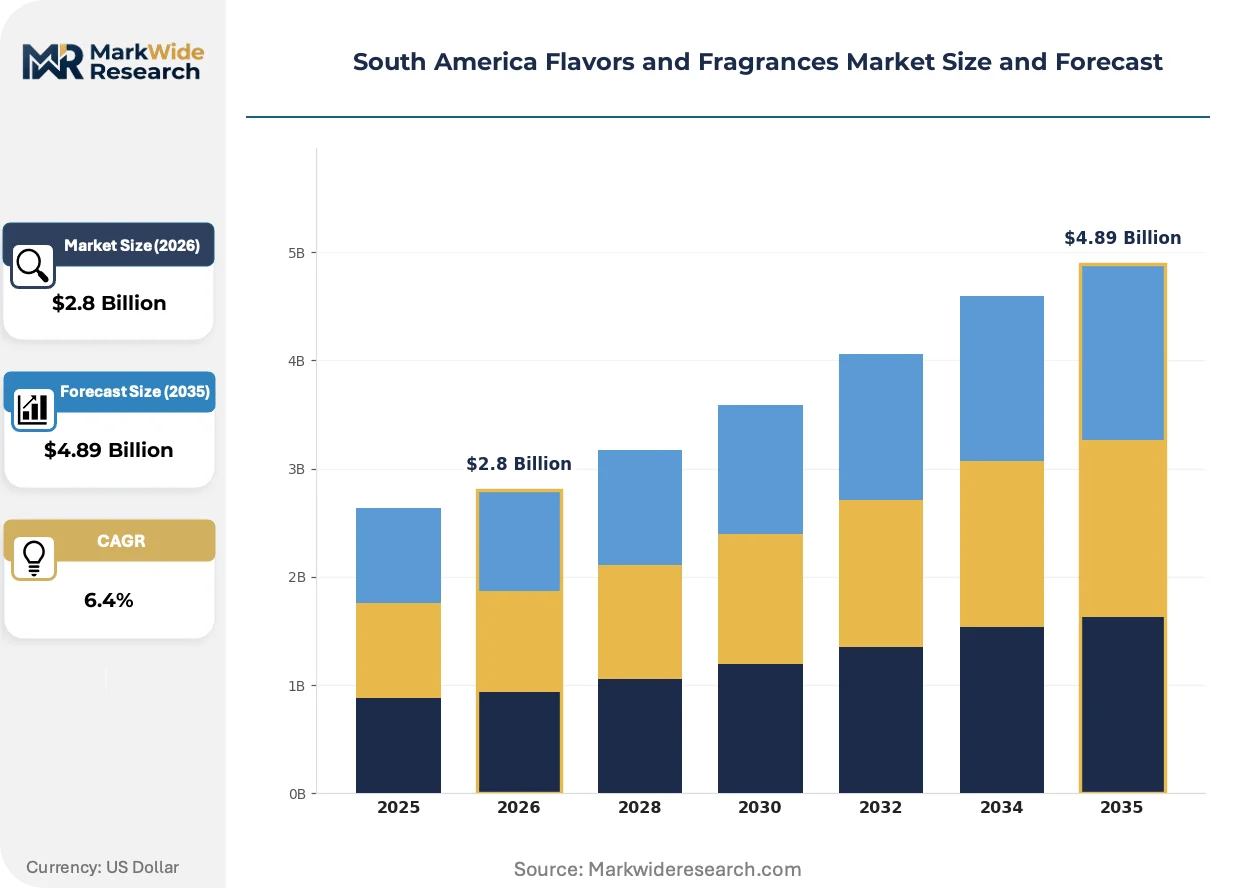
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Extracts, Synthetic Flavors, Fragrance Oils, Essential Oils Application: Food & Beverage, Cosmetic & Personal Care, Household Products, Pharmaceutical End User: Manufacturers, Distributors, Retailers, Wholesalers Distribution Channel: Online Sales, Direct Sales, Retail Stores, B2B Sales |
| Companies Covered | International Flavors & Fragrances Inc., Symrise AG, Firmenich International SA, Takasago International Corporation, Sensient Technologies Corporation, Givaudan SA, DSM-Firmenich AG, Kerry Group PLC, MANE SA, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Flavors and Fragrances Market Evolving Landscape
Digital traceability platforms and biotechnology-derived compounds are displacing traditional extraction and verification methods across South America's flavor and fragrance value chain.
Biotechnology-derived aroma molecules are digitizing supply chain verification by enabling batch-level tracking from fermentation through formulation. Brazilian cosmetic manufacturers are adopting these platforms fastest, driven by clean-label export requirements. The technology is digitizing compliance documentation that previously required manual pharmacopeia cross-referencing.
ANVISA's maximum usage limit updates for synthetic additives are forcing reformulation investments across beverage and confectionery segments. Manufacturers must now resubmit stability data for existing products, compressing product lifecycle management timelines. Argentina's alignment with Mercosur codification is creating divergent compliance obligations that favor regional compounders with dual-jurisdiction expertise.
Consolidated procurement by São Paulo-based personal care multinationals is displacing fragmented distributor networks that historically served mid-tier household product manufacturers. Direct supplier relationships now dominate volume contracting, with fragrance oil specifications increasingly bundled with technical service agreements. This concentration is most visible in Brazil's southeastern industrial corridor where manufacturing clusters have densified.
South America Flavors and Fragrances Market Segmentation
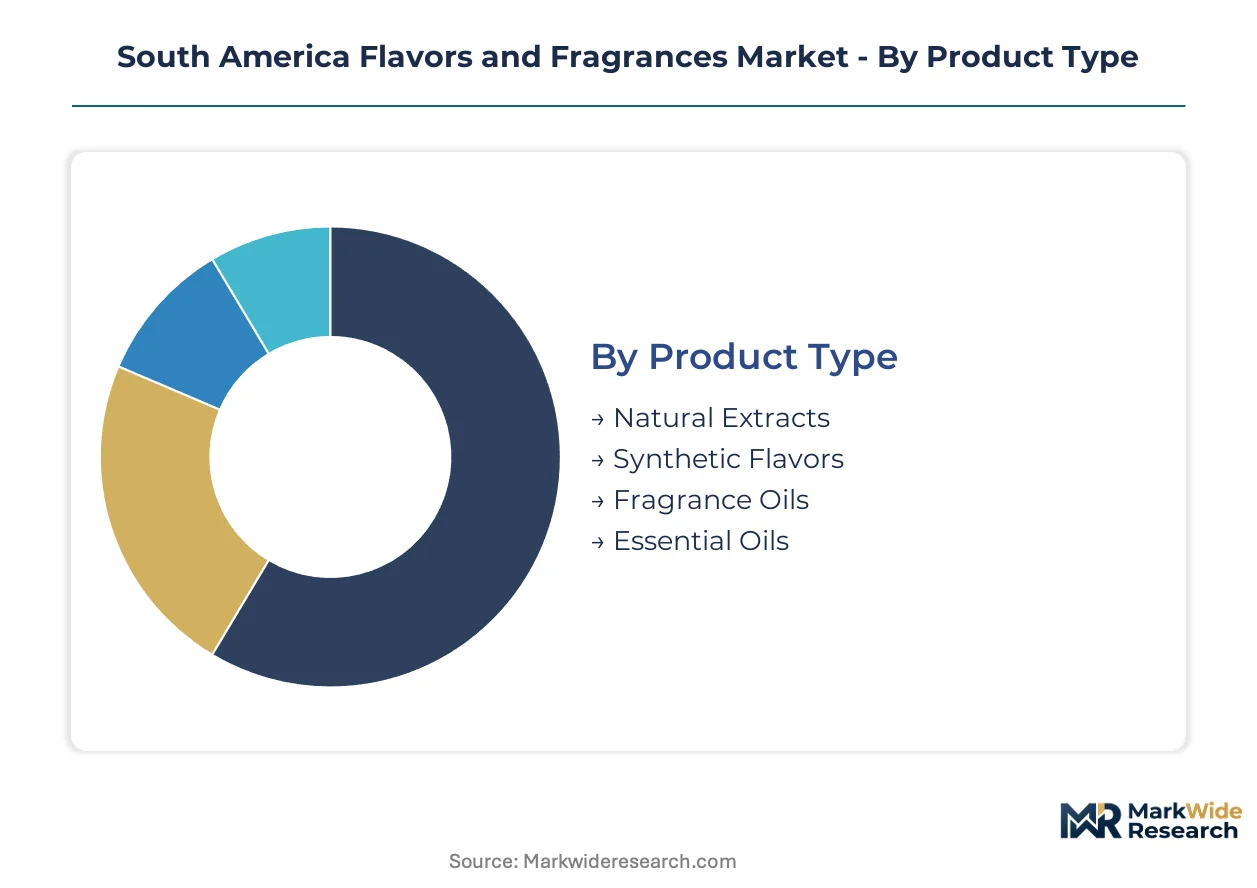
Segmentation in South America's flavors and fragrances market reveals how formulation requirements, regulatory exposure, and channel economics split procurement behavior across distinct buyer profiles. Understanding these divisions exposes where margin pools concentrate and which technology investments compound competitive advantage.
Product Type:
Mature synthetic formulations coexist with emerging biotechnology-derived alternatives, creating a bifurcated supply base where extraction infrastructure and fermentation capacity command divergent capital commitments.
- Natural Extracts:Botanical-derived compounds from citrus, vanilla, and native Amazonian species typically require purity thresholds above 95% and batch-level traceability documentation. São Paulo-based cosmetic manufacturers pull disproportionate volume here, driven by clean-label export requirements and ANVISA's tightening additive scrutiny.
- Synthetic Flavors:Chemically engineered aroma molecules offer cost stability and standardized performance across pH ranges 3.0 to 8.0. Mass-market beverage processors in Brazil's southeastern corridor dominate procurement, prioritizing procurement predictability over label claims.
- Fragrance Oils:Concentrated aromatic formulations blending natural and synthetic inputs serve personal care and household product manufacturers with bundled technical service agreements.
- Essential Oils:Steam-distilled or cold-pressed volatile compounds from regional citrus processors supply captive terpene feedstocks to integrated compounders.
Natural Extracts handles the majority of throughput; Synthetic Flavors is the fastest mover on share.
Application:
End-use diversification tracks regulatory stringency, with pharmaceutical and cosmetic segments absorbing compliance costs that food processors resist.
- Food & Beverage:Palatability enhancement for processed products spans confectionery, dairy, and ready-to-drink categories where ANVISA's maximum usage limit updates force recurring reformulation cycles.
- Cosmetic & Personal Care:Sensorial positioning in skincare, haircare, and fine fragrance commands premium positioning, with São Paulo manufacturing clusters generating procurement efficiencies for fragrance oil suppliers.
- Household Products:Functional scenting for cleaners and air care operates on compressed margin structures where synthetic alternatives dominate volume.
- Pharmaceutical:Taste-masking for pediatric and geriatric formulations requires excipient compatibility testing that extends approval timelines.
Food & Beverage captures the deepest volume base; Cosmetic & Personal Care climbs the fastest as clean beauty regulatory tailwinds accelerate.
End User:
Channel position determines technical service intensity, with direct manufacturer relationships displacing intermediary layers.
- Manufacturers:Integrated food, cosmetic, and pharmaceutical producers with in-house formulation teams purchase bulk compounds and specify stability parameters directly.
- Distributors:Regional inventory holders serving mid-tier processors face margin compression from direct-to-manufacturer digital platforms.
- Retailers:Private-label product developers procure finished flavor systems for captive brand development.
- Wholesalers:Fragmented bulk handlers of essential oils and commodity aroma chemicals serve small-scale regional processors.
Manufacturers control the dominant procurement share; Retailers are expanding most quickly as private-label penetration deepens.
Distribution Channel:
Channel economics split between relationship-intensive direct sales and efficiency-driven digital procurement.
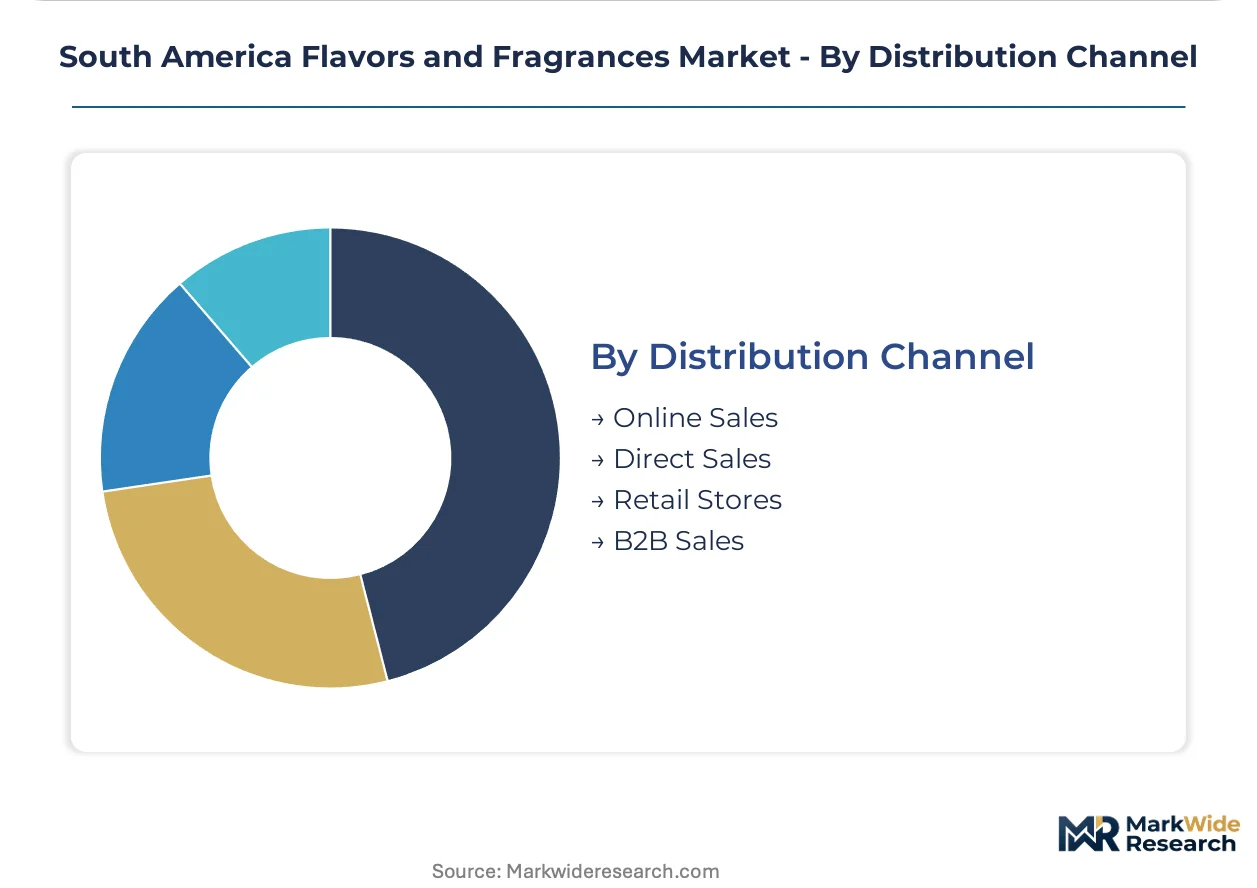
- Direct Sales:Technical sales teams co-develop formulations with major manufacturers, embedding stability testing and regulatory documentation into long-term contracts.
- B2B Sales:Volume contracting between compounders and industrial buyers concentrates in Brazil's southeastern corridor where manufacturing clusters have densified.
- Online Sales:Emerging digital platforms compress distributor margins and enable smaller flavor houses to access mid-tier processors with standardized product catalogs.
- Retail Stores:Limited to small-volume essential oil and specialty extract sales for artisanal producers and consumer DIY segments.
Direct Sales manages the largest transaction value; Online Sales is gaining share fastest as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's southeastern industrial corridor concentrates flavor compounding infrastructure, while Argentina, Chile, Colombia, and Peru develop distinct procurement profiles shaped by trade alignment and domestic regulatory frameworks.
Brazil
São Paulo state anchors regional fragrance oil demand through densified personal care manufacturing clusters. ANVISA's updated labeling requirements for flavor compounds compress formulation timelines while elevating compliance costs for imported synthetic molecules. Campinas and São Paulo city house integrated extraction facilities serving cosmetic and food clients with reduced lead times.
Argentina
Buenos Aires province drives Mercosur-aligned food processing demand for savory flavor systems. The national food safety authority enforces standardized additive codification that reduces cross-border formulation friction with Brazilian trade partners. Rosario's agricultural processing belt generates concentrated procurement of natural extracts for clean-label reformulation.
Chile
Santiago's pharmaceutical and cosmetic manufacturing base pulls taste-masking and sensorial positioning compounds. The country's national pharmaceutical regulator maintains pharmacopeia standards that extend excipient compatibility testing timelines. Valparaíso's port infrastructure facilitates essential oil imports for regional redistribution.
Colombia
Bogotá's processed food sector expands natural extract procurement to meet export-market clean-label requirements. The national food safety authority enforces additive maximum usage limits that mirror ANVISA's tightening scrutiny. Medellín's household product manufacturers concentrate demand for cost-optimized synthetic fragrance formulations.
Peru
Lima's beverage processors drive volume procurement of synthetic flavors where cost control dominates procurement criteria. The country's national food safety authority implements emerging chemical registration requirements that elevate compliance burdens for imported aroma molecules. Arequipa's emerging food processing corridor attracts regional distributor investment for mid-tier processor access.
South America Flavors and Fragrances Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with captive feedstock positions. The vendor base spans integrated multinationals with botanical extraction infrastructure, regional compounders with Mercosur regulatory expertise, and emerging biotechnology-derived molecule developers. Three archetypes dominate: terpene-integrated citrus processors, savory flavor system specialists, and digital-traceability-enabled clean-label suppliers. Competitive moves concentrate on backward integration into Amazonian biodiversity sourcing and direct-to-manufacturer digital platform deployment.
Among Swiss-headquartered integrated compounders, Givaudan SA and Firmenich International SA exemplify platform integrators leveraging botanical extraction infrastructure near São Paulo. Symrise AG represents the terpene-integrated archetype through positioning with Brazilian citrus processors. Kerry Group PLC occupies the regional savory specialization tier with Mercosur-tailored formulation capabilities.
| Leading Market Players |
|---|
| International Flavors & Fragrances Inc. |
| Symrise AG |
| Firmenich International SA |
| Takasago International Corporation |
| Sensient Technologies Corporation |
| Givaudan SA |
| DSM-Firmenich AG |
| Kerry Group PLC |
| MANE SA |
| Others |
Value Network & Pricing Analysis
São Paulo state's concentrated fragrance oil manufacturing clusters concentrate procurement leverage among integrated compounders with captive botanical extraction infrastructure. ANVISA's compliance cost escalation for imported synthetic molecules amplifies regional pricing premiums against foreign competitors lacking local formulation facilities.
Pricing Analysis
ANVISA's maximum usage limit updates dictate the pricing tier structure across Brazil's processed food sector, separating clean-label natural extract premiums from cost-optimized synthetic alternatives. Price differentiation rests on certification grade alignment with Mercosur codification and volume scale commitments from São Paulo-based personal care multinationals. Margins are tightening due to REACH-equivalent registration cost burdens elevating imported synthetic molecule landed costs. Mass-market beverage processors exhibit highest price sensitivity, while cosmetic manufacturers absorbing clean-label export requirements show lowest elasticity.
Supply Chain Analysis
Extended payment terms from São Paulo-based personal care multinationals compress working capital cycles for mid-tier distributors lacking supply-chain finance facilities. Geographic supply concentration centers on Brazil, Argentina, and Chile, with raw material dependencies on citrus terpenes, Amazonian botanicals, and fermentation-derived aroma molecules. Single-source vulnerability runs through Brazilian orange processors controlling captive terpene feedstocks. Distribution runs through direct manufacturer relationships displacing fragmented distributor networks, particularly in Brazil's southeastern industrial corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service agreements bundled with fragrance oil specifications represent a service-attach opportunity expanding faster than commodity compound sales, as São Paulo cosmetic manufacturers demand embedded regulatory documentation and stability testing.
For Market Incumbents: Entrench market position through backward integration into Amazonian biodiversity sourcing and capacity expansion in Campinas extraction facilities. Biotechnology-derived molecule developers threaten traditional extraction margins, necessitating captive supply of native botanicals and dual-jurisdiction regulatory expertise spanning ANVISA and Argentina's national food safety authority. For New Entrants and Emerging Players: Peru's Arequipa food processing corridor offers geographic underpenetration with emerging chemical registration requirements creating temporary compliance asymmetries favoring nimble regional compounders. Mid-tier household product manufacturers in Medellín represent the most penetrable segment, accessible through direct-to-manufacturer digital platforms compressing traditional distributor layers. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated citrus processors seeking to monetize captive terpene positions through fragrance oil compounding spinouts. Long-term viability over a multi-year horizon favors terpene-integrated assets with established São Paulo manufacturing cluster access. The signal to watch is accelerating clean beauty regulatory tailwinds expanding cosmetic ingredient blacklists across national pharmacopeias.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amazonian Biodiversity | Captive supply of novel botanicals secures premium positioning as clean-label mandates tighten across ANVISA jurisdiction. |
| Direct-to-Manufacturer Digital Platform Launch | Compression of distributor margins enables smaller flavor houses to access mid-tier processors in Brazil's southeastern corridor. |
| Dual-Jurisdiction Regulatory Certification Investment | Mercosur-aligned expertise reduces cross-border formulation friction between Brazilian and Argentine food safety authorities. |
| Biotechnology-Derived Molecule Capacity Buildout | Fermentation-based aroma production digitizes batch-level traceability for cosmetic manufacturers facing export-market clean-label requirements. |
| Technical Service Agreement Bundling | Embedded stability testing and pharmacopeia documentation deepens switching costs among São Paulo personal care multinationals. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ANVISA regulatory filings, Mercosur trade documentation, and customs import records for aroma chemical categories. Interviews with flavor compound procurement managers at Brazilian food processors, regulatory affairs leads at Argentine cosmetic manufacturers, and technical sales directors at regional distribution networks inform demand-side validation. Bottom-up volume estimates from manufacturing cluster capacity data triangulate against top-down market sizing derived from trade flow analysis.
Forecast inputs span product type segmentation across natural extracts, synthetic flavors, and biotechnology-derived alternatives, application splits between food and beverage versus cosmetic and personal care, and end-user channel dynamics. CAGRs emerge from regression analysis of historical volume trends against projected regulatory compliance cost trajectories and clean-label penetration curves. Modeling incorporates ANVISA maximum usage limit revision schedules and REACH-equivalent registration rollout timelines as structural demand shifters.
Practitioners should monitor ANVISA additive blacklist expansions and Amazonian biodiversity export restriction proposals for early signals of supply-side constraint. Forecasts reflect assumptions around continued Mercosur trade alignment and stable citrus harvest yields. Macroeconomic volatility in Brazilian real exchange rates, regulatory divergence between national pharmacopeias, or biotechnology scale-up breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Global Acerola Extracts Market
Flavorings and Food Additives
Food Grade Menthol Crystal Market
Flavorings and Food Additives
Orange Terpenes Market
Flavorings and Food Additives
Mandarin Oil Market
Flavorings and Food Additives
Water-Soluble Flavors Market
Flavorings and Food Additives
Sour Cream Powder Market
Flavorings and Food Additives
Lecithin Oleoresin Market
Flavorings and Food Additives
Natural Food Colors and Flavors Market
Flavorings and Food Additives
Vanilla Extract Market
Flavorings and Food Additives
Yeast Based Savory Flavors Market
Flavorings and Food Additives
Citrus Concentrate Market
Flavorings and Food Additives
Dry Powder Flavors Market
Flavorings and Food Additives
Egypt Food Flavor and Enhancer Market
Flavorings and Food Additives
US Flavors Market
Flavorings and Food Additives
Blueberry Extract Market
Flavorings and Food Additives
Flavor Masking Agents Market