
 Pulses Ingredients Market | 2026-2036
Pulses Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Pulses Ingredients Market Analytics
Ingredient-as-a-service contracting is consolidating procurement relationships between food manufacturers and pulse processors. Roquette Frères leverages its European pea protein extraction infrastructure to anchor supply agreements with multinational brands. Cargill competes through backward integration into North American yellow pea sourcing, controlling origination logistics. AGT Food and Ingredients specializes in fractionation technology that extends value capture beyond commodity whole-pulse sales.
Pulses ingredients comprise milled, flaked, fractionated, or extruded derivatives from dried legume seeds, typically containing 20-30% protein and 40-60% starch by dry weight, serving as functional replacers for wheat gluten and dairy proteins in formulated foods. Pea protein isolates lead value generation due to superior emulsion stability and neutral flavor profiles in meat analog applications. Chickpea flour segments sustain premium positioning within gluten-free bakery channels where water-binding capacity commands price separation from commodity starches.
EU REACH and novel food regulations under EFSA govern protein isolate approvals and labeling claims across European food manufacturing. India's FSSAI fortification standards and PLI scheme for food processing infrastructure shape domestic ingredient value addition requirements. Stakeholders must monitor evolving protein content thresholds in codex standards and adapt extraction investments to emerging allergen classification protocols.
Market Dynamics
Plant-based meat manufacturers are consolidating procurement around fractionation-capable processors, compressing supplier tiers and rewiring origination-to-ingredient value capture away from commodity traders.
Growth Catalysts
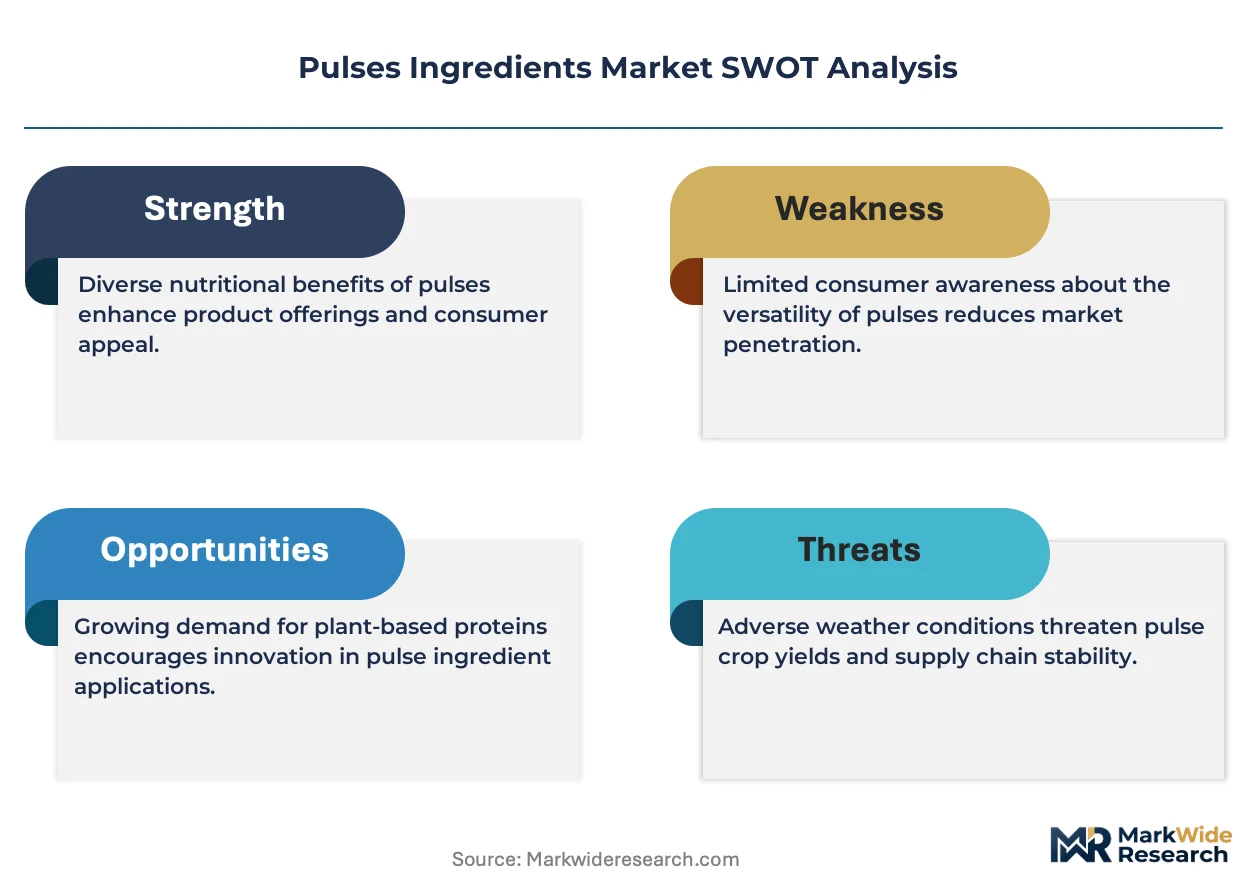
- EU Green Deal protein diversification mandates:Binding targets for livestock protein reduction are redirecting R&D budgets toward pulse-derived isolates in European food manufacturing.
- India's PLI scheme for food processing infrastructure:Capital subsidies for pulse fractionation units are accelerating domestic value addition and export-grade ingredient output.
- Clean-label meat analog formulations:Consumer rejection of methylcellulose and soy isolates is pulling pea protein concentrates into mainstream retail product lines.
Market Restraints
- Yellow pea origination concentration:Canadian and North American prairie supply dominance exposes processors to weather-driven volume volatility and basis risk.
- EFSA novel food approval timelines:Protein isolate authorizations for emerging legume species face 18-24 month safety assessment queues, delaying product launches.
- Functional gaps in high-moisture extrusion:Pea protein's inferior fibrous texture formation versus soy concentrate limits penetration in whole-muscle analog segments.
Strategic Opportunities
- Underpenetrated African processing infrastructure:Faba bean and cowpea surplus zones in Ethiopia and Nigeria lack fractionation capacity, creating first-mover origination advantages.
- Convergence of precision fermentation and pulse protein bases:Hybrid formulations combining heme proteins with pea isolates are opening premium price tiers in foodservice channels.
- FSSAI fortification standards expansion:India's school feeding and public distribution mandates for protein-enriched staples are institutionalizing bulk ingredient offtake.
Industry Challenges
- Fractionation engineering talent scarcity:Specialized protein extraction and membrane filtration expertise concentrates in European and North American technical institutes, constraining plant commissioning in emerging supply regions.
- Legacy dairy and gluten infrastructure retrofit costs:Bakery and dairy processors face capital intensity in adapting extrusion and drying lines for pulse flour handling and allergen segregation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulses Ingredients Market |
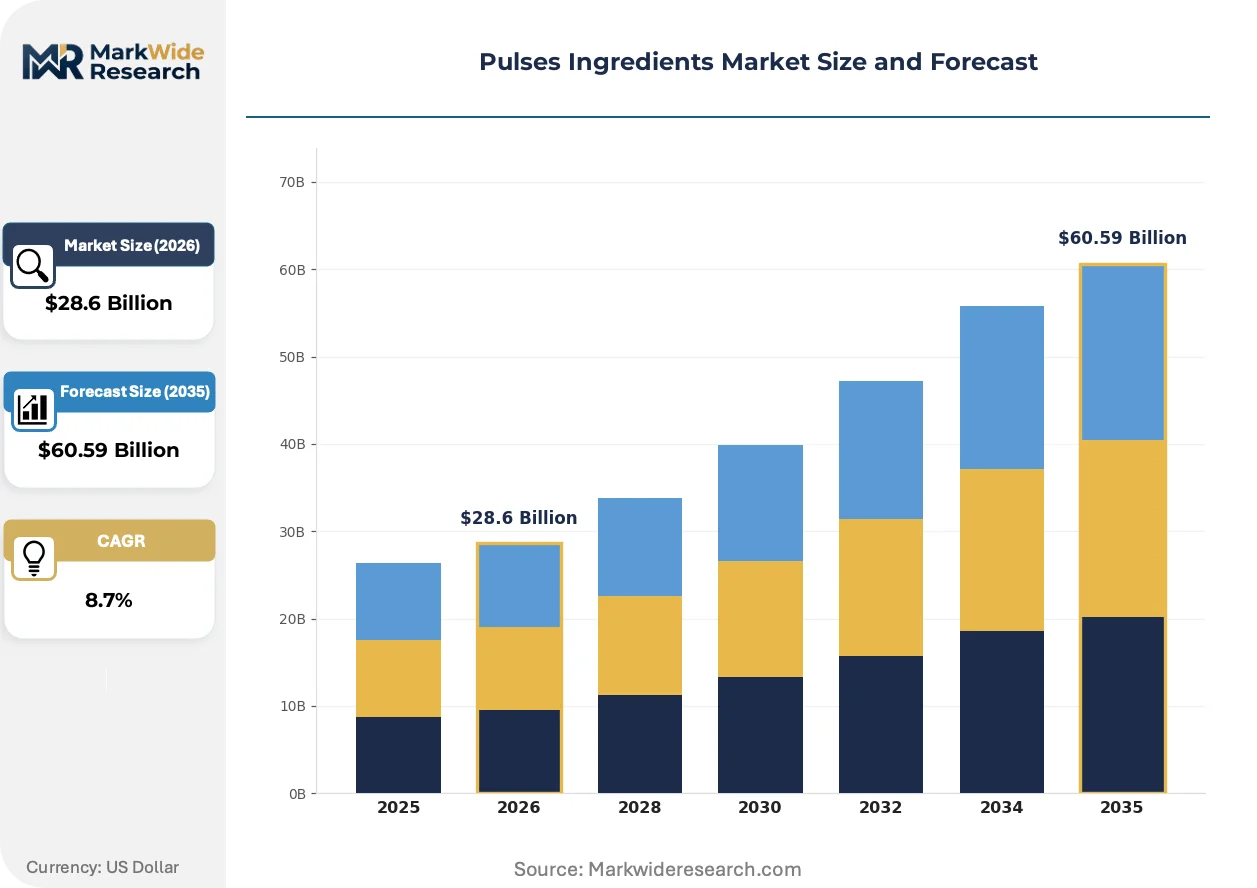
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lentils, Chickpeas, Peas, Beans Application: Snack Foods, Flour, Soups, Dals End User: Food Manufacturers, Restaurants, Retailers, Home Cooks Distribution Channel: Online Retail, Supermarkets, Direct Sales, Wholesalers |
| Companies Covered | Ingredion Incorporated, Roquette Frères, Archer-Daniels-Midland Company, Cargill, AGT Food and Ingredients, Olam International, Adani Wilmar Limited, Emsland Group, Axiom Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulses Ingredients Market Evolving Landscape
Extraction technology advances and procurement contracting models are compressing development cycles and rewiring who captures margin in the ingredient value chain.
Air classification combined with dry fractionation is rewriting protein concentration economics. Mid-scale processors in the Netherlands and Canada are deploying these systems to bypass wet extraction capital requirements. Bakery and snack manufacturers are absorbing these lower-purity concentrates at price points that undercut isolates by 40 percent, forcing incumbent wet-fractionation operators to defend volume through long-term offtake guarantees.
REACH substance authorization expansions are tightening solvent residue thresholds in protein isolate production. Wet extraction facilities using hexane or ethanol face retrofit investments in closed-loop recovery systems. German and French ingredient manufacturers are accelerating enzymatic extraction pilots to preempt regulatory displacement of conventional solvent-based processes.
Ingredient-as-a-service contracts are consolidating procurement decisions at the brand level rather than the commodity desk. Multinational food manufacturers are signing direct supply agreements with pulse processors that bundle formulation support, quality certification, and inventory management. This shift is most visible in European plant-based meat supply chains, where R&D collaboration clauses now accompany volume commitments.
Pulses Ingredients Market Segmentation
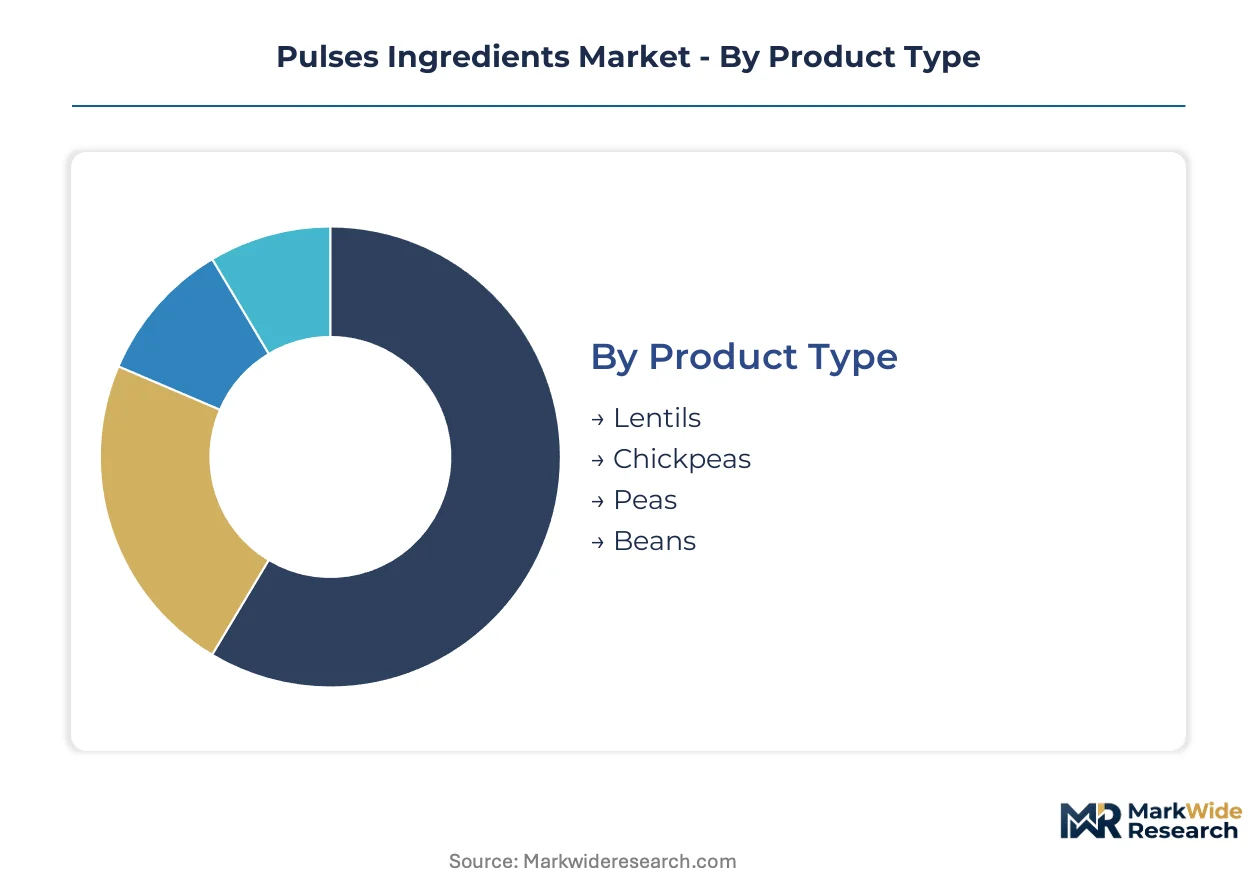
Pulse ingredient procurement patterns diverge sharply across product forms and buyer sophistication tiers. Food manufacturers prioritize functional specifications while retail channels respond to convenience positioning and origin claims.
Product Type:
Protein concentration and fractionation feasibility define competitive positioning across legume species.
- Peas:Yellow and green pea varieties yield isolates with 80-90% protein content and superior emulsion stability for meat analog applications. Clean-label formulators in European plant-based meat channels are substituting pea concentrates for soy isolates as EFSA novel food pathways mature.
- Chickpeas:Flour milled from desi and kabuli varieties delivers water-binding capacity valued in gluten-free bakery formulations. Premium positioning in North American and European retail channels reflects chickpea flour's price separation from commodity wheat alternatives.
- Lentils:Red and green lentil fractions serve emerging protein fortification applications with lower processing intensity than pea isolates.
- Beans:Navy, black, and kidney bean flours anchor ethnic food manufacturing and emerging extruded snack applications.
Pea ingredients lead on scale; chickpea ingredients lead on momentum.
Application:
End-use functionality requirements determine processing investment and margin capture potential.
- Snack Foods:Extruded pulse crisps and puffed formulations leverage lentil and pea flour expansion properties. North American and European clean-label snack brands are displacing potato and corn bases with pulse-derived alternatives as sodium reduction targets tighten.
- Flour:Milled whole-pulse and refined fractions serve gluten-free bakery and pasta manufacturing with varying protein content specifications. Chickpea flour commands premium positioning in European retail channels where celiac certification requirements elevate quality thresholds.
- Soups:Dehydrated pulse ingredients and instant soup bases utilize lentil and bean fractions for texture and protein enrichment.
- Dals:Split and processed lentil products serve South Asian ethnic food manufacturing and diaspora retail channels.
Flour applications concentrate volume; snack foods concentrate growth investment.
End User:
Procurement sophistication and specification control separate institutional buyers from dispersed retail demand.
- Food Manufacturers:Plant-based meat, bakery, and snack processors negotiate direct supply agreements with fractionation-capable pulse processors. Ingredient-as-a-service contracts now bundle formulation support, quality certification, and inventory management for multinational brands.
- Restaurants:Foodservice operators source pulse ingredients through broadline distributors with limited specification control beyond basic allergen documentation.
- Retailers:Private-label pulse flour and packaged dal procurement concentrates in supermarket chains with emerging clean-label requirements.
- Home Cooks:Packaged whole pulses and basic flours reach consumers through retail channels with minimal value addition.
Food manufacturers anchor procurement scale; restaurants show steepest expansion trajectory as plant-based menu penetration deepens.
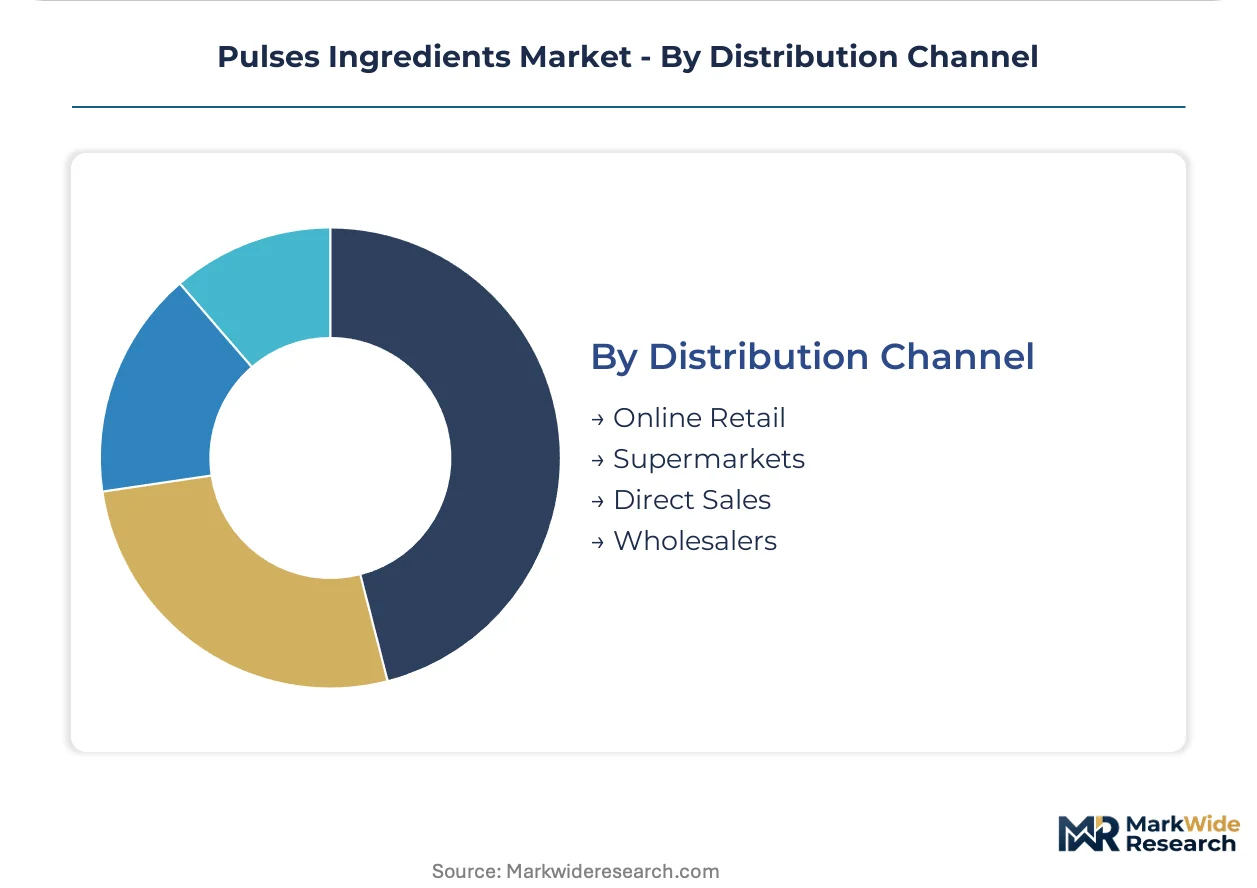
Distribution Channel:
Channel selection reflects buyer scale, specification complexity, and inventory turnover requirements.
- Direct Sales:Large food manufacturers contract directly with Roquette Frères, Cargill, and AGT Food and Ingredients for volume commitments with R&D collaboration clauses. These arrangements bypass commodity traders and compress origination-to-ingredient margin capture.
- Supermarkets:Retail pulse flour and packaged whole-pulse distribution concentrates in European and North American chains with expanding clean-label and organic assortments.
- Wholesalers:Foodservice and smaller food manufacturers source through regional distributors with limited technical support and standard quality grades.
- Online Retail:Direct-to-consumer pulse flour and specialty ingredient sales serve home cooks and small-scale food entrepreneurs with niche origin claims.
Direct sales concentrate value capture; online retail gains share fastest in specialty and organic segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redrawing production geography as wet-fractionation capital migrates toward jurisdictions with faster novel-food approvals and subsidized processing infrastructure. Cost-of-compliance gaps between EFSA timelines and India's PLI scheme are accelerating facility placement decisions.
United States
Yellow pea origination concentrates in North Dakota and Montana prairie zones, supplying domestic fractionation demand from plant-based meat manufacturers. FDA GRAS self-determination pathways allow faster isolate commercialization than EFSA queues. Minneapolis-St. Paul anchors processor headquarters and R&D collaboration clusters for multinational food brands.
Canada
Prairie pulse production in Saskatchewan and Manitoba dominates global yellow pea export volumes for protein extraction. Health Canada novel food consultations run shorter than EFSA equivalents, attracting European processor subsidiary placement. Winnipeg and Regina concentrate fractionation engineering talent and origination logistics control.
India
Government-backed pulse processing clusters in Madhya Pradesh and Maharashtra leverage PLI scheme capital subsidies for domestic value addition. FSSAI fortification standards for school feeding programs institutionalize bulk ingredient offtake. Indore and Mumbai anchor export-grade fractionation capacity and diaspora retail distribution networks.
Germany
REACH solvent residue thresholds are forcing retrofit investments in closed-loop recovery systems at wet extraction facilities. EFSA novel food approval timelines delay emerging legume species launches, compressing first-mover advantages. Hamburg and Frankfurt concentrate enzymatic extraction pilot programs and brand-level procurement contracting.
Netherlands
Air classification and dry fractionation technology deployment bypasses wet extraction capital requirements for mid-scale processors. EU Green Deal protein diversification mandates redirect food manufacturing R&D budgets toward pulse-derived isolates. Wageningen and Rotterdam anchor formulation support services and inventory management integration for ingredient-as-a-service contracts.
Pulses Ingredients Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with fractionation-capable processors consolidating procurement relationships through direct supply agreements. The vendor base organizes around three archetypes: European extraction infrastructure operators, North American origination-integrated traders, and Asian brand-house conglomerates. Capacity expansion and backward integration into sourcing represent the dominant competitive moves, compressing origination-to-ingredient margin capture.
Within the European infrastructure tier, Roquette Frères exemplifies fractionation-scale positioning, while Emsland Group occupies a comparable anchor position in continental processing. Cargill represents the North American origination-integrated archetype with upstream control over prairie logistics. AGT Food and Ingredients sits within the specialized technology tier, with its name signaling Canadian base and ingredients focus.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Roquette Frères |
| Archer-Daniels-Midland Company |
| Cargill |
| AGT Food and Ingredients |
| Olam International |
| Adani Wilmar Limited |
| Emsland Group |
| Axiom Foods |
| Others |
Value Network & Pricing Analysis
Isolate-to-concentrate bifurcation splits procurement tiers, with wet-fractionation isolates commanding premium positions through EFSA novel food certifications while dry-fractionation concentrates penetrate bakery channels at 40 percent discounts. This divergence concentrates margin capture with Roquette Frères and Cargill in premium tiers, while mid-scale Dutch and Canadian processors absorb volume through air-classification economics.
Pricing Analysis
Distributor margins compress in direct-to-manufacturer contracting, where ingredient-as-a-service agreements bundle formulation support and displace commodity traders. Three-tier pricing structure across premium isolates, standard concentrates, and economy whole-pulse flours reflects protein content thresholds and certification grade. Pricing pressure stems from air-classification technology bypassing wet extraction capital requirements. Food manufacturers show highest price sensitivity in snack applications, while plant-based meat processors absorb premiums for emulsion stability specifications.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Minneapolis-St. Paul, and Mumbai anchor hub-and-spoke patterns for fractionated ingredients. Origination concentrates in Canada, India, and the United States for yellow pea supply, with Ethiopian faba bean and Nigerian cowpea zones remaining underdeveloped. Processing draws from prairie logistics infrastructure, PLI-subsidized Indian clusters, and European enzymatic extraction pilots. Single-source vulnerability runs through Canadian prairie weather exposure. Distribution runs through direct sales for multinational food manufacturers and broadline distributors for foodservice channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Pulses Ingredients Market functions as a regulatory compounder, with EU Green Deal protein diversification mandates and India's PLI scheme for food processing infrastructure institutionalizing procurement scale and accelerating facility placement decisions.
For Market Incumbents: Deploy backward integration into origination logistics to defend against Cargill's prairie supply control and AGT Food and Ingredients' fractionation technology specialization. Secure long-term offtake guarantees with plant-based meat manufacturers before air-classification concentrates erode isolate premiums. Invest in closed-loop solvent recovery systems ahead of REACH residue threshold tightening. For New Entrants and Emerging Players: Capture first-mover origination advantages in Ethiopian faba bean and Nigerian cowpea surplus zones where fractionation capacity is absent. Target India's FSSAI fortification standards expansion for institutional bulk ingredient offtake. Enter through enzymatic extraction pilots that preempt regulatory displacement of hexane-based wet extraction. For Investors and Strategic Acquirers: Consolidation pressure builds where fractionation engineering talent concentrates in European and North American technical institutes, constraining plant commissioning in emerging supply regions. Mid-scale processors with air-classification deployment capability represent priority acquisition targets. Monitor EFSA novel food approval timeline compression as inflection signal for emerging legume species commercialization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Origination | Cargill's prairie logistics control secures yellow pea supply against weather-driven volatility. |
| Enzymatic Extraction Pilot Investment | German and French manufacturers preempt REACH solvent residue threshold displacements. |
| Ingredient-as-a-Service Contracting | Roquette Frères bundles formulation support with volume commitments from multinational brands. |
| Air-Classification Technology Deployment | Dutch mid-scale processors bypass wet extraction capital requirements for bakery concentrate supply. |
| PLI Scheme Facility Placement | Indian pulse processing clusters in Madhya Pradesh leverage capital subsidies for export-grade output. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region triangulated against secondary validation. Interviews with fractionation engineering directors, plant-based meat procurement leads, FSSAI regulatory affairs specialists, and pulse processor supply chain managers combined with FDA GRAS filings, EFSA novel food registers, Indian customs trade data, and EU Green Deal implementation reports. Bottom-up facility capacity modeling and top-down protein demand projections were reconciled.
Rate-of-change decomposition separates volume drivers from price-mix effects across the analysis window. Segmentation dimensions include legume species, protein concentration tier, application functionality, and buyer sophistication archetype. CAGRs were derived from facility commissioning timelines, origination yield projections, and regulatory approval queue modeling. Forecast inputs incorporated PLI scheme disbursement schedules and EFSA safety assessment throughput assumptions.
EFSA timeline delays, prairie drought cycles, and enzymatic extraction technology cost curves are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Siraitia Grosvenorii Extract Market
Ingredients
Global Infant Nutrition Ingredients Market
Ingredients
South America Soy Protein Ingredients Market
Ingredients
US Plant-Based Oils Market
Ingredients
Marine Collagen Ingredients Market
Ingredients
Food Ingredients Market
Ingredients
Soy Protein Ingredients Market
Ingredients
Corn Starch Market
Ingredients
Asia-Pacific Potato Protein Market
Ingredients
Canada Soy Protein Market
Ingredients
Europe Agar Market
Ingredients
Lipids Market
Ingredients
Mastic Gum Market
Ingredients
Centella Asiatica Extract Market
Ingredients
Europe Brewers Spent Yeast Market
Ingredients
Edible Halal Gelatin Market