
 Moringa Ingredients Market | 2026-2036
Moringa Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Moringa Ingredients Market Analysis
India's agro-processing corridors are reconfiguring moringa supply dynamics as mechanized drying infrastructure expands in Andhra Pradesh and Gujarat. Organic India Pvt. Ltd. leverages vertically integrated farm networks spanning Madhya Pradesh and Rajasthan to secure organic leaf powder volumes. Grenera Nutrients Pvt. Ltd. anchors its position through ISO-certified extraction facilities that serve pharmaceutical contract manufacturers. Kuli Kuli, Inc. competes via direct-to-consumer channels in North America while sourcing from established African cooperatives.
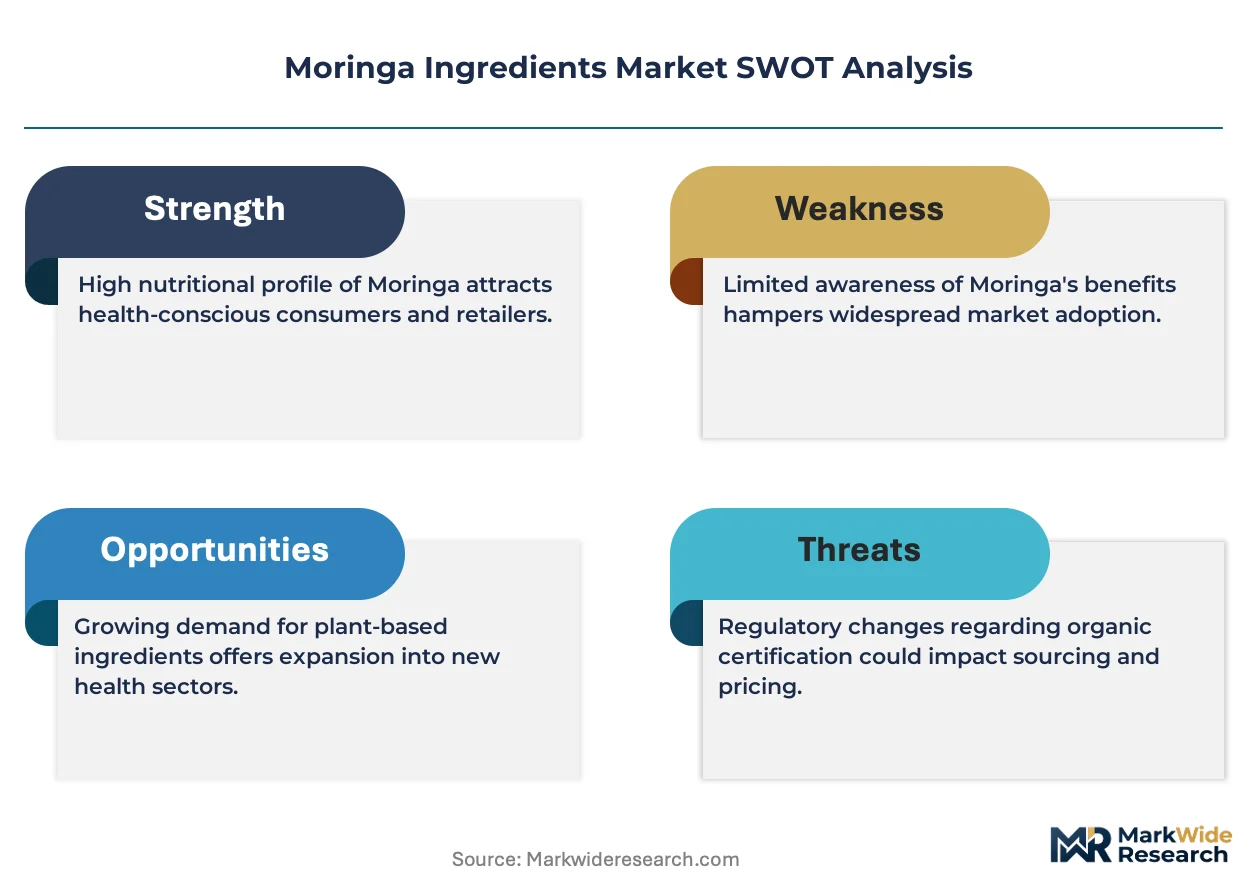
Moringa ingredients comprise dried leaf powder, cold-pressed seed oil, solvent and aqueous extracts, and encapsulated formulations standardized for isothiocyanates, flavonoids, and protein content between 25-30% by dry weight. These inputs serve functional food fortification, topical dermatological preparations, and dietary supplement matrices requiring documented bioactive stability. Leaf powder dominates volume throughput due to its lower processing cost and broader formulation compatibility across food and nutraceutical applications. Seed oil extracts command premium positioning in cosmetics as formulators seek oxidative-stability alternatives to argan and marula oils. The organic feature segment captures disproportionate margin as EU and US buyers enforce residue-testing protocols that exclude conventional smallholder supply.
India's FSSAI mandates pesticide residue limits for botanical ingredients entering food channels, while the USDA National Organic Program governs US import eligibility through accredited certifier verification. EFSA novel food status determinations for moringa leaf extracts create compliance bottlenecks that filter supplier pools to dossier-capable firms. Stakeholders must monitor evolving alkaloid threshold debates in European pharmacopeial forums, as these specifications will determine which extraction processes retain market access.
Market Dynamics
EFSA novel food dossier requirements are filtering supplier pools in Europe, forcing extraction specialists to document bioactive stability and alkaloid profiles that conventional smallholders cannot furnish. This regulatory compression is reshaping procurement relationships between Indian processing clusters and EU nutraceutical formulators.
Growth Catalysts
- EU Green Deal sustainable sourcing mandates:German and Dutch buyers now require deforestation-free supply chain documentation, advantaging certified organic producers in Tamil Nadu and Karnataka with traceable farm networks.
- Seed oil oxidative stability advantages:Cosmetics formulators are substituting moringa oleifera oil for argan and marula oils in facial serums and hair treatments due to superior shelf-life performance.
- Mechanized drying infrastructure expansion:Andhra Pradesh and Gujarat processing corridors are reducing moisture-content variability in leaf powder, enabling pharmaceutical-grade contract manufacturing volumes.
Market Restraints
- Input cost volatility in organic certification:Smallholder conversion to USDA National Organic Program standards requires three-year transition periods without premium pricing, constraining raw material expansion.
- Supply concentration in South Indian monsoon belts:Tamil Nadu and Karnataka clusters face climate-induced yield variability that propagates through European just-in-time procurement schedules.
- EFSA novel food status determination delays:Aqueous leaf extracts remain in regulatory review, blocking formulation entry for dossier-deficient suppliers.
Strategic Opportunities
- Underpenetrated African supply corridors:Malawian and Kenyan cooperatives with Fairtrade certification can bypass Indian price premiums for North American direct-to-consumer channels.
- Convergence of encapsulation and isothiocyanate stabilization:Liposomal delivery technologies are opening sports nutrition applications previously inaccessible to oxidation-prone botanical extracts.
- PLI scheme agro-processing incentives:India's production-linked incentive scheme for food processing infrastructure is subsidizing cold-chain investments that reduce post-harvest bioactive degradation.
Industry Challenges
- Phytochemical standardization skill scarcity:Analytical chemists capable of validating flavonoid and protein content consistency across harvest batches command salary premiums that strain mid-tier processors.
- Multi-jurisdiction certification timeline compression:Simultaneous FSSAI, USDA-NOP, and EU organic audits require dedicated compliance staff that fragmenting supplier bases cannot retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Moringa Ingredients Market |
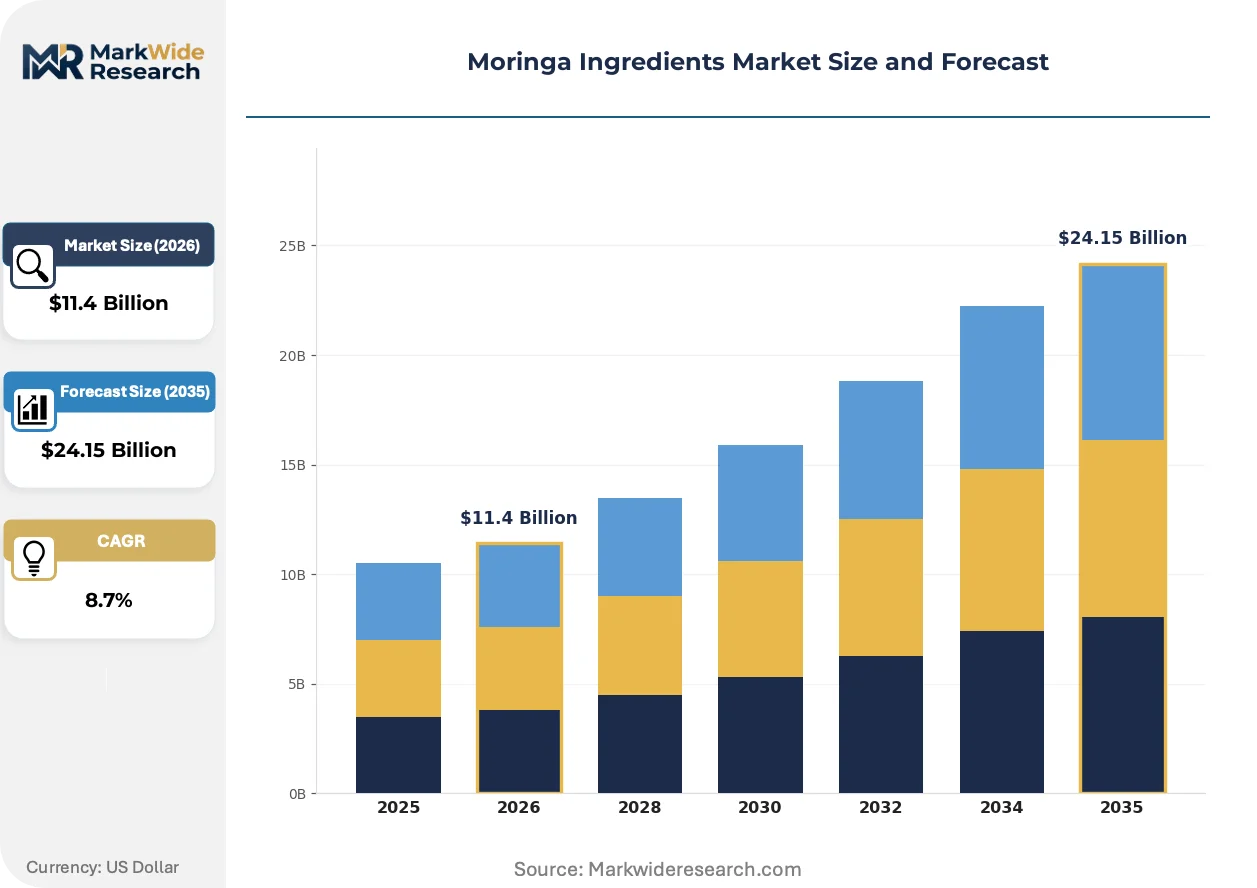
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $24.15 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leaf Powder, Seed Oil, Extracts, Capsules End Use Industry: Food & Beverage, Pharmaceuticals, Cosmetics, Nutraceuticals Feature: Organic, Non-GMO, Vegan, Gluten-Free Form: Whole Leaves, Dried Powder, Liquid Extract, Tablets |
| Companies Covered | Organic India Pvt. Ltd., Earth Expo Company, Kuli Kuli, Inc., Ancient Greenfields Pvt. Ltd., Grenera Nutrients Pvt. Ltd., Botanica Natural Products, Herbs & Crops Overseas, Moringa Initiative Ltd., Green Virgin Products LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Moringa Ingredients Market Emerging Trajectories
Solvent-free supercritical CO2 extraction is displacing conventional hexane-based oil recovery, altering capital intensity thresholds and geographic competitive positioning among processing specialists.
Supercritical CO2 extraction systems recover seed oil without residual solvent contamination, satisfying pharmaceutical contract manufacturer specifications. German and Swiss cosmetics houses are retrofitting extraction lines to secure EFSA-compliant inputs. This capital-intensive shift is rendering obsolete hexane-dependent facilities in unregulated processing zones.
REACH registration requirements for imported botanical extracts are tightening contaminant disclosure obligations for EU market entry. Extraction specialists must now document heavy metal and pesticide residue profiles across supply chain tiers. Leaf powder shipments to Rotterdam and Hamburg are undergoing enhanced customs inspection protocols that delay clearance for non-dossiered suppliers.
Direct-to-consumer subscription models are disintermediating traditional ingredient distributor relationships in North American nutraceutical channels. Kuli Kuli and comparable brands are building captive consumer bases that bypass bulk wholesale purchasing. This channel compression is most visible in California and New York metropolitan markets where wellness-focused demographics prioritize traceable origin claims over price minimization.
Moringa Ingredients Market Segmentation
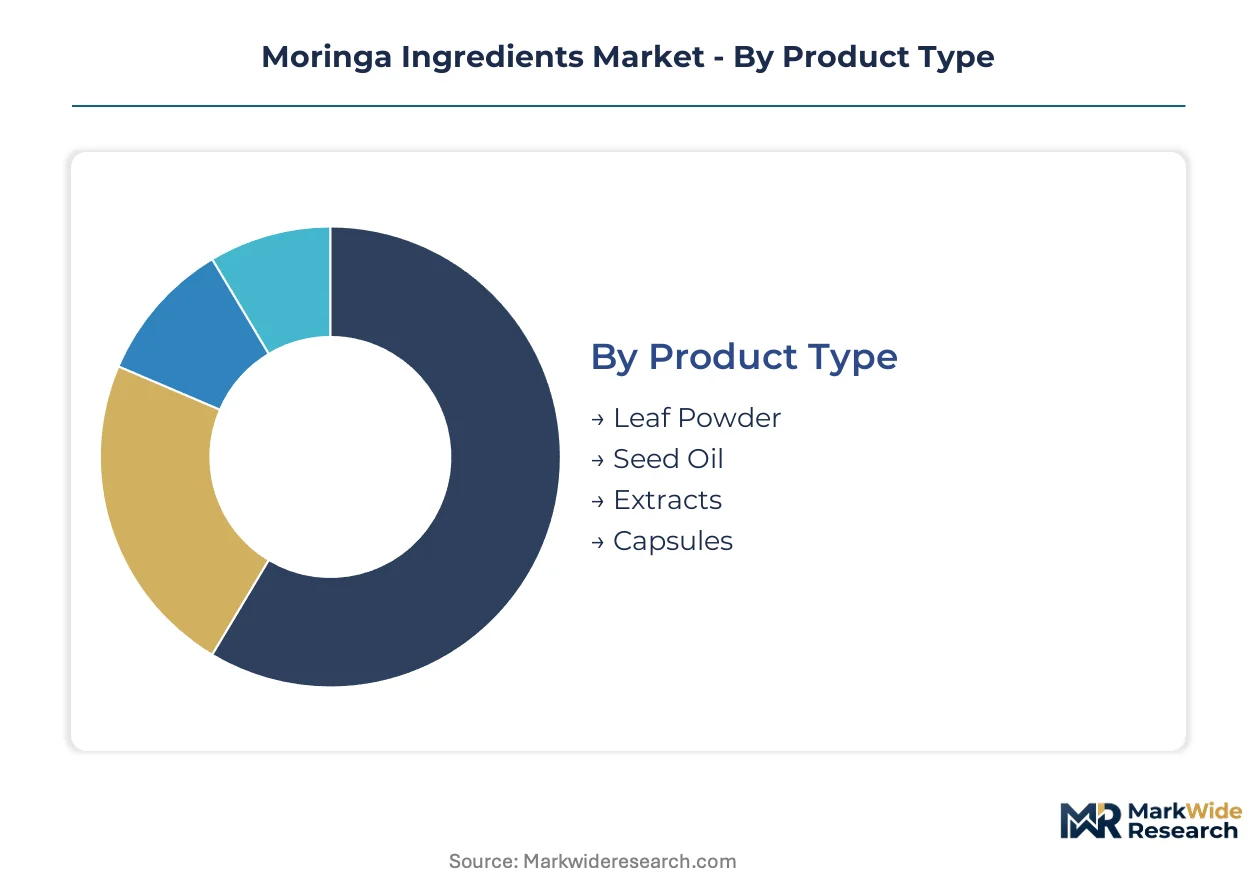
Moringa ingredient procurement patterns diverge sharply across product formats, with shelf-life sensitivity and certification complexity driving distinct inventory velocities. Formulators select segments based on bioactive stability requirements and regulatory pathway feasibility rather than commodity pricing alone.
Product Type:
Leaf powder turns inventory fastest due to lower processing overhead and broader formulation compatibility, while seed oil extracts occupy longer production cycles tied to cold-press or supercritical CO2 extraction timelines.
- Leaf Powder:Dried and milled leaf material standardized to 25-30% protein content by dry weight. Demand concentrates in German nutraceutical formulators seeking EFSA-compliant novel food inputs, constrained by FSSAI pesticide residue mandates that filter Indian supplier pools.
- Seed Oil:Cold-pressed or supercritically extracted oil prized for oxidative stability exceeding argan and marula alternatives. Cosmetics houses in Rotterdam and Hamburg are retrofitting extraction lines to secure REACH-registered volumes for facial serum formulations.
- Extracts:Solvent and aqueous concentrates standardized for isothiocyanates and flavonoids. Aqueous variants face EFSA novel food determination delays that block formulation entry for dossier-deficient suppliers.
- Capsules:Encapsulated formulations targeting sports nutrition and direct-to-consumer channels. Liposomal delivery technologies are opening oxidation-sensitive applications previously inaccessible to botanical extracts.
Leaf powder anchors the volume base while seed oil gains share at the steepest rate.
End Use Industry:
Cost tier stratification separates pharmaceutical contract manufacturers demanding ISO-certified extraction facilities from food fortifiers tolerating broader specification ranges.
- Food & Beverage:Functional fortification applications requiring FSSAI-compliant leaf powder for Indian domestic channels and USDA-NOP-certified inputs for US import eligibility.
- Pharmaceuticals:Bioactive stability documentation and alkaloid profiling requirements filter supplier pools to dossier-capable extraction specialists serving European contract manufacturers.
- Cosmetics:Oxidative stability specifications favor moringa oleifera oil in facial serums and hair treatments. German and Swiss formulators enforce deforestation-free supply chain documentation under EU Green Deal mandates.
- Nutraceuticals:Dietary supplement matrices requiring documented flavonoid consistency. Direct-to-consumer subscription models in California and New York metropolitan markets prioritize traceable origin claims.
Cosmetics commands the steepest margin tier while food and beverage provides the volume foundation.
Feature:
Certification layering determines market access velocity, with organic conversion timelines creating three-year supply gaps that non-GMO and vegan claims bypass.
- Organic:USDA National Organic Program and EU organic certification requiring accredited verifier oversight. Smallholder conversion in Tamil Nadu and Karnataka faces transition-period financing constraints without premium pricing.
- Non-GMO:Identity preservation protocols less stringent than organic standards. Malawian and Kenyan cooperatives leverage Fairtrade certification to bypass Indian organic price premiums for North American channels.
- Vegan:Plant-origin verification targeting wellness-focused demographics in direct-to-consumer markets. Kuli Kuli and comparable brands build captive consumer bases around traceable vegan claims.
- Gluten-Free:Allergen control specifications relevant to celiac-sensitive formulations. Cross-contamination prevention protocols add analytical testing overhead for mid-tier processors.
Organic certification captures disproportionate margin while vegan labeling expands most quickly in North American direct-to-consumer channels.
Form:
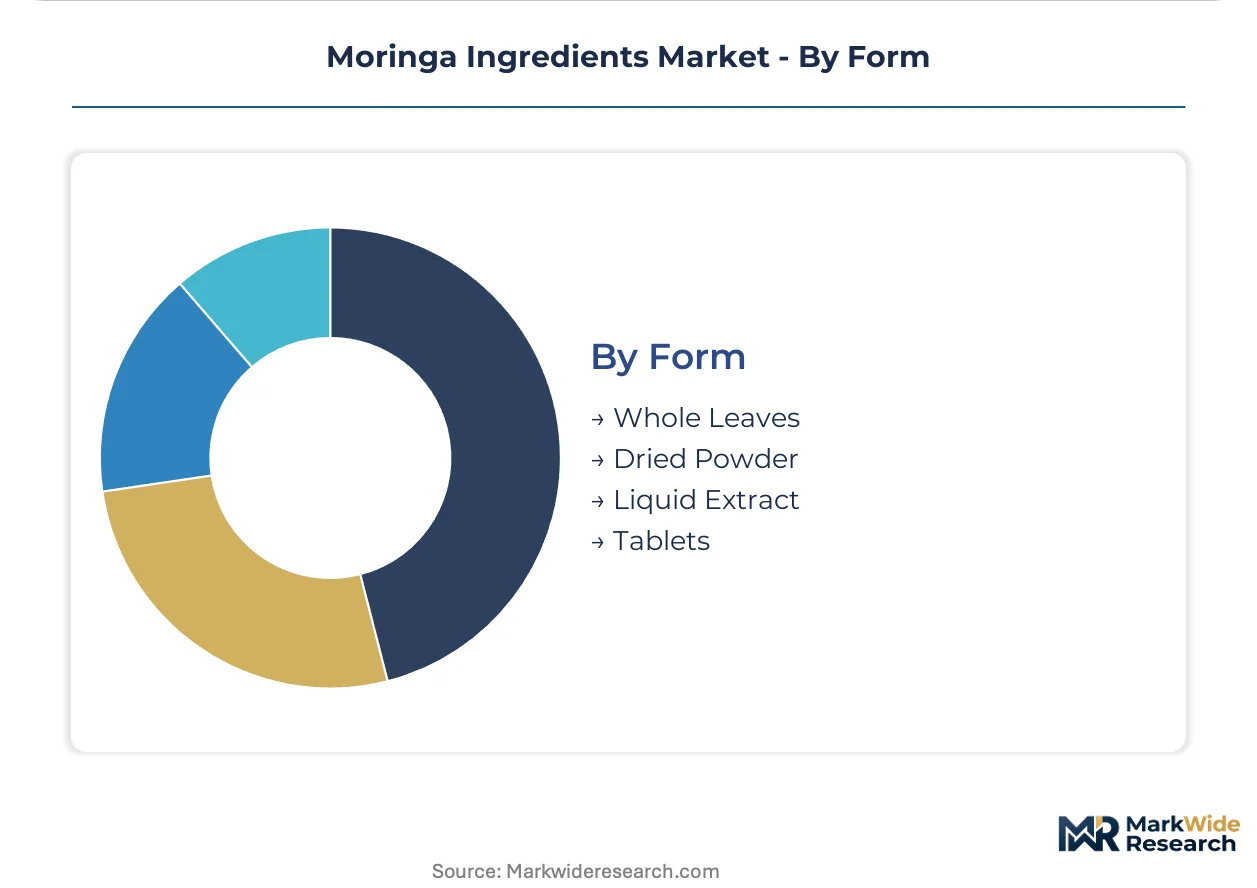
Moisture-content variability and bioactive degradation risk stratify forms by supply chain infrastructure requirements, with whole leaves demanding the most rapid post-harvest processing.
- Whole Leaves:Fresh or minimally processed leaf material requiring immediate cold-chain handling. India's PLI scheme for food processing infrastructure subsidizes investments that reduce post-harvest degradation in Andhra Pradesh and Gujarat corridors.
- Dried Powder:Mechanized drying infrastructure in South Indian processing clusters reduces moisture-content variability. Pharmaceutical-grade contract manufacturing volumes require batch-to-batch flavonoid consistency validation.
- Liquid Extract:Aqueous and solvent-based concentrates. REACH registration requirements for EU market entry mandate heavy metal and pesticide residue documentation across supply chain tiers.
- Tablets:Compressed formulations for dietary supplement channels. Encapsulation and isothiocyanate stabilization convergence opens sports nutrition applications through liposomal delivery technologies.
Dried powder anchors the volume base while liquid extracts face the steepest regulatory pathway constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: European buyers prioritize certified organic leaf powder for novel food applications, while North American channels favor direct-to-consumer seed oil formulations, and Indian domestic demand centers on pharmaceutical-grade extracts.
Germany
German nutraceutical formulators drive premium procurement of EFSA-compliant leaf powder as novel food dossier requirements tighten. The EU Green Deal mandates deforestation-free supply chain documentation that filters conventional smallholder imports. Processing demand concentrates in Hamburg and Rotterdam gateway corridors where REACH-registered extraction specialists serve cosmetics contract manufacturers.
United States
US buyers enforce USDA National Organic Program verification through accredited certifiers, creating three-year transition barriers for Indian supplier conversion. Direct-to-consumer subscription models in California and New York metropolitan markets prioritize traceable vegan claims over price minimization. The FDA dietary supplement regulations govern encapsulated formulation channels while bypassing novel food pathways required in Europe.
India
Domestic pharmaceutical contract manufacturing absorbs ISO-certified extraction volumes from Tamil Nadu and Karnataka processing clusters. FSSAI pesticide residue limits for botanical ingredients entering food channels constrain supplier pools to mechanized drying facilities. Andhra Pradesh and Gujarat agro-processing corridors expand cold-chain infrastructure under PLI scheme subsidies that reduce post-harvest bioactive degradation.
Kenya
Kenyan cooperatives with Fairtrade certification bypass Indian organic price premiums for North American direct-to-consumer channels. The country's national agricultural regulator oversees export phytosanitary protocols that enable seed oil shipments to Rotterdam and Hamburg. Malawian and Kenyan supply corridors remain underpenetrated relative to South Asian volumes but gain traction in wellness-focused demographic segments.
Switzerland
Swiss cosmetics houses retrofit extraction lines to secure supercritical CO2-processed seed oil for facial serum formulations. Swissmedic pharmaceutical regulations align with EFSA novel food guidance, creating dual compliance requirements for extraction specialists. Geneva and Basel processing hubs serve as quality gatekeepers for EU-destined botanical inputs requiring documented heavy metal and pesticide residue profiles.
Moringa Ingredients Market Vendor Landscape
Capability concentration sits with extraction specialists possessing EFSA dossier competence; scale advantage sits with vertically integrated farm networks spanning multiple Indian states. The supplier base stratifies into three tiers: certified organic processors serving European pharmaceutical contract manufacturers, mechanized drying operators supplying North American bulk channels, and direct-to-consumer brands building captive subscription bases. Dominant competitive moves include backward integration into captive farm networks and technology licensing for supercritical CO2 extraction systems.
Among Indian integrated operators, Organic India Pvt. Ltd. and Grenera Nutrients Pvt. Ltd. exemplify the certified-processing archetype with multi-state farm networks and ISO-accredited facilities. Kuli Kuli, Inc. occupies a distinct position as a North American direct-to-consumer specialist sourcing from established African cooperatives. These three anchors illustrate the geographic and channel segmentation that defines competitive positioning: Indian processors compete on certification depth, while US-based brands compete on consumer relationship captivity.
| Leading Market Players |
|---|
| Organic India Pvt. Ltd. |
| Earth Expo Company |
| Kuli Kuli, Inc. |
| Ancient Greenfields Pvt. Ltd. |
| Grenera Nutrients Pvt. Ltd. |
| Botanica Natural Products |
| Herbs & Crops Overseas |
| Moringa Initiative Ltd. |
| Green Virgin Products LLC |
| Others |
Supply Flow & Price Mechanics
Undercapacity in mechanized drying infrastructure across Andhra Pradesh and Gujarat processing corridors is compressing supplier margins while elevating pricing power for ISO-certified operators serving pharmaceutical contract manufacturers. This utilization squeeze simultaneously drives consolidation toward capital-intensive facilities and widens bid-ask spreads between certified organic and conventional smallholder supply.
Pricing Analysis
Long-term offtake agreements dominate procurement between European nutraceutical formulators and Indian processing clusters, locking in volume commitments that insulate certified suppliers from spot-market volatility. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-dossiered organic leaf powder from FSSAI-compliant conventional grades and unstandardized smallholder lots. Cost compression in mid-tier mechanized drying operations is intensifying because PLI scheme subsidies favor capital-intensive entrants over legacy operators. German buyers exhibit least price sensitivity due to EU Green Deal compliance mandates, while North American direct-to-consumer channels prioritize traceable origin claims over cost minimization.
Supply Chain Analysis
Extended payment terms from Rotterdam and Hamburg gateway buyers are straining working capital for Tamil Nadu and Karnataka cooperatives, accelerating supplier consolidation toward vertically integrated farm networks. Raw material flows draw from leaf cultivation belts in India, seed oil extraction corridors in Kenya and Malawi, and supercritical CO2 processing hubs in Germany and Switzerland. Single-source vulnerability concentrates in South Indian monsoon-dependent harvests that propagate yield variability through European just-in-time schedules. Distribution runs through certified organic aggregators serving pharmaceutical contract manufacturers, direct-to-consumer subscription platforms in North America, and cosmetics houses retrofitting extraction lines for REACH-registered volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The moringa ingredients market is navigating cyclical recovery as EFSA novel food dossier backlogs clear and deferred pharmaceutical procurement resumes. This regulatory normalization is releasing pent-up demand from European nutraceutical formulators.
For Market Incumbents: Harden EFSA dossier capabilities against emerging African cooperative competition by embedding analytical chemists for batch-to-batch flavonoid validation. Deepen backward integration into captive farm networks spanning Madhya Pradesh and Rajasthan to secure organic transition-period volumes before three-year certification timelines constrain competitor expansion.
For New Entrants and Emerging Players: Build out Fairtrade-certified supply corridors in Kenyan and Malawian cooperatives to bypass Indian organic price premiums for North American direct-to-consumer channels. Target wellness-focused demographic segments in California and New York metropolitan markets with traceable vegan claims that command subscription pricing power unavailable in bulk wholesale.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across supercritical CO2 extraction sub-segments as German and Swiss cosmetics houses retrofit lines to secure EFSA-compliant seed oil volumes. Acquire extraction specialists with REACH registration competence and documented heavy metal profiling capabilities. Watch EFSA novel food determination timelines for aqueous leaf extracts as the inflection signal for formulation entry expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Dossier Investment | Secures novel food pathway access for European nutraceutical formulators facing regulatory compression. |
| Supercritical CO2 Retrofit | Enables REACH-registered seed oil supply to Hamburg and Rotterdam cosmetics contract manufacturers. |
| Fairtrade Certification Buildout | Unlocks North American direct-to-consumer channels bypassing Indian organic price premiums. |
| Backward Farm Integration | Captures three-year organic transition volumes in Madhya Pradesh before competitor lock-in. |
| Liposomal Delivery Development | Opens sports nutrition applications for oxidation-sensitive isothiocyanate formulations. |
Methodological Framework
A standing panel of extraction facility operators, organic certification auditors, nutraceutical procurement managers, and cosmetics formulators provided ongoing calibration across primary interview cycles. Secondary validation drew from FSSAI regulatory filings, EFSA novel food submission databases, USDA National Organic Program certifier records, and Indian PLI scheme disbursement disclosures. Bottom-up volume estimates from Tamil Nadu and Karnataka processing clusters were triangulated against top-down demand assessments from European and North American buyer channels.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning product type, end-use industry, certification feature, and geographic supply corridor. CAGRs were derived from modeled volume trajectories incorporating mechanized drying capacity expansion, EFSA determination timeline assumptions, and organic conversion rate sensitivities. Industry-specific inputs included alkaloid threshold debates in European pharmacopeial forums and REACH registration requirement phase-ins for botanical extracts.
Stress conditions across monsoon yield variability, EFSA review timeline extensions, and organic certification auditor availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway clearance and infrastructure subsidy continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Europe Dairy Ingredients Market
Ingredients
Asia-Pacific Yeast Market
Ingredients
Europe Corn Glucose Market
Ingredients
Global Palm Kernel Oil and Coconut Oil Based Natural Fatty Acids Market
Ingredients
Sea Salt Market
Ingredients
All Purpose Flour Market
Ingredients
Blackcurrant Concentrate Market
Ingredients
Aroma Ingredients Market
Ingredients
Malted Barley Flour Market
Ingredients
Global Protein Hydrolysate Ingredients Market
Ingredients
Coconut Cream Powder Market
Ingredients
Elecampane Root Market
Ingredients
Soybean Oil Market
Ingredients
Isoamyl Laurate Market
Ingredients
Global Vitamin Ingredients Market
Ingredients
Global Dry Yeast Market