
 Beef Concentrate Market | 2026-2036
Beef Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Beef Concentrate Market Analysis
The gap between premium grass-fed beef concentrate and commodity grain-fed variants is realigning procurement patterns across the food industry. JBS S.A. leverages its integrated Brazilian supply chain to anchor volume in Latin American markets. Cargill Inc. competes through specialized extraction technologies that sustain higher protein yields in dry concentrate formats. Tyson Foods differentiates via controlled channel relationships with large-scale catering operators in North America.
Beef concentrate is a reduced, shelf-stable derivative produced by simmering beef and bones to extract proteins, minerals, and flavor compounds, then concentrating the liquid through evaporation or dehydration to achieve solids content typically exceeding 50 percent. Food manufacturers deploy it as a foundational flavoring and nutritional additive in soups, sauces, and processed meat applications. Liquid beef concentrate leads current volume owing to its ease of incorporation in industrial batch processing, while freeze-dried formats command premium positioning among specialty retail channels. The food industry segment dominates end-user demand, though online retailers represent the fastest-growing outlet as direct-to-consumer brands bypass traditional distribution tiers.
FDA oversight of labeling and safety standards for meat products in the United States shapes product claims and import documentation requirements, while EFSA and REACH frameworks in Europe govern contaminant thresholds and chemical inputs in processing facilities. Brazil's Ministry of Agriculture and ANVISA enforce sanitary protocols that determine export eligibility for South American concentrate suppliers. Stakeholders must monitor evolving carbon-accounting rules under the EU Green Deal and assess how emerging traceability mandates will reshape sourcing decisions across beef concentrate value chains.
Market Dynamics
The EU's Farm to Fork Strategy is compressing sourcing timelines for livestock-derived ingredients while Brazilian supply chain expansion creates new volume anchors for South American concentrate exports.
Growth Catalysts
- Clean-label formulation mandates:EFSA contaminant thresholds are pushing soup and sauce manufacturers toward certified concentrate bases with documented provenance.
- Ready-to-eat meal proliferation:Processed meat manufacturers are expanding procurement of concentrated beef bases for industrial batch processing.
- Freeze-drying technology maturation:Specialty retail channels are absorbing premium-positioned dry formats as protein yield extraction improves.
Market Restraints
- Feed input cost volatility:Grain and forage price swings transmit directly into beef concentrate production economics with limited hedging instruments.
- Sanitary protocol fragmentation:Divergent ANVISA, FDA, and EFSA documentation requirements create export eligibility friction for cross-border suppliers.
- Plant protein substitution:Pea and mycelium-derived flavor bases are capturing formulation share in mid-tier soup and sauce applications.
Strategic Opportunities
- Direct-to-consumer channel emergence:Online retailers represent the fastest-growing outlet as specialty brands bypass traditional distribution tiers.
- Carbon-accounting compliance services:EU Green Deal traceability mandates are creating demand for integrated sourcing verification platforms.
- Specialty retail premiumization:Freeze-dried formats command price multiples in gourmet and health-food segments underserved by liquid concentrate suppliers.
Industry Challenges
- Cross-functional regulatory expertise scarcity:Few procurement teams possess simultaneous fluency in FDA labeling, REACH chemical inputs, and ANVISA sanitary protocols.
- Legacy ERP integration complexity:Batch processing facilities struggle to embed carbon-accounting modules into existing manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beef Concentrate Market |
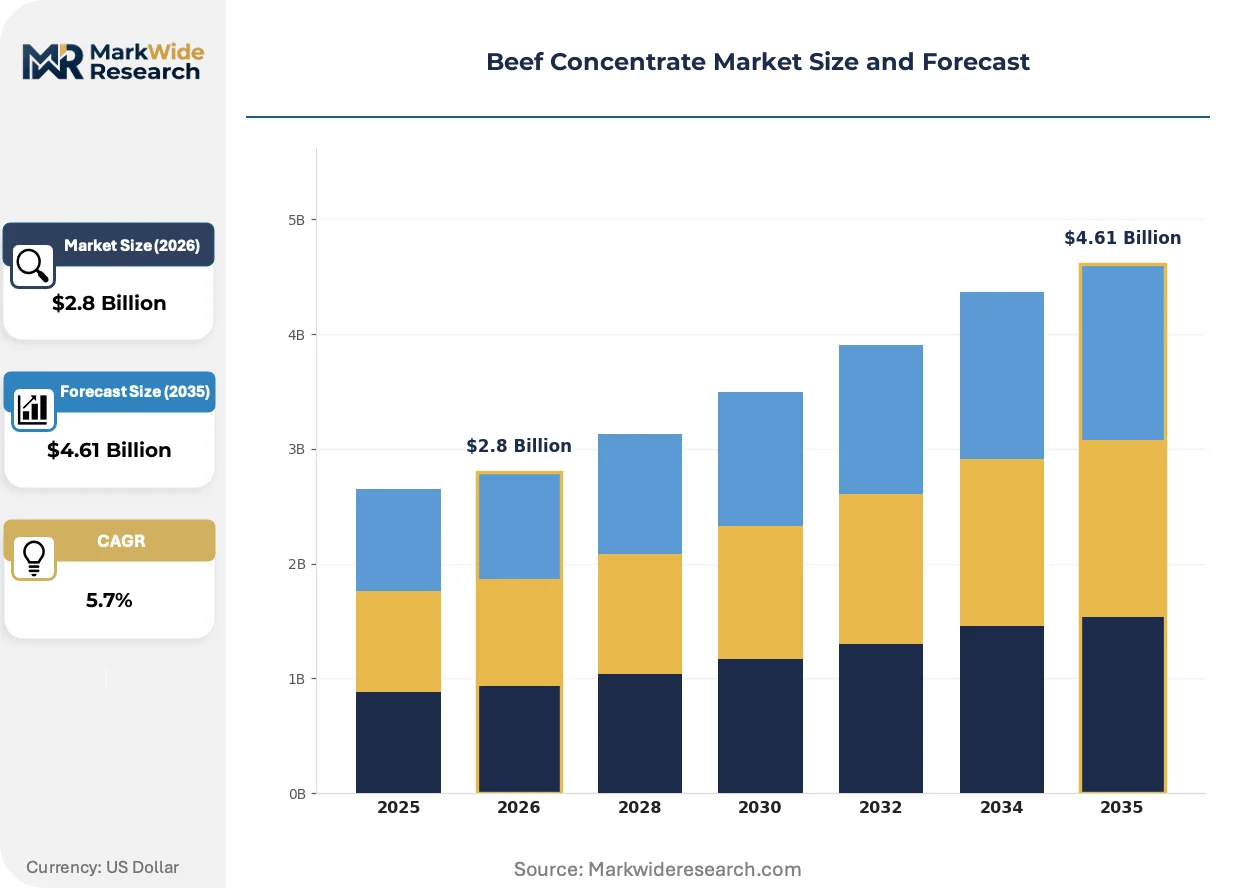
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Beef Concentrate, Liquid Beef Concentrate, Freeze-Dried Beef, Beef Broth End User: Food Industry, Catering Services, Retail Stores, Online Retailers Packaging Type: Bottles, Pouches, Cans, Tetra Packs Distribution Channel: Direct Sales, Distributors, Online Platforms, Retail Chains |
| Companies Covered | Cargill Inc., Tyson Foods Inc., JBS S.A., BRF S.A., National Beef Packing Company LLC, Hormel Foods, Conagra Brands, Sysco Corporation, Verde Farm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beef Concentrate Market Emerging Trajectories
Extraction technology advances and regulatory traceability mandates are reconfiguring how beef concentrate moves from abattoir to formulation facility.
Membrane filtration systems are electrifying protein recovery rates in liquid concentrate production. Mid-scale soup manufacturers in North America are retrofitting evaporator lines with ceramic ultrafiltration modules. The technology is electrifying competitive dynamics between dry and liquid format suppliers by collapsing yield gaps that previously favored freeze-dried alternatives.
REACH chemical input disclosures are tightening processing facility compliance burdens across European concentrate operations. ECHA registration requirements now extend to flavor compound precursors used in thermal extraction. Dry format producers with integrated solvent recovery systems are capturing preferential supplier status from multinational sauce manufacturers.
Direct sourcing contracts between concentrate producers and catering operators are displacing traditional broker-mediated procurement in North American foodservice. Large-scale institutional buyers are negotiating multi-year protein supply agreements with specified solids content and origin documentation. Brazil-based processors with captive cattle supply are securing preferred vendor positions in this channel shift.
Beef Concentrate Market Segmentation
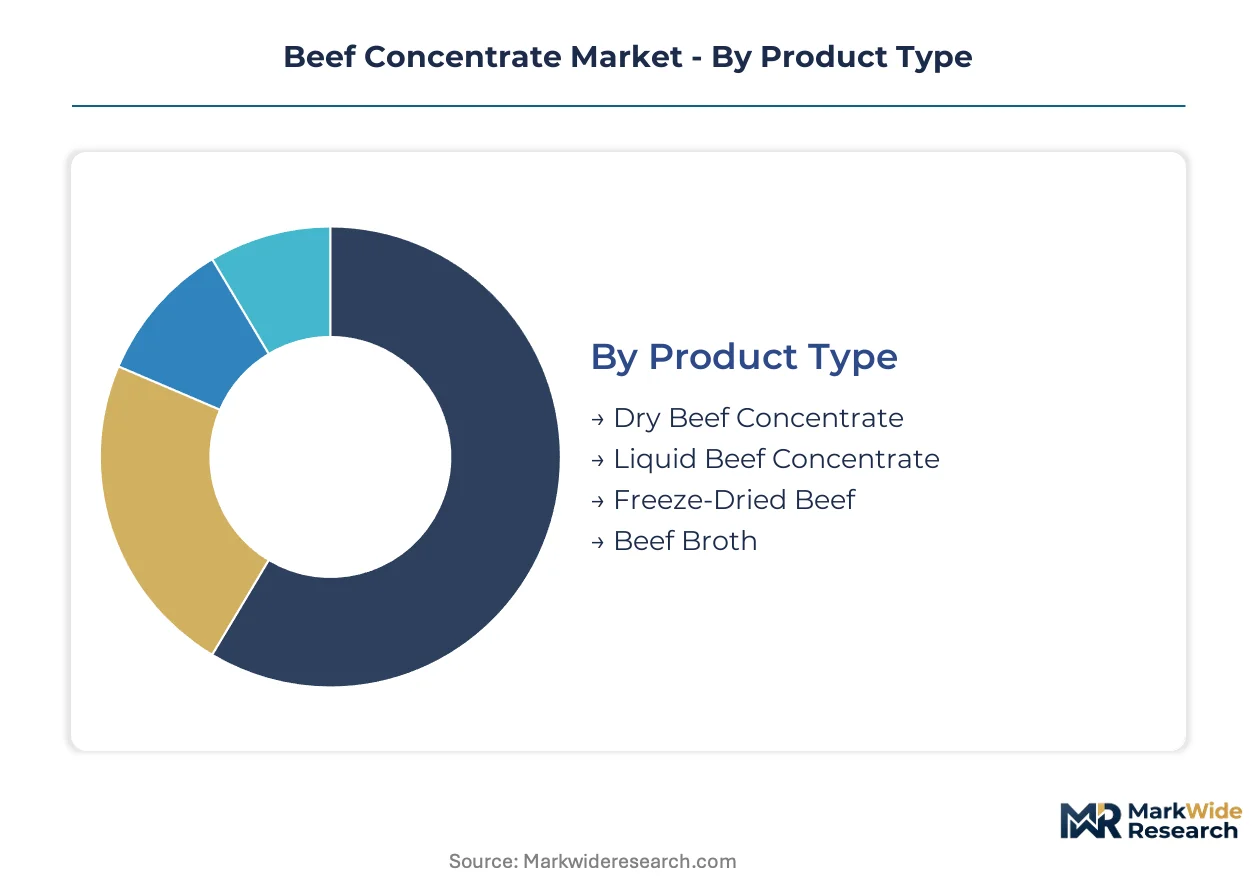
Beef concentrate procurement varies sharply by format, end-use scale, and channel economics. Capital allocation decisions across extraction technology, packaging lines, and distribution infrastructure determine competitive positioning in each segment cluster.
Product Type:
Freeze-drying and evaporation systems demand the heaviest upfront equipment investment, while liquid processing lines offer lower barriers to entry.
- Liquid Beef Concentrate:Produced through thermal reduction and membrane filtration to achieve 50%+ solids content. Industrial soup and sauce manufacturers in the United States deploy this format for seamless batch incorporation. FDA labeling requirements for meat product claims shape formulation specifications.
- Dry Beef Concentrate:Spray-dried or roller-dried powders with extended shelf stability. Brazilian processors supply bulk volumes to institutional catering operators seeking transport efficiency. ANVISA sanitary protocols govern export eligibility documentation.
- Freeze-Dried Beef:Sublimation dehydration preserves volatile flavor compounds for premium applications. Specialty retail channels absorb limited volumes.
- Beef Broth:Lower concentration liquid requiring refrigeration or aseptic packaging. Foodservice distributors move this through refrigerated logistics networks.
Liquid concentrate absorbs the bulk of installed capacity; freeze-dried formats are expanding most quickly.
End User:
Volume concentration follows customer scale, with industrial processors commanding dedicated production lines and small-lot specialty buyers driving margin capture.
- Food Industry:Processed meat manufacturers and soup base formulators purchase in bulk totes or tanker quantities. EFSA contaminant thresholds under EU Green Deal traceability mandates are compressing supplier qualification timelines.
- Catering Services:Large-scale institutional operators negotiate multi-year protein supply agreements with specified solids content. Tyson Foods maintains controlled channel relationships with North American catering networks.
- Retail Stores:Branded consumer packs through conventional grocery placement. Shelf space competition from plant-based alternatives intensifies.
- Online Retailers:Direct-to-consumer specialty brands bypass traditional distribution tiers. Freeze-dried premium formats gain traction through subscription models.
Food industry procurement commands the largest share of production volume; online retailers are climbing the fastest.
Packaging Type:
Barrier properties and shelf-life extension requirements drive capital allocation across filling lines and sterilization equipment.
- Pouches:Flexible multilayer films with oxygen scavenging layers. Food manufacturers favor this format for industrial ingredient shipments due to cubic efficiency.
- Bottles:PET or glass containers for liquid concentrate retail presentation. REACH chemical input disclosures affect European blow-molding facility compliance.
- Cans:Metal containers with thermal processing compatibility. Established infrastructure supports legacy soup base supply chains.
- Tetra Packs:Aseptic carton systems for extended ambient shelf life. Higher line investment limits adoption to volume-committed processors.
Pouch packaging dominates industrial ingredient flows; aseptic cartons are gaining share fastest in retail liquid segments.
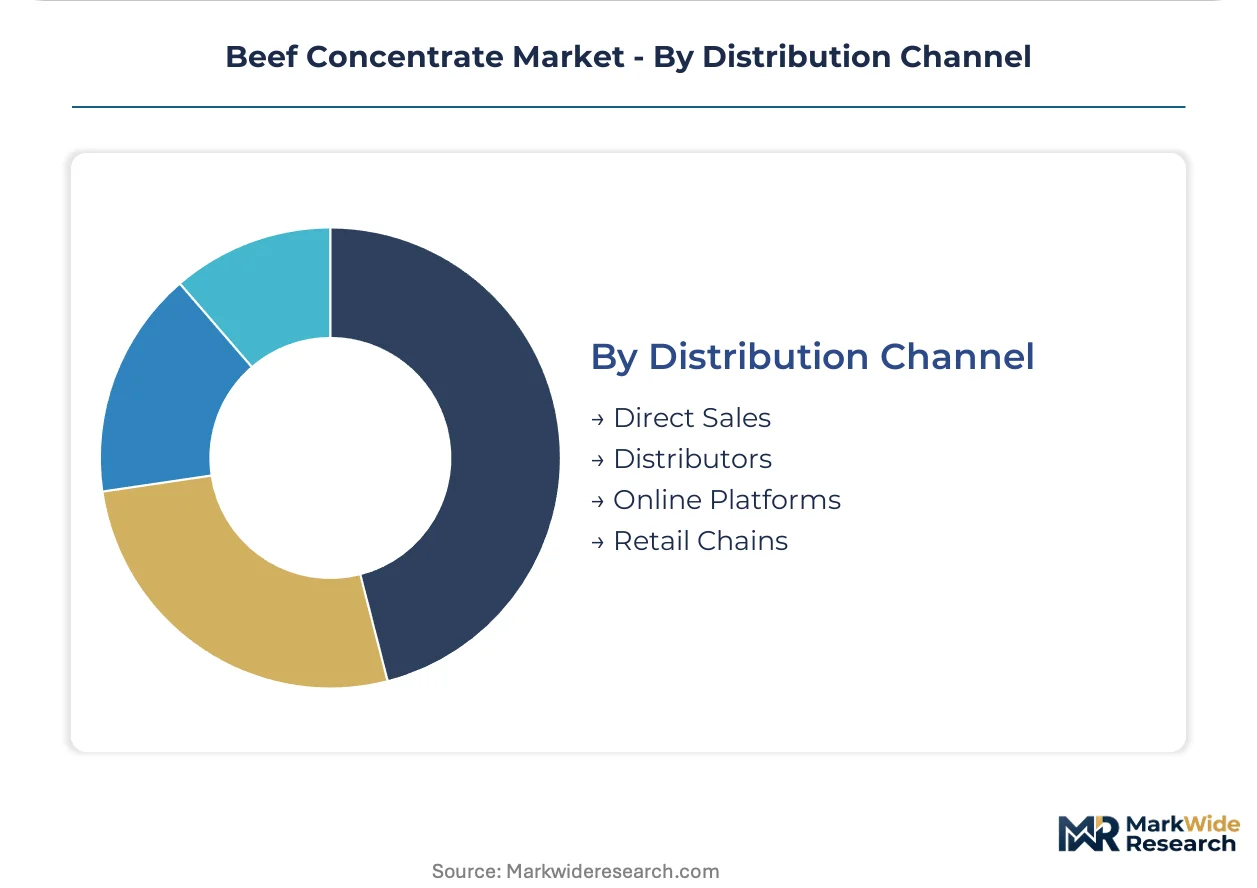
Distribution Channel:
Channel selection determines working capital intensity and customer relationship depth across the value chain.
- Direct Sales:Producer-to-manufacturer contracts with multi-year protein supply agreements. Brazilian processors with captive cattle supply secure preferred vendor positions.
- Distributors:Broker-mediated procurement serving fragmented foodservice accounts. Margin compression from inventory carrying costs pressures this tier.
- Online Platforms:Direct-to-consumer fulfillment bypassing wholesale markups. Specialty brands leverage subscription models for freeze-dried formats.
- Retail Chains:Slotting fees and promotional spending requirements strain smaller concentrate suppliers. Consolidated buyer power concentrates in North American and European grocery networks.
Direct sales channels absorb the majority of industrial volume; online platforms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors South American beef concentrate production through JBS S.A.'s integrated processing corridors. The city's captive cattle supply and export infrastructure position Brazilian suppliers as volume leaders for international food manufacturers seeking documented provenance.
United States
Processed meat manufacturers in Chicago and Omaha drive bulk procurement of liquid concentrate for industrial soup bases. FDA labeling requirements for meat product claims shape formulation specifications and import documentation. Tyson Foods maintains controlled channel relationships with large-scale catering operators across the Midwest and Southeast corridors.
Brazil
JBS S.A. and BRF S.A. expand South American production capacity to capture ready-to-eat meal sector demand. ANVISA sanitary protocols determine export eligibility documentation for cross-border shipments. São Paulo's integrated abattoir-to-concentrate facilities anchor volume supply for institutional catering networks.
Germany
Soup and sauce manufacturers in Bavaria and North Rhine-Westphalia source certified concentrate bases with documented provenance. EFSA contaminant thresholds under EU Green Deal traceability mandates compress supplier qualification timelines. Cologne's food processing clusters retrofit evaporator lines with membrane filtration modules for yield optimization.
China
Industrial food processors in Shandong and Guangdong provinces absorb imported beef concentrate for flavor base formulations. The country's national food safety regulator enforces contaminant thresholds that determine import eligibility for South American suppliers. Qingdao's port infrastructure facilitates bulk liquid concentrate shipments for regional distribution.
Canada
Specialty retail channels in Toronto and Vancouver absorb freeze-dried premium formats through direct-to-consumer subscription models. Health Canada and PMRA govern chemical input disclosures in processing facility compliance. Alberta's cattle processing corridors supply raw material for domestic concentrate production serving North American gourmet segments.
Beef Concentrate Market Vendor Landscape
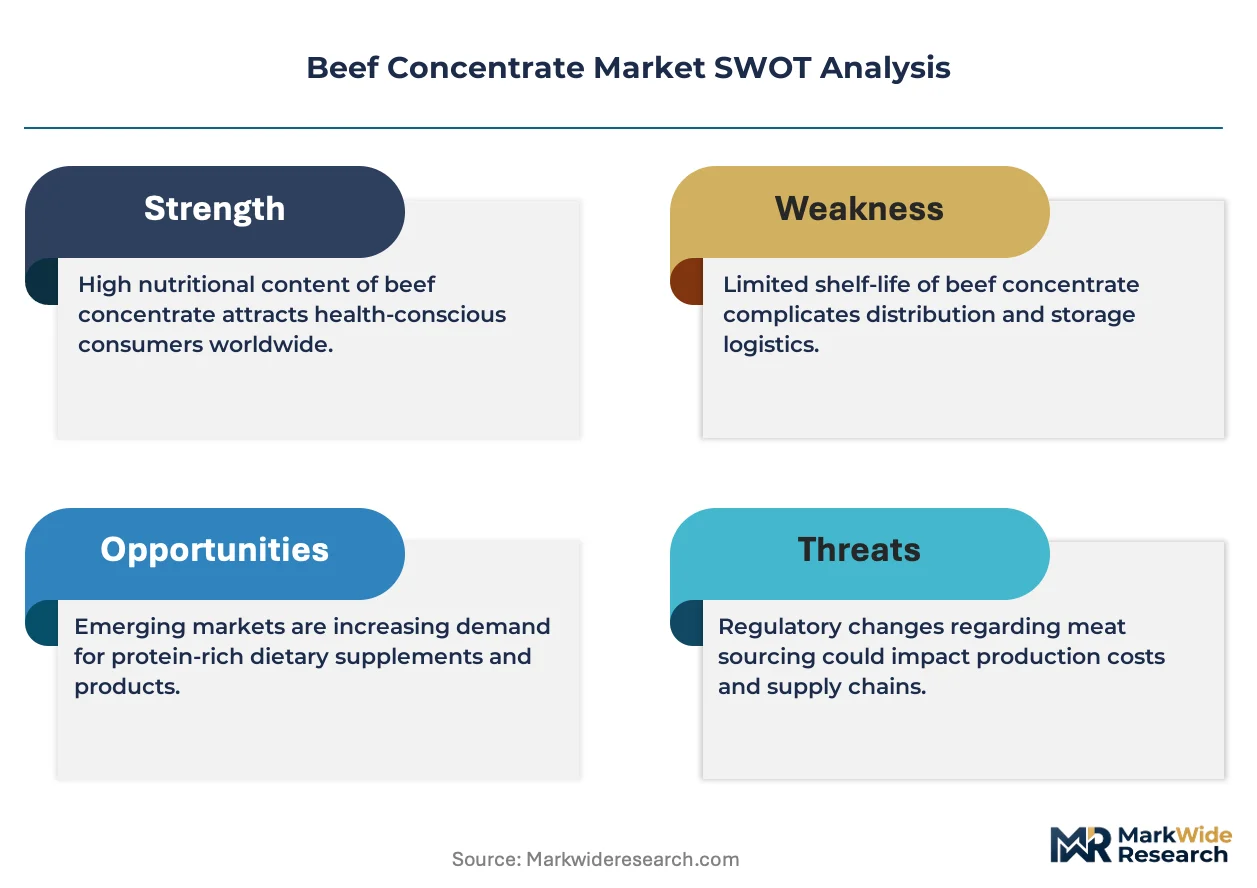
Capital-heavy producers compete with asset-light designers across the beef concentrate value chain. The market exhibits tiered consolidation with integrated meatpackers controlling upstream supply and specialized extractors dominating technology-intensive segments. Three archetypes define competitive positioning: captive supply chain operators, extraction technology specialists, and direct-to-consumer brand builders. Capacity expansion in Brazilian processing corridors and strategic partnerships for carbon-accounting compliance represent dominant competitive moves.
Among Brazilian-based integrated processors, JBS S.A. and BRF S.A. occupy positions anchored by captive cattle supply and export infrastructure. Cargill Inc. exemplifies the extraction technology specialist archetype through its focus on protein yield optimization in dry concentrate formats. Tyson Foods represents the North American channel control model with established relationships across institutional catering networks.
| Leading Market Players |
|---|
| Cargill Inc. |
| Tyson Foods Inc. |
| JBS S.A. |
| BRF S.A. |
| National Beef Packing Company LLC |
| Hormel Foods |
| Conagra Brands |
| Sysco Corporation |
| Verde Farm |
| Others |
Supply Flow & Price Mechanics
Chicago Mercantile Exchange live cattle futures transmit volatility directly into beef concentrate production economics, compressing margins for grain-fed processors while amplifying price premiums for grass-fed certification tiers across North American and European procurement networks.
Pricing Analysis
Yield-per-ton extraction rates anchor value-based pricing tiers in liquid concentrate procurement. Three-tier pricing structure across premium grass-fed, standard commodity grain-fed, and economy industrial-grade levels separates JBS S.A.'s Brazilian-origin certified bases from unbranded commodity alternatives. Price differentiation hinges on EFSA contaminant documentation and carbon-accounting traceability under EU Green Deal mandates. Food industry buyers exhibit highest price sensitivity in bulk liquid formats, while specialty retail channels absorb freeze-dried premiums with minimal volume elasticity.
Supply Chain Analysis
EU Green Deal traceability certification and ANVISA sanitary documentation function as dual gating mechanisms for export eligibility. Supply concentrates in Brazil, the United States, and Germany, with São Paulo's integrated abattoir corridors feeding captive cattle into JBS S.A.'s concentrate extraction facilities. Raw material flows draw from Midwestern U.S. feedlot operations, Brazilian pasture systems, and Bavarian dairy-beef crossbreed programs. Single-source vulnerability concentrates in Brazilian export infrastructure exposed to currency fluctuation. Distribution runs through direct producer-to-manufacturer contracts displacing traditional broker tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freeze-drying capacity expansion lags specialty retail demand growth, propping pricing premiums for protein yield-optimized formats as membrane filtration retrofit investments absorb available technical talent pools.
For Market Incumbents: Lock in multi-year protein supply agreements with institutional catering operators before carbon-accounting compliance costs escalate. Defend channel position by retrofitting evaporator lines with ceramic ultrafiltration modules to collapse yield gaps with freeze-dried competitors. Prioritize backward integration into captive cattle supply in São Paulo corridors to anchor volume against grain price volatility. For New Entrants and Emerging Players: Membrane filtration technology-first wedges into mid-scale North American soup manufacturers seeking yield optimization without freeze-drying capital intensity. White-space targets include direct-to-consumer subscription models for premium freeze-dried formats and carbon-accounting compliance services for EU-bound exporters. Go-to-market through online platform partnerships bypasses slotting fee barriers blocking retail chain entry. For Investors and Strategic Acquirers: The window for entry favors extraction technology specialists with integrated solvent recovery systems serving REACH-compliant European sauce manufacturers. Long-term viability rests on protein yield optimization IP and regulatory documentation capabilities rather than commodity volume scale. Watch membrane filtration adoption rates among mid-scale processors as inflection signal for technology-driven consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Retrofit | Ceramic ultrafiltration modules collapse yield gaps between liquid and freeze-dried formats for North American soup manufacturers. |
| Carbon-Accounting Compliance Platform | Integrated sourcing verification services capture EU Green Deal traceability mandate spending from multinational sauce producers. |
| Direct-to-Consumer Channel Launch | Subscription models for freeze-dried premium formats bypass wholesale markups and slotting fee barriers in consolidated retail. |
| Captive Cattle Supply Integration | São Paulo-based abattoir-to-concentrate corridors secure preferred vendor status in institutional catering procurement shifts. |
| REACH Chemical Input Disclosure System | Solvent recovery infrastructure captures preferential supplier status from European manufacturers facing ECHA registration requirements. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study, cross-referenced with primary interviews involving concentrate plant managers, procurement leads at soup and sauce manufacturers, ANVISA compliance officers, and membrane filtration equipment specialists. Bottom-up volume modeling triangulated against top-down value estimates derived from EFSA contaminant threshold documentation and FDA meat product labeling filings.
Granularity-level modeling deployed product format, end-user scale, and distribution channel as core segmentation dimensions, with carbon-accounting compliance tier and extraction technology type as industry-specific overlays. CAGRs were derived through regression analysis of historical procurement patterns and regulatory timeline impacts across the projection horizon. Forecast inputs incorporated membrane filtration adoption curves and EU Green Deal traceability implementation schedules.
Several conditions sit outside the modeled scope, including abrupt feed grain price shocks, ANVISA-FDA regulatory harmonization failures, and breakthrough plant protein flavor base technologies. Forecasts reflect documented assumptions about technology diffusion rates and regulatory enforcement intensity. A model refresh is warranted upon material change in EU carbon-border adjustment implementation or membrane filtration cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Soy Protein Isolate Market
Ingredients
Industrial Sugar Market
Ingredients
North America Rice Protein Ingredients Market
Ingredients
Europe Dairy Protein Market
Ingredients
Soy Derivatives Market
Ingredients
Europe Algae Omega-3 Ingredients Market
Ingredients
Salt Market
Ingredients
Germany Gelatin Market
Ingredients
Microencapsulated Oil Market
Ingredients
France Protein Market
Ingredients
Rice Bran Fatty Alcohols Market
Ingredients
Konjac Root Fiber Market
Ingredients
Fonio Flour Market
Ingredients
Global Edible Oil Market
Ingredients
Australia Sodium Reduction Ingredients Market
Ingredients
Psyllium Products Market