
 Corn-Based Ingredients Market | 2026-2036
Corn-Based Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Corn-Based Ingredients Market Analysis
Modular ingredient bundling is rebalancing procurement patterns across the Corn-Based Ingredients Market. Cargill Incorporated leverages its integrated grain origination network to sustain cost advantages in bulk starch delivery. Tate & Lyle PLC differentiates through specialty sweetener formulations that command premium positioning in beverage applications. Archer Daniels Midland Company anchors North American ethanol output with captive corn milling capacity tied to biofuel offtake agreements.
Corn-based ingredients encompass refined derivatives including native and modified starches, high-fructose corn syrups, corn oils, and specialty flours produced through wet milling, dry milling, or enzymatic conversion processes, serving as functional inputs across food formulation, animal nutrition, and industrial fermentation. Starch and syrup categories dominate value capture due to their ubiquity in processed foods and beverage sweetening, while biofuel applications represent the fastest-growing demand pool as renewable fuel mandates expand. Food & Beverage applications maintain the largest volume footprint, though pharmaceutical-grade corn derivatives are emerging as a concentrated margin segment driven by excipient purity requirements.
The EPA enforces Renewable Fuel Standard blending obligations that directly determine corn ethanol demand volumes and starch allocation priorities. FDA food additive regulations and USDA organic certification standards govern ingredient labeling, clean-label migration, and non-GMO verification pathways that processors must navigate for market access. Stakeholders must monitor how evolving biofuel policy thresholds and food-grade specification tightening will reshape margin allocation between fuel and food end uses.
Market Dynamics
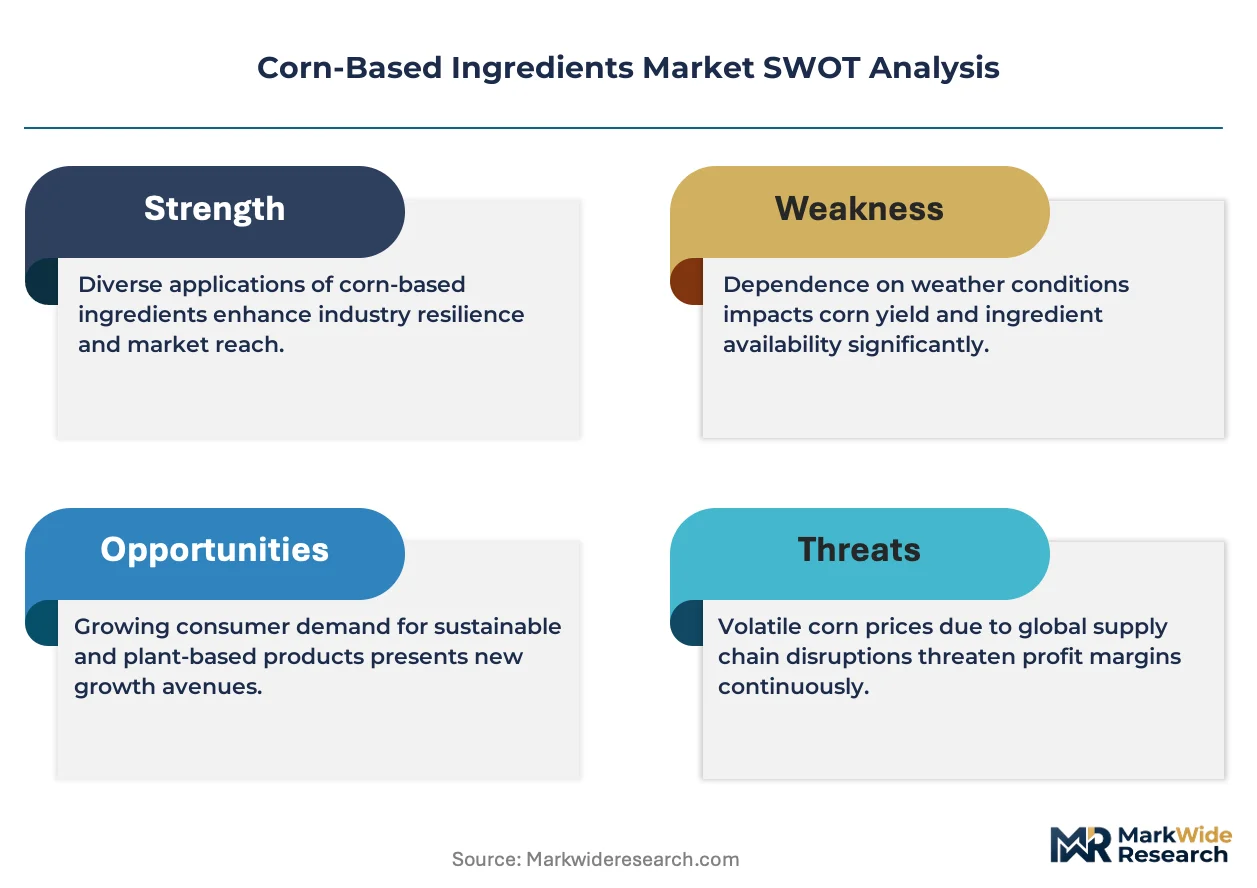
The EPA's Renewable Fuel Standard is forcing a structural reallocation of corn starch volumes between food-grade and fuel-grade applications, compressing margin pools for processors navigating dual-product mandates.
Growth Catalysts
- Renewable Fuel Standard mandates:The EPA's blending obligations redirect corn starch toward ethanol production, creating captive offtake for Midwestern wet millers.
- Clean-label reformulation:Processed food manufacturers in the United States are substituting modified starches and corn syrups for synthetic additives to meet FDA labeling transparency expectations.
- Pharmaceutical excipient purity requirements:Drug formulators are specifying USP-grade corn derivatives for tablet binders and disintegrants, opening premium margin tiers.
Market Restraints
- Input cost volatility:Corn futures price swings tied to Midwestern weather patterns and USDA crop reports compress processor margins unpredictably.
- Supply concentration risk:Wet milling capacity clusters in Iowa and Illinois create geographic vulnerability to regional logistics disruptions or localized drought.
- Sugar substitution threat:Beet and cane sugar processors are recapturing beverage sweetener share as high-fructose corn syrup faces formulation scrutiny.
Strategic Opportunities
- Biofuel policy tailwinds:The EPA's evolving renewable volume obligations position corn ethanol as the dominant compliance pathway for transportation fuel blenders.
- Specialty starch convergence:Enzymatic conversion technologies are enabling resistant starch variants targeting functional food and digestive health applications.
- India feed ingredient penetration:Corn gluten meal and distillers dried grains remain underutilized in Indian poultry and aquaculture nutrition relative to soybean meal displacement potential.
Industry Challenges
- Clean-label certification timelines:Non-GMO Project verification and USDA Organic accreditation require 12-18 month audit cycles that delay new product commercialization.
- Legacy equipment retrofit costs:Dry millers face capital intensity upgrading to fractionation capabilities that separate germ, fiber, and starch streams for higher-value capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corn-Based Ingredients Market |
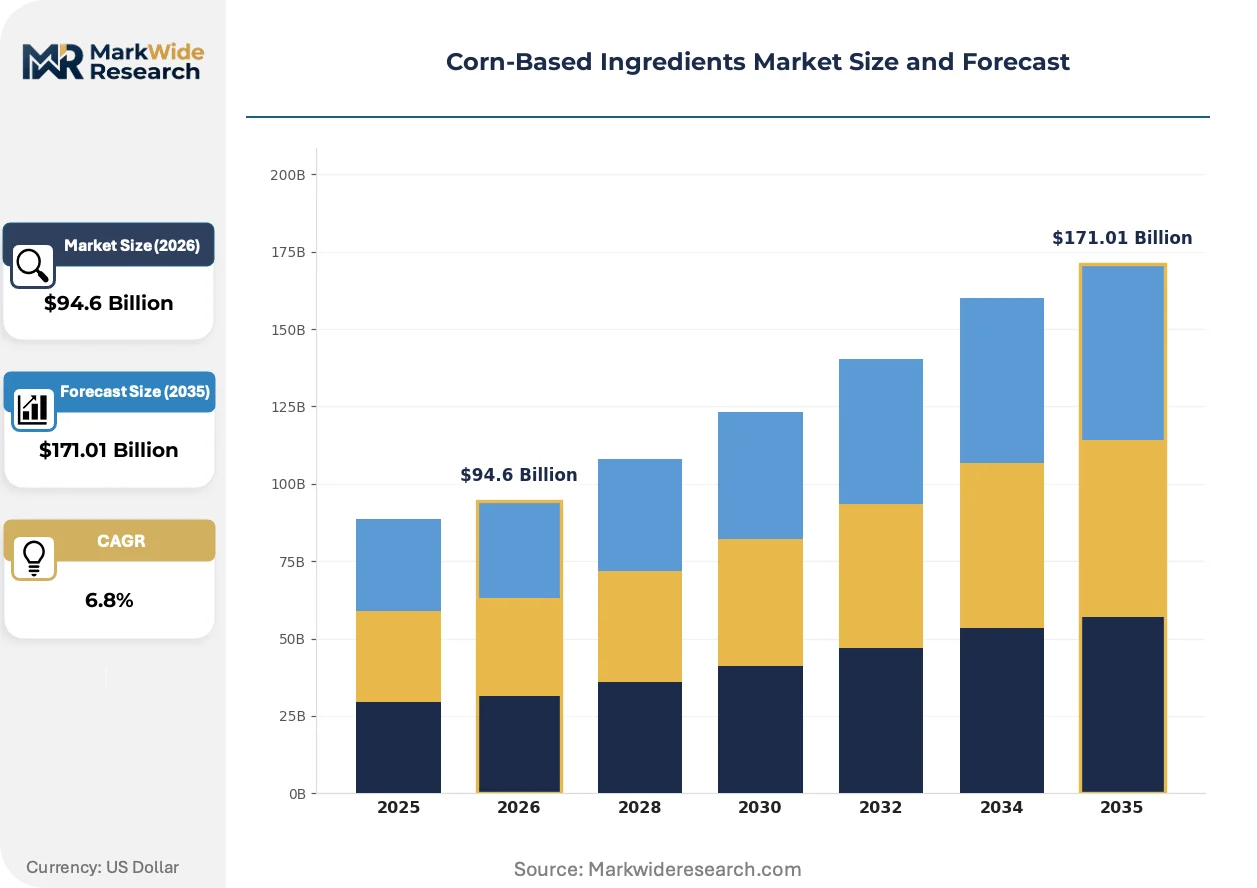
| Market Size in 2026 | $94.6 Billion |
| Market Size in 2035 | $171.01 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Starch, Syrup, Flour, Oil Application: Food & Beverage, Feed, Biofuel, Pharmaceuticals End User: Agriculture, Food Processing, Nutraceuticals, Industrial Packaging Type: Bags, Bulk, Drums, Containers |
| Companies Covered | Tate & Lyle PLC, Bunge Limited, Cargill Incorporated, AGRANA Beteiligungs-AG, Tereos SA, Archer Daniels Midland Company, Roquette Frères, POET LLC, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corn-Based Ingredients Market Emerging Trajectories
Enzymatic processing advances and regulatory pressure on synthetic inputs are reshaping how corn derivatives compete across food, fuel, and pharmaceutical end uses.
Enzymatic starch modification is electrifying the specialty ingredients segment. Precision enzyme cocktails enable targeted molecular architectures for film-forming, gelling, and encapsulation functions. Pharmaceutical and personal care formulators are adopting these starches at accelerating rates. This technology is electrifying margin capture away from commodity native starch into performance-tuned derivatives.
The EPA's Renewable Fuel Standard and evolving state-level low-carbon fuel standards are tightening compliance thresholds for transportation fuel blenders. Corn ethanol processors must document lifecycle carbon intensity through certified pathways to maintain RIN generation eligibility. Fuel-grade starch allocation is most affected in the Midwestern United States, where captive milling capacity is expanding carbon accounting infrastructure.
Direct sourcing contracts between food manufacturers and corn processors are consolidating procurement relationships previously mediated by distributors. Large beverage and snack companies are negotiating multi-year starch and syrup supply agreements with price collars tied to USDA crop forecasts. This pattern is most visible in North American processed food manufacturing, where CPG giants are securing volume commitments from Iowa and Illinois wet millers.
Corn-Based Ingredients Market Segmentation
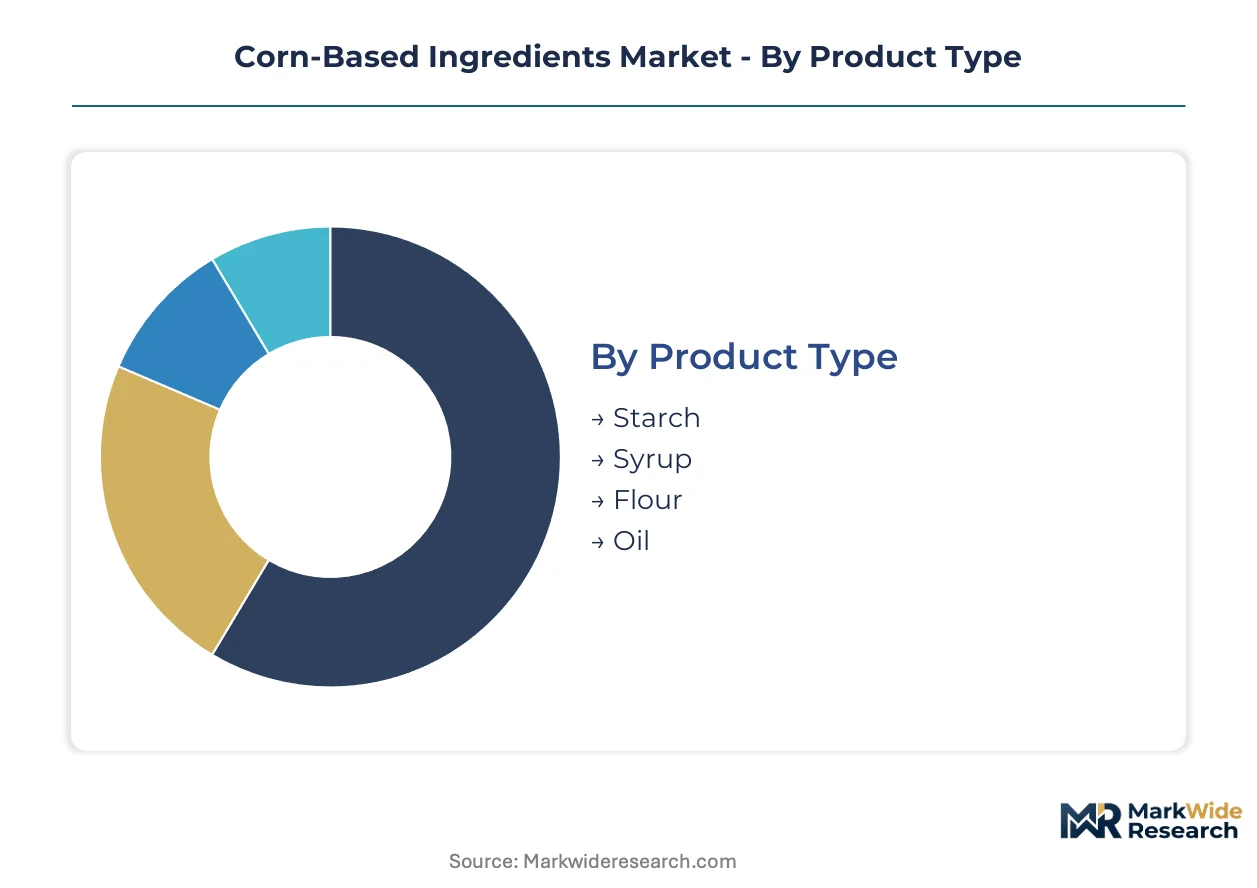
Corn-based ingredients fragment across four functional dimensions that determine pricing power and regulatory exposure. Product type and application dictate margin tiers, while end-user concentration and packaging format shape logistics economics and inventory velocity.
Product Type:
Certification burdens fall heaviest on starch and syrup segments, where FDA food additive status and EPA renewable fuel pathway approvals create dual-track compliance requirements.
- Starch:Native and modified starches serve as texturizers, binders, and encapsulation matrices. Food-grade specifications require GRAS affirmation from FDA, while fuel-grade streams need RIN eligibility documentation under EPA protocols. Demand concentrates in Midwestern wet milling clusters supplying CPG reformulation programs.
- Syrup:High-fructose corn syrups and glucose syrups deliver sweetness and humectancy in beverage and bakery applications. HFCS 55 and HFCS 42 grades face formulation scrutiny from clean-label migration, compressing share in carbonated soft drinks while stabilizing in industrial baking.
- Flour:Degermed and whole-grain corn flours carry lighter additive scrutiny but require allergen management protocols.
- Oil:Refined corn oil competes in cooking oil and biodiesel feedstock markets with simpler specification chains than starch derivatives.
Starch sits at the top of the volume ranking, with syrup climbing the fastest as beverage manufacturers seek cost-optimized sweetening solutions.
Application:
Margin structures diverge sharply across application tiers, with pharmaceutical and biofuel end uses capturing premium spreads over commodity food channels.
- Food & Beverage:The largest volume sink spanning confectionery, dairy, bakery, and beverage subsegments. Modified starches and HFCS dominate formulation budgets, though clean-label substitution pressures are redirecting some volume toward tapioca and rice alternatives.
- Feed:Corn gluten meal and distillers dried grains with solubles (DDGS) anchor protein and energy supplementation in poultry, swine, and ruminant nutrition.
- Biofuel:Ethanol production captures the steepest expansion trajectory as EPA renewable volume obligations tighten and state low-carbon fuel standards proliferate.
- Pharmaceuticals:USP-grade starches for tablet binders and disintegrants command 3-5x commodity starch pricing, with purity specifications enforced by FDA drug master file requirements.
Food & Beverage maintains absolute volume leadership, though biofuel is expanding most quickly as policy mandates harden.
End User:
Procurement scale and specification intensity separate end-user tiers, with industrial buyers leveraging volume commitments against nutraceutical specialists prioritizing certificate-of-analysis depth.
- Agriculture:Livestock operations and feed compounders purchase DDGS and corn gluten meal in bulk railcar quantities, with pricing indexed to soybean meal futures spreads.
- Food Processing:Snack, cereal, and beverage manufacturers negotiate multi-year starch and syrup contracts with price collars tied to USDA crop forecasts.
- Nutraceuticals:Dietary supplement formulators specify resistant starch and prebiotic corn fiber variants, requiring non-GMO Project verification and organic accreditation.
- Industrial:Fermentation feedstock buyers and biodegradable polymer producers source dextrose and specialty starches with carbon intensity documentation for scope 3 reporting.
Food Processing commands the deepest volume commitments, while Nutraceuticals is gaining share fastest on functional health positioning.
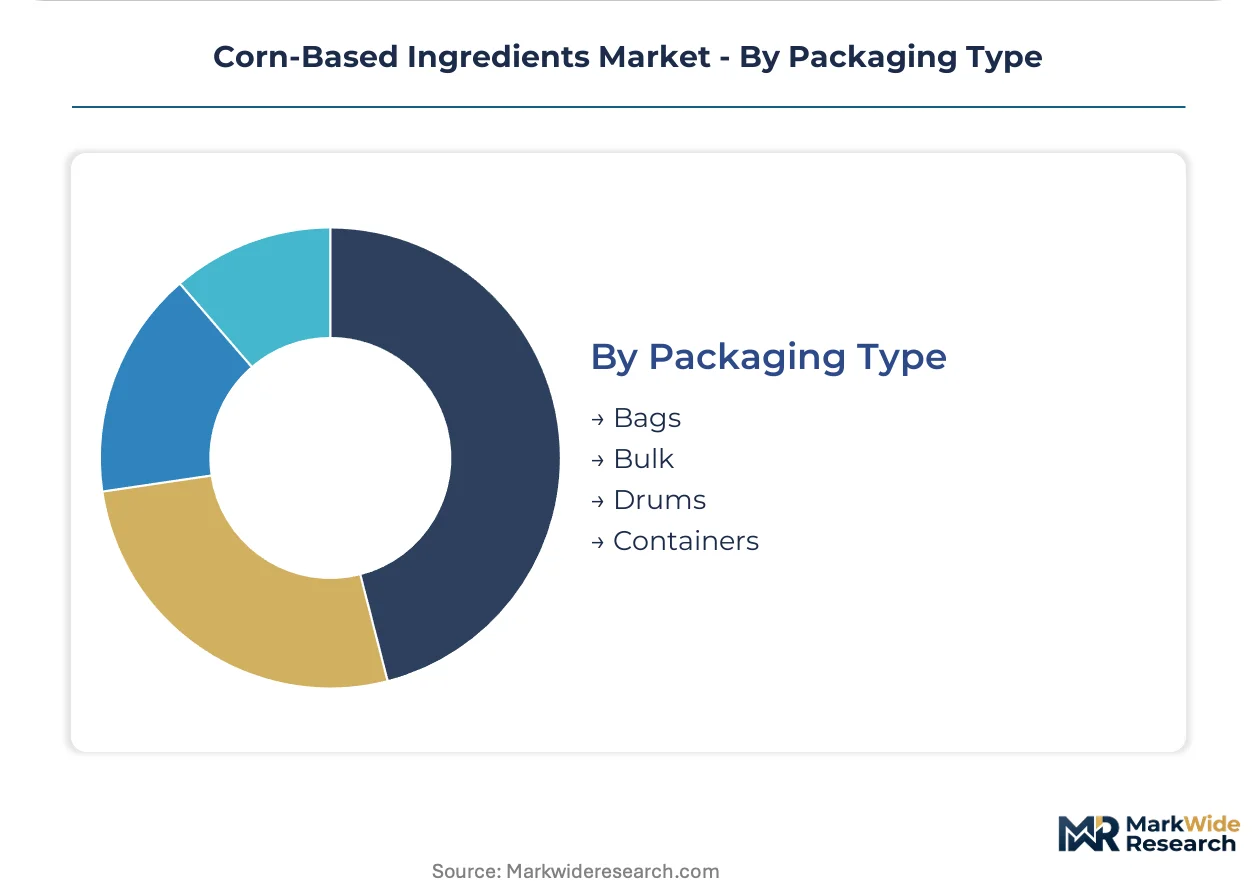
Packaging Type:
Packaging selection tracks customer scale and handling infrastructure, with bulk formats dominating ingredient manufacturing and unitized packaging serving smaller compounders.
- Bags:25-50 kg multiwall paper bags serve mid-scale food processors and regional bakeries with standard warehousing capabilities.
- Bulk:Pneumatic railcar and truckload deliveries minimize unit costs for ethanol plants and large wet mill customers with silo reception.
- Drums:Fiber and steel drums protect hygroscopic syrup and modified starch grades from moisture ingress during extended storage.
- Containers:Intermediate bulk containers and totes bridge bag and bulk formats for specialty ingredient distributors serving fragmented downstream accounts.
Bulk formats lead on tonnage moved, with containers expanding most quickly as third-party ingredient distribution networks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The corn-based ingredients industry traces its modern scale to the post-war mechanization of Midwestern grain processing in the United States, where wet milling infrastructure first achieved industrial density. That historical foundation now shapes regional specialization patterns worldwide.
United States
EPA Renewable Fuel Standard mandates and clean-label reformulation by CPG manufacturers drive dual-track demand for food-grade starches and fuel-grade ethanol. The USDA administers crop insurance programs and biofuel subsidy frameworks that stabilize processor input costs. Iowa and Illinois anchor North American wet milling capacity, with Cedar Rapids and Decatur processing clusters expanding carbon accounting infrastructure for RIN eligibility.
Brazil
Safrinha corn expansion and poultry sector growth are accelerating demand for corn gluten meal and distillers dried grains in animal nutrition. ANVISA governs food additive approvals while the national biofuel policy RenovaBio mandates ethanol blending thresholds that compete for starch allocation. Mato Grosso and Goiás processing hubs are capturing margin from soybean meal displacement in feed formulations.
China
Industrial fermentation feedstock demand and biodegradable polymer manufacturing are redirecting corn starch volumes away from traditional food applications. SAMR enforces food safety standards and GB technical regulations for modified starch specifications. Shandong Province wet millers near Qingdao are upgrading enzymatic conversion capabilities for pharmaceutical-grade dextrose production.
Germany
Specialty starch demand from pharmaceutical excipient formulators and EU Green Deal bioeconomy targets are reshaping processor product mixes. EFSA governs novel food approvals while REACH compliance burdens enzymatic modification chemistries. North Rhine-Westphalia biorefinery clusters around Cologne are integrating carbon capture documentation for scope 3 reporting by industrial buyers.
India
Poultry and aquaculture feed penetration by corn gluten meal remains underdeveloped relative to soybean meal displacement potential. FSSAI regulates food additive standards while DGFT export incentives support starch derivative shipments to Southeast Asian markets. Gujarat and Maharashtra processing facilities near Ahmedabad and Mumbai are expanding fractionation capacity for higher-value germ and fiber separation.
Corn-Based Ingredients Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification intensity and application specification tiers. The vendor base organizes into three concentration levels: integrated agribusiness conglomerates with captive grain origination, regional wet milling specialists with enzymatic technology positions, and toll processors serving pharmaceutical purity requirements. Dominant competitive moves include backward integration into seed genetics and grain handling infrastructure, plus multi-year offtake contracting with beverage and snack manufacturers.
Within the integrated agribusiness tier, Cargill Incorporated and Archer Daniels Midland Company exemplify scale-driven positioning through Midwestern wet milling density and biofuel offtake alignment. Tate & Lyle PLC occupies a specialty-formulation position emphasizing beverage sweetener premiumization and pharmaceutical excipient certification. Among European specialists, Roquette Frères and AGRANA Beteiligungs-AG represent enzymatic modification and regional fractionation archetypes respectively.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Bunge Limited |
| Cargill Incorporated |
| AGRANA Beteiligungs-AG |
| Tereos SA |
| Archer Daniels Midland Company |
| Roquette Frères |
| POET LLC |
| Ingredion Incorporated |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical-grade starch premiums diverging from commodity ethanol feedstock pricing create parallel procurement ecosystems that reshape logistics infrastructure and contract structures across the Corn-Based Ingredients Market. This bifurcation concentrates margin capture in enzymatic modification capabilities while compressing returns on legacy wet milling capacity serving fuel-grade offtake.
Pricing Analysis
Contract-based long-term offtake agreements dominate volume transactions, with multi-year supply commitments tied to USDA crop forecast collars anchoring pricing for CPG manufacturers. Price differentiation rests on certification grade—USP pharmaceutical tiers command substantial premiums over fuel-grade specifications—and volume scale, where railcar-quantity buyers extract favorable terms. Cost compression in standard-grade modified starches is intensifying because sugar substitution in beverage formulations redirects procurement leverage. Small-batch nutraceutical compounders exhibit highest price sensitivity, while ethanol blenders with RIN eligibility requirements show lowest sensitivity due to policy-mandated demand.
Supply Chain Analysis
Skilled enzymatic process engineers and certified quality control specialists concentrate in Iowa, Illinois, and Indiana, creating workforce bottlenecks that constrain specialty starch expansion. Geographic supply concentration centers on the United States, Brazil, and China, with Midwestern wet milling clusters anchoring global starch derivative output. Raw material dependencies include #2 yellow corn futures, sulfuric acid for steeping operations, and alpha-amylase enzyme formulations. Single-source vulnerability manifests in Iowa-Illinois processing corridor concentration exposed to localized drought patterns. Distribution runs through captive rail networks serving ethanol plants and pneumatic bulk delivery to large food processors, with regional distributors bridging fragmented downstream accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Corn-Based Ingredients Market represents a late-cycle quality story as pharmaceutical excipient specifications and clean-label certification requirements displace commodity-grade volume from margin capture. Premium-grade starch demand from drug formulators and functional food manufacturers now drives sustainable returns.
For Market Incumbents: Lock in multi-year offtake agreements with beverage and snack manufacturers before sugar substitution accelerates, while securing backward integration into non-GMO corn origination to defend against certification timeline delays that threaten clean-label market access. Expand carbon accounting infrastructure in Iowa and Illinois processing clusters to maintain RIN generation eligibility as EPA compliance thresholds tighten. For New Entrants and Emerging Players: Enter via enzymatic modification technology licensing to capture pharmaceutical-grade starch premiums, targeting the underdeveloped India feed ingredient segment where corn gluten meal penetration lags soybean meal displacement potential. Pursue toll processing arrangements with established wet millers to bypass capital-intensive fractionation equipment requirements while building certificate-of-analysis capabilities for nutraceutical customers. For Investors and Strategic Acquirers: Consolidation pressure builds where specialty enzymatic capabilities overlap with captive grain origination assets in the Midwestern United States. The five-to-ten year viability window favors processors with integrated carbon intensity documentation for scope 3 reporting compliance. Target acquisition archetypes include regional wet milling specialists with FDA drug master file approvals and non-GMO Project verification infrastructure. Watch EPA renewable volume obligation announcements as the critical inflection signal for fuel-grade starch allocation priorities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Non-GMO Corn Origination | Cargill and ADM secure clean-label supply chains ahead of 12-18 month certification timelines. |
| Enzymatic Modification Capacity Expansion | Specialty starch variants capture pharmaceutical excipient premiums from tablet binder formulations. |
| Carbon Accounting Infrastructure Investment | RIN eligibility documentation satisfies EPA lifecycle carbon intensity requirements for ethanol offtake. |
| Direct Sourcing Contract Consolidation | CPG giants negotiate price collars tied to USDA crop forecasts with Iowa and Illinois wet millers. |
| India Feed Ingredient Market Penetration | Corn gluten meal and DDGS displace soybean meal in poultry and aquaculture nutrition programs. |
Methodological Framework
Multiple input streams — executive interviews with wet milling plant managers, procurement leads at downstream CPG manufacturers, and regulatory affairs specialists — were reconciled against customs and trade data, USDA crop reports, and EPA RIN generation disclosures. Bottom-up volume modeling across product type, application, and end-user segments was cross-validated with top-down macroeconomic indicators to establish market sizing boundaries.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation dimensions spanning starch/syrup/flour/oil categories, food/beverage/feed/biofuel/pharmaceutical applications, and bulk/bag/drum/container packaging formats. CAGRs were derived from trend extrapolation of policy-mandated ethanol demand and clean-label reformulation velocity, incorporating corn futures price volatility bands and enzymatic conversion technology adoption curves as industry-specific forecast inputs.
Inputs from wet miller executives and FDA regulatory filings were available through the study window; gaps in real-time DDGS export pricing to Southeast Asian markets introduce uncertainty bands around feed segment projections. Forecasts reflect documented assumptions regarding EPA renewable volume obligation stability and Midwestern weather pattern distributions. Material deviation in biofuel policy thresholds or pharmaceutical excipient purity standard revisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Fucoidan Extract Market
Ingredients
Sunflower Protein Market
Ingredients
Sprouted Brown Rice Protein Market
Ingredients
Vital Wheat Gluten Market
Ingredients
Cheese Powder Market
Ingredients
Starch Market
Ingredients
Modified Flour Market
Ingredients
Avocado Powder Market
Ingredients
Meat Tenderizer Powder Market
Ingredients
Cocoa Bean Extract Market
Ingredients
Global Alpha-Lactalbumin Market
Ingredients
Textured Milk Protein Market
Ingredients
Cocoa Processing Market
Ingredients
Interesterified Fats Market
Ingredients
Baobab Ingredient Market
Ingredients
China Soy Protein Market