
 Global Pine Pollen Powder Market | 2026-2036
Global Pine Pollen Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pine Pollen Powder Market Outlook
Buyer concentration across the nutritional brands segment is broadening as mid-size supplement houses diversify their adaptogen portfolios beyond ashwagandha and rhodiola. Xi'an TCM Adaptogen Bio-tech anchors its position through backward integration into Shaanxi Province pine forest leases. RAW Forest Foods differentiates via small-batch wildcrafted sourcing protocols and direct-to-consumer channel control. Canadian Pine Pollen Company leverages its British Columbia harvesting territories to supply North American private-label manufacturers.
Pine pollen powder consists of the male microgametophytes of Pinus massoniana and related species, typically harvested as a fine golden powder containing bioactive phytosterols, flavonoids, and amino acids; processors employ low-temperature cell-wall fracture methods to enhance nutrient bioavailability for human consumption. The organic product type commands premium positioning among health enthusiasts seeking wildcrafted provenance, while the dietary supplements application leads volume as capsule and tincture formats dominate consumer purchasing. E-commerce distribution channels are capturing margin pools previously held by specialty retail, particularly among athlete and fitness-oriented end users.
The FDA's dietary supplement Current Good Manufacturing Practices enforce identity testing and contaminant screening for pollen-derived products entering US commerce, while China's NMPA and GB standards govern agricultural residue limits for exported raw material. The EU's Novel Food categorization and EFSA safety assessments create compliance barriers for new market entrants lacking historical consumption documentation. Stakeholders must monitor evolving botanical authentication protocols and regional wildcrafting permit restrictions that threaten sustainable supply continuity.
Market Dynamics
Wildcrafting permit restrictions across Pacific Northwest harvesting corridors are compressing raw material availability while nutritional brands accelerate adaptogen portfolio diversification, creating a structural squeeze between supply concentration and demand fragmentation.
Growth Catalysts
- EU Novel Food regulatory clarity:EFSA safety assessments for Pinus massoniana-derived ingredients are streamlining market access for documented historical consumption cases, reducing compliance uncertainty for European entrants.
- Cell-wall fracture technology:Low-temperature processing methods are enhancing bioavailability of phytosterols and amino acids, expanding addressable consumer segments beyond traditional TCM users.
- Fitness-oriented e-commerce channels:Direct-to-consumer platforms are capturing athlete and bodybuilding segments previously served through specialty retail, accelerating volume throughput.
Market Restraints
- Wildcrafting permit volatility:British Columbia and Washington State harvesting restrictions are constraining premium organic raw material flows to North American processors.
- Input cost concentration:Pinus massoniana pollen harvests depend on seasonal wind patterns and forest access, creating unhedgeable supply timing risks.
- Novel Food documentation barriers:EU entrants lacking pre-1997 consumption evidence face multi-year EFSA safety assessment timelines.
Strategic Opportunities
- Underpenetrated German functional food market:Adaptogenic ingredient acceptance in DACH-region beverage formulations remains below Nordic penetration levels.
- Tincture format expansion:Liquid delivery systems are displacing capsule dominance among bioavailability-focused consumers in Australian and Canadian markets.
- China NMPA herbal product registration:Simplified pathways for traditional medicine derivatives are accelerating export-ready raw material certification.
Industry Challenges
- Botanical authentication skill scarcity:Pollen species verification and adulterant detection require specialized phytochemical expertise that outpaces current training pipeline output.
- Dual certification burden:USDA Organic and EU Organic equivalency maintenance demands parallel documentation systems that strain mid-size processor administrative capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pine Pollen Powder Market |
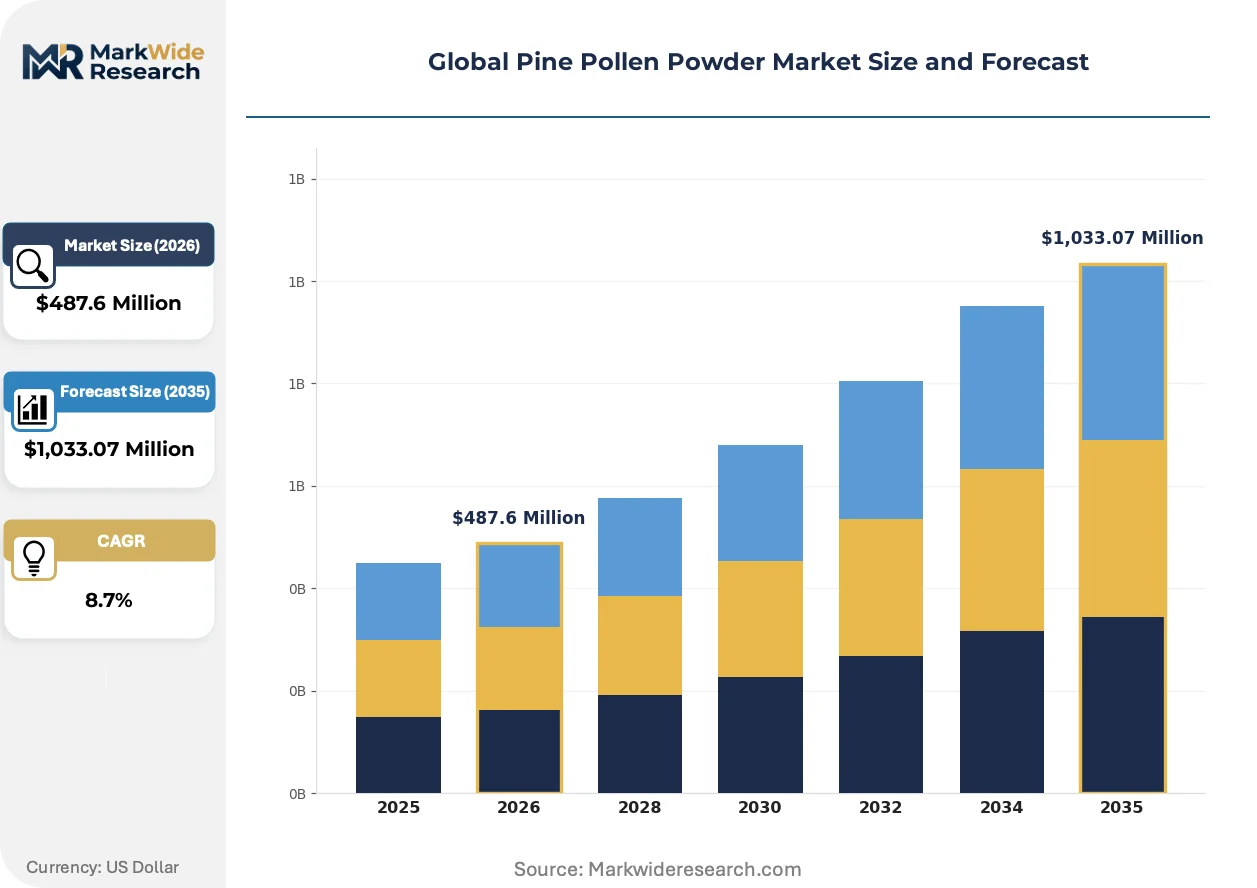
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Non-Organic, Raw, Processed Application: Dietary Supplements, Health Foods, Functional Foods, Cosmetics Distribution Channel: Retail, E-commerce, Direct Sales, Wholesale End User: Individuals, Athletes, Health Enthusiasts, Nutritional Brands |
| Companies Covered | Na'vi Organics, Surthrival Premium Supplements, Hybrid Herbs, Canadian Pine Pollen Company, Xi'an TCM Adaptogen Bio-tech, RAW Forest Foods, VitaJing Herbs, Woodland Essence, Lost Empire Herbs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pine Pollen Powder Market Strategic Shifts
Processing technology convergence with authentication protocols is compressing quality assurance timelines while regulatory documentation requirements harden across major import jurisdictions.
Near-infrared spectroscopy paired with blockchain traceability is automating real-time pollen species verification and harvest-origin documentation. Mid-size supplement manufacturers are adopting these systems at accelerated rates to preempt FDA identity testing enforcement. The technology is automating compliance workflows that previously required third-party laboratory outsourcing, collapsing certification cycle times from weeks to hours.
China's NMPA revised agricultural residue limits under GB standards are tightening export raw material specifications for heavy metals and pesticide contaminants. Processors serving EU and US markets must now maintain dual compliance documentation streams. Small-batch wildcrafted suppliers in Shaanxi Province are most affected, responding through backward integration into controlled forest lease arrangements.
Subscription-based replenishment models are displacing one-time purchase patterns among core adaptogen consumers. Direct-to-consumer brands are capturing recurring revenue streams that specialty retail channels cannot replicate. This behavioral shift is most visible in United States Pacific Coast metropolitan markets where fitness-oriented demographics concentrate.
Global Pine Pollen Powder Market Segmentation
Pine pollen powder segmentation reveals how processing protocols, regulatory pathways, and channel economics partition value capture across the adaptogen supply chain. Category boundaries shift as fitness-oriented consumers migrate between formats and procurement standards tighten in major import jurisdictions.
Product Type:
Upgrade cycles in pine pollen powder track evolving certification requirements and bioavailability expectations, with consumers trading up from basic processed grades toward authenticated organic and raw formats.
- Organic:Wildcrafted Pinus massoniana pollen certified to USDA Organic and EU Organic equivalency standards commands premium positioning among health enthusiasts seeking contaminant-free provenance. Demand concentrates in United States Pacific Coast metropolitan markets and British Columbia harvesting corridors where procurement documentation satisfies dual certification burdens.
- Processed:Low-temperature cell-wall fracture methods enhance phytosterol and amino acid bioavailability, expanding addressable segments beyond traditional TCM users into athlete and bodybuilding demographics. Volume placements concentrate in capsule and tincture manufacturing for nutritional brands diversifying adaptogen portfolios.
- Raw:Unprocessed pollen retains full enzymatic activity for consumers prioritizing whole-food integrity over convenience formats.
- Non-Organic:Conventional harvesting from managed forest leases serves price-sensitive bulk purchasers in Asian traditional medicine channels.
Volume placements concentrate in Processed; the faster expansion belongs to Organic.
Application:
Application segmentation reflects divergent margin structures between regulated supplement pathways and emerging functional food integrations.
- Dietary Supplements:Capsule and tincture formats dominate procurement volumes as nutritional brands accelerate adaptogen portfolio diversification beyond ashwagandha and rhodiola. FDA Current Good Manufacturing Practices enforcement drives identity testing investments that favor established processors with in-house authentication capabilities.
- Functional Foods:Adaptogenic ingredient acceptance in beverage formulations remains below Nordic penetration levels in German-speaking markets, creating whitespace for early entrants. EFSA Novel Food safety assessments for Pinus massoniana derivatives streamline compliance for documented historical consumption cases.
- Health Foods:Powder formats integrate into smoothie and meal-replacement applications among fitness-oriented e-commerce consumers.
- Cosmetics:Topical applications leverage flavonoid content for antioxidant positioning in premium skincare lines.
Revenue concentration sits with Dietary Supplements; Functional Foods are climbing the fastest as beverage manufacturers seek differentiation.
Distribution Channel:
Channel economics are compressing as direct-to-consumer platforms capture recurring revenue streams that specialty retail cannot replicate.
- E-commerce:Subscription-based replenishment models displace one-time purchase patterns among core adaptogen consumers, with direct-to-consumer brands capturing margin pools previously held by multi-brand retailers. Fitness-oriented demographics in United States Pacific Coast cities drive platform throughput.
- Retail:Specialty health food stores and TCM apothecaries maintain relevance for consumer education and trial conversion among traditional medicine adherents.
- Direct Sales:Practitioner channels serve clinical integrative medicine practices prescribing adaptogenic protocols.
- Wholesale:Bulk raw material flows supply North American private-label manufacturers from British Columbia harvesting territories.
Margin capture concentrates in E-commerce; Wholesale maintains volume leadership in raw material throughput.
End User:
End-user segmentation maps purchasing authority from individual wellness optimization to institutional procurement at nutritional brands.
- Nutritional Brands:Mid-size supplement houses diversify adaptogen portfolios through backward integration into controlled forest lease arrangements, with procurement teams demanding blockchain traceability and real-time species verification. China's NMPA herbal product registration pathways accelerate export-ready raw material certification for this segment.
- Athletes:Bioavailability-focused consumers in Australian and Canadian markets displace capsule dominance with liquid delivery systems, driving tincture format expansion.
- Health Enthusiasts:Early-adopter demographics in fitness-oriented metropolitan clusters experiment with novel delivery formats and wildcrafted provenance claims.
- Individuals:Mass-market consumers enter through price-accessible processed formats in conventional retail channels.
Procurement scale concentrates in Nutritional Brands; Athletes are gaining share fastest as sports nutrition formulations integrate adaptogenic ingredients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for pine pollen powder concentrates in harvesting corridors where wildcrafting cooperatives supply premium raw material to nutritional brand processors. The United States Pacific Northwest and British Columbia anchor procurement volumes, while Shaanxi Province in China and select European markets drive differentiated growth through regulatory pathway maturation.
United States
Nutritional brands in the Pacific Northwest diversify adaptogen portfolios beyond ashwagandha and rhodiola, creating procurement pull for wildcrafted Pinus massoniana derivatives. FDA Current Good Manufacturing Practices enforcement drives identity testing investments that favor established processors with in-house authentication capabilities. Seattle and Portland metropolitan clusters concentrate fitness-oriented e-commerce demand through subscription-based replenishment models.
Canada
British Columbia harvesting territories supply North American private-label manufacturers with premium organic raw material certified to dual USDA-EU Organic equivalency standards. Wildcrafting permit volatility across provincial forest lands constrains premium supply flows to processors serving cross-border demand. Vancouver-based cooperatives maintain backward integration into controlled lease arrangements to secure sustainable harvest continuity.
China
Shaanxi Province pine forest leases anchor backward integration strategies for export-ready raw material certification under NMPA herbal product registration pathways. GB standards revisions tighten agricultural residue limits for heavy metals and pesticide contaminants, demanding parallel compliance documentation for EU and US market access. Xi'an processors deploy low-temperature cell-wall fracture methods to enhance phytosterol bioavailability for international nutritional brand clients.
Germany
Adaptogenic ingredient acceptance in beverage formulations remains below Nordic penetration levels, creating whitespace for early entrants in the DACH-region functional food market. EFSA Novel Food safety assessments for Pinus massoniana derivatives streamline compliance for documented historical consumption cases. Berlin and Hamburg metropolitan clusters concentrate practitioner-channel demand through clinical integrative medicine practices prescribing adaptogenic protocols.
Australia
Bioavailability-focused consumers in Sydney and Melbourne displace capsule dominance with liquid delivery systems, driving tincture format expansion among athlete demographics. TGA regulatory frameworks govern imported pollen-derived products entering domestic commerce, with contaminant screening requirements mirroring FDA enforcement patterns. Direct-to-consumer brands capture recurring revenue streams through fitness-oriented e-commerce platforms that specialty retail channels cannot replicate.
Global Pine Pollen Powder Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue wildcrafted provenance differentiation and direct-to-consumer channel control. The vendor base stratifies across three maturity tiers: large-scale processors with multi-jurisdiction certification capabilities, mid-size supplement houses diversifying through backward integration into forest lease arrangements, and small-batch wildcrafting specialists serving premium organic segments. Dominant competitive moves include strategic partnerships with harvesting cooperatives for supply security and portfolio diversification into tincture and functional food formats.
Within the wildcrafting specialist tier, Canadian Pine Pollen Company exemplifies geographic anchoring through British Columbia harvesting territory control, while RAW Forest Foods represents direct-to-consumer channel dominance with small-batch sourcing protocols. Xi'an TCM Adaptogen Bio-tech occupies a position as a China-based limited company leveraging Shaanxi Province forest lease backward integration for export-ready raw material certification. These three entities collectively illustrate how procurement geography and regulatory pathway access determine competitive positioning across the adaptogen supply chain.
| Leading Market Players |
|---|
| Na'vi Organics |
| Surthrival Premium Supplements |
| Hybrid Herbs |
| Canadian Pine Pollen Company |
| Xi'an TCM Adaptogen Bio-tech |
| RAW Forest Foods |
| VitaJing Herbs |
| Woodland Essence |
| Lost Empire Herbs |
| Others |
Value Chain & Pricing Dynamics
Pinus massoniana raw pollen spot indices cascade through three distinct value tiers as harvest timing volatility and dual-certification burdens stratify processor margins across wildcrafted, organic-certified, and conventional grades.
Pricing Analysis
Volume concentrates in processed conventional grades while margin pools accrue to authenticated organic wildcraft. Premium-mid-economy pricing differentiation separates USDA-EU dual-certified organic harvests from single-certified and conventional bulk tiers. Cost compression in the organic tier is intensifying because British Columbia and Washington State permit restrictions are constraining premium raw material flows. Nutritional brands demonstrate lowest price sensitivity due to backward integration investments, while Asian traditional medicine bulk purchasers exhibit highest elasticity to harvest-season price swings.
Supply Chain Analysis
Certification gating through USDA Organic and EU Organic equivalency standards fragments supplier tiers and elevates compliance costs for mid-size processors. Raw material sourcing concentrates in China, Canada, and the United States, with Shaanxi Province forest leases and British Columbia harvesting territories anchoring premium supply. Processing draws from seasonal wind-pattern-dependent pollen collection, low-temperature cell-wall fracture equipment, and third-party authentication laboratory services. Single-source vulnerability runs through Pacific Northwest wildcrafting cooperatives facing permit volatility. Distribution runs through direct-to-consumer subscription platforms capturing recurring revenue from fitness-oriented demographics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over Shaanxi Province and British Columbia forest lease arrangements determines who captures margin pools as procurement documentation requirements harden.
For Market Incumbents: Deepen backward integration into controlled harvesting territories to preempt supply discontinuity from wildcrafting permit volatility in British Columbia and Washington State. Invest in near-infrared spectroscopy and blockchain traceability systems to collapse authentication cycle times and defend against FDA identity testing enforcement. Secure dual USDA-EU Organic certification maintenance capabilities to sustain premium tier access.
For New Entrants and Emerging Players: Enter via underpenetrated German functional food beverage formulations where adaptogenic ingredient acceptance trails Nordic levels. Target tincture format expansion in Australian and Canadian athlete demographics displacing capsule dominance. Pursue practitioner-channel relationships in Berlin and Hamburg clinical integrative medicine practices as a go-to-market angle bypassing saturated e-commerce competition.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-size supplement houses with existing forest lease backward integration in Shaanxi Province or British Columbia facing temporary certification compliance strain. Long-term viability hinges on procurement geography control rather than brand equity in this raw-material-constrained vertical. Watch for EFSA Novel Food safety assessment completion for Pinus massoniana derivatives as an inflection signal accelerating European market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forest Leases | Secures sustainable Pinus massoniana harvest continuity against British Columbia permit volatility. |
| Low-Temperature Cell-Wall Fracture Scale-Up | Enhances phytosterol bioavailability for athlete and bodybuilding demographic expansion. |
| Blockchain Traceability Implementation | Automates real-time species verification to preempt FDA identity testing enforcement actions. |
| Tincture Format Development | Captures liquid-delivery preference among bioavailability-focused Australian and Canadian consumers. |
| NMPA Herbal Product Registration | Accelerates export-ready raw material certification for nutritional brand procurement teams. |
Study Parameters
Document review covered customs and trade databases, FDA warning letters, EFSA Novel Food submissions, and NMPA herbal product registration filings, complemented by interviews with wildcrafting cooperative managers, nutritional brand procurement directors, third-party authentication laboratory technicians, and TCM export processors. Secondary validation drew from USDA Organic certification records, EU Organic equivalency documentation, and British Columbia forest harvesting permit registries. Bottom-up volume builds across product type, application, distribution channel, and end-user segments were cross-checked against top-down market sizing from raw material flow analysis.
Historical shipment data from Shaanxi Province export statistics and British Columbia harvesting cooperative output records were cross-referenced against panel input from processor capacity expansion plans. Segmentation modeling covered organic versus conventional grade tiers, dietary supplement versus functional food applications, e-commerce versus retail channel economics, and nutritional brand versus individual consumer purchasing authority. CAGRs were derived from trend extrapolation adjusted for regulatory pathway maturation timelines and technology adoption curves in authentication protocols.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of acute wildcrafting permit restriction or accelerated EFSA Novel Food approval timelines. Forecasts reflect assumptions regarding seasonal harvest yield stability and dual-certification equivalency maintenance. A model refresh is warranted upon material change in FDA enforcement intensity for botanical identity testing or NMPA agricultural residue limit revisions under GB standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Protein Hydrolysate Market
Ingredients
Europe Amino Acid Market
Ingredients
Calendula Oil Market
Ingredients
Edible Fiber Market
Ingredients
Clean Label Starch Market
Ingredients
Flaxseed Derivatives Market
Ingredients
Chickpea Protein Ingredients Market
Ingredients
Commercial Amino Acids Market
Ingredients
Durian Powder Market
Ingredients
Soy Protein Hydrolysate Market
Ingredients
Global Organic Personal Care Ingredients Market
Ingredients
Textural Food Ingredients Market
Ingredients
Dill Seed Oil Market
Ingredients
Middle-East and Africa Vegetable Oil Market
Ingredients
Plant Based Ingredients Market
Ingredients
Volatile Fatty Acids Market