
 United States Melanoma Diagnostics & Therapeutics Market | 2026-2036
United States Melanoma Diagnostics & Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
United States Melanoma Diagnostics & Therapeutics Market Insights
Market Context
Multi-source biomarker procurement is pivoting toward vertically integrated assay development as laboratories seek supply chain resilience. Merck & Co., Inc. anchors its position through deep immuno-oncology manufacturing scale. Bristol-Myers Squibb Company competes via checkpoint inhibitor specialization. F. Hoffmann-La Roche Ltd. dominates diagnostic platform integration across clinical and research channels.
Technical Definition and Segment Structure
Melanoma diagnostics and therapeutics encompass histopathological biopsy analysis, dermoscopic imaging, circulating tumor DNA blood assays, and systemic treatment modalities including immune checkpoint blockade and BRAF/MEK-targeted small molecules, serving the clinical imperative of early-stage detection and metastatic disease management. Genetic testing and immunotherapy command premium positioning within the technology dimension as companion diagnostics tighten their linkage to therapy selection. Hospitals absorb the largest share of end-user value, though laboratories are capturing faster volume expansion as decentralized molecular testing proliferates.
Regulatory Framework and Outlook
FDA breakthrough therapy designation and accelerated approval pathways compress development timelines while elevating post-market evidence requirements for melanoma therapeutics. CMS coverage determinations and state-level laboratory licensing regimes shape reimbursement access and operational geography for diagnostic providers. Stakeholders must monitor evolving FDA guidance on real-world evidence standards and state Medicaid formulary controls as access gatekeepers.
Market Dynamics
FDA breakthrough therapy designations are compressing commercialization timelines while elevating post-market evidence burdens, fundamentally restructuring how melanoma therapeutics reach patients and how diagnostic platforms align with treatment selection.
Growth Catalysts
- Accelerated Approval Pathways:FDA breakthrough therapy and accelerated approval mechanisms truncate development cycles for novel immuno-oncology agents. Manufacturers recoup R&D investments faster, incentivizing pipeline investment in melanoma indications.
- Molecular Diagnostic Integration:Companion diagnostic mandates for BRAF, NRAS, and PD-L1 testing are expanding laboratory infrastructure. Academic medical centers and community oncology networks are deploying next-generation sequencing panels to guide therapy selection.
- California-Texas-Florida Demand Cluster:Elevated melanoma incidence rates in these three states concentrate specialized oncology infrastructure and patient volume. Regional health systems are consolidating dermatopathology and medical oncology services to capture this demand.
Market Restraints
- Reimbursement Compression:CMS national coverage determinations and Medicare Advantage formulary controls are narrowing payment margins for molecular diagnostic assays. Laboratories face prior authorization requirements that delay test turnaround.
- Plasma Supply Concentration:Circulating tumor DNA assays depend on specialized blood collection and processing logistics controlled by a limited vendor base. Supply disruptions in specimen handling materials constrain assay scalability.
- Immunotherapy Resistance Mechanisms:Primary and acquired resistance to checkpoint inhibitors limits durable response rates in metastatic patients. Clinical utility of combination regimens remains constrained by toxicity profiles and biomarker selection uncertainty.
Strategic Opportunities
- Neoadjuvant Therapy Expansion:FDA approval pathways for perioperative immunotherapy in resectable Stage III melanoma are creating new treatment settings. Surgical oncology and medical oncology coordination models are evolving to capture this patient flow.
- Artificial Intelligence-Enabled Dermoscopy:Machine learning algorithms for pigmented lesion classification are gaining 510(k) clearance. Dermatology practices in high-volume screening environments are piloting AI-assisted triage to optimize biopsy yield.
- Decentralized Molecular Testing:Point-of-care PCR and isothermal amplification platforms are enabling same-day BRAF mutation results in community oncology clinics. This channel innovation reduces referral leakage to academic centers.
Industry Challenges
- Dermatopathology Workforce Constraints:Fellowship-trained specialists are concentrated in coastal metropolitan areas. Community hospitals in the Mountain West and Great Plains face recruitment gaps that delay definitive diagnosis.
- Real-World Evidence Infrastructure:FDA post-market study requirements for accelerated approvals demand sophisticated patient registries. Manufacturers must invest in data capture systems that integrate electronic health records across fragmented delivery networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Melanoma Diagnostics & Therapeutics Market |
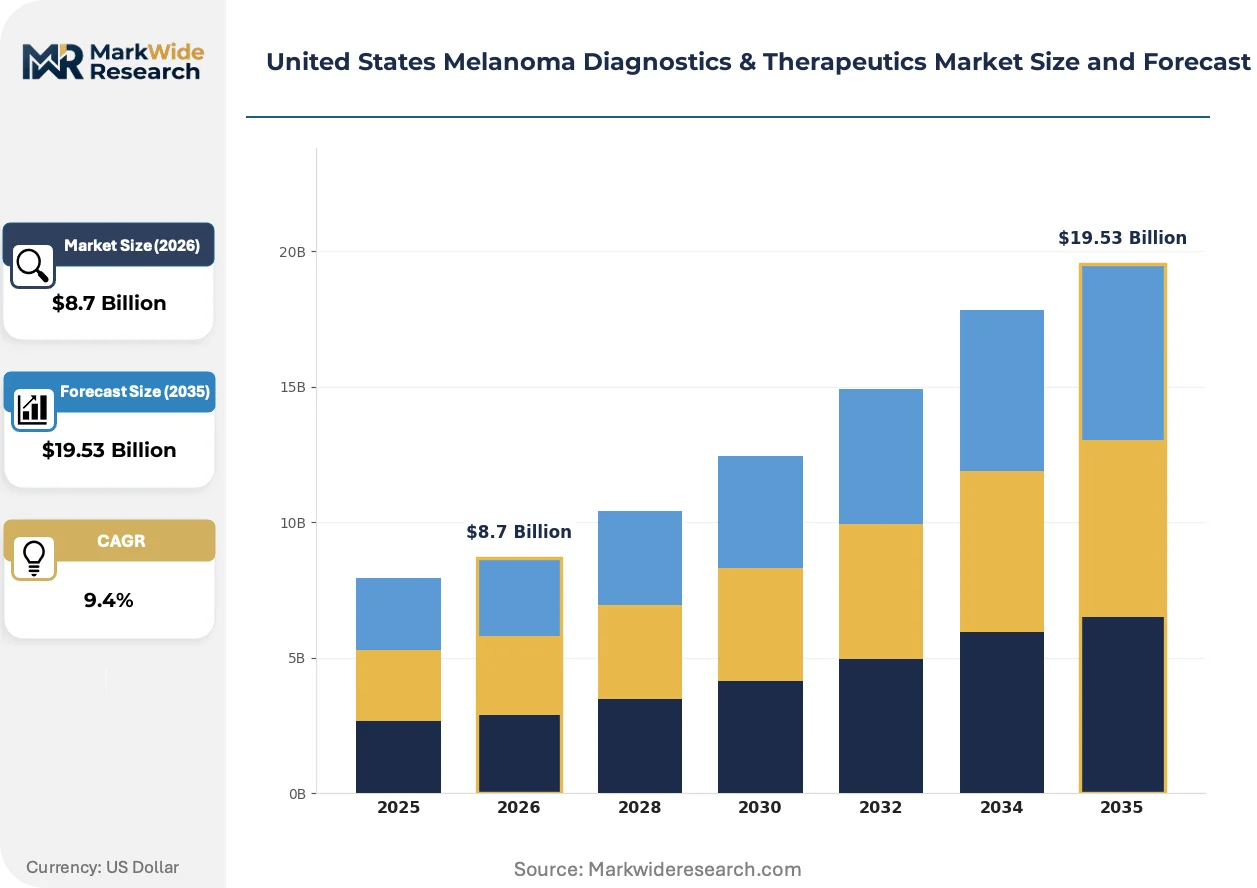
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biopsy, Imaging, Blood Tests, Skin Examination Technology: Genetic Testing, Immunotherapy, Chemotherapy, Targeted Therapy Application: Early Detection, Treatment Monitoring, Post-Treatment Surveillance, Risk Assessment End User: Hospitals, Clinics, Research Institutions, Laboratories |
| Companies Covered | Merck & Co., Inc., Novartis AG, Amgen, Inc., Agilent Technologies, Abbott Laboratories, Bristol-Myers Squibb Company, GlaxoSmithKline PLC, AstraZeneca PLC, F. Hoffmann-La Roche Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Melanoma Diagnostics & Therapeutics Market Trends and Innovations
Liquid biopsy platforms are displacing tissue-dependent workflows while regulatory frameworks and care delivery models co-evolve to accommodate decentralized diagnostic decision-making.
Multiplexed circulating tumor DNA assays are electrifying minimal residual disease monitoring in adjuvant therapy settings. Community oncology networks in Texas and Florida are adopting these platforms to reduce dependence on serial imaging. This technology is electrifying longitudinal patient management by enabling earlier detection of recurrence without invasive tissue acquisition.
FDA guidance on real-world evidence standards for supplemental indications is reshaping post-approval study design. Manufacturers must now construct digital infrastructure capable of capturing outcomes data across heterogeneous community practice settings. Melanoma therapeutics with accelerated approvals face the steepest evidentiary requirements as confirmatory trials compete for patient enrollment.
Integrated delivery networks are consolidating pathology and oncology service lines under single administrative structures. This organizational restructuring displaces independent laboratory relationships and redirects diagnostic volume toward captive reference laboratories. Kaiser Permanente in California and MD Anderson's regional network exemplify this vertical integration pattern.
United States Melanoma Diagnostics & Therapeutics Market Segmentation
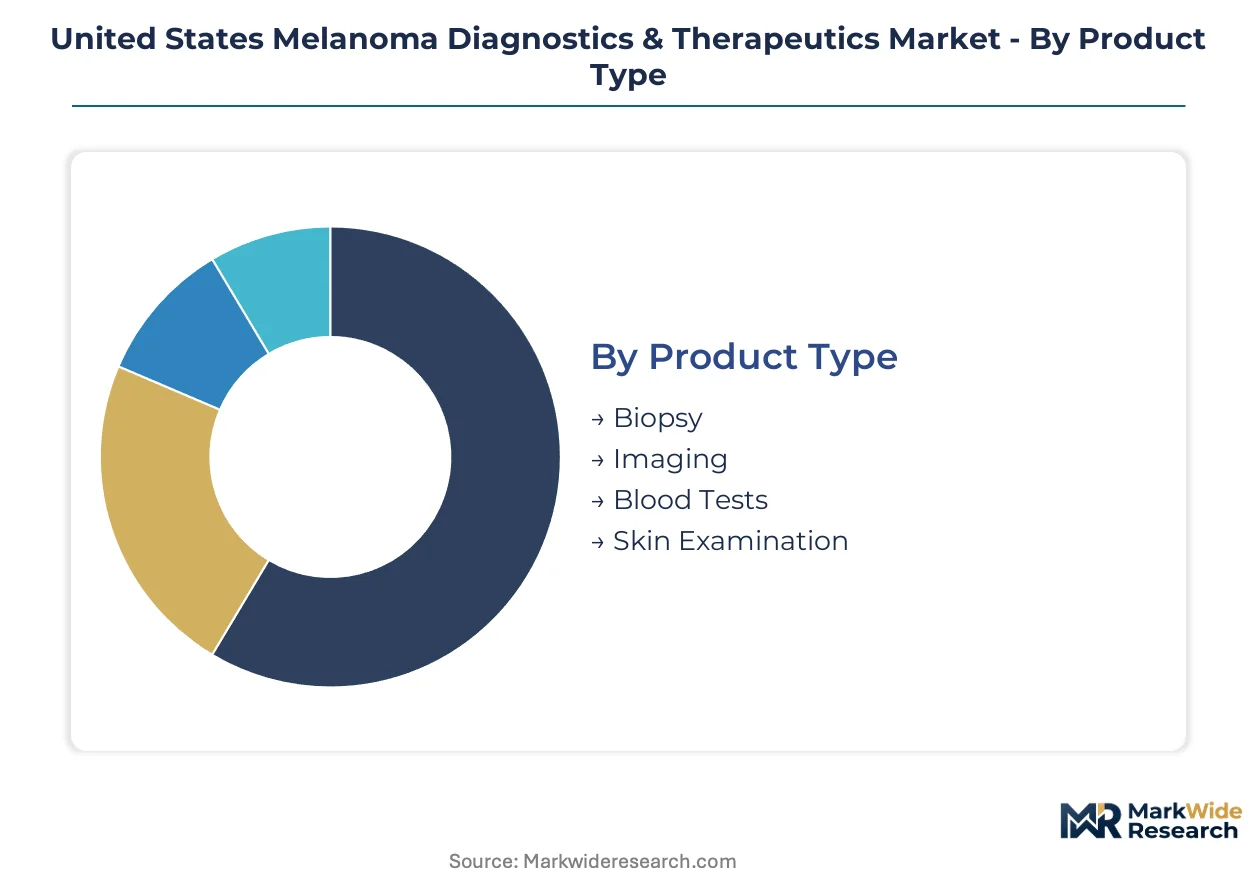
Segmentation in the United States melanoma market reveals how diagnostic and therapeutic value flows through distinct clinical channels. Each category captures different decision-makers, reimbursement pathways, and technology adoption curves that shape commercial strategy.
Product Type:
Buyers differentiate by invasiveness tolerance, turnaround urgency, and reimbursement certainty when selecting diagnostic modalities.
- Biopsy:Tissue extraction via punch, shave, or excisional methods provides definitive histopathological diagnosis with Breslow thickness staging. Academic medical centers in California and Texas deploy rapid on-site evaluation to reduce patient anxiety and surgical scheduling delays.
- Imaging:Dermoscopic and confocal microscopy systems enable non-invasive lesion characterization with digital documentation for longitudinal comparison. Florida dermatology groups are investing in handheld dermoscopes with integrated AI classification to triage biopsy referrals in high-volume screening practices.
- Blood Tests:Circulating tumor DNA and LDH monitoring support metastatic surveillance with liquid biopsy convenience.
- Skin Examination:Visual inspection with standardized photography underpins population screening and self-monitoring protocols.
Biopsy leads volumes today; blood tests are gaining share fastest as minimal residual disease monitoring expands into adjuvant settings.
Technology:
Cost tier separation dominates this category, with premium-priced precision therapies commanding hospital pharmacy budgets against commoditized cytotoxic alternatives.
- Genetic Testing:Next-generation sequencing panels and PCR-based BRAF/NRAS mutation analysis guide targeted therapy selection and clinical trial matching. Community oncology networks in Texas are deploying point-of-care BRAF testing to accelerate treatment initiation.
- Immunotherapy:Anti-PD-1 and anti-CTLA-4 checkpoint inhibitors deliver durable responses in metastatic disease but carry significant immune-related adverse event management costs. FDA breakthrough designations have compressed approval timelines for combination regimens in resectable Stage III disease.
- Chemotherapy:Dacarbazine and temozolomide persist as salvage options in resource-constrained settings or rare histologic subtypes.
- Targeted Therapy:BRAF/MEK inhibitor combinations address oncogene-driven disease with defined resistance timelines requiring serial monitoring.
Immunotherapy captures the steepest revenue trajectory; genetic testing is expanding most quickly as companion diagnostic mandates tighten.
Application:
Customer maturity varies sharply across the care continuum, with established protocols in early detection contrasting experimental frameworks in minimal residual disease surveillance.
- Early Detection:Screening programs and patient-initiated evaluations drive biopsy volume through dermatology and primary care access points. California's Kaiser Permanente system has integrated teledermatology triage to filter pigmented lesion referrals.
- Treatment Monitoring:Imaging and serologic surveillance track response to systemic therapy with RECIST criteria and ctDNA dynamics. Academic centers are piloting radiomics signatures to predict immunotherapy response earlier than conventional CT assessment.
- Post-Treatment Surveillance:Structured follow-up protocols with regional lymph node ultrasound and periodic imaging dominate Stage II-III management.
- Risk Assessment:Family history evaluation and germline testing identify high-risk populations for intensified screening.
Early detection leads volumes today; post-treatment surveillance is climbing the fastest as adjuvant therapy expands the monitored population.
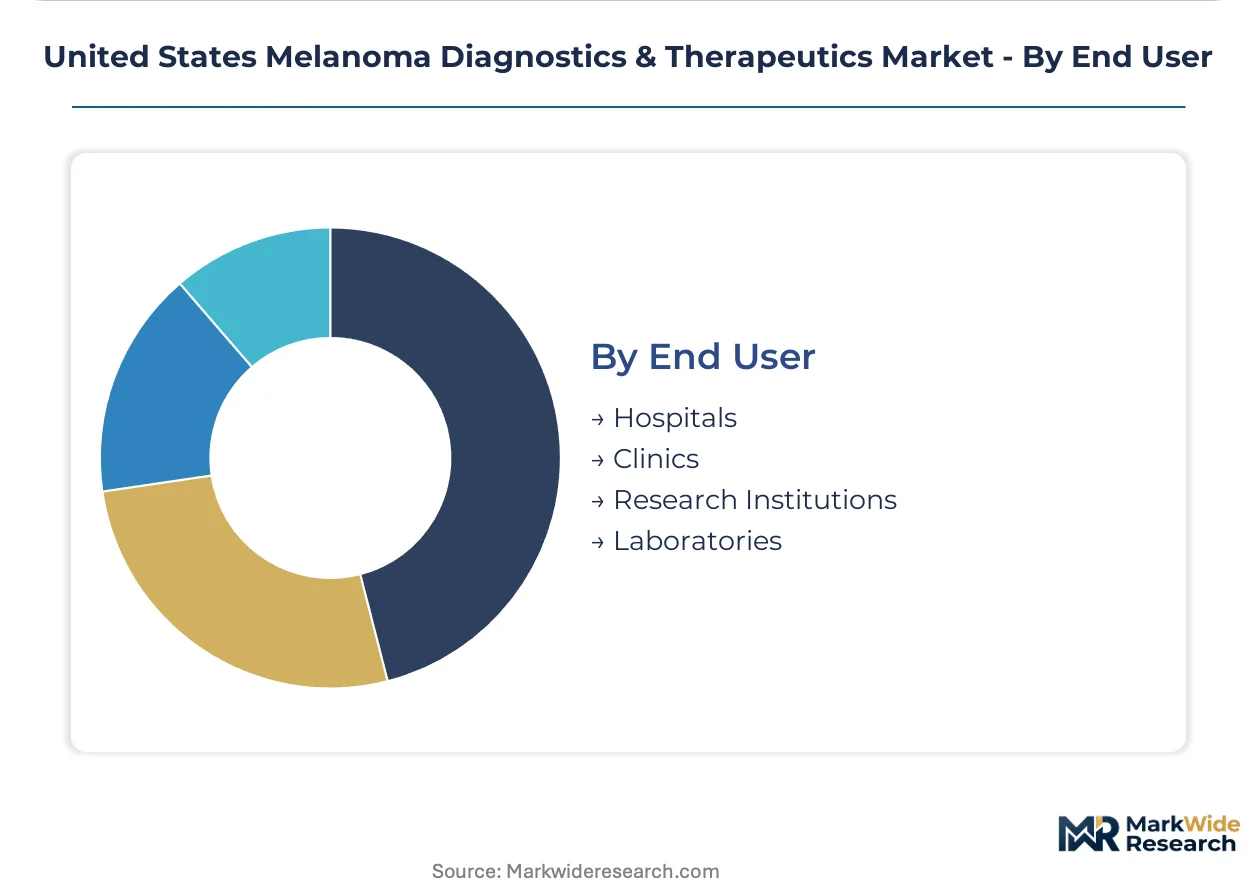
End User:
Procurement authority and reimbursement sophistication separate institutional buyers, with hospitals capturing high-complexity cases and laboratories absorbing decentralized testing growth.
- Hospitals:Integrated cancer centers control infusion therapy revenue and complex diagnostic workups through captive pathology and pharmacy services. MD Anderson's regional network exemplifies vertical consolidation of melanoma care across Texas and the Southeast.
- Laboratories:Independent and hospital-affiliated reference labs process molecular diagnostic volume with specialized histopathology and NGS capabilities. Prior authorization requirements from Medicare Advantage plans are extending turnaround times and increasing administrative burden.
- Clinics:Community dermatology and oncology practices serve as gatekeepers for referral decisions and initial therapy selection.
- Research Institutions:Academic medical centers conduct biomarker discovery and early-phase clinical trials with specialized correlative science infrastructure.
Hospitals lead volumes today; laboratories are gaining share fastest as point-of-care molecular testing decentralizes diagnostic decision-making.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The California-Texas-Florida corridor anchors United States melanoma care infrastructure, concentrating specialized dermatopathology capacity, academic oncology centers, and molecular diagnostic laboratories that serve disproportionate patient volumes relative to national population distribution.
California
Elevated ultraviolet exposure rates and aging demographics sustain demand for screening and treatment services across Southern California dermatology networks. Kaiser Permanente's integrated delivery model has pioneered teledermatology triage protocols that filter pigmented lesion referrals. The San Francisco Bay Area concentrates biomarker discovery infrastructure alongside venture capital flows into diagnostic platform development.
Texas
MD Anderson Cancer Center's regional network consolidates melanoma surgical oncology and medical oncology services across Houston, Dallas-Fort Worth, and Austin metropolitan clusters. State Medicaid formulary controls influence molecular diagnostic reimbursement access for community oncology practices. Point-of-care BRAF testing adoption is accelerating in Texas community clinics to reduce referral leakage to academic centers.
Florida
Retiree population density and year-round sun exposure generate sustained biopsy volumes through Miami, Tampa, and Orlando dermatology markets. Florida Blue's Medicare Advantage prior authorization requirements extend molecular diagnostic turnaround times. Palm Beach and Broward County practices are deploying AI-enabled dermoscopy systems to triage high-volume screening populations.
New York Metro
Memorial Sloan Kettering's regional affiliations extend specialized melanoma pathology services into community hospital networks across New York, New Jersey, and Connecticut. State laboratory licensing regimes shape operational geography for independent reference laboratories. The Long Island dermatology corridor concentrates private practice screening volume with limited fellowship-trained dermatopathology coverage.
Pacific Northwest
Seattle's Fred Hutchinson Cancer Center anchors immuno-oncology clinical trial enrollment for Pacific Northwest patient catchments. Oregon Health Authority coverage determinations influence diagnostic assay adoption in Portland-area community oncology networks. Rural Washington and Idaho face dermatopathology workforce gaps that delay definitive diagnosis and staging.
United States Melanoma Diagnostics & Therapeutics Market Competitive Landscape
Established pharmaceutical manufacturers occupy the standard tier; emerging diagnostic platform developers pursue decentralized testing and artificial intelligence-enabled triage as differentiation vectors. The market structure reflects dual consolidation patterns: immuno-oncology therapeutics concentrate around large-cap developers with manufacturing scale, while diagnostic platforms fragment across specialized assay developers, reference laboratories, and point-of-care device manufacturers. Three archetypes dominate: vertically integrated oncology-pharma conglomerates, molecular diagnostic specialists with companion diagnostic regulatory expertise, and AI-enabled imaging platform developers seeking 510(k) clearance pathways. Competitive maneuvering centers on strategic partnerships between therapeutic developers and diagnostic platform owners, plus geographic expansion of reference laboratory networks into underserved Mountain West and Great Plains markets.
Within the large-cap therapeutic tier, Merck & Co., Inc. and Bristol-Myers Squibb Company exemplify manufacturers with deep immuno-oncology manufacturing infrastructure. F. Hoffmann-La Roche Ltd. occupies a distinctive position bridging diagnostic platform integration and therapeutic development through captive assay and pharmaceutical pipelines. These three entities represent contrasting strategic postures: checkpoint inhibitor specialization, diagnostic-therapeutic vertical alignment, and broad oncology portfolio diversification.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Novartis AG |
| Amgen, Inc. |
| Agilent Technologies |
| Abbott Laboratories |
| Bristol-Myers Squibb Company |
| GlaxoSmithKline PLC |
| AstraZeneca PLC |
| F. Hoffmann-La Roche Ltd. |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up dermatopathology laboratory networks anchor supply-side consolidation across California, Texas, and Florida, compressing procurement costs through centralized reagent purchasing while extracting pricing premiums from community hospital clients lacking in-house molecular capabilities.
Pricing Analysis
Input-cost pass-through from specialized blood collection tube manufacturers and NGS reagent suppliers drives pricing stratification across premium, standard, and economy tiers in molecular diagnostic assays. Price differentiation hinges on FDA breakthrough device designation status and CAP laboratory accreditation tier, with Medicare Advantage prior authorization requirements intensifying cost compression in community oncology settings. Hospital systems exhibit lowest price sensitivity due to captive patient volume, while independent dermatology practices face acute margin pressure from extended test turnaround penalties.
Supply Chain Analysis
Dual-sourcing requirements for circulating tumor DNA assay components mandate qualification of backup suppliers for blood stabilization tubes and nucleic acid extraction chemistries across domestic and European manufacturing bases. Geographic supply concentration centers on Germany and Switzerland for precision optics in dermoscopy systems, China for PCR consumables, and the United States for specialized immunohistochemistry reagents. Raw material dependencies include semiconductor-grade optical sensors, medical-grade plastics, and recombinant enzyme preparations. Single-source vulnerability in CRISPR guide RNA synthesis constrains assay development scalability. Distribution runs through integrated delivery network captive laboratories and national reference laboratory networks serving community oncology practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in United States melanoma diagnostics and therapeutics rests on automation-driven cost reduction in histopathology workflows and premium-tier positioning of AI-enabled dermoscopy platforms in high-volume screening environments.
For Market Incumbents: Acquire point-of-care molecular testing device manufacturers to preempt decentralized diagnostic channel capture by emerging platform developers. Consolidate dermatopathology workforce capacity in Mountain West and Great Plains markets through telepathology infrastructure deployment. Defend against AI-enabled imaging entrants by embedding machine learning triage tools directly into existing dermoscopy hardware installed bases. Prioritize CAP accreditation investment for community hospital laboratory partnerships to lock in reference testing volume. For New Entrants and Emerging Players: Underserved community oncology practices in rural Texas and Florida present immediate addressable white space for same-day BRAF mutation testing platforms. Neoadjuvant therapy monitoring applications in resectable Stage III melanoma offer minimal residual disease assay entry points with limited incumbent penetration. Target Medicare Advantage formulary access as the decisive go-to-market gatekeeper, structuring reimbursement strategy around CMS coverage determination precedents rather than private payer carve-outs. For Investors and Strategic Acquirers: Valuations sit cheapest among independent reference laboratories with companion diagnostic regulatory expertise but limited therapeutic developer partnerships. Long-term viability over the next decade hinges on successful pivot from fee-for-service histopathology to longitudinal minimal residual disease monitoring contracts with risk-bearing oncology networks. Acquisition target archetypes include AI-enabled dermoscopy platform developers with 510(k) clearance runway and liquid biopsy assay specialists with adjuvant therapy surveillance validation data. Watch FDA real-world evidence guidance evolution as the critical inflection signal for post-market study infrastructure investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Regulatory Submission | FDA breakthrough device designation accelerates commercialization timelines for BRAF-directed assay platforms. |
| Integrated Delivery Network Partnership | Kaiser Permanente and MD Anderson regional networks consolidate diagnostic volume through captive laboratory relationships. |
| AI-Enabled Dermoscopy 510(k) Clearance | Machine learning triage algorithms reduce unnecessary biopsy referrals in Florida high-volume screening practices. |
| Point-of-Care Molecular Testing Deployment | Community oncology clinics in Texas reduce academic center referral leakage through same-day mutation results. |
| Real-World Evidence Infrastructure Investment | Post-market study requirements for accelerated approvals demand EHR integration across fragmented delivery networks. |
Research Methodology
Multiple input streams — structured interviews with dermatopathology laboratory directors, immuno-oncology pharmaceutical executives, and Medicare Advantage formulary managers — were reconciled against CMS coverage determination databases, FDA 510(k) and PMA filing records, and CAP laboratory accreditation registries. Secondary validation drew from hospital procurement database extracts, GPO contract repositories, and state-level Medicaid formulary documentation. Bottom-up testing volume modeling and top-down therapeutic revenue triangulation anchored market size estimation across product type, technology, application, and end-user segmentation dimensions.
Data-stream reconciliation integrated patient flow analysis through academic medical centers and community oncology networks with molecular diagnostic assay reimbursement trajectory modeling across the projection horizon. Segmentation dimensions encompassed diagnostic modality invasiveness, therapeutic mechanism class, disease stage application, and institutional buyer procurement authority. CAGRs were derived from log-linear trend fitting to historical volume and value trajectories, adjusted for FDA approval pathway acceleration effects and laboratory consolidation patterns. Forecast inputs included melanoma incidence rate projections by state, companion diagnostic mandate expansion timelines, and point-of-care testing technology adoption curves.
Underlying measurement precision varies by segment; hospital-based therapeutic revenue carries tighter precision than emerging minimal residual disease monitoring assay volumes. Forecasts reflect assumptions regarding FDA breakthrough therapy designation persistence, CMS national coverage determination stability, and state Medicaid formulary access continuity. Deviation in real-world evidence standards guidance or Medicare Advantage prior authorization intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Direct Fluorescent Antibody Test Kits Market
Diagnostics
Latex Agglutination Test Market
Diagnostics
Middle East and Africa HIV Diagnosis and Treatment Market
Diagnostics
Global Predictive and Presymptomatic Testing Market
Diagnostics
Influenza Diagnostic Tests Market
Diagnostics
Global Molecular Diagnostics Services Market
Diagnostics
Melioidosis Diagnostic Market
Diagnostics
US Prostate Cancer Nuclear Medicine Diagnostics Market
Diagnostics
Global STD Diagnostics Market
Diagnostics
Global Paper Diagnostics Market
Diagnostics
Global Companion Diagnostic Technologies Market
Diagnostics
Diagnostic Enzymes Market
Diagnostics
Animal Auto-Immune Disease Diagnostics Market
Diagnostics
US in Vitro Diagnostics Market
Diagnostics
Cryptococcal Antigen Lateral Flow Assay Test Market
Diagnostics
Pathogen Detection Market