
 Asia Pacific Predictive Disease Analytics Market | 2026-2036
Asia Pacific Predictive Disease Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Predictive Disease Analytics Market Insights
Multi-source data partnerships between health systems and algorithm vendors is recalibrating competitive dynamics across the region. IBM Corporation leverages its Watson Health architecture to anchor enterprise contracts with large hospital networks. Siemens Healthineers competes through imaging-data integration, while Oracle Corporation extends cloud infrastructure dominance into clinical analytics pipelines.
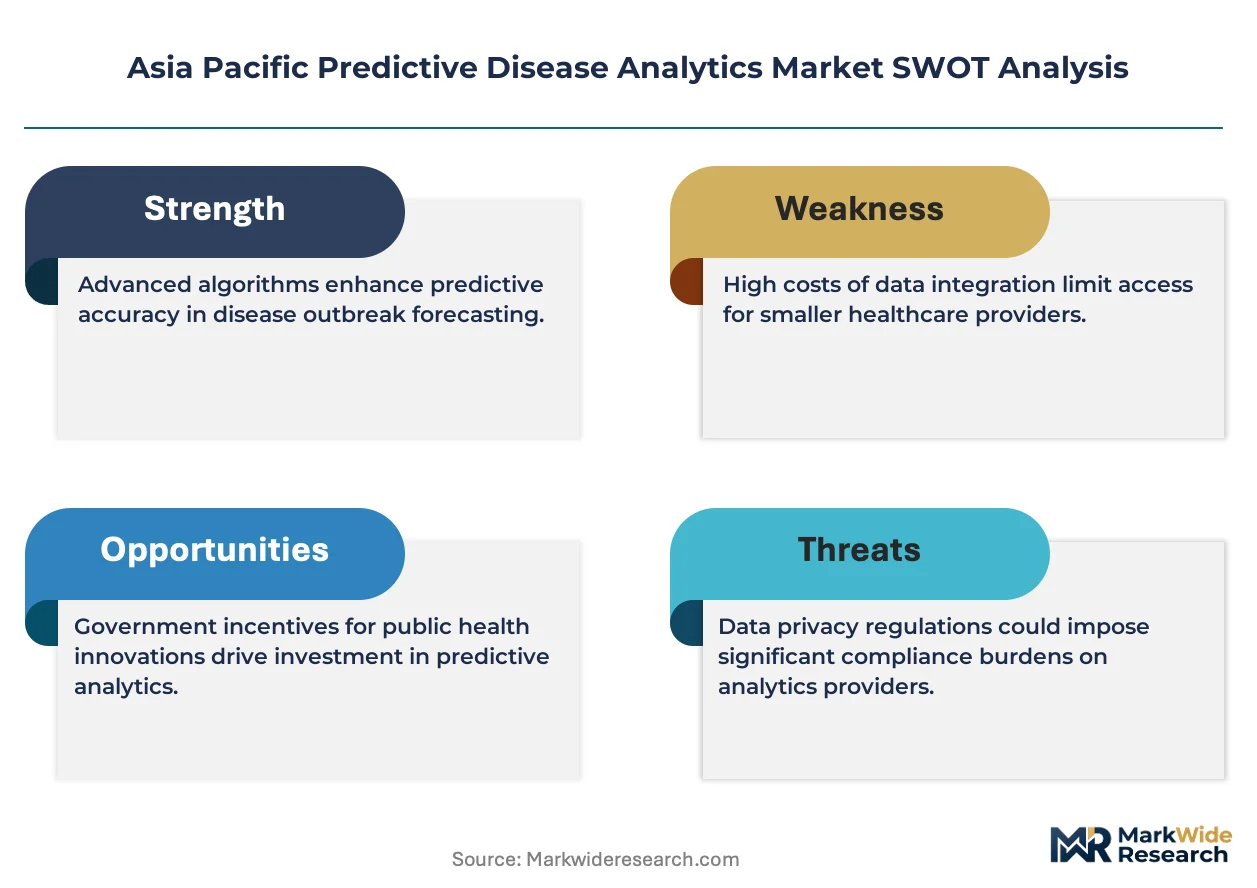
Predictive disease analytics encompasses computational systems that apply statistical modeling and artificial intelligence to patient records, biometric streams, and population health databases to forecast disease onset, progression, or outbreak patterns. These platforms typically process structured electronic health data alongside unstructured clinical notes through natural language processing engines to generate risk scores with defined confidence intervals. Machine learning deployments currently occupy the largest technology share, though deep learning segments for medical imaging prediction are expanding fastest due to higher accuracy thresholds in oncology and cardiology applications. Cloud-based delivery dominates among research institutions seeking elastic compute capacity, while hybrid architectures gain traction among hospitals balancing data sovereignty requirements with scalability needs.
Japan's PMDA governs software-as-medical-device classifications, directly shaping which predictive algorithms require clinical validation before reimbursement eligibility. Australia's TGA and South Korea's MFDS maintain parallel oversight frameworks for AI diagnostic tools, creating a fragmented compliance landscape for vendors operating across multiple jurisdictions. India's CDSCO is developing digital health guidelines that will determine market access for foreign analytics platforms in public hospital procurement. Stakeholders must monitor regulatory divergence on algorithmic transparency requirements as this will determine which deployment models achieve sustainable reimbursement across the region's major health systems.
Market Dynamics
Multi-source data partnerships between health systems and algorithm vendors are recalibrating competitive dynamics across Asia Pacific. Hospital procurement committees now weight interoperability scores above standalone accuracy metrics when evaluating predictive analytics platforms.
Growth Catalysts
- India's PLI scheme for pharmaceutical manufacturing:Accelerating data infrastructure investment across contract research organizations and hospital networks. The incentive structure mandates digitized clinical trial endpoints.
- Deep learning for medical imaging prediction:Expanding fastest in oncology and cardiology applications due to higher accuracy thresholds. Tertiary care networks in Australia and Japan prioritize these tools for surgical planning.
- Japan's integrated health delivery organizations:Consolidating purchasing power and standardizing AI-enabled risk stratification protocols across prefectural hospital alliances.
Market Restraints
- Regulatory fragmentation:Japan's PMDA, Australia's TGA, and South Korea's MFDS maintain divergent software-as-medical-device classifications. Vendors face redundant clinical validation costs across jurisdictions.
- Cloud infrastructure concentration:Dominant hyperscaler architectures create vendor lock-in risks for hospitals balancing data sovereignty with elastic compute needs.
- Biometric data governance gaps:Absence of harmonized cross-border patient data transfer protocols limits multi-site algorithm training.
Strategic Opportunities
- Southeast Asia hospital system expansion:Procurement of AI-enabled risk stratification tools is accelerating in Vietnam, Thailand, and Indonesia as health infrastructure investment scales.
- Natural language processing convergence with genomic sequencing:Creating predictive phenotyping platforms for rare disease diagnosis in Australia's research hospitals.
- India's CDSCO digital health guidelines:Pending framework will determine market access for foreign analytics platforms in public hospital procurement, favoring early compliance investments.
Industry Challenges
- Clinical informaticist shortage:Health systems lack personnel capable of validating algorithm outputs against electronic health record workflows.
- Legacy electronic health record integration:Predictive platforms require costly middleware development to interface with heterogeneous hospital information systems deployed across the region.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Predictive Disease Analytics Market |
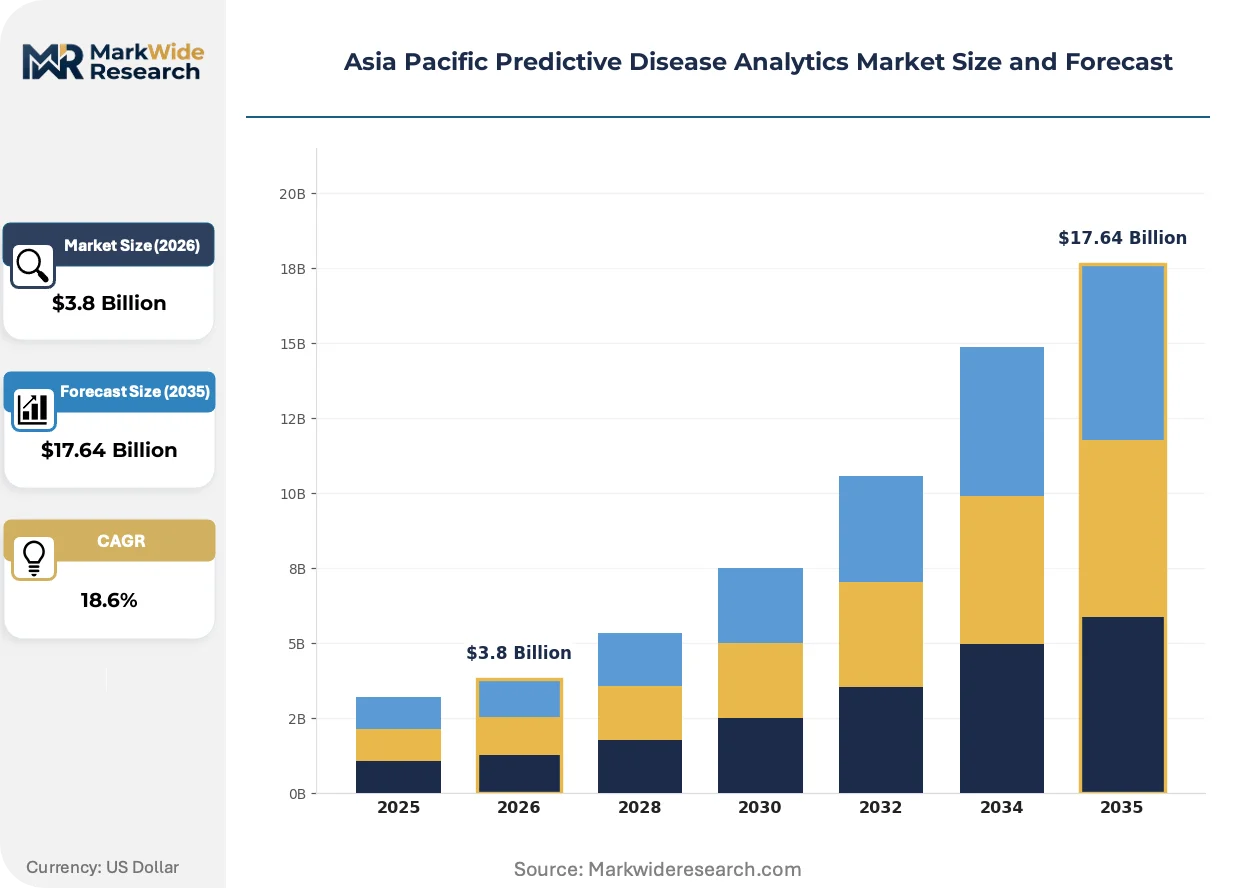
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Deep Learning, Natural Language Processing, Data Mining Application: Chronic Disease Management, Disease Outbreak Prediction, Patient Monitoring, Risk Assessment End User: Hospitals, Research Institutions, Healthcare Providers, Pharmaceutical Companies Deployment: Cloud-Based, On-Premises, Hybrid, Web-Based |
| Companies Covered | IBM Corporation, SAS Institute Inc., Oracle Corporation, Optum Inc., Merative, Cerner Corporation, GE Healthcare, Siemens Healthineers, Health Catalyst, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Predictive Disease Analytics Market Trends and Innovations
Federated learning architectures and edge-compute deployments are reshaping how predictive models train on distributed patient data without centralization. These shifts alter capital allocation patterns for both health systems and algorithm vendors.
Transformer-based clinical language models are expanding into unstructured electronic health record analysis across Australian tertiary care networks. Hospital IT departments deploy these systems to extract medication adherence signals from discharge summaries. The technology is expanding into real-time risk scoring pipelines that previously relied on structured data fields alone.
Japan's PMDA software-as-medical-device classification framework is tightening validation requirements for predictive algorithms seeking reimbursement eligibility. Vendors must now submit prospective clinical performance data rather than retrospective accuracy studies. Oncology risk stratification tools face the steepest compliance burden, with several platforms undergoing extended review cycles.
Hospital procurement committees are consolidating vendor relationships around full-stack analytics partnerships rather than point-solution contracts. Australia's integrated care networks now require predictive platforms to include embedded biostatistical support and continuous model retraining services. This bundling trend disadvantages standalone algorithm developers lacking implementation infrastructure.
Asia Pacific Predictive Disease Analytics Market Segmentation
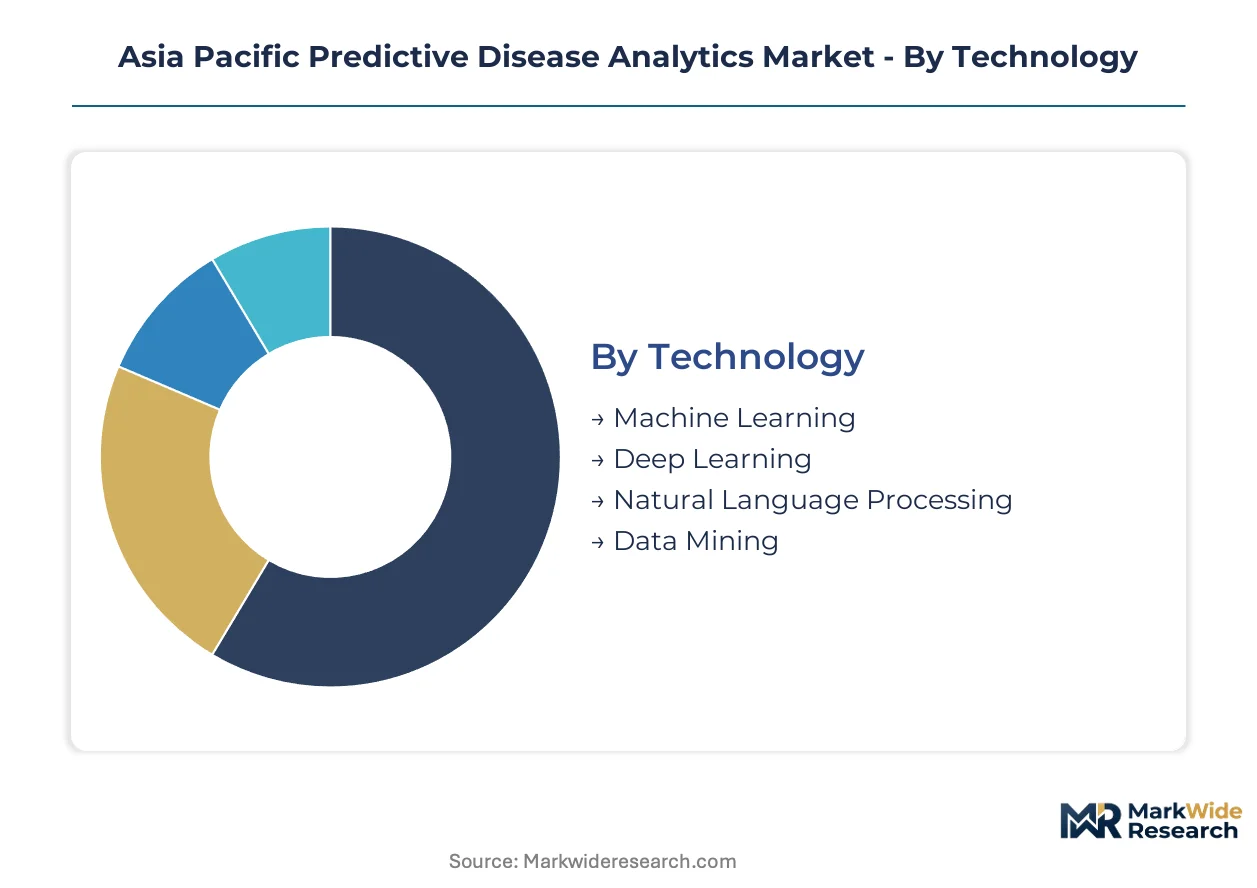
Predictive disease analytics platforms fragment across technology maturity, clinical workflow integration depth, and infrastructure constraints. Each segment carries distinct regulatory validation burdens and capital deployment profiles across Asia Pacific health systems.
Technology:
PMDA software-as-medical-device classifications impose tiered compliance thresholds across algorithmic approaches, with deep learning facing the steepest prospective clinical data requirements.
- Machine Learning:Statistical modeling frameworks process structured electronic health records to generate risk scores with defined confidence intervals. Australian tertiary care networks concentrate procurement here for surgical planning workflows, though model drift requires continuous retraining infrastructure.
- Deep Learning:Neural network architectures achieve higher accuracy thresholds in oncology and cardiology imaging prediction. Japan's prefectural hospital alliances prioritize these tools despite extended PMDA review cycles and substantial validation costs.
- Natural Language Processing:Extracts medication adherence signals from unstructured clinical notes. Australia's integrated care networks deploy these for real-time risk scoring pipelines.
- Data Mining:Pattern recognition across population health databases supports disease outbreak prediction. India's contract research organizations leverage these for digitized clinical trial endpoints under PLI scheme mandates.
Leading the category by volume: Machine Learning. Growing fastest: Deep Learning.
Application:
Reimbursement eligibility varies sharply by clinical use case, with chronic disease management securing sustainable funding pathways earlier than outbreak prediction systems.
- Chronic Disease Management:Longitudinal risk stratification for diabetes and cardiovascular conditions. Japan's integrated health delivery organizations standardize these protocols across prefectural alliances.
- Disease Outbreak Prediction:Population-level surveillance combining biometric streams with epidemiological models. Southeast Asian hospital systems in Vietnam and Thailand expand procurement here for pandemic preparedness.
- Patient Monitoring:Real-time biometric analysis from wearable devices and bedside sensors. Australian tertiary networks prioritize perioperative monitoring applications.
- Risk Assessment:Pre-operative and post-discharge scoring for adverse event probability. India's hospital networks invest here under digitization mandates tied to pharmaceutical manufacturing incentives.
Dominant by revenue: Chronic Disease Management. Steepest expansion trajectory: Disease Outbreak Prediction.
End User:
Procurement authority concentrates in institutions with dedicated informaticist teams capable of algorithm validation against electronic health record workflows.
- Hospitals:Primary deployment sites for clinical decision support integration. Australia's integrated care networks require embedded biostatistical support and continuous retraining services.
- Research Institutions:Federated learning architectures train models on distributed patient data without centralization. Edge-compute deployments alter capital allocation patterns here.
- Healthcare Providers:Ambulatory and primary care settings adopt cloud-based delivery for elastic compute capacity. Data sovereignty requirements drive hybrid architecture interest.
- Pharmaceutical Companies:Accelerate data infrastructure investment under India's PLI scheme with digitized clinical trial endpoint mandates.
Top spender segment: Hospitals. Fastest budget growth: Research Institutions.
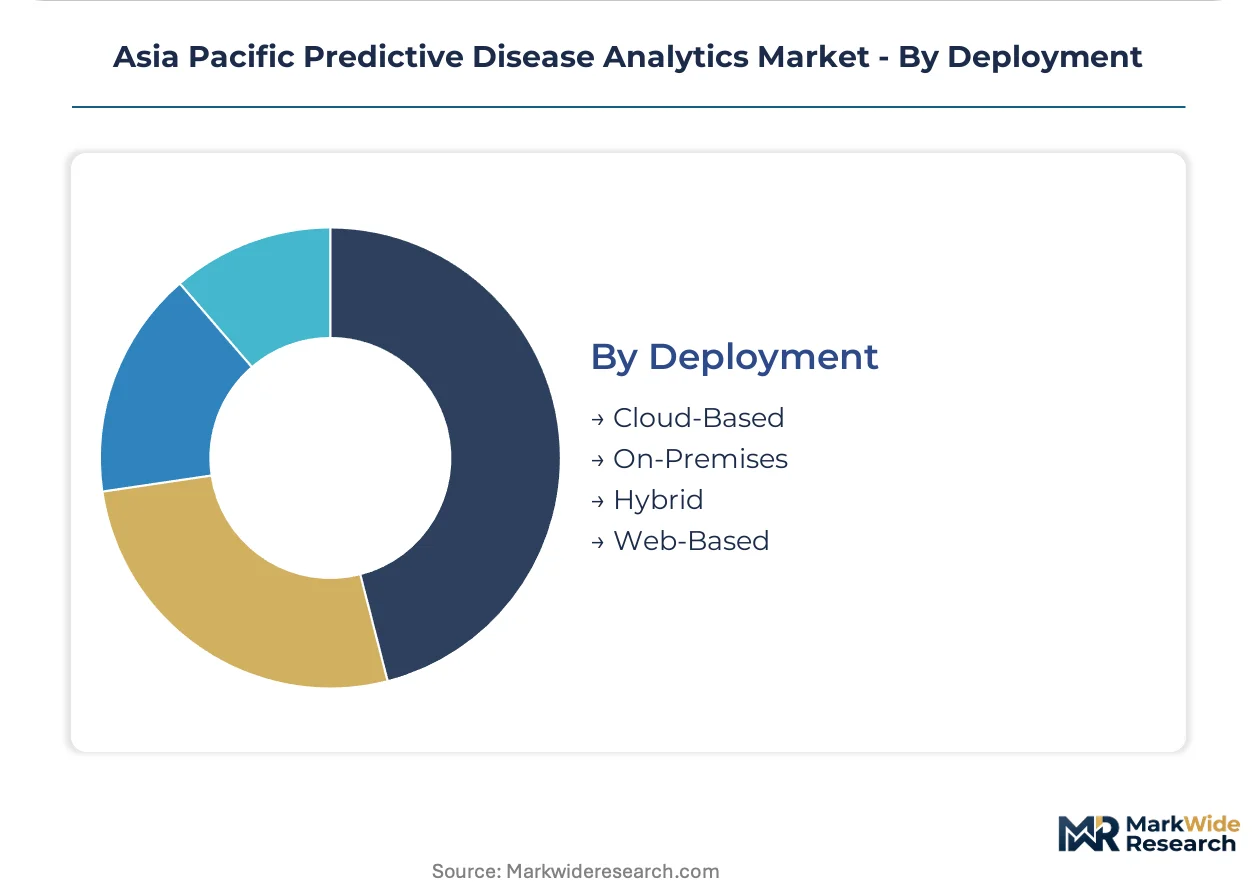
Deployment:
Infrastructure choice reflects the tension between scalability demands and data sovereignty requirements across fragmented national regulatory frameworks.
- Cloud-Based:Elastic compute capacity dominates among research institutions. Hyperscaler concentration creates vendor lock-in risks for hospitals balancing sovereignty with scalability.
- On-Premises:Local server installations satisfy Japan's PMDA data residency expectations and Australia's TGA audit requirements for algorithmic transparency.
- Hybrid:Split architectures gain traction as hospitals process sensitive records locally while leveraging cloud for model training. South Korea's MFDS frameworks accommodate this approach.
- Web-Based:Browser-accessible platforms reduce middleware development costs for legacy electronic health record integration across heterogeneous hospital information systems.
Installed base leader: Cloud-Based. Gaining share fastest: Hybrid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement authority concentrates in Japan's prefectural alliances and Australia's integrated care networks, with India's pharmaceutical incentive schemes redirecting infrastructure investment toward digitized clinical endpoints.
Japan
Prefectural hospital alliances consolidate purchasing power for AI-enabled risk stratification tools. PMDA software-as-medical-device classifications mandate prospective clinical validation before reimbursement eligibility, tightening compliance timelines for oncology platforms. Tokyo and Osaka anchor enterprise contract negotiations for full-stack analytics partnerships.
Australia
Tertiary care networks prioritize deep learning deployments for surgical planning in oncology and cardiology workflows. TGA oversight frameworks for AI diagnostic tools require algorithmic transparency documentation. Sydney and Melbourne health systems drive procurement for embedded biostatistical support and continuous model retraining services.
India
Contract research organizations accelerate data infrastructure investment under PLI scheme mandates for digitized clinical trial endpoints. CDSCO digital health guidelines pending finalization will determine foreign platform access in public hospital procurement. Hyderabad and Bengaluru clusters concentrate pharmaceutical manufacturing data pipeline development.
South Korea
Integrated health delivery organizations standardize predictive protocols across metropolitan hospital networks. MFDS regulatory frameworks accommodate hybrid cloud architectures balancing data sovereignty with model training scalability. Seoul Capital Area facilities lead edge-compute deployments for federated learning architectures.
Southeast Asia
Hospital systems in Vietnam, Thailand, and Indonesia expand procurement of AI-enabled risk stratification tools as health infrastructure investment scales. National pharmaceutical regulators develop software-as-medical-device classifications for outbreak prediction platforms. Ho Chi Minh City and Bangkok anchor regional vendor partnership negotiations.
Asia Pacific Predictive Disease Analytics Market Competitive Landscape
Strategic partnerships between health systems and algorithm vendors dominate the current landscape, recalibrating procurement criteria toward interoperability scores above standalone accuracy metrics. The vendor base organizes around three archetypes: cloud infrastructure providers extending clinical analytics pipelines, imaging-data integrators leveraging diagnostic equipment installed bases, and enterprise health IT platforms anchoring hospital network contracts. M&A activity and technology licensing agreements represent the primary competitive moves as vendors seek middleware capabilities for legacy electronic health record integration.
Within the cloud infrastructure tier, Oracle Corporation and IBM Corporation occupy positions anchored by hyperscaler architectures and Watson Health enterprise frameworks respectively. Siemens Healthineers exemplifies the imaging-data integration archetype, competing through diagnostic platform connectivity. These three entities represent distinct strategic vectors—cloud dominance, AI architecture licensing, and equipment-anchored analytics—shaping how procurement committees evaluate full-stack versus point-solution contracts.
| Leading Market Players |
|---|
| IBM Corporation |
| SAS Institute Inc. |
| Oracle Corporation |
| Optum Inc. |
| Merative |
| Cerner Corporation |
| GE Healthcare |
| Siemens Healthineers |
| Health Catalyst |
| Others |
Pricing and Supply Chain Analysis
Deep learning validation tier divergence separates oncology and cardiology platforms commanding premium implementation fees from commodity machine learning risk scores, with PMDA software-as-medical-device classifications enforcing cost premiums on neural network architectures while cloud infrastructure concentration in hyperscaler ecosystems compresses margins for standardized deployments.
Pricing Analysis
Volume concentrates in subscription SaaS-tiered contracts for machine learning risk stratification tools, while margins accrue to deep learning platforms facing extended PMDA review cycles. Price differentiation stems from clinical validation tier and embedded biostatistical support bundling. Cost compression in standardized cloud deployments intensifies as Oracle Corporation and IBM Corporation leverage infrastructure scale. Public hospital procurement committees in India exhibit highest price sensitivity, while Japan's prefectural alliances prioritize interoperability scores over unit cost.
Supply Chain Analysis
Reverse-logistics flows for algorithm model retraining and continuous validation services create recurring revenue attachments that reshape vendor economics. Component concentration centers on NVIDIA GPU clusters sourced from Taiwan and USA, with edge-compute hardware fabrication anchored in South Korea and Japan. Single-source vulnerability in hyperscaler cloud infrastructure threatens hospital data sovereignty compliance. Distribution runs through direct enterprise contracts with integrated care networks rather than channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Federated learning architectures are displacing centralized model training across Asia Pacific health systems, with edge-compute deployments replacing legacy cloud-only pipelines as the dominant infrastructure paradigm.
For Market Incumbents: Extend Watson Health enterprise frameworks into hybrid cloud architectures to counter Oracle Corporation's infrastructure dominance. Anchor full-stack analytics partnerships with Australia's integrated care networks before procurement committees consolidate vendor relationships. Invest in middleware capabilities for legacy electronic health record integration to defend against standalone algorithm developers.
For New Entrants and Emerging Players: Begin with natural language processing convergence opportunities in Australia's research hospitals, where transformer-based clinical language models penetrate unstructured data workflows with lower validation burdens than imaging prediction platforms. Target Vietnam and Thailand hospital system expansion with outbreak prediction tools as pandemic preparedness procurement accelerates. Pursue white-label partnerships with Siemens Healthineers for imaging-data integration access.
For Investors and Strategic Acquirers: Re-rating potential sits with federated learning specialists given MFDS regulatory accommodation of hybrid architectures across South Korea's metropolitan hospital networks. Long-term viability favors vendors with embedded biostatistical support services rather than standalone algorithm licensing. Monitor CDSCO digital health guideline finalization as inflection indicator for foreign platform access in Indian public procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Software-as-Medical-Device Submission | Prospective clinical validation data unlocks reimbursement eligibility in Japan's prefectural hospital alliances. |
| Hybrid Cloud Architecture Deployment | Split processing satisfies Australia's TGA audit requirements while enabling elastic model training capacity. |
| Natural Language Processing Platform Integration | Transformer-based clinical models extract medication adherence signals from unstructured discharge summaries. |
| Hospital System Partnership | Enterprise contracts with integrated care networks consolidate procurement around full-stack analytics bundles. |
| Federated Learning Infrastructure Investment | Edge-compute deployments train models on distributed patient data without centralization across research institutions. |
Research Methodology
Multi-period observation of PMDA software-as-medical-device approval timelines, hospital procurement contract values, and cloud infrastructure capex disclosures anchored the trend analysis, supplemented by interviews with hospital informaticists, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at algorithm vendors. Secondary validation drew from TGA guidance documents, MFDS framework publications, CDSCO draft guidelines, hospital procurement databases, and hyperscaler segment revenue disclosures. Bottom-up segment sizing triangulated against top-down health system IT spending estimates.
Segment-weighting approaches modeled technology type, application use case, deployment architecture, and end-user institution scale across the projection horizon. CAGRs derived from algorithmic diffusion curves calibrated to regulatory approval velocity and reimbursement pathway establishment. Forecast inputs incorporated PLI scheme infrastructure investment trajectories in India and prefectural hospital alliance consolidation patterns in Japan.
Regulatory divergence on algorithmic transparency requirements, PMDA validation timeline extensions, and CDSCO guideline finalization delays are the dominant revision risks to forecast assumptions. Practitioners should monitor reimbursement eligibility determinations and cross-border data transfer protocol developments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Antinuclear Antibody Test Market
Diagnostics
North America Thyroid Cancer Diagnostics Market
Diagnostics
Companion Animal Diagnostic Services Market
Diagnostics
Alanine Aminotransferase Reagent Market
Diagnostics
Hepatitis Test Solution and Diagnosis Market
Diagnostics
Septicemia Diagnostic Testing Market
Diagnostics
Livestock Diagnostics Market
Diagnostics
Global Hemostasis Diagnostics Market
Diagnostics
Cryptococcal Antigen Lateral Flow Assay Test Market
Diagnostics
Hepatitis E Diagnostic Tests Market
Diagnostics
North America Breast Cancer Screening Tests Market
Diagnostics
Global Urinalysis Market
Diagnostics
Semen Analysis Market
Diagnostics
US in Vitro Diagnostics Market
Diagnostics
Global Lateral Flow Assay Market
Diagnostics
North America and Europe Companion Animal Diagnostics Imaging Market